
 Bio-Based Adhesives Market | 2026-2036
Bio-Based Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Based Adhesives Market Analysis
Packaging is consolidating as the dominant end-use vertical for bio-based adhesives, displacing slower-growing solvent-heavy applications in general assembly. Henkel AG & Co. KGaA leverages its European formulation network to supply water-based bio-adhesives to corrugated board producers. H.B. Fuller Company anchors its position through captive supply of hot-melt systems for food-safe packaging lines. Arkema competes via specialized polyurethane platforms targeting automotive interior lamination.
Bio-based adhesives are bonding agents derived from renewable biomass feedstocks such as starch, plant oils, lignin, or bio-polyols, formulated to achieve shear strengths and cure profiles comparable to petroleum-derived alternatives for industrial joining and surface lamination. Starch-based formulations dominate volume in paper laminating and fiberboard applications due to low raw material cost and compatibility with existing spreader equipment. Polyurethane adhesives command premium positioning in woodworking and textile bonding where flexibility, moisture resistance, and VOC compliance create differentiated margin pools. Water-based formulations lead environmental positioning across all applications, while solvent-based systems retain niche use in high-performance textile bonding where rapid tack development remains critical.
EPA bio-preferred procurement standards and EU Green Deal sustainability frameworks are mandating renewable content thresholds in federal and commercial packaging contracts, directly shaping product certification requirements and market access conditions for adhesive suppliers. REACH chemical registration and FDA food-contact compliance add parallel compliance layers that filter formulation choices and raw material sourcing. Stakeholders must monitor how evolving carbon border adjustments and state-level extended producer responsibility laws in California and New York reshape total cost of ownership calculations for adhesive procurement decisions.
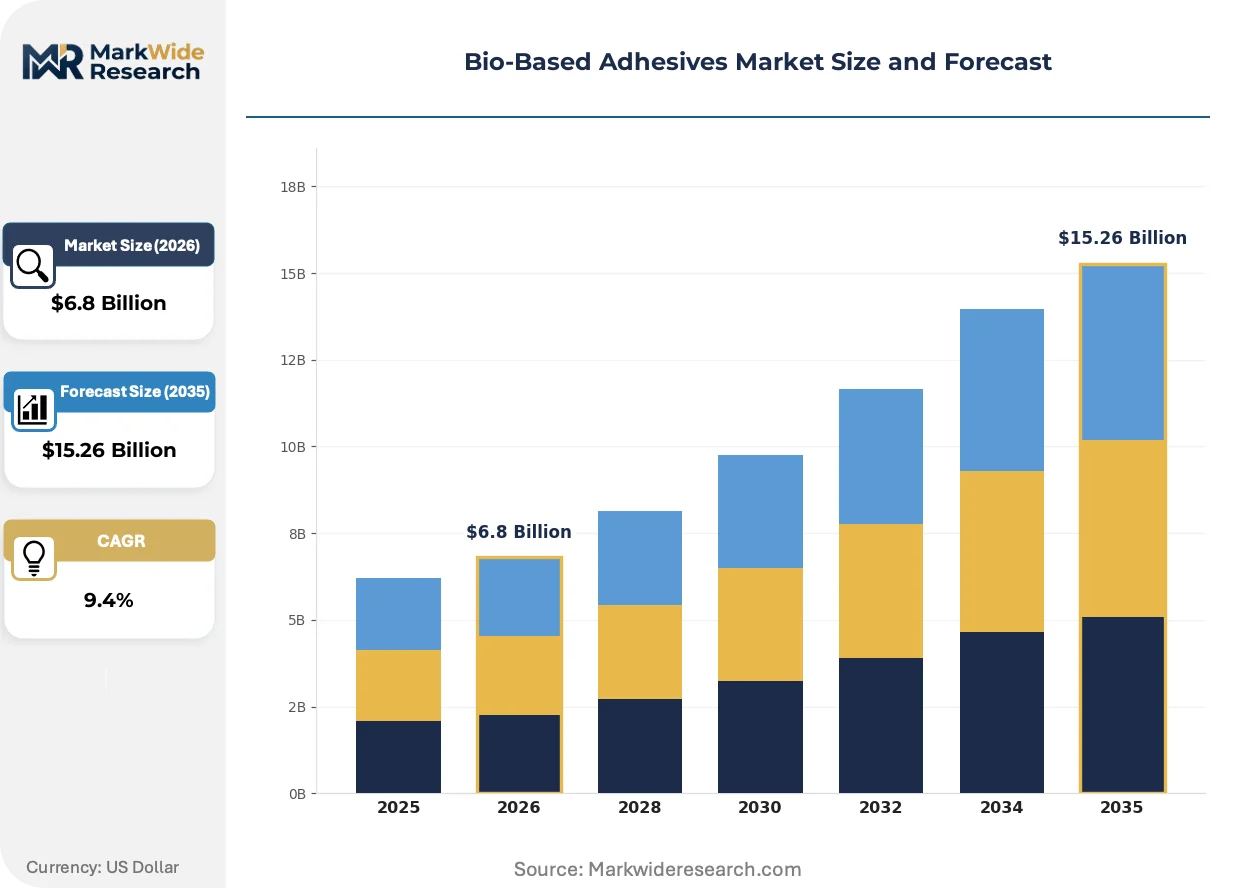
Market Dynamics
EU Green Deal packaging mandates and EPA bio-preferred procurement thresholds are forcing formulation switches across corrugated board, automotive lamination, and plywood manufacturing, compressing qualification timelines and certifier bandwidth.
Growth Catalysts
- REACH chemical registration:EU adhesive suppliers reformulating petroleum-based systems face compliance cost cliffs, redirecting R&D budgets toward starch and lignin feedstocks that bypass SVHC scrutiny.
- Automotive lightweighting:German OEMs specify bio-polyurethane interior laminates to meet fleet CO2 targets, creating pull-through demand for certified bonding systems in Tier 2 seating and panel suppliers.
- China dual carbon goals:Provincial manufacturing clusters in Shandong and Jiangsu receive preferential energy quotas for bio-based chemical production, lowering effective input costs for domestic adhesive compounders.
Market Restraints
- Feedstock cost volatility:Corn starch and soy polyol prices track agricultural commodity futures, exposing formulators to margin compression when grain harvests underperform in Brazil and the US Midwest.
- Technical performance gaps:Bio-based hot-melt systems exhibit slower tack development and narrower temperature operating windows versus petroleum EVA alternatives, limiting uptake in high-speed packaging lines.
- Certification bottlenecks:USDA BioPreferred and TÜV OK Compost audit queues extend 14-18 months, freezing product launches and locking out smaller compounders lacking dedicated regulatory affairs staff.
Strategic Opportunities
- India PLI scheme for chemicals:Domestic manufacturing incentives for specialty chemicals reduce import dependency, enabling local production of starch ester adhesives for paperboard converters in Gujarat and Maharashtra.
- Textile bonding convergence:Water-based polyurethane dispersions combined with plasma surface pretreatment eliminate solvent use in footwear and apparel lamination, opening premium positioning in athletic wear supply chains.
- Extended producer responsibility laws:California and New York packaging waste statutes mandate recyclable adhesive selection, creating first-mover advantage for suppliers with cradle-to-cradle certified formulations.
Industry Challenges
- Formulation chemist scarcity:Cross-disciplinary expertise spanning polymer science, food-contact compliance, and rheology engineering concentrates at Henkel, H.B. Fuller, and Arkema, leaving mid-tier compounders dependent on external consultants.
- Legacy equipment incompatibility:Starch-based adhesives require modified spreader rolls and drying tunnel configurations, forcing packaging converters to choose between capital retrofit or supplier lock-in.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Based Adhesives Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Polyvinyl Acetate, Epoxy, Starch-based End User: Plywood Industry, Packaging, Automotive, Construction Formulation: Water-based, Solvent-based, Powder-based, Hot-melt Application: Woodworking, Paper Laminating, Textile Bonding, Fiberboard |
| Companies Covered | Henkel AG & Co. KGaA, H.B. Fuller Company, Arkema, 3M, Sika, Dow, DuPont de Nemours, Inc., EcoSynthetix Inc., Ingredion Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Based Adhesives Market Emerging Trajectories
Formulation architectures are fragmenting into application-specific modules as end-users reject universal adhesives, while regulatory bandwidth constraints and procurement centralization reshape how bonding systems reach industrial buyers.
Lignin-derived thermoset resins are modularizing across plywood and engineered wood panel manufacturing. European OSB producers in Austria and Germany adopt these systems to replace phenol-formaldehyde binders, compressing cure cycles from 8 minutes to 4 minutes while satisfying E1 emission classifications. This modularity enables discrete product lines for interior versus exterior grade panels without reformulating base chemistry.
CSRD sustainability disclosure requirements are mandating supply chain emissions transparency for EU-listed packaging converters. Adhesive suppliers must now provide cradle-to-gate carbon footprints verified against ISO 14067, with non-compliant formulators excluded from tender shortlists. German corrugated board producers have responded by consolidating procurement around three certified compounders with dedicated lifecycle assessment teams.
Specification authority is migrating from plant engineers to corporate sustainability officers who control approved vendor lists through ESG scorecards. Food-safe packaging lines in the United States now require third-party certified bio-content thresholds before trial batches, displacing traditional technical qualification pathways. This shift concentrates volume among suppliers with pre-certified platforms, marginalizing smaller compounders lacking audit infrastructure.
Bio-Based Adhesives Market Segmentation
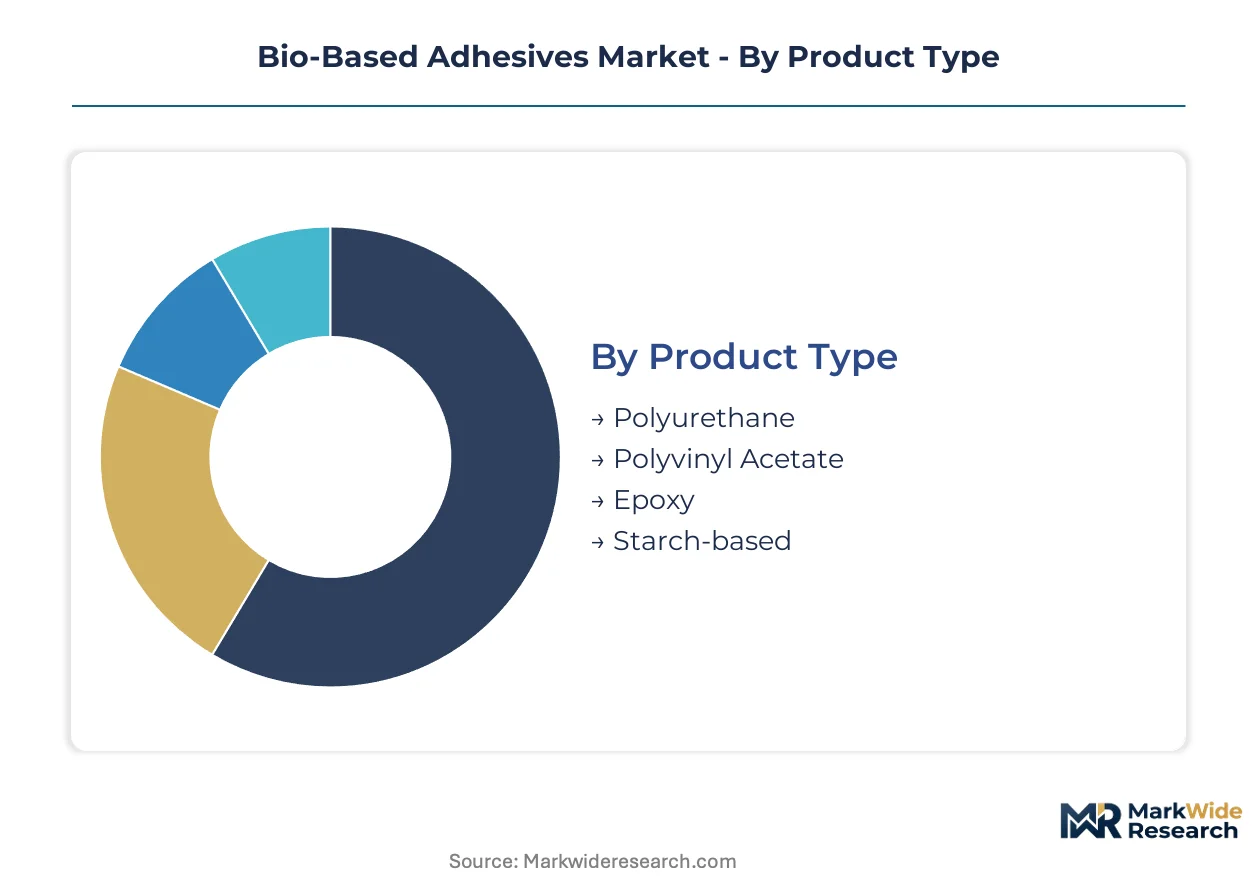
Segmentation in bio-based adhesives reveals how capital allocation, regulatory exposure, and technical specifications fragment procurement decisions across end-use verticals. Formulators must match feedstock chemistry to application performance thresholds while navigating divergent compliance burdens.
Product Type:
Polyurethane and starch-based platforms demand the heaviest upfront capital for dedicated polymerization reactors and drying infrastructure, while epoxy and polyvinyl acetate lines repurpose existing petrochemical equipment with lower retrofit costs.
- Polyurethane:Derived from bio-polyols and isocyanate crosslinkers, these systems achieve flexible, moisture-resistant bonds for automotive interior lamination and engineered wood panels. German OEMs specify certified bio-polyurethane formulations to meet fleet CO2 targets, pulling through demand from Tier 2 seating suppliers.
- Starch-based:Native or modified starches from corn, wheat, or cassava form the lowest-cost bio-adhesive platform, compatible with existing paperboard spreader equipment. Demand concentrates in corrugated board manufacturing across Germany and the United States, where EU Green Deal and EPA bio-preferred thresholds mandate renewable content.
- Polyvinyl Acetate:Bio-based PVAc emulsions substitute petroleum-derived vinyl acetate with bio-ethylene feedstocks for woodworking and general assembly applications.
- Epoxy:Bio-epoxy systems utilizing lignin-derived bisphenol alternatives serve high-strength bonding in construction composites and wind turbine blade manufacturing.
Most installed capacity flows through starch-based formulations. Expansion is steepest in polyurethane as automotive lightweighting specifications harden.
End User:
Packaging converters and automotive OEMs operate on opposite ends of the customer spectrum —前者 consolidate procurement through sustainability scorecards,后者 impose exacting performance validation protocols.
- Packaging:Corrugated board and flexible film laminators drive the highest volume demand for water-based starch and bio-polyurethane adhesives, with EU-listed converters now requiring cradle-to-gate carbon footprints verified against ISO 14067.
- Plywood Industry:Engineered wood panel manufacturers in China and Europe adopt lignin-derived thermoset resins to replace phenol-formaldehyde binders, compressing cure cycles while satisfying E1 emission classifications.
- Automotive:Interior lamination for seating, headliners, and door panels specifies bio-polyurethane systems meeting VOC and fogging standards.
- Construction:Structural bonding and insulation panel assembly utilize bio-epoxy and modified starch systems for exterior-grade applications.
Volume leadership sits with packaging. The steepest expansion trajectory belongs to automotive as lightweighting targets tighten.
Formulation:
Water-based systems require the most extensive drying tunnel retrofits, while hot-melt and powder-based lines demand lower capital outlay but impose stricter raw material purity specifications.
- Water-based:Emulsion adhesives with bio-polymer dispersed phases dominate environmental positioning across all end-uses, leading VOC compliance in food-safe packaging lines.
- Hot-melt:Bio-based EVA and polyamide alternatives serve high-speed packaging and bookbinding applications where rapid tack development is critical.
- Solvent-based:Retains niche use in textile bonding and specialty laminations where rapid solvent evaporation enables production speed incompatible with aqueous systems.
- Powder-based:Dry starch and dextrin adhesives serve paper tube winding and remoistenable envelope applications with minimal shipping costs.
Environmental mandates are concentrating procurement in water-based platforms. Hot-melt is gaining share fastest where line speed constraints dominate.
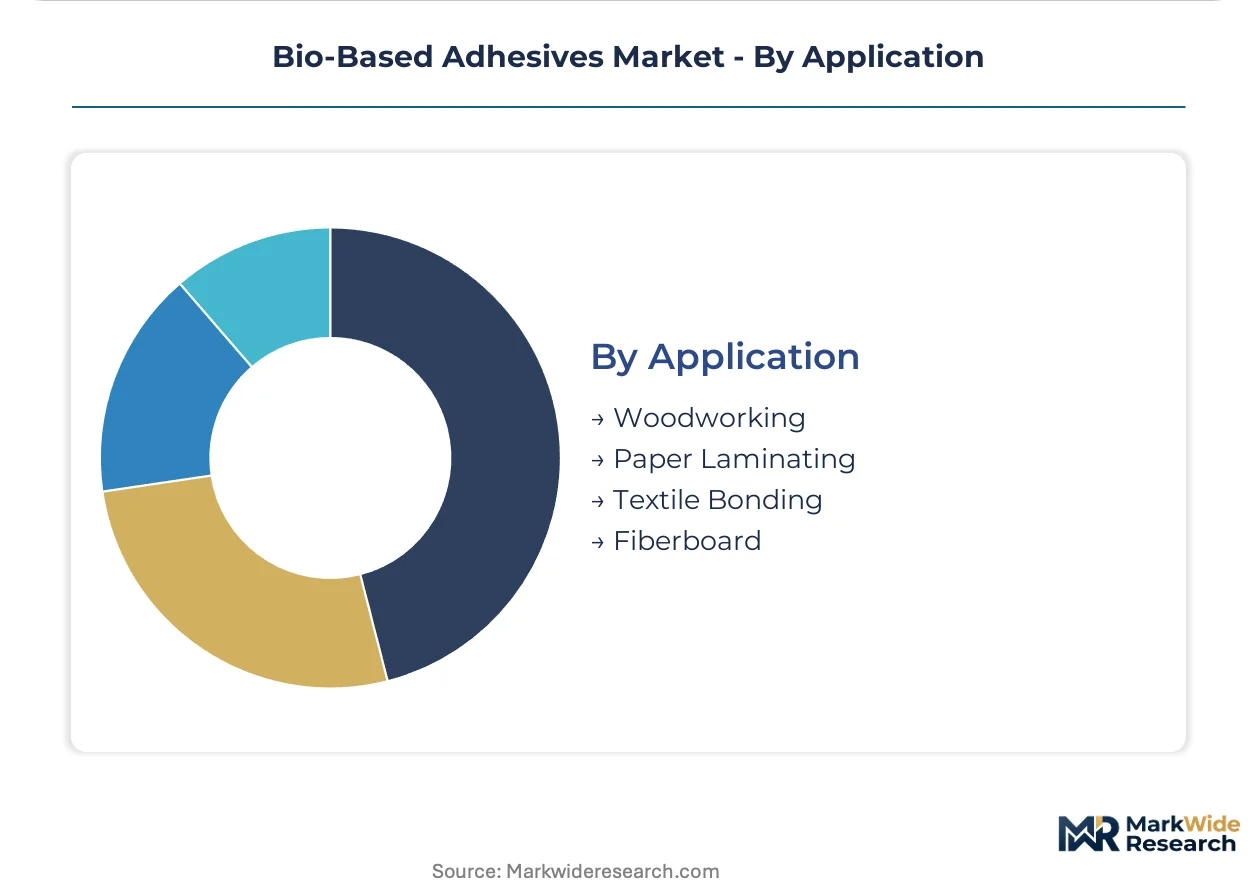
Application:
Woodworking and paper laminating applications absorb the largest capital deployment for application equipment, while textile bonding and fiberboard processing utilize more standardized spreading infrastructure.
- Woodworking:Furniture assembly, flooring installation, and structural timber bonding utilize bio-polyurethane and modified starch systems requiring controlled clamp pressure and humidity conditioning.
- Paper Laminating:Corrugated board fluting, carton sealing, and label stock production represent the highest-volume adhesive consumption, with starch-based formulations dominating due to equipment compatibility.
- Textile Bonding:Footwear, apparel, and automotive textile lamination specify water-based polyurethane dispersions combined with plasma surface pretreatment to eliminate solvent use.
- Fiberboard:Medium-density fiberboard and particleboard manufacturing integrate bio-based binders directly into the mat-forming process, with lignin-derived systems replacing synthetic resins.
Installed capacity concentrates in paper laminating. Expansion is most rapid in textile bonding as athletic wear supply chains decarbonize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive and engineered wood clusters drive the steepest procurement shifts toward bio-polyurethane and lignin-derived systems. EU Green Deal packaging mandates and national CO2 fleet regulations compress qualification timelines for adhesive suppliers across industrial verticals.
Germany
Automotive interior lamination and OSB panel manufacturing absorb the bulk of certified bio-adhesive volume. REACH chemical registration redirects R&D budgets toward starch and lignin feedstocks that bypass SVHC scrutiny. Bavarian and Baden-Württemberg manufacturing belts host Tier 2 seating suppliers converting production lines to bio-polyurethane bonding systems.
United States
Corrugated board converters and food-safe packaging lines dominate procurement of water-based starch formulations. EPA bio-preferred procurement standards mandate renewable content thresholds in federal contracts. Midwest grain belt proximity lowers effective input costs for corn starch compounders supplying Chicago and Detroit industrial corridors.
China
Plywood manufacturing clusters and engineered wood panel producers drive demand for lignin-derived thermoset resins. Provincial dual carbon goals in Shandong and Jiangsu award preferential energy quotas to bio-based chemical production. Yangtze River Delta adhesive compounders scale output to serve furniture export manufacturing around Shanghai and Suzhou.
India
Paperboard converters in Gujarat and Maharashtra represent the fastest-expanding demand pool for starch ester adhesives. PLI scheme incentives for specialty chemicals reduce import dependency for domestic manufacturing. Mumbai-Pune industrial corridor packaging plants consolidate procurement around certified bio-content suppliers with dedicated regulatory affairs teams.
France
Luxury packaging and automotive textile lamination specify water-based polyurethane dispersions with cradle-to-cradle certification. CSRD sustainability disclosure requirements mandate supply chain emissions transparency for listed converters. Auvergne-Rhône-Alpes industrial basin hosts compounders serving athletic wear supply chains with plasma-pretreatment bonding lines.
Bio-Based Adhesives Market Vendor Landscape
Capacity expansion dominates the current landscape as established compounders retrofit petrochemical reactors for bio-polyol polymerization. The vendor base stratifies into three tiers: multinational chemical conglomerates with captive raw material sourcing, mid-tier regional specialists with formulation flexibility, and niche bio-feedstock pure-plays with certification depth. Strategic archetypes include sustainability-integrated diversified industrials, feedstock-locked agricultural processors, and application-specific modular formulators. M&A activity and geographic licensing partnerships concentrate volume among suppliers with pre-certified platforms.
Among sustainability-integrated diversified industrials, Henkel AG & Co. KGaA and H.B. Fuller Company exemplify archetypes with European formulation networks and North American hot-melt supply chains respectively. Arkema occupies a position within the specialty polyurethane tier, anchoring automotive interior lamination demand through certified bio-polyol platforms. These three represent the dominant competitive anchors shaping procurement consolidation around pre-audited adhesive systems.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| H.B. Fuller Company |
| Arkema |
| 3M |
| Sika |
| Dow |
| DuPont de Nemours, Inc. |
| EcoSynthetix Inc. |
| Ingredion Incorporated |
| Others |
Supply Flow & Price Mechanics
Corn futures price volatility on the Chicago Board of Trade cascades through bio-based adhesive supply chains, compressing margins for starch compounders in the US Midwest while creating arbitrage opportunities for cassava-sourced formulators in Southeast Asia. This input-cost transmission splits the market into three distinct pricing tiers tethered to feedstock security and certification depth.
Pricing Analysis
Input-cost pass-through dominates pricing architecture, with corn starch and soy polyol fluctuations transmitting directly to contract renegotiations within 60-90 day lags. Three-tier pricing structure across premium, standard, and economy levels separates USDA BioPreferred-certified polyurethane systems from uncertified starch formulations and commodity dextrin alternatives. Pricing pressure stems from Brazilian harvest shortfalls and energy cost spikes in European polymerization facilities. Mid-tier regional compounders exhibit highest price sensitivity due to thin working capital buffers, while automotive OEM procurement teams prioritize performance guarantees over unit economics.
Supply Chain Analysis
Reverse-logistics flows remain underdeveloped for bio-based adhesive packaging, though corrugated board converters in Germany and California pilot take-back programs for spent starch containers to recover agricultural feedstock value. Raw material sourcing concentrates in the United States, Brazil, and Thailand for corn and cassava starches, with bio-polyol production anchored in Germany and China. Feedstock dependency on agricultural commodity cycles and single-source isocyanate suppliers from BASF and Covestro facilities creates vulnerability to logistics chokepoints at Rotterdam and Shanghai ports. Distribution runs through regional chemical distributors with technical service capabilities, bypassing direct OEM relationships for mid-volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Arbitrage opportunities emerge between EU carbon border adjustment costs and US EPA bio-preferred procurement incentives, rewarding suppliers with dual-continent formulation capacity and harmonized certification portfolios.
For Market Incumbents: Cement market position by acquiring captive starch processing assets in the US grain belt to insulate margin structures from commodity futures volatility. Prioritize TÜV OK Compost and USDA BioPreferred certification renewals ahead of EU Green Deal packaging mandate enforcement windows, as non-compliant formulators face exclusion from tender shortlists at major corrugated board converters. For New Entrants and Emerging Players: Mid-tier plywood manufacturers in Shandong Province represent the most penetrable buyer archetype, underserved by international compounders lacking provincial regulatory affairs presence. Target lignin-derived thermoset resin formulations for engineered wood panel applications where cure cycle compression commands premium positioning. Establish technical service partnerships with regional equipment distributors rather than direct sales forces to minimize customer acquisition costs. For Investors and Strategic Acquirers: Consolidation pressure builds where certification audit queues extend beyond 14 months, freezing product launches and stranding R&D investments at sub-scale compounders. Long-term viability favors feedstock-locked agricultural processors with backward integration into adhesive formulation and dedicated lifecycle assessment teams. Monitor USDA BioPreferred program budget allocations and EU CSRD disclosure enforcement intensity as inflection signals for procurement centralization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Processing | Corn starch compounders in Iowa and Illinois secure margin insulation against CBOT futures volatility. |
| Green Certification Program Expansion | TÜV and USDA audit infrastructure investments unlock EU-listed packaging converter procurement pipelines. |
| Long-term Supply Agreement with Automotive OEMs | Tier 2 seating suppliers in Bavaria lock in bio-polyurethane volumes against spot market exposure. |
| Joint Venture with Regional Equipment Distributors | Technical service partnerships in Gujarat reduce customer acquisition costs for starch ester adhesives. |
| Capacity Expansion in Yangtze River Delta | Shanghai-area compounders capture plywood manufacturing demand from furniture export clusters. |
Methodological Framework
Multiple input streams — primary interviews with adhesive formulation chemists, corrugated board procurement directors, and automotive Tier 2 supplier quality managers; secondary validation through EPA BioPreferred program databases, ECHA REACH registration filings, and European adhesive association technical reports; plus customs trade data for starch and polyol feedstock flows — were reconciled through bottom-up volume modeling and top-down market sizing triangulation.
Cross-referencing historical capacity utilization patterns against expert panel assessments of qualification timeline compression shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product chemistry type, end-use vertical, formulation technology, and regional regulatory cluster intensity. CAGRs were derived from elasticity-adjusted demand curves incorporating automotive lightweighting specifications and EU packaging mandate enforcement phasing. Industry-specific forecast inputs encompassed corn futures price trajectory assumptions and CSRD disclosure adoption rates among listed converters.
Underlying measurement precision varies by segment; water-based starch formulations for corrugated board carry tighter precision than emerging lignin-thermoset systems for engineered wood panels due to established production reporting. Forecasts reflect assumptions about regulatory enforcement consistency and agricultural yield stability that commodity price shocks or policy reversals could materially revise. Practitioners should monitor EPA BioPreferred program funding levels, EU carbon border adjustment implementation timing, and Brazilian corn harvest forecasts for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Flexible Packaging Adhesive Market
Adhesives & Sealants
Acrylic Glue Market
Adhesives & Sealants
Acrylate Market
Adhesives & Sealants
Singapore Adhesives Market
Adhesives & Sealants
Aviation Adhesives and Sealants Market
Adhesives & Sealants
Melamine Based Adhesives Market
Adhesives & Sealants
Middle East and Africa Bone Glue Market
Adhesives & Sealants
Vietnam Construction Chemicals Market
Adhesives & Sealants
France Adhesives Market
Adhesives & Sealants
Global Adhesive Coating Market
Adhesives & Sealants
Isobornyl Acrylate Market
Adhesives & Sealants
Low VOC Adhesive Market
Adhesives & Sealants
North America Automotive Adhesives and Sealants Market
Adhesives & Sealants
Solvent Based Laminating Adhesives Market
Adhesives & Sealants
Middle-East and Africa Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Global Bone Cement and Glue Market