
 Dispersion Adhesives Market | 2026-2036
Dispersion Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Dispersion Adhesives Market Outlook
Buyer fragmentation across mid-sized packaging converters and specialty woodworking shops is repositioning procurement patterns throughout the value chain. Henkel AG & Co. KGaA leverages its European distribution network to serve these dispersed accounts with tailored water-based acrylic lines. BASF SE anchors large-volume supply relationships with construction and automotive OEMs through integrated polymer production. Dow Inc. competes on technical service depth in North American flooring and laminating applications.
Dispersion adhesives are aqueous polymer emulsions—typically 40–60% solids content—formulated from polyvinyl acetate, ethylene vinyl acetate, acrylic, or urethane polymers that coalesce upon water evaporation to form bonded joints. They serve primary industrial purposes in porous substrate assembly, heat-sensitive material joining, and low-VOC emission environments where solvent-based systems face regulatory exclusion. Polyvinyl acetate dominates volume due to mature woodworking and paper-packaging demand, while acrylic and urethane dispersions command margin premiums in automotive interior bonding and resilient flooring where flexibility and moisture resistance prove critical. Water-based technology leads all platforms as environmental compliance hardens, though reactive urethane dispersions are gaining fastest in automotive laminating and high-performance coating segments.
EPA regulations in the United States restrict hazardous air pollutants from adhesive manufacturing, while REACH and the EU Green Deal in Europe enforce chemical safety registration and carbon footprint disclosure across formulation supply chains. ECHA substance evaluation protocols are pushing manufacturers toward bio-based monomer feedstocks and reduced formaldehyde content in construction-grade dispersions. Stakeholders must monitor evolving polymer classification thresholds under EU MDR and state-level VOC rules in California and New York, as compliance timing will determine which formulation platforms retain market access.
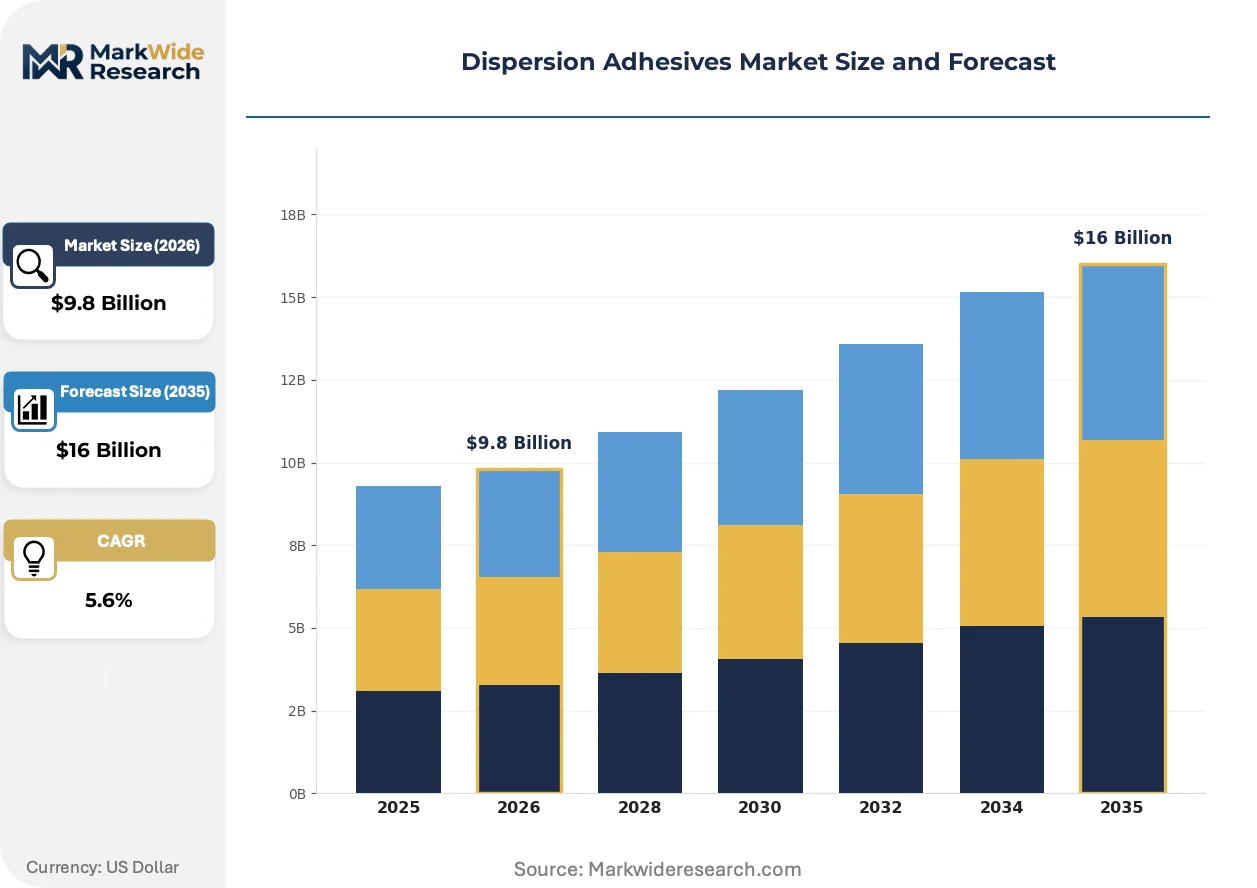
Market Dynamics
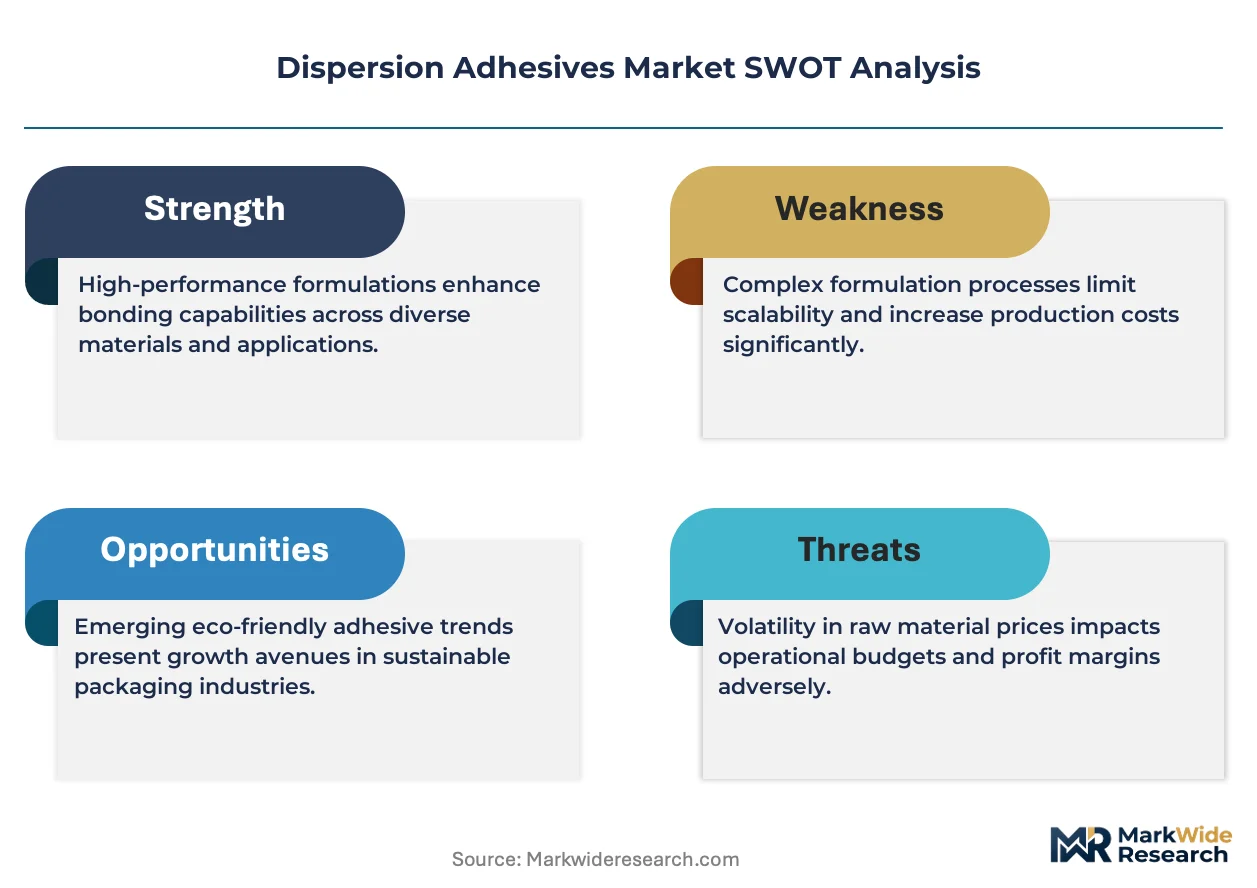
Water-based formulation mandates under REACH and the EU Green Deal are compressing solvent-based capacity while redirecting capital toward bio-based polymer development and VOC-compliant manufacturing infrastructure.
Growth Catalysts
- Automotive interior laminating:OEM specifications for low-emission cabin environments are accelerating urethane dispersion adoption in headliner and trim assembly across German and US production facilities.
- REACH chemical registration:Accelerated substance evaluation timelines are disqualifying legacy solvent systems and creating preferential market access for pre-registered aqueous formulations.
- Resilient flooring installation:Moisture-resistant acrylic dispersions are capturing specification share in luxury vinyl tile and engineered hardwood bonding applications.
Market Restraints
- Petrochemical feedstock volatility:Ethylene and propylene derivative costs for EVA and acrylic monomer production create margin compression without pass-through mechanisms.
- Specialty additive supply concentration:Defoamer and rheology modifier production clusters in Germany and the Netherlands expose formulators to single-source disruption risk.
- Cure rate limitations:Water evaporation kinetics restrict line speeds in high-throughput packaging converting versus hot-melt alternatives.
Strategic Opportunities
- Indian packaging converter base:Food-grade water-based adhesive penetration remains below Western levels despite BIS standards alignment and export-oriented capacity expansion.
- Reactive urethane dispersion chemistry:Crosslinking technology convergence with UV-curable systems opens automotive clear-coat lamination and electronics potting applications.
- EU Green Deal carbon border adjustments:Embedded emissions disclosure requirements favor regional bio-based feedstock sourcing and localized polymer production.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in colloidal stability and film-forming dynamics is concentrating at integrated polymer producers, constraining independent compounder scale-up.
- Multi-jurisdiction registration synchronization:Divergent EPA state-level VOC rules in California and New York versus ECHA substance evaluation timelines complicate unified product portfolio management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dispersion Adhesives Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $16 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyvinyl Acetate, Ethylene Vinyl Acetate, Urethane, Acrylic End User: Construction, Automotive, Packaging, Woodworking Application: Flooring, Bonding, Coating, Laminating Technology: Water-Based, Solvent-Based, Hot Melt, Reactive |
| Companies Covered | Arkema Group, H.B. Fuller Company, Henkel AG & Co. KGaA, The Lubrizol Corporation, Sika AG, BASF SE, Covestro AG, Wanhua Chemical Group Co., Ltd., Dow Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dispersion Adhesives Market Strategic Shifts
Formulation science is pivoting from incremental solids-content improvements toward radical feedstock substitution and process-integration redesigns that redefine competitive advantage.
Bio-based monomer feedstocks derived from corn starch and tall oil rosin are rewriting raw material sourcing strategies for polyvinyl acetate and acrylic dispersions. Flooring manufacturers in Germany and construction adhesive specifiers in the US are piloting these alternatives at commercial scale. The technology is rewriting cost structures by decoupling formulation economics from naphtha-cracker margins while introducing agricultural commodity exposure.
ECHA substance evaluation protocols under REACH are tightening formaldehyde content thresholds in construction-grade dispersions. Manufacturers are reformulating crosslinker packages and accelerating bio-based aldehyde scavenger development. Construction adhesive portfolios in Germany and France face the most immediate reformulation pressure, with classification changes triggering supply chain requalification cycles.
Specification-driven procurement consolidation is concentrating purchasing authority at packaging converters with dedicated sustainability compliance functions. Regional distributors serving mid-sized woodworking shops are losing share to direct manufacturer relationships with volume commitment tiers. The shift is most visible in German automotive supply chains and US flooring contractor networks where EPD documentation and VOC certification gates determine vendor eligibility.
Dispersion Adhesives Market Segmentation
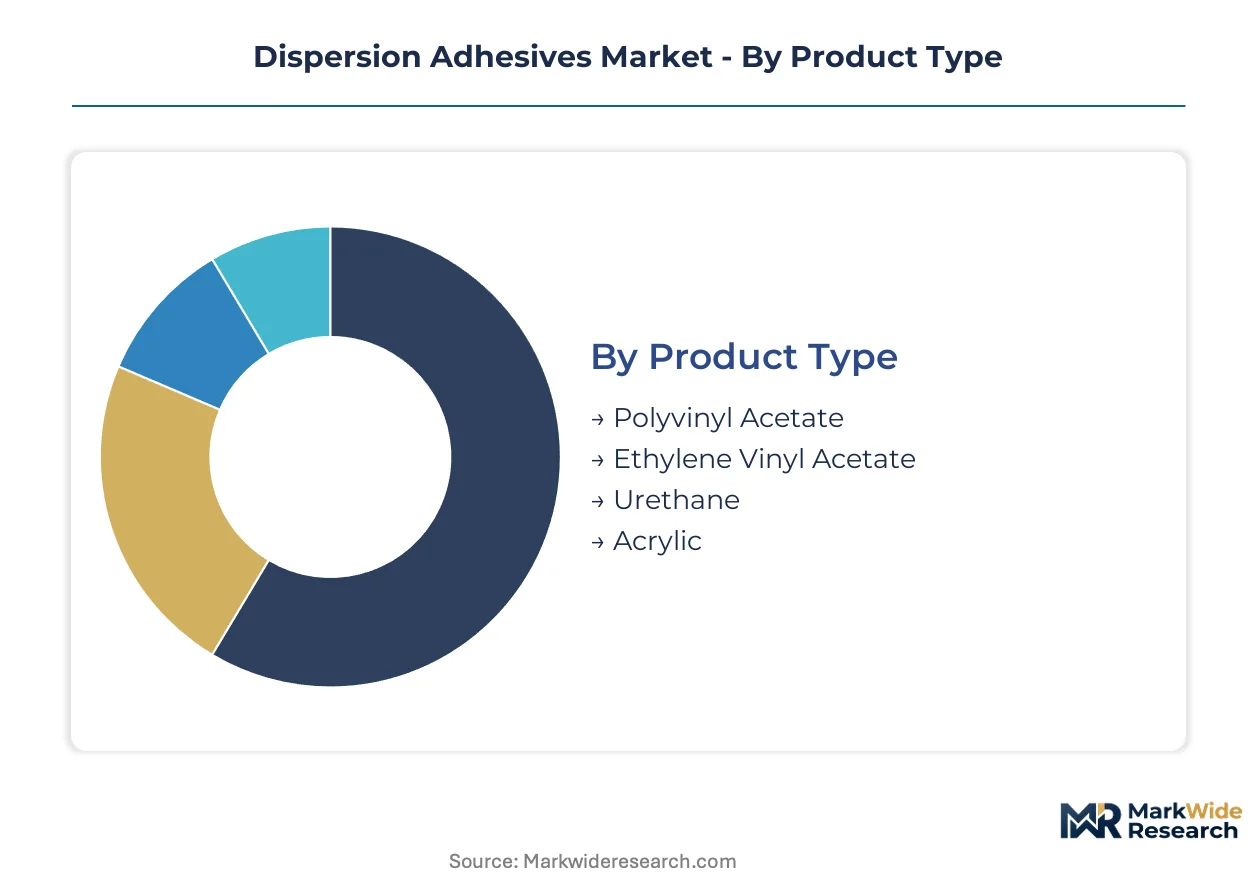
Segmentation in dispersion adhesives reveals how polymer chemistry, end-use specifications, and regulatory exposure create divergent margin profiles. Buyers select platforms based on substrate compatibility, emission constraints, and line-speed requirements rather than price alone.
Product Type:
Polymer supply concentrates at integrated petrochemical producers in Germany, the Netherlands, and Texas, creating tiered access to monomer feedstocks.
- Polyvinyl Acetate:Mature emulsion chemistry with 40-55% solids content dominates woodworking and paper-packaging assembly. German flooring manufacturers and US furniture producers anchor volume demand; REACH formaldehyde thresholds are forcing aldehyde-scavenger reformulation cycles.
- Acrylic:Copolymer dispersions with superior UV stability and moisture resistance command specification in luxury vinyl tile bonding and exterior construction membranes. Demand clusters in German resilient flooring supply chains and California-compliant construction applications where VOC limits are strictest.
- Urethane:Reactive systems with crosslinking capability serve automotive interior laminating and high-performance coating segments.
- Ethylene Vinyl Acetate:EVA emulsions balance cost and flexibility in general-purpose packaging and textile bonding.
Polyvinyl acetate absorbs the bulk of installed capacity; urethane is expanding most quickly.
End User:
Customer concentration varies sharply, with automotive OEMs and national packaging converters wielding specification authority over fragmented woodworking shops.
- Construction:Adhesive demand concentrates in flooring installation, tile bonding, and insulation membrane assembly. German construction chemical distributors and US regional contractor networks drive specification; ECHA substance evaluations and EPA state-level VOC rules determine product eligibility.
- Packaging:Water-based systems dominate paperboard lamination and flexible film converting. Mid-sized European converters and export-oriented Indian facilities are expanding capacity; BIS standards alignment and EU Green Deal carbon disclosure requirements shape procurement.
- Automotive:OEM cabin-air-quality protocols favor low-emission urethane dispersions for headliner, trim, and carpet bonding.
- Woodworking:Furniture and cabinetry assembly relies on PVA and PVAc emulsions with fast tack development.
Construction commands the deepest specification expertise; packaging is climbing the fastest as sustainability mandates harden.
Application:
Process requirements determine technology selection, with moisture resistance and cure speed acting as primary filters.
- Bonding:General-purpose assembly of porous substrates—wood, paper, textiles—represents the foundational use case. German woodworking clusters and Indian packaging corridors concentrate volume demand; water-based PVA and EVA systems face pressure from hot-melt alternatives in high-speed converting.
- Flooring:Acrylic and urethane dispersions provide moisture resistance and flexibility for luxury vinyl tile, engineered hardwood, and carpet installation. German manufacturers and US contractor networks specify products with EPD documentation and VOC certification.
- Laminating:Multi-layer film and decorative surface bonding requires controlled rheology and heat resistance.
- Coating:Protective and decorative film formation on paper, textiles, and wood substrates demands tailored film-forming temperature and gloss control.
Bonding retains the broadest installed base; flooring is gaining share fastest on resilient surface demand.
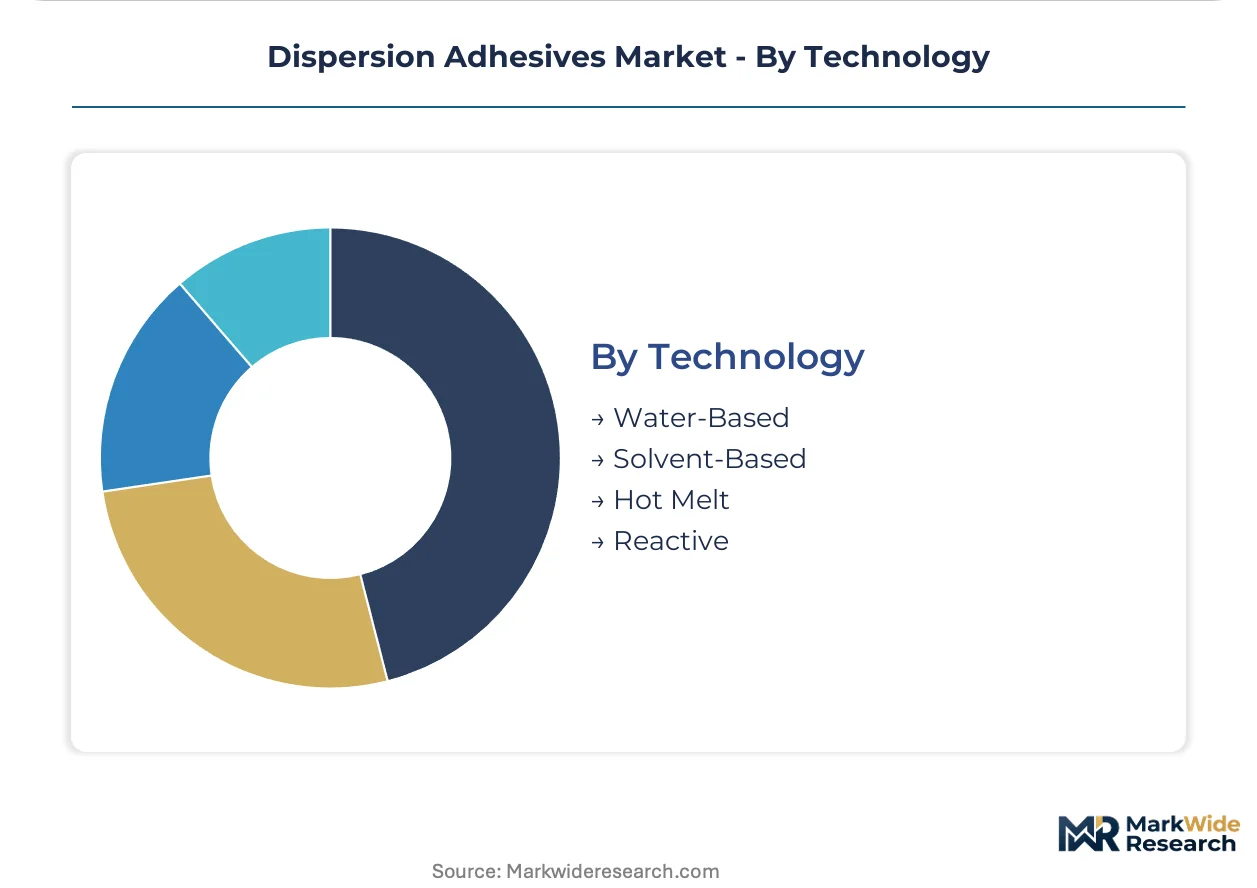
Technology:
Environmental compliance timelines are compressing solvent-based capacity while redirecting capital toward aqueous and reactive platforms.
- Water-Based:Aqueous polymer emulsions with 40-60% solids content lead all platforms under REACH and EPA regulatory pressure. German automotive OEMs and US flooring contractors specify these systems for low-VOC emission profiles; bio-based monomer feedstocks are penetrating at commercial scale.
- Reactive:Crosslinking urethane and silane-modified systems cure through moisture or thermal activation to deliver solvent-grade performance. German automotive laminating and electronics potting applications are piloting UV-convergent chemistry.
- Hot Melt:100% solids thermoplastic systems compete on cure speed in high-throughput packaging converting.
- Solvent-Based:Declining share as REACH registration deadlines and EU Green Deal protocols disqualify legacy formulations.
Water-based technology carries the majority of production investment; reactive systems are accelerating fastest on performance convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in manufacturing corridors where automotive OEMs, packaging converters, and flooring producers cluster near petrochemical feedstock sources and specialized formulation expertise.
Germany
Automotive interior laminating and resilient flooring installation drive urethane and acrylic dispersion consumption. REACH substance evaluation protocols under ECHA accelerate reformulation toward bio-based monomer feedstocks. The Cologne-Düsseldorf chemical corridor anchors integrated polymer production serving construction adhesive distributors and OEM specification networks.
United States
EPA state-level VOC rules in California and New York compress solvent-based capacity while redirecting procurement toward water-based systems. Flooring contractors in the Southeast and packaging converters in the Midwest specify low-emission formulations. The Gulf Coast petrochemical cluster supplies ethylene and propylene derivatives for EVA and acrylic emulsion production.
China
Dual carbon goals and MEE environmental enforcement tighten emission standards for adhesive manufacturing. Wanhua Chemical and domestic producers expand water-based capacity for construction and automotive applications. The Yangtze River Delta concentration of flooring manufacturers and electronics assemblers pulls in moisture-resistant dispersion formulations.
India
Export-oriented packaging converters in Maharashtra and Gujarat expand food-grade water-based adhesive capacity despite BIS standards alignment gaps. Construction activity in Delhi-NCR and Bangalore drives flooring and tile bonding demand. Domestic formulators face feedstock cost volatility from imported petrochemical monomers.
Japan
METI industrial standards and automotive OEM cabin-air-quality protocols favor low-emission urethane dispersions for headliner and trim assembly. Precision electronics potting applications in the Nagoya industrial corridor demand reactive crosslinking systems. Domestic producers maintain formulation expertise in colloidal stability and film-forming dynamics.
Dispersion Adhesives Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue bio-based feedstock specialization and regional compliance consulting services. The vendor base stratifies across integrated petrochemical conglomerates with captive polymer supply, mid-sized compounders serving niche specification markets, and regional distributors managing fragmented woodworking and packaging accounts. Three archetypes dominate: scale-driven integrated producers, technology-focused reactive system specialists, and sustainability-certified regional formulators. Competitive moves concentrate on backward integration into bio-based monomer production and strategic partnerships with automotive OEMs for specification lock-in.
Among European integrated chemical producers, BASF SE and Covestro AG exemplify the scale-driven archetype with upstream polymer production and direct OEM supply relationships. Henkel AG & Co. KGaA occupies a distinct position bridging formulation expertise and distribution reach to serve dispersed mid-sized accounts. Arkema Group and Sika AG represent the specialty tier, anchoring positions in reactive urethane and construction-grade applications where technical service depth determines vendor selection.
| Leading Market Players |
|---|
| Arkema Group |
| H.B. Fuller Company |
| Henkel AG & Co. KGaA |
| The Lubrizol Corporation |
| Sika AG |
| BASF SE |
| Covestro AG |
| Wanhua Chemical Group Co., Ltd. |
| Dow Inc. |
| Others |
Value Chain & Pricing Dynamics
Specialized formulation chemists concentrated in the Cologne-Düsseldorf corridor and Nagoya industrial zone command wage premiums that propagate through tiered pricing structures. REACH compliance costs and ECHA substance evaluation timelines widen spreads between premium reactive urethane systems and economy-grade PVA emulsions.
Pricing Analysis
Volume-mass polyvinyl acetate emulsions trade on thin margins anchored to naphtha-cracker economics, while reactive urethane dispersions capture substantial premiums in automotive laminating applications. Three-tier pricing structure across premium, standard, and economy levels separates EPD-certified low-VOC formulations from commodity woodworking grades. Price differentiation hinges on certification tier—REACH-registered and EPA-compliant systems command substantial premiums over non-registered alternatives. Cost compression in standard-grade PVA is intensifying because Indian packaging converters and mid-sized European distributors lack pass-through mechanisms for ethylene derivative volatility. Woodworking shops and general-purpose packaging converters exhibit highest price sensitivity, whereas German automotive OEMs and US flooring contractors prioritize emission certification over unit cost.
Supply Chain Analysis
EU Green Deal carbon border adjustments and domestic-content preferences in Indian BIS standards are redirecting sourcing toward regional bio-based feedstock networks. Production gravity centers on Germany, the United States, and China, with integrated petrochemical corridors in each anchoring monomer supply. Formulation draws from ethylene and propylene derivatives, tall oil rosin, and corn starch feedstocks. Single-source vulnerability clusters in German and Dutch specialty additive production—defoamer and rheology modifier capacity concentration exposes formulators to disruption. Distribution runs through construction chemical distributors in Germany, regional flooring contractor networks in the US Southeast, and export-oriented packaging corridors in Maharashtra and Gujarat.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as players pursue captive bio-based monomer production to decouple from petrochemical volatility and secure REACH-compliant feedstock access.
For Market Incumbents: Cement specification lock-in with German automotive OEMs and US flooring contractors through integrated EPD documentation and VOC certification services. Backward integration into tall oil rosin and corn starch processing secures bio-based feedstock supply against REACH substance evaluation disruptions. Capacity expansion in the Cologne-Düsseldorf corridor reinforces proximity to formulation chemist talent pools. For New Entrants and Emerging Players: Regional distributors serving fragmented woodworking shops in India and mid-tier packaging converters represent the most penetrable channel partner type for bypassing established direct-manufacturer relationships. Food-grade water-based adhesive penetration in Indian export corridors and reactive urethane dispersion adoption in Japanese electronics potting offer white-space entry points. Technical service partnerships with automotive laminating specialists provide credentialing pathways for specification-driven procurement networks. For Investors and Strategic Acquirers: The window for entry favors specialty reactive system formulators with crosslinking chemistry expertise and established ECHA pre-registration portfolios. Long-term viability centers on bio-based feedstock transition completion and carbon disclosure compliance capability. Watch for EU Green Deal carbon border adjustment implementation timing as the inflection signal determining regional production cost competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Monomers | Tall oil rosin and corn starch processing decouples formulation economics from naphtha-cracker margins. |
| REACH Pre-Registration Portfolio Expansion | ECHA substance evaluation timelines favor pre-registered aqueous formulations over legacy solvent systems. |
| EPD Documentation and VOC Certification Investment | German automotive OEMs and US flooring contractors gate vendor eligibility on emission disclosure compliance. |
| Reactive Urethane Dispersion Capacity Buildout | Crosslinking technology convergence with UV-curable systems opens automotive clear-coat lamination applications. |
| Regional Production Footprint in India | BIS standards alignment and export-oriented packaging converter expansion create localized supply advantages. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with adhesive formulation chemists, procurement leads at automotive OEMs, construction chemical distributors, and technical R&D directors at integrated polymer producers were cross-referenced against ECHA substance evaluation databases, EPA state-level VOC rule compilations, and Cefic sector reports. Bottom-up segment sizing triangulated with top-down demand modeling across polymer chemistry, end-use application, and geographic production clusters.
Granularity-level framing applied country-specific regulatory compliance timelines and feedstock cost structures to each polymer platform. Segmentation dimensions modeled included polymer chemistry tier, end-use industry concentration, technology platform adoption curves, and regional manufacturing hub characteristics. CAGRs were derived from installed capacity trajectories, substitution elasticity estimates for solvent-based systems, and specification-driven procurement consolidation patterns. Industry-specific forecast inputs incorporated REACH registration deadline pacing and EU Green Deal carbon border adjustment implementation sequencing.
Caveats apply where ECHA substance evaluation reclassifications, petrochemical feedstock volatility spikes, or Indian BIS standards enforcement acceleration could materially shift the outlook. Forecasts reflect assumptions about regulatory compliance timing, bio-based monomer scale-up rates, and automotive OEM specification stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Global Adhesion Promoter Market
Adhesives & Sealants
Global Concrete Bonding Agents Market
Adhesives & Sealants
Malaysia Adhesives and Sealants Market
Adhesives & Sealants
Polyurethane (PU) Hot-Melt Adhesive Market
Adhesives & Sealants
Middle East and Africa Adhesives Market
Adhesives & Sealants
Butyl Adhesive Market
Adhesives & Sealants
Asia-Pacific Contact Adhesives Market
Adhesives & Sealants
Global Footwear Adhesives Market
Adhesives & Sealants
US Pressure Sensitive Adhesives Market
Adhesives & Sealants
Global Adhesion Barrier Market
Adhesives & Sealants
Lead Encapsulants Market
Adhesives & Sealants
Conductive Glue Market
Adhesives & Sealants
Malaysia Adhesives Market
Adhesives & Sealants
North America Waterborne Adhesives Market
Adhesives & Sealants
United Kingdom Adhesives Market
Adhesives & Sealants
North America Construction Adhesives and Sealants Market