
 US Pressure Sensitive Adhesives Market | 2026-2036
US Pressure Sensitive Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
US Pressure Sensitive Adhesives Market Insights
ASTM D3330 peel adhesion certification is bifurcating the competitive landscape into qualified suppliers and commodity producers. 3M leverages its materials science depth to sustain premium positioning across electronics and medical tapes. H.B. Fuller Company anchors its presence through backward integration into polymer synthesis, securing formulation control. Avery Dennison Corporation differentiates via direct channel relationships with Fortune 500 packaging buyers, reducing distributor dependency.
Pressure sensitive adhesives bond surfaces through viscoelastic flow under light pressure without solvent activation or heat curing, typically formulated with tackifying resins, elastomers, and plasticizers in acrylic, silicone, or rubber bases. Water-based acrylic emulsions dominate volume in labels and flexible packaging where FDA indirect food contact compliance matters, while hot melt systems capture share in logistics tapes driven by e-commerce fulfillment speed requirements. Radiation-curable formulations command premium pricing in electronics applications demanding optical clarity and thermal stability.
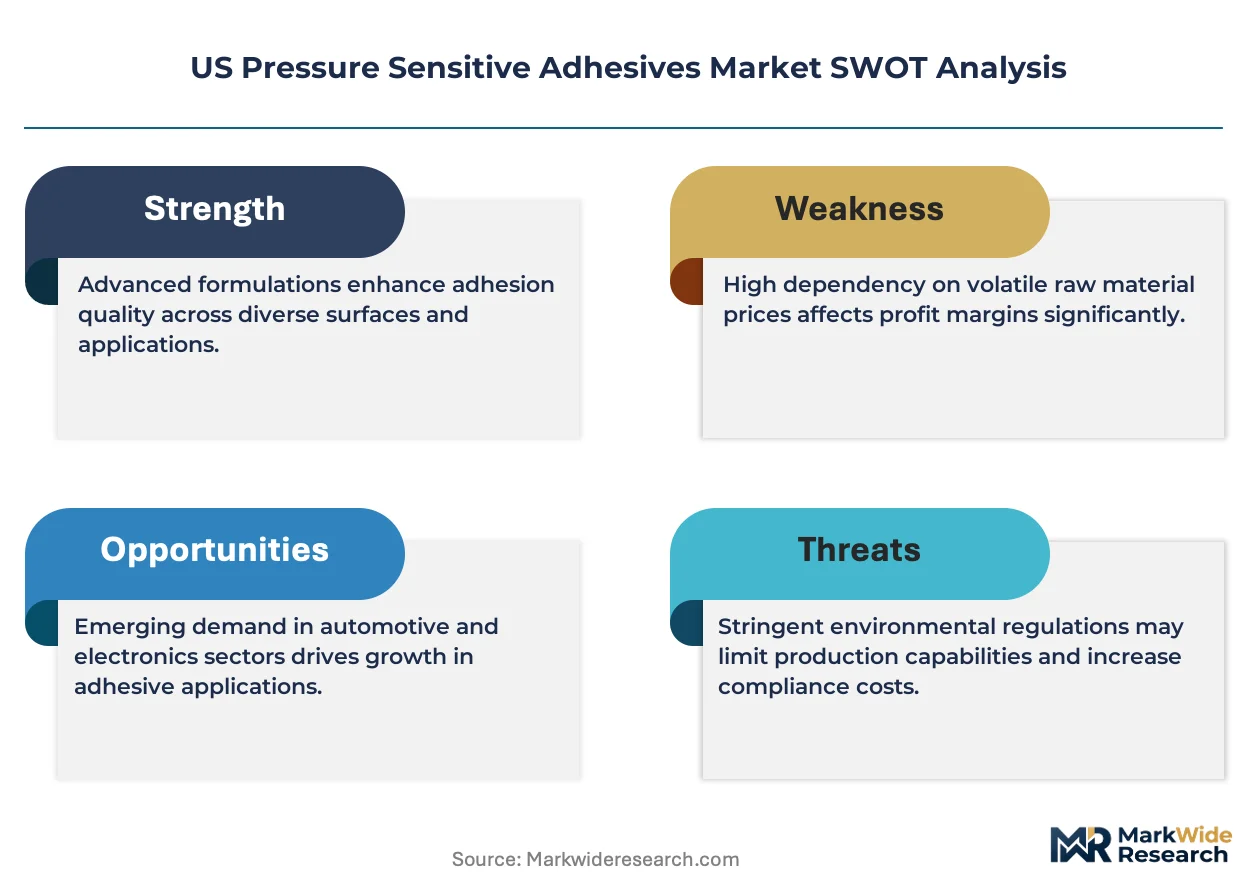
EPA VOC emission standards under the Clean Air Act constrain solvent-based production, while OSHA workplace exposure limits push manufacturers toward enclosed hot melt systems. FDA 21 CFR 175.105 adhesive regulations govern food-contact applications, creating compliance barriers for imported formulations. Buyers must monitor state-level extended producer responsibility legislation in California and New York, which threatens to restructure labeling waste economics and adhesive recyclability requirements.
Market Dynamics
Automotive electrification is restructuring adhesive demand patterns across battery assembly lines and lightweight structural bonding, while EPA VOC enforcement under the Clean Air Act accelerates formulation chemistry shifts from solvent-based systems toward water-based acrylics and hot melt alternatives.
Growth Catalysts
- IRA clean vehicle tax credits:Domestic battery production incentives are expanding adhesive consumption in cell-to-pack bonding and thermal interface materials across Michigan and Ohio assembly plants.
- E-commerce fulfillment velocity:Logistics hubs in Tennessee and Kentucky are driving hot melt tape volumes for automated carton sealing and same-day shipment processing.
- Medical device miniaturization:Wearable health monitors and transdermal drug delivery systems are pulling silicone adhesive demand toward skin-contact biocompatibility standards.
Market Restraints
- Petrochemical feedstock volatility:Acrylic monomer and tackifying resin prices fluctuate with crude oil indices, compressing margin stability for mid-tier formulators.
- Southeast production concentration:Georgia and South Carolina host disproportionate tape and label capacity, creating hurricane exposure and logistics bottleneck risks.
- Hot melt temperature performance ceilings:Polyolefin and EVA-based systems soften above 80°C, excluding them from under-hood automotive applications requiring silicone or acrylic alternatives.
Strategic Opportunities
- Texas Gulf Coast petrochemical integration:Proximity to propylene and ethylene crackers enables backward integration into acrylic monomer production, capturing margin from raw material through formulated adhesive.
- California extended producer responsibility mandates:Label waste regulations are creating demand for recyclable and repulpable adhesive formulations that separate cleanly from fiber substrates.
- UV-LED curing convergence:Electronics manufacturers are combining radiation-curable adhesives with mini-LED assembly processes for display bonding applications.
Industry Challenges
- FDA 21 CFR 175.105 compliance timelines:Food-contact adhesive certifications require 18-24 month validation cycles, delaying new product commercialization for packaging converters.
- Skilled polymer chemist scarcity:Formulation expertise in viscoelastic design and tackifier-elastomer compatibility commands premium compensation, constraining R&D expansion.
- Legacy solvent equipment stranded costs:Converting production lines from solvent-based to water-based or hot melt systems requires $2-5 million per facility in drying and application infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Pressure Sensitive Adhesives Market |
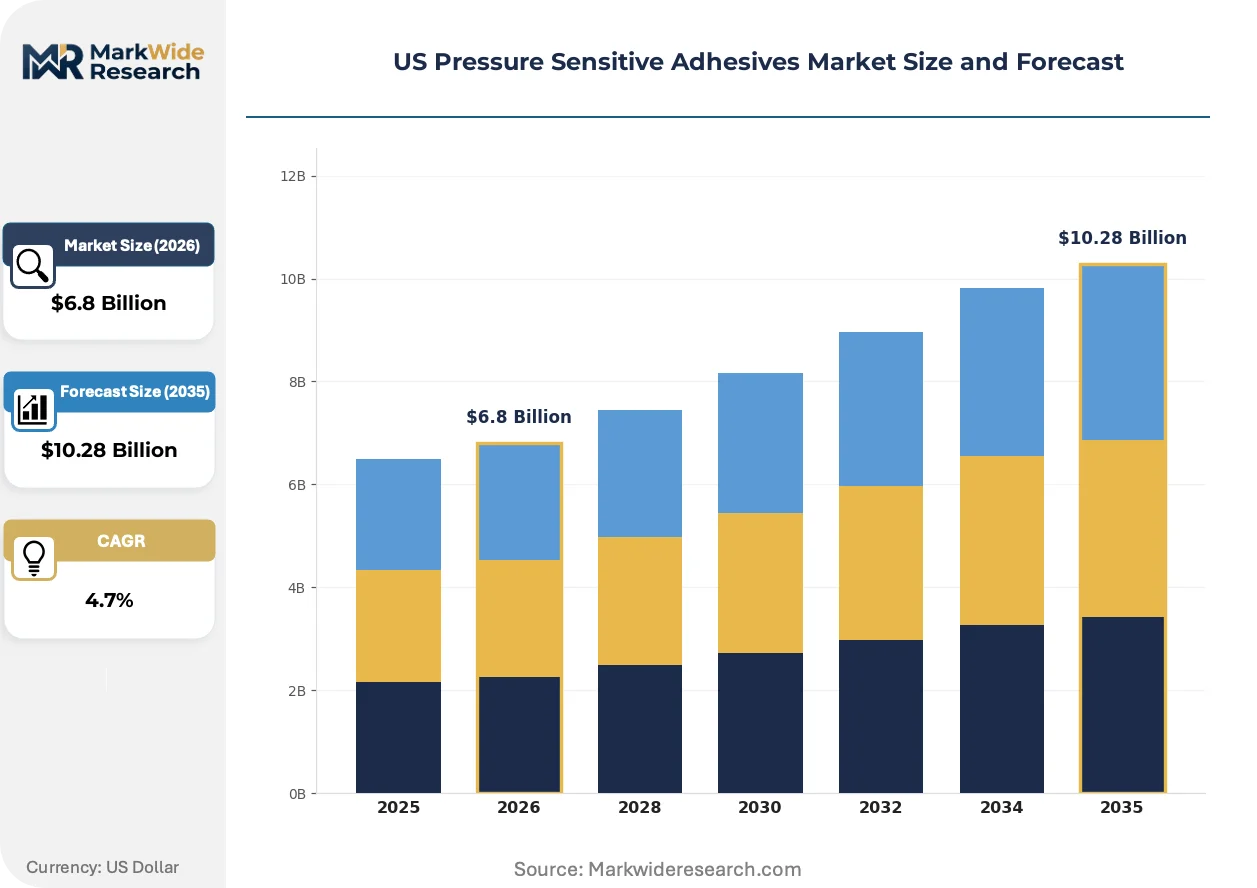
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, Hot Melt, Radiation-Curable End User: Automotive, Electronics, Healthcare, Packaging Application: Labels, Tapes, Graphics, Surface Protection Formulation: Polymer-Based, Acrylic, Silicone, Others |
| Companies Covered | Dow, Arkema, 3M, tesa SE, Sika AG, Avery Dennison Corporation, Henkel AG & Co. KGaA, Nitto Denko Corporation, H.B. Fuller Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Pressure Sensitive Adhesives Market Trends and Innovations
Formulation chemistry is pivoting toward energy-efficient curing mechanisms and bio-based feedstocks, while regulatory pressure and end-use performance requirements are segmenting the competitive landscape into specialized qualification tiers.
Water-based acrylic emulsions are capturing volume in flexible packaging and pressure-sensitive labels where FDA indirect food contact compliance is mandatory. Major converters in Wisconsin and Illinois are retrofitting coating lines to handle higher solids content emulsions that reduce drying energy. This technology is bifurcating the supplier base into qualified food-contact certified producers and commodity generalists locked out of premium segments.
EPA enforcement of National Emission Standards for Hazardous Air Pollutants is constraining solvent-based adhesive production capacity in legacy manufacturing corridors. Formulators face capital decisions on enclosed hot melt systems or aqueous conversions to maintain operating permits. California Air Resources Board district rules are tightening most aggressively, pushing coastal producers toward zero-VOC alternatives ahead of federal timelines.
Direct procurement relationships between Fortune 500 packaging buyers and specialized adhesive formulators are displacing traditional distributor networks. Large CPG manufacturers in Minnesota and New Jersey are consolidating supplier bases, demanding formulation customization and technical service co-location. This channel consolidation concentrates volume with qualified suppliers capable of ASTM D3330 peel adhesion certification and lot-to-lot consistency guarantees.
US Pressure Sensitive Adhesives Market Segmentation
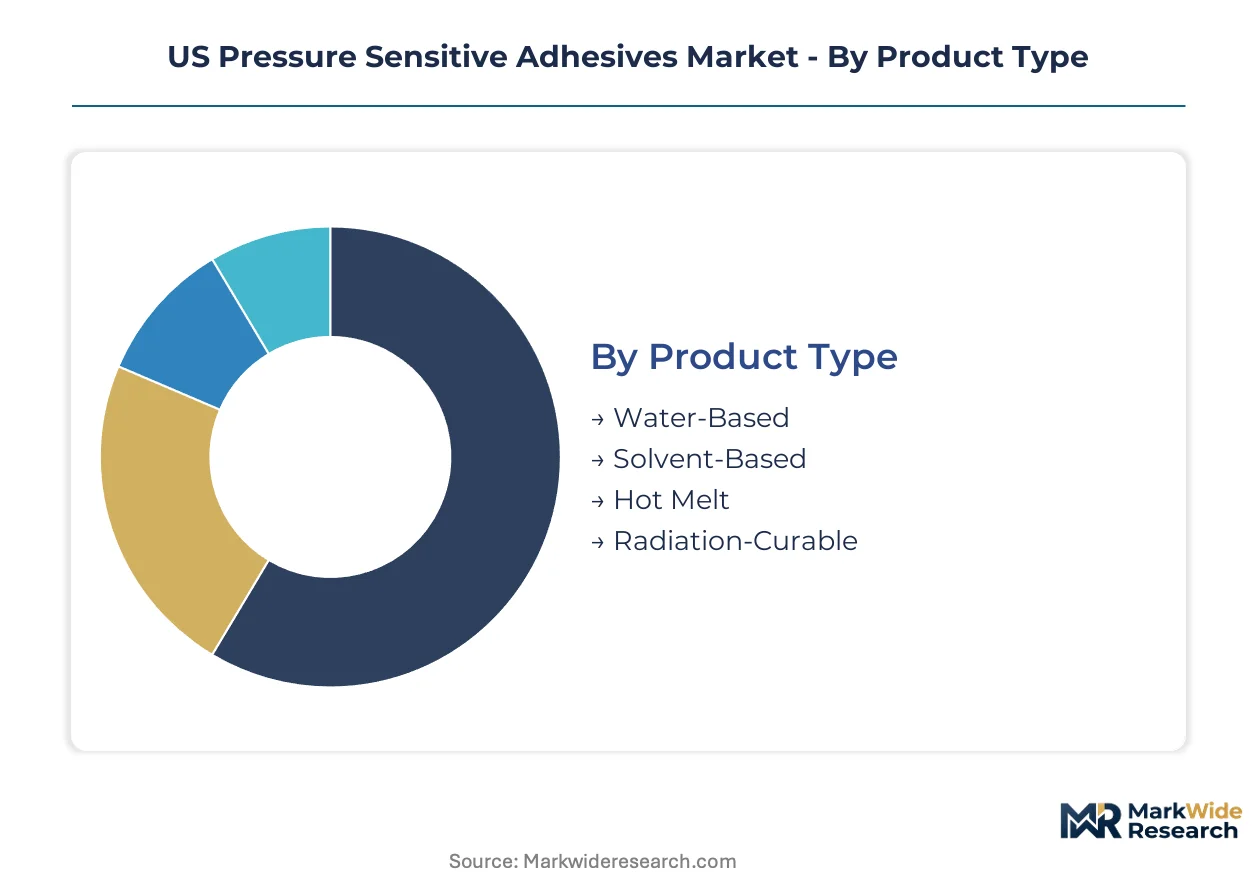
Segmentation in the US pressure sensitive adhesives market reveals how formulation chemistry, end-use performance requirements, and regulatory compliance reshape procurement patterns across distinct buyer channels. Each dimension carries implications for margin structure, certification burden, and supply chain configuration.
Product Type:
Water-based and hot melt formulations flow through high-volume packaging distributors serving e-commerce fulfillment centers, while radiation-curable and solvent-based systems route through specialized electronics and industrial adhesives channels demanding technical service support.
- Water-Based:Acrylic emulsions formulated at 40-60% solids content serve flexible packaging and label applications where FDA 21 CFR 175.105 indirect food contact compliance is mandatory. Wisconsin and Illinois converters are retrofitting coating lines to handle higher solids emulsions that reduce drying energy consumption. Demand concentrates in the Southeast manufacturing corridor where major CPG packaging buyers cluster.
- Hot Melt:Polyolefin and EVA-based systems applied at 150-180°C bond instantly without drying, capturing logistics tape volumes in Tennessee and Kentucky fulfillment hubs. Automated carton sealing lines favor these formulations for same-day shipment processing velocity. Temperature performance ceilings above 80°C exclude under-hood automotive applications.
- Solvent-Based:Solutions of natural rubber or synthetic elastomers in organic carriers deliver aggressive tack and shear resistance for heavy-duty industrial tapes. EPA National Emission Standards for Hazardous Air Pollutants constrain production capacity in legacy manufacturing corridors.
- Radiation-Curable:UV or electron-beam initiated polymerization yields optical clarity and thermal stability for electronics display bonding and medical device assembly. California Air Resources Board district rules push coastal producers toward these zero-VOC alternatives.
Water-based systems dominate installed base across packaging and label segments. Radiation-curable formulations represent the fastest-growing trajectory as electronics miniaturization demands precision bonding.
End User:
Automotive and electronics buyers command premium pricing tiers through direct procurement relationships, while healthcare and packaging segments consolidate volume through distributor networks with formulation customization capabilities.
- Automotive:Battery assembly applications pull acrylic and silicone adhesives for cell-to-pack bonding and thermal interface materials in Michigan and Ohio IRA-incentivized plants. Lightweight structural bonding in body-in-white assembly replaces mechanical fasteners. OEM qualification cycles extend 24-36 months.
- Electronics:Display lamination, mini-LED assembly, and flexible circuit bonding demand radiation-curable formulations with optical clarity and dielectric stability. UV-LED curing convergence enables miniaturization without thermal damage to sensitive components.
- Healthcare:Transdermal drug delivery systems and wearable health monitors require silicone adhesives meeting ISO 10993 biocompatibility standards for skin-contact applications. FDA device regulations govern adhesive selection in Minnesota and New Jersey medical device manufacturing clusters.
- Packaging:Label and flexible packaging converters in Georgia and South Carolina drive water-based acrylic volume for food-contact compliance. California extended producer responsibility mandates are creating demand for recyclable and repulpable adhesive formulations.
Packaging commands the largest volume footprint. Automotive electrification is where expansion concentrates most steeply.
Application:
Labels and tapes generate recurring consumable demand through established distribution channels, while graphics and surface protection applications require specialized technical sales support for project-based procurement.
- Labels:Pressure-sensitive facestock constructions for prime labels, shipping labels, and variable information printing constitute the highest-volume adhesive application. Direct thermal and thermal transfer coatings demand precise release and adhesion balance.
- Tapes:Carton sealing, masking, and industrial bonding tapes span commodity logistics grades through high-performance aerospace and electronics specifications. Automated application equipment favors consistent unwind and adhesion properties.
- Graphics:Vehicle wraps, signage, and architectural films require repositionable adhesives with clean removability windows ranging from hours to years. Air-egress channels and bubble-free application characteristics differentiate premium grades.
- Surface Protection:Temporary films for electronics displays, appliance surfaces, and automotive paint guard against scratching and contamination during manufacturing and transit. Low-adhesion silicones prevent residue transfer upon removal.
Tapes anchor the installed base across industrial and logistics segments. Labels are climbing the fastest as e-commerce shipping volumes expand.
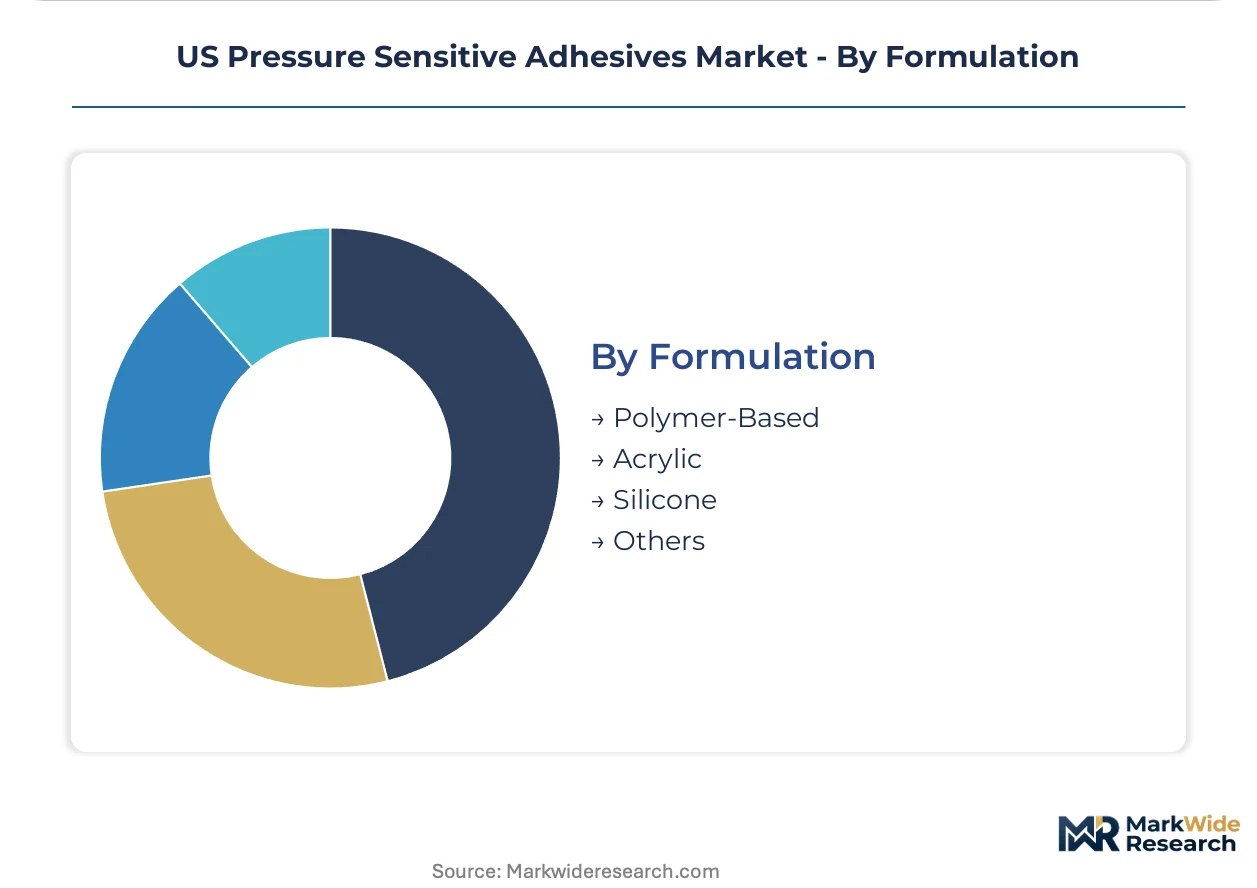
Formulation:
Acrylic and silicone formulations command premium positioning through proprietary polymer synthesis and qualification barriers, while commodity polymer-based systems compete on scale and raw material cost management.
- Polymer-Based:Natural rubber, SBR, and block copolymer formulations deliver high tack and shear strength for industrial tape applications. Petrochemical feedstock volatility compresses margin stability for mid-tier formulators dependent on spot market monomer purchases.
- Acrylic:Emulsion and solvent-borne acrylic polymers offer UV resistance, aging stability, and broad substrate adhesion for outdoor signage and automotive applications. Texas Gulf Coast propylene integration enables backward integration into monomer production.
- Silicone:Polydimethylsiloxane-based adhesives withstand temperature extremes from -60°C to 260°C, serving aerospace, electronics, and medical applications where thermal stability and chemical resistance are critical. Biocompatibility grades command substantial premiums.
- Others:Polyurethane, polyamide, and hybrid formulations address niche performance gaps in high-moisture or chemically aggressive environments. Development activity concentrates in radiation-curable modifications.
Acrylic formulations dominate the installed base across packaging and industrial segments. Silicone is gaining share fastest in electrification and healthcare applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
IRA clean vehicle tax credits are redirecting adhesive demand toward Michigan and Ohio battery plants, while EPA VOC enforcement accelerates formulation shifts across state manufacturing corridors.
Southeast Manufacturing Corridor
Georgia and South Carolina host disproportionate tape and label capacity serving CPG packaging buyers. EPA National Emission Standards for Hazardous Air Pollutants constrain solvent-based production in coastal facilities. Atlanta and Greenville-Spartanburg clusters are retrofitting coating lines for water-based acrylic emulsions to maintain operating permits.
Great Lakes Automotive Belt
Michigan and Ohio assembly plants consume acrylic and silicone adhesives for cell-to-pack bonding and thermal interface materials. IRA domestic battery production incentives are expanding consumption across Detroit and Toledo manufacturing zones. OEM qualification cycles extend 24-36 months, locking in supplier relationships.
Texas Gulf Coast
Proximity to propylene and ethylene crackers enables backward integration into acrylic monomer production. Houston and Beaumont petrochemical complexes supply raw material feedstock for formulated adhesive manufacturing. Formulators capture margin from captive monomer through finished product.
California Coastal Zone
Air Resources Board district rules push producers toward zero-VOC alternatives ahead of federal timelines. Los Angeles and Bay Area converters demand recyclable and repulpable adhesive formulations under extended producer responsibility mandates. UV-curable systems gain share in electronics display bonding applications.
Tennessee-Kentucky Logistics Hub
Memphis and Louisville fulfillment centers drive hot melt tape volumes for automated carton sealing. E-commerce shipment processing velocity favors instant-bonding polyolefin and EVA-based systems. Distribution infrastructure concentrates procurement with qualified suppliers capable of lot-to-lot consistency guarantees.
US Pressure Sensitive Adhesives Market Competitive Landscape
Listed leaders compete with private specialists across formulation chemistry and qualification tiers, producing a bifurcated structure where certified suppliers capture premium segments. The vendor base separates into three archetypes: diversified materials conglomerates with polymer synthesis depth, specialized adhesive formulators with direct Fortune 500 relationships, and regional converters competing on scale and raw material cost management. Dominant competitive moves include backward integration into monomer production and strategic consolidation of distributor networks into direct procurement channels.
Within the diversified materials tier, 3M and Dow exemplify integrated players leveraging captive technology portfolios across electronics and automotive applications. H.B. Fuller Company occupies a position among specialized formulators with emphasis on polymer synthesis control and technical service co-location. Avery Dennison Corporation anchors the direct-channel segment, reducing distributor dependency through consolidated relationships with large packaging buyers. These three represent distinct competitive vectors: materials science depth, formulation customization, and channel consolidation.
| Leading Market Players |
|---|
| Dow |
| Arkema |
| 3M |
| tesa SE |
| Sika AG |
| Avery Dennison Corporation |
| Henkel AG & Co. KGaA |
| Nitto Denko Corporation |
| H.B. Fuller Company |
| Others |
Pricing and Supply Chain Analysis
Water-based acrylic emulsions replacing solvent-based systems in Georgia and South Carolina coating lines simultaneously concentrate supply in the Southeast manufacturing corridor and compress margin structures for legacy producers lacking FDA 21 CFR 175.105 certification. This substitution dynamic redistributes pricing power toward qualified suppliers while stranding capital in enclosed hot melt retrofits.
Pricing Analysis
Certification level under FDA 21 CFR 175.105 creates the primary spread between premium and commodity tiers. Three-tier pricing structure across premium, standard, and economy levels dominates, with ASTM D3330 peel adhesion qualification and indirect food-contact compliance as the key differentiation drivers. Cost compression in mid-tier water-based formulations is intensifying because of acrylic monomer feedstock volatility tied to Gulf Coast propylene pricing. Large CPG packaging buyers in Minnesota and New Jersey exhibit lowest price sensitivity due to consolidation-driven supplier base reduction, while regional logistics converters in Tennessee and Kentucky face highest sensitivity from automated carton sealing volume pressures.
Supply Chain Analysis
Strategic stockpiling of tackifying resins and acrylic monomers prevails over just-in-tight inventory among qualified suppliers facing 18-24 month FDA validation cycles. Supply concentrates in the United States, with Texas Gulf Coast propylene crackers and Southeast coating corridors as primary nodes. Raw material dependencies center on petroleum-derived acrylic monomers, rosin ester tackifiers, and silicone polymers sourced from Dow Corning facilities. Single-source vulnerability runs through Gulf Coast petrochemical complexes exposed to hurricane disruption. Distribution runs through direct procurement channels consolidating Fortune 500 packaging relationships, displacing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation expertise in viscoelastic design and tackifier-elastomer compatibility represents the critical scarcity constraining R&D expansion across the competitive landscape. Qualified polymer chemists command premium compensation, creating defensive moats for incumbents with established technical teams.
For Market Incumbents: Secure backward integration into Texas Gulf Coast propylene supply to capture margin from monomer through formulated adhesive, insulating against petrochemical feedstock volatility. Defend qualification moats by accelerating ASTM D3330 certification investments before EPA VOC enforcement tightens further in coastal districts. Channel control through direct Fortune 500 relationships reduces distributor dependency and locks in volume against emerging specialized formulators. For New Entrants and Emerging Players: FDA 21 CFR 175.105 fast-track consulting partnerships with Wisconsin and Illinois converters offer the most penetrable entry path into food-contact packaging segments. Target California extended producer responsibility mandates driving recyclable adhesive demand as a regulatory-forced white space. Go-to-market positioning as zero-VOC specialty suppliers to coastal electronics manufacturers leverages CARB district rules ahead of federal timelines. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier formulators in Georgia and South Carolina lacking water-based conversion capital. Long-term viability over the next decade hinges on regulatory compliance infrastructure rather than scale economics alone. Watch EPA enforcement intensity in legacy manufacturing corridors as the inflection signal for stranded solvent-equipment write-downs and distressed acquisition opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Production | Captures margin from Texas Gulf Coast propylene through formulated adhesive, insulating against feedstock volatility. |
| FDA 21 CFR 175.105 Certification Investment | Unlocks premium packaging segments with 18-24 month validation cycles creating supplier lock-in. |
| Direct Channel Consolidation | Reduces distributor dependency through Fortune 500 co-location and technical service partnerships. |
| Zero-VOC Formulation Pivot | Aligns with CARB district rules and EPA NESHAP enforcement ahead of compliance deadlines. |
| Recyclable Adhesive Development | Addresses California extended producer responsibility mandates for clean fiber substrate separation. |
Research Methodology
A standing panel of adhesive formulators, packaging converter procurement leads, automotive OEM platform engineers, and EPA regulatory affairs specialists provided ongoing calibration across the study period. Primary interviews with plant managers at Tennessee and Kentucky logistics hubs, technical R&D directors at Southeast coating facilities, and distribution channel partners in the Great Lakes automotive belt combined with secondary validation from SEC 10-K filings, customs and trade data, American Chemistry Council reports, and FDA 510(k) adhesive submissions. Bottom-up volume modeling triangulated against top-down value estimates from industry association benchmarks.
Consistency checks against external production databases and regional manufacturing surveys validated output ranges across the projection horizon. The analytical framework modeled formulation chemistry, end-use industry vertical, regional production hub clustering, and certification tier as primary segmentation dimensions. CAGRs derived from historical growth pattern analysis and forward-looking capacity expansion announcements, with IRA clean vehicle tax credit impact and e-commerce fulfillment velocity as industry-specific demand inputs.
The analysis sits within stated boundaries; outcomes outside sustained IRA incentive structures or accelerated EPA enforcement timelines would require recalibration. Forecasts reflect assumptions regarding acrylic monomer supply continuity and Southeast hurricane frequency patterns. Revision becomes warranted when Gulf Coast petrochemical disruption crosses thresholds affecting national feedstock availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Butyl Adhesive Market
Adhesives & Sealants
Asia-Pacific Automotive Adhesives and Sealants Market
Adhesives & Sealants
Central Reinforced Tape Market
Adhesives & Sealants
Polyurethane (PU) Adhesives in Electronics Market
Adhesives & Sealants
Global Ethyl Methacrylate (97-63-2) Market
Adhesives & Sealants
Middle-East and Africa Cyanoacrylate Adhesives Market
Adhesives & Sealants
Wearable Adhesives Market
Adhesives & Sealants
UV Cured Adhesives Market
Adhesives & Sealants
Paper-Backing Abrasive Adhesive Discs Market
Adhesives & Sealants
Hydrophobic Pore-Blocking Agents for Waterproof Concrete Market
Adhesives & Sealants
South America Adhesives and Sealants Market
Adhesives & Sealants
Fuel Resistant Sealant Market
Adhesives & Sealants
Floor Tile Adhesive Market
Adhesives & Sealants
Temporary Bonding Adhesives Market
Adhesives & Sealants
Middle-East and Africa Electronics Adhesives Market
Adhesives & Sealants
Middle-East and Africa Acrylic Adhesives Market