
 Global Vascular Sealant Market | 2026-2036
Global Vascular Sealant Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vascular Sealant Market Foresight
EU MDR is repositioning the cost-of-entry calculus for vascular sealant manufacturers seeking CE marking in Europe. Baxter International leverages its plasma-derived fibrin portfolio to sustain leadership across cardiac and vascular surgical segments. Johnson & Johnson (Ethicon) anchors its competitive stance through broad suture-adhesive bundling with hospital procurement networks. CryoLife differentiates via cryopreserved biological platforms that navigate stringent biocompatibility thresholds.
Vascular sealants comprise topical hemostatic agents formulated from fibrinogen, thrombin, synthetic polymers, or collagen matrices that polymerize upon tissue contact to achieve rapid bleeding control. These products typically achieve hemostasis within three to five minutes and degrade via enzymatic pathways over seven to fourteen days, serving primarily to reduce transfusion requirements and operative time in open and minimally invasive procedures. Fibrin sealants occupy the largest revenue pool owing to established surgeon familiarity and extensive clinical validation across cardiovascular applications. Synthetic sealants represent the fastest-expanding category as polyethylene glycol and cyanoacrylate formulations gain traction in neurosurgery and thoracic procedures where blood-borne pathogen transmission risks deter biological products. Albumin-based sealants command premium positioning in Europe where REACH-compliant sourcing and EMA biologics licensing reinforce margin structures.
FDA 510(k) clearance pathways and EMA MDR compliance frameworks govern product authorization, while ISO 10993 biocompatibility standards dictate cytotoxicity and sensitization testing protocols for all implantable formulations. Japan's PMDA maintains distinct clinical trial requirements that extend registration timelines for foreign manufacturers relative to domestic entrants. Stakeholders must monitor evolving reimbursement classifications for adjunct hemostasis in bundled payment environments and assess synthetic platform investments against biological supply chain vulnerabilities in plasma fractionation.
Market Dynamics
EU MDR biocompatibility documentation requirements are compressing the addressable manufacturer base for vascular sealants in Europe, favoring plasma fractionation incumbents with established ISO 10993 testing infrastructure over synthetic platform entrants.
Growth Catalysts
- Aging procedural demographics:Cardiovascular surgery volumes in tertiary hospitals across the United States, Germany, and Japan are expanding the installed base for adjunct hemostasis. Fibrin sealant familiarity among cardiac surgeons sustains repeat purchasing.
- Synthetic polymer advancement:Polyethylene glycol and cyanoacrylate formulations are displacing biological products in neurosurgery and thoracic suites where blood-borne pathogen transmission risks constrain fibrin adoption.
- REACH-compliant sourcing mandates:European albumin-based sealant manufacturers command premium positioning through EMA biologics licensing and compliant supply chains, reinforcing margin structures against commoditization.
Market Restraints
- Plasma fractionation concentration:Biological sealant supply chains depend on concentrated plasma collection networks in the United States and Germany, exposing manufacturers to raw material volatility and donor pool constraints.
- PMDA registration timelines:Japan's distinct clinical trial requirements for foreign manufacturers extend market entry timelines relative to domestic entrants, compressing revenue recognition windows.
- Mechanical hemostasis substitution:Advanced energy devices and topical hemostatic powders in minimally invasive procedures reduce sealant attachment rates in laparoscopic and robotic surgery suites.
Strategic Opportunities
- Underpenetrated thoracic expansion:Lung resection and esophageal surgery in China represent white-space applications where synthetic sealant platforms can bypass biological supply chain dependencies.
- Bundled payment tailwinds:United States hospital procurement networks are consolidating suture-adhesive purchasing, creating volume leverage points for integrated hemostasis suppliers.
- Cryopreserved biological convergence:Cryopreservation technology combined with collagen matrix platforms navigates stringent EU biocompatibility thresholds while extending shelf stability against lyophilized alternatives.
Industry Challenges
- ISO 10993 certification timelines:Cytotoxicity and sensitization testing protocols for implantable formulations extend product development cycles, delaying revenue conversion from R&D investment.
- Legacy procurement system integration:Hospital ERP and materials management platforms require custom API development for sealant inventory tracking, raising implementation friction for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vascular Sealant Market |
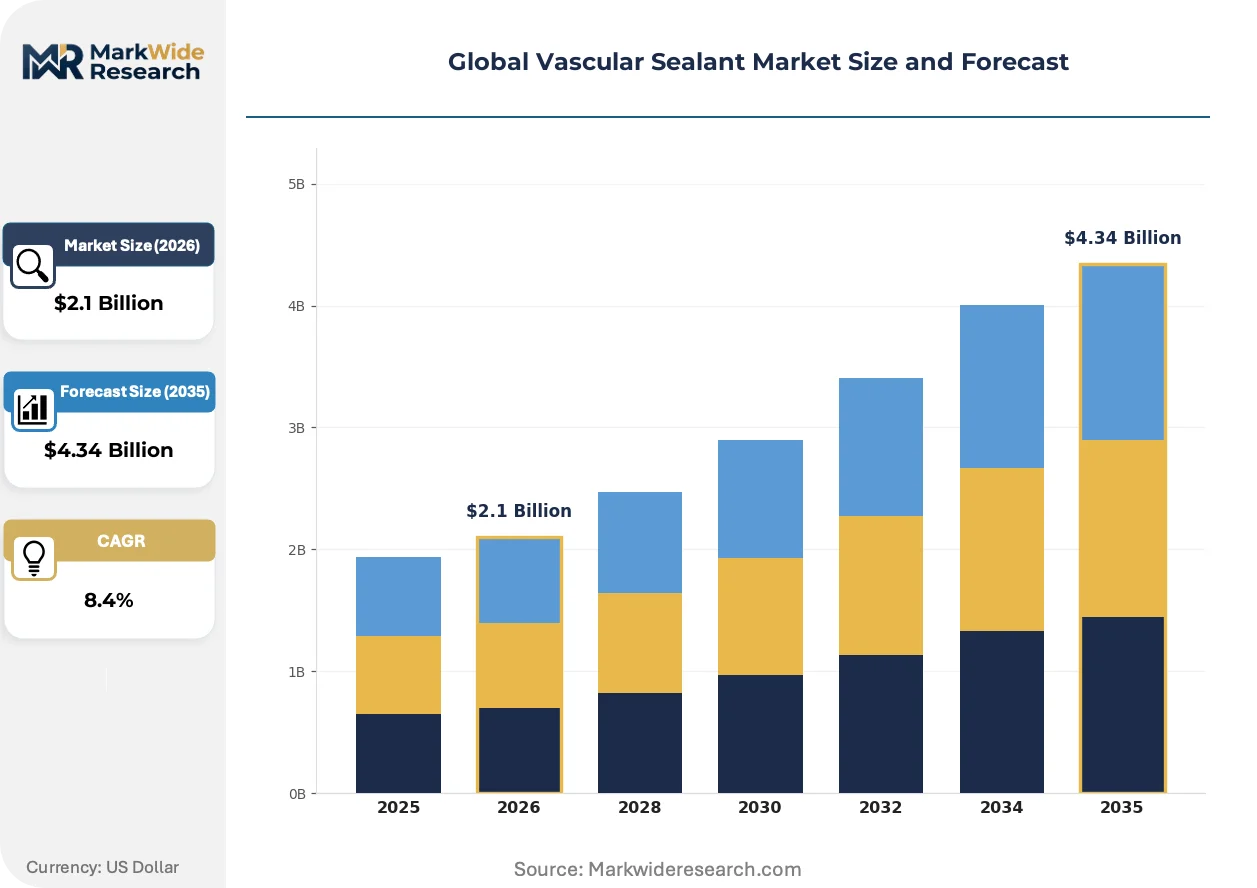
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fibrin Sealants, Synthetic Sealants, Albumin-Based Sealants, Polysaccharide Sealants, Collagen Sealants Application: Cardiovascular Surgery, Neurosurgery, Thoracic Surgery, Orthopedic Procedures, General Surgery End User: Hospitals, Surgical Centers, Ambulatory Care Facilities, Research Institutes, Specialty Clinics Delivery Mode: Liquid Adhesives, Powder Formulations, Preloaded Cartridges, Spray Systems, Patch Systems |
| Companies Covered | Baxter International, Johnson & Johnson (Ethicon), CryoLife, Becton Dickinson, Medtronic, B. Braun Melsungen, Integra LifeSciences, Grifols, CSL Behring, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vascular Sealant Market Shifts & Advancements
Synthetic polymer chemistry and regulatory data requirements are compressing the competitive set while procurement consolidation restructures how hemostasis products reach surgical suites.
Polyethylene glycol-based synthetic sealants are rewriting competitive positioning in neurosurgical applications. Academic medical centers in the United States and Germany are adopting these platforms at accelerating pace for dural closure and cranial procedures. The technology is compressing biological sealant incumbents into cardiac and vascular niches where fibrin familiarity remains entrenched.
EU Medical Device Regulation tightening is restructuring market access economics for vascular sealant manufacturers. The framework demands expanded clinical evidence and post-market surveillance infrastructure that favors scaled plasma fractionation operators. Synthetic platform developers without legacy ISO 10993 testing capabilities face capital-intensive compliance buildouts to sustain CE marking.
Hospital procurement networks are consolidating hemostasis purchasing through integrated suture-adhesive contracts. United States health systems and German hospital chains are displacing standalone sealant vendors with bundled suppliers. This concentration is most visible in cardiovascular surgery suites where procurement committees standardize across product categories to capture volume discounts.
Global Vascular Sealant Market Segmentation
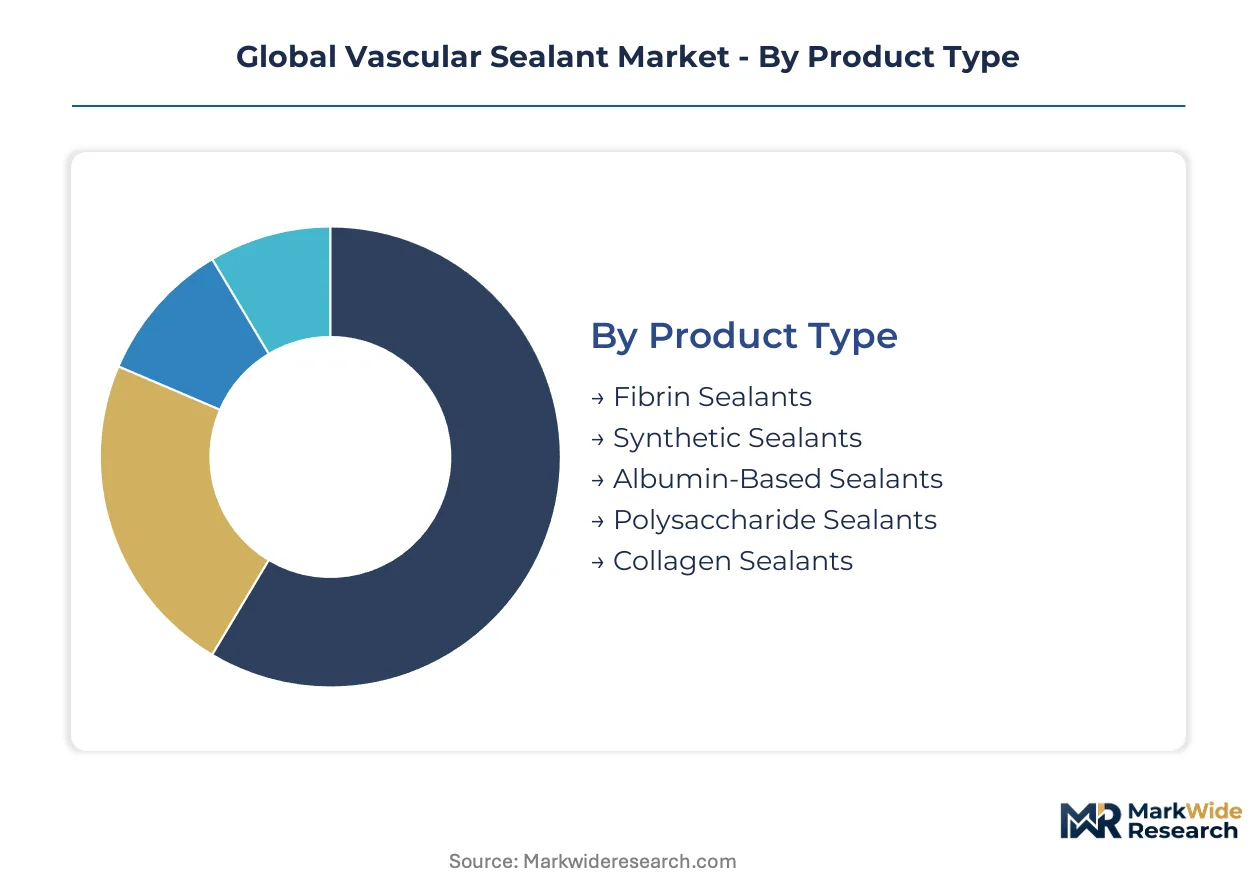
Vascular sealant segmentation reveals distinct technology-performance tradeoffs across product chemistry, surgical application, and delivery format. Procurement committees weigh hemostatic efficacy against supply chain reliability and regulatory compliance burden when standardizing across categories.
Product Type:
Material composition dictates polymerization kinetics, biocompatibility profile, and degradation pathway.
- Fibrin Sealants:Dual-component systems combining human fibrinogen and thrombin replicate final coagulation cascade stages. Cardiac surgery suites in the United States and Germany sustain repeat purchasing through established surgeon training and extensive clinical validation libraries. Plasma fractionation concentration in North American and German collection networks constrains raw material security.
- Synthetic Sealants:Polyethylene glycol and cyanoacrylate platforms polymerize via moisture-activated crosslinking independent of patient coagulation status. Neurosurgical and thoracic applications in academic medical centers are climbing the fastest as blood-borne pathogen transmission risks deter biological alternatives. REACH-compliant polymer sourcing in Europe reinforces margin structures against commodity pressure.
- Albumin-Based Sealants:Bovine or human albumin carriers with glutaraldehyde crosslinking achieve high tensile strength in vascular anastomosis.
- Polysaccharide Sealants:Oxidized cellulose and starch derivatives provide absorbable hemostasis through swelling and platelet activation.
- Collagen Sealants:Bovine or porcine collagen matrices promote platelet aggregation and clot formation at bleeding sites.
Mature deployment sits with Fibrin Sealants. Newer deployment is concentrated in Synthetic Sealants.
Application:
Procedural complexity and bleeding risk profile determine sealant selection criteria.
- Cardiovascular Surgery:Aortic reconstruction, coronary bypass, and valve replacement procedures demand rapid hemostasis under systemic heparinization. Tertiary hospitals in Japan and the United States are expanding procedural volumes fastest among aging populations. Fibrin sealant familiarity among cardiac surgeons sustains category dominance despite synthetic alternatives.
- Neurosurgery:Dural closure and cranial reconstruction require watertight sealing without foreign body reaction or mass effect. Academic centers in Germany and the United States are displacing biological products with synthetic platforms to eliminate Creutzfeldt-Jakob disease transmission concerns. PMDA registration timelines for foreign manufacturers compress revenue recognition windows in Japan.
- Thoracic Surgery:Lung resection and esophageal procedures utilize sealants for air leak prevention and parenchymal bleeding control.
- Orthopedic Procedures:Joint reconstruction and spine surgery employ sealants for cancellous bone bleeding and soft tissue adherence.
- General Surgery:Hepatic resection and splenic trauma management apply topical hemostasis across diverse tissue types.
Revenue concentration aligns with Cardiovascular Surgery. Technology substitution is most advanced in Neurosurgery.
End User:
Purchasing authority and case volume distribution shape vendor access strategies.
- Hospitals:Integrated health systems and academic medical centers command procurement committee authority over standardization decisions. Bundled payment environments in the United States are consolidating suture-adhesive purchasing through multi-year contracts. ERP integration requirements raise implementation friction for standalone sealant vendors.
- Surgical Centers:Ambulatory surgery facilities prioritize cost efficiency and rapid turnover in lower-acuity procedures.
- Ambulatory Care Facilities:Outpatient wound management and minor procedural suites apply topical hemostasis in limited intervention contexts.
- Research Institutes:Preclinical and clinical trial sponsors evaluate novel sealant platforms for regulatory submission packages.
- Specialty Clinics:Cardiovascular and neurological focused practices maintain limited on-site sealant inventory for emergency applications.
Volume leverage concentrates with Hospitals. Emerging demand is surfacing in Surgical Centers.
Delivery Mode:
Application precision and operative workflow integration determine format selection.
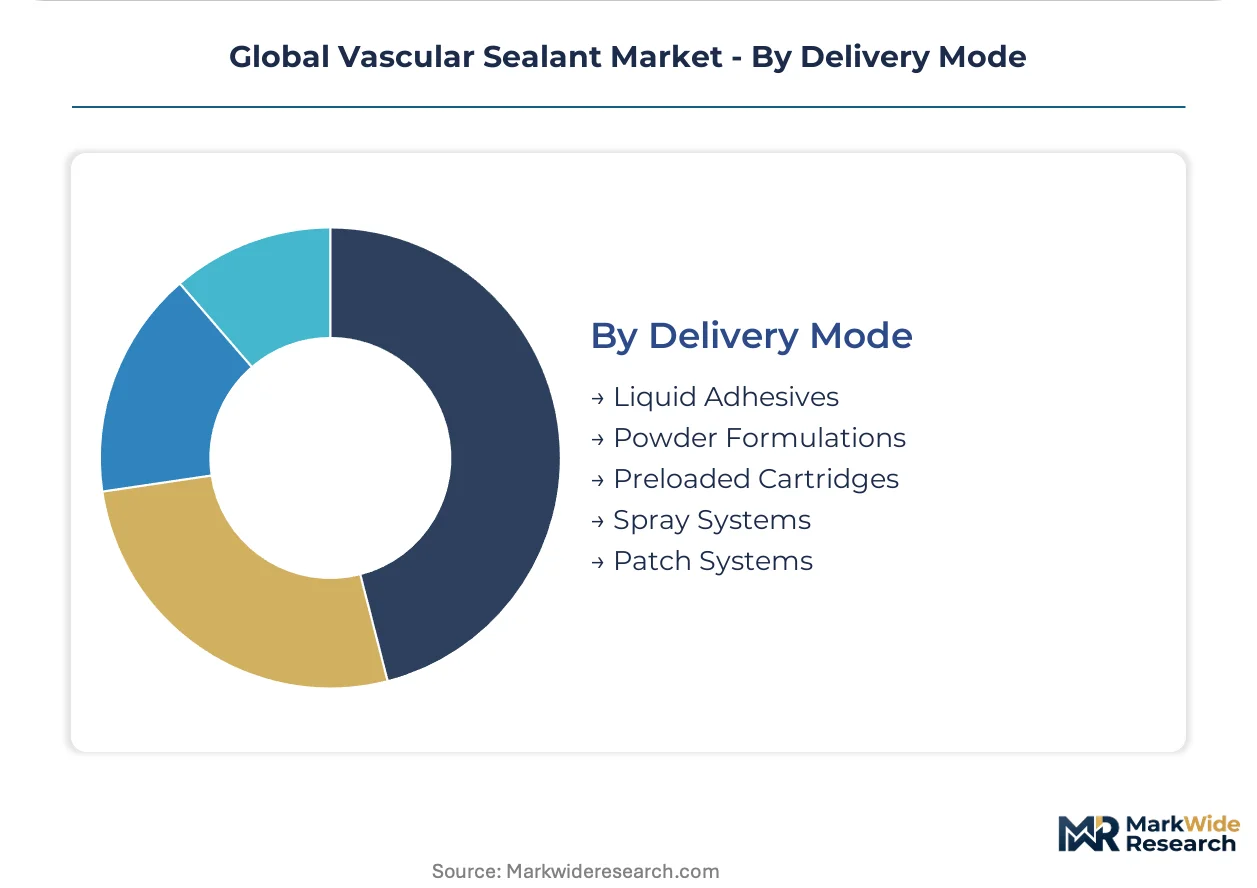
- Liquid Adhesives:Flowable formulations enable topical application across irregular tissue surfaces and suture lines. Cardiovascular and general surgery suites in German hospital chains standardize on dual-barrel syringe systems for controlled mixing. Custom API development for inventory tracking raises implementation costs.
- Preloaded Cartridges:Single-use devices eliminate mixing variability and reduce preparation time in high-throughput environments. United States health systems are consolidating procurement around cartridge-based platforms to capture volume discounts and simplify materials management.
- Powder Formulations:Granular hemostats provide rapid deployment across broad bleeding surfaces without flowable spread.
- Spray Systems:Aerosolized application achieves uniform coverage across large tissue areas in thoracic and hepatic procedures.
- Patch Systems:Preformed matrices with embedded active agents enable mechanical compression combined with chemical hemostasis.
Workflow standardization favors Liquid Adhesives. Procurement consolidation is accelerating Preloaded Cartridges.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shanghai and Shenzhen concentrate vascular sealant manufacturing capacity through tax-advantaged R&D facilities serving Asia-Pacific distribution networks. German industrial clusters around Frankfurt and Munich anchor European plasma fractionation infrastructure. United States medical device corridors in Minneapolis and Boston drive innovation in synthetic polymer platforms.
United States
Tertiary hospitals in Cleveland Clinic and Mayo Clinic networks are expanding cardiovascular procedural volumes fastest among aging patient populations. FDA 510(k) clearance pathways maintain streamlined market access relative to European regulatory frameworks. Minneapolis-based medical device clusters concentrate fibrin sealant manufacturing capacity alongside major plasma fractionation operators.
Germany
Academic medical centers in Berlin and Heidelberg are displacing biological sealants with synthetic platforms in neurosurgical applications. EU MDR biocompatibility documentation requirements favor established ISO 10993 testing infrastructure over new market entrants. Frankfurt-Rhine-Main biotech corridors anchor albumin-based sealant production serving REACH-compliant European supply chains.
Japan
Cardiovascular surgery suites in Tokyo and Osaka university hospitals sustain fibrin sealant familiarity despite synthetic alternatives. PMDA maintains distinct clinical trial requirements that extend registration timelines for foreign manufacturers relative to domestic entrants. Kansai region medical device clusters concentrate distribution infrastructure for imported hemostasis products.
China
Lung resection and esophageal surgery volumes in Shanghai and Beijing represent underpenetrated white-space applications for synthetic sealant platforms. NMPA regulatory pathways are converging toward international standards while maintaining domestic clinical trial requirements. Yangtze River Delta special zones attract foreign joint ventures seeking localized manufacturing capacity.
Switzerland
Swissmedic maintains streamlined biologics licensing frameworks that attract albumin-based sealant manufacturers seeking premium European positioning. Basel and Zurich medical technology clusters concentrate R&D facilities for next-generation hemostasis platforms. Alpine logistics corridors enable efficient distribution across German, French, and Italian hospital networks.
Global Vascular Sealant Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology platforms and geographic markets. Plasma fractionation incumbents leverage backward integration into donor collection networks to secure raw material supply. Three archetypes dominate: diversified healthcare conglomerates with broad surgical portfolios, biological platform specialists with cryopreservation capabilities, and synthetic chemistry developers with polymer expertise. Competitive moves concentrate on strategic partnerships for distribution access and technology licensing for regulatory acceleration.
Among diversified healthcare conglomerates, Baxter International and Johnson & Johnson occupy positions representing integrated surgical portfolio strategies. CryoLife exemplifies the biological specialist archetype through cryopreserved platform positioning. These three companies anchor the competitive structure while Becton Dickinson and Medtronic represent additional scale-driven participants in hemostasis markets.
| Leading Market Players |
|---|
| Baxter International |
| Johnson & Johnson (Ethicon) |
| CryoLife |
| Becton Dickinson |
| Medtronic |
| B. Braun Melsungen |
| Integra LifeSciences |
| Grifols |
| CSL Behring |
| Others |
Supply & Pricing Matrix
United States hospital procurement committees concentrating cardiovascular surgical purchasing through multi-year bundled contracts enforce contract-based long-term offtake pricing that privileges scaled plasma fractionation operators over synthetic platform entrants. This buyer consolidation compresses margin structures for standalone sealant vendors while rewarding integrated suture-adhesive suppliers with volume leverage points.
Pricing Analysis
Lead-time-driven pricing separates premium-positioned albumin-based sealants with EMA biologics licensing from standard fibrin formulations and economy-tier synthetic alternatives. Certification grade under ISO 10993 and REACH-compliant sourcing in Europe command measurable premiums against commodity fibrin products. Cost compression in economy synthetic tiers is intensifying as polyethylene glycol platform proliferation erodes differentiation. Ambulatory surgery centers exhibit highest price sensitivity while academic medical centers prioritize clinical validation libraries over unit cost.
Supply Chain Analysis
Direct-to-hospital channels handle tier-one health system demand while specialty distributors serve mid-tier surgical centers and ambulatory facilities. Plasma collection networks in the United States and Germany anchor biological sealant feedstocks, with synthetic polymer precursors drawing from Chinese and South Korean chemical manufacturing bases. Single-source vulnerability concentrates in North American plasma fractionation infrastructure where donor pool constraints threaten raw material security. Distribution runs through integrated health system materials management platforms requiring custom API development for inventory tracking.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vascular sealant sector is consolidating around backward integration into plasma collection networks and forward control over hospital procurement committee relationships. Players securing captive donor pool access and bundled contract positioning capture sustainable margin structures against commoditization pressure.
For Market Incumbents: Anchor fibrin sealant category leadership through ISO 10993 testing infrastructure expansion that accelerates EU MDR compliance for synthetic platform competitors. Secure multi-year suture-adhesive bundling with United States health systems to forestall polyethylene glycol substitution in cardiovascular applications. Counter mechanical hemostasis substitution threat by embedding sealant protocols into robotic surgery training curricula. For New Entrants and Emerging Players: Begin with thoracic surgery white-space in China where lung resection volumes outpace biological supply chain infrastructure. Target neurosynthetic platform positioning in German academic centers displacing fibrin alternatives over Creutzfeldt-Jakob transmission concerns. Pursue NMPA joint venture pathways to bypass PMDA-extended timelines for foreign manufacturers. For Investors and Strategic Acquirers: The window for entry favors cryopreservation technology specialists navigating EU biocompatibility thresholds with collagen matrix platforms. Long-term viability rests on procurement network integration rather than isolated product innovation. Monitor bundled payment penetration rates in United States cardiovascular service lines as inflection indicator for sector consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | EU MDR compliance infrastructure compresses competitive set for European market access. |
| Plasma Collection Network Acquisition | Captive donor pools in United States and Germany secure biological sealant raw material continuity. |
| Hospital System Partnership | Integrated suture-adhesive contracts with Cleveland Clinic and Mayo Clinic networks standardize procurement. |
| Synthetic Polymer Platform Launch | Polyethylene glycol formulations displace fibrin in German neurosurgical applications over pathogen transmission risks. |
| Reimbursement Strategy Development | Adjunct hemostasis coding optimization in CMS bundled payment environments protects margin structures. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with cardiac surgeons, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers supplied operational validation. FDA 510(k) clearance databases, EMA MDR submission records, hospital procurement databases, and CMS Medicare reimbursement files provided structured secondary sources. Bottom-up procedure volume modeling triangulated against top-down plasma fractionation capacity estimates across the analysis window.
Segment-level granularity modeled product chemistry, surgical application, delivery format, and end-user purchasing authority as distinct forecast dimensions. CAGRs derived from procedure volume elasticity against sealant attachment rates, with synthetic platform substitution curves and EU MDR compliance timelines as industry-specific forecast inputs throughout the projection horizon.
Underlying measurement precision varies by segment; cardiovascular surgery volumes carry tighter precision than emerging thoracic applications due to established registry infrastructure. Forecasts reflect assumptions regarding PMDA registration timeline convergence and plasma collection network expansion that stress-testing against donor pool constraints and reimbursement reclassification risks should periodically validate.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Plastic Adhesives Market
Adhesives & Sealants
Hydrophobic Pore-Blocking Agents for Waterproof Concrete Market
Adhesives & Sealants
Middle-East and Africa Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
India Tile Adhesive Market
Adhesives & Sealants
Instant Adhesive Market
Adhesives & Sealants
Middle-East and Africa Polyurethane (PU) Adhesives Market
Adhesives & Sealants
Central Reinforced Tape Market
Adhesives & Sealants
UV Cured Adhesives Market
Adhesives & Sealants
Asia-Pacific Contact Adhesives Market
Adhesives & Sealants
Malaysia Adhesives and Sealants Market
Adhesives & Sealants
Global Glass Bonding Adhesive Market
Adhesives & Sealants
Global Silicone Adhesives and Sealants Market
Adhesives & Sealants
Europe Acrylic Adhesives Market
Adhesives & Sealants
South America Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Asia-Pacific EVA Adhesives Market
Adhesives & Sealants
Global EVA Adhesives Market