
 Dental Impression Tray Adhesives Market | 2026-2036
Dental Impression Tray Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Impression Tray Adhesives Market Insights
Germany is fragmenting as a production hub for dental impression tray adhesives, with regional manufacturers challenging established supply chains. 3M leverages its polymer science heritage to sustain premium positioning across European dental channels. Dentsply Sirona anchors North American distribution through integrated dental equipment and consumables portfolios. Ivoclar Vivadent differentiates via specialized light-cured adhesive formulations tailored for high-precision digital dentistry.
Dental impression tray adhesives are bonding agents applied to the inner surface of impression trays to secure elastomeric or rigid impression materials during clinical procedures, typically formulated from methacrylate resins or solvent-based compositions with viscosity parameters calibrated for specific tray materials and setting times. Their primary commercial purpose is to prevent distortion or separation of the impression material from the tray, ensuring dimensional accuracy for prosthetic fabrication and orthodontic appliance production. Light-cured adhesives dominate clinical settings due to instant polymerization under LED curing units, while dual-cure adhesives capture growing share in complex multi-unit impressions where complete light penetration cannot be guaranteed. Pressure-sensitive adhesives occupy a mature niche in removable prosthodontics, though margin pools have compressed as generic alternatives proliferate through dental supply distributors.
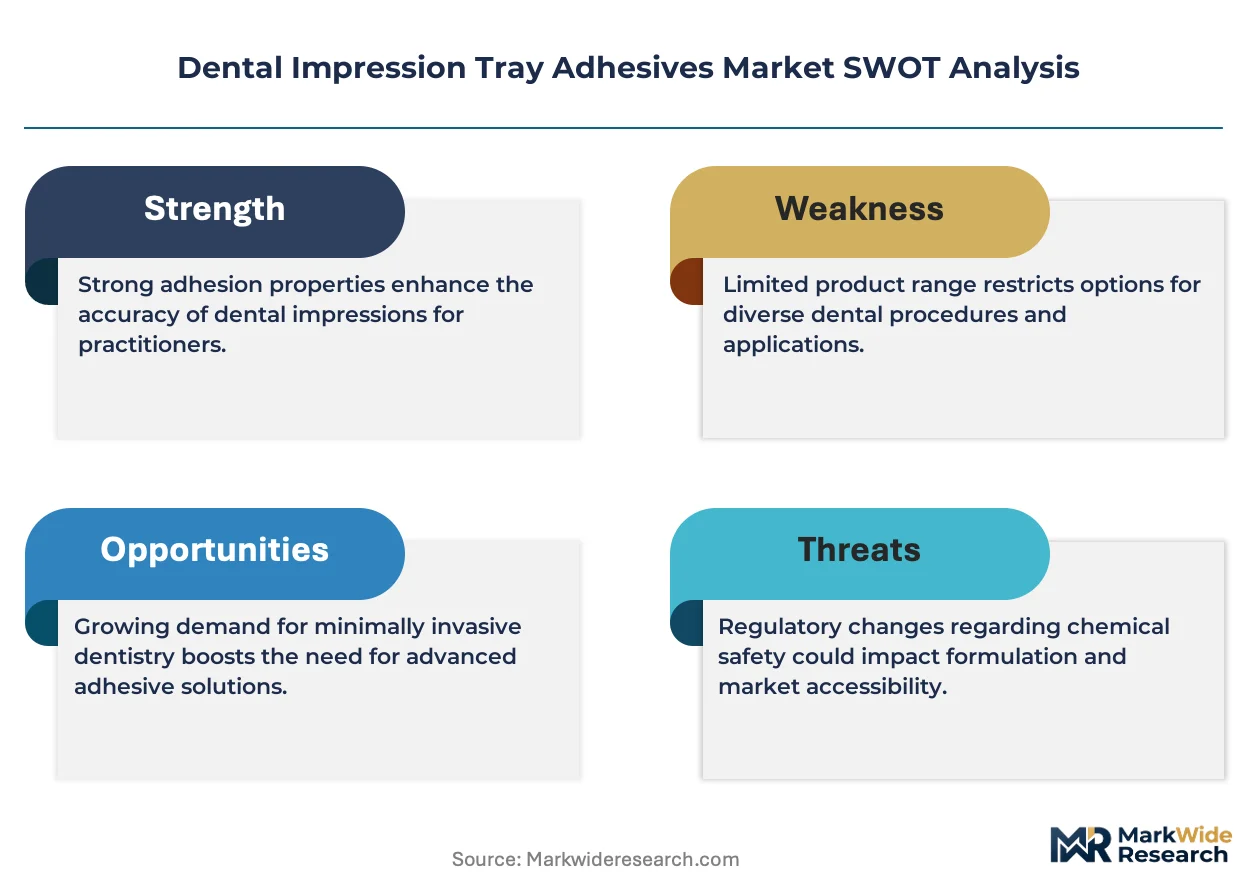
FDA 510(k) premarket notification requirements govern biocompatibility and performance claims for tray adhesives sold in the United States, while the EU Medical Device Regulation mandates CE marking and clinical evidence documentation for European market access. ISO 10993 biological evaluation standards shape testing protocols that manufacturers must satisfy before regulatory submission in both jurisdictions. Stakeholders should monitor evolving FDA guidance on dental material cytotoxicity thresholds and MDR transition timelines, as compliance cost differentials will reshape competitive viability across mid-tier suppliers.
Market Dynamics
Digital dentistry workflows are compressing impression accuracy tolerances, forcing adhesive manufacturers to reformulate for faster polymerization kinetics and enhanced bond strength to polyether and addition silicone materials.
Growth Catalysts
- EU Medical Device Regulation (MDR):CE marking requirements for clinical evidence documentation are filtering out low-grade competitors and elevating demand for validated, premium adhesive formulations across German and French dental laboratories.
- Chairside CAD/CAM integration:Dental clinics are accelerating adoption of intraoral scanners that require specialized tray adhesives compatible with digital impression capture protocols.
- Methacrylate resin innovation:Advanced polymer chemistry is enabling single-component adhesives with extended working times and reduced technique sensitivity for complex multi-unit impressions.
Market Restraints
- Acrylic monomer price volatility:Feedstock cost fluctuations for methacrylate precursors squeeze margin structures for mid-tier adhesive producers dependent on spot market sourcing.
- Supply concentration in specialty solvents:German and Swiss chemical suppliers dominate high-purity solvent production, creating geographic vulnerability for manufacturers lacking long-term supply agreements.
- Technical ceiling on bond durability:Current formulations face inherent limitations in achieving reliable adhesion to thermoplastic tray materials without surface pretreatment protocols.
Strategic Opportunities
- Underpenetrated Indian dental sector:CDSCO regulatory harmonization with ISO 10993 standards is lowering market entry barriers for biocompatible adhesive portfolios targeting price-sensitive clinic chains.
- Light-cured and dual-cure convergence:Hybrid polymerization systems are opening white space in complex implant impressions where LED penetration is incomplete.
- Direct-to-laboratory e-commerce channels:Specialized dental supply platforms are bypassing traditional distributor markups and capturing growing share among independent German dental technicians.
Industry Challenges
- Biocompatibility testing talent scarcity:ISO 10993-5 cytotoxicity assay expertise is concentrated among specialized contract research organizations, extending regulatory submission timelines for smaller manufacturers.
- Legacy equipment integration friction:New adhesive chemistries require recalibration of existing LED curing units, creating adoption resistance in capital-constrained clinic environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Impression Tray Adhesives Market |
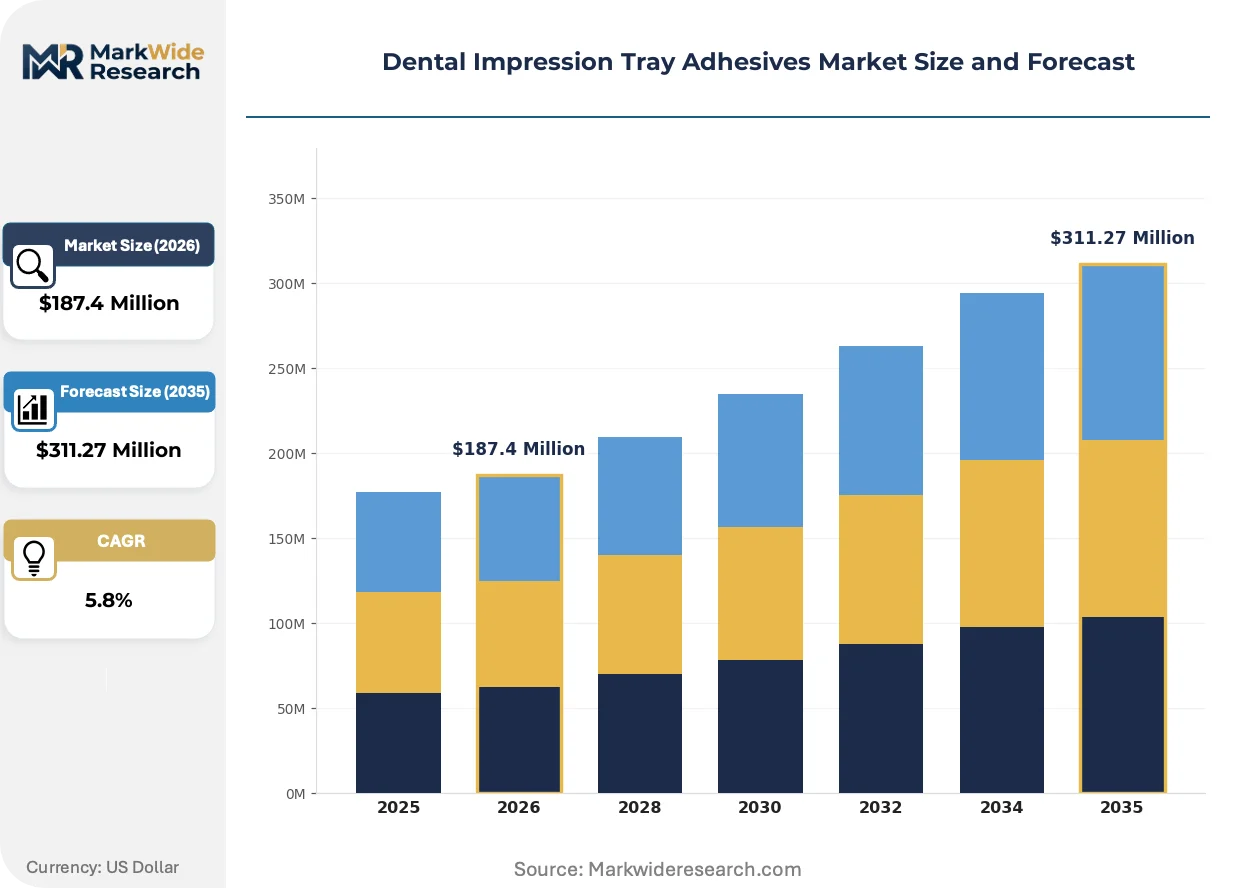
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light-Cured Adhesives, Self-Adhesive, Dual-Cure Adhesives, Pressure-Sensitive Adhesives Application: Dental Clinics, Hospitals, Home Care, Research Labs Material: Polymer-Based, Metal-Based, Hybrid Materials, Glass Ionomer End User: Dentists, Dental Technicians, Orthodontists, Dental Assistants |
| Companies Covered | 3M, Ivoclar Vivadent, Dentsply Sirona, Zhermack SpA, GC Corporation, BISCO, Inc., Kuraray America, Inc., Ultradent Products Inc., SDI Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Impression Tray Adhesives Market Trends and Innovations
Formulation science and regulatory stringency are jointly elevating performance benchmarks, with adhesive developers racing to match the precision demands of digital prosthodontics while navigating evolving biocompatibility protocols.
Light-cured adhesive systems are migrating from conventional halogen-dependent curing to high-intensity LED-optimized formulations with tailored photoinitiator packages. German dental laboratories are leading this transition, driven by throughput pressures from high-volume crown-and-bridge production. The shift is compressing demand for older solvent-based alternatives that require extended evaporation protocols.
REACH chemical registration requirements are tightening disclosure obligations for residual monomer content in dental materials sold across EU member states. Manufacturers must now submit comprehensive toxicological dossiers for adhesive constituents previously exempt under grandfathered classifications. Small and mid-sized suppliers face disproportionate compliance burdens, accelerating consolidation toward vertically integrated chemical houses with dedicated regulatory affairs capabilities.
Dental technicians are consolidating purchasing through group procurement organizations that negotiate adhesive supply contracts on behalf of independent laboratory networks. This channel shift is displacing traditional dental distributor relationships in France and Italy, where technician associations have formalized collective buying structures. The behavioral change is most pronounced among high-volume prosthetic laboratories serving implant restorative workflows.
Dental Impression Tray Adhesives Market Segmentation
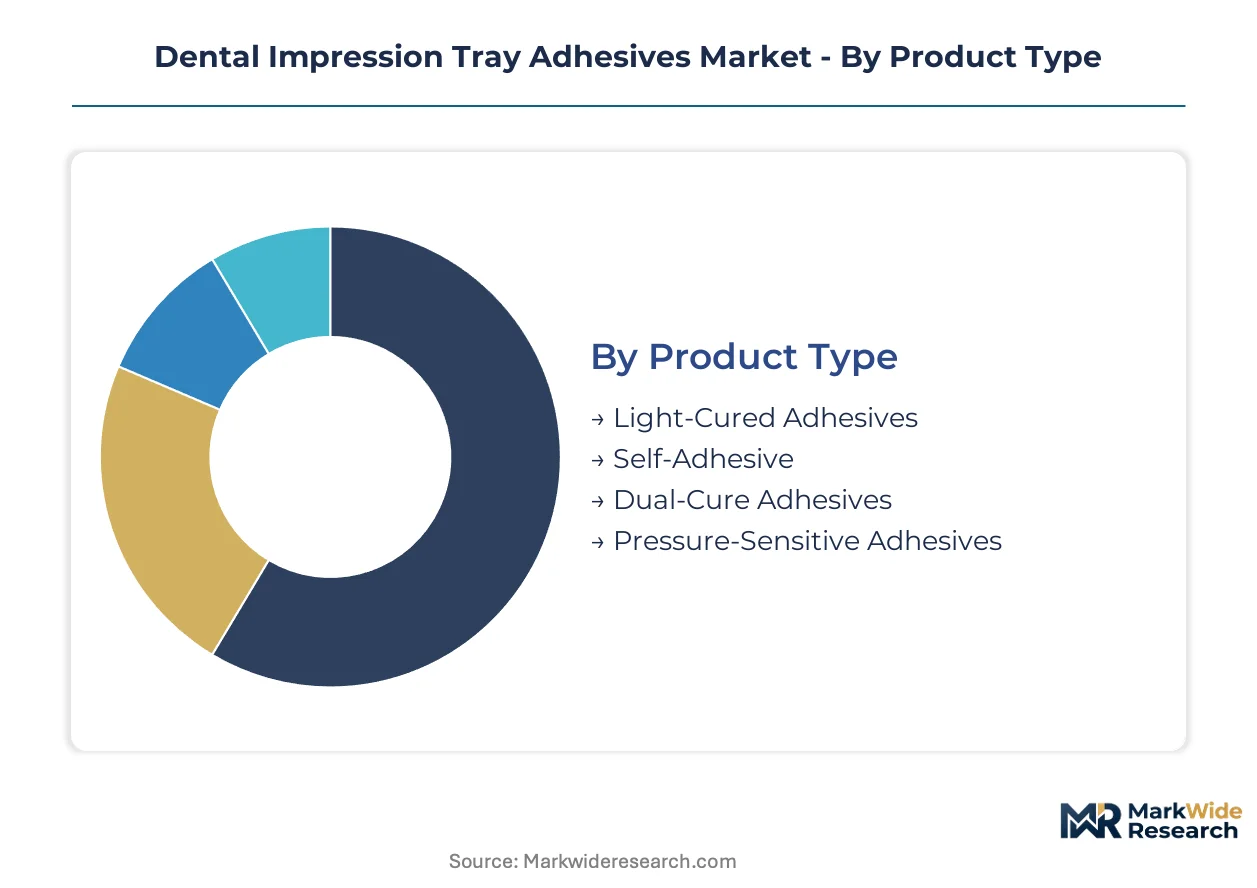
Dental impression tray adhesives fragment across polymerization chemistry, clinical setting, substrate compatibility, and operator workflow. Each dimension carries distinct inventory velocity and margin implications for manufacturers targeting crown-and-bridge versus orthodontic versus research applications.
Product Type:
Light-cured systems turn inventory fastest due to chairside immediacy, while pressure-sensitive formulations linger in distributor warehouses serving removable prosthodontics.
- Light-Cured Adhesives:Photoinitiator-activated methacrylate resins polymerize under LED curing units within seconds. German dental laboratories concentrate procurement here, driven by throughput pressures from high-volume digital impression workflows.
- Dual-Cure Adhesives:Hybrid photoinitiator and chemical-catalyst systems polymerize where LED penetration is incomplete. Complex multi-unit implant impressions in United States academic medical centers drive specification, though per-unit cost premiums constrain clinic adoption.
- Self-Adhesive:Pre-activated single-component formulations eliminate mixing steps. Convenience positioning targets general practitioners with limited laboratory support.
- Pressure-Sensitive Adhesives:Tackified elastomeric coatings for removable prosthodontic trays. Mature demand concentrates in French and Italian denture laboratories with legacy equipment.
Light-cured adhesives dominate installed base. Dual-cure formulations are where expansion concentrates.
Application:
Procurement patterns diverge sharply between high-throughput institutional settings and episodic home-based use.
- Dental Clinics:Private practice networks in Germany and the United States drive volume through recurring impression appointments. Chairside CAD/CAM integration forces adhesive specification upgrades compatible with intraoral scanning protocols.
- Hospitals:Academic medical centers and trauma units require bulk supply contracts with extended shelf-life guarantees. Complex maxillofacial reconstruction cases demand dual-cure reliability.
- Home Care:Direct-to-consumer impression kits for clear aligner therapy. Regulatory ambiguity around self-administered dental materials constrains legitimate channel development.
- Research Labs:Biomaterials testing facilities and university prosthodontic programs. Small batch sizes and custom formulation requests compress margin structures.
Dental clinics anchor volume procurement. Research labs show the steepest expansion trajectory for specialized high-precision formulations.
Material:
Substrate chemistry determines supply chain exposure to petrochemical feedstock volatility and REACH registration obligations.
- Polymer-Based:Methacrylate and urethane formulations with tunable viscosity parameters. German manufacturers lead formulation innovation, though acrylic monomer price swings squeeze mid-tier producers.
- Hybrid Materials:Ceramic-filled polymer matrices balancing bond strength with handling characteristics. Japanese dental technicians specify these for high-accuracy implant impressions.
- Metal-Based:Zinc oxide-eugenol and cyanoacrylate compositions for specialized tray substrates. Niche positioning in orthodontic laboratories with metal tray inventories.
- Glass Ionomer:Fluoroaluminosilicate glass and polyacrylic acid systems with chemical adhesion to tooth structure. Limited tray adhesive application due to moisture sensitivity.
Polymer-based materials command production scale. Hybrid formulations gain share fastest among digital dentistry adopters.
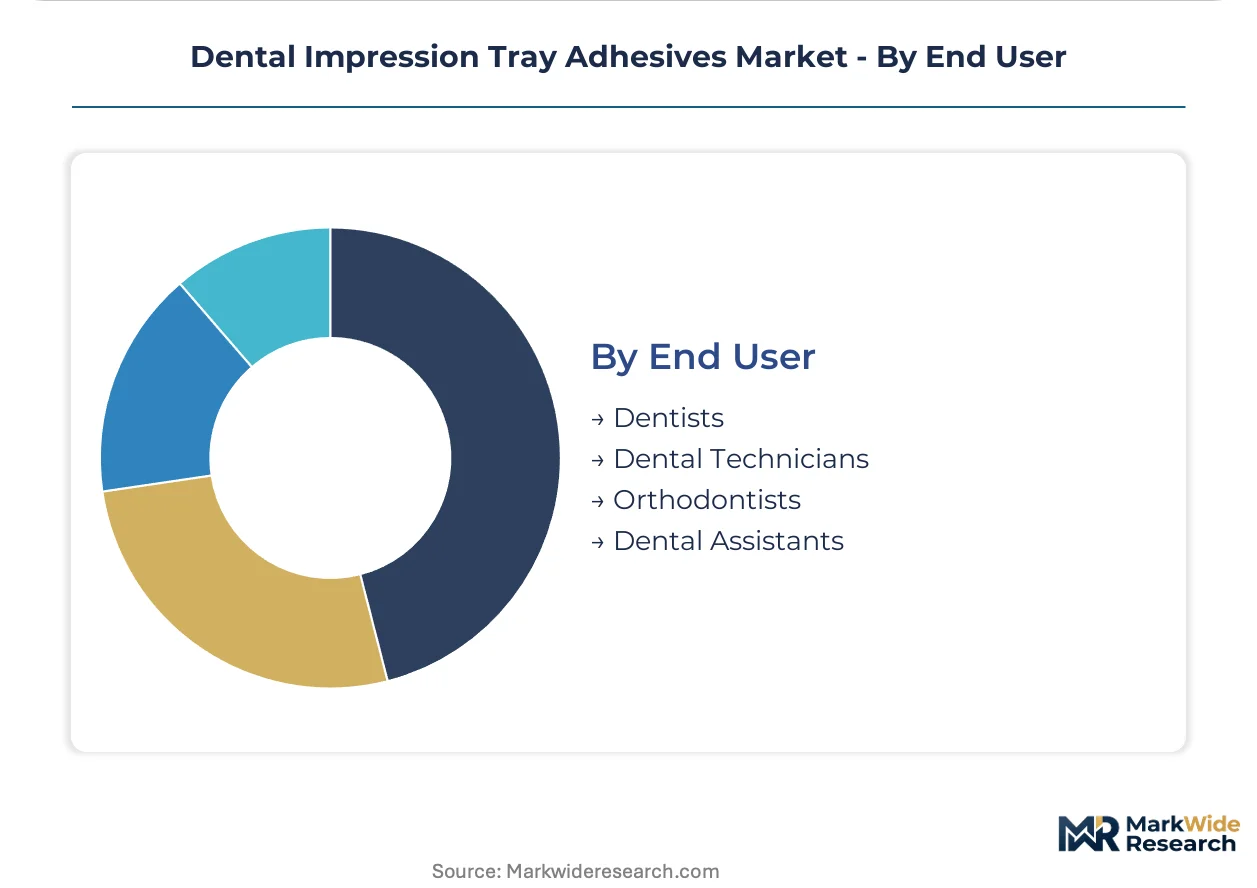
End User:
Technical sophistication and purchasing authority split across clinical operators and laboratory fabricators.
- Dental Technicians:Independent laboratory operators in Germany consolidate through group procurement organizations. Digital workflow adoption forces adhesive specification alignment with scanner compatibility.
- Dentists:General practitioners and prosthodontists with direct purchasing control. Brand loyalty to integrated equipment-consumables portfolios constrains switching.
- Orthodontists:Specialized practices with distinct tray material preferences for study model impressions. Thermoplastic tray adhesion challenges limit formulation options.
- Dental Assistants:Procedural execution without specification authority. Training requirements influence adhesive selection for technique-sensitive applications.
Dental technicians dominate specification influence. Orthodontists represent the fastest-climbing customer segment for simplified single-component systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical handling infrastructure underwrites European distribution networks for dental adhesive precursors, while the Rhine River corridor connects German formulation plants to Benelux packaging facilities.
United States
FDA 510(k) premarket notification requirements govern biocompatibility claims for tray adhesives, with academic medical centers in Boston and Baltimore driving dual-cure specification for complex maxillofacial cases. The FDA's updated cytotoxicity guidance is extending regulatory timelines for mid-tier suppliers.
Germany
The national dental technician association's endorsement of polymer-based formulations for digital workflows concentrates procurement authority in Cologne and Munich laboratory clusters. EU MDR CE marking mandates are filtering out low-grade competitors from the German market.
Japan
METI industrial standards for dental materials shape formulation requirements, with Osaka-based prosthodontic laboratories specifying hybrid ceramic-filled adhesives for implant impression accuracy. PMDA consultation procedures for novel photoinitiator packages add 8-12 months to product registration.
India
CDSCO harmonization with ISO 10993 biological evaluation standards is lowering entry barriers for biocompatible portfolios targeting Mumbai and Bangalore clinic chains. Price-sensitive procurement dominates, though group purchasing organizations in Maharashtra are consolidating specification influence.
Brazil
ANVISA registration requirements for dental materials create compliance bottlenecks, with São Paulo state laboratories driving volume demand for light-cured systems. Import substitution policies favor local adhesive repackagers serving the Southeast region's prosthodontic market.
Dental Impression Tray Adhesives Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in formulation chemistry and photoinitiator supply. The market structures around three tiers: multinational dental equipment conglomerates with integrated consumables portfolios, mid-sized adhesive specialists with regional formulation expertise, and generic suppliers competing on distributor price. Consolidation pressures favor players with captive regulatory affairs capabilities and long-term solvent supply agreements. Strategic moves concentrate on backward integration into methacrylate resin production and direct-to-laboratory e-commerce channel development.
Among diversified dental equipment manufacturers, 3M leverages polymer science heritage across European channels, Dentsply Sirona anchors North American distribution through integrated portfolios, and Ivoclar Vivadent occupies specialized positioning in light-cured formulations. These three represent distinct archetypes: materials science conglomerate, equipment-consumables integrator, and premium formulation specialist. Zhermack SpA and GC Corporation exemplify mid-tier regional specialists competing on technician relationship depth and workflow-specific product customization.
| Leading Market Players |
|---|
| 3M |
| Ivoclar Vivadent |
| Dentsply Sirona |
| Zhermack SpA |
| GC Corporation |
| BISCO, Inc. |
| Kuraray America, Inc. |
| Ultradent Products Inc. |
| SDI Limited |
| Others |
Pricing and Supply Chain Analysis
The Rhine-Alpine freight corridor's barge and rail cost dynamics compress margin structures for German formulation plants while amplifying price differentiation between premium polymer-based adhesives and economy solvent alternatives imported through Rotterdam.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies procurement based on ISO 10993-5 cytotoxicity certification grade and volume scale. Brand premiums attach to validated formulations from established polymer science houses, while generic alternatives compete on distributor price for price-sensitive independent French laboratories. Pricing pressure stems from acrylic monomer feedstock volatility squeezing mid-tier producers dependent on spot market sourcing. Dental technicians in group procurement organizations exhibit lowest price sensitivity due to specification authority, whereas general practitioners with direct purchasing control drive economy tier volume.
Supply Chain Analysis
Acrylic monomer and high-purity solvent feedstock sourcing draws from German, Swiss, and Belgian chemical suppliers dominating specialty methacrylate production. Photoinitiator packages for LED-cured formulations rest on Japanese and South Korean specialty chemical houses. Single-source vulnerability concentrates in high-purity solvent supply agreements, with limited qualified alternatives for REACH-compliant adhesive constituents. Distribution runs through dental supply distributors in Southern Europe and direct-to-laboratory e-commerce platforms consolidating share among German technician networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital dentistry workflow fragmentation creates niche positioning opportunities as intraoral scanner compatibility demands splinter adhesive specification across laboratory, clinic, and hospital procurement channels.
For Market Incumbents: Pre-empt regulatory compliance cost escalation by securing captive ISO 10993-5 testing capabilities or exclusive contract research organization relationships before MDR transition deadlines filter smaller competitors. Anchor polymer science heritage through backward integration into methacrylate resin production, insulating margin structures from acrylic monomer spot market volatility threatening mid-tier producers.
For New Entrants and Emerging Players: Pursue white-space positioning in Indian clinic chains where CDSCO harmonization with international biocompatibility standards lowers entry barriers for validated formulations. Target Maharashtra-based group purchasing organizations consolidating specification influence among price-sensitive procurement networks. Deploy direct-to-laboratory e-commerce channels bypassing traditional distributor markups to capture technician relationship depth.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified dental equipment conglomerates seeking to rationalize non-core consumables portfolios amid equipment-software convergence pressures. Mid-sized European adhesive specialists with captive regulatory affairs capabilities and long-term solvent supply agreements present durable acquisition profiles. Monitor FDA cytotoxicity guidance evolution and EU MDR enforcement intensity as inflection indicators for competitive viability thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Methacrylate Resin Production | Captive supply of core polymer feedstock insulates margin structures from acrylic monomer price swings. |
| CE Marking Pathway Investment | MDR clinical evidence documentation requirements filter low-grade competitors from German laboratory procurement. |
| Direct-to-Laboratory E-Commerce Launch | Specialized dental supply platforms bypass distributor markups and capture technician purchasing consolidation. |
| ISO 10993-5 Testing Capability Acquisition | In-house cytotoxicity assay expertise compresses regulatory submission timelines against contract research organization bottlenecks. |
| LED Photoinitiator Package Development | Tailored polymerization kinetics match high-intensity curing unit specifications in German digital dentistry workflows. |
Research Methodology
Operator-level perspectives from dental technicians, prosthodontists, GPO contracts managers, and biomedical engineers anchored the qualitative base for this analysis. Primary field engagement combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, CDSCO registration records, and ISO 10993 biological evaluation standards. Customs data on methacrylate resin trade flows and dental supply distributor inventory disclosures provided volume calibration. Bottom-up segment sizing triangulated against top-down macro dental procedure estimates.
Scenario-bracketing framed demand trajectories across the projection horizon, with polymerization chemistry, clinical setting, substrate compatibility, and operator workflow dimensions modeled separately. CAGRs derived from procedure volume elasticity to adhesive consumption ratios, calibrated against digital dentistry adoption curves and regulatory transition timelines. Photoinitiator innovation cycles and LED curing unit replacement rates informed technology transition assumptions throughout the modeling period.
Macroeconomic conditions sit as an overlay; deviation in acrylic monomer feedstock pricing, freight corridor cost structures, or dental clinic capital expenditure cycles would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement intensity and digital workflow penetration rates. Quarterly review of FDA guidance publication cadence, EU MDR notified body capacity, and group purchasing organization contract award patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Global Ethyl Methacrylate (97-63-2) Market
Adhesives & Sealants
Europe Acrylic Adhesives Market
Adhesives & Sealants
Adhesives and Sealants Distribution Market
Adhesives & Sealants
Specialty Adhesives Market
Adhesives & Sealants
Global Electrically Conductive Adhesives Market
Adhesives & Sealants
United States Construction Adhesives and Sealants Market
Adhesives & Sealants
Global Bonding Varnish Market
Adhesives & Sealants
Middle East & Africa Construction Adhesives & Sealants Market
Adhesives & Sealants
Australia Adhesives Market
Adhesives & Sealants
South Korea Sealants Market
Adhesives & Sealants
Global MS Polymer Adhesives Market
Adhesives & Sealants
Global Silicone Adhesives Market
Adhesives & Sealants
Polyurethane (PU) Adhesives Market
Adhesives & Sealants
Textile Binders Market
Adhesives & Sealants
Silane Coupling Agents Market
Adhesives & Sealants
Asia-Pacific Reactive Adhesives Market