
 Foam Adhesive Market | 2026-2036
Foam Adhesive Market Size, Share, and Industry Trends Forecast 2026-2036
Foam Adhesive Market Analytics
The EU Green Deal's embodied carbon targets for construction materials is repositioning specification criteria across European building projects. Henkel AG & Co. KGaA leverages its adhesive technology portfolio to serve automotive OEMs transitioning to multi-material vehicle platforms. 3M dominates the high-performance acrylic foam tape segment with proprietary viscoelastic polymer chemistry. Saint-Gobain S.A. anchors European supply through specialized acrylic and polyurethane foam bonding solutions for industrial applications.
Foam adhesive denotes a pressure-sensitive or structural bonding system comprising a cellular polymer carrier impregnated with tackifying resins, typically ranging from 0.1 mm to 3.0 mm in thickness, engineered to absorb dynamic stress and accommodate thermal expansion differentials between dissimilar substrates. Polyurethane formulations command the largest volume share due to their versatility across construction and automotive seam sealing, while silicone variants capture premium positioning in electronics thermal management applications where sustained performance above 150°C remains mandatory. Acrylic chemistry leads growth trajectories driven by clean-room electronics assembly and exterior automotive trim attachment requiring UV and moisture resistance.
EPA VOC emission standards for industrial adhesives and the EU REACH framework on isocyanate labeling collectively elevate compliance costs for solvent-containing formulations while creating preferential market access for low-emission alternatives. China's GB standards on indoor air quality and Japan's JIS specifications for building materials further fragment certification requirements across major supply corridors. Buyers must monitor regulatory divergence between jurisdictions to avoid specification mismatches that strand inventory or trigger reformulation investments.
Market Dynamics
Automotive lightweighting mandates in Germany and Japan are compressing bonding specifications toward structural foam tapes that accommodate multi-material assemblies. REACH restrictions on solvent-based formulations are simultaneously forcing technology migrations across European supply chains.
Growth Catalysts
- Hot-melt technology migration:Waterborne and reactive hot-melt systems capture share from solvent-containing alternatives as EPA VOC standards and EU REACH frameworks tighten compliance thresholds for industrial adhesives.
- EV battery pack assembly:China's eastern manufacturing corridor concentrates demand for thermal interface foam bonding solutions serving electric vehicle battery module attachment and electronics contract manufacturing clusters.
- Acrylic chemistry advancement:UV-stable acrylic foam tapes penetrate exterior automotive trim and clean-room electronics applications where sustained performance under thermal cycling and moisture exposure remains critical.
Market Restraints
- Isocyanate input cost volatility:Polyurethane formulation margins compress when crude-derived MDI and TDI feedstock prices spike, forcing reformulation investments or pricing adjustments that strain long-term supply agreements.
- Specialty resin supply concentration:High-performance tackifying resin production clusters in specific Asian chemical manufacturing hubs, creating single-source vulnerability for European and North American foam adhesive compounders.
- Silicone thermal ceiling:Premium silicone foam adhesives face substitution pressure from emerging thermal gap fillers in electronics cooling applications where sustained operation above 180°C remains rare.
Strategic Opportunities
- India construction retrofit:BIS certification alignment for low-VOC foam sealants opens specification pathways in commercial building envelope applications as the country's energy efficiency codes tighten.
- Photovoltaic frame bonding:EVA-foam hybrid adhesive systems penetrate solar module manufacturing as frame attachment specifications shift from mechanical fastening to bonded joints.
- EU Green Deal embodied carbon:Construction material procurement criteria now reward suppliers with verified carbon footprints, creating preferential access for bio-based foam carrier technologies.
Industry Challenges
- Polymer rheology expertise scarcity:Formulation chemists capable of tuning viscoelastic polymer networks for specific substrate combinations command premium compensation, constraining R&D throughput at mid-tier manufacturers.
- Multi-jurisdiction certification timelines:Simultaneous pursuit of EPA VOC compliance, REACH registration, and China's GB indoor air quality standards extends product launch cycles by 18-24 months.
- Legacy equipment retrofit costs:Hot-melt dispensing system upgrades require capital deployment that smaller regional compounders struggle to finance, consolidating specification access among integrated suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foam Adhesive Market |
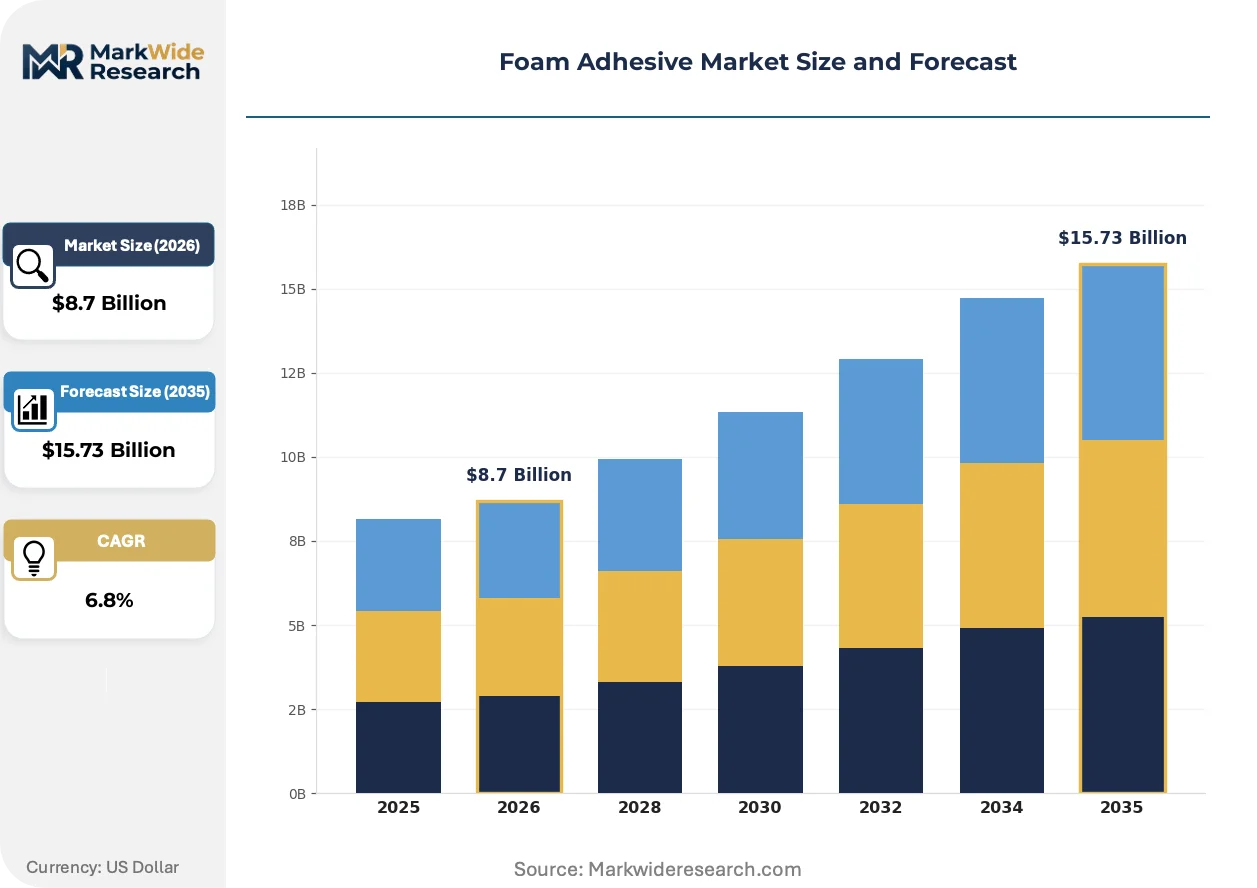
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Acrylic, Silicone, Rubber Application: Automotive, Electronics, Construction, Packaging End User: Manufacturers, Contractors, Retailers, Repair Services Distribution Channel: Direct Sales, Retail, E-commerce, Wholesalers |
| Companies Covered | Nitto Denko Corporation, Saint-Gobain S.A., 3M, Scapa Group PLC, Tesa SE, Henkel AG & Co. KGaA, Intertape Polymer Group, Rogers Corporation, Avery Dennison Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foam Adhesive Market Evolving Landscape
Active chemistry evolution and regulatory compression are reshaping competitive positioning across foam adhesive value chains. Technology investments now prioritize clean-room compatibility and thermal performance over legacy cost optimization.
Structural acrylic foam tapes with proprietary viscoelastic polymer cores are electrifying automotive exterior attachment specifications. German and Japanese OEMs specify these systems for multi-material body-in-white assemblies where thermal expansion differentials between aluminum and composite panels demand stress-absorbing bond lines. The technology is compressing mechanical fastening content in premium vehicle platforms while elevating performance requirements for tape suppliers.
REACH restrictions on isocyanate labeling and EPA VOC emission standards for industrial adhesives are elevating compliance costs for solvent-containing polyurethane formulations. European compounders accelerate waterborne system development while North American manufacturers invest in reactive hot-melt capacity to maintain specification access. Construction and automotive OEM procurement teams now mandate low-emission alternatives in new supplier qualification protocols.
Specification-driven procurement patterns are concentrating buying power among tier-one automotive and electronics OEMs with dedicated adhesive engineering functions. Distributors lose technical specification influence as direct supplier-OEM collaboration deepens around application-specific bonding solutions. China's EV assembly plants and electronics contract manufacturers exemplify this shift, with procurement teams embedding adhesive selection criteria into platform design gates rather than treating bonding as a commoditized input.
Foam Adhesive Market Segmentation
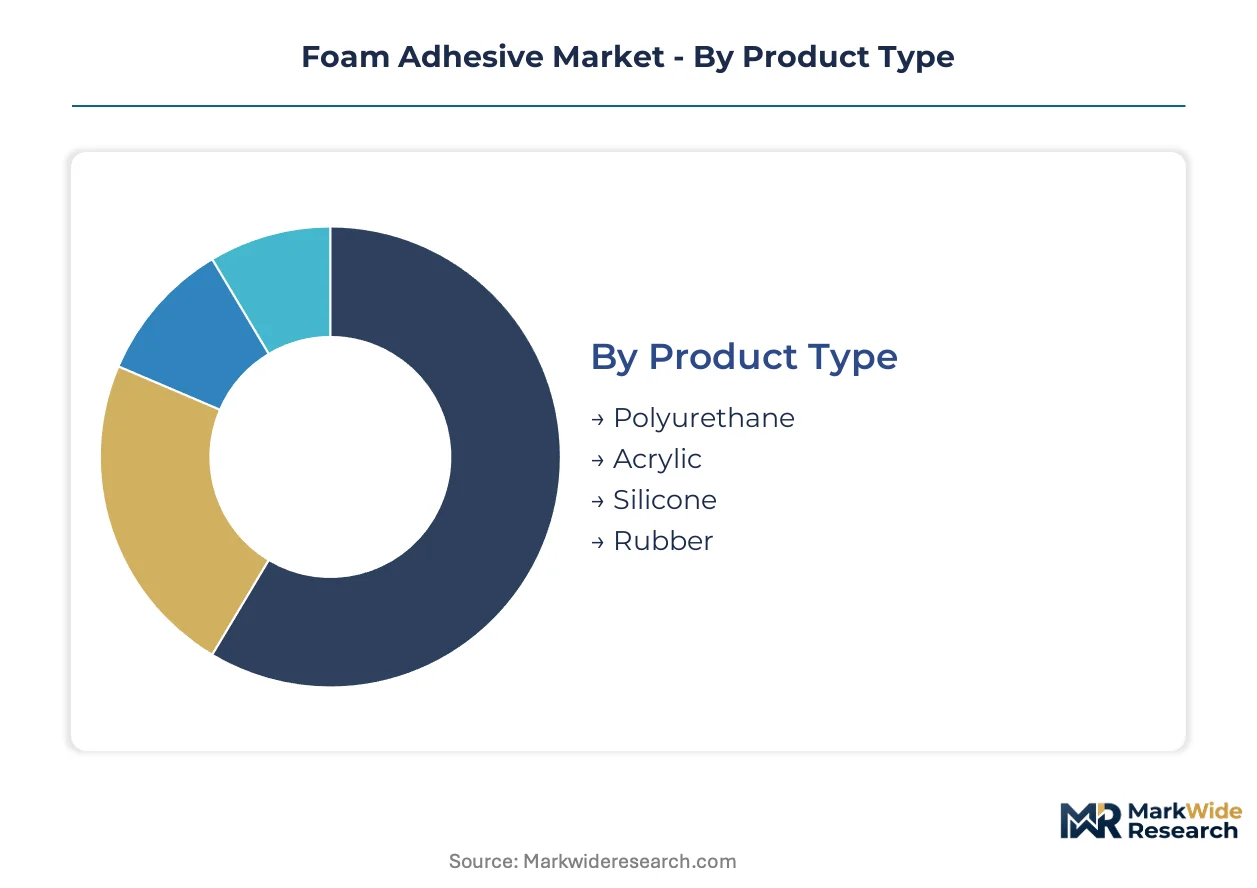
Foam adhesive purchasing patterns diverge sharply across chemistry types and end-use specifications. Capital allocation, regulatory compliance burdens, and application-specific performance thresholds fragment supplier strategies across each dimension.
Product Type:
Capital intensity peaks with silicone and specialized acrylic formulations requiring clean-room polymerization infrastructure, while polyurethane scales through conventional reactor networks.
- Polyurethane:Formulations blend isocyanate-terminated prepolymers with polyol carriers to create cellular structures ranging from flexible to rigid densities. Construction seam sealing in Germany and automotive body assembly in Japan concentrate demand, though MDI feedstock price volatility from crude derivatives compresses margin stability during petrochemical cycles.
- Acrylic:UV-curable and solvent-free acrylic systems incorporate proprietary viscoelastic polymer cores engineered for thermal expansion accommodation. Exterior automotive trim attachment specifications at German OEMs and clean-room electronics bonding in China's eastern manufacturing corridor propel specification upgrades toward UV-stable, moisture-resistant grades.
- Silicone:Platinum-catalyzed addition-cure chemistry sustains performance above 150°C for thermal interface applications.
- Rubber:Natural and synthetic rubber-based carriers serve cost-sensitive packaging and temporary bonding applications with lower capital barriers.
Most installed capacity flows through polyurethane. Expansion is steepest in acrylic.
Application:
Specification authority concentrates with OEM engineering teams in automotive and electronics, while construction procurement fragments across regional contractors.
- Automotive:Structural foam tapes replace mechanical fasteners in multi-material body-in-white assemblies where aluminum-composite bonding demands stress absorption. German and Japanese lightweighting mandates compress bonding specifications toward tapes accommodating thermal expansion differentials, with direct supplier-OEM collaboration displacing distributor influence.
- Electronics:Thermal interface materials and clean-room compatible bonding solutions serve battery module assembly and semiconductor packaging. China's eastern manufacturing corridor concentrates EV battery pack and contract electronics manufacturing demand, with procurement teams embedding adhesive selection into platform design gates.
- Construction:Building envelope sealing and insulation attachment drive volume across commercial and residential projects.
- Packaging:Temporary bonding and protective cushioning applications prioritize cost efficiency over performance longevity.
Automotive commands the highest specification premiums. Electronics represents the fastest-growing trajectory.
End User:
Technical sophistication and volume scale separate manufacturer procurement from fragmented contractor purchasing.
- Manufacturers:Tier-one automotive and electronics OEMs maintain dedicated adhesive engineering functions with specification authority embedded in design gates. Direct supplier relationships dominate, with REACH-compliant and low-VOC formulations mandatory for European and North American facility qualification.
- Contractors:Regional construction and installation specialists purchase through distributor networks with price-sensitive, project-based procurement patterns.
- Retailers:Consumer and light industrial applications stock standardized grades for DIY and maintenance markets.
- Repair Services:Aftermarket automotive and electronics refurbishment demands small-lot, quick-turn fulfillment.
Manufacturer demand absorbs the highest-performance grades. Contractor volume expands most quickly in India's commercial retrofit segment.
Distribution Channel:
Channel selection correlates with buyer technical capability and lot size requirements.
- Direct Sales:Technical specification collaboration between adhesive compounders and OEM engineering teams dominates automotive and electronics procurement. Application-specific formulation development, joint testing protocols, and long-term supply agreements characterize these relationships.
- Retail:Big-box and specialty distributors serve contractor and consumer segments with standardized product ranges.
- E-commerce:Digital procurement penetrates small-lot industrial and aftermarket repair segments.
- Wholesalers:Regional distributors aggregate construction and packaging demand with inventory positioning advantages.
Direct sales capture the highest-margin specifications. E-commerce infrastructure investment is climbing fastest among mid-tier compounders seeking aftermarket access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized adhesive formulation chemists cluster in Germany's industrial corridor and Japan's chemical manufacturing belt, anchoring premium product development. China's eastern seaboard concentrates electronics assembly demand, while US Gulf Coast petrochemical infrastructure feeds polyurethane feedstock supply. India's construction retrofit market draws regional compounder investment as energy efficiency codes tighten.
Germany
Automotive lightweighting programs at BMW and Mercedes-Benz compress bonding specifications toward structural foam tapes for aluminum-composite body assemblies. KBA vehicle safety mandates and EU REACH isocyanate labeling restrictions accelerate waterborne formulation adoption. The Baden-Württemberg and Bavaria industrial corridors host Henkel AG & Co. KGaA and specialized compounders serving multi-material vehicle platforms.
China
EV battery pack assembly and semiconductor packaging concentrate demand for thermal interface foam bonding solutions. MIIT new energy vehicle subsidies and GB indoor air quality standards shape procurement criteria for domestic and export markets. The Yangtze River Delta manufacturing belt around Shanghai and Suzhou clusters electronics contract manufacturers embedding adhesive selection into platform design gates.
Japan
Automotive OEMs and electronics assemblers specify high-performance acrylic foam tapes for thermal expansion accommodation in precision assemblies. METI carbon neutrality roadmaps and JIS building material standards elevate low-emission formulation requirements. The Chubu region around Nagoya anchors polyurethane and silicone adhesive production serving domestic automotive and industrial markets.
United States
Construction envelope sealing and automotive aftermarket applications drive volume demand across commercial and residential projects. EPA VOC emission standards for industrial adhesives and OSHA workplace exposure limits compress solvent-containing formulation margins. The Southeast automotive manufacturing corridor and Texas Gulf Coast petrochemical complexes concentrate compounding and feedstock supply infrastructure.
India
Commercial building retrofit and infrastructure expansion absorb low-VOC foam sealants as energy efficiency codes penetrate tier-two cities. BIS certification alignment for construction materials opens specification pathways previously dominated by unorganized suppliers. Maharashtra and Gujarat industrial zones attract regional compounder capacity investments targeting Western India construction demand.
Foam Adhesive Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across distinct technology tiers in the foam adhesive market. Integrated chemical conglomerates with captive resin supply dominate volume segments, while specialized compounders capture premium niches through application-specific formulation expertise. Three archetypes define competitive positioning: diversified materials conglomerates with adhesive divisions, pure-play tape and bonding specialists, and regional compounders serving construction and packaging markets. Consolidation pressure intensifies as REACH compliance costs and hot-melt equipment upgrades favor scaled players with balance sheet capacity.
Among diversified materials conglomerates, 3M and Saint-Gobain S.A. exemplify the integrated archetype combining polymer chemistry expertise with global specification access. Nitto Denko Corporation anchors the pure-play specialist tier with Japanese precision manufacturing heritage. These three entities represent contrasting strategic postures: technology licensing versus captive manufacturing versus regional market penetration.
| Leading Market Players |
|---|
| Nitto Denko Corporation |
| Saint-Gobain S.A. |
| 3M |
| Scapa Group PLC |
| Tesa SE |
| Henkel AG & Co. KGaA |
| Intertape Polymer Group |
| Rogers Corporation |
| Avery Dennison Corporation |
| Others |
Value Network & Pricing Analysis
The EU Green Deal's embodied carbon thresholds for construction materials gate qualified supply access and premium-tier pricing power for foam adhesive compounders. Buyers seeking specification entry into European public procurement must demonstrate verified carbon footprints, creating a bifurcated market where certified suppliers command structural premiums and uncertified competitors face margin compression or market exclusion.
Pricing Analysis
Bundled formulation-development services separate from unbundled commodity tape supply define the dominant pricing split. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation, with REACH-compliant and low-VOC formulations capturing the top tier. Cost compression in standard-grade polyurethane runs through MDI feedstock volatility, while automotive OEMs exhibit the lowest price sensitivity due to specification-locked supply agreements. Regional contractors purchasing through distributor networks display the highest price sensitivity, prioritizing per-meter cost over performance longevity.
Supply Chain Analysis
Dual-sourcing mandates from tier-one automotive and electronics OEMs require compounders to qualify secondary resin suppliers and maintain geographic redundancy. Feedstock supply draws from Germany, Japan, and the US Gulf Coast for isocyanate precursors and specialized tackifying resins, while acrylic polymer production clusters in South Korea and Taiwan. Single-source vulnerability concentrates in high-performance viscoelastic polymer cores where proprietary formulations create captive supply relationships. Distribution runs through direct technical sales for OEM specifications and regional wholesalers serving construction and packaging segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where European REACH compliance costs and Asian manufacturing scale differentials create relocation incentives for mid-tier compounders.
For Market Incumbents: Extend specification lock-in through joint application engineering with automotive OEMs transitioning to multi-material platforms. Deepen backward integration into captive tackifying resin production to offset Asian feedstock price volatility. Accelerate waterborne formulation R&D to defend margin position against regulatory compression on solvent-containing alternatives.
For New Entrants and Emerging Players: Capture India's commercial building retrofit segment where BIS certification alignment opens specification pathways previously blocked to unorganized suppliers. Target thermal interface foam bonding for EV battery pack assembly in China's eastern manufacturing corridor. Lead with technical service partnerships rather than price competition to bypass entrenched distributor relationships.
For Investors and Strategic Acquirers: Roll-up economics work for regional European compounders because REACH registration costs and hot-melt equipment upgrades favor scaled balance sheets over fragmented operations. The five-to-ten year viability window rewards platforms consolidating specification access across automotive and electronics verticals. Watch for MDI price inflection as the signal triggering accelerated M&A among margin-stressed polyurethane specialists.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tackifying Resins | Captive resin supply insulates margin stability against Asian petrochemical price cycles. |
| Waterborne Formulation Scale-Up | REACH and EPA VOC compliance secures specification access in European and North American automotive. |
| Joint Application Engineering Partnerships | Direct OEM collaboration displaces distributor influence in structural foam tape procurement. |
| Regional Capacity Expansion in India | BIS-certified local production captures commercial retrofit demand as energy codes tighten. |
| Long-Term Supply Agreements with EV Battery Assemblers | Platform-embedded adhesive selection locks in volume through China's eastern manufacturing corridor. |
Research Methodology
Bottom-up automotive and electronics demand modeling reconciled against top-down chemical feedstock and compounding capacity tracking forms the analytical core of this study. Primary interviews with adhesive formulation chemists, Tier 1 automotive procurement managers, electronics contract manufacturing engineers, and construction materials distributors combined with secondary validation from ECHA REACH registration databases, EPA VOC emission filings, customs trade data, and SEC disclosures from diversified materials conglomerates. Triangulation between end-use consumption estimates and supply-side production capacity ensures statistical coherence across segmentation dimensions.
Input-output matrices map chemistry-specific feedstock requirements through formulation, compounding, and end-use application stages across the projection horizon. Segmentation dimensions modeled include chemistry type, application sector, end-user archetype, and regional regulatory cluster, with CAGRs derived from elasticity-adjusted demand curves and capacity expansion schedules. Industry-specific forecast inputs incorporate EV battery pack production ramp rates and automotive lightweighting program timelines without year-specific anchoring.
Feedstock price volatility, regulatory divergence between jurisdictions, and substitution pressure from emerging thermal gap fillers are the dominant revision risks to the outlook. Deviation in MDI and TDI pricing cycles would shift margin and competitive positioning materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Europe Reactive Adhesives Market
Adhesives & Sealants
Temporary Bonding Adhesives Market
Adhesives & Sealants
Butyl Adhesive Market
Adhesives & Sealants
Plastic Adhesives Market
Adhesives & Sealants
Europe Contact Adhesives Market
Adhesives & Sealants
North America Epoxy Curing Agents Market
Adhesives & Sealants
South America Reactive Adhesives Market
Adhesives & Sealants
Polyurethane (PU) Adhesives Market
Adhesives & Sealants
Global Underfill Material Market
Adhesives & Sealants
China Construction Chemicals Market
Adhesives & Sealants
Middle East & Africa Construction Adhesives & Sealants Market
Adhesives & Sealants
Middle East and Africa Adhesives Market
Adhesives & Sealants
Low Trauma/Skin Friendly Adhesives Market
Adhesives & Sealants
Marine Sealants Market
Adhesives & Sealants
Structural Sealants Market
Adhesives & Sealants
Global Construction Adhesives and Sealants Market