
 Lithium-Ion Battery Housing Cases Market | 2026-2036
Lithium-Ion Battery Housing Cases Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium-Ion Battery Housing Cases Market Insights
Modular case architecture is decoupling housing procurement from pack assembly, letting automakers source enclosures separately from cell integration. SGL Carbon leverages its carbon fiber composite expertise to compete in premium lightweight segments where every kilogram matters for range. ThyssenKrupp AG anchors European supply through integrated aluminum rolling and closed-loop recycling operations near its Duisburg mills. Novelis specializes in high-recycled-content aluminum sheet, positioning its housing-grade alloys for OEMs with binding carbon-reduction targets.
Lithium-ion battery housing cases are structural enclosures that protect electrochemical cells from mechanical damage, thermal runaway propagation, and environmental intrusion while providing mounting interfaces for cooling systems and electrical management hardware. These components typically incorporate flame-retardant polymers, corrosion-resistant aluminum alloys, or fiber-reinforced composites engineered to withstand crush loads and vibration profiles specified by UN 38.3 testing protocols. Aluminum housings dominate automotive applications where crashworthiness and thermal conductivity requirements are most stringent, while plastic cases sustain cost-sensitive consumer electronics volumes. Modular cases represent the fastest-growing structural category as platform-sharing strategies across EV lineups demand standardized enclosure footprints. Custom designs still occupy the margin pool in heavy industrial and specialty energy storage installations where non-standard cell configurations prevail.
UN 38.3 lithium battery transport regulations, China's GB/T standards for power battery safety, and the EU Battery Regulation collectively tighten housing integrity, material traceability, and end-of-life recyclability mandates. GB/T testing protocols specifically require housing cases to contain thermal events without external flame propagation, directly shaping aluminum thickness and venting design specifications. Stakeholders must monitor how evolving solid-state cell formats alter housing structural loads, cooling interface requirements, and sealing geometries before committing to multi-year tooling investments.
Market Dynamics
Platform-sharing strategies across EV lineups are decoupling housing procurement from pack assembly, forcing suppliers to design modular enclosures that serve multiple vehicle architectures without customization.
Growth Catalysts
- EU Battery Regulation:Binding recyclability mandates and carbon footprint disclosure requirements are pushing OEMs toward closed-loop aluminum suppliers with verified material traceability.
- Cell-to-pack architectures:Elimination of module frames reduces housing internal complexity while increasing structural load requirements on the enclosure itself.
- Germany's automotive corridor:Dedicated battery assembly facilities operated by BMW, Volkswagen, and Mercedes-Benz concentrate demand for crash-tested housing designs.
Market Restraints
- Primary aluminum price volatility:Energy-intensive smelting operations expose housing costs to electricity price spikes and carbon border adjustment mechanisms.
- Chinese supply concentration:GB/T certification bodies and rolling mill capacity cluster domestically, creating bottleneck risks for non-Chinese OEMs.
- Thermal runaway containment limits:Solid-state cell chemistries promise reduced flammability but remain unproven at automotive scale, delaying housing redesign commitments.
Strategic Opportunities
- Second-life stationary storage:Retired EV battery housings require refurbishment protocols and standardized mounting interfaces for grid-scale redeployment.
- India's PLI scheme for ACC batteries:Domestic cell manufacturing incentives are attracting housing suppliers to establish rolling and extrusion capacity near emerging pack assembly zones.
- Carbon fiber composite convergence with automated fiber placement:Aerospace-derived manufacturing methods are reducing cycle times for premium lightweight enclosures.
Industry Challenges
- UN 38.3 certification timelines:Updated crush and vibration testing protocols extend validation cycles for new housing geometries.
- Multi-material bonding expertise:Hybrid aluminum-composite designs require adhesive selection and surface preparation capabilities scarce in traditional metal-forming workforces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium-Ion Battery Housing Cases Market |
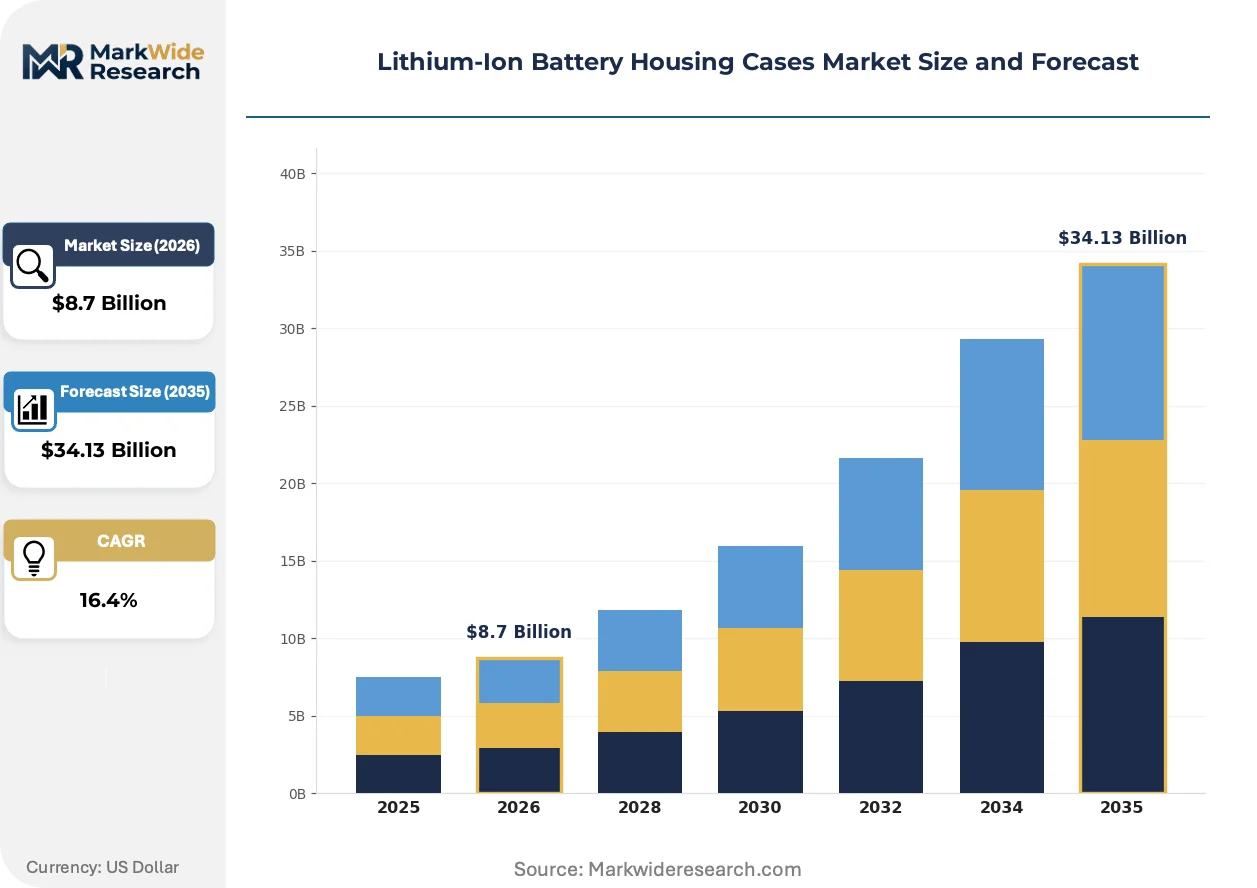
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Aluminum, Plastic, Steel, Composite Application: Consumer Electronics, Automotive, Industrial Equipment, Energy Storage Structure: Sealed Cases, Open Cases, Modular Cases, Custom Designs Size: Small, Medium, Large, Custom |
| Companies Covered | SGL Carbon, ThyssenKrupp AG, Novelis, GF Casting Solutions, Nemak, Magna International Inc., Gestamp, Minth Group Co., Ltd., Norsk Hydro ASA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium-Ion Battery Housing Cases Market Trends and Innovations
Structural integration of thermal management channels into housing walls is eliminating discrete cooling plates, compressing part count while complicating die-casting and extrusion tooling.
Chassis-integrated battery enclosures are unifying crash structure and energy containment functions into single aluminum castings or extruded profiles. Automakers adopting skateboard platforms specify these designs for cross-vehicle reuse. This unifying architecture is collapsing the historical separation between body-in-white engineering and battery pack development, forcing housing suppliers to co-design with vehicle platform teams earlier in development cycles.
China's updated GB/T 38031-2025 power battery safety standards mandate five-minute thermal runaway warning intervals and flame containment without external propagation. Housing suppliers must thicken aluminum walls or engineer venting geometries that satisfy these timelines. European OEMs importing cells into China must dual-certify enclosures against both UN 38.3 and GB/T protocols, extending qualification programs.
Fleet operators and energy storage developers now specify housing recyclability percentages and end-of-life material recovery rates in procurement tenders. Third-party certification of recycled content is displacing self-reported environmental claims. Germany's automotive OEMs and California's utility-scale storage developers are most advanced in embedding these requirements into supplier scorecards.
Lithium-Ion Battery Housing Cases Market Segmentation
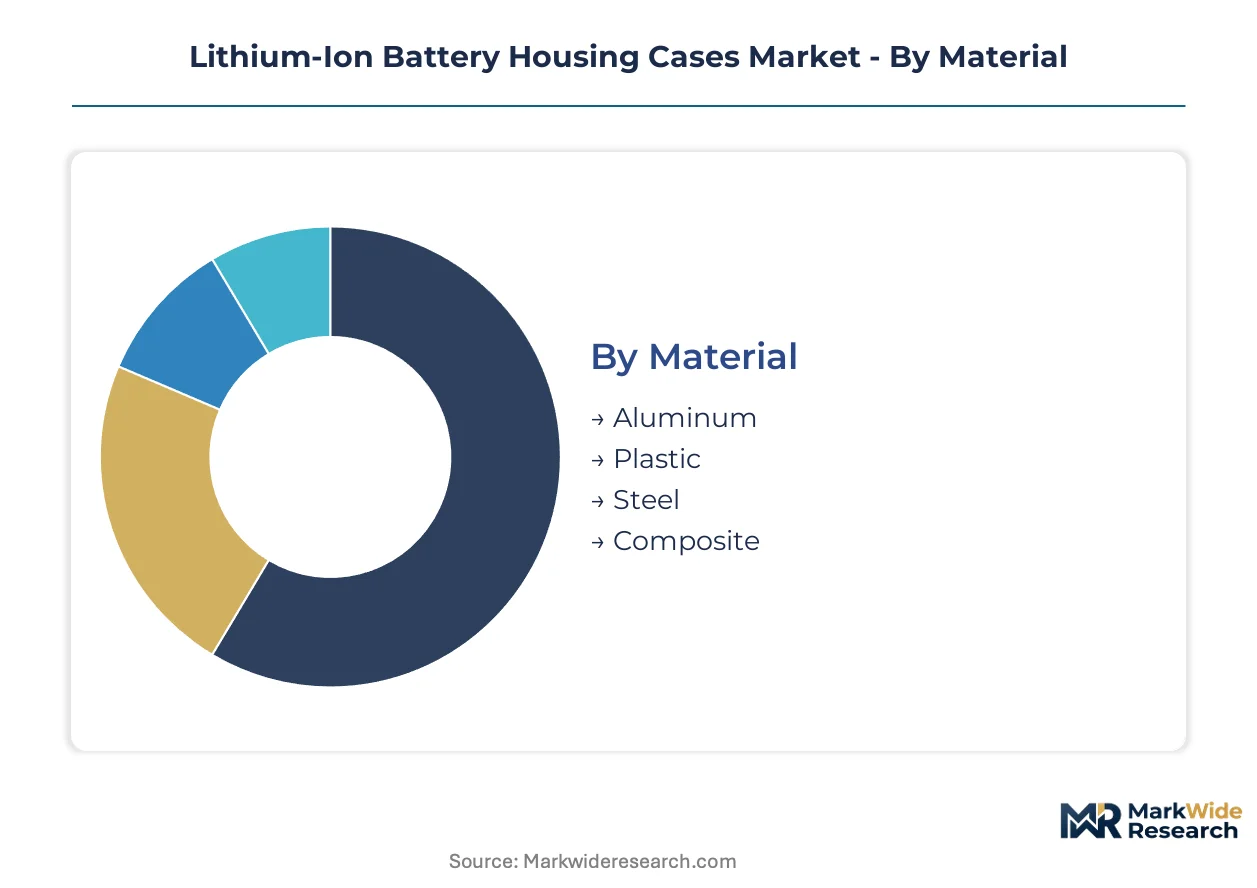
Material choices in battery housing directly determine crashworthiness, thermal conductivity, and recyclability compliance. Structural formats now separate procurement from pack assembly, reshaping supplier relationships across automotive and stationary storage applications.
Material:
Supply concentration in aluminum rolling capacity shapes cost structures and certification access for housing manufacturers.
- Aluminum:Corrosion-resistant alloys dominate automotive platforms where UN 38.3 crush loads and GB/T thermal containment requirements apply. German OEMs specify high-recycled-content grades from Novelis and ThyssenKrupp to meet EU Battery Regulation carbon disclosure mandates.
- Plastic:Flame-retardant polymers sustain cost-sensitive consumer electronics volumes where weight minimization matters less than unit economics. Chinese molding operations cluster near Shenzhen and Dongguan cell assembly zones.
- Steel:Cold-rolled grades persist in heavy industrial equipment where puncture resistance outweighs mass penalties.
- Composite:Carbon fiber-reinforced variants from SGL Carbon serve premium EV segments where range optimization justifies material premiums.
Today's leader: Aluminum. Tomorrow's challenger: Composite.
Application:
End-use differentiation separates high-volume standardized procurement from low-volume custom engineering.
- Automotive:Chassis-integrated enclosures from BMW, Volkswagen, and Mercedes-Benz assembly facilities demand crash-tested designs with five-minute thermal runaway containment per GB/T 38031-2025. Cell-to-pack architectures increase structural load requirements on housings.
- Energy Storage:Grid-scale developers in California specify end-of-life material recovery rates in procurement tenders, pushing suppliers toward closed-loop aluminum certification.
- Consumer Electronics:Smartphone and laptop manufacturers prioritize thin-wall plastic molding for cost containment at billion-unit scales.
- Industrial Equipment:Forklift and mining vehicle OEMs specify custom sealing geometries for non-standard cell configurations.
Automotive commands premium pricing. Energy storage is climbing the fastest.
Structure:
Platform-sharing strategies favor formats that decouple housing sourcing from pack integration.
- Modular Cases:Standardized footprints enable cross-vehicle reuse across skateboard EV platforms, collapsing historical separation between body-in-white and battery engineering teams.
- Sealed Cases:IP67-rated enclosures protect marine and outdoor stationary installations from environmental intrusion.
- Custom Designs:Heavy industrial and specialty storage applications retain non-standard geometries for unique cell configurations.
- Open Cases:Rack-mounted data center and telecom backup systems prioritize service access over environmental sealing.
Modular cases expand most quickly. Custom designs defend margin pools.
Size:
Format scaling determines tooling amortization and logistics efficiency across manufacturing footprints.
- Large:EV battery enclosures require integrated thermal management channels and structural mounting interfaces, complicating die-casting and extrusion tooling investments.
- Small:Consumer electronics housings sustain high-volume stamping and injection molding operations with rapid tool changeover.
- Medium:Power tool and e-bike applications balance portability with cell count optimization.
- Custom:Medical device and aerospace applications specify exact dimensional tolerances for specialized electrochemical stacks.
Large formats concentrate supplier investment. Custom sizes extract premium engineering fees.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Battery housing manufacturing originated in German automotive engineering centers before expanding to Chinese rolling mill corridors and North American EV assembly zones. Production geography now tracks cell manufacturing investments, with housing suppliers co-locating near pack assembly facilities to reduce logistics costs and qualification timelines.
Germany
BMW, Volkswagen, and Mercedes-Benz operate dedicated battery assembly facilities across Bavaria and Lower Saxony, concentrating demand for crash-tested aluminum enclosures. KBA vehicle safety protocols and EU Battery Regulation carbon disclosure mandates push OEMs toward high-recycled-content suppliers. The Duisburg-Ruhr industrial corridor anchors European aluminum rolling and closed-loop recycling capacity for housing-grade alloys.
China
Domestic EV production exceeding seven million units annually drives housing procurement at unprecedented scale. GB/T 38031-2025 power battery safety standards mandate five-minute thermal runaway containment, directly shaping aluminum wall thickness specifications. Shenzhen and Dongguan molding clusters supply flame-retardant polymer cases for consumer electronics alongside automotive-grade rolling mill output in Shandong and Henan provinces.
United States
IRA domestic content incentives are reshoring cell and pack assembly to Michigan, Tennessee, and South Carolina manufacturing corridors. NHTSA crashworthiness standards and UN 38.3 transport regulations govern housing certification for automotive applications. Detroit-area stamping operations and Tennessee aluminum extrusion capacity are expanding to serve Ford, GM, and Volkswagen Chattanooga battery facilities.
Japan
Panasonic and Toyota joint ventures in Kyoto and Shiga prefectures sustain precision aluminum forming expertise for hybrid and solid-state battery platforms. METI battery supply chain security initiatives prioritize domestic housing procurement for strategic energy storage applications. Nagoya-area automotive suppliers coordinate enclosure development with Toyota's next-generation cell-to-pack architectures.
South Korea
LG Energy Solution and Samsung SDI cell manufacturing in Gyeonggi and Chungcheong provinces generates housing demand for export-oriented EV programs. MFDS industrial safety frameworks and KSA quality certification shape supplier qualification requirements. Busan-Ulsan heavy industry zones host aluminum processing capacity serving both automotive and marine battery enclosure segments.
Lithium-Ion Battery Housing Cases Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material specialization and certification depth, with carbon fiber composite specialists commanding material premiums while aluminum rollers compete on scale and recycled-content verification. The supplier base stratifies into three tiers: integrated metals conglomerates with captive rolling capacity, specialized automotive Tier-1s with platform engineering relationships, and regional fabricators serving aftermarket and industrial niches. Dominant competitive moves include backward integration into aluminum smelting and recycling streams, plus co-development partnerships with EV platform engineering teams for chassis-integrated enclosure designs.
Within the premium lightweight materials tier, SGL Carbon exemplifies carbon fiber composite specialization for range-critical EV segments. ThyssenKrupp AG anchors European supply security through integrated Duisburg-based aluminum operations. Novelis occupies a position at the intersection of high-recycled-content certification and automotive OEM carbon-reduction procurement scorecards. These three represent divergent strategic archetypes: materials science specialization, vertical metals integration, and circular-economy positioning.
| Leading Market Players |
|---|
| SGL Carbon |
| ThyssenKrupp AG |
| Novelis |
| GF Casting Solutions |
| Nemak |
| Magna International Inc. |
| Gestamp |
| Minth Group Co., Ltd. |
| Norsk Hydro ASA |
| Others |
Pricing and Supply Chain Analysis
EU Battery Regulation carbon disclosure mandates are forcing OEM procurement teams toward high-recycled-content aluminum suppliers, compressing margins for primary metal rollers while rewarding closed-loop recyclers with verified material traceability. This specification shift is restructuring supplier tiers around certification depth rather than tonnage scale.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates crash-tested automotive enclosures from industrial commodity cases and consumer electronics plastic housings. Price differentiation hinges on GB/T 38031-2025 thermal containment certification and high-recycled-content aluminum grade verification. Cost compression in standard aluminum tiers is intensifying because Chinese rolling mill overcapacity floods export markets. Fleet operators and utility-scale storage developers show lowest price sensitivity, prioritizing end-of-life material recovery guarantees over unit cost.
Supply Chain Analysis
Regional distribution centers in Germany's Duisburg-Ruhr corridor, China's Shandong province, and Tennessee's automotive manufacturing zones form a hub-and-spoke pattern serving pack assembly facilities. Raw material flows draw from Australian bauxite, Chinese alumina refining, and European scrap aluminum collection networks. Single-source vulnerability concentrates in Chinese GB/T certification bodies and rolling mill capacity. Distribution runs through just-in-time direct delivery to OEM battery assembly lines, bypassing traditional warehousing for large-format EV enclosures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in premium lightweight segments where cell-to-pack architectures increase structural load requirements on housings, justifying material science premiums over commodity aluminum tonnage.
For Market Incumbents: Cement platform engineering relationships through early co-development partnerships for chassis-integrated enclosure designs. Deepen captive recycling operations to secure high-recycled-content aluminum certification ahead of EU Battery Regulation enforcement. Defend against carbon fiber composite substitution in range-critical EV segments by demonstrating crashworthiness cost parity at scale. For New Entrants and Emerging Players: Enter via India's PLI scheme for ACC batteries, where domestic cell manufacturing incentives are attracting housing suppliers without established incumbent relationships. Target second-life stationary storage refurbishment protocols, where standardized mounting interfaces for grid-scale redeployment remain underdeveloped. Pursue automated fiber placement expertise licensed from aerospace manufacturing to reduce carbon fiber composite cycle times. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized automotive Tier-1s possessing platform engineering relationships and GB/T dual-certification capabilities. Long-term viability favors suppliers with backward integration into aluminum smelting and recycling streams rather than pure fabrication plays. Watch solid-state cell chemistry commercialization timelines as the inflection indicator for housing structural load and cooling interface redesign cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycling Streams | Captive supply of high-recycled-content aluminum secures EU Battery Regulation compliance for German OEM procurement teams. |
| GB/T Dual-Certification Investment | UN 38.3 plus Chinese thermal containment validation opens access to seven-million-unit annual EV production volumes. |
| Platform Engineering Partnership | Early co-development with skateboard platform teams collapses historical separation between body-in-white and battery engineering. |
| Automated Fiber Placement Adoption | Aerospace-derived manufacturing methods reduce carbon fiber composite cycle times for premium lightweight enclosure segments. |
| Second-Life Refurbishment Capability | Standardized mounting interfaces for grid-scale stationary storage extend housing economic life beyond automotive first use. |
Research Methodology
Multiple input streams — procurement director interviews at BMW, Volkswagen, and Mercedes-Benz battery assembly facilities, technical consultations with aluminum rolling mill operations managers, and regulatory affairs discussions with GB/T certification bodies — were reconciled against trade flow data from Chinese customs, EU aluminum association production statistics, and SEC filings from listed housing suppliers. Bottom-up volume estimates from pack assembly facility capacities were triangulated with top-down OEM procurement budget allocations.
Data-stream reconciliation across material grade, application end-use, structural format, and regional production cluster dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories weighted by aluminum alloy pricing indices and composite material cost curves. Cell-to-pack architecture penetration rates and solid-state cell chemistry development milestones served as critical forecast inputs.
Inputs from OEM procurement directors, rolling mill technical leads, and certification body regulators were available through the study window; gaps in solid-state cell commercialization timelines introduce uncertainty bands around structural load requirement assumptions. Forecasts reflect documented assumptions regarding platform-sharing strategy adoption and regulatory enforcement timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Infrastructure
North America Electric Vehicle Battery Separator Market
Battery Infrastructure
China Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
North America Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
Advance Battery Technologies Market
Battery Infrastructure
Global Automotive 48 Volt Battery System Market
Battery Infrastructure
Battery Lug Market
Battery Infrastructure
ASEAN Countries Electric Vehicle Battery Separator Market
Battery Infrastructure
Solar Containers Market
Battery Infrastructure
Battery Production Machine Market
Battery Infrastructure
North America Electric Vehicle Battery Electrolyte Market
Battery Infrastructure
Lithium-Ion Battery Filling Machine Market
Battery Infrastructure
Battery Swap-Ready Pack Systems for Urban Fleets Market
Battery Infrastructure
Global Battery Packaging Market
Battery Infrastructure
Europe Lithium Foil Market
Battery Infrastructure
Carbon Battery Bank Market
Battery Infrastructure
Battery Tray Market