
 China Electric Vehicle Battery Separator Market | 2026-2036
China Electric Vehicle Battery Separator Market Size, Share, and Industry Trends Forecast 2026-2036
China Electric Vehicle Battery Separator Market Insights
China's dual carbon goals and MIIT battery safety mandates are realigning procurement standards across the separator value chain. SEMCORP leverages integrated polymer film production to sustain cost advantages in high-volume contracts. Senior anchors its position through ceramic coating specialization for premium cell architectures. Sinoma competes via in-house control over base material supply, reducing feedstock exposure.
An electric vehicle battery separator is a microporous membrane, typically 25–40 microns thick, positioned between cathode and anode to prevent internal short circuits while enabling lithium-ion transport through controlled porosity. Polymer separators dominate current manufacturing output due to established extrusion infrastructure and cost scalability, though ceramic separators are capturing margin pools in high-nickel cell designs where thermal runaway resistance commands premium positioning. Composite separators occupy a narrowing mid-tier as OEMs bifurcate procurement between cost-optimized polymer and safety-critical ceramic specifications.
GB standards under SAMR, MEE emissions frameworks, and MIIT new energy vehicle catalog requirements collectively dictate separator thermal stability thresholds and manufacturing facility compliance. NMPA-aligned battery safety protocols are forcing upstream material qualification cycles that favor suppliers with certified testing laboratories. Stakeholders must monitor how provincial carbon intensity audits reshape plant location economics and qualification timelines for separator makers serving CATL and BYD supply networks.
Market Dynamics
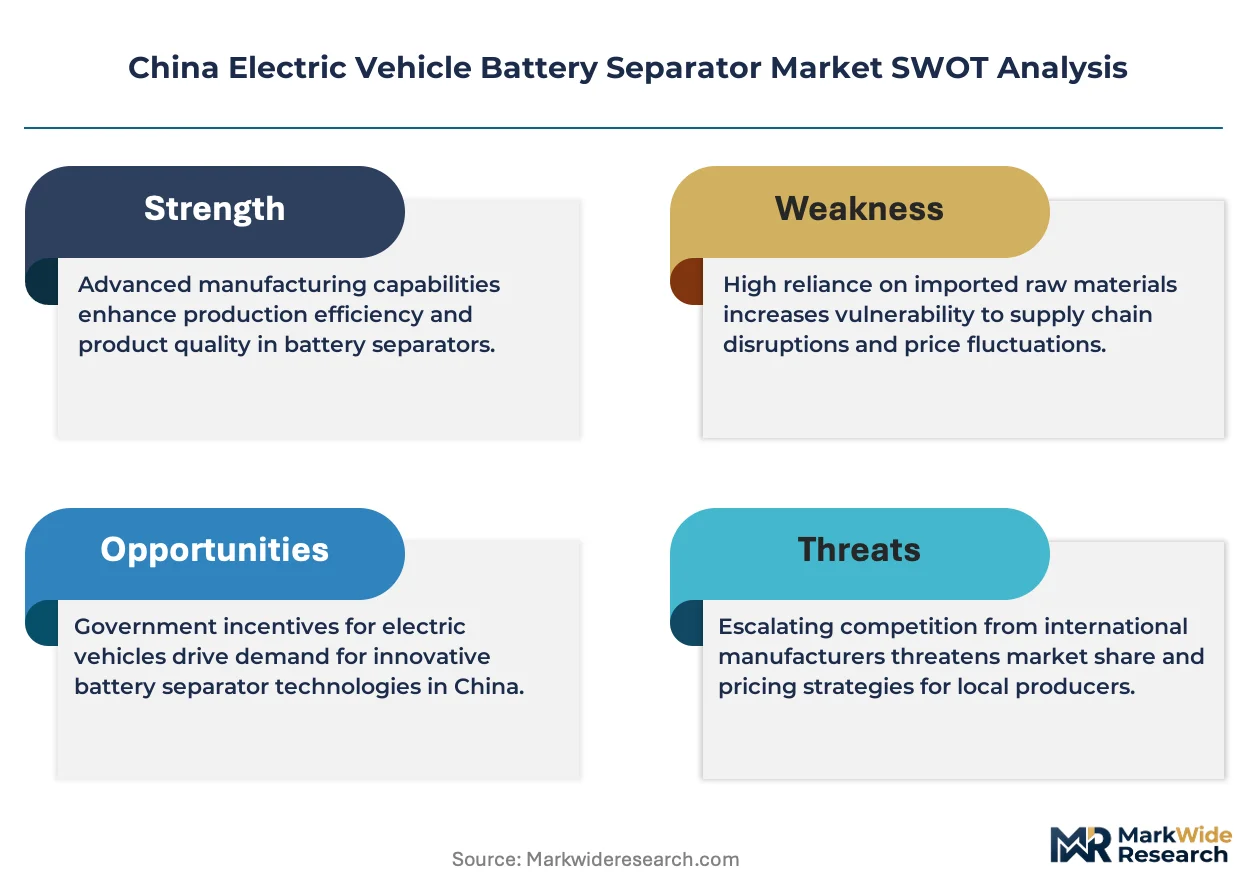
MIIT battery safety mandates and dual carbon goals are compressing qualification timelines while forcing separator suppliers to reconfigure manufacturing footprints around carbon intensity audits.
Growth Catalysts
- High-nickel cell architectures:OEMs specifying NCM 811 cathodes require ceramic-coated separators with enhanced thermal shutdown thresholds, pulling premium material volumes.
- Guangdong and Jiangsu procurement clusters:CATL and BYD supply chain localization is directing separator qualification spend toward domestic coating specialists with certified testing laboratories.
- Dual carbon goals:Provincial emissions frameworks under MEE are accelerating plant retrofits that favor suppliers with integrated polymer film production and captive energy supply.
Market Restraints
- Polypropylene feedstock volatility:Separator base material costs fluctuate with propylene monomer pricing, compressing margins for non-integrated coaters serving cost-optimized polymer specifications.
- Base material supply concentration:Domestic control over ultra-high molecular weight polyethylene remains concentrated among state-controlled petrochemical complexes, creating qualification bottlenecks for new entrants.
- GB standard thermal stability thresholds:SAMR-mandated testing protocols extend certification cycles, freezing out suppliers lacking in-house SAMR-accredited laboratories.
Strategic Opportunities
- Solid-state battery interface materials:Next-generation cell architectures require separator-compatible solid electrolyte interlayers, opening white space for composite material specialists.
- Ningbo manufacturing cluster expansion:CATL's Zhejiang base is localizing separator procurement, creating entry points for ceramic coating specialists with proven high-volume throughput.
- Carbon border adjustment readiness:MEE provincial audits are rewarding suppliers with renewable energy certificates, positioning certified plants for premium OEM contract tiers.
Industry Challenges
- Coating technician scarcity:Ceramic slurry formulation expertise concentrates among senior engineers at established players, constraining capacity scaling for mid-tier coaters.
- MIIT catalog synchronization:Separator qualification must align with quarterly NEV catalog updates, forcing suppliers to maintain parallel testing tracks for multiple cell formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Electric Vehicle Battery Separator Market |
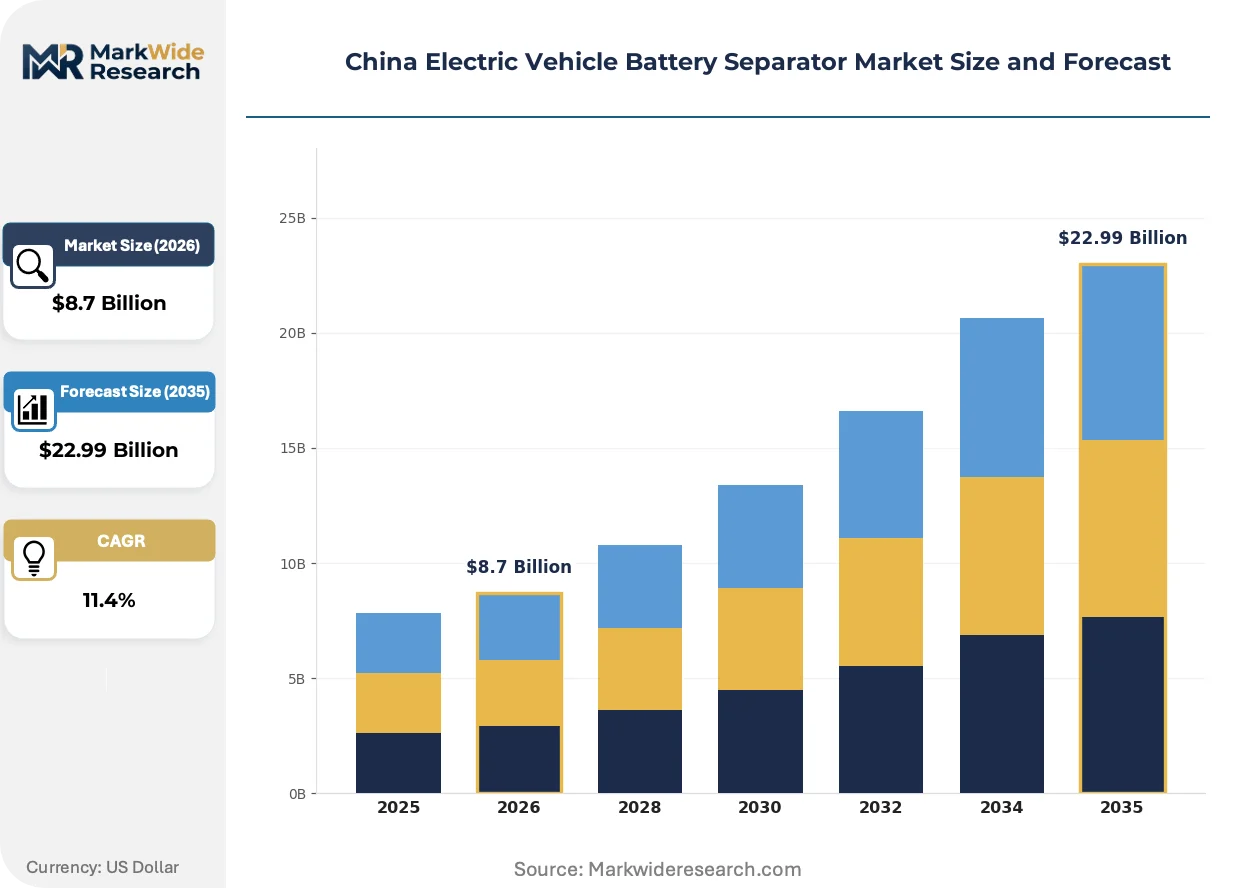
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Separators, Ceramic Separators, Composite Separators, Others End User: OEMs, Aftermarket Providers, Battery Manufacturers, Research Institutions Thickness: 25 Micron, 30 Micron, 35 Micron, 40 Micron Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Energy Storage Systems |
| Companies Covered | SEMCORP, Senior, Sinoma, Gellec, ZIMT, Huiqiang, Cangzhou Mingzhu, BS, Pulead, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Electric Vehicle Battery Separator Market Trends and Innovations
Ceramic coating specialization is bifurcating the supplier base between cost-optimized polymer producers and safety-critical ceramic specialists serving premium cell architectures.
Dry-process ceramic coating is overtaking wet-coating methods in high-nickel cell applications. The technology eliminates solvent recovery infrastructure while achieving more uniform particle distribution across microporous substrates. CATL and BYD procurement teams are fast-tracking dry-process qualified suppliers into premium contract tiers. This shift is compressing capital deployment timelines for wet-coating incumbents while rewarding equipment suppliers with dry-process turnkey installations.
MIIT new energy vehicle catalog requirements now mandate separator thermal runaway propagation resistance testing. The regulation forces upstream material qualification cycles that favor suppliers with certified testing laboratories co-located with manufacturing. Guangdong-based OEMs are responding by consolidating procurement around vertically integrated separators with in-house SAMR accreditation, freezing out trading-house intermediaries.
Buyer concentration around CATL and BYD supply networks is compressing switching cycles and unbundling after-sales technical service. Tier-2 cell makers are losing negotiating leverage as procurement teams centralize volume commitments in exchange for dedicated coating line allocations. This concentration is most visible in Shenzhen manufacturing clusters, where separator inventory now flows through OEM-managed consignment models rather than distributor-held stock.
China Electric Vehicle Battery Separator Market Segmentation
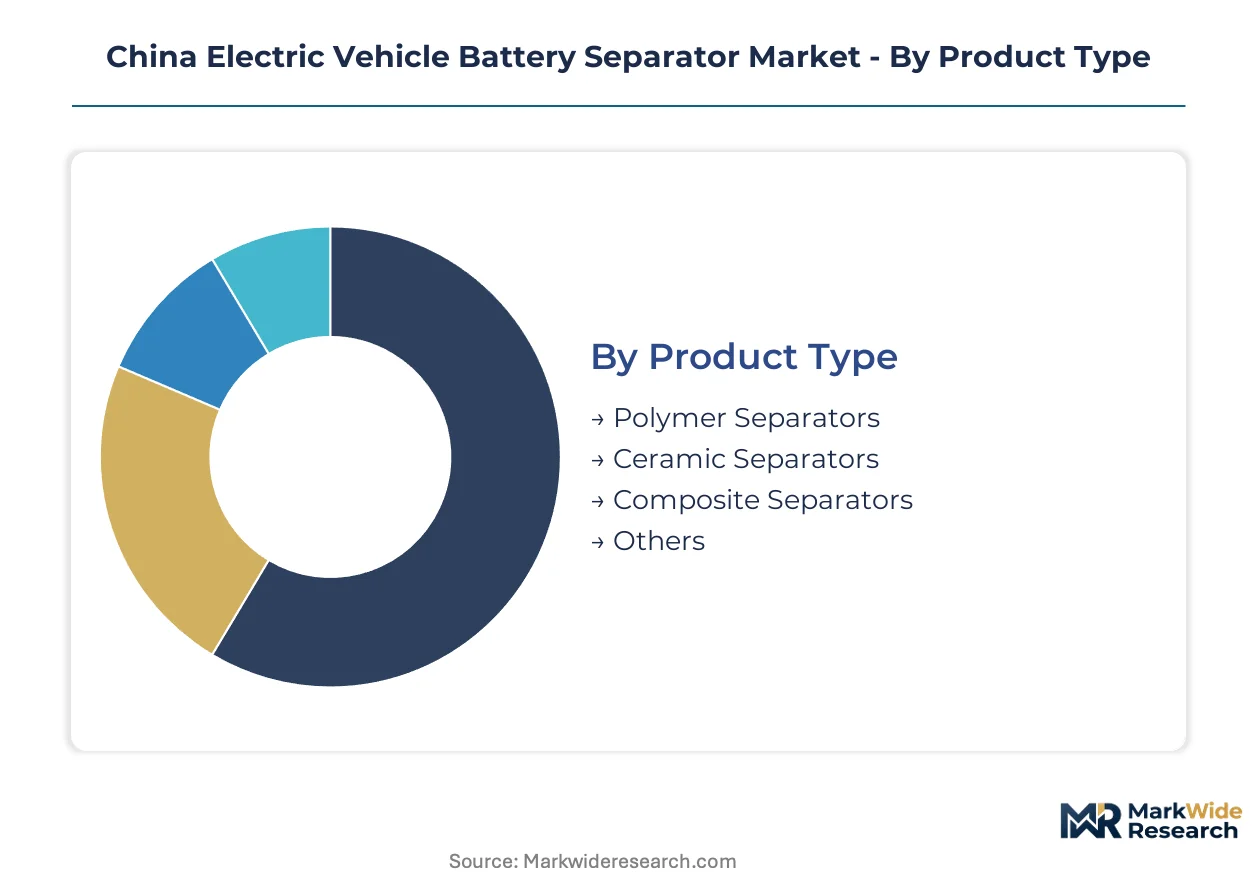
Battery separator procurement in China segments across material chemistry, cell integration depth, and OEM specification tiers. Each dimension shapes qualification cycles, pricing bandwidths, and supplier positioning within CATL and BYD supply networks.
Product Type:
Integration depth varies sharply: polymer separators deploy as standalone microporous films in cost-optimized cells, while ceramic coatings embed directly onto base substrates for thermal-critical architectures.
- Polymer Separators:Microporous polypropylene or polyethylene films, 25–40 microns thick, dominate volume production through established extrusion infrastructure. Guangdong-based OEMs specify these for standard-range passenger vehicles where cost-per-kWh drives procurement decisions.
- Ceramic Separators:Base polymer substrates coated with aluminum oxide or boehmite ceramic layers deliver enhanced thermal shutdown resistance. Jiangsu and Ningbo manufacturing clusters are scaling procurement of these specifications for NCM 811 high-nickel cell architectures where MIIT safety mandates tighten material requirements.
- Composite Separators:Hybrid constructions blending polymer matrices with ceramic fillers occupy mid-tier positioning.
- Others:Experimental architectures including solid-electrolyte interlayers and gel-polymer hybrids remain pre-commercial.
Polymer separators lead volumes today; ceramic separators are gaining share fastest.
End User:
Customer type determines contract structure: integrated cell makers demand dedicated coating line allocations, while aftermarket channels tolerate spot purchasing with looser technical service terms.
- OEMs:Passenger vehicle manufacturers including BYD and NIO specify separator grades through direct qualification agreements, locking in multi-year volume commitments with ceramic coating specialists.
- Battery Manufacturers:CATL, Gotion High-Tech, and EVE Energy consolidate procurement power through centralized separator sourcing, compressing supplier margins in exchange for guaranteed offtake volumes.
- Aftermarket Providers:Replacement cell producers and independent repair networks source polymer separators through distributor channels with minimal technical qualification overhead.
- Research Institutions:CAS-affiliated labs and university engineering centers purchase small-batch specialty separators for next-generation solid-state cell development.
Battery manufacturers command the largest procurement volumes; OEM direct sourcing is expanding most quickly.
Thickness:
Thickness selection trades ionic conductivity against mechanical integrity, with thinner specifications penetrating high-energy-density cell designs.
- 25 Micron:Ultra-thin specifications maximize energy density in premium passenger vehicle packs. Shenzhen-based OEMs are qualifying these for flagship EV platforms where cell-to-pack architectures eliminate module-level redundancy.
- 30 Micron:The prevailing standard balances manufacturing yield with performance, dominating current procurement across Guangdong and Jiangsu production bases.
- 35 Micron:Thicker constructions retain penetration in commercial vehicle applications where cycle life and abuse tolerance outweigh energy density priorities.
- 40 Micron:Legacy specifications persist in energy storage systems and two-wheeler segments with less stringent volumetric constraints.
30 micron specifications anchor current production; 25 micron grades are climbing the fastest.
Application:
End-use segmentation separates high-volume automotive qualification tracks from lower-volume specialty channels with divergent technical service requirements.
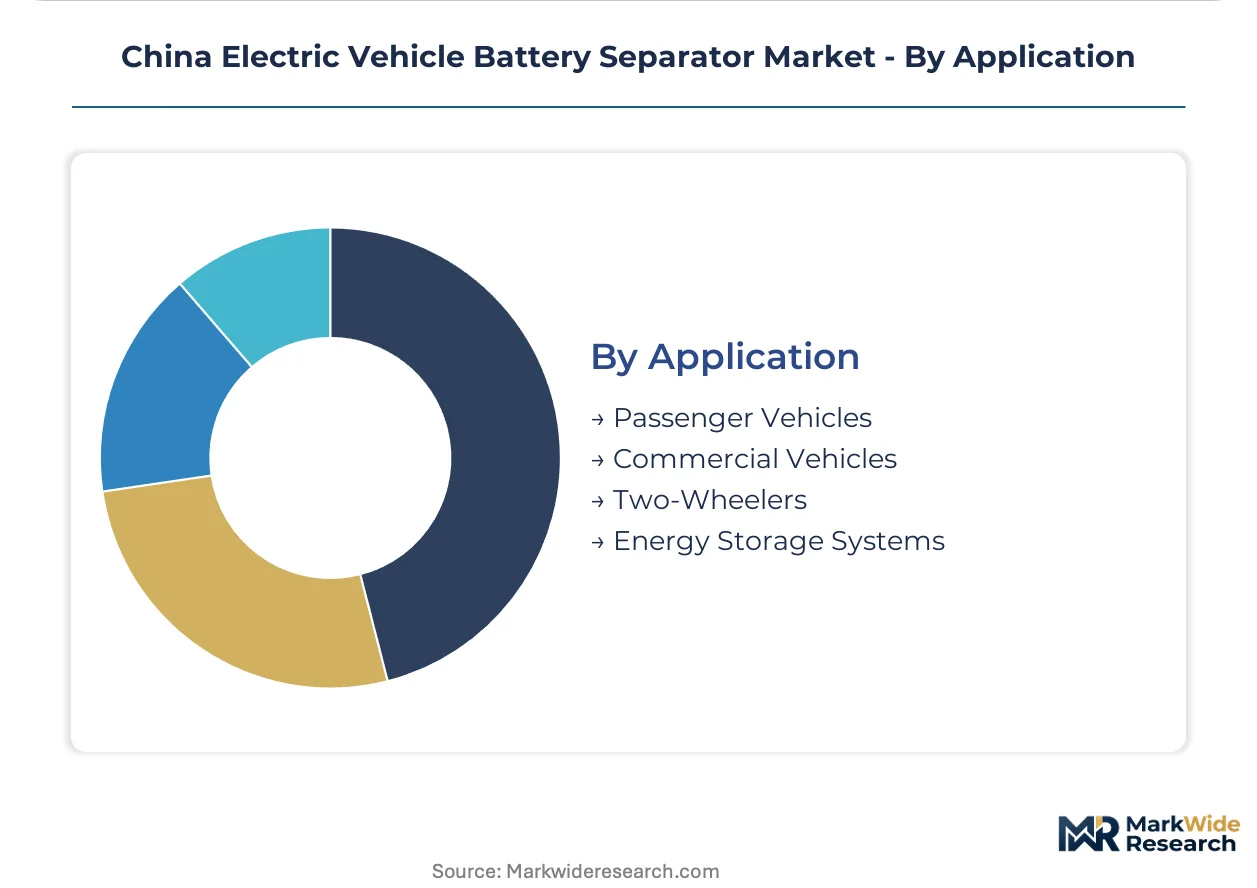
- Passenger Vehicles:NEV catalog requirements under MIIT mandate separator thermal runaway propagation resistance, forcing ceramic coating adoption in premium cell architectures. Ningbo and Shenzhen manufacturing clusters concentrate demand.
- Commercial Vehicles:Bus and truck applications prioritize cycle life and safety margins, sustaining demand for thicker polymer separators with proven field durability.
- Two-Wheelers:E-bike and e-motorcycle producers source cost-optimized polymer specifications through trading-house intermediaries with minimal qualification overhead.
- Energy Storage Systems:Grid-scale battery projects specify thicker separators emphasizing long-term reliability over energy density, with procurement flowing through state-backed utility tenders.
Passenger vehicles generate dominant volumes; energy storage systems are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Battery separator manufacturing in China traces its industrial lineage to the polymer film extrusion corridors of Jiangsu and Guangdong provinces, where petrochemical feedstock access and precision coating infrastructure first converged in the early 2010s.
Guangdong Province
Shenzhen and Dongguan manufacturing clusters concentrate procurement from CATL and BYD supply chains. MIIT battery safety mandates under the NEV catalog system enforce thermal runaway propagation testing. Ceramic coating specialists with SAMR-accredited laboratories dominate separator qualification tracks in the Pearl River Delta.
Jiangsu Province
Changzhou and Suzhou industrial bases anchor polymer film extrusion capacity serving high-volume passenger vehicle contracts. Dual carbon goals and MEE emissions frameworks accelerate plant retrofits toward renewable energy certificates. Domestic coaters with integrated base material production capture premium OEM contract tiers.
Zhejiang Province
Ningbo manufacturing expansion localizes separator sourcing for CATL's Zhejiang cell production base. Provincial carbon intensity audits reshape qualification timelines for suppliers seeking entry into premium procurement channels. Dry-process ceramic coating adoption concentrates among NCM 811 cell architecture suppliers.
Fujian Province
Xiamen and Quanzhou petrochemical corridors supply ultra-high molecular weight polyethylene feedstock for separator base materials. State-controlled petrochemical complexes maintain concentration over domestic UHMWPE production. New entrants face qualification bottlenecks accessing certified feedstock streams.
Sichuan-Chongqing Region
Chengdu and Chongqing emerging as western manufacturing alternatives as eastern coastal capacity saturates. Provincial governments offer renewable energy certificate incentives to attract separator producers with captive hydropower access. Cell-to-pack architecture adoption in regional OEM supply chains pulls ultra-thin 25 micron specifications.
China Electric Vehicle Battery Separator Market Competitive Landscape
Capital-heavy producers with integrated polymer film extrusion compete with asset-light coating specialists outsourcing base material supply. The supplier base bifurcates between scale-driven polymer manufacturers and safety-critical ceramic coating specialists. Three archetypes dominate: vertically integrated polymer producers, ceramic coating specialists with certified testing laboratories, and mid-tier composite separator fabricators. Capacity expansion and strategic qualification partnerships with CATL and BYD procurement teams constitute the dominant competitive moves.
Among established domestic fabricators, SEMCORP exemplifies the integrated polymer film archetype with captive base material production, while Senior occupies the ceramic coating specialist tier serving premium cell architectures. Sinoma anchors the state-affiliated feedstock control archetype through in-house UHMWPE supply chain positioning.
| Leading Market Players |
|---|
| SEMCORP |
| Senior |
| Sinoma |
| Gellec |
| ZIMT |
| Huiqiang |
| Cangzhou Mingzhu |
| BS |
| Pulead |
| Others |
Pricing and Supply Chain Analysis
Propylene monomer price volatility cascades through separator manufacturing into three distinct procurement tiers. Guangdong-based OEMs sourcing ceramic-coated specifications absorb premium positioning tied to SAMR-accredited testing, while Jiangsu polymer extrusion specialists compete on feedstock cost advantages.
Pricing Analysis
Contract-based long-term offtake dominates procurement between CATL, BYD, and qualified separator suppliers. Price differentiation hinges on SAMR certification grade and ceramic coating thickness specification. Cost compression in standard polymer tiers is intensifying because polypropylene feedstock volatility squeezes non-integrated coaters. Aftermarket channels serving two-wheeler producers exhibit highest price sensitivity; OEM direct contracts show lowest.
Supply Chain Analysis
Inland freight costs from Fujian petrochemical corridors to Jiangsu coating facilities shape regional cost structures. Supply concentrates in China, South Korea, and Japan for base polymer extrusion equipment and ceramic slurry formulation expertise. The chain draws from ultra-high molecular weight polyethylene feedstock, aluminum oxide ceramic powders, and precision coating machinery. Single-source vulnerability runs through state-controlled UHMWPE production. Distribution runs through OEM-managed consignment models in Shenzhen and Ningbo clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The China EV battery separator market represents a late-cycle quality story as NCM 811 high-nickel cell architectures displace standard-range specifications. OEM procurement teams now mandate ceramic coating adoption for thermal runaway resistance.
For Market Incumbents: Lock in dedicated coating line allocations with CATL and BYD procurement teams through multi-year volume commitments. Secure SAMR-accredited laboratory certification to freeze out trading-house intermediaries. Defensive capacity expansion in Zhejiang positions against Ningbo manufacturing cluster localization. For New Entrants and Emerging Players: Capture white space in solid-state battery interface materials where separator-compatible solid electrolyte interlayers remain pre-commercial. Target Sichuan-Chongqing regional OEM supply chains where renewable energy certificate incentives attract producers with captive hydropower. Lead with dry-process ceramic coating qualification to bypass wet-coating incumbent lock-in. For Investors and Strategic Acquirers: Asymmetric upside sits with ceramic coating specialists possessing certified testing laboratories and proven high-volume throughput. Five-to-ten year viability favors suppliers with backward integration into base polymer production. Monitor MIIT NEV catalog update frequency as inflection indicator for qualification cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Dry-Process Coating Capacity Expansion | Eliminates solvent recovery infrastructure while achieving uniform particle distribution for NCM 811 cells. |
| Backward Integration into UHMWPE Production | Reduces feedstock exposure to state-controlled petrochemical complex concentration in Fujian corridors. |
| SAMR Laboratory Accreditation Investment | Enables direct qualification tracks with Guangdong OEMs under MIIT thermal runaway propagation mandates. |
| Renewable Energy Certificate Procurement | Positions manufacturing plants for premium contract tiers under MEE provincial carbon intensity audits. |
| Solid-State Interface Material Development | Opens next-generation revenue streams as cell architectures evolve toward solid electrolyte interlayers. |
Research Methodology
Direct dialogue with separator plant managers, CATL procurement leads, ceramic slurry formulation engineers, and MIIT regulatory affairs specialists grounded qualitative assessment. Secondary validation drew from MIIT NEV catalog filings, SAMR GB standard updates, MEE emissions framework disclosures, and customs trade data for UHMWPE imports. Bottom-up capacity modeling triangulated against top-down OEM procurement spend estimates.
Segment-level outputs across the projection horizon reflect discrete modeling of polymer, ceramic, and composite separator chemistries by thickness specification and end-user category. CAGRs derived from regression analysis of historical procurement volumes against NEV production forecasts and cell energy density evolution curves. Forecast inputs incorporated MIIT battery safety mandate compliance timelines and provincial carbon intensity audit implementation schedules.
Feedstock price volatility, regulatory qualification cycle extensions, and solid-state battery technology substitution are the dominant revision risks to modeled outputs. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Infrastructure
United States Electric Vehicle Battery Separator Market
Battery Infrastructure
Global Battery Packaging Market
Battery Infrastructure
Italy Electric Vehicle Battery Separator Market
Battery Infrastructure
Lithium-Ion Battery Housing Cases Market
Battery Infrastructure
North America Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
Substation Battery Market
Battery Infrastructure
ASEAN Countries Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
Europe Electric Vehicle Battery Separator Market
Battery Infrastructure
Middle East and Africa Electric Vehicle Battery Separator Market
Battery Infrastructure
Battery Raw Materials Market
Battery Infrastructure
Germany Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
North America Electric Vehicle Battery Electrolyte Market
Battery Infrastructure
Battery Production Machine Market
Battery Infrastructure
ASEAN Countries Electric Vehicle Battery Separator Market
Battery Infrastructure
Battery Maintenance Service Market
Battery Infrastructure
Lithium-Ion Battery Filling Machine Market