
 Automotive Battery Plate Market | 2026-2036
Automotive Battery Plate Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Battery Plate Market Outlook
Passenger EV manufacturing is pivoting toward higher energy-density plate designs as automakers phase out legacy 12V auxiliary systems. Clarios leverages its North American production network to supply start-stop optimized plates. GS Yuasa Corporation anchors Asian supply through its Kyoto-based R&D campus and Osaka manufacturing footprint. Enersys competes in heavy-duty commercial segments with thick-plate designs for deep-cycle duty.
Automotive battery plates are cast or rolled metal grids, typically lead-alloy or coated copper, that serve as current collectors supporting active material adhesion and electron transfer during charge-discharge cycles. Manufacturing employs continuous casting, strip expansion, or punched-grid processes with calcium-tin or silver-bearing alloys to minimize corrosion and extend cycle life. Lead-Acid plates retain dominant installed base across ICE and mild-hybrid vehicles, though Lithium-Ion plate architectures capture margin pools in premium EV platforms. Start-Stop Systems technology commands growing plate surface area requirements as automakers deploy enhanced flooded and absorbed glass mat configurations for frequent cycling duty.
EPA emissions rules and NHTSA fuel economy standards in the United States pressure OEMs toward electrified powertrains, directly expanding plate demand for hybrid traction batteries. China's SAMR enforces GB standards for battery component safety, while the EU Green Deal accelerates CE-marked sustainable plate sourcing requirements. Stakeholders must monitor evolving alloy substitution trends as regulators tighten restrictions on lead content and carbon intensity across battery supply chains.
Market Dynamics
Passenger EV manufacturing is pivoting toward higher energy-density plate designs as automakers phase out legacy 12V auxiliary systems. China's NMPA battery safety standards and the EU's F-Gas Regulation are tightening material compliance requirements across casting and coating processes.
Growth Catalysts
- EPA emissions rules and NHTSA fuel economy standards:These US regulations pressure OEMs toward electrified powertrains, directly expanding plate demand for hybrid traction batteries across Detroit and Southern automotive clusters.
- Start-Stop Systems technology:Frequent cycling duty in mild-hybrid vehicles commands growing plate surface area requirements, driving enhanced flooded and absorbed glass mat configuration adoption.
- East Asian manufacturing clusters:Demand concentrates in South Korea's battery component ecosystem around Seoul and Gwangju, creating scale efficiencies for calcium-tin alloy production.
Market Restraints
- Lead price volatility:Raw material input costs for lead-acid plate manufacturing fluctuate with LME trading patterns, compressing margin pools for continuous casting operations.
- Technical limitation in energy density:Lead-alloy plate architectures face physical ceiling constraints that lithium-ion coated copper designs circumvent in premium EV platforms.
- EU Green Deal carbon intensity restrictions:CE-marked sustainable plate sourcing requirements add compliance friction to legacy smelter-dependent supply chains.
Strategic Opportunities
- Silver-bearing alloy adoption:Advanced corrosion-resistant formulations are expanding into heavy-duty commercial segments where deep-cycle duty extends replacement intervals.
- India's PLI scheme for advanced chemistry cells:Domestic manufacturing incentives create white space for localized plate production serving two-wheeler and three-wheeler electrification.
- Japan's METI battery supply chain resilience initiatives:Policy tailwinds favor diversified sourcing architectures beyond concentrated East Asian production nodes.
Industry Challenges
- GB standards certification timeline:China's SAMR enforcement of battery component safety protocols extends product qualification cycles for new alloy formulations.
- Strip expansion equipment capex intensity:Precision grid manufacturing requires specialized continuous casting lines that strain mid-tier producer balance sheets.
- Integration complexity with legacy 12V architectures:Dual-system vehicles demand plate designs compatible with existing starter motor specifications while supporting higher cycling frequency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Battery Plate Market |
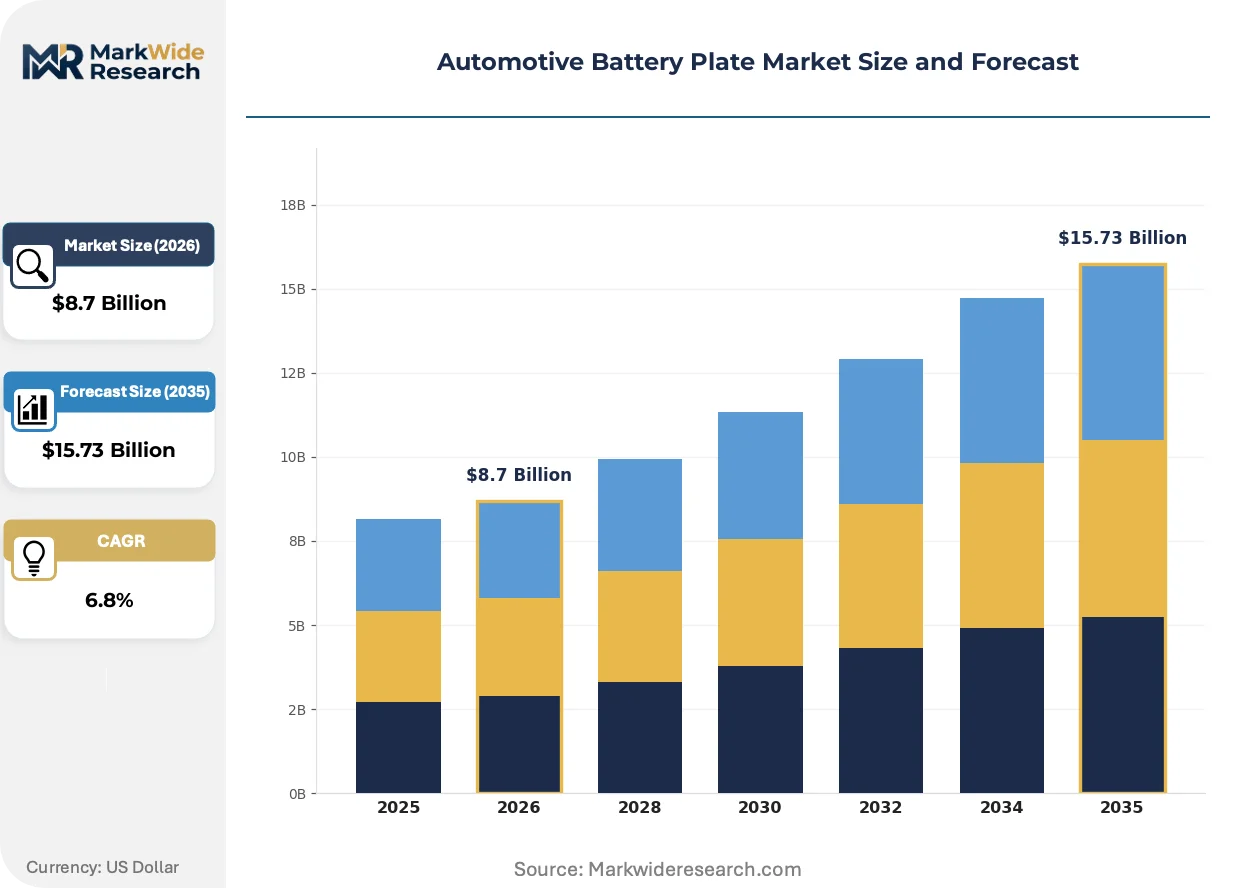
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead-Acid, Lithium-Ion, Nickel-Metal Hydride, Gel Cell End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Fleet Operators Technology: Start-Stop Systems, Regenerative Braking, Power Management, Wireless Monitoring Installation: Front Mount, Rear Mount, Side Mount, Integrated |
| Companies Covered | Enersys, Furukawa Battery, Exide Technologies, Amara Raja Batteries, Clarios, Johnson Controls, GS Yuasa Corporation, C&D Technologies, East Penn Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Battery Plate Market Strategic Shifts
Active material adhesion technologies and electron transfer optimization are reshaping competitive positioning across plate architectures. Manufacturing process convergence with battery pack integration is compressing traditional supplier tiers.
Coated copper current collectors are expanding into premium EV traction battery applications where weight reduction and thermal management override cost considerations. European automakers in Stuttgart and Munich are qualifying these architectures for 800V platforms. The technology is expanding into territory previously dominated by pure aluminum designs in high-performance segments.
The EU's F-Gas Regulation and associated ECHA restrictions on fluorinated greenhouse gases are forcing reformulation of plate coating chemistries used in sealed battery assemblies. Industrial consequence includes accelerated R&D spending on water-based binder alternatives. Heavy-duty commercial vehicle battery suppliers face the steepest compliance timeline given extended product certification cycles.
Fleet operators and energy storage integrators are consolidating procurement around outcome-based performance contracts rather than unit-based plate purchasing. Tier-1 battery assemblers are capturing this value chain position from independent plate distributors. This pattern is most visible in German industrial vehicle manufacturing where total-cost-of-ownership modeling dominates supplier selection.
Automotive Battery Plate Market Segmentation
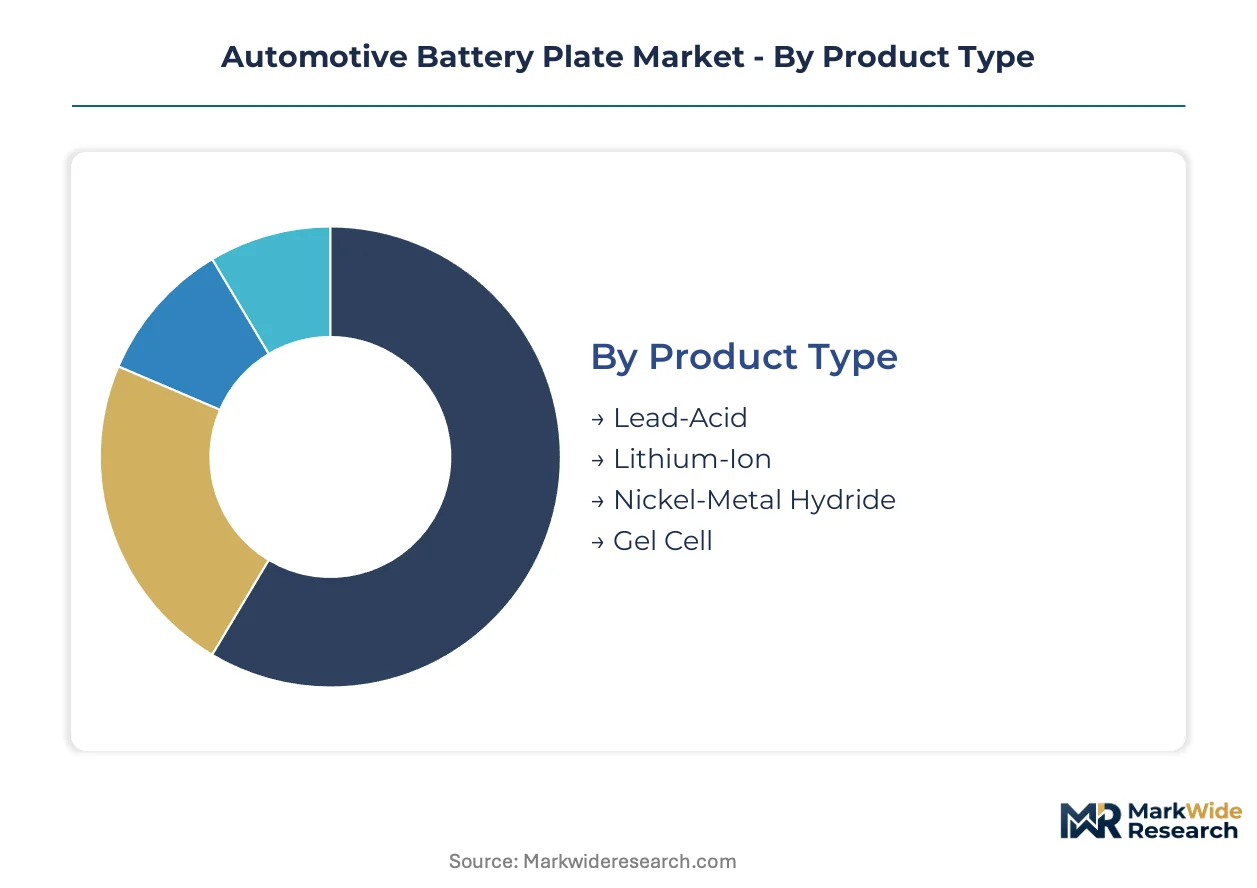
Automotive battery plate architectures diverge sharply across powertrain electrification levels and duty-cycle requirements. Procurement patterns differ materially between ICE legacy platforms and emerging EV traction battery designs.
Product Type:
Cost tier separates buyers seeking mature recycling infrastructure from those prioritizing energy density and weight reduction.
- Lead-Acid:Calcium-tin or silver-bearing alloy grids dominate ICE and mild-hybrid vehicle production. Demand concentrates in Detroit and Southern US automotive clusters where EPA emissions rules pressure OEMs toward electrified powertrains yet retain 12V auxiliary systems.
- Lithium-Ion:Coated copper current collectors support premium EV traction batteries requiring thermal management and weight reduction. Stuttgart and Munich automakers are qualifying these architectures for 800V platforms, displacing pure aluminum designs in high-performance segments.
- Nickel-Metal Hydride:Hybrid-electric vehicle legacy applications in Japanese manufacturing.
- Gel Cell:Sealed maintenance-free configurations for marine and recreational vehicle niches.
Lead-Acid leads volumes today; Lithium-Ion is gaining share fastest.
End User:
Application dictates specification rigor, with traction battery suppliers facing stricter qualification cycles than replacement market distributors.
- OEMs:Direct procurement from plate manufacturers for integrated battery pack assembly. China's SAMR enforces GB standards certification timelines that extend product qualification cycles for new alloy formulations entering East Asian manufacturing clusters.
- Aftermarket Providers:Independent distributors serving replacement demand with legacy lead-acid architectures. Margin compression from LME lead price volatility strains continuous casting operations serving this channel.
- Vehicle Assemblers:Contract manufacturers requiring dual-system compatibility for transitional powertrain architectures.
- Fleet Operators:Outcome-based performance contracting consolidates procurement around total-cost-of-ownership modeling rather than unit-based plate purchasing.
OEMs dominate procurement value; Fleet Operators are expanding contract scope most aggressively.
Technology:
Volume requirements scale with cycling frequency, separating mild-hybrid frequent-cycling applications from baseline ICE configurations.
- Start-Stop Systems:Enhanced flooded and absorbed glass mat configurations command expanded plate surface area for frequent cycling duty. South Korea's battery component ecosystem around Seoul and Gwangju generates scale efficiencies for calcium-tin alloy production serving this segment.
- Regenerative Braking:Deep-cycle plate designs capture kinetic energy recovery in hybrid architectures. Silver-bearing alloy formulations are expanding into heavy-duty commercial segments where extended replacement intervals justify material cost premiums.
- Power Management:Intelligent charge-discharge optimization for integrated battery systems.
- Wireless Monitoring:Sensor-enabled plate health tracking for predictive maintenance applications.
Start-Stop Systems anchor installed base expansion; Regenerative Braking shows steepest adoption trajectory in commercial vehicle electrification.
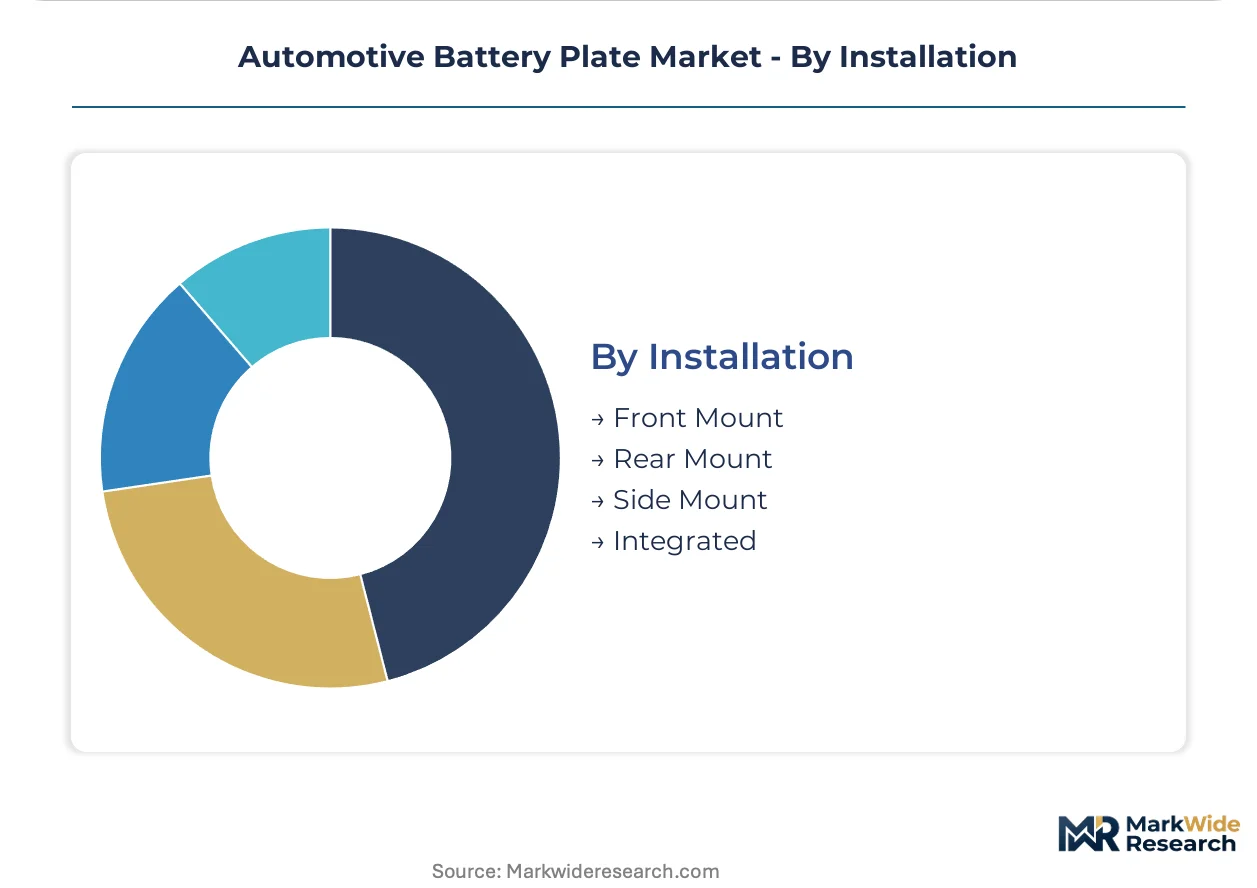
Installation:
Customer type determines packaging constraints, with integrated designs capturing EV platform engineering while discrete mounting retains ICE legacy flexibility.
- Front Mount:Traditional engine compartment placement for starter motor compatibility. India's PLI scheme for advanced chemistry cells creates white space for localized plate production serving two-wheeler and three-wheeler electrification with front-accessible configurations.
- Rear Mount:Trunk or under-floor positioning for weight distribution optimization in hybrid architectures.
- Side Mount:Commercial vehicle chassis integration for heavy-duty cycling applications.
- Integrated:Structural battery pack incorporation eliminating discrete plate housings. Japan's METI battery supply chain resilience initiatives favor diversified sourcing architectures beyond concentrated East Asian production nodes for these advanced designs.
Front Mount retains largest unit volumes; Integrated designs are climbing fastest as EV platform engineering matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting plate production toward jurisdictions with lower carbon-intensity compliance costs. Manufacturers are relocating casting operations to exploit gaps between EU Green Deal restrictions and emerging-market enforcement timelines.
United States
EPA emissions rules and NHTSA fuel economy standards pressure Detroit and Southern automotive clusters toward electrified powertrains. The IRA domestic content provisions incentivize localized plate production for qualifying battery assemblies. Michigan and Tennessee manufacturing corridors concentrate calcium-tin alloy casting capacity serving hybrid traction battery demand.
Germany
Stuttgart and Munich automakers are qualifying coated copper current collectors for 800V platforms. The EU's F-Gas Regulation and ECHA restrictions force reformulation of plate coating chemistries in sealed battery assemblies. Bavarian industrial zones anchor R&D spending on water-based binder alternatives.
China
NMPA battery safety standards and SAMR enforcement of GB standards extend product qualification cycles for new alloy formulations. Dual carbon goals under MEE oversight tighten smelter emissions requirements. Yangtze River Delta manufacturing clusters around Shanghai concentrate strip expansion capacity for start-stop optimized plates.
South Korea
Seoul and Gwangju battery component ecosystems generate scale efficiencies for calcium-tin alloy production. MFDS-aligned safety protocols and METI-influenced supply chain resilience initiatives favor diversified sourcing architectures. Busan-Ulsan industrial corridors host precision grid manufacturing for absorbed glass mat configurations.
India
The PLI scheme for advanced chemistry cells creates white space for localized plate production serving two-wheeler and three-wheeler electrification. BIS certification requirements and DGFT import substitution policies protect domestic manufacturers. Gujarat and Maharashtra industrial zones concentrate front-mount plate assembly for cost-sensitive vehicle platforms.
Automotive Battery Plate Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with OEM-direct procurement favoring integrated suppliers and aftermarket channels sustaining independent distributors. The vendor base clusters around three strategic archetypes: vertically integrated battery assemblers controlling captive plate production, dedicated grid specialists supplying multiple pack manufacturers, and regional foundries serving replacement demand. Dominant competitive moves include backward integration into alloy smelting and geographic expansion through licensing arrangements.
Among North American-based suppliers, Clarios and East Penn Manufacturing occupy positions within the branded specialist tier. GS Yuasa Corporation anchors Asian supply chain representation. These three exemplify divergent strategic postures: Clarios leverages continental production networks, East Penn Manufacturing concentrates on heavy-duty commercial configurations, and GS Yuasa Corporation maintains Kyoto-based R&D coordination with Osaka manufacturing scale.
| Leading Market Players |
|---|
| Enersys |
| Furukawa Battery |
| Exide Technologies |
| Amara Raja Batteries |
| Clarios |
| Johnson Controls |
| GS Yuasa Corporation |
| C&D Technologies |
| East Penn Manufacturing |
| Others |
Value Chain & Pricing Dynamics
Strip expansion equipment upgrades across East Asian manufacturing clusters simultaneously compress unit economics and concentrate supply authority among capital-intensive producers. Calcium-tin alloy casting lines in South Korea and Japan now require specialized continuous casting infrastructure that mid-tier foundries cannot finance, creating bifurcated pricing power between integrated battery assemblers and independent grid suppliers.
Pricing Analysis
Distributor margins for aftermarket lead-acid plates range from 15-25% above OEM-direct contract rates, with pricing stratifying across premium, standard, and economy tiers based on alloy composition and cycle-life certification. OEM procurement teams leverage volume commitments to extract 8-12% discounts against spot replacement market rates. Pricing pressure stems from LME lead price volatility that strains continuous casting operations serving price-sensitive aftermarket channels. Fleet operators demonstrate lowest price sensitivity, accepting 20-30% premiums for silver-bearing alloy formulations that extend replacement intervals.
Supply Chain Analysis
Ocean freight costs from South Korean component hubs to Stuttgart and Munich automakers add 4-7% to landed plate costs, incentivizing regional casting capacity investments. Primary supply concentrates in China, South Korea, and Japan for precision grid manufacturing, with secondary lead smelting anchored in US and European recycling corridors. Raw material dependencies span LME-traded lead ingots, calcium-tin master alloys, and copper cathodes for coated current collectors. Single-source vulnerability concentrates in Yangtze River Delta strip expansion equipment suppliers. Distribution runs through Tier 1 battery assemblers capturing direct OEM contracts, with independent distributors serving fragmented aftermarket demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive battery plate demand is maturing into a late-cycle quality story as OEM procurement shifts toward 800V platform specifications and extended cycle-life warranties that favor premium alloy formulations.
For Market Incumbents: Anchor defensive positioning through backward integration into alloy smelting operations that secure captive calcium-tin supply against LME price volatility. Clarios and GS Yuasa Corporation exemplify this posture with continental production networks and Kyoto-based R&D coordination. Invest in GB standards pre-certification for next-generation silver-bearing formulations before China's SAMR extends enforcement timelines. Channel control through exclusive OEM supply agreements limits entrant access to start-stop system procurement. For New Entrants and Emerging Players: Capture white space in India's PLI scheme for advanced chemistry cells, where localized plate production for two-wheeler electrification faces limited incumbent penetration. Gujarat and Maharashtra industrial zones offer front-mount assembly capacity at 30-40% cost advantages against imported Korean components. Target fleet operator outcome-based contracting with performance-guaranteed deep-cycle designs that bypass established distributor relationships. For Investors and Strategic Acquirers: Roll-up economics work for regional foundry consolidation because strip expansion equipment capex intensity prevents organic entry and creates acquisition currency for scale players. Mid-tier Japanese and European casting operations face succession-driven exit pressure. Long-term viability hinges on coated copper current collector qualification for 800V platforms. Watch for NMPA battery safety standard revisions as inflection signal for alloy substitution R&D returns.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Smelting | Captive calcium-tin supply insulates margin pools from LME lead price volatility cycles. |
| GB Standards Pre-Certification Investment | Early SAMR compliance locks in OEM qualification timelines before enforcement tightens. |
| Coated Copper Current Collector Scale-Up | 800V platform qualification at Stuttgart and Munich automakers displaces aluminum designs. |
| India PLI Scheme Manufacturing Localization | Gujarat assembly capacity captures two-wheeler electrification demand with import substitution protection. |
| Fleet Performance Contracting Capability | Outcome-based procurement consolidation favors suppliers with total-cost-of-ownership modeling expertise. |
Study Parameters
Bottom-up vehicle production modeling reconciled against top-down battery pack shipment tracking forms the analytical core of this study. Primary interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations managers were validated against secondary sources including vehicle production databases, IHS Markit registration data, SEC 10-K filings from listed battery manufacturers, and customs records for lead alloy trade flows. Triangulation across these sources ensures segmentation integrity across propulsion architecture and regional production cluster dimensions.
Historical trendline analysis of plate content per vehicle across ICE, mild-hybrid, and full-electric architectures established baseline penetration rates. The projection framework models volume and value outputs across product type, end user, technology, and installation segmentation dimensions throughout the forecast period. CAGRs were derived from regression analysis of alloy substitution curves and OEM platform electrification roadmaps, with specific inputs from EPA emissions rule compliance timelines and EU Green Deal carbon intensity restriction phase-ins.
Lead price volatility, NMPA regulatory revision timing, and lithium-ion plate architecture substitution rates are the dominant revision risks to modeled outputs. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Infrastructure
France Electric Vehicle Battery Materials Market
Battery Infrastructure
Global Battery Packaging Market
Battery Infrastructure
Advance Battery Technologies Market
Battery Infrastructure
Global Automotive 48 Volt Battery System Market
Battery Infrastructure
Middle East and Africa Electric Vehicle Battery Separator Market
Battery Infrastructure
Electric Vehicle Battery Swapping Market
Battery Infrastructure
New Energy Battery Structural Parts Market
Battery Infrastructure
Lithium-Ion Battery Filling Machine Market
Battery Infrastructure
Europe Lithium Foil Market
Battery Infrastructure
Global Battery Technology Market
Battery Infrastructure
China Electric Vehicle Battery Electrolyte Market
Battery Infrastructure
India Electric Vehicle Battery Separator Market
Battery Infrastructure
United States Electric Vehicle Battery Separator Market
Battery Infrastructure
Battery Swap-Ready Pack Systems for Urban Fleets Market
Battery Infrastructure
Battery Maintenance Service Market
Battery Infrastructure
Canada Electric Vehicle Battery Separator Market