
 France Electric Vehicle Battery Separator Market | 2026-2036
France Electric Vehicle Battery Separator Market Size, Share, and Industry Trends Forecast 2026-2036
France Electric Vehicle Battery Separator Market Insights
EU Battery Regulation is repositioning the cost-of-entry calculus for separator suppliers serving French cell manufacturers. Asahi Kasei Corporation leverages its polypropylene expertise to anchor supply relationships with European gigafactories. SK Innovation Co. Ltd. competes through integrated separator-to-cell capabilities that sustain margin control across the value chain. Toray Industries Inc. differentiates via wet-process technology leadership that dominates premium ceramic-coated separator tiers.
France Electric Vehicle Battery Separators are microporous membranes, typically 5–30 micrometers thick, engineered from polyolefin substrates or ceramic composites to electrically isolate anode and cathode while permitting lithium-ion transport between electrodes. Their primary purpose is preventing internal short circuits under thermal stress and mechanical abuse during charge-discharge cycling in high-energy-density cells. Polyethylene and ceramic composites currently lead installed capacity, while coating technology segments capture expanding margin pools as OEMs demand shutdown-function separators for solid-state transition readiness. Wet process manufacturing occupies the volume center for passenger vehicle applications, though dry process lines are gaining share in commercial vehicle contracts where thickness tolerance requirements relax.
France's national implementation of EU Battery Regulation, supervised by national market surveillance authorities coordinating with ECHA REACH compliance frameworks, mandates recycled content thresholds and supply chain due diligence that reshape procurement specifications for separator materials. DGCCRF enforcement of product safety standards and impending CSRD disclosure requirements further tighten documentation burdens for imported separator films. Stakeholders must monitor how France's national battery industrialization strategy allocates gigafactory offtake commitments between domestic separator capacity investments and Asian supplier long-term agreements.
Market Dynamics
France's battery separator market is being restructured by the EU Battery Regulation's recycled content mandates, which are forcing separator suppliers to reengineer polyolefin substrates for traceable circular feedstocks before gigafactory offtake contracts renew.
Growth Catalysts
- Hauts-de-France Battery Valley:The Dunkirk-Verkor-ACC manufacturing cluster is concentrating demand for ceramic-coated separators within a 150-kilometer procurement radius.
- EU Green Deal Industrial Plan:Production tax credits for clean technology manufacturing are lowering effective capex hurdles for domestic separator film extrusion lines.
- Solid-state readiness mandates:OEM technical specifications now require shutdown-function separators compatible with sulfide electrolyte interfaces.
Market Restraints
- Polypropylene resin concentration:Basell and Borealis control over 70% of European battery-grade polyolefin supply, creating feedstock bottlenecks during automotive production ramps.
- Wet-process equipment lead times:Japanese and Korean machinery suppliers quote 18-to-24-month delivery schedules for simultaneous biaxial stretching lines.
- CSRD disclosure burden:The Corporate Sustainability Reporting Directive requires granular Scope 3 carbon accounting that many Asian separator exporters cannot yet document.
Strategic Opportunities
- Occitanie recycling corridor:Toulouse-based pyrolysis ventures are developing battery-grade separator regeneration capabilities for post-industrial film waste.
- Stationary storage crossover:Grid-scale lithium iron phosphate systems tolerate thicker dry-process separators, opening margin-accretive volume for second-tier suppliers.
- Digital Product Passport integration:Early compliance with EU battery passport data standards is creating preferential supplier status for French OEM sourcing committees.
Industry Challenges
- Thin-film quality engineering talent:France produces fewer than 50 annual graduates with combined polymer science and battery electrochemistry expertise.
- Coating line qualification timelines:Ceramic slurry validation for specific cell chemistries requires 12-to-18-month parallel testing with gigafactory pilot lines.
- REACH SVHC substitution:Separator binders containing perfluorinated compounds face impending authorization restrictions that demand reformulation investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Electric Vehicle Battery Separator Market |
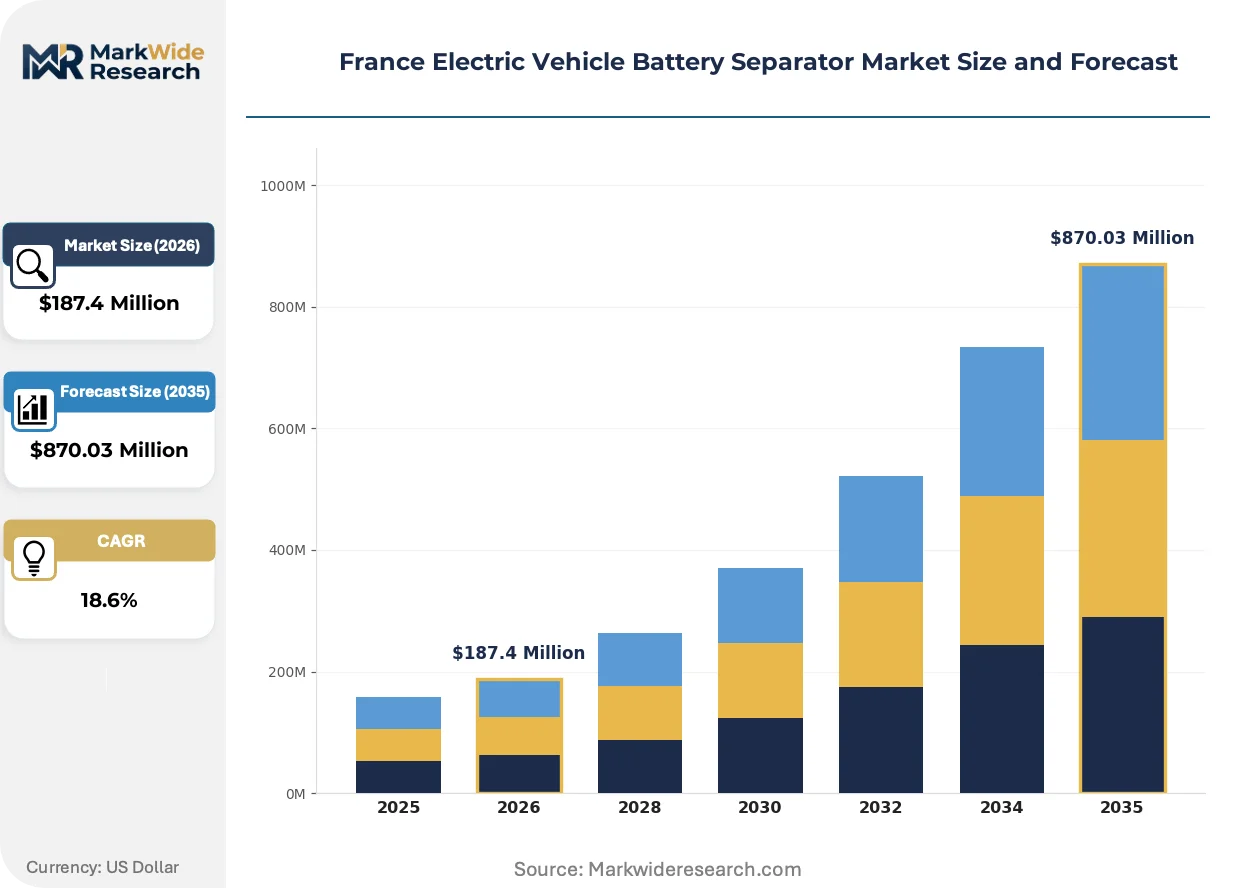
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polyethylene, Ceramic, Composites End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Fleet Operators Technology: Dry Process, Wet Process, Coating Technology, Nanotechnology Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Energy Storage Systems |
| Companies Covered | Asahi Kasei Corporation, SK Innovation Co. Ltd., Mitsubishi Chemical Group Corporation, Toray Industries Inc., Sumitomo Chemical Co. Ltd., W-SCOPE Corporation, SEMCORP Co., UBE Corporation, ENTEK International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Electric Vehicle Battery Separator Market Trends and Innovations
Separator technology is converging around thermal stability and ionic conductivity specifications that bridge liquid electrolyte and solid-state architectures. French cell manufacturers are accelerating qualification cycles to lock in supply before capacity ramps.
Ceramic-polymer composite coatings are unifying mechanical strength and shutdown functionality in single-layer architectures. Renault and Stellantis procurement teams are prioritizing these hybrid separators for their 800-volt platform launches. The technology is compressing qualification timelines by eliminating separate base film and coating supplier coordination.
France's DGCCRF enforcement of EU Battery Regulation delegated acts is mandating supply chain due diligence documentation for separator imports. Cell manufacturers must now verify that polyolefin resins originate from conflict-free and environmentally audited sources. Premium separator tiers are capturing margin premiums through pre-certified compliance packages.
Buyer committees at French OEMs are consolidating supplier panels from six-to-eight vendors down to three-to-four strategic partners. Long-term offtake agreements with volume commitments and price corridors are displacing quarterly spot purchasing. This concentration is most visible in the Hauts-de-France cluster, where Verkor and ACC have both issued five-year separator supply tenders.
France Electric Vehicle Battery Separator Market Segmentation
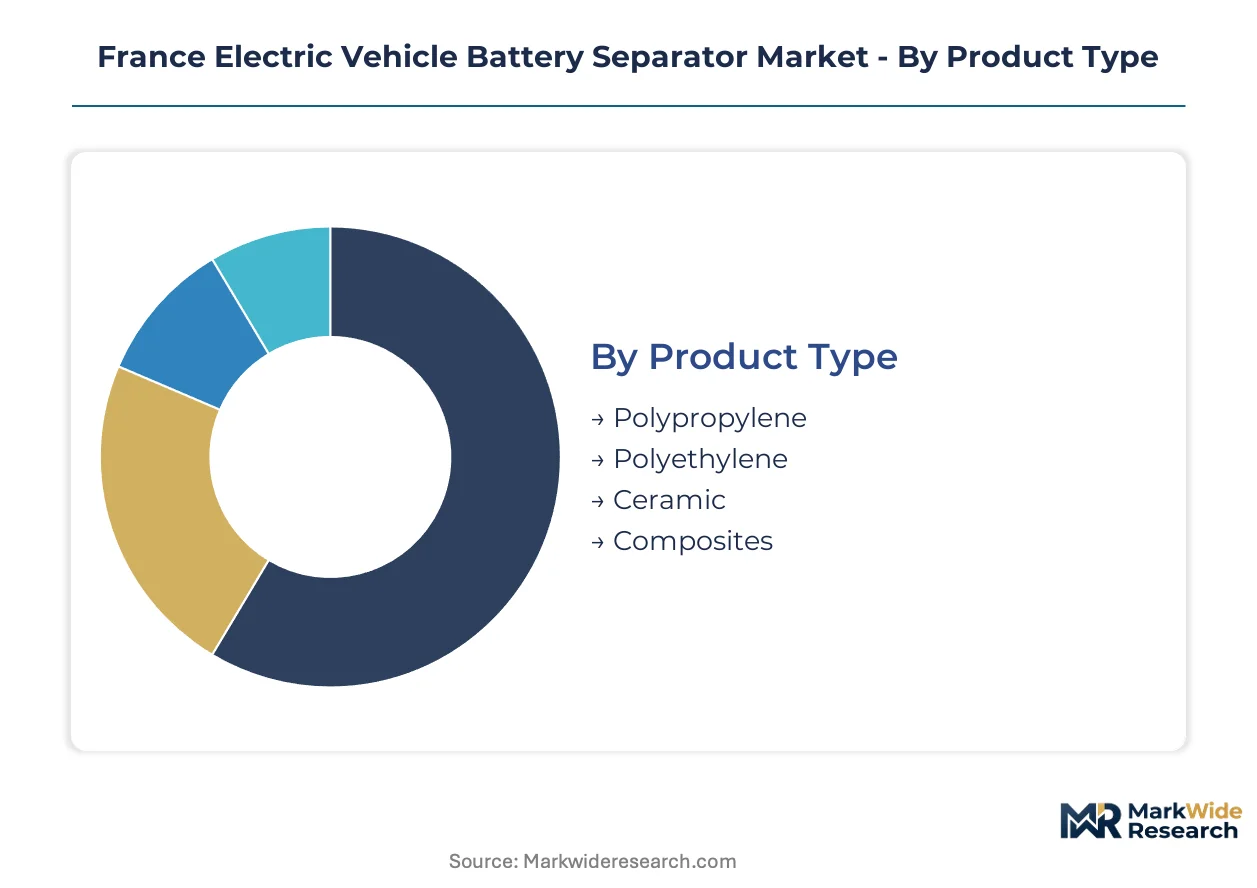
Separator segmentation in France tracks how material chemistry, manufacturing process, and end-use voltage requirements map onto distinct certification and procurement pathways. Each dimension carries specific DGCCRF documentation burdens and REACH SVHC exposure risks that reshape supplier economics.
Product Type:
Polypropylene and polyethylene substrates face divergent ECHA REACH authorization timelines, while ceramic and composite tiers trigger enhanced carbon footprint disclosure under CSRD delegated acts.
- Polypropylene:Microporous membranes manufactured through melt-extrusion and biaxial stretching achieve 25-40% porosity with shutdown temperatures near 165°C. Hauts-de-France gigafactories specify this substrate for 400-volt passenger cell platforms due to established supply from Basell and Borealis resin streams.
- Polyethylene:Lower melting point (135°C) enables earlier thermal shutdown functionality, making this chemistry preferred for high-nickel cathode chemistries where thermal runaway thresholds compress. Wet-process lines at Asian suppliers dominate qualification pipelines for this segment.
- Ceramic:Alumina or silica coatings on polyolefin bases deliver dimensional stability above 200°C. Demand concentrates around Verkor's Dunkirk facility for 800-volt architectures.
- Composites:Hybrid polymer-ceramic architectures integrate shutdown layers with mechanical reinforcement. Renault procurement teams prioritize these for solid-state transition readiness.
Polypropylene sits at the top of the volume ranking, with ceramic climbing the fastest.
End User:
Procurement authority and qualification timelines fragment sharply across this dimension, with OEM direct contracts demanding 18-month validation cycles versus fleet operator spot purchasing.
- OEMs:Stellantis and Renault maintain captive separator qualification laboratories in Guyancourt and Lardy, respectively. Their technical specifications mandate batch-level traceability from resin pellet to finished cell.
- Tier-1 Suppliers:ACC and Verkor procure separators under long-term offtake agreements with volume corridors and price adjustment clauses indexed to polypropylene feedstock indices.
- Aftermarket Providers:Replacement separator demand remains negligible in France due to cell-level sealing that prevents field serviceability.
- Fleet Operators:Postal and municipal vehicle fleets in Île-de-France negotiate separator supply indirectly through battery pack refurbishment contractors.
OEMs command the procurement volume hierarchy, with Tier-1 Suppliers expanding their direct contracting authority fastest.
Technology:
Capital intensity and yield rates separate these process categories, with wet-process equipment requiring 40% higher capex per line but delivering tighter thickness tolerance.
- Wet Process:Solvent-based extraction of plasticizers creates highly uniform pore structures (0.03-0.1 micrometer range). Toray Industries and SK Innovation dominate equipment supply and process licensing for French installations.
- Dry Process:Mechanical stretching of beta-crystal polypropylene avoids solvent recovery infrastructure. Thickness variation tolerance of ±15% suits commercial vehicle applications where energy density requirements relax.
- Coating Technology:Ceramic slurry deposition adds 2-4 micrometers to base films. Qualification timelines extend 12-18 months due to chemistry-specific adhesion validation requirements.
- Nanotechnology:Electrospun nanofiber layers for solid-state electrolyte interfaces remain pre-commercial in France, with CEA Grenoble piloting domestic capability.
Wet Process maintains installed capacity leadership, with Coating Technology gaining share fastest through integrated base-and-coat supplier consolidation.
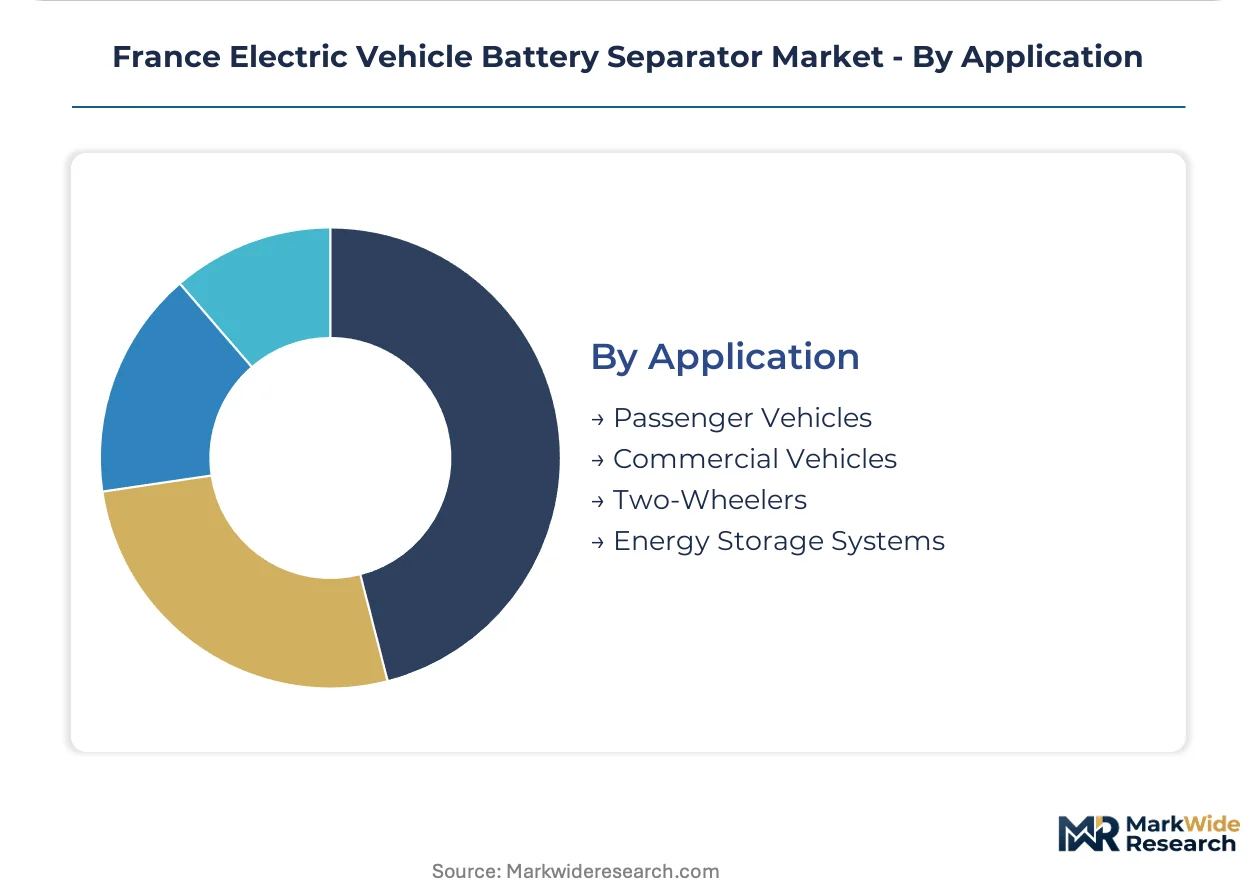
Application:
Voltage architecture and duty cycle severity drive separator specification divergence, with passenger vehicle platforms demanding thinnest films and energy storage systems tolerating thicker, lower-cost alternatives.
- Passenger Vehicles:800-volt platforms from Stellantis and Renault specify 7-12 micrometer ceramic-coated wet-process separators with shutdown functionality. ACC's Douai supply contract anchors volume concentration in this segment.
- Commercial Vehicles:Bus and truck applications accept 16-25 micrometer dry-process films where cycle life rather than gravimetric energy density governs design. Irizar and Heuliez procurement specifications reflect this tolerance.
- Two-Wheelers:Micromobility separator demand in France remains import-dependent, with Asian cell suppliers integrating separators at origin before pack assembly.
- Energy Storage Systems:Grid-scale lithium iron phosphate installations prioritize cost over thickness minimization. RTE and Engie utility procurement favors dry-process separators with 20+ year degradation warranties.
Passenger Vehicles holds the volume position, with Energy Storage Systems expanding most quickly as Occitanie solar-storage hybrid projects accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's polymer science and battery electrochemistry talent concentrates in the Paris-Saclay university cluster and Grenoble's CEA research centers, anchoring separator qualification capabilities for domestic gigafactories.
Germany
BASF and Covestro resin streams supply polyolefin feedstocks to French separator manufacturers under long-term offtake contracts. The KBA enforces battery safety standards that French OEMs must mirror for cross-border platform homologation. North Rhine-Westphalia's chemical corridor ships battery-grade polymers through Rotterdam-Antwerp port networks into Hauts-de-France.
Belgium
Antwerp's petrochemical hub hosts Borealis polypropylene production lines that supply 40% of French battery separator resin demand. REACH enforcement through ECHA's Helsinki headquarters creates regulatory alignment with French DGCCRF documentation requirements. The Port of Antwerp-Bruges handles bulk resin shipments to Dunkirk separator extrusion facilities.
Netherlands
LyondellBasell's Rotterdam refinery outputs battery-grade polyolefins qualified for Renault's separator specifications. The Dutch Emissions Authority implements EU Battery Regulation delegated acts ahead of French national adoption, creating compliance precedent. Eindhoven's Brainport region develops coating equipment automation exported to French separator lines.
Spain
Stellantis' Zaragoza manufacturing complex sources separators through French ACC supply contracts rather than direct Spanish procurement. The Spanish Ministry for Ecological Transition administers battery industrialization grants that compete with France's national strategy for European cell capacity. Basque Country polymer research centers collaborate with CEA Grenoble on ceramic coating adhesion science.
Italy
Enel X's grid-scale storage deployments in Sicily and Sardinia create secondary demand for French-exported dry-process separators with 20-year degradation warranties. The Italian National Institute for Insurance against Accidents at Work enforces industrial safety standards affecting separator manufacturing equipment imports. Lombardy-based automotive suppliers qualify French ceramic-coated separators for Stellantis platform integration.
France Electric Vehicle Battery Separator Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across separator supply tiers, creating a bifurcated structure where chemical conglomerates leverage resin backward integration while membrane specialists dominate coating technology licensing. The vendor base organizes around three strategic archetypes: Asian integrated petrochemical-to-membrane conglomerates, European specialty chemical coating technology providers, and Korean-Japanese equipment-process licensors. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with qualification timeline compression emerging as a secondary battleground.
Within the Asian conglomerate tier, Asahi Kasei Corporation and SK Innovation Co. Ltd. exemplify integrated separator-to-cell capabilities that sustain margin control across value chain positions. Toray Industries Inc. occupies a position within wet-process technology licensing, anchoring equipment and process IP supply to European gigafactory installations. These three companies represent distinct archetypal strategies: resin-backed membrane production, captive cell integration, and process technology specialization.
| Leading Market Players |
|---|
| Asahi Kasei Corporation |
| SK Innovation Co. Ltd. |
| Mitsubishi Chemical Group Corporation |
| Toray Industries Inc. |
| Sumitomo Chemical Co. Ltd. |
| W-SCOPE Corporation |
| SEMCORP Co. |
| UBE Corporation |
| ENTEK International |
| Others |
Pricing and Supply Chain Analysis
Polypropylene resin indices from Rotterdam-Antwerp barge markets cascade through French separator supply tiers, compressing margins for uncoated base film suppliers while ceramic-coated grades capture carbon-accounting premiums from CSRD-compliant OEM procurement committees.
Pricing Analysis
Base film and ceramic coating services remain unbundled for Tier-2 suppliers, though integrated base-and-coat offerings from Asian conglomerates command 15-25% premia through single-source liability structures. Three-tier pricing structure across premium, standard, and economy levels separates EU Battery Regulation pre-certified separators from REACH SVHC-exposed imports and dry-process commercial vehicle grades. Cost compression in standard-tier wet-process films is intensifying because Basell and Borealis resin supply bottlenecks during automotive production ramps. Fleet operators and energy storage integrators exhibit highest price sensitivity, while Stellantis and Renault captive qualification laboratories tolerate extended payback periods for shutdown-function ceramic architectures.
Supply Chain Analysis
DGCCRF qualification documentation gates entry for Asian separator exporters unable to demonstrate conflict-free polyolefin resin provenance under EU Battery Regulation delegated acts. Manufacturing concentrates in South Korea, Japan, and China, with European extrusion capacity scaling through Hauts-de-France greenfield investments. Feedstock supply draws from Belgian Borealis lines, Dutch LyondellBasell Rotterdam output, and German BASF resin streams. Single-source vulnerability runs through Japanese and Korean simultaneous biaxial stretching equipment suppliers quoting extended delivery schedules. Distribution runs through Antwerp-Dunkirk port corridors into gigafactory extrusion facilities, with coating line qualification extending validation timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France battery separator market functions as a geographic-arbitrage play where domestic coating qualification capabilities capture margin premia unavailable to Asian exporters facing CSRD Scope 3 disclosure gaps.
For Market Incumbents: To counter qualification timeline compression by integrated Asian conglomerates, accelerate ceramic slurry adhesion science partnerships with CEA Grenoble and secure five-year offtake corridors with volume commitments indexed to polypropylene feedstock indices. Backward integration into solvent recovery infrastructure at Dunkirk-Verkor cluster sites defends margin position against equipment import delays. For New Entrants and Emerging Players: Enter via dry-process separator regeneration capabilities at Toulouse pyrolysis ventures, targeting grid-scale lithium iron phosphate energy storage systems where thickness tolerance requirements relax and 20-year degradation warranties command margin-accretive pricing. Stationary storage procurement specifications from RTE and Engie represent the most penetrable segment for second-tier suppliers lacking automotive qualification laboratory access. For Investors and Strategic Acquirers: Asymmetric upside sits with European specialty chemical coating technology providers possessing EU Battery Regulation pre-certification packages and CEA-licensed nanofiber pilot capabilities. Long-term viability over the next decade hinges on solid-state transition readiness and sulfide electrolyte interface compatibility. Watch for inflection when Renault and Stellantis issue unified 800-volt platform separator specifications consolidating supplier panels.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Dunkirk-Verkor-ACC cluster proximity reduces logistics costs for Hauts-de-France gigafactory offtake. |
| Backward Integration | In-house polyolefin extrusion lines mitigate Basell-Borealis resin concentration risks during production ramps. |
| Long-term Supply Agreement | Five-year tenders with price corridors indexed to Rotterdam-Antwerp resin indices stabilize margin forecasting. |
| Joint Venture | CEA Grenoble partnerships accelerate ceramic coating qualification timelines for solid-state transition readiness. |
| Green Certification Program | EU Battery Regulation pre-certification packages create preferential supplier status with French OEM committees. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with separator procurement leads at ACC and Verkor, platform engineers at Stellantis and Renault, coating equipment automation specialists at Eindhoven Brainport, and DGCCRF market surveillance officers with secondary validation against ECHA REACH authorization timelines, EU Battery Regulation delegated acts, customs records through Antwerp-Dunkirk corridors, and SEC filings from listed Asian conglomerates. Bottom-up gigafactory offtake commitments were triangulated against top-down polymer resin demand projections.
Historical reference periods anchored the projection horizon through verified production capacity installations and qualification pipeline statuses, with growth trajectories modeled across product type, manufacturing process, end-user procurement authority, and application voltage architecture dimensions. CAGRs were derived from segmented volume buildup analysis incorporating coating line yield rates, wet-process equipment delivery schedules, and ceramic slurry qualification timeline compression factors.
Inputs from ECHA regulatory filings and CEA pilot line disclosures were available through the study window; gaps in proprietary ceramic adhesion science performance data introduce uncertainty bands around solid-state transition timing assumptions. Forecasts reflect documented assumptions regarding EU Green Deal Industrial Plan production tax credit continuity and REACH SVHC substitution timelines. A model refresh is warranted upon material change in DGCCRF enforcement intensity or Basell-Borealis resin supply allocation priorities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Infrastructure
Battery Lug Market
Battery Infrastructure
India Electric Vehicle Battery Separator Market
Battery Infrastructure
Italy Electric Vehicle Battery Separator Market
Battery Infrastructure
Global Battery Packaging Market
Battery Infrastructure
Battery Maintenance Service Market
Battery Infrastructure
Battery Production Machine Market
Battery Infrastructure
Smart Battery Swap Station Market
Battery Infrastructure
France Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
Battery Swap-Ready Pack Systems for Urban Fleets Market
Battery Infrastructure
United Kingdom Electric Vehicle Battery Separator Market
Battery Infrastructure
United States Battery Manufacturing Equipment Market
Battery Infrastructure
Automatic Battery Manufacturing Equipment Market
Battery Infrastructure
South America Electric Vehicle Battery Separator Market
Battery Infrastructure
ASEAN Countries Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
Carbon Battery Bank Market
Battery Infrastructure
North America Electric Vehicle Battery Electrolyte Market