
 ASEAN Electric Vehicle VRLA Batteries Market | 2026-2036
ASEAN Electric Vehicle VRLA Batteries Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Electric Vehicle VRLA Batteries Market Insights
Deep-cycle performance tier upgrades is reorganizing procurement standards across ASEAN electric vehicle programs. GS Yuasa Corporation leverages its Thai manufacturing base to supply regional OEMs with high-temperature tolerant VRLA designs. Clarios competes through aftermarket channel control, while Exide Industries anchors its position with cost-optimized flooded battery production for two-wheeler electrification schemes.
Valve-regulated lead-acid batteries for ASEAN electric vehicles employ absorbed glass mat or gel electrolyte immobilization to prevent acid stratification during partial-state-of-charge cycling typical of urban bus routes. These systems deliver 200–500 cycles at 80% depth of discharge, serving as auxiliary power units, low-voltage backup systems, and primary traction batteries for entry-level electric two-wheelers. Absorbent glass mat configurations capture the dominant margin pool due to superior vibration resistance demanded by ASEAN road conditions. Fleet operators represent the fastest-growing end-user category as government-contracted bus services consolidate procurement volumes across Jakarta, Bangkok, and Ho Chi Minh City.
Thailand's Board of Investment EV incentives, Indonesia's Ministry of Industry localization mandates, and Vietnam's Ministry of Transport emission zone regulations collectively mandate battery traceability and domestic assembly thresholds. These frameworks pressure foreign suppliers to establish local production or forfeit public procurement eligibility. Stakeholders must monitor how nickel-cobalt supply partnerships in Indonesia's Morowali Industrial Park reshape regional cost structures for competing lithium-ion alternatives against VRLA's incumbent position in price-sensitive vehicle categories.
Market Dynamics
Municipal fleet electrification mandates across Thailand, Indonesia, and Vietnam are compressing procurement timelines for VRLA auxiliary systems, forcing battery suppliers to localize assembly or forfeit government contract eligibility.
Growth Catalysts
- Thailand's Board of Investment EV incentives:Tax holidays and import duty exemptions for localized battery assembly are drawing component manufacturers to the Eastern Economic Corridor, creating captive supply clusters for Chinese and Japanese OEMs.
- Deep-cycle performance tier upgrades:Urban bus operators now specify 80% depth-of-discharge cycling tolerance, expanding addressable demand for absorbed glass mat configurations in auxiliary power applications.
- Indonesia's nickel-to-battery downstream policies:Ministry of Industry localization mandates require domestic assembly thresholds, compelling foreign VRLA suppliers to establish co-production arrangements with Morowali Industrial Park partners.
Market Restraints
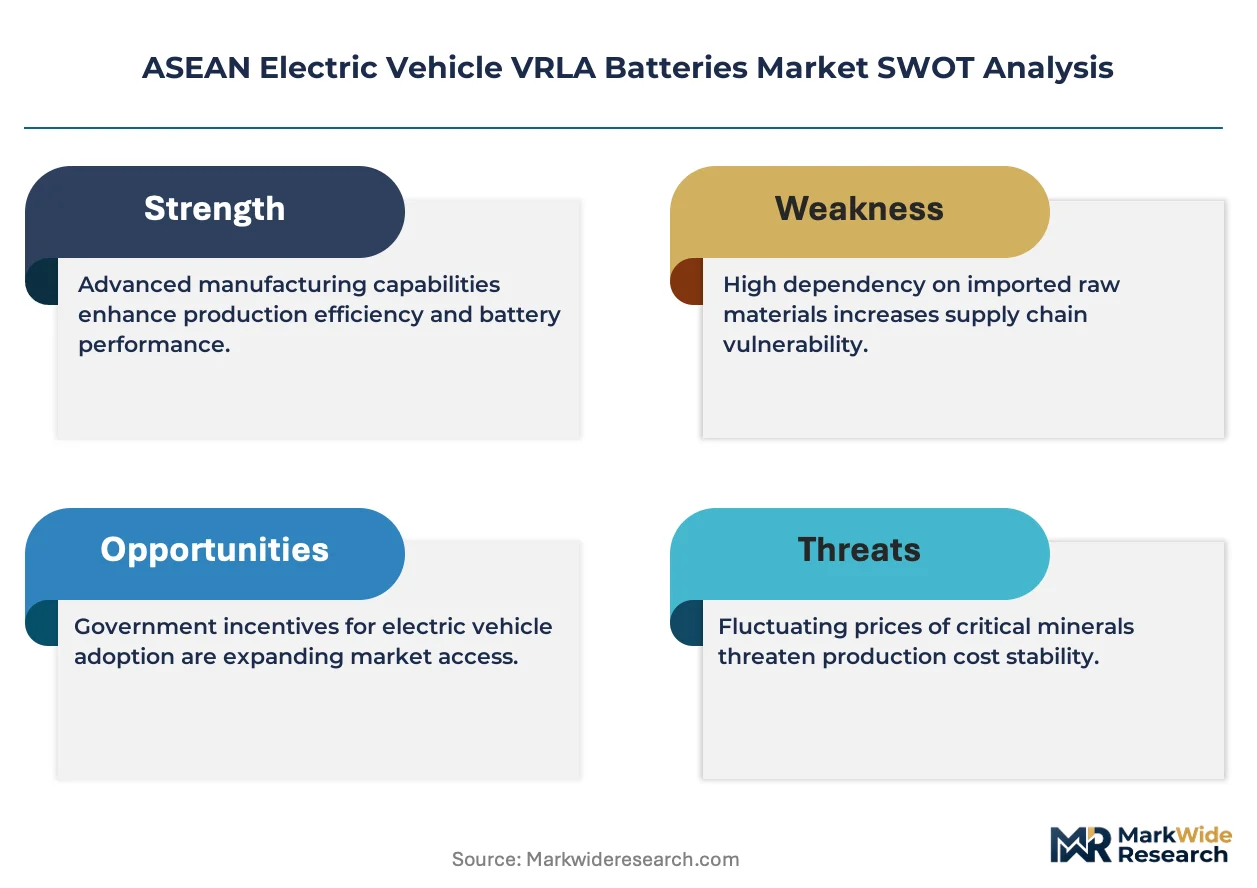
- Lead price volatility:Input cost swings for refined lead ingot compress margin stability for cost-optimized flooded battery producers serving two-wheeler electrification schemes.
- Lithium-ion substitution in premium segments:Nickel-cobalt supply partnerships in Indonesia's industrial parks are reducing cost gaps between advanced lithium-ion packs and VRLA systems in bus traction applications.
- Acid stratification in partial-state-of-charge cycling:Technical limitations of conventional flooded designs restrict cycle life below 200 cycles in stop-start urban routes, disqualifying uncertified products from fleet procurement.
Strategic Opportunities
- Vietnam's emission zone regulations:Ministry of Transport mandates in Ho Chi Minh City are accelerating electric two-wheeler uptake, creating white space for gel electrolyte systems in entry-level scooters.
- Aftermarket channel consolidation:Fleet operators in Jakarta and Bangkok are unbundling service contracts from hardware procurement, opening direct supplier relationships bypassing traditional distributor markups.
- High-temperature tolerant VRLA designs:Convergence of enhanced AGM separators with corrosion-resistant grid alloys is enabling auxiliary power units to operate without thermal management in tropical climates.
Industry Challenges
- Battery traceability system integration:Domestic assembly thresholds require real-time production monitoring linked to national certification databases, extending compliance timelines for foreign suppliers.
- Skill scarcity in gel electrolyte formulation:Regional workforce gaps in controlled silica gelling processes limit production scale-up for premium deep-cycle products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Electric Vehicle VRLA Batteries Market |
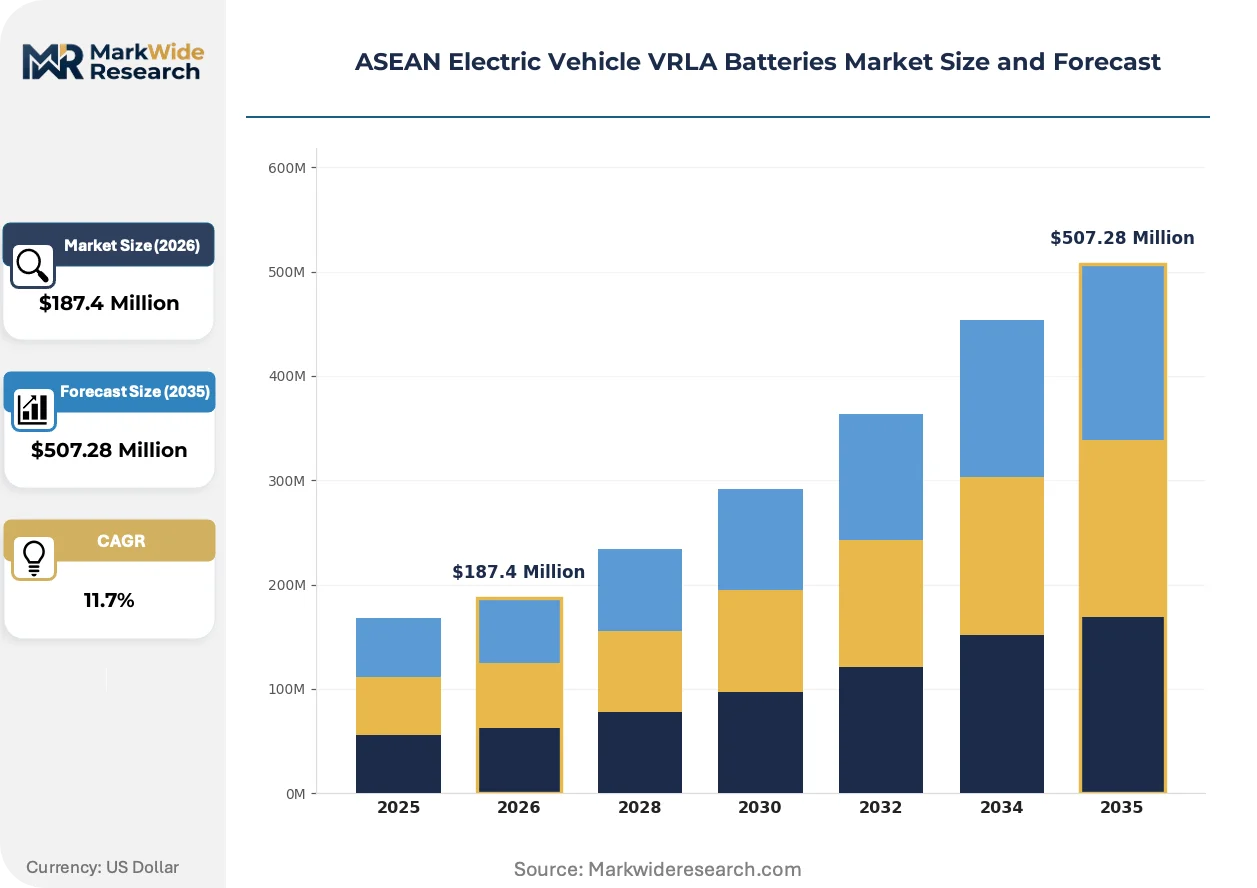
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sealed Lead Acid, Gel, Absorbent Glass Mat, Flooded End User: OEMs, Fleet Operators, Charging Stations, Aftermarket Providers Application: Electric Buses, Passenger Vehicles, Two-Wheelers, Commercial Vehicles Service Type: Installation, Maintenance, Repair, Replacement |
| Companies Covered | GS Yuasa Corporation, Siam GS Battery, Siam Furukawa, Clarios, Exide Industries, Leoch International Technology, EnerSys, Panasonic Energy, Amalgamated Batteries, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Electric Vehicle VRLA Batteries Market Trends and Innovations
Product architecture choices in ASEAN electric vehicle programs are diverging between auxiliary power optimization and primary traction displacement, with material science advances compressing traditional performance trade-offs.
Absorbed glass mat configurations with enhanced fiber compression ratios are supplanting conventional flooded designs in municipal bus auxiliary systems. Fleet procurement officers in Bangkok and Jakarta now specify vibration-resistant AGM units for low-voltage backup applications, compressing supplier qualification timelines from 18 to 8 months as crash-testing data from Thai assembly operations validates field durability.
Indonesia's Ministry of Industry localization mandates now require 40% domestic value-added thresholds for public procurement eligibility. Battery assemblers without co-production arrangements in Batang or Karawang industrial zones face automatic disqualification from state-owned enterprise tenders, redirecting foreign investment toward joint venture structures with nickel smelter operators.
Consolidated procurement by government-contracted bus services is fragmenting distributor influence across ASEAN urban centers. Fleet managers in Ho Chi Minh City now negotiate direct volume agreements with battery manufacturers, displacing multi-tier aftermarket networks that previously captured 25-30% margin layers in auxiliary power supply chains.
ASEAN Electric Vehicle VRLA Batteries Market Segmentation
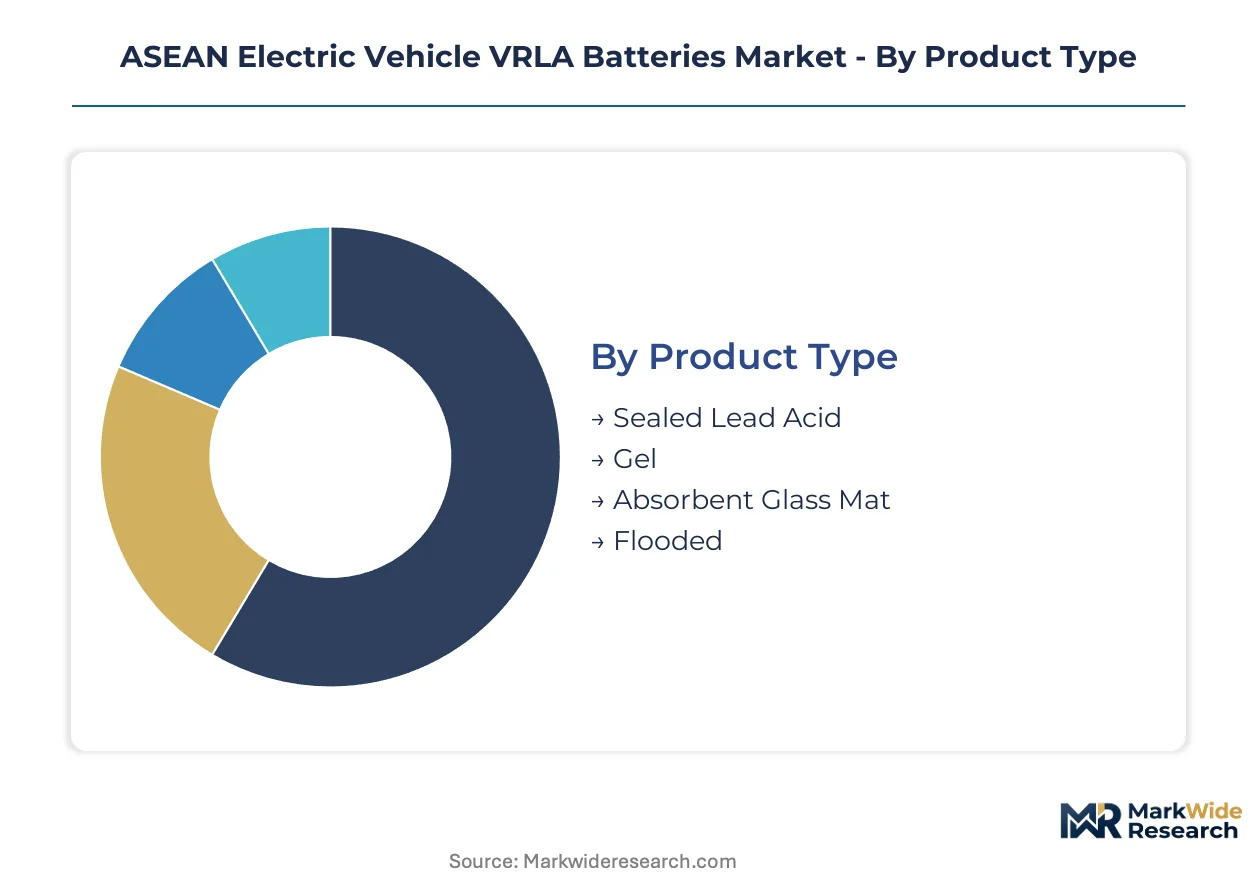
Segmentation in the ASEAN Electric Vehicle VRLA Batteries Market reveals how procurement patterns diverge between domestic fleet electrification programs and export-oriented OEM supply chains. Understanding these splits enables suppliers to align production footprints with regulatory eligibility thresholds across Thailand, Indonesia, and Vietnam.
Product Type:
Domestic assembly mandates in Thailand and Indonesia favor locally produced sealed lead-acid and gel systems, while absorbent glass mat configurations serve both regional OEMs and re-export markets to neighboring countries.
- Sealed Lead Acid:Maintenance-free designs with pressure-regulated valves prevent electrolyte loss during deep discharge cycles. Municipal bus fleets in Bangkok and Jakarta specify these units for auxiliary power applications, driven by 80% depth-of-discharge cycling requirements that disqualify conventional flooded alternatives.
- Gel:Silica-thickened electrolyte immobilization eliminates acid stratification in partial-state-of-charge operation typical of urban stop-start routes. Vietnam's electric two-wheeler uptake in Ho Chi Minh City emission zones creates concentrated demand for entry-level scooters requiring vibration-resistant gel configurations.
- Absorbent Glass Mat:Compressed glass fiber separators enable high-rate discharge tolerance for tropical climates without thermal management systems.
- Flooded:Cost-optimized wet-cell designs retain position in price-sensitive two-wheeler electrification schemes where periodic maintenance is acceptable.
Absorbent glass mat commands the established base across ASEAN auxiliary power applications. The steepest expansion runs through gel electrolyte systems as Vietnam's emission zone regulations accelerate two-wheeler electrification.
End User:
Procurement consolidation patterns separate consolidated fleet operators negotiating direct manufacturer relationships from fragmented aftermarket channels capturing residual replacement demand.
- OEMs:Chinese and Japanese vehicle assemblers in Thailand's Eastern Economic Corridor require localized VRLA sourcing to satisfy Board of Investment incentive compliance and domestic value-added thresholds.
- Fleet Operators:Government-contracted bus services in Jakarta, Bangkok, and Ho Chi Minh City now unbundle service contracts from hardware procurement, bypassing traditional distributor markups through direct volume agreements with battery manufacturers.
- Charging Stations:Grid-buffering auxiliary power units at fast-charging hubs employ deep-cycle VRLA systems for load balancing during peak demand periods.
- Aftermarket Providers:Multi-tier distribution networks face margin compression as fleet procurement consolidation displaces 25-30% markup layers previously captured in auxiliary power supply chains.
Fleet operators concentrate the fastest volume gains. OEMs anchor the premium tier through captive supply arrangements with localized assembly operations.
Application:
Vehicle category segmentation tracks how electrification mandates cascade from municipal bus procurement through commercial vehicle conversion programs to consumer two-wheeler adoption.
- Electric Buses:Urban transit electrification programs specify AGM auxiliary systems and gel primary traction batteries for entry-level fleet deployments, with procurement officers compressing supplier qualification timelines from 18 to 8 months using crash-testing data from Thai assembly operations.
- Two-Wheelers:Vietnam's Ministry of Transport emission zone regulations and Indonesia's motorcycle electrification subsidies create parallel demand channels for cost-optimized VRLA systems in entry-level scooters.
- Passenger Vehicles:Low-voltage backup systems in hybrid platforms employ sealed lead-acid units for 12V auxiliary functions.
- Commercial Vehicles:Light-duty truck electrification schemes in Thailand's logistics corridors specify deep-cycle tolerance for last-mile delivery routes.
Electric buses command the established base through consolidated government procurement. Two-wheelers deliver the steepest expansion trajectory as Vietnam's regulatory framework accelerates consumer adoption.
Service Type:
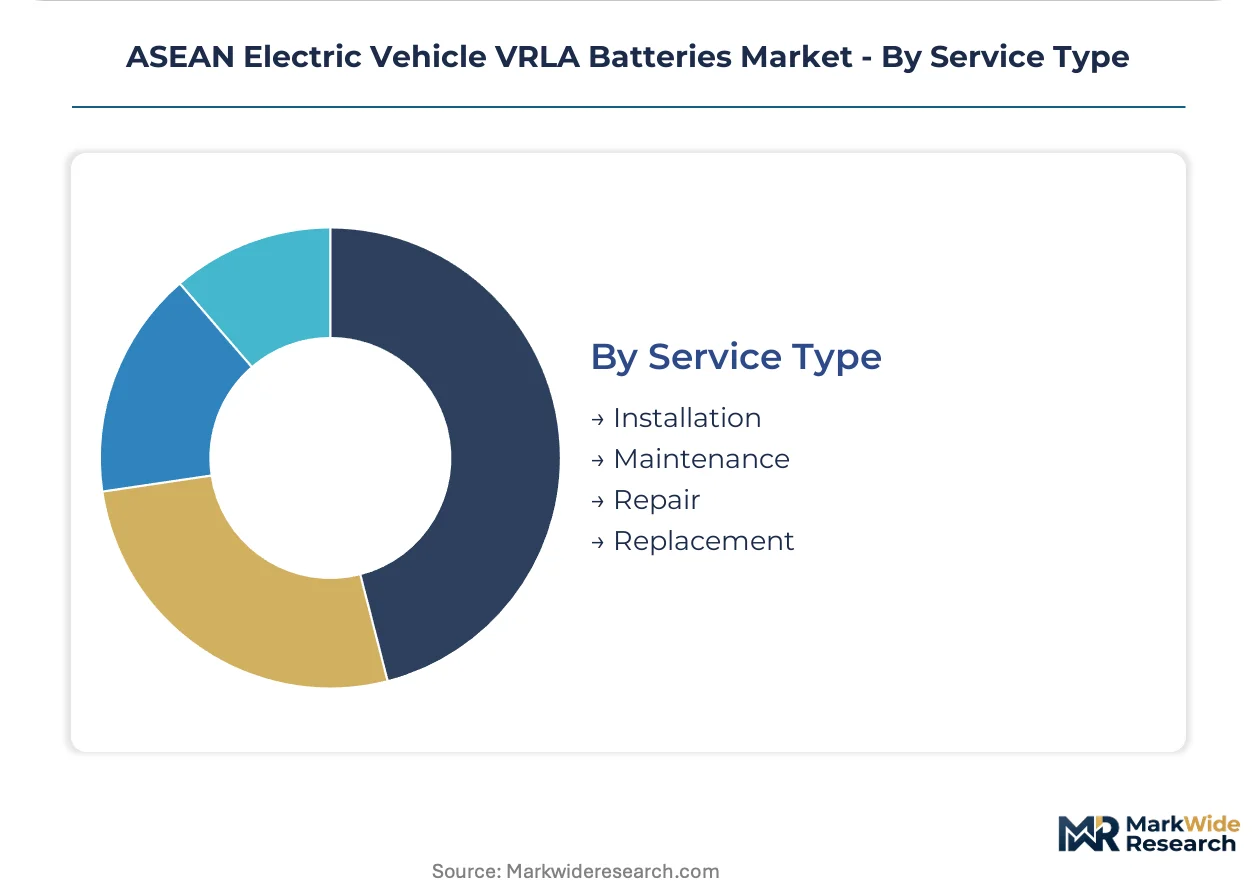
Service revenue distribution reflects the shift from hardware-centric procurement toward lifecycle cost optimization as fleet operators internalize maintenance capabilities.
- Installation:System integration services at OEM assembly plants in Batang and Karawang industrial zones require compliance with Indonesia's Ministry of Industry localization mandates and real-time production monitoring linked to national certification databases.
- Maintenance:Predictive service contracts for municipal bus fleets incorporate cycle-count monitoring and electrolyte-specific gravity testing to maximize operational life in tropical climates.
- Repair:Cell-balancing and terminal refurbishment services extend operational life for cost-sensitive two-wheeler operators.
- Replacement:End-of-life battery exchange programs face traceability requirements under domestic assembly thresholds mandating documentation of recycling chain custody.
Installation services command the established base through OEM captive demand. Maintenance contracts deliver the steepest expansion as fleet operators unbundle service from hardware procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across ASEAN. Vietnam's two-wheeler buyers demand entry-level VRLA systems, while Thailand's municipal fleets prioritize cycle-life performance over unit cost.
Thailand
Municipal bus electrification drives deep-cycle AGM procurement in Bangkok and the Eastern Economic Corridor. Thailand's Board of Investment grants tax holidays and import duty exemptions for localized battery assembly. Chinese and Japanese OEMs operate captive supply clusters in Chonburi and Rayong provinces, sourcing VRLA units for auxiliary power applications.
Indonesia
State-owned enterprise tenders require 40% domestic value-added thresholds for battery suppliers. Indonesia's Ministry of Industry mandates co-production arrangements with nickel smelter operators in Batang and Karawang industrial zones. Morowali Industrial Park partnerships reshape cost structures as nickel-cobalt supply chains expand downstream.
Vietnam
Ho Chi Minh City emission zone regulations accelerate electric two-wheeler uptake among price-sensitive consumers. Vietnam's Ministry of Transport mandates battery traceability linked to national certification databases. Gel electrolyte systems capture concentrated demand in entry-level scooter segments across southern urban centers.
Malaysia
Light-duty commercial vehicle electrification schemes in Penang and Selangor specify VRLA auxiliary systems for last-mile logistics. Malaysia's national automotive policy incentivizes domestic assembly of EV components. Johor Bahru industrial corridors host battery pack integration facilities serving cross-border Singapore demand.
Philippines
Jeepney fleet modernization programs in Metro Manila create sporadic demand for sealed lead-acid auxiliary units. The Philippines' Department of Energy promotes EV adoption through import duty reductions on battery components. Cebu and Davao manufacturing zones develop limited assembly capacity for two-wheeler electrification schemes.
ASEAN Electric Vehicle VRLA Batteries Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the ASEAN VRLA battery market. The supplier base organizes into three tiers: Japanese and Korean multinationals with regional manufacturing footprints, Chinese scale players with cost-optimized export platforms, and domestic ASEAN joint ventures serving protected procurement channels. Archetypes include high-temperature design specialists, aftermarket channel controllers, and integrated nickel-to-battery downstream operators. Capacity expansion and strategic partnerships dominate competitive moves as localization mandates compress supplier qualification timelines.
Among Japanese multinationals, GS Yuasa Corporation exemplifies the technology-led archetype through its Thai manufacturing base. Siam GS Battery and Siam Furukawa occupy positions within ASEAN joint venture structures. Clarios represents aftermarket channel control strategies, while Exide Industries anchors cost-optimized production for price-sensitive vehicle categories. Chinese players including Leoch International Technology and EnerSys exemplify scale-driven export platforms. Panasonic Energy and Amalgamated Batteries sit within diversified energy storage portfolios spanning multiple battery chemistries.
| Leading Market Players |
|---|
| GS Yuasa Corporation |
| Siam GS Battery |
| Siam Furukawa |
| Clarios |
| Exide Industries |
| Leoch International Technology |
| EnerSys |
| Panasonic Energy |
| Amalgamated Batteries |
| Others |
Pricing and Supply Chain Analysis
Eighteen-month supplier qualification timelines for Indonesian state-owned enterprise tenders compress pricing power toward battery assemblers with established co-production arrangements in Batang and Karawang industrial zones. This lead-time rigidity concentrates procurement decisions around domestic value-added thresholds rather than unit cost alone.
Pricing Analysis
After-sales maintenance contracts drive lifetime value for fleet operators unbundling service from hardware procurement. Three-tier pricing structure across premium AGM, standard sealed lead-acid, and economy flooded configurations differentiates offerings based on cycle-life certification and vibration-resistance ratings. Cost compression in the flooded tier intensifies as Chinese scale players export through Vietnam's two-wheeler channels. Fleet operators in Bangkok and Jakarta exhibit lowest price sensitivity, prioritizing 80% depth-of-discharge warranties over unit economics.
Supply Chain Analysis
Strait of Malacca transit underwrites refined lead ingot flows from Australia and China into Thai and Indonesian assembly plants. Regional production draws from Malaysian separator manufacturing, Vietnamese electrolyte chemical processing, and Indonesian nickel smelter byproducts. Single-source vulnerability concentrates in corrosion-resistant grid alloy supply from Japanese specialty metal producers. Distribution runs through OEM captive supply clusters in Thailand's Eastern Economic Corridor and direct volume agreements with consolidated fleet operators displacing multi-tier aftermarket networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Municipal fleet electrification cycles track government procurement budget approvals across Thailand, Indonesia, and Vietnam, creating predictable demand troughs during fiscal consolidation periods.
For Market Incumbents: Compound defensive positioning through backward integration into lead smelting partnerships in Indonesia's Morowali Industrial Park and certification investment for Indonesia's Ministry of Industry traceability databases. Lithium-ion substitution in bus traction applications threatens premium AGM volumes, necessitating high-temperature design R&D lock-in with Thai OEM assembly operations. For New Entrants and Emerging Players: Predictive maintenance service gaps in Vietnam's fragmented two-wheeler aftermarket present white-space capture opportunities. Gel electrolyte formulation for Ho Chi Minh City emission zone scooters offers the most penetrable entry point, with direct-to-fleet sales bypassing traditional distributor markups as the viable go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a regional consolidation play because localization mandates are structurally raising barriers for non-integrated foreign suppliers. Acquisition targets should display captive nickel supply linkages or established Ministry of Transport certification databases. The signal to watch is Indonesia's domestic value-added threshold adjustments in state tender regulations.| Strategic Initiative | Industry Significance |
|---|---|
| Co-Production Joint Venture | Indonesia's Ministry of Industry mandates 40% domestic value-added thresholds for public procurement eligibility. |
| High-Temperature AGM Development | Thai OEM assembly operations validate tropical climate durability without thermal management systems. |
| Direct Fleet Contracting | Bangkok and Jakarta bus operators bypass 25-30% distributor markups through unbundled procurement. |
| Gel Electrolyte Scale-Up | Vietnam's Ho Chi Minh City emission zones accelerate entry-level scooter electrification demand. |
| Battery Traceability Integration | Real-time production monitoring links to national certification databases under Thailand's Board of Investment compliance. |
Research Methodology
Desk research of customs trade data, ASEAN automotive production databases, and Ministry of Industry regulatory filings preceded structured interviews with OEM procurement managers, fleet operations directors, battery plant engineers, and aftermarket distribution heads. Primary fieldwork across Thai Eastern Economic Corridor facilities and Indonesian Batang industrial zone operations validated secondary estimates. Bottom-up cell-level production modeling triangulated against top-down vehicle electrification mandate projections.
Variance decomposition across product type, end-user category, and application segments anchored the analytical framework over the projection horizon. Modeled dimensions encompassed sealed lead-acid, gel, AGM, and flooded configurations; OEM, fleet operator, charging station, and aftermarket channels; and electric bus, two-wheeler, passenger vehicle, and commercial vehicle applications. CAGRs derived from segment-level volume build-ups incorporating domestic assembly threshold compliance timelines and nickel-cobalt supply chain cost evolution.
Forecasts assume regulatory continuity in Thailand's Board of Investment incentive regimes and Indonesia's Ministry of Industry localization mandates; material policy shifts would require re-modeling of supplier qualification timelines and domestic value-added thresholds. Lead price volatility and lithium-ion substitution acceleration in bus traction segments constitute primary revision risks. Practitioners should keep alternative scenarios live as Indonesia's nickel-to-battery downstream integration and Vietnam's emission zone expansion evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
EV Batteries
China Electric Vehicle Battery Market
EV Batteries
United States Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
European EV Battery Systems Market
EV Batteries
Europe Electric Vehicle Battery Electrolyte Market
EV Batteries
North America LFP Battery Pack Market
EV Batteries
South America Electric Vehicle Battery Anode Market
EV Batteries
United Kingdom Electric Vehicle Battery Manufacturing Market
EV Batteries
United States Electric Vehicle Battery Manufacturing Market
EV Batteries
Canada EV Battery Pack Market
EV Batteries
Europe Electric Bus Battery Pack Market
EV Batteries
Electric Vehicle Traction Batteries Market
EV Batteries
Europe Electric Vehicle VRLA Batteries Market
EV Batteries
France EV Battery Pack Market
EV Batteries
Canada Electric Vehicle Battery Manufacturing Equipment Market
EV Batteries
Asia-Pacific EV Battery Pack Market
EV Batteries
Electric Vehicle Battery Thermal Management Systems Market