
 Middle East and Africa Confectionery Market | 2026-2036
Middle East and Africa Confectionery Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Confectionery Market Foresight
Asset-light franchising and third-party manufacturing partnerships is reconfiguring competitive entry barriers across the Middle East and Africa confectionery landscape. Mars, Incorporated leverages its pan-African distribution infrastructure to sustain shelf presence in fragmented retail environments. Nestlé S.A. anchors premium positioning through localized production hubs in Egypt and South Africa. Mondelēz International differentiates via chocolate-focused R&D tailored to Gulf heat-stability requirements.
Confectionery comprises sugar-based or chocolate-based food products formulated with cocoa mass, cocoa butter, sweeteners, emulsifiers, and flavoring agents, manufactured through conching, tempering, molding, or depositing processes for sensory pleasure and ceremonial gifting purposes. Chocolate commands margin pools across Gulf duty-free and luxury retail channels, while gummies capture volume growth in South African and Nigerian mass markets. Specialty shops and online retail segments expand fastest where cold-chain logistics investment lags, pushing brands toward heat-resistant formulations and seasonal packaging innovations.
Saudi Food and Drug Authority standards and South African National Regulator for Compulsory Specifications frameworks govern ingredient labeling, additive limits, and halal certification requirements across the region. Egypt's food safety authority enforces progressively stricter sugar-content thresholds that reshape product formulation pipelines. Stakeholders must monitor evolving Gulf Cooperation Council harmonization talks and local sugar-tax proposals to anticipate reformulation costs and premium positioning opportunities.
Market Dynamics
Heat-stability formulation requirements are compressing R&D timelines across the Middle East and Africa confectionery sector as Gulf ambient temperatures force reformulation of conventional chocolate matrices. This thermal constraint is reshaping competitive positioning toward specialized fat-bloom inhibitors and modified cocoa butter equivalents.
Growth Catalysts
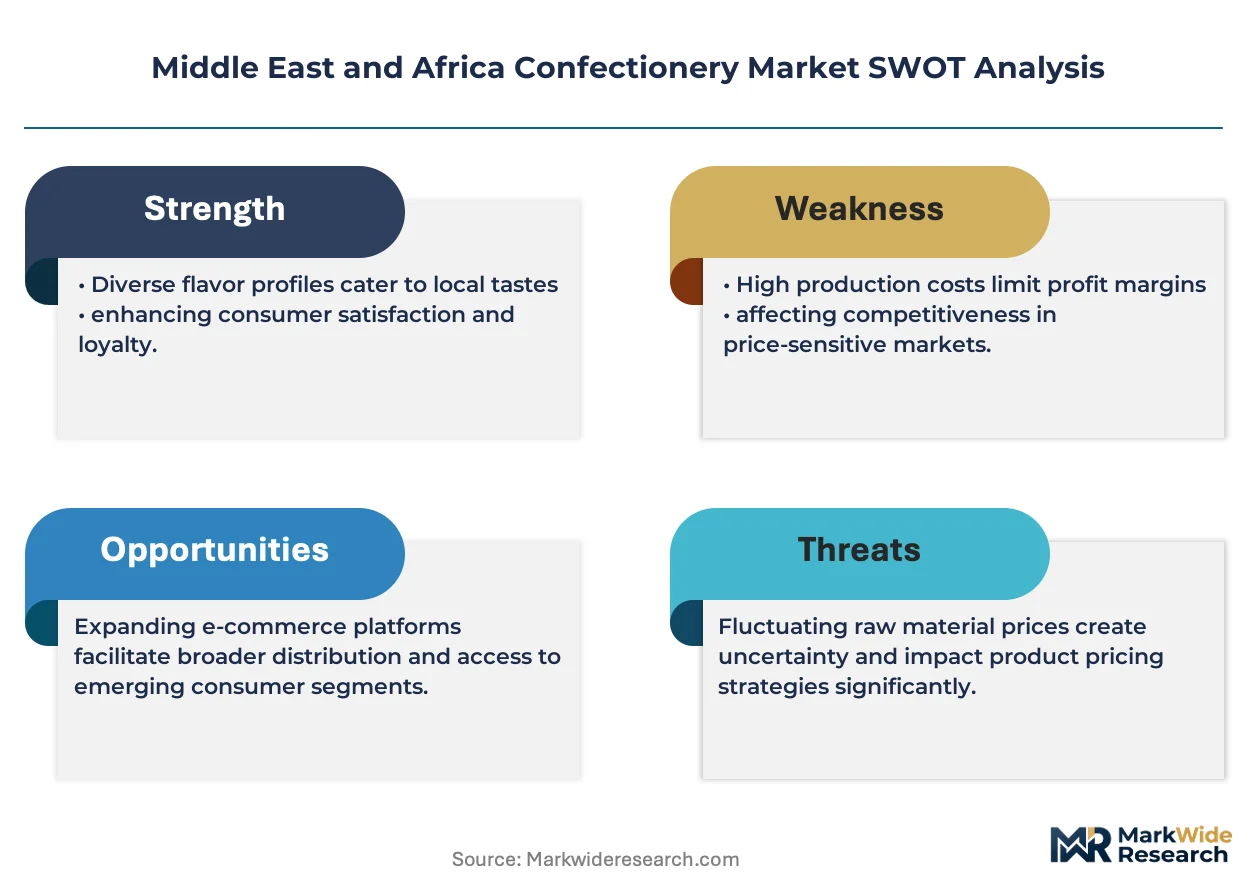
- Saudi Food and Drug Authority halal certification harmonization:Unified standards across Gulf Cooperation Council member states reduce multi-jurisdictional compliance burdens for cross-border manufacturers.
- South African National Regulator for Compulsory Specifications sugar-content thresholds:Progressive tightening of additive limits accelerates clean-label innovation pipelines and premium positioning for reformulated portfolios.
- Urban retail density in Lagos and Nairobi:Modern trade expansion in West and East African metropolitan corridors creates shelf-space access previously concentrated in Southern African markets.
Market Restraints
- Cocoa butter price volatility:Input cost swings from Côte d'Ivoire and Ghana supply concentration compress margin pools for chocolate-dependent product lines.
- Cold-chain infrastructure gaps:Temperature-controlled distribution limitations across Sahel and East African corridors restrict premium chocolate segment penetration.
- Egyptian food safety authority enforcement variance:Inconsistent provincial implementation of national sugar-content regulations creates compliance uncertainty for centralized production facilities.
Strategic Opportunities
- Nigerian informal retail digitization:Mobile payment integration in open-air markets and kiosks enables direct-to-retailer distribution bypassing traditional wholesale layers.
- Date-sugar and camel milk confectionery convergence:Indigenous ingredient technology fusion creates differentiated positioning for Gulf-origin premium gifting segments.
- United Arab Emirates luxury hospitality channel:Five-star hotel and airline amenity partnerships offer margin accretive volume outside price-sensitive mass retail.
Industry Challenges
- Halal certification timeline compression:Multi-stage religious authority approvals for new production facilities extend time-to-market for greenfield investments in Saudi Arabia and Egypt.
- Legacy ERP integration with track-and-trace mandates:Saudi Food and Drug Authority serialization requirements force expensive retrofitting of established manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Confectionery Market |
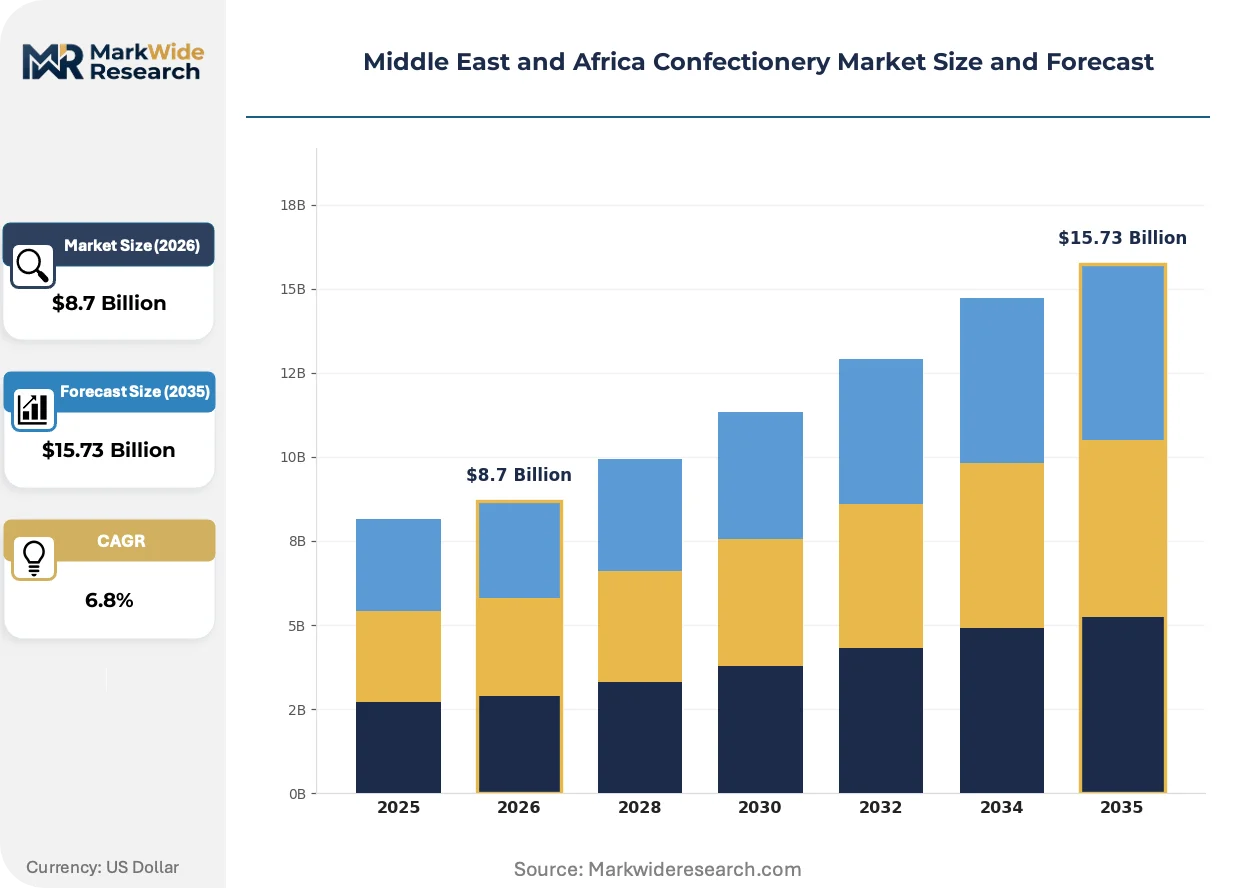
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chocolate, Gummies, Hard Candies, Licorice Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Shops End User: Retail Consumers, Bakeries, Food Service, Event Planners Packaging Type: Boxed, Bags, Tins, Bulk |
| Companies Covered | Ferrero SpA, Lindt & Sprüngli AG, Mars, Incorporated, Perfetti Van Melle Group B.V., Haribo GmbH, Mondelēz International, Inc., The Hershey Company, Pladis Global, Nestlé S.A., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Confectionery Market Shifts & Advancements
Thermal resilience engineering and indigenous ingredient valorization are actively reshaping formulation priorities across Middle East and Africa confectionery. These shifts compress traditional chocolate-centric portfolios while elevating regional raw material integration.
Modified fat systems with enhanced polymorphic stability are hybridizing conventional tempering protocols. Gulf-based luxury retailers and duty-free operators are adopting these heat-resistant chocolate matrices at accelerated procurement cycles. This thermal adaptation is hybridizing the boundary between premium chocolate and ambient-stable confectionery categories, enabling shelf presence in non-climate-controlled retail environments.
Saudi Food and Drug Authority's progressive alignment with Gulf Cooperation Council technical regulations is compressing formulation divergence across member states. Industrial consequence includes consolidated SKU strategies for manufacturers serving multiple Gulf markets. Chocolate and premium gifting segments face the steepest compliance adaptation costs as labeling and additive limits tighten.
Seasonal purchasing calendars anchored to Ramadan and Eid observances are compressing annual revenue concentration into discrete eight-week windows. Modern trade channels in Dubai and Jeddah are displacing year-round inventory models with just-in-time seasonal fulfillment. This demand pulse is most visible in Saudi Arabia and UAE urban centers where gifting expenditure concentrates during religious observance periods.
Middle East and Africa Confectionery Market Segmentation
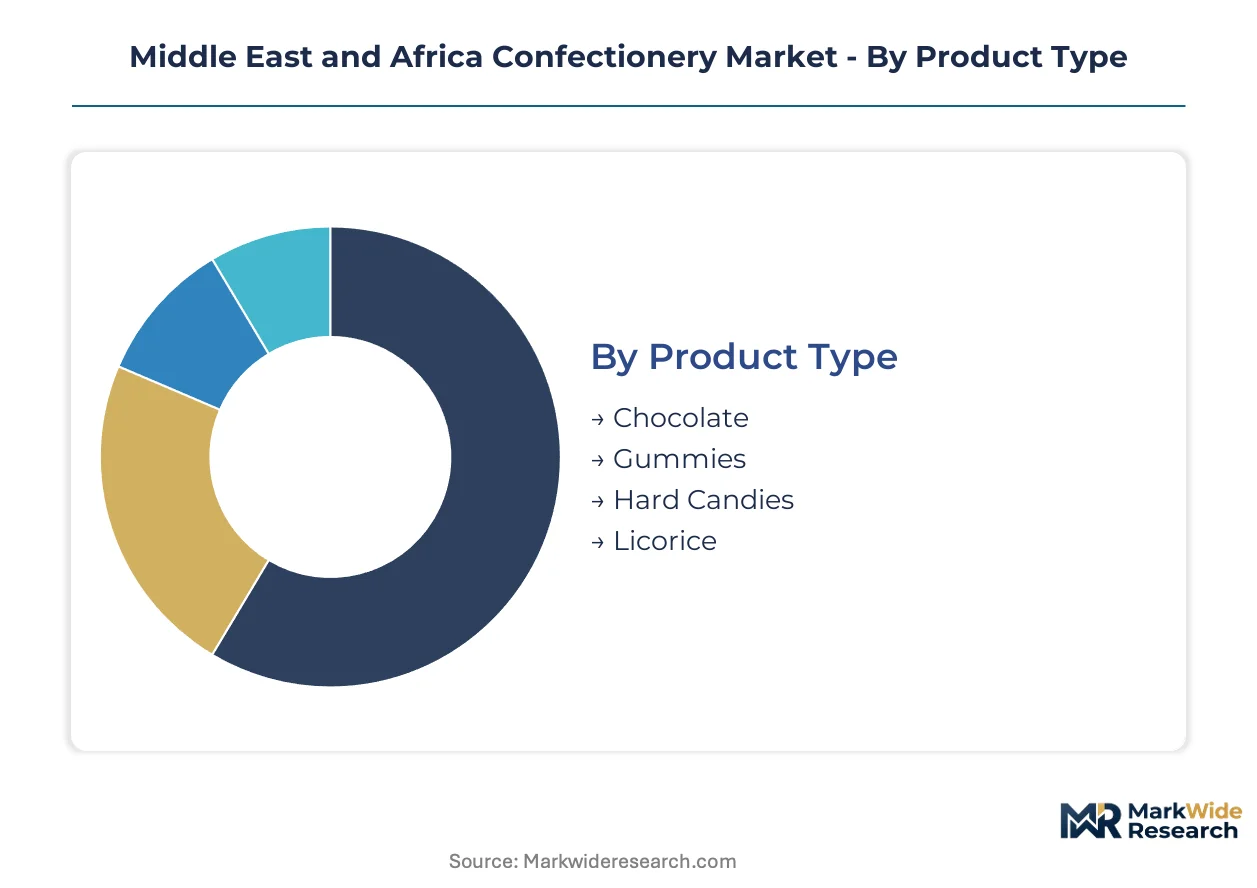
Segmentation across the Middle East and Africa confectionery market reveals divergent margin architectures between Gulf premium corridors and mass-market African expansion zones. Each dimension carries distinct regulatory, thermal, and channel-specific constraints that reshape portfolio prioritization.
Product Type:
Mature chocolate segments anchor value pools while emerging gummy formats capture volume growth in heat-stressed retail environments.
- Chocolate:Cocoa butter and cocoa mass formulations require modified fat systems with enhanced polymorphic stability for Gulf ambient conditions. Saudi Arabia and UAE duty-free channels concentrate demand for premium gifting assortments, though Egyptian sugar-content thresholds force progressive reformulation of milk chocolate matrices.
- Gummies:Gelatin and pectin-based chewy confectionery formulated with fruit purees and acidulants for tropical flavor profiles. Nigerian and South African mass retail drives volume, with heat stability advantages over chocolate enabling shelf presence in non-climate-controlled kiosks and open-air markets.
- Hard Candies:Sugar or isomalt-based amorphous solids produced through high-temperature cooking and pulling processes.
- Licorice:Glycyrrhizin-root extract formulations with anise flavoring, concentrated in North African heritage markets.
Chocolate handles the majority of throughput; gummies are expanding most quickly on share.
Distribution Channel:
Cost tier stratification separates capital-intensive modern trade from asset-light informal retail penetration models.
- Supermarkets:Climate-controlled hypermarket and supermarket chains with centralized procurement and planogram-managed shelf space. South African Shoprite and Pick n Pay networks, plus Saudi Carrefour and Lulu operations, concentrate volume for heat-sensitive chocolate segments.
- Online Retail:E-commerce platforms and direct-to-consumer fulfillment with cold-chain or ambient-stable logistics requirements. UAE and Saudi urban corridors show fastest adoption for seasonal gifting bundles, bypassing traditional wholesale markups.
- Convenience Stores:Small-format neighborhood retailers with limited refrigeration and high turnover velocity.
- Specialty Shops:Premium confectionery boutiques and chocolatiers targeting ceremonial gifting occasions.
Supermarkets dominate current value capture; online retail shows the steepest expansion trajectory.
End User:
Customer type fragmentation spans ceremonial purchasing, ingredient sourcing, and hospitality procurement with divergent specification requirements.
- Retail Consumers:Individual purchasers acquiring finished confectionery for personal consumption or gifting across Ramadan and Eid seasonal windows. Saudi and UAE households concentrate expenditure in eight-week religious observance periods, with premium chocolate assortments commanding ceremonial placement.
- Bakeries:Commercial pastry operations sourcing chocolate couverture, compound coatings, and decorative elements for cake and patisserie production. Cairo and Casablanca artisanal bakeries drive demand for heat-stable compound alternatives to pure chocolate.
- Food Service:Hotels, restaurants, and catering operations procuring portion-controlled and bulk formats.
- Event Planners:Corporate and wedding segment purchasers sourcing customized gifting and favor packaging.
Retail consumers absorb the bulk of volume; bakeries are climbing the fastest on share as food service outsourcing expands.
Packaging Type:
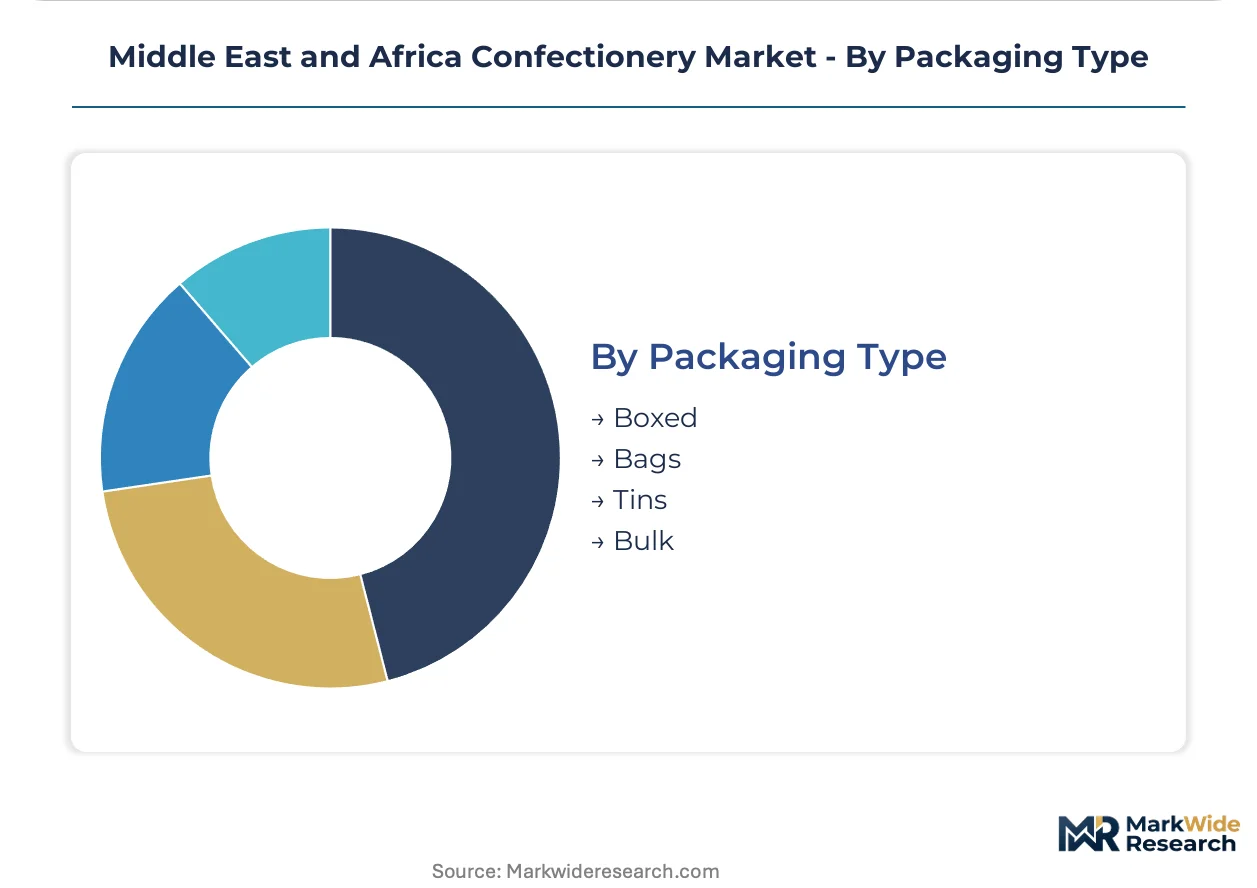
Supply concentration in seasonal and gifting formats elevates premium presentation requirements over functional containment.
- Boxed:Rigid paperboard or tin constructions with partition inserts for assorted chocolate presentation, often incorporating foil stamping and regional design motifs. UAE five-star hotel amenity partnerships and duty-free operators specify luxury boxed formats for margin-accretive hospitality channel placement.
- Bags:Flexible film or paper pouches with reseal features for portion-controlled consumption. South African and Nigerian mass-market gummy and hard candy segments favor bags for price-accessible single-serve and family formats.
- Tins:Metal containers with hermetic seals for extended shelf life and collectible reuse value.
- Bulk:Unpackaged or industrial-scale formats for food service and bakery ingredient applications.
Boxed formats command the premium tier; bags are gaining share fastest in volume terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Food and Drug Authority harmonization with Gulf Cooperation Council technical regulations is compressing cross-border compliance costs for manufacturers serving multiple jurisdictions. Egypt's progressive sugar-content thresholds and South Africa's clean-label mandates are accelerating reformulation investments. Urban retail expansion in Lagos and Nairobi is creating new shelf-space competition outside traditional Southern African concentration zones.
Saudi Arabia
Urban households in Riyadh and Jeddah concentrate ceremonial gifting expenditure during Ramadan and Eid observance periods. Saudi Food and Drug Authority halal certification requirements govern ingredient sourcing and production facility approvals. Duty-free operators at King Abdulaziz International Airport anchor premium chocolate volume for outbound travelers.
United Arab Emirates
Five-star hotel chains and airline amenity programs in Dubai generate margin-accretive hospitality channel demand. Dubai Municipality food safety regulations enforce labeling standards and additive limits for imported confectionery. Mall-based luxury retail in Downtown Dubai and Dubai Marina clusters heat-stable premium assortments for tourist and resident purchasers.
South Africa
Shoprite and Pick n Pay hypermarket networks concentrate volume for climate-controlled chocolate distribution. National Regulator for Compulsory Specifications frameworks govern sugar-content thresholds and clean-label additive limits. Gauteng and Western Cape provinces anchor manufacturing and logistics infrastructure for regional supply.
Egypt
Cairo-based artisanal bakeries drive demand for heat-stable compound coatings as alternatives to pure chocolate. Egyptian food safety authority enforcement of national sugar-content regulations creates formulation uncertainty for centralized production facilities. Alexandria and Suez Canal corridor cities concentrate import logistics and redistribution to Levant markets.
Nigeria
Lagos metropolitan retail density and mobile payment integration enable direct-to-retailer distribution bypassing wholesale layers. National Agency for Food and Drug Administration and Control standards govern product registration and import clearance. Open-air markets and kiosk networks in Ibadan and Kano capture mass-market gummy and hard candy volume.
Middle East and Africa Confectionery Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented retail environments and climate-stressed logistics corridors. The market structure tilts toward consolidated multinational presence in Gulf premium segments alongside distributed local manufacturing in African mass markets. Three archetypes dominate: heat-stability technology specialists, indigenous ingredient innovators, and pan-regional distribution integrators. Dominant competitive moves include third-party manufacturing partnerships and asset-light franchising arrangements that reduce capital deployment in cold-chain-constrained corridors.
Within the premium gifting tier, Ferrero SpA and Lindt & Sprüngli AG exemplify European-origin positioning focused on ceremonial occasions and duty-free channels. Mars, Incorporated anchors the pan-African distribution archetype through infrastructure spanning fragmented retail environments. These three entities represent contrasting strategic postures: European premium specialization, Swiss heritage positioning, and emerging market logistics integration.
| Leading Market Players |
|---|
| Ferrero SpA |
| Lindt & Sprüngli AG |
| Mars, Incorporated |
| Perfetti Van Melle Group B.V. |
| Haribo GmbH |
| Mondelēz International, Inc. |
| The Hershey Company |
| Pladis Global |
| Nestlé S.A. |
| Others |
Supply & Pricing Matrix
Cairo and Alexandria corridor production clusters anchor cocoa butter and compound coating supply for Levant and Gulf redistribution, with capacity utilization rates directly transmitting into downstream margin compression for Saudi and UAE finished goods manufacturers. Egyptian sugar-content enforcement variance and Saudi Food and Drug Authority halal certification timelines create asymmetric cost pass-through capabilities across the value chain.
Pricing Analysis
Certification level (halal-grade, SFDA-approved facility status) creates the primary spread between premium gifting assortments and mass-market formats. Three-tier pricing structure across ceremonial premium, heat-stable standard, and kiosk economy levels stratifies buyer segments, with duty-free operators and five-star hotel channels showing lowest price sensitivity. Pricing pressure stems from Côte d'Ivoire and Ghana cocoa butter volatility compressing chocolate-dependent margin pools. Open-air market retailers in Lagos and Ibadan represent the most price-sensitive segment, driving demand toward gummy and hard candy alternatives.
Supply Chain Analysis
Export-control regimes on specialized fat-bloom inhibitor technologies limit heat-stability formulation access for non-multinational manufacturers, concentrating advanced thermal resilience capabilities among licensed Gulf production facilities. Raw material dependencies center on Ghanaian and Ivorian cocoa mass, Malaysian palm oil derivatives, and Indian gelatin inputs. Single-source vulnerability runs through Côte d'Ivoire cocoa butter supply concentration, with logistics chokepoints at Suez Canal transit points amplifying disruption risk. Distribution runs through pan-African distributor networks in fragmented retail environments and climate-controlled hypermarket chains in Gulf urban centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion in West African metropolitan retail digitization and indigenous ingredient premiumization creates penetration tailwinds for differentiated positioning ahead of competitive saturation in Gulf gifting segments.
For Market Incumbents: Harden heat-stability R&D moats through captive formulation partnerships with Egyptian compound coating specialists, defending against emerging Gulf-based private label entrants. Prioritize backward integration into date-sugar and camel milk supply chains to anchor indigenous premium positioning. Lock in multi-year halal certification pre-approvals across Saudi greenfield capacity to compress competitor time-to-market. For New Entrants and Emerging Players: Establish a beachhead in Nigerian mobile-payment-integrated kiosk distribution, bypassing wholesale markup layers that burden incumbent cost structures. Target Lagos and Nairobi modern trade shelf-space expansion where planogram competition remains less concentrated than Southern African markets. Lead with heat-stable gummy formats priced for open-air market velocity. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors pan-African distribution integrators with cold-chain-agnostic product portfolios over pure-play chocolate specialists tethered to climate-controlled infrastructure. Five-to-ten year viability hinges on thermal resilience patent estates and Gulf hospitality channel lock-in. Watch for Saudi-Egyptian regulatory harmonization completion as inflection signal for consolidated SKU strategy premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Stability Formulation Partnership | Access to SFDA-approved thermal resilience patents locks in Gulf duty-free shelf presence against private label erosion. |
| Indigenous Ingredient Supply Integration | Backward control over Saudi date-sugar and UAE camel milk streams anchors premium gifting differentiation. |
| Mobile Payment Distribution Bypass | Direct-to-kiosk fulfillment in Nigerian open-air markets captures volume outside incumbent wholesale structures. |
| Halal Certification Pre-Approval Investment | Compressed religious authority timelines accelerate Saudi greenfield deployment versus competitor facility approvals. |
| Seasonal Fulfillment Infrastructure | Just-in-time Ramadan and Eid logistics capabilities capture ceremonial gifting revenue concentration windows. |
Research Methodology
Operator-level perspectives from category buyers at Saudi Carrefour and Lulu hypermarkets, Nestlé and Mars supply chain directors, Cairo artisanal bakery procurement leads, and Nigerian mobile payment platform operators anchored the qualitative base. Secondary validation drew from Saudi Food and Drug Authority regulatory filings, Egyptian food safety authority enforcement bulletins, customs trade data on cocoa butter imports, and Nielsen retail audit coverage of Gulf duty-free channels. Bottom-up SKU-level volume builds triangulated against top-down macro consumption models.
Scenario-bracketing around cocoa price volatility bands and regulatory harmonization timelines framed the analytical approach across the projection horizon. Segmentation dimensions modeled include product type (chocolate, gummies, hard candies), distribution channel (modern trade, online retail, informal retail), and end user (retail consumers, bakeries, food service). CAGRs derived from regression-based adoption curves incorporating heat-stability technology penetration rates and seasonal purchasing calendar concentration.
Macroeconomic conditions sit as an overlay; deviation in Gulf consumer discretionary spending, Egyptian pound volatility, and Nigerian naira liquidity would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement consistency and cold-chain infrastructure investment pace. Material shifts in Saudi-Egyptian sugar-content regulatory alignment or Côte d'Ivoire cocoa supply disruptions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Gum Base Candy Market
Confectionery
Asia-Pacific Sugar Free Chewing Gum Market
Confectionery
Middle-East and Africa Compound Chocolate Market
Confectionery
Pralines Market
Confectionery
Real and Compound Chocolate Market
Confectionery
Low Calorie Keto Desserts Market
Confectionery
Jellies and Gummies Market
Confectionery
Europe Confectionery Market
Confectionery
Licorice Candy Market
Confectionery
Black Treacle Market
Confectionery
Sugar-Free Sweets Market
Confectionery
Confectionery Fillings Market
Confectionery
Global Compound Chocolate Market
Confectionery
North America Chocolate Market
Confectionery
Salted Caramel Products Market
Confectionery
Confectionery Fats Market