
 Black Treacle Market | 2026-2036
Black Treacle Market Size, Share, and Industry Trends Forecast 2026-2036
Black Treacle Market Outlook
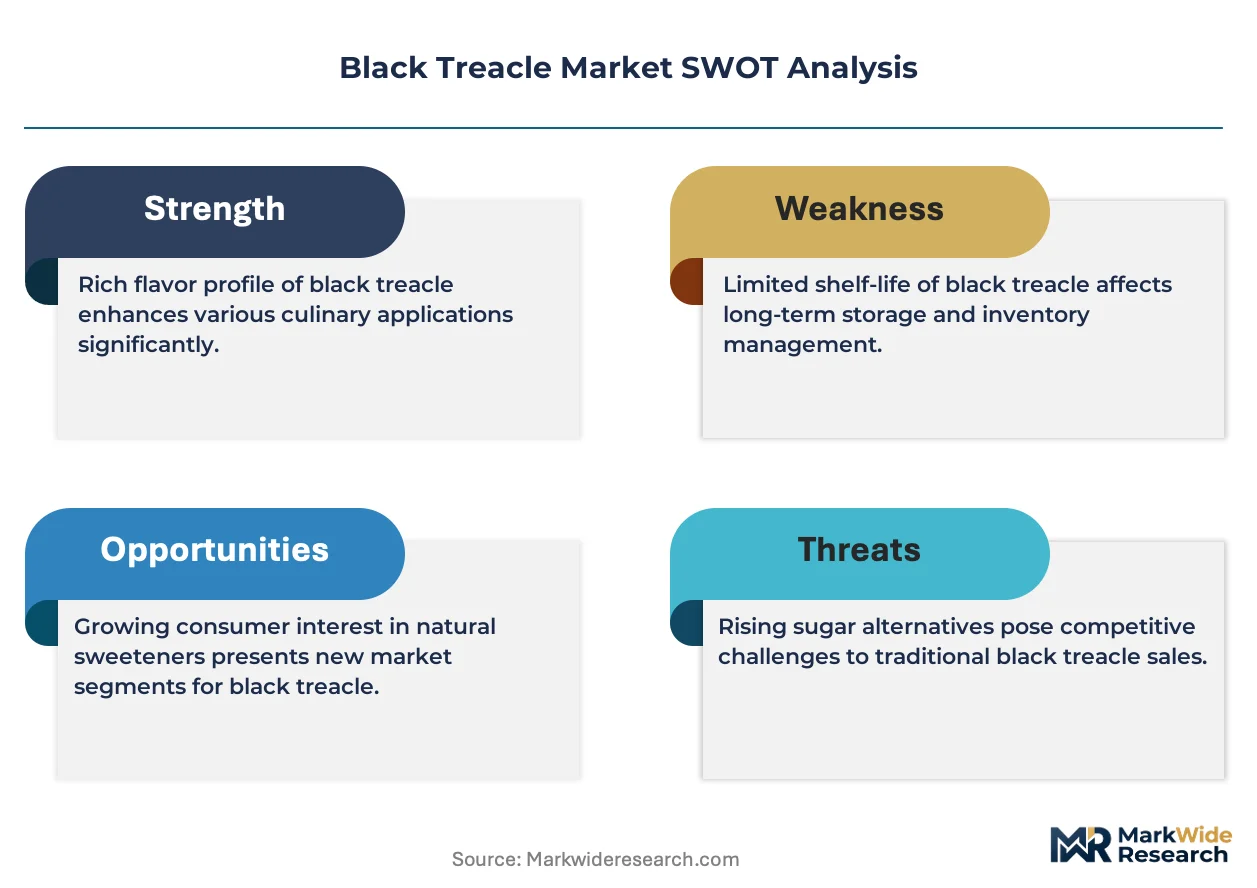
Aftermarket recipe formulation services is tilting margin pools away from commodity treacle sales toward technical support and custom blend development. Ragus leverages its century-old refining heritage to anchor premium positioning in British industrial accounts. Tate & Lyle competes through vertically integrated cane supply chains spanning multiple continents. Cargill extends its agricultural origination network into specialized molasses distribution across North American food manufacturers.
Black treacle is a viscous, dark-brown syrup produced during the refining of sugarcane or sugar beet into sucrose, containing approximately 25-30% inverted sugars, 20-25% sucrose, and significant mineral content including iron and calcium, functioning primarily as a humectant, colorant, and flavoring agent in baked goods, confectionery, and brewing applications. Dark Treacle occupies the dominant volume position due to its traditional role in gingerbread and fruitcake formulations across Commonwealth markets. Golden Syrup differentiates through its lighter color profile and cleaner sweetness, capturing premium positioning in artisanal baking segments where visual clarity matters. Industrial Grade product commands stable offtake from brewing and fermentation sectors where standardized Brix levels and consistent mineral content reduce process variability.
The EU Green Deal and REACH framework govern molasses import standards and residual chemical thresholds within European markets, while the FDA and USDA regulate domestic treacle labeling and processing in the United States. BIS food-grade specifications in India and FSSAI purity standards shape market access for imported black treacle across South Asian confectionery channels. Stakeholders must monitor evolving sugar beet cultivation subsidies and cane sustainability certifications that will determine long-term feedstock availability and cost structures.
Market Dynamics
The EU Green Deal's farm-to-fork sustainability targets are compressing molasses supply chains toward certified cane origins and traceable beet cultivation, forcing treacle processors to requalify feedstock sources or forfeit access to premium industrial accounts.
Growth Catalysts
- EU Green Deal farm-to-fork mandates:REACH-aligned purity standards are pulling treacle demand toward verified sustainable supply chains, rewarding processors with certified origination networks.
- Heritage confectionery revival:British gingerbread and fruitcake formulations are absorbing rising volumes of dark treacle as domestic brands emphasize traditional ingredient provenance.
- Clean-label bakery expansion:Western European artisanal bakers are specifying black treacle for its single-ingredient humectant credentials, displacing synthetic alternatives.
Market Restraints
- Cane sugar price volatility:Brazilian and Indian harvest fluctuations transmit directly into molasses input costs, compressing processor margins without forward-contract hedging.
- REACH residual chemical thresholds:ECHA-enforced contaminant limits are disqualifying traditional sourcing routes from Eastern European beet suppliers.
- High-fructose corn syrup substitution:North American industrial bakers are reformulating toward cheaper sweetener alternatives where color and mineral content are secondary.
Strategic Opportunities
- Underpenetrated Indian confectionery channels:FSSAI-compliant treacle imports face limited domestic competition for premium halwa and chikki applications.
- EU carbon border adjustment mechanisms:The CBAM framework will advantage European treacle processors with verified low-carbon cane supply chains against imported alternatives.
- Specialty brewing fermentation:Craft distillers in Scotland and Ireland are specifying mineral-rich black treacle for rum and stout flavor profiles.
Industry Challenges
- Refining heritage skill attrition:Centuries-old open-pan evaporation expertise is disappearing as British sugar refineries automate, threatening batch consistency.
- Multi-jurisdiction certification timelines:Simultaneous BIS, FSSAI, and FDA approvals stretch product launch cycles for exporters targeting multiple markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Black Treacle Market |
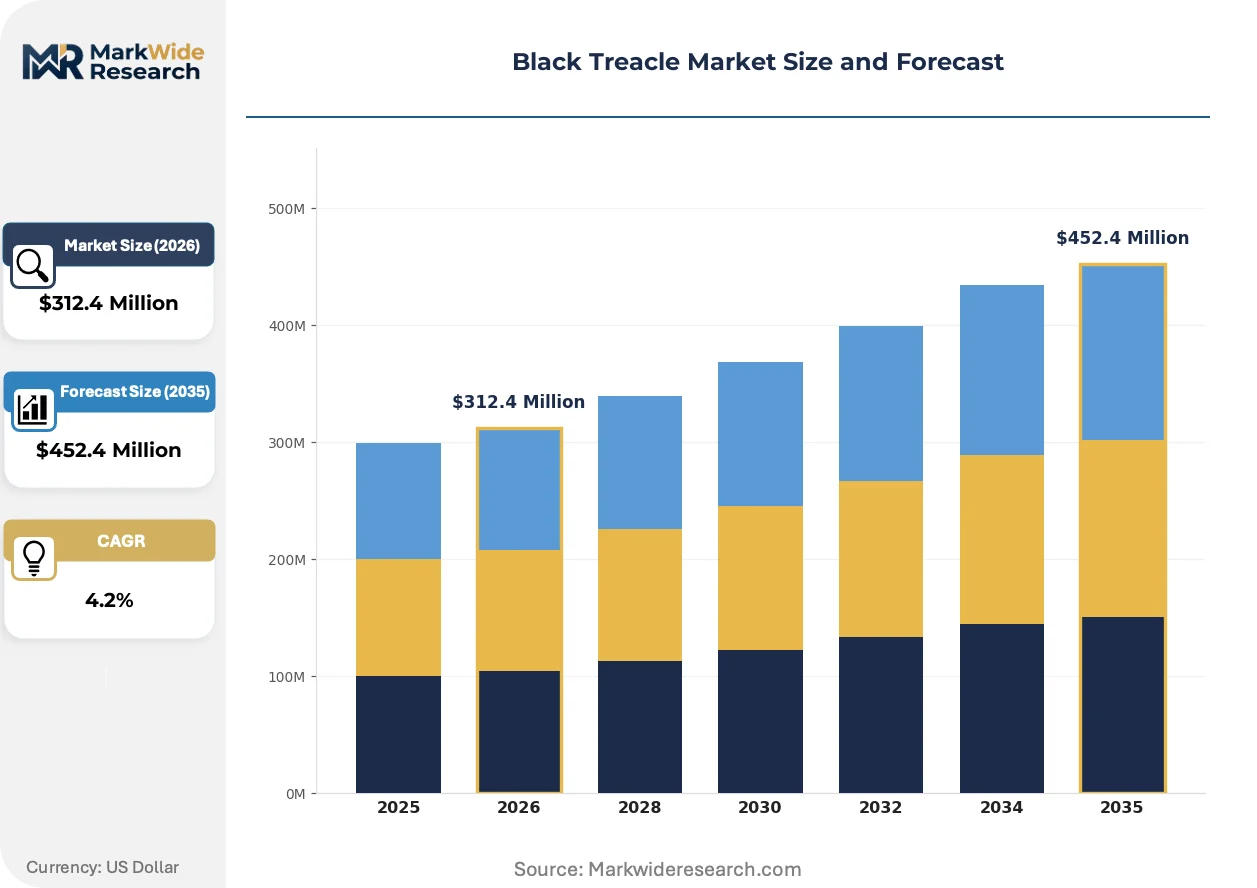
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $452.4 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Treacle, Light Treacle, Blackstrap Molasses, Golden Syrup End Use: Baking, Confectionery, Sauces, Beverages Grade: Food Grade, Industrial Grade, Organic, Non-Organic Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Ragus, Knorr, Tate & Lyle, British Sugar, Wilkin & Sons, Sun Agro Foods, Chelsea Sugar, Cargill, Shepcote, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Black Treacle Market Strategic Shifts
Digital traceability platforms and precision fermentation are rewriting how treacle processors demonstrate provenance and explore alternative production pathways, while regulatory pressure on residual contaminants accelerates separation technology investment.
Blockchain-enabled origin verification is virtualizing supply chain documentation for black treacle shipments. British industrial bakers and EU confectionery manufacturers are mandating lot-level traceability from cane field to finished goods. This technology is virtualizing the audit function, compressing third-party certification costs while locking out uncertified competitors.
REACH Annex XVII updates are tightening polycyclic aromatic hydrocarbon limits in molasses-derived food additives. ECHA enforcement is forcing processors to install activated carbon filtration or switch to certified low-PAH cane varieties. Dark treacle destined for infant food and pharmaceutical applications faces the steepest compliance burden, with German and Dutch importers leading qualification efforts.
Direct-procurement platforms are disintermediating traditional molasses brokers. Large British bakery groups and North American brewing conglomerates are negotiating volume contracts directly with Mauritian and Fiji cane processors. This channel compression is most advanced in the United Kingdom, where heritage brands leverage century-old relationships to secure preferential offtake from specific plantation cooperatives.
Black Treacle Market Segmentation
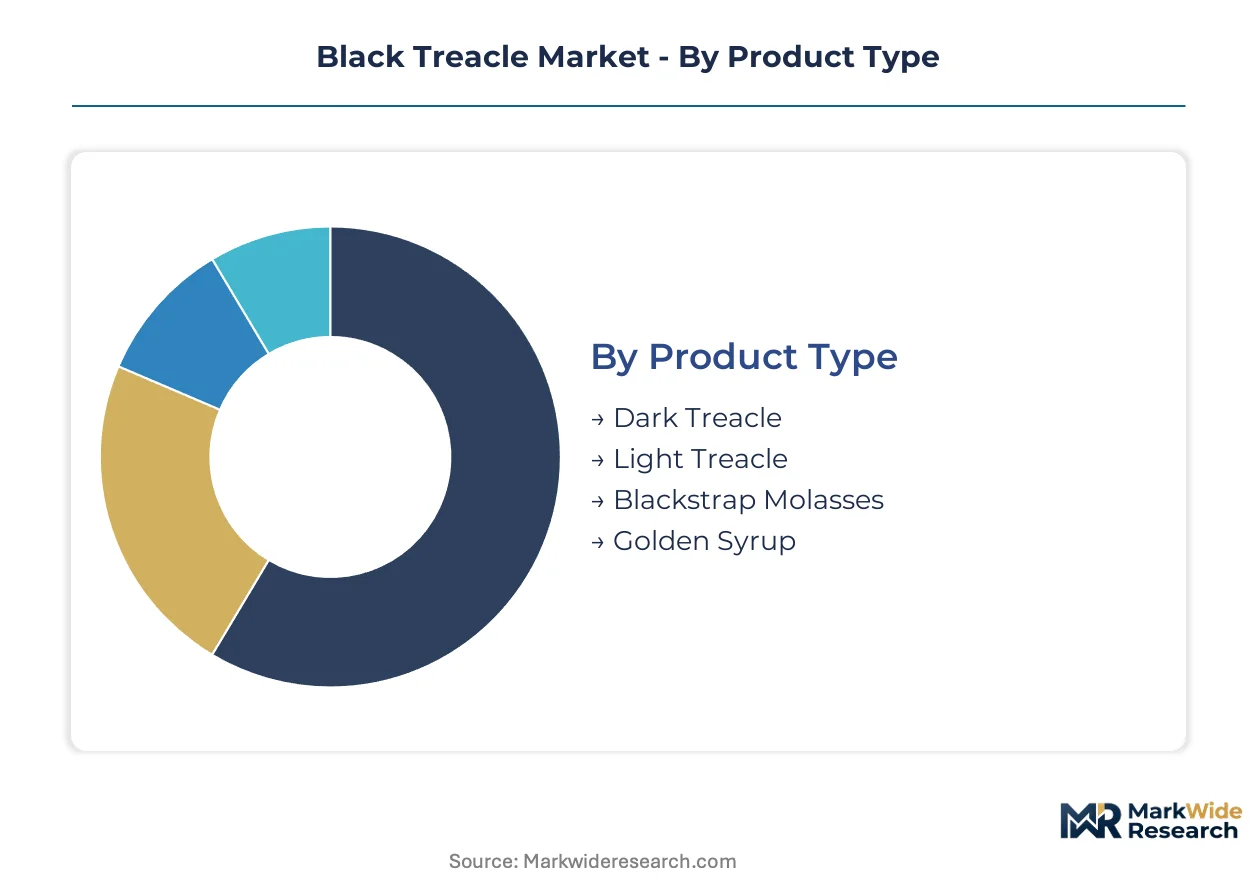
Black treacle's diverse functional profiles create distinct margin architectures across product tiers. Segmentation reveals how technical specifications, application requirements, and distribution economics fragment addressable markets into specialized competitive arenas.
Product Type:
After-sales formulation support intensity varies sharply across product types, with industrial bakers demanding ongoing technical consultation that commodity traders cannot match.
- Dark Treacle:This viscous syrup contains 25-30% inverted sugars and significant mineral content, delivering the characteristic bitter-sweet depth essential to traditional British gingerbread and fruitcake formulations. United Kingdom heritage confectionery brands specify this grade for its humectant properties and color stability. Demand concentrates in Commonwealth markets where colonial-era recipes remain culturally embedded.
- Golden Syrup:Lighter in color with cleaner sweetness, this refined product captures premium positioning in artisanal baking segments where visual clarity matters. Western European clean-label bakers specify it for single-ingredient credentials that displace synthetic alternatives. The product commands formulation flexibility in high-end patisserie applications.
- Light Treacle:Intermediate viscosity and mineral content serve industrial bakers seeking cost-optimized humectant functionality.
- Blackstrap Molasses:Highest mineral concentration targets health-positioned food applications and supplement formulations.
By volume, Dark Treacle leads. By growth pace, Golden Syrup is ahead.
End Use:
Application economics split sharply between high-volume industrial contracts and specification-intensive artisanal accounts.
- Baking:Industrial-scale bread and cake manufacturers absorb standardized treacle volumes for moisture retention and browning control. British commercial bakery groups negotiate direct-procurement contracts with Mauritian cane processors to secure preferential offtake. REACH-aligned purity standards are compressing supply chains toward certified sustainable origins.
- Confectionery:Heritage British brands anchor domestic offtake for traditional toffee and treacle tart applications. EU Green Deal farm-to-fork mandates are pulling demand toward verified supply chains with blockchain-enabled traceability. German and Dutch importers lead qualification efforts for infant-food-grade specifications.
- Sauces:Barbecue and savory glaze applications in North American food service drive stable industrial demand.
- Beverages:Craft distillers in Scotland and Ireland specify mineral-rich black treacle for rum and stout flavor profiles.
Baking commands absolute tonnage. Confectionery shows the steepest expansion trajectory as clean-label positioning accelerates.
Grade:
Certification tiering determines market access velocity and pricing power across regulatory jurisdictions.
- Food Grade:Standardized Brix levels and contaminant thresholds serve mainstream bakery and confectionery channels. FDA and USDA labeling requirements govern United States market entry, while BIS specifications shape Indian access. Processors must maintain parallel certification portfolios to serve multiple geographies simultaneously.
- Industrial Grade:Consistent mineral content and fermentation predictability reduce process variability for brewing and distillation applications. ECHA-enforced REACH thresholds are disqualifying traditional Eastern European beet sourcing routes. Scottish and Irish craft distillers drive specialty demand for flavor-complex profiles.
- Organic:Certified cane and beet cultivation commands premium positioning in Western European clean-label segments.
- Non-Organic:Conventional cultivation serves price-sensitive industrial accounts where certification adds no functional value.
Food Grade dominates shipment volumes. Organic certification is climbing the fastest as EU sustainability mandates harden.
Distribution Channel:
Channel structure reflects customer scale and technical service requirements, with direct procurement eroding traditional broker roles.
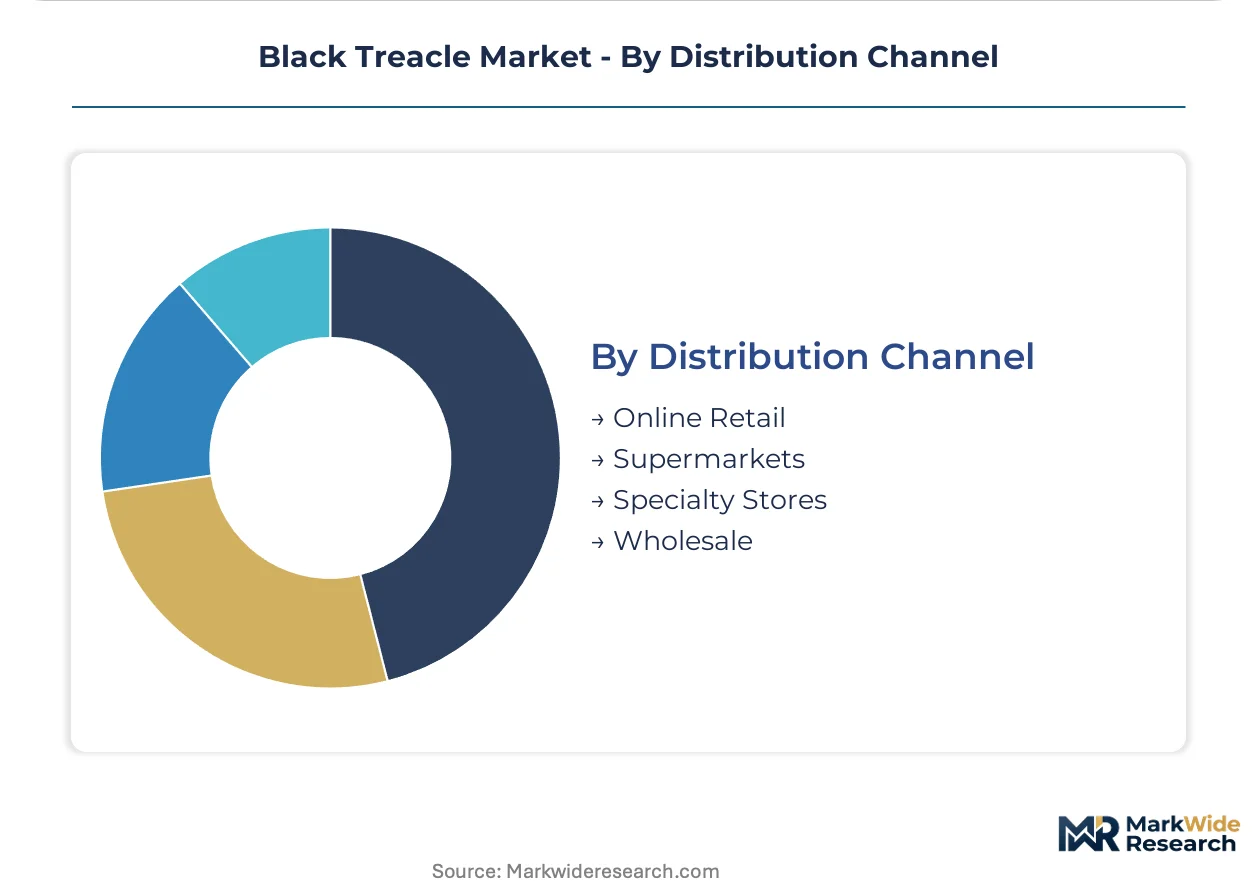
- Wholesale:Volume contracts with industrial bakeries and brewing conglomerates bypass intermediaries through direct-procurement platforms. Large British groups leverage century-old relationships with specific plantation cooperatives. Channel compression is most advanced in the United Kingdom market.
- Specialty Stores:Artisanal bakers and heritage confectionery producers source small-batch treacle with documented provenance. Blockchain-enabled lot-level traceability is becoming mandatory for EU and British industrial accounts. This channel captures premium pricing through technical consultation bundling.
- Supermarkets:Packaged retail formats serve home bakers in Commonwealth markets with traditional recipe cultures.
- Online Retail:Direct-to-consumer platforms expand access for specialty grades in underpenetrated geographic markets.
Wholesale moves the most tonnage. Specialty Stores are gaining share fastest as traceability requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in North American industrial bakeries exhibit acute price sensitivity, driving substitution toward corn syrup alternatives, while British heritage confectioners absorb premium pricing for certified-provenance treacle without volume elasticity.
United Kingdom
Heritage gingerbread and fruitcake manufacturers anchor domestic offtake for dark treacle with documented colonial-era recipe provenance. The Food Standards Agency enforces strict molasses labeling requirements that reward processors with transparent supply chains. Industrial clusters in East Anglia and the West Midlands concentrate treacle refining capacity where century-old open-pan expertise persists.
Germany
Artisanal bakers in Bavaria and Baden-Württemberg specify golden syrup for clean-label patisserie applications demanding visual clarity. ECHA-enforced REACH Annex XVII updates tighten polycyclic aromatic hydrocarbon thresholds in molasses imports. The Rhine-Ruhr industrial corridor hosts specialized distributors qualifying treacle for infant-food-grade pharmaceutical applications.
United States
North American brewing conglomerates absorb industrial-grade molasses for standardized fermentation predictability, though high-fructose corn syrup substitution pressures commodity treacle volumes. FDA and USDA labeling regulations govern domestic processing standards. Craft distillers in Kentucky and Tennessee specify mineral-rich blackstrap for bourbon and rum flavor complexity.
India
FSSAI-compliant treacle imports face limited domestic competition for premium halwa and chikki confectionery applications in Maharashtra and Gujarat. BIS food-grade specifications shape market access for imported molasses across South Asian channels. Mumbai and Ahmedabad industrial zones concentrate traditional sweetmeat manufacturing that specification-grade treacle suppliers target.
Mauritius
Plantation cooperatives supply certified sustainable cane origins that British bakery groups procure through direct-procurement platforms bypassing traditional brokers. EU Green Deal farm-to-fork traceability requirements advantage island processors with blockchain-enabled documentation. Port Louis serves as the primary export hub for premium treacle destined for Commonwealth heritage brands.
Black Treacle Market Competitive Environment
Capability concentration sits with heritage refiners possessing century-old open-pan expertise; scale advantage sits with agricultural conglomerates with captive cane supply chains. The market structures around three tiers: British industrial specialists, vertically integrated sugar processors, and regional plantation-direct distributors. Dominant competitive moves include backward integration into certified cane origination and technical service bundling that displaces commodity trading margins.
Among British heritage specialists, Ragus and Tate & Lyle exemplify the premium-tier positioning built on refining lineage and formulation support capabilities. Cargill occupies the scale-driven agricultural-origination segment with continental supply chain breadth. These three anchors demonstrate how competitive advantage splits between technical consultation intensity and feedstock control.
| Leading Market Players |
|---|
| Ragus |
| Knorr |
| Tate & Lyle |
| British Sugar |
| Wilkin & Sons |
| Sun Agro Foods |
| Chelsea Sugar |
| Cargill |
| Shepcote |
| Others |
Value Chain & Pricing Dynamics
Port Louis-to-Southampton freight corridors transmit Brazilian and Mauritian cane harvest volatility directly into British bakery procurement costs, compressing processor margins while amplifying price spreads between certified-sustainable and conventional treacle grades. This logistics-cost dynamic concentrates pricing power with heritage refiners possessing direct plantation relationships, forcing commodity traders toward technical-service bundling to defend position.
Pricing Analysis
After-sales formulation support and extended technical consultation contracts generate lifetime value that exceeds commodity treacle sales by significant multiples. Three-tier pricing structure across premium certified-provenance, standard food-grade, and economy industrial tiers reflects certification depth and origin traceability. Pricing pressure stems from high-fructose corn syrup substitution in North American industrial baking, where color and mineral content carry secondary priority. Large British heritage brands show minimal price elasticity, while North American brewing conglomerates negotiate aggressively on volume contracts.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Mauritian plantation cooperatives anchor working-capital structures for British industrial bakery groups. Feedstock draws from Brazil, India, and Mauritius cane belts, with secondary beet sourcing from France and Germany. Raw material dependencies center on sucrose extraction rates, seasonal harvest timing, and EU Green Deal sustainability certification status. Single-source vulnerability concentrates in blockchain-enabled traceability platform providers serving EU compliance mandates. Distribution runs through direct-procurement platforms disintermediating traditional molasses brokers, with specialty stores capturing premium artisanal volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-enabled origin verification and EU carbon border adjustment mechanisms are disrupting competitive positioning, rewarding processors with certified low-carbon supply chains against import-dependent competitors. This technological-regulatory inflection compresses launch timelines for uncertified entrants while amplifying returns on upstream sustainability investment.
For Market Incumbents: Pre-empt high-fructose corn syrup substitution threat in North American brewing by deepening formulation support capabilities that commodity sweeteners cannot replicate. Consolidate backward integration into certified Mauritian and Fijian cane cooperatives before EU carbon border adjustments harden. Lock in blockchain traceability partnerships with plantation-direct distributors to foreclose competitor access to premium British industrial accounts.
For New Entrants and Emerging Players: Build out FSSAI-compliant supply chains targeting premium halwa and chikki applications in Maharashtra and Gujarat, where domestic competition remains limited. Capture share in Indian confectionery channels through direct technical consultation models that established commodity traders have neglected. Lead with infant-food-grade qualification capabilities to penetrate German and Dutch pharmaceutical-adjacent import channels.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified sugar conglomerates with underutilized treacle refining assets and dormant certification portfolios. Long-term viability hinges on feedstock origination control rather than commodity trading scale. Watch EU Green Deal implementation velocity as the signal for margin compression timing among import-dependent processors lacking verified supply chains.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Cane Origination | Mauritian plantation cooperatives with EU Green Deal compliance command preferential offtake from British heritage brands. |
| Blockchain Traceability Platform Deployment | Lot-level origin verification virtualizes audit functions and locks out uncertified competitors from premium EU accounts. |
| Technical Service Bundling | Formulation consultation contracts displace commodity trading margins with recurring revenue from industrial bakery accounts. |
| Multi-Jurisdiction Certification Investment | Parallel BIS, FSSAI, and FDA approvals compress product launch cycles for exporters targeting Indian and North American channels. |
| Specialty Brewing Fermentation Partnerships | Craft distillers in Scotland and Ireland specify mineral-rich profiles that commodity molasses suppliers cannot replicate. |
Study Parameters
A spread of perspectives from treacle refinery operations managers, procurement leads at British industrial bakery groups, Mauritian plantation cooperative directors, ECHA regulatory affairs specialists, and specialty brewing fermentation scientists converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against EU customs data, FSSAI import filings, British Sugar industry association reports, and REACH Annex XVII enforcement disclosures. Bottom-up volume modeling from end-use application segments triangulated against top-down cane and beet harvest projections.
Demand-supply-balance framing anchored the analytical approach across the analysis window, with segmentation modeling across product type, end-use application, certification grade, and distribution channel dimensions. CAGRs derived from trend extrapolation of clean-label bakery expansion rates, heritage confectionery revival intensity, and EU sustainability mandate implementation pacing. Industry-specific inputs included sucrose extraction yield forecasts and blockchain traceability adoption curves among British industrial accounts.
Sensitivities concentrate around Brazilian harvest volatility, EU carbon border adjustment implementation timing, and high-fructose corn syrup substitution elasticity in North American brewing. Forecasts reflect documented assumptions on regulatory enforcement intensity and certification cost trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Ruby Chocolate Market
Confectionery
Europe Compound Chocolate Market
Confectionery
Edible Glitter Market
Confectionery
Green Tea Chocolate Market
Confectionery
Middle East and Africa Premium Chocolate Market
Confectionery
Asia Pacific Chocolate Market
Confectionery
Sugar Free Lollipops Market
Confectionery
Sugar-Free Confectionery Market
Confectionery
Asia Pacific Sugar Confectionery Market
Confectionery
Dietary Chocolate Products Market
Confectionery
Global Chocolate Sprinkles Market
Confectionery
Infused Fruits Jellies Market
Confectionery
North America Sugar Confectionery Market
Confectionery
Low-Fat Sweets Market
Confectionery
Mooncake Market
Confectionery
Diet Candy Market