
 North America Chocolate Market | 2026-2036
North America Chocolate Market Size, Share, and Industry Trends Forecast 2026-2036
North America Chocolate Market Intelligence
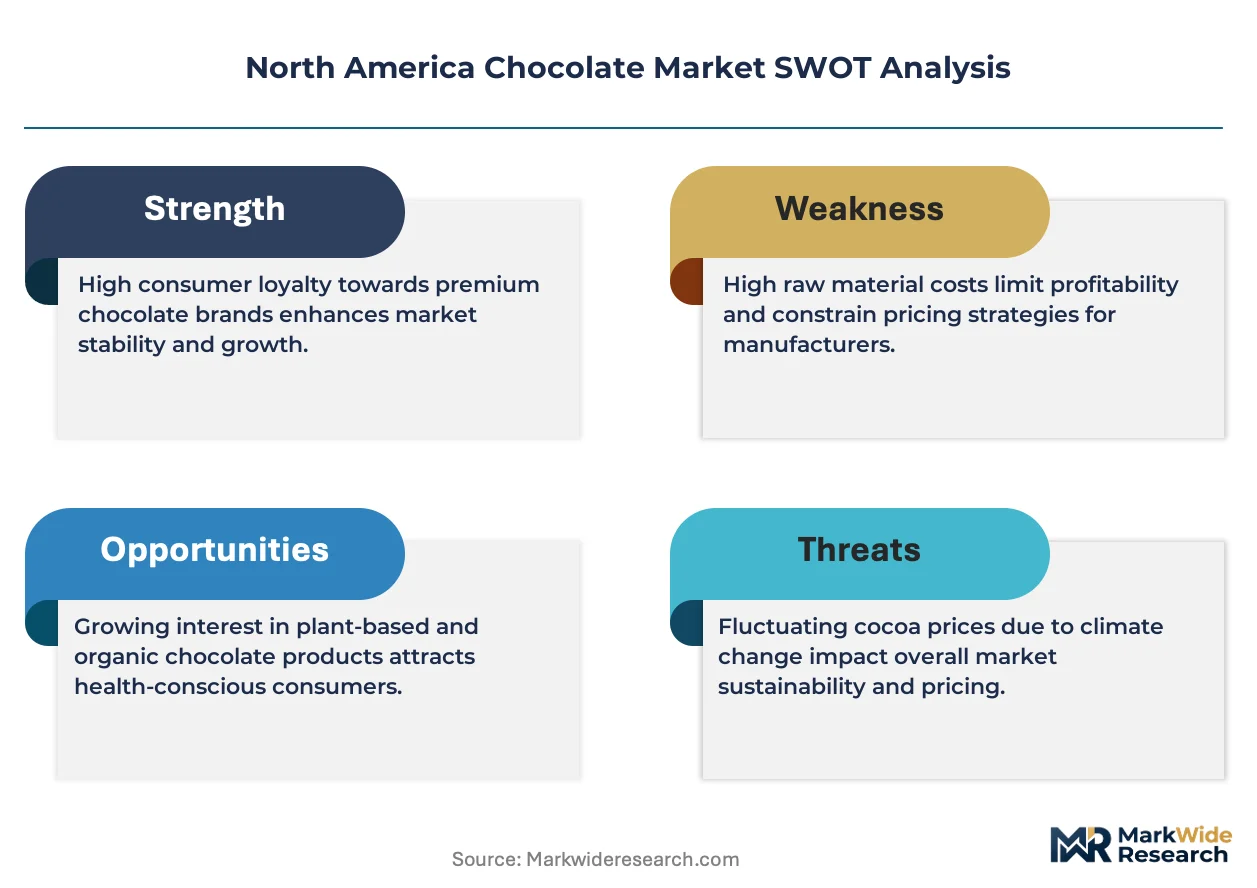
The divergence in capital investment between integrated bean-to-bar production and artisanal batch processing is redrawing competitive lines in the North America chocolate market. The Barry Callebaut Group leverages its extensive global sourcing and processing infrastructure to supply industrial clients. In contrast, The Hershey Company sustains its market position through massive brand recognition and distribution scale in the retail consumer space. Niche players like See's Candies differentiate through a focus on premium gifting and direct-to-consumer channels.
Chocolate is a food product derived from roasted and ground cacao seeds, typically processed through conching to refine its texture. Its composition of cocoa solids and cocoa butter determines its classification and flavor profile, serving primarily as a key ingredient in confectionery and as a standalone consumer treat. While milk chocolate continues to hold the largest volume share, dark chocolate products are gaining traction due to perceived health benefits. The retail consumers segment dominates sales, but the food service channel, including bakeries, offers higher-margin opportunities.
Market access in North America is governed by stringent food safety and labeling regulations enforced by the U.S. Food and Drug Administration (FDA) and Health Canada. These agencies' standards of identity for cacao products dictate composition requirements, impacting everything from ingredient sourcing to final product marketing. Future competitive advantage will depend on a company's ability to navigate evolving consumer demands for ethical sourcing transparency and supply chain traceability.
Market Dynamics
The central force in the North America chocolate market is the tension between industrial supply needs and consumer demands for ethical sourcing and transparency, amplified by stricter FDA regulations on product labeling.
Growth Catalysts
- Premium Product Demand:Heightened consumer interest in craft and single-origin chocolate stimulates growth in the artisanal segment, particularly in major metropolitan areas across the United States.
- Health and Wellness Trend:The perceived benefits of dark chocolate, rich in cocoa flavanols, are driving product innovation and marketing, aligning with consumer wellness priorities.
- Direct-to-Consumer Channels:The expansion of e-commerce and subscription models provides new market access for niche producers, bypassing traditional retail gatekeepers.
Market Restraints
- Input Cost Volatility:Price fluctuations for raw cacao, sourced mainly from West Africa, create significant margin pressure and planning uncertainty for manufacturers in North America.
- Stringent Regulatory Standards:The FDA's standards of identity for cacao products can limit formulation flexibility and slow the introduction of non-traditional chocolate-like confections.
- Supply Chain Concentration:Heavy reliance on a few agricultural regions for cocoa introduces considerable risk related to climate events, crop disease, and geopolitical instability.
Strategic Opportunities
- Functional Food Integration:Incorporating chocolate into functional foods like protein bars or probiotic-enhanced snacks opens new application segments beyond traditional confectionery.
- Plant-Based Formulations:Developing high-quality vegan milk chocolate using alternatives like oat milk caters to a growing demographic and commands a premium price point.
- Ethical Sourcing Certification:Leveraging certifications like Fair Trade as a key marketing differentiator can attract ethically-minded consumers and justify premium pricing.
Industry Challenges
- Supply Chain Traceability:Implementing and verifying robust traceability systems to substantiate ethical sourcing claims from farm to consumer remains a complex and costly operational hurdle.
- Skilled Labor Scarcity:Artisanal producers face a shortage of trained chocolatiers capable of managing bean-to-bar production and maintaining consistent quality control.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Chocolate Market |
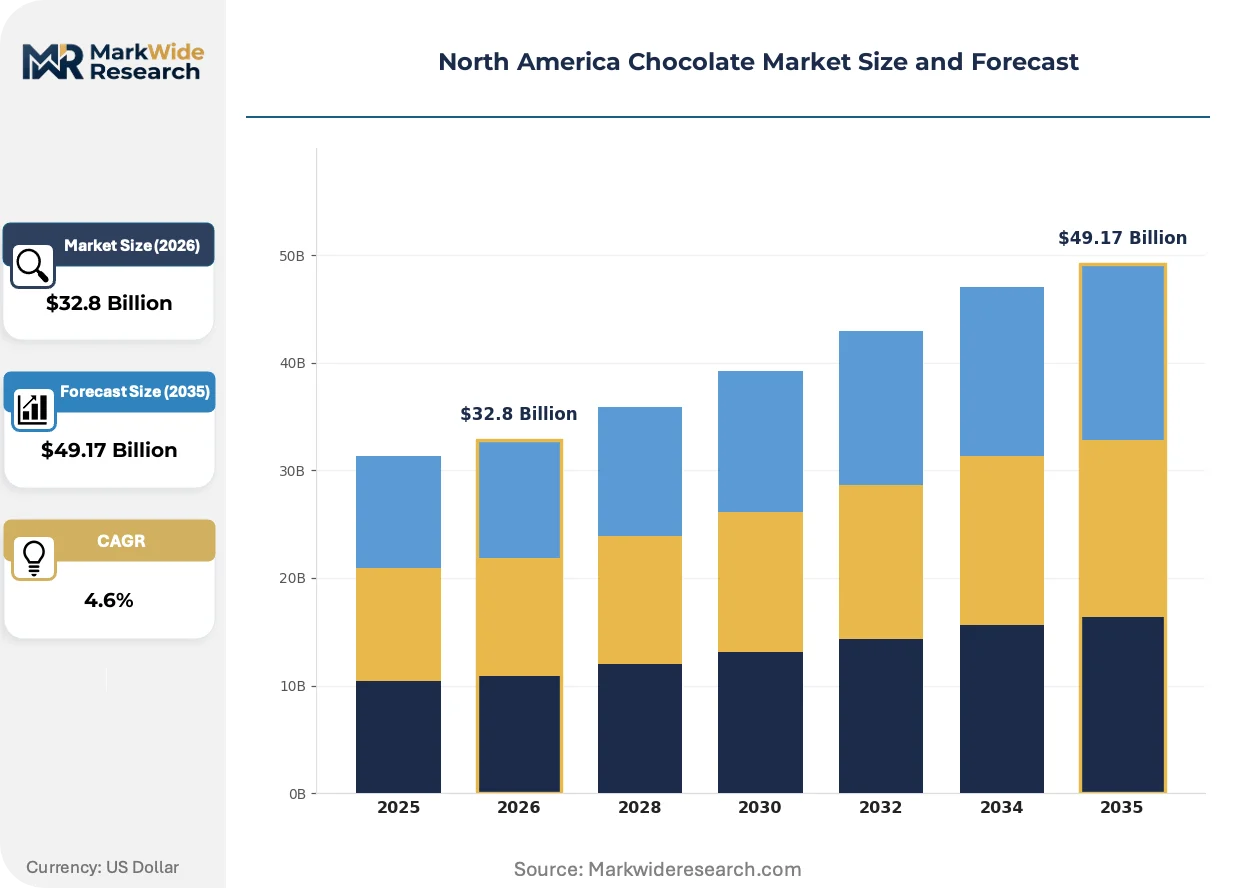
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $49.17 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dark Chocolate, Milk Chocolate, White Chocolate, Ruby Chocolate End User: Retail Consumers, Food Service, Confectionery Manufacturers, Bakeries Application: Gifting, Snacking, Baking, Food Processing Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Shops |
| Companies Covered | Nestle S.A., The Barry Callebaut Group, The Hershey Company, See's Candies, Lindt & Sprungli AG, Mars, Inc., Ferrero International S.A., Moonstruck Chocolate Company, Mondelez International, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Chocolate Market Strategic Shifts & Innovations
Evolving consumer health consciousness, enabled by digital transparency tools, is intersecting with new processing technologies. This convergence forces producers to innovate on formulation and supply chain storytelling to maintain relevance.
Small-scale, automated conching equipment allows for precise control over flavor development in small batches. Artisanal producers and high-end restaurants are rapidly adopting this machinery. This accessibility is fragmenting the premium segment, enabling a proliferation of local bean-to-bar makers that compete with established luxury brands.
New FDA guidance on declaring added sugars on the Nutrition Facts panel is compelling widespread product reformulation. This directly impacts mass-market milk chocolate composition. The confectionery manufacturers segment is most affected, investing in alternative sweeteners to meet regulatory requirements without sacrificing taste.
Consumer purchasing behavior is shifting from spontaneous buys to planned acquisitions based on ethical and quality attributes. This disrupts the dominance of checkout-aisle placements, with sales migrating toward specialty food grocers and direct-to-consumer online channels. The trend is most prominent in urban markets within the United States and Canada.
North America Chocolate Market Segmentation
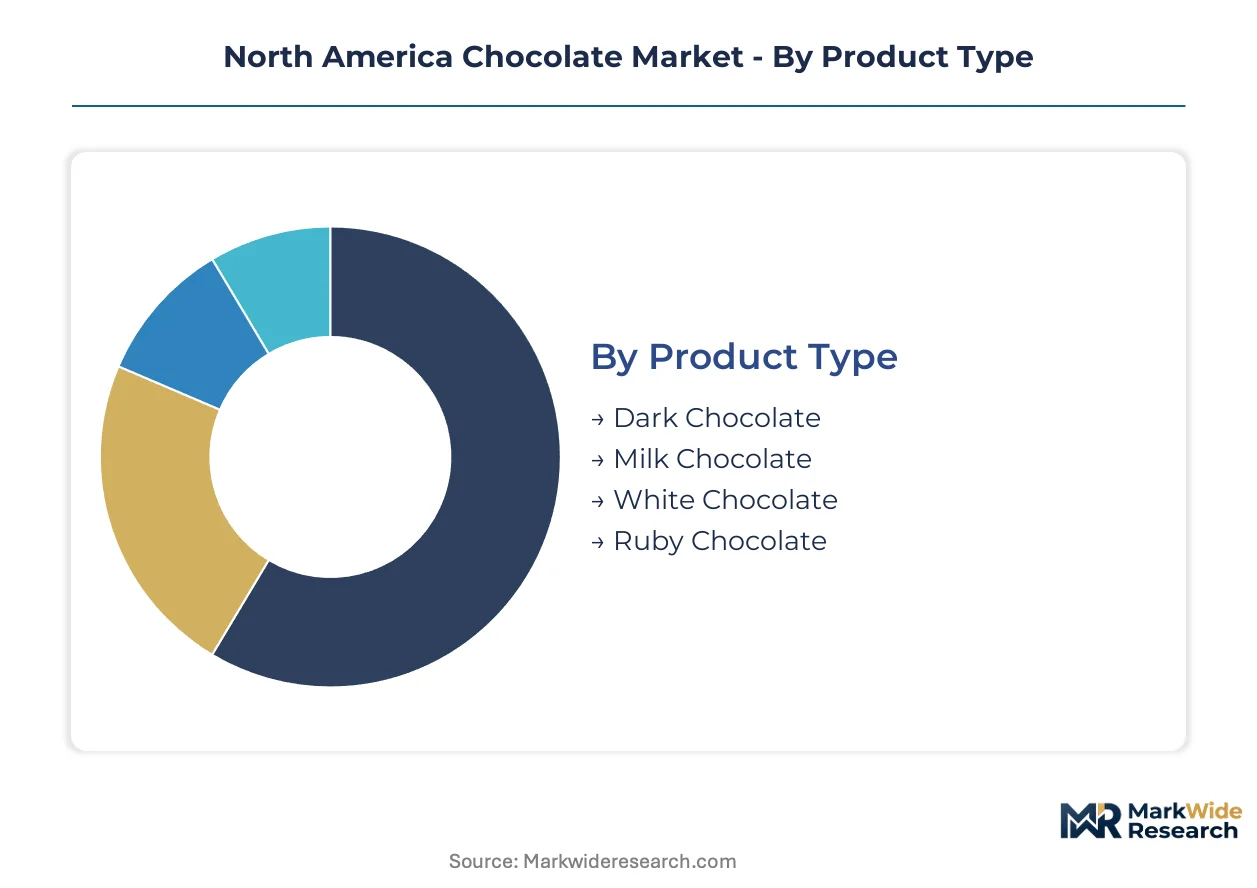
Segmentation in the North America chocolate market illuminates the diverse pathways for product delivery and consumption. Understanding these distinct segments helps manufacturers tailor offerings to specific consumer preferences and operational requirements. This analysis provides a structured view of the market's composition across key dimensions.
Product Type:
The North America chocolate market's product type segmentation influences how various formulations are distributed and consumed across different channels.
- Milk Chocolate:This classic confection contains a significant proportion of milk solids, cocoa solids, and sugar, resulting in a creamy texture. Demand concentrates heavily within the mass-market retail consumer segment across the United States, driven by widespread familiarity and comfort.
- Dark Chocolate:Characterized by a higher cocoa solids content and lower sugar, dark chocolate offers a more intense flavor profile and perceived health benefits. Consumer interest in wellness trends in Canada and the US drives its increasing presence in specialty food stores and online channels.
- White Chocolate:This confection is composed of cocoa butter, sugar, and milk solids, lacking cocoa solids. It finds application in confectionery manufacturing in the US and as a baking ingredient.
- Ruby Chocolate:This distinct chocolate variety possesses a natural pink hue and fruity flavor. It targets premium and novelty confectionery segments in urban centers.
Milk Chocolate dominates the installed product base in North America. Dark Chocolate is where expansion concentrates.
End User:
Volume concentration significantly shapes the North America chocolate market's end-user segmentation.
- Retail Consumers:This segment comprises individual purchasers buying chocolate for personal consumption or gifting through various channels. Demand is concentrated across all demographic groups in the United States, driven by everyday indulgence and seasonal purchases.
- Confectionery Manufacturers:These industrial clients purchase bulk chocolate as a primary ingredient for producing a wide array of candies, bars, and other sweet treats. Their demand is characterized by consistent, large-volume supply requirements, influencing procurement strategies across North America.
- Food Service:This segment includes restaurants and cafes using chocolate for desserts and specialty items. It offers higher-margin opportunities.
- Bakeries:Bakeries integrate chocolate into pastries and cakes, requiring various forms like chips or couverture. Local bakeries drive this demand.
Retail Consumers generate the highest revenue for chocolate producers. The Food Service channel offers the highest growth potential.
Application:
Consumer behavior patterns significantly differentiate the North America chocolate market's application segments.
- Snacking:This application involves immediate consumption of chocolate products, often in single-serve formats, for indulgence or quick energy. Everyday demand from consumers across the US and Canada sustains this segment, making it a volume cornerstone.
- Gifting:Chocolate products designated for gifting typically involve premium packaging, unique formulations, or artisanal quality. This application drives demand for specialty chocolates, particularly during holidays and celebrations in urban North American markets.
- Baking:Chocolate used as an ingredient by home bakers and commercial bakeries for cakes and cookies. Both retail and bulk formats serve this application.
- Food Processing:Chocolate as an ingredient in other manufactured food products like ice cream or cereals. Large food corporations primarily drive this industrial application.
Snacking remains the primary driver of chocolate volume. Gifting applications contribute significantly to value creation.
Distribution Channel:
Market access for chocolate products in North America is fundamentally shaped by the diverse distribution channel landscape.
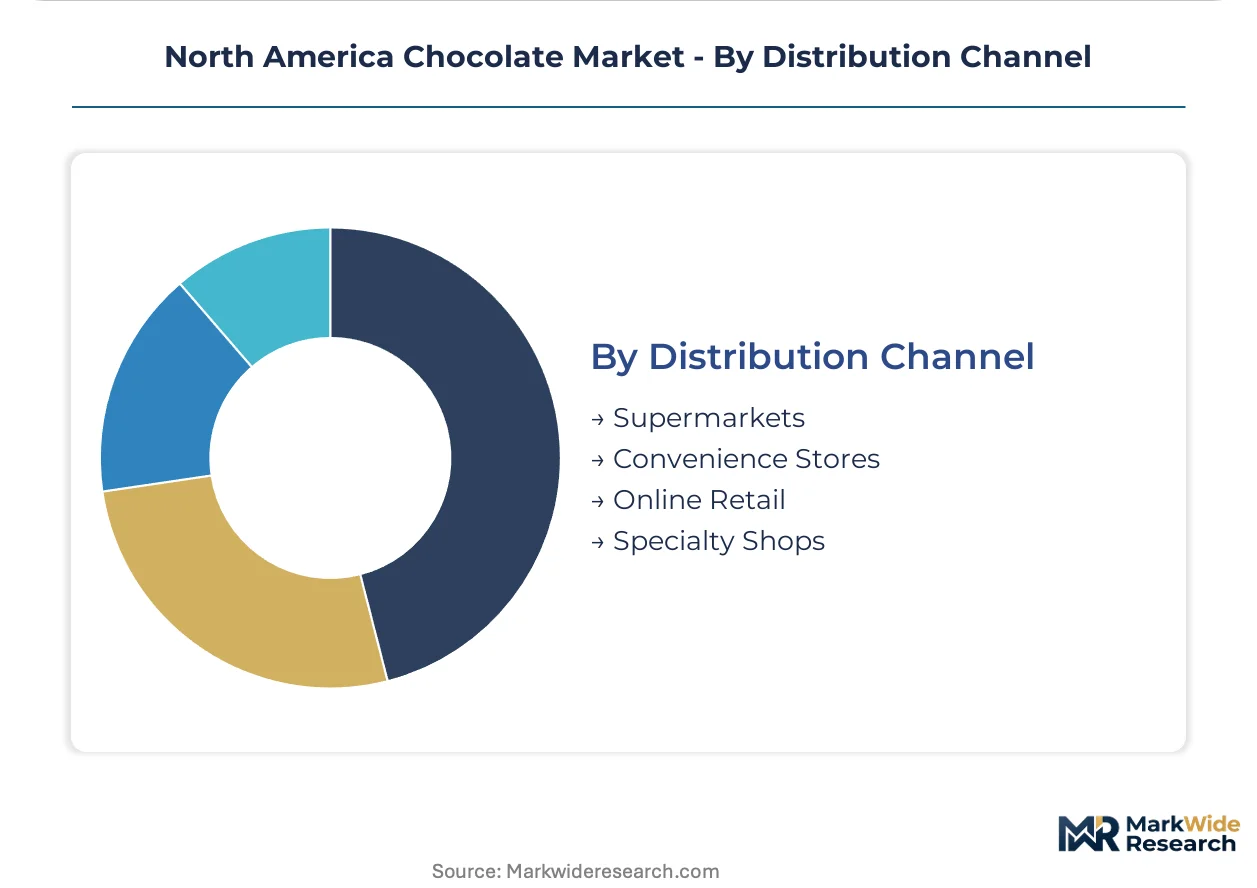
- Supermarkets:These large-format retail stores serve as the primary channel for mass-market chocolate sales, offering extensive product ranges and competitive pricing. High-volume consumer purchases across the United States and Canada define this channel's consistent demand.
- Online Retail:E-commerce platforms and direct-to-consumer websites facilitate chocolate sales, particularly for niche, premium, or subscription-based products. This channel provides new market access for smaller producers and caters to ethically-minded consumers in urban centers.
- Convenience Stores:These smaller retail outlets focus on impulse purchases, offering a limited selection of popular chocolate bars. Their widespread presence supports accessibility.
- Specialty Shops:Dedicated chocolate boutiques provide curated selections, often emphasizing premium or craft products. These shops cater to discerning consumers seeking unique experiences.
Supermarkets remain the dominant channel for chocolate sales. Online Retail represents a disruptive force in market access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States and Canada exhibit stronger consumer pricing power for premium chocolate products compared to Mexico, where affordability often drives volume. This disparity influences product development and distribution strategies across the North American market. Local manufacturers adapt pricing models to align with diverse economic conditions and consumer expectations within each nation.
United States
Demand for ethically sourced and premium dark chocolate is high in major metropolitan areas, influencing product innovation. The U.S. Food and Drug Administration (FDA) enforces strict labeling requirements for cocoa content and allergen declarations, impacting formulation. Consumer interest in craft and single-origin chocolates stimulates growth in the artisanal segment. California and New York City serve as hubs for artisanal chocolate production and specialty retail channels.
Canada
Heightened consumer preference for health-conscious options and sustainable products drives sales of organic and plant-based chocolates. Health Canada's food regulations dictate ingredient standards and nutritional claims for all chocolate products sold domestically. E-commerce channels provide new market access for niche producers across the country. Toronto's diverse food scene supports a growing number of bean-to-bar chocolatiers and premium confectionery shops.
Mexico
Traditional chocolate consumption, often in beverage form, coexists with a rising interest in international confectionery brands across various demographics. The Federal Commission for the Protection against Sanitary Risks (COFEPRIS) oversees food safety and quality standards for both chocolate imports and domestic production. Local producers often leverage indigenous cacao varieties to create unique flavor profiles. Mexico City's expanding middle class fuels demand for both mass-market and specialty chocolate products.
North America Chocolate Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the North America chocolate market. The market exhibits a tiered structure, with a few large integrated manufacturers alongside numerous specialized artisanal producers. Strategic archetypes include global confectionery giants, industrial ingredient suppliers, and premium direct-to-consumer brands. Capacity expansion and portfolio diversification represent dominant competitive moves among established players.
At the scale-driven end, The Hershey Company exemplifies a consumer-focused entity leveraging massive brand recognition and extensive retail distribution across North America. The Barry Callebaut Group, a global entity, represents a major industrial ingredient supplier, anchoring the market's bulk chocolate needs with its extensive processing infrastructure. Niche players like See's Candies occupy a position in the premium gifting segment, differentiating through direct-to-consumer channels and a focus on artisanal quality. These companies collectively illustrate the diverse strategies employed to capture market share across different segments, from mass-market to luxury.
| Leading Market Players |
|---|
| Nestle S.A. |
| The Barry Callebaut Group |
| The Hershey Company |
| See's Candies |
| Lindt & Sprungli AG |
| Mars, Inc. |
| Ferrero International S.A. |
| Moonstruck Chocolate Company |
| Mondelez International, Inc. |
| Others |
Cost & Logistics Intelligence
Alternative sweetener adoption reshapes cacao sourcing geography and pricing economics simultaneously, influencing formulation strategies across North America. This dynamic creates new value propositions for health-conscious consumers while introducing novel supply chain complexities for manufacturers.
Pricing Analysis
Customization-premium spreads drive pricing differentiation for chocolate products in North America. Value-based pricing applies to specialty and artisanal offerings, while contract-based long-term offtake agreements secure bulk supply for industrial clients. Price differentiation stems from cocoa quality grade, ethical sourcing certification, and volume scale. Pricing pressure on mass-market milk chocolate intensifies due to FDA added sugar guidance. Confectionery manufacturers exhibit the highest price sensitivity for bulk ingredients, whereas retail consumers show lower sensitivity for premium gifting chocolates.
Supply Chain Analysis
Port congestion and container availability influence inbound logistics costs for raw cacao, particularly from West African trade lanes. Geographic supply concentration for cacao beans centers heavily on Côte d'Ivoire and Ghana, with secondary sourcing from Ecuador. Raw cacao beans, sugar, and milk solids represent critical raw material dependencies for chocolate production. Commodity price volatility for cacao creates a significant structural risk for manufacturers. Distribution runs through a dual model, supplying industrial ingredients to confectionery manufacturers and consumer-packaged goods to retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America chocolate market presents a fragmentation opportunity, driven by heightened consumer demand for ethically sourced and premium products, creating diverse niches.
For Market Incumbents: Shield mass-market share by investing in robust supply chain traceability systems. Diversify cacao sourcing regions beyond West Africa to mitigate geopolitical and climate-related risks. Leverage extensive distribution networks to push reformulated products compliant with new FDA labeling requirements. Focus R&D on plant-based milk chocolate alternatives to counter emerging niche players.
For New Entrants and Emerging Players: Fair Trade certification fast-tracks market entry by appealing to ethically-minded consumers. Target underpenetrated urban markets in Canada and the United States with single-origin dark chocolate products. Focus on direct-to-consumer online channels for unique flavor profiles and brand storytelling. Develop functional chocolate lines, such as protein-enriched bars, to capture wellness trends.
For Investors and Strategic Acquirers: New FDA guidance on nutritional labeling reshapes the acquisition landscape, favoring companies with adaptable formulations. Evaluate targets with strong intellectual property in plant-based chocolate alternatives or established ethical sourcing platforms for long-term viability. Look for niche bean-to-bar producers demonstrating consistent quality and strong brand loyalty. Increased M&A activity in certified organic or functional chocolate brands signals market inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Supply Chain Diversification | Reduces reliance on single cacao regions, mitigating geopolitical and climate risks. |
| Plant-Based Product Development | Captures growing vegan consumer segments, expanding overall market reach. |
| Direct-to-Consumer Channel Expansion | Bypasses traditional retail gatekeepers, enabling premium brand storytelling. |
| Ethical Sourcing Certification Investment | Builds consumer trust and justifies premium pricing for specialty products. |
| Automated Conching Technology Adoption | Enhances flavor control for small batches, supporting artisanal quality and consistency. |
Research Approach
Cross-validation between primary interviews and secondary data sources anchors the qualitative findings of this analysis. Industry stakeholders interviewed included confectionery R&D directors, retail category managers, cacao farmers' cooperative representatives, and regulatory officials from FDA and Health Canada. Secondary data sources comprised USDA agricultural reports, industry association publications, company financial filings, and trade journals. This approach facilitated bottom-up and top-down triangulation for market sizing.
Sensitivity analysis frames the quantitative modeling approach, integrating historical trends and projected market dynamics over the projection horizon. The analytical framework modeled segmentation dimensions including product type, end-user, application, distribution channel, and cocoa origin. Compound annual growth rates were derived from a synthesis of historical performance and anticipated market shifts. Key industry-specific forecast inputs included global cacao commodity prices and consumer spending patterns on discretionary food items.
Underlying assumptions cover macroeconomic stability and regulatory consistency, with deviation risk concentrated in extreme climate events affecting cacao crops. Geopolitical instability in major cacao-producing regions also poses a significant risk to supply chain continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Truffle Chocolate Market
Confectionery
Asia-Pacific Cocoa Products Market
Confectionery
Vegan Candies Market
Confectionery
Sugar Free Candy Market
Confectionery
North America Confectionery Market
Confectionery
Premium Chocolate Market
Confectionery
Asia-Pacific Confectionery Market
Confectionery
Middle East and Africa Chocolate Market
Confectionery
Low Calorie Nutella Market
Confectionery
Low Calorie Sweets Market
Confectionery
Cocoa and Chocolate Market
Confectionery
Pralines Market
Confectionery
Bangladesh Candy Market
Confectionery
Confectionery Fats Market
Confectionery
Asia-Pacific Compound Chocolate Market
Confectionery
Middle East Chocolate Market