
 Pralines Market | 2026-2036
Pralines Market Size, Share, and Industry Trends Forecast 2026-2036
Pralines Market Analytics
Buyer concentration among luxury hotel chains and corporate procurement departments is decoupling from traditional retail dependence as B2B gift programs expand. Godiva leverages its direct-to-corporate channel infrastructure across North American and Asian business districts. Ferrero Group anchors its praline portfolio through scale manufacturing and hazelnut supply control. Neuhaus differentiates through heritage Belgian craftsmanship and certified couverture sourcing.
Pralines are shell-molded confections comprising a hard chocolate exterior encasing soft centers of ganache, nut paste, or fruit-based fillings, typically requiring tempering between 31°C and 32°C for proper crystallization and snap. The primary commercial purpose spans premium gifting, seasonal retail, and hospitality amenity programs where perceived craftsmanship commands price elasticity. Chocolate pralines occupy the dominant margin pool due to cocoa butter costs and consumer willingness to pay for origin-designated cacao, while nut prralines sustain volume leadership through hazelnut and almond accessibility across European and Middle Eastern markets. Specialty stores and online retailers are capturing share from grocery channels as experiential purchasing and subscription gifting reshape distribution economics.
EFSA allergen labeling requirements and EU REACH standards on food contact substances govern ingredient disclosure and packaging material compliance across European production. FDA food facility registration and FSMA preventive controls apply to pralines manufactured or distributed in the United States, with particular scrutiny on nut cross-contamination protocols. Stakeholders must monitor evolving sugar taxation frameworks and deforestation-free cocoa sourcing mandates to anticipate reformulation costs and supply chain certification burdens.
Market Dynamics
Corporate gifting programs are redirecting praline demand from retail shelves toward direct B2B procurement channels, compressing distributor margins while elevating volume commitments from luxury hospitality and financial services buyers.
Growth Catalysts
- EFSA Allergen Labeling Mandates:Strict disclosure requirements are accelerating clean-label reformulation investments, differentiating premium Belgian and Swiss producers from mass-market competitors.
- Hotel Chain Amenity Programs:Luxury hospitality groups in Dubai, Singapore, and Paris are standardizing craft praline turndown services, creating recurring institutional demand.
- Bean-to-Bar Traceability Technology:Blockchain-enabled cacao sourcing is unifying origin verification with consumer-facing storytelling, commanding price premiums in Japanese and Scandinavian markets.
Market Restraints
- Cocoa Butter Price Volatility:Weather-driven supply fluctuations in Côte d'Ivoire and Ghana are compressing margin buffers for couverture-dependent producers.
- Hazelnut Supply Concentration:Turkish and Italian orchards dominate global output, exposing Ferrero-scale manufacturers to single-region climate risk.
- EU REACH Compliance Burden:Food contact material testing and documentation requirements are extending new product development timelines by 8-14 months.
Strategic Opportunities
- Saudi Corporate Gifting Culture:Eid and Ramadan business gift customs in Riyadh and Jeddah remain underpenetrated by European heritage brands.
- Subscription Gifting Platforms:Monthly curated praline deliveries are displacing one-time retail purchases among affluent urban professionals.
- EU Deforestation-Free Cocoa Mandate:Early certification adopters will secure preferential supply relationships as due diligence requirements tighten.
Industry Challenges
- Master Chocolatier Talent Scarcity:Traditional tempering and ganache formulation expertise is concentrating among aging Belgian and Swiss craftspeople.
- Legacy Equipment Retrofit Costs:Enrobing and shell-molding lines require substantial capital outlay to meet modern hygiene and energy standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pralines Market |
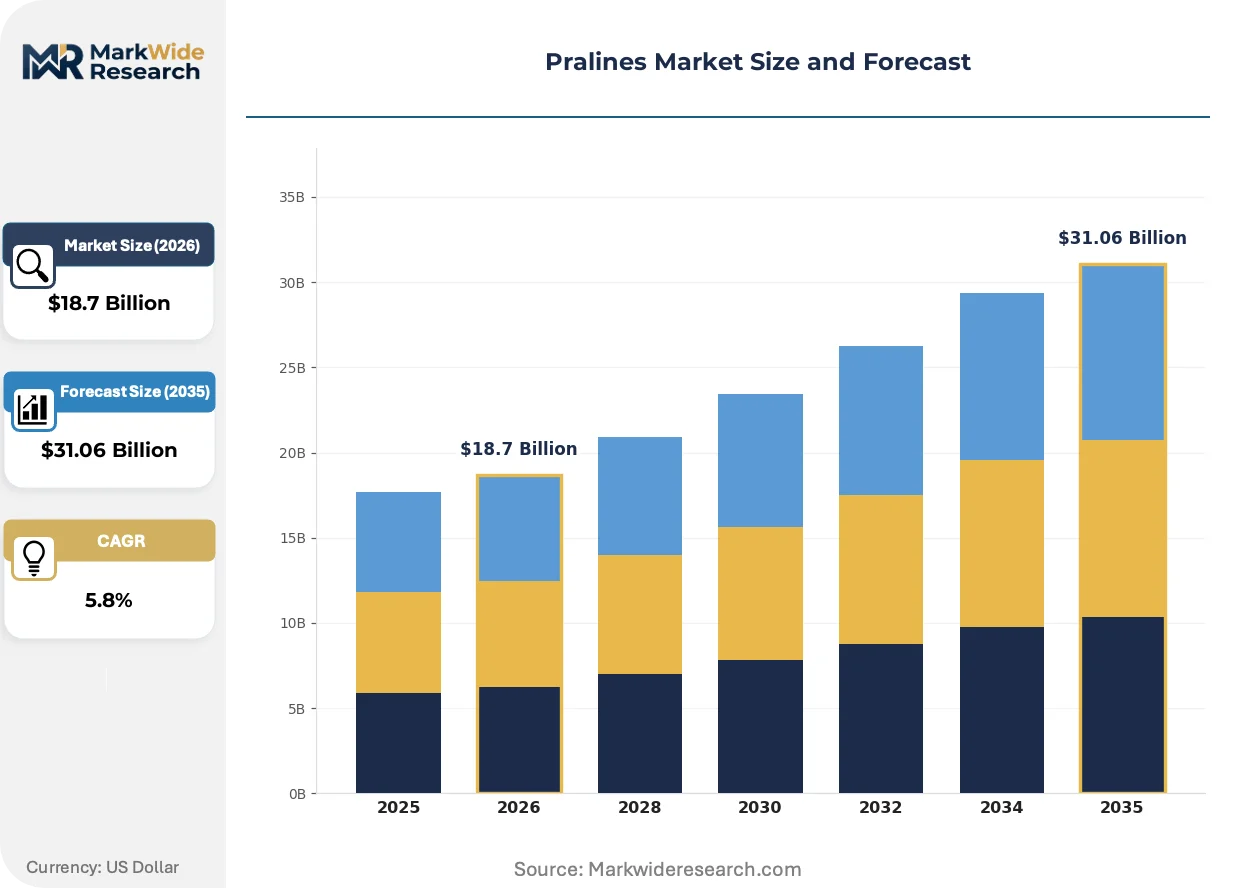
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chocolate Pralines, Nut Pralines, Fruity Pralines, Creamy Pralines Packaging Type: Boxes, Bags, Tins, Bulk Distribution Channel: Online Retailers, Specialty Stores, Grocery Stores, Cafés Customer Type: Individuals, Corporates, Gift Buyers, Event Planners |
| Companies Covered | Nestlé SA, Chocoladenfabriken Lindt & Sprungli AG, Mondelez International, Godiva, Neuhaus, Mars Inc., Hershey Co., Guylian Chocolates, Ferrero Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pralines Market Evolving Landscape
Precision fermentation and alternative fat technologies are disrupting century-old praline formulation conventions, while regulatory pressure on sugar content and packaging waste forces simultaneous reformulation across multiple vectors.
Precision fermentation-derived cocoa butter equivalents are unifying mouthfeel consistency with supply security for mid-tier manufacturers. Hotel and airline catering divisions are piloting these alternatives to hedge against origin cacao volatility. The technology is compressing the traditional premium-mass quality gradient by democratizing tempering tolerance.
EU Packaging and Packaging Waste Regulation is mandating recyclability targets and extended producer responsibility fees by 2030. Praline producers face reformulation of laminated foil wraps and plastic trays into fiber-based or mono-material alternatives. Belgian exporters are most exposed given their reliance on gift-oriented secondary packaging.
Corporate procurement departments are consolidating chocolate gifting spend under centralized sustainability criteria. Specialty distributors with direct-trade certification portfolios are displacing traditional wholesale importers in London, Frankfurt, and New York. Financial services and technology verticals are driving this consolidation fastest.
Pralines Market Segmentation
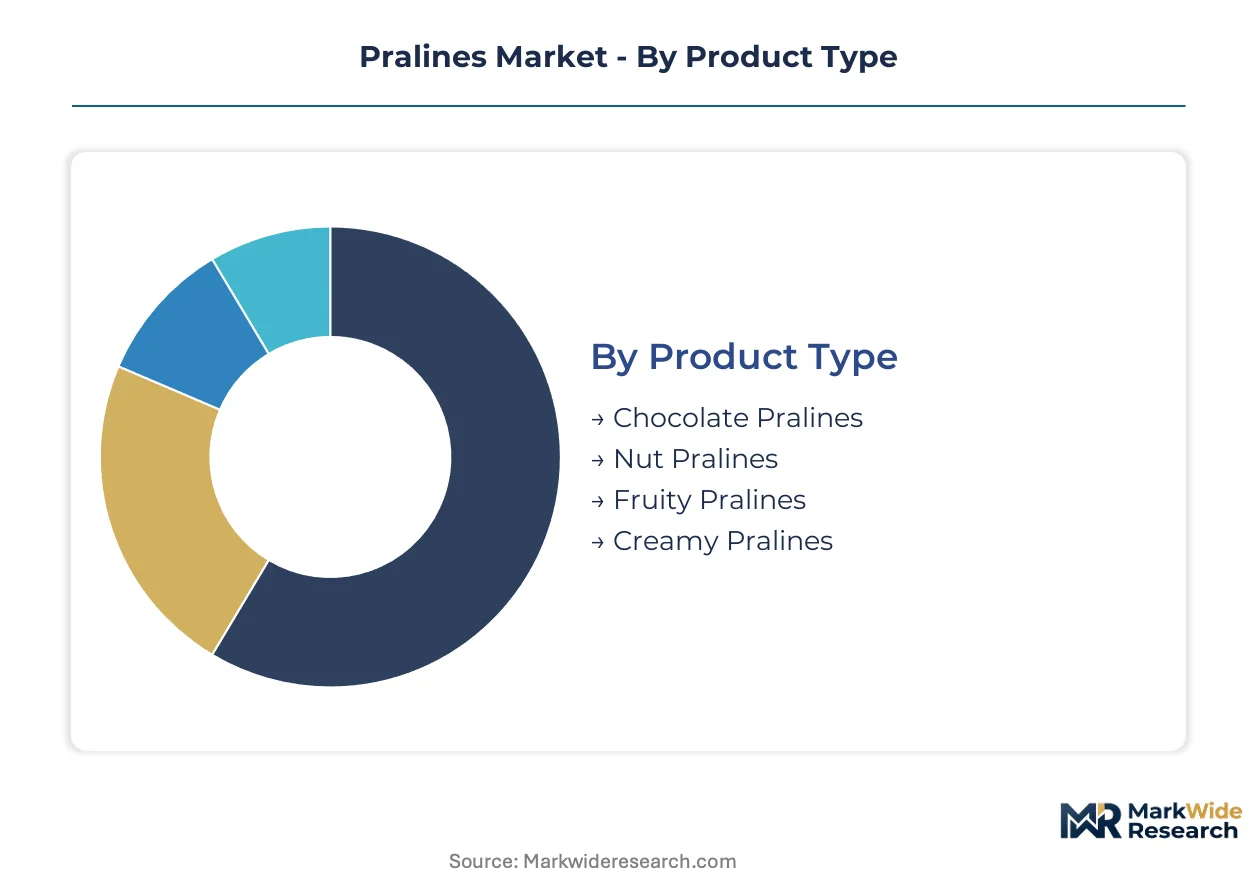
Praline manufacturers configure production assets around crystallization chemistry and filling viscosity rather than generic confectionery lines. Segmentation reveals where capital deployment locks in margin structure and which buyer channels reward origin certification.
Product Type:
Chocolate pralines demand the heaviest upfront investment in tempering tunnels and couverture climate control, while nut-based variants require integrated roasting and paste-milling infrastructure.
- Chocolate Pralines:Hard shell-molded exteriors encasing ganache or soft centers demand precise tempering between 31°C and 32°C for proper cocoa butter crystallization. Demand clusters in Belgian and Swiss craft ateliers where origin-designated cacao commands price premiums from Japanese and Scandinavian buyers.
- Nut Pralines:Hazelnut and almond paste fillings sustain volume leadership across European and Middle Eastern markets through accessible commodity inputs. Ferrero-scale manufacturers anchor supply through Turkish and Italian orchard relationships, exposing production to single-region climate volatility.
- Fruity Pralines:Fruit-based centers require pH-balanced formulations and moisture barriers to prevent shell degradation.
- Creamy Pralines:Dairy-forward fillings necessitate shorter shelf-life logistics and cold-chain distribution partnerships.
Most installed capacity flows through nut pralines. Expansion is steepest in chocolate pralines.
Packaging Type:
Secondary packaging economics separate gift-oriented exporters from commodity producers, with laminated foil and rigid formats carrying divergent compliance burdens under EU waste regulations.
- Boxes:Rigid gift boxes dominate premium corporate gifting and hospitality amenity programs. Belgian exporters face acute exposure to EU Packaging and Packaging Waste Regulation mandates for fiber-based or mono-material alternatives by 2030.
- Tins:Metal containers sustain heirloom positioning in Swiss and German retail, though extended producer responsibility fees are compressing margin structures for mid-tier brands.
- Bags:Flexible pouches serve impulse retail and travel channel distribution.
- Bulk:Unpackaged formats supply foodservice and in-house hotel confectionery programs.
Revenue concentrates in box formats. Bags are climbing the fastest as subscription gifting platforms displace one-time retail purchases.
Distribution Channel:
Channel selection determines whether producers capture origin storytelling premiums or compete on shelf-turn velocity, with direct-to-corporate infrastructure now outperforming traditional wholesale margins.
- Specialty Stores:Experiential purchasing environments in Brussels, Zurich, and Paris anchor craft praline discovery and trial. Blockchain-enabled cacao sourcing unifies origin verification with consumer-facing storytelling in these channels.
- Online Retailers:Subscription gifting platforms and curated monthly deliveries are displacing one-time retail purchases among affluent urban professionals in London, New York, and Tokyo.
- Grocery Stores:Mass retail channels favor scale manufacturers with automated enrobing lines and standardized shelf-life logistics.
- Cafés:Coffee shop partnerships create impulse occasions for single-serve praline purchases.
Specialty stores retain the highest margin pool. Online retailers are gaining share fastest as procurement shifts toward centralized sustainability criteria.
Customer Type:
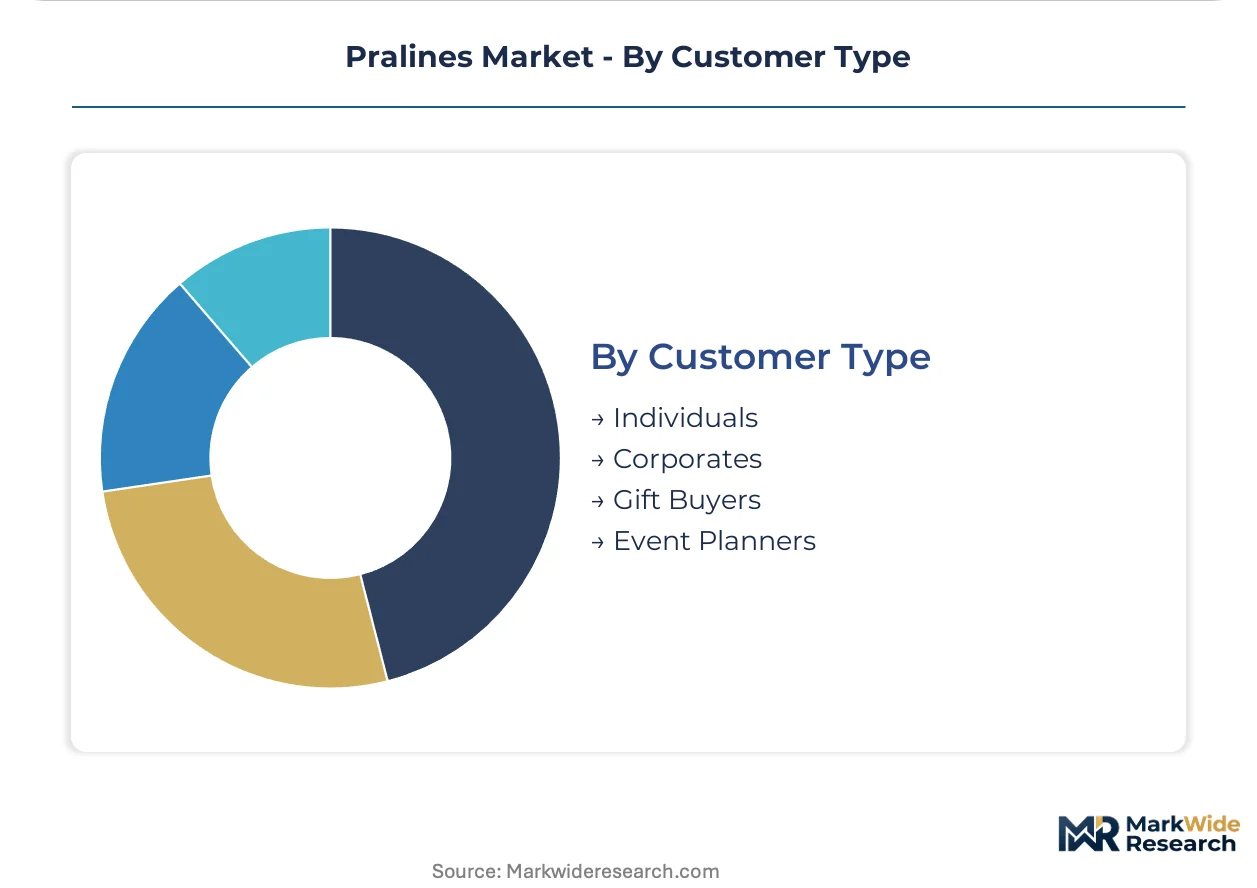
Buyer concentration patterns split between fragmented individual purchasing and consolidated corporate procurement with recurring volume commitments and certified sourcing requirements.
- Corporates:Luxury hotel chains and financial services procurement departments are consolidating chocolate gifting spend under direct B2B channels. Dubai, Singapore, and Paris hospitality groups standardize craft praline turndown services, creating recurring institutional demand.
- Gift Buyers:Seasonal and occasion-based purchasing concentrates in Eid and Ramadan customs across Riyadh and Jeddah, where European heritage brands remain underpenetrated.
- Individuals:Personal consumption favors accessible price points and convenience-oriented packaging formats.
- Event Planners:Wedding and corporate event coordination drives bulk customization and logo-imprinting services.
Corporate procurement commands the largest volume commitments. Gift buyers in Saudi Arabia represent the steepest expansion trajectory for heritage brand penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Belgium commands craft heritage premiums while the United States drives corporate gifting volume, creating divergent margin structures across Atlantic markets.
Belgium
Brussels and Bruges ateliers anchor European demand for origin-designated cacao pralines. EFSA allergen labeling mandates under Regulation 1169/2011 compel reformulation investments that differentiate heritage producers from mass-market entrants. The Flanders confectionery cluster concentrates bean-to-bar traceability expertise and certified couverture sourcing for Japanese export markets.
Switzerland
Zurich and Geneva luxury hospitality groups sustain recurring institutional demand for turndown amenity programs. Swissmedic food contact material standards align with EU REACH compliance burdens, extending new product development timelines. The Lake Geneva region hosts precision fermentation research partnerships targeting cocoa butter alternatives.
United States
Manhattan and Chicago financial services procurement departments consolidate chocolate gifting spend under direct B2B channels. FDA food facility registration and FSMA preventive controls enforce nut cross-contamination protocols. The Northeast corridor concentrates specialty distributor networks with direct-trade certification portfolios.
Saudi Arabia
Riyadh and Jeddah corporate gift customs during Eid and Ramadan remain underpenetrated by European heritage brands. SFDA food labeling requirements govern import compliance for nut-containing confections. The Western Region hospitality construction pipeline in Mecca and Medina creates emerging amenity program demand.
Japan
Tokyo and Osaka affluent consumers command price premiums for blockchain-enabled cacao provenance storytelling. METI consumer protection standards shape packaging material recyclability expectations. The Kanto region anchors subscription gifting platform headquarters displacing traditional retail import channels.
Pralines Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered price positioning. Consolidation concentrates among scale manufacturers controlling hazelnut supply chains and automated enrobing infrastructure. Three archetypes dominate: heritage Belgian ateliers leveraging craft credentials, mass-market conglomerates optimizing commodity input costs, and mid-tier regional chocolatiers pursuing geographic niche penetration. Capacity expansion and strategic partnerships represent the dominant competitive moves as producers secure deforestation-free cocoa certification ahead of regulatory deadlines.
Within the heritage craft tier, Neuhaus and Godiva exemplify Belgian positioning anchored in certified couverture sourcing and direct-to-corporate channel infrastructure. Ferrero Group occupies the scale-driven archetype through Turkish and Italian hazelnut supply control and automated manufacturing density. Among diversified conglomerates, Nestlé SA and Mondelez International represent volume leadership through global distribution networks and portfolio breadth across confectionery categories.
| Leading Market Players |
|---|
| Nestlé SA |
| Chocoladenfabriken Lindt & Sprungli AG |
| Mondelez International |
| Godiva |
| Neuhaus |
| Mars Inc. |
| Hershey Co. |
| Guylian Chocolates |
| Ferrero Group |
| Others |
Value Network & Pricing Analysis
Family-owned Belgian ateliers and Swiss heritage houses anchor supply discipline through generational control of couverture sourcing relationships, insulating premium pricing tiers from commodity volatility while forcing mid-tier producers into cost-competitive automation investments.
Pricing Analysis
Capacity additions in Turkey and Italy are reshaping price floors for hazelnut-dependent praline categories. Three-tier pricing structure across premium, standard, and economy levels separates origin-designated cacao ateliers from scale manufacturers and private-label entrants. Price differentiation hinges on bean-to-bar certification grade and volume scale. Cost compression in the mid-tier is intensifying because precision fermentation alternatives are democratizing tempering tolerance. Corporate procurement departments show least price sensitivity; individual convenience buyers show most.
Supply Chain Analysis
Regional distribution centers in Antwerp and Zurich anchor hub-and-spoke patterns for European craft exports. Cacao supply concentrates in Côte d'Ivoire, Ghana, and Ecuador; hazelnut sourcing draws from Turkey and Italy. Couverture climate control, roasting infrastructure, and tempering tunnel equipment constitute critical component dependencies. Single-source vulnerability in Turkish hazelnut orchards exposes Ferrero-scale manufacturers to climate-driven disruption. Distribution runs through specialty importers with direct-trade certification portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Corporate gifting procurement is consolidating spend under centralized sustainability criteria, elevating certified origin pralines over commodity alternatives.
For Market Incumbents: To counter precision fermentation disruption in cocoa butter equivalents, heritage Belgian and Swiss producers must deepen backward integration into certified cacao estates and secure deforestation-free supply relationships ahead of EU regulatory deadlines. Channel control through direct-to-corporate infrastructure offers the strongest defensive moat.
For New Entrants and Emerging Players: Saudi corporate gift buyers during Eid and Ramadan represent the most penetrable white-space target. Subscription gifting platforms in Tokyo and London offer secondary entry vectors. A bean-to-bar traceability narrative with blockchain-enabled provenance storytelling provides the sharpest go-to-market angle against established import channels.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier regional chocolatiers with underutilized tempering capacity and dormant corporate channel relationships. Long-term viability over a multi-year horizon favors targets with early deforestation-free certification and installed base in hospitality amenity programs. The signal to watch is accelerated consolidation of financial services procurement spend under sustainability criteria.
| Strategic Initiative | Industry Significance |
|---|---|
| Deforestation-Free Certification | Early adopters secure preferential cacao supply as EU due diligence tightens. |
| Direct-to-Corporate Channel Buildout | Bypasses wholesale margin compression from distributor consolidation in London and Frankfurt. |
| Precision Fermentation Partnership | Hedges cocoa butter price volatility through alternative fat technology licensing. |
| Subscription Platform Launch | Captures recurring revenue from affluent urban professionals displacing one-time retail. |
| Hospitality Amenity Program Expansion | Dubai and Singapore hotel chains standardize craft praline turndown services. |
Research Methodology
Coverage spans Belgium, Switzerland, the United States, Saudi Arabia, and Japan, with primary inputs from each market. The analysis combines interviews with master chocolatiers, corporate procurement managers at luxury hotel chains, specialty distributor principals, and regulatory affairs leads with secondary validation from EFSA guidance documents, FDA facility registration databases, customs trade records, and hospitality procurement databases. Bottom-up capacity assessments and top-down demand modeling provide triangulation.
Granularity-level modeling distinguishes crystallization chemistry requirements, filling viscosity categories, and packaging format compliance burdens across the projection horizon. Segmentation dimensions include product type, packaging format, distribution channel, and customer archetype. CAGRs derive from volume trajectory analysis against pricing elasticity assumptions. Forecast inputs incorporate cocoa butter futures patterns and hazelnut harvest yield variability.
Underlying measurement precision varies by segment; corporate procurement and specialty store channels carry tighter precision than fragmented individual purchasing. Forecasts reflect documented assumptions around regulatory implementation timelines and commodity supply stability. Cocoa price volatility, REACH compliance delays, and master chocolatier talent scarcity constitute primary revision risks. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Non-Chocolate Candy Market
Confectionery
North America Gummy Market
Confectionery
Sugar-Free Gummy Market
Confectionery
North America Compound Chocolate Market
Confectionery
Asia-Pacific Confectionery Market
Confectionery
Sugar Free Candy Market
Confectionery
Brazil Chocolate Market
Confectionery
Green Tea Chocolate Market
Confectionery
Bean-To-Bar Chocolate Market
Confectionery
Sugar Free Mints Market
Confectionery
Caramel Market
Confectionery
Europe Premium Chocolate Market
Confectionery
Asia-Pacific Cocoa Products Market
Confectionery
Chocolate Confectionery Market
Confectionery
Chocolate Hazelnut Spread Market
Confectionery
Canada Chocolate Market