
 Gum Base Candy Market | 2026-2036
Gum Base Candy Market Size, Share, and Industry Trends Forecast 2026-2036
Gum Base Candy Market Insights
The capital-intensity divergence between integrated gum base producers and brand-focused confectioners is rotating competitive advantage toward upstream control. Mars Wrigley Confectionery leverages its proprietary gum base supply chain to sustain margin stability across volatile resin markets. Perfetti Van Melle anchors European production through scale-efficient manufacturing hubs in Italy and the Netherlands. Mondelēz International competes via diversified confectionery portfolios that offset seasonal gum demand fluctuations.
Gum base candy comprises chewable confectionery products formulated around an insoluble elastomer matrix—typically polyisobutylene, polyvinyl acetate, or natural chicle resins—that delivers pliability, flavor retention, and controlled release over 10-30 minutes of mastication. The primary commercial purpose centers on oral refreshment, breath enhancement, and increasingly on functional delivery of vitamins, caffeine, or nicotine alternatives. Chewing gum and functional gum categories concentrate the highest margin pools as health-positioned products command price premiums over commodity bubble gum. Sugar-free ingredients within the ingredient dimension are expanding fastest, driven by reformulation investments responding to dental health claims and clean-label preferences across North American and European retail.
The FDA governs food additive safety and GRAS status for synthetic gum bases in the United States, while EFSA evaluates novel ingredient petitions and health claim substantiation across European markets. BIS standards in India and GB standards in China add compliance layers for entrants targeting Asia-Pacific volume opportunities. Stakeholders must monitor evolving plastic-free and biodegradable gum base mandates in the EU and California, as regulatory pressure on synthetic polymer content threatens incumbent formulation architectures and rewards early movers in natural resin alternatives.
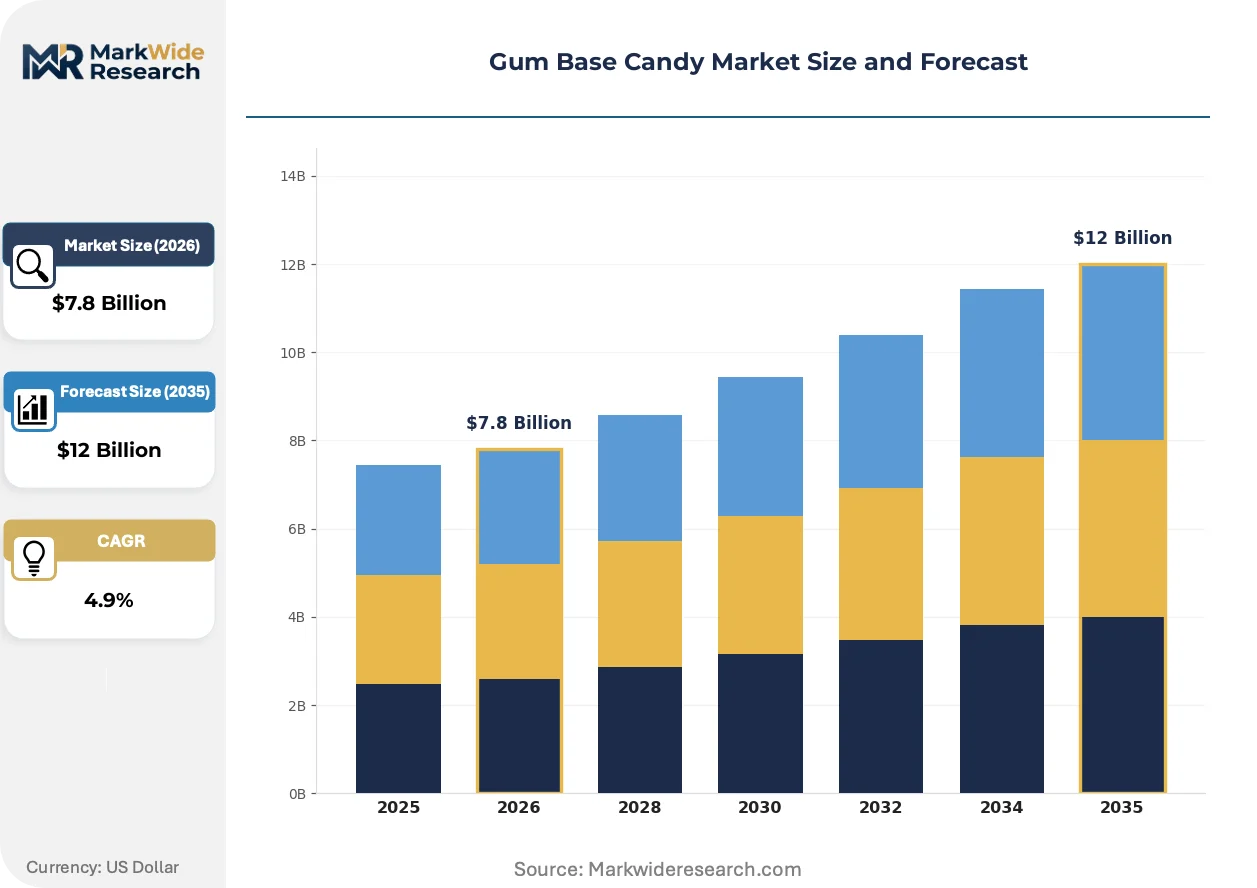
Market Dynamics
Biodegradable gum base mandates from the EU and California are forcing wholesale reformulation of synthetic polymer architectures, concentrating competitive advantage among producers with captive natural resin supply chains.
Growth Catalysts
- Functional Delivery Systems:Caffeine, vitamin, and nicotine alternative formulations are expanding addressable demand beyond traditional breath-freshening use cases into wellness and cessation adjacencies.
- FDA GRAS Pathway:Streamlined food additive safety approvals for novel natural resins are accelerating time-to-market for clean-label gum base alternatives in United States retail channels.
- Impulse Channel Expansion:Convenience store operators are dedicating incremental shelf space to sugar-free and functional varieties, concentrating volume growth in high-margin checkout-positioned SKUs.
Market Restraints
- Petrochemical Input Volatility:Polyisobutylene and polyvinyl acetate prices track crude oil derivatives, compressing margins for synthetic-dependent formulators during energy price spikes.
- Natural Resin Supply Concentration:Chicle and jelutong harvests concentrate in Central American and Southeast Asian cooperatives, creating geographic single-point-of-failure exposure for biodegradable transitions.
- EFSA Health Claim Substantiation:Novel functional ingredient petitions face 18-24 month evaluation timelines, delaying premium positioning for vitamin-fortified and dental-benefit products.
Strategic Opportunities
- India PLI Scheme:Production-linked incentives for food processing infrastructure are attracting contract manufacturing investment for export-oriented gum base candy production.
- Direct-to-Consumer Subscription:Functional gum brands are bypassing traditional retail slotting fees through personalized delivery models targeting nicotine cessation and nootropic user cohorts.
- EU Single-Use Plastics Directive:Biodegradable mandates are creating first-mover advantage windows for natural resin suppliers with certified compostable formulation capabilities.
Industry Challenges
- Polymer Chemistry Talent Scarcity:Formulation expertise bridging elastomer science and food-grade safety compliance concentrates among retiring cohorts at legacy suppliers.
- Legacy Equipment Retooling:Synthetic-to-natural resin transitions require extruder and cooling tunnel modifications that strain capex budgets for mid-scale confectioners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gum Base Candy Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12 Billion |
| CAGR (2026 – 2036) | 4.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chewing Gum, Bubble Gum, Mints, Functional Gum Ingredient: Natural Gum, Synthetic Gum, Sugar-Free Ingredients, Flavor Enhancers Packaging Type: Bulk Packaging, Retail Packs, Sugar-Free Packs, Functional Packs Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Specialty Stores |
| Companies Covered | Mars Wrigley Confectionery, Perfetti Van Melle, Mondelēz International, Lotte Confectionery, The Hershey Company, Grupo Arcor, Cloetta, Cafosa, Gumlink Confectionery Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gum Base Candy Market Trends and Innovations
Formulation science is pivoting toward bio-based elastomers as regulatory pressure on petroleum-derived polymers intensifies, while delivery mechanisms evolve to support precision dosing of active ingredients.
Plant-derived chicle and jelutong resins are displacing polyisobutylene in premium and environmentally-positioned product lines. European and North American brand owners are accelerating adoption to preempt compliance deadlines. This displacement is compressing demand for synthetic gum base imports while rewarding vertically integrated harvest-to-package operators with price premiums.
REACH restrictions on microplastic shedding are extending to chewing gum disposal classifications across EU member states. Industrial consequence includes mandatory biodegradability certification for products sold in France, Italy, and Germany. Sugar-free functional varieties face the tightest compliance timelines, driving accelerated partnerships between confectioners and natural resin cooperatives.
Buyer procurement is consolidating toward single-source biodegradable formulation partnerships that bundle resin supply with co-manufacturing services. Traditional ingredient distributor intermediaries are losing share to direct relationships in North American premium segments. This consolidation is most visible in United States functional gum startups seeking supply chain transparency for ESG reporting requirements.
Gum Base Candy Market Segmentation
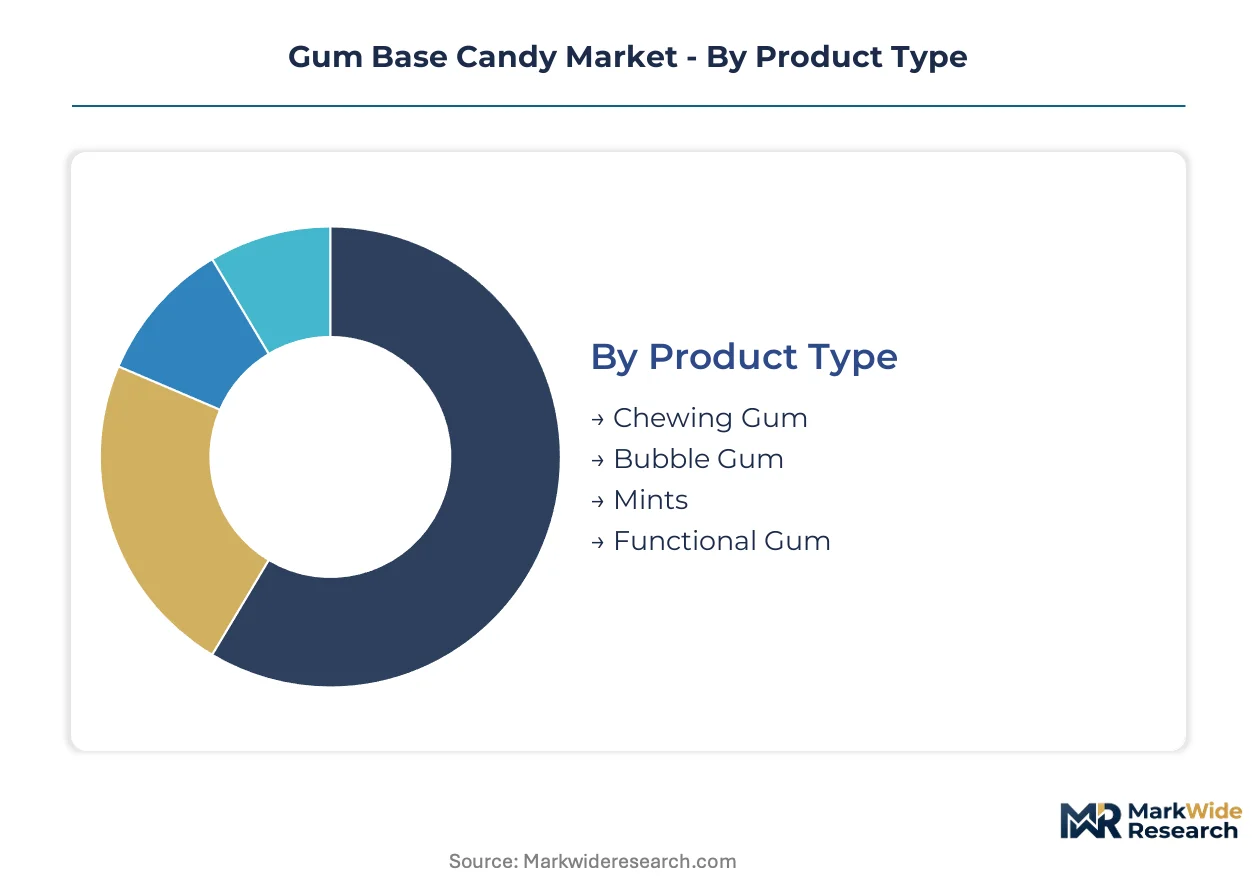
Segmentation in the gum base candy market reveals how formulation chemistry, packaging economics, and channel access combine to determine margin capture. Regulatory pressure on synthetic polymers and sugar content is fragmenting historical category boundaries, creating new competitive arenas defined by biodegradability certifications and functional ingredient approvals.
Product Type:
FDA GRAS determinations and EFSA novel food evaluations create divergent compliance burdens across product categories, with functional and sugar-free lines facing extended substantiation timelines that reshape launch sequencing.
- Chewing Gum:Formulated around polyisobutylene or polyvinyl acetate elastomer matrices delivering 10-30 minute mastication profiles. United States convenience store checkout lanes concentrate volume for traditional mint and fruit varieties, though biodegradable reformulation mandates in California and the EU are elevating natural resin input costs.
- Functional Gum:Precision-dosed delivery systems incorporating caffeine, vitamins, nicotine alternatives, or dental-active compounds. United States direct-to-consumer subscription models are capturing cessation and nootropic user cohorts, bypassing traditional retail slotting fees while EFSA health claim substantiation delays European premium positioning.
- Bubble Gum:Lower molecular weight elastomer formulations optimized for elastic recovery and large bubble formation. Children's confectionery segments in emerging markets sustain commodity-grade demand.
- Mints:Compressed tablet or panned candy formats without elastomer matrices, competing at price points below functional gum while sharing breath-freshening positioning.
Chewing gum handles the majority of throughput; functional gum is the fastest mover on share.
Ingredient:
Cost tier differentiation separates premium natural resin formulations from commodity synthetic bases, with supply chain control over chicle and jelutong harvests becoming the decisive margin variable.
- Sugar-Free Ingredients:Polyol sweetener systems—xylitol, sorbitol, maltitol—formulated to support dental health claims and clean-label positioning. United States retail channels are expanding shelf space allocation as FDA GRAS status for novel polyol blends streamlines reformulation pathways.
- Natural Gum:Chicle from Central American cooperatives and jelutong from Southeast Asian harvests, requiring biodegradability certification under EU Single-Use Plastics Directive and California mandates. Vertically integrated harvest-to-package operators command price premiums as synthetic polymer demand compresses.
- Synthetic Gum:Petroleum-derived polyisobutylene and polyvinyl acetate elastomers facing regulatory displacement pressure. Margin volatility tracks crude oil derivative pricing.
- Flavor Enhancers:Encapsulation technologies for controlled release, including spray-dried and coacervation systems.
Natural gum absorbs the steepest expansion trajectory; synthetic gum retains volume leadership in price-sensitive segments.
Packaging Type:
Application-driven packaging economics separate impulse-consumption formats from subscription and bulk procurement channels, with unit economics dictating margin recovery.
- Retail Packs:Single-serve blister and stick formats optimized for convenience store checkout positioning and vending machine compatibility. Impulse channel expansion in the United States is concentrating volume growth here.
- Functional Packs:Child-resistant and precision-dose packaging for caffeine, nicotine alternative, and vitamin delivery systems. Direct-to-consumer subscription models in wellness cohorts favor this format.
- Bulk Packaging:Multi-unit formats for foodservice, hospitality, and institutional procurement. Price compression limits margin recovery.
- Sugar-Free Packs:Segregated packaging lines preventing cross-contamination, supporting dental health claim substantiation.
Retail packs dominate transaction velocity; functional packs are climbing the fastest.
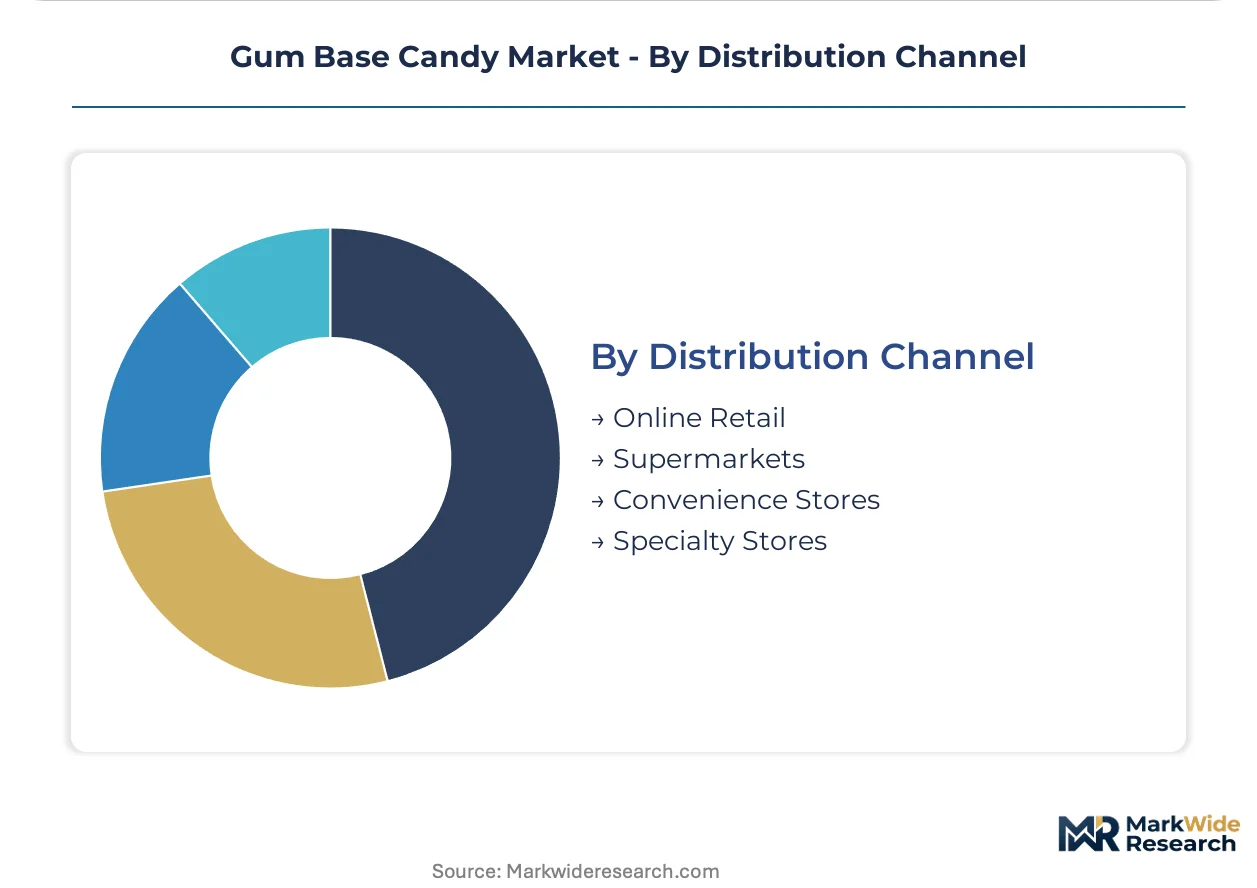
Distribution Channel:
Customer type concentration determines channel strategy, with convenience store impulse purchasing separating mass-market penetration from premium functional positioning.
- Convenience Stores:Checkout lane and front-counter positioning capturing unplanned purchases. United States operators are dedicating incremental shelf space to sugar-free and functional varieties, concentrating high-margin SKU placement.
- Online Retail:Subscription and replenishment models for functional gum brands, with personalized delivery targeting nicotine cessation and nootropic user cohorts. ESG reporting requirements are driving procurement consolidation toward transparent supply chains.
- Supermarkets:Planned purchase occasions with broader assortment but lower per-unit margins than impulse channels.
- Specialty Stores:Premium and import positioning, limited volume contribution.
Convenience stores anchor volume throughput; online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium functional gum lines in the United States command price premiums that outstrip commodity bubble gum margins in Brazil by significant multiples, creating a pricing-power asymmetry that rewards formulation innovation in wealthy consumer markets.
United States
FDA GRAS pathway streamlining accelerates clean-label gum base alternatives into retail channels, while convenience store operators dedicate incremental checkout space to sugar-free and functional varieties. Direct-to-consumer subscription models for nicotine cessation and nootropic user cohorts bypass traditional slotting fees and concentrate margin capture in wellness-positioned brands.
Germany
REACH restrictions on microplastic shedding extend to chewing gum disposal classifications, mandating biodegradability certification for products sold through retail channels. The EU Single-Use Plastics Directive compresses compliance timelines for sugar-free functional varieties, driving partnerships between confectioners and natural resin cooperatives in advance of enforcement deadlines.
China
GB standards and SAMR oversight add compliance layers for entrants targeting domestic volume opportunities, while dual carbon goals pressure synthetic polymer formulations. Yangtze River Delta manufacturing clusters absorb contract production for export-oriented brands seeking cost-efficient scale without European regulatory exposure.
India
FSSAI standards govern food additive safety while the PLI scheme for food processing infrastructure attracts contract manufacturing investment. Maharashtra and Gujarat industrial corridors concentrate packaging and formulation capacity serving Middle East and African export markets with price-competitive synthetic gum base products.
Brazil
ANVISA pharmaceutical-adjacent oversight creates compliance complexity for functional gum entrants positioning caffeine and vitamin delivery systems. São Paulo state anchors Latin American production gravity, with Grupo Arcor's integrated operations exemplifying regional scale efficiency in commodity-grade bubble and chewing gum segments.
Gum Base Candy Market Competitive Landscape
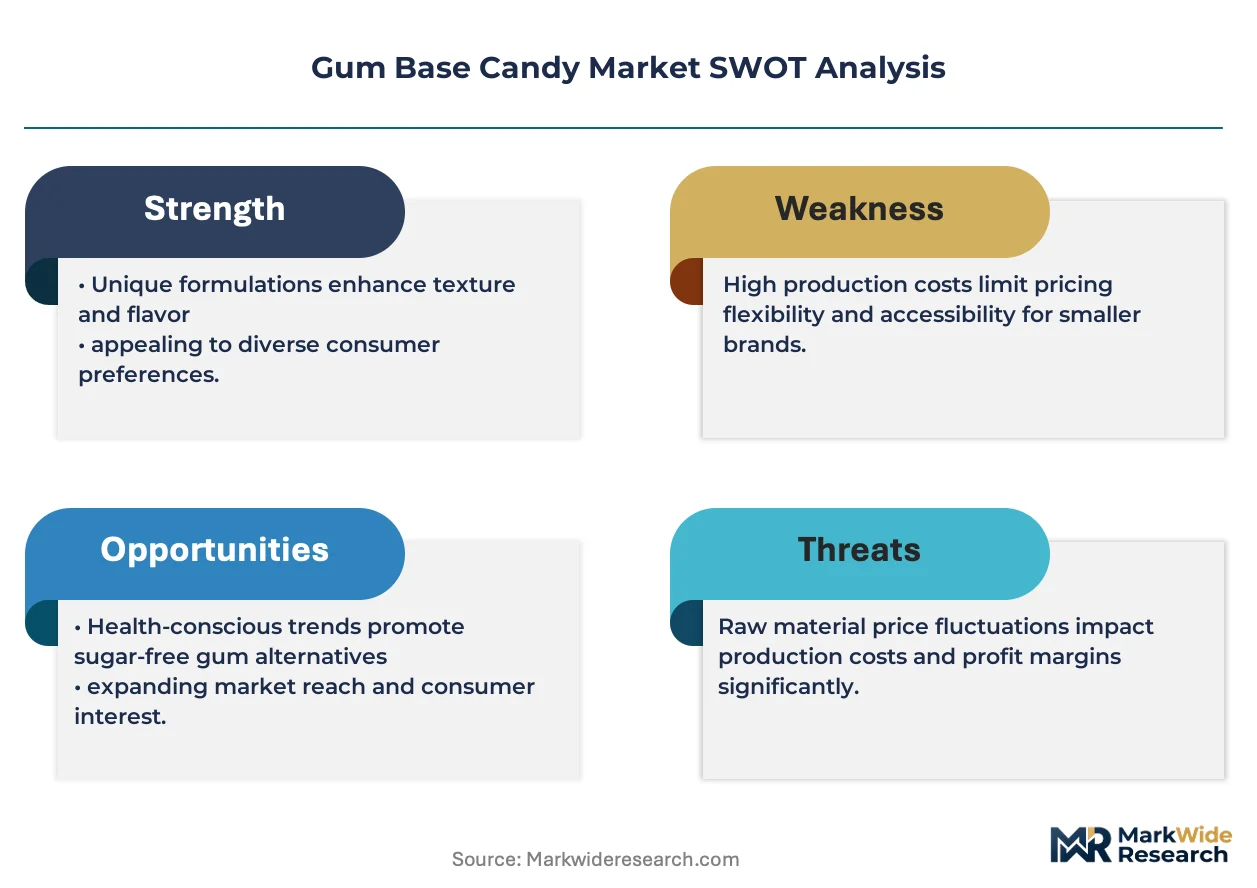
Concentration sits with integrated gum base producers who control upstream resin supply chains. The vendor base stratifies into three tiers: multinational confectioners with proprietary formulation capabilities, regional specialists leveraging geographic procurement advantages, and contract manufacturers serving private-label demand. Mars Wrigley Confectionery leverages captive gum base supply chains to sustain margin stability across volatile input markets. Competitive moves center on backward integration into natural resin harvesting and accelerated partnerships with biodegradable certification bodies.
Within the integrated multinational tier, Mars Wrigley Confectionery, Perfetti Van Melle, and Mondelēz International occupy positions that exemplify divergent strategic postures. Mars Wrigley Confectionery represents upstream control over proprietary gum base supply chains. Perfetti Van Melle anchors European production through scale-efficient manufacturing hubs. Mondelēz International exemplifies portfolio diversification that offsets seasonal gum demand fluctuations through broader confectionery holdings.
| Leading Market Players |
|---|
| Mars Wrigley Confectionery |
| Perfetti Van Melle |
| Mondelēz International |
| Lotte Confectionery |
| The Hershey Company |
| Grupo Arcor |
| Cloetta |
| Cafosa |
| Gumlink Confectionery Company |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day resin procurement lead times for natural chicle and jelutong tether pricing power to harvest-to-package operators with captive Central American and Southeast Asian cooperative relationships, compressing margin recovery for synthetic-dependent formulators facing petrochemical volatility.
Pricing Analysis
The customization-premium spread between configured-to-order functional gum formulations and standard mint varieties runs wide. Three-tier pricing structure across premium, standard, and economy levels separates biodegradable-certified natural resin products from commodity synthetic bases, with brand premium and certification grade as primary differentiation drivers. Pricing pressure stems from crude oil derivative volatility hitting synthetic gum margins, while buyer price sensitivity concentrates in emerging market bubble gum segments and institutional bulk procurement channels.
Supply Chain Analysis
Inventory-to-sales ratios for natural resin inputs run leaner than synthetic polymer stocks, reflecting harvest seasonality and cooperative processing bottlenecks. Geographic supply concentration centers on Mexico, Guatemala, and Indonesia for chicle and jelutong harvesting, with Malaysia and Thailand as secondary jelutong sources. Raw material dependencies rest on polyisobutylene, polyvinyl acetate, and xylitol sweetener systems. Single-source vulnerability from Central American cooperative concentration threatens biodegradable transition timelines. Distribution runs through convenience store checkout lanes, direct-to-consumer subscription platforms, and foodservice institutional procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a substitution defense against nicotine pouches, mint strips, and functional beverages that displace traditional breath-freshening occasions.
For Market Incumbents: Fortify upstream control over natural resin harvesting partnerships in Guatemala and Indonesia before EU Single-Use Plastics Directive enforcement compresses synthetic polymer demand. Deepen certification investments with biodegradable standards bodies to preempt compliance windows. Defend against functional beverage entrants by accelerating caffeine and nootropic delivery formulations through FDA GRAS pathways. For New Entrants and Emerging Players: Anchor in United States direct-to-consumer subscription models for nicotine cessation and wellness cohorts, where transparent supply chains satisfy ESG reporting requirements and bypass retail slotting fee barriers. Target white-space in personalized dosing formats for vitamin delivery. Pursue co-manufacturing partnerships with India PLI scheme beneficiaries for cost-competitive export production. For Investors and Strategic Acquirers: Long-term, this sits as a sustainability-transition play because regulatory pressure on petroleum-derived polymers creates durable competitive advantage for vertically integrated natural resin operators. Watch for biodegradable certification capacity constraints as the inflection signal indicating supply scarcity premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Natural Resin Harvesting | Captive chicle and jelutong supply secures margin stability under EU biodegradable mandates. |
| Biodegradable Certification Investment | REACH compliance and compostable labeling preempt regulatory displacement of synthetic formulations. |
| Direct-to-Consumer Subscription Launch | Wellness cohort targeting bypasses convenience store slotting fees and concentrates margin capture. |
| Functional Ingredient Partnership | FDA GRAS pathway acceleration for caffeine and vitamin delivery expands addressable demand beyond breath-freshening. |
| India Contract Manufacturing Scale-Up | PLI scheme incentives attract export-oriented production serving Middle East and African price-sensitive segments. |
Research Methodology
Cross-validation between primary interviews with gum base formulators, procurement leads at multinational confectioners, natural resin cooperative managers, and convenience store category buyers anchors the qualitative findings, while secondary validation draws from FDA GRAS determinations, EFSA novel food petitions, customs trade data for chicle and jelutong imports, and SEC filings from listed confectionery manufacturers. Bottom-up demand modeling triangulates against top-down market sizing across ingredient chemistry, product format, and distribution channel dimensions.
Sensitivity analysis around resin price volatility, regulatory enforcement timelines, and functional ingredient approval velocities stress-tests projection outputs across the analysis window. Segmentation modeling incorporates formulation chemistry, packaging economics, channel access patterns, and geographic regulatory clusters. CAGRs derive from elasticity-adjusted volume projections and price trajectory assumptions tied to input cost movements and premium positioning shifts.
Material uncertainties — sudden EU Single-Use Plastics Directive enforcement acceleration, Central American harvest disruption from climate events, and FDA GRAS pathway delays for novel natural resins — sit outside the modeled envelope. Forecasts reflect documented assumptions about substitution elasticity between synthetic and natural gum bases. Revision becomes warranted when biodegradable certification capacity utilization crosses eighty percent thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Confectionery
Saudi Arabia Chocolate Market
Confectionery
Middle East and Africa Premium Chocolate Market
Confectionery
Low-Calorie Jelly Market
Confectionery
Milk Chocolate Market
Confectionery
Chocolate Flavors Market
Confectionery
Middle East and Africa Confectionery Market
Confectionery
Europe Confectionery Market
Confectionery
Infused Fruits Jellies Market
Confectionery
Jellies and Gummies Market
Confectionery
Sugar-Free Chocolate Market
Confectionery
Mints Market
Confectionery
Crunchy Chocolate Market
Confectionery
Asia-Pacific Sugar Free Chewing Gum Market
Confectionery
Diet Candy Market
Confectionery
Global Chocolate Market
Confectionery
North America Marshmallow Market