
 Middle East and Africa Biometrics in Government Market | 2026-2036
Middle East and Africa Biometrics in Government Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Biometrics in Government Market Foresight
Silicon-based fingerprint sensors is realigning cost structures for large-scale government enrollment programs across the Middle East and Africa. NEC Corporation leverages its iris recognition portfolio to dominate airport and seaport deployments in the Gulf states. IDEMIA anchors civil identity contracts through its biometric document personalization capabilities. Fujitsu Limited differentiates via palm vein authentication systems targeting high-security defense installations.
Biometrics in government encompasses the automated measurement and statistical analysis of physiological and behavioral characteristics—fingerprint minutiae, iris patterns, facial geometry, voiceprints—for the purpose of verifying or establishing individual identity within public sector systems. These technologies operate through enrollment, template extraction, and matching algorithms against centralized or distributed databases, serving critical functions from voter registration to criminal identification. Fingerprint recognition occupies the largest installed base due to legacy infrastructure and cost efficiency, while facial recognition represents the fastest-expanding segment driven by contactless requirements and CCTV integration. Deployment through hybrid solutions captures growing margin pools as agencies balance data sovereignty with cloud scalability.
Saudi Arabia's National Information Center, South Africa's Information Regulator under POPIA, and the UAE's Telecommunications and Digital Government Regulatory Authority collectively enforce data localization, consent protocols, and interoperability standards that determine vendor eligibility. Compliance with these frameworks shapes procurement specifications, particularly for cross-border identity verification systems and criminal biometric databases. Stakeholders must monitor evolving national data protection implementations and alignment with ISO/IEC 30107 presentation attack detection standards to sustain contract viability across divergent regulatory timelines.
Market Dynamics
Multimodal biometric enrollment is consolidating procurement specifications across Gulf Cooperation Council states, compressing vendor qualification cycles and elevating data sovereignty requirements as the defining selection criterion.
Growth Catalysts
- National Identity Mandates:Nigeria's National Identity Management Commission enrollment directives are expanding civil registration infrastructure and creating sustained hardware refresh cycles.
- Border Modernization:UAE seaport and airport authorities are deploying iris recognition corridors at Abu Dhabi and Dubai entry points, accelerating contactless passenger processing.
- Smart City Integration:Saudi Arabia's National Information Center is embedding biometric authentication into municipal service portals across Riyadh and Neom.
Market Restraints
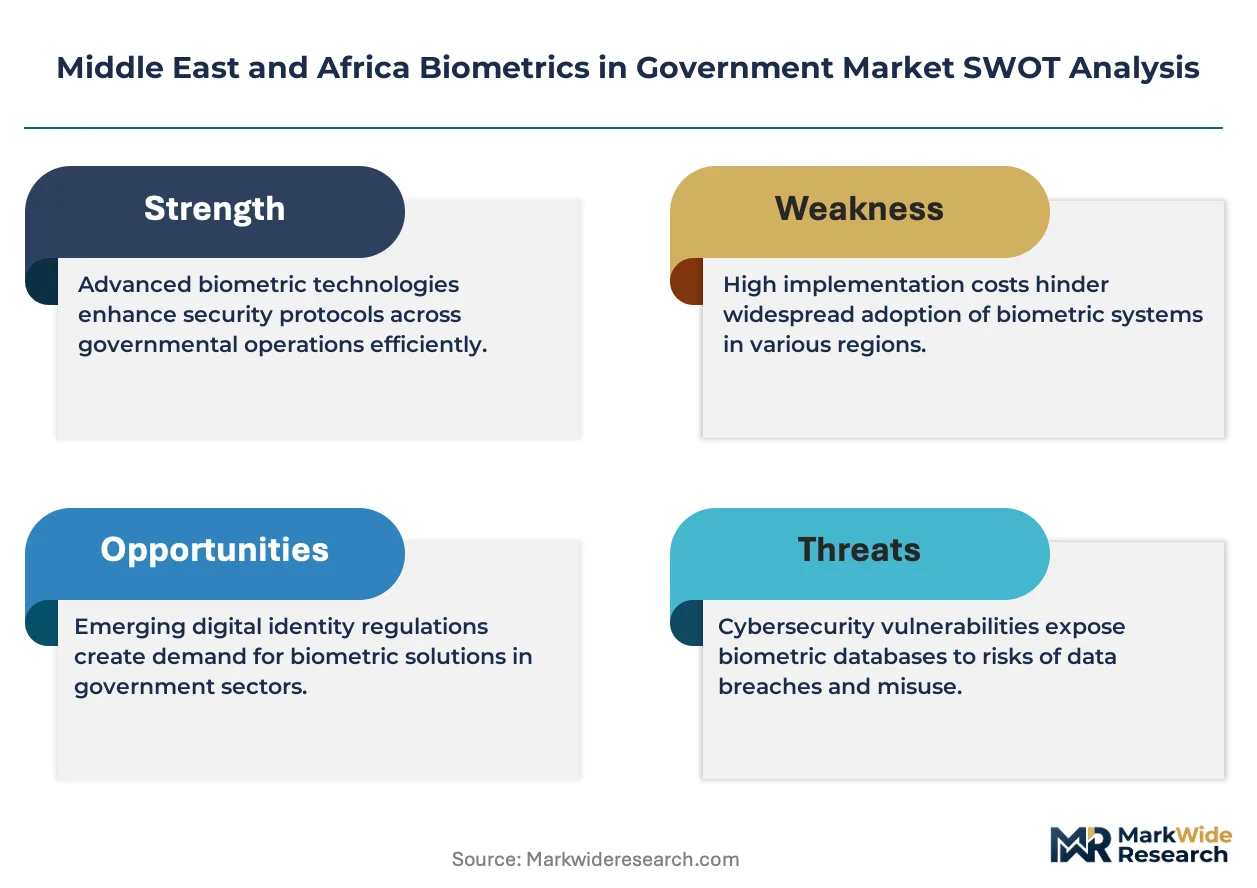
- Silicon Supply Concentration:Fingerprint sensor fabrication depends on East Asian semiconductor foundries, exposing procurement timelines to regional supply disruptions.
- Data Localization Costs:South Africa's POPIA mandates require in-country server infrastructure, elevating total cost of ownership for foreign biometric vendors.
- Template Interoperability Gaps:Divergent national biometric data formats across Middle East and Africa jurisdictions fragment cross-border identity verification.
Strategic Opportunities
- Egyptian Civil Registry Expansion:Untapped rural enrollment populations present first-mover advantages for mobile biometric capture units.
- Palm Vein Defense Applications:Convergence of vascular pattern recognition with access control systems opens high-security military installation contracts.
- Cloud-Edge Hybrid Architectures:Distributed processing models align with GCC data sovereignty frameworks while enabling scalable criminal database queries.
Industry Challenges
- Biometric Engineer Scarcity:Template extraction algorithm specialists and ISO/IEC 30107 presentation attack detection experts remain concentrated in European and East Asian labor markets.
- Legacy System Integration:Decades-old fingerprint AFIS infrastructure in South African law enforcement requires costly middleware development for multimodal upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Biometrics in Government Market |
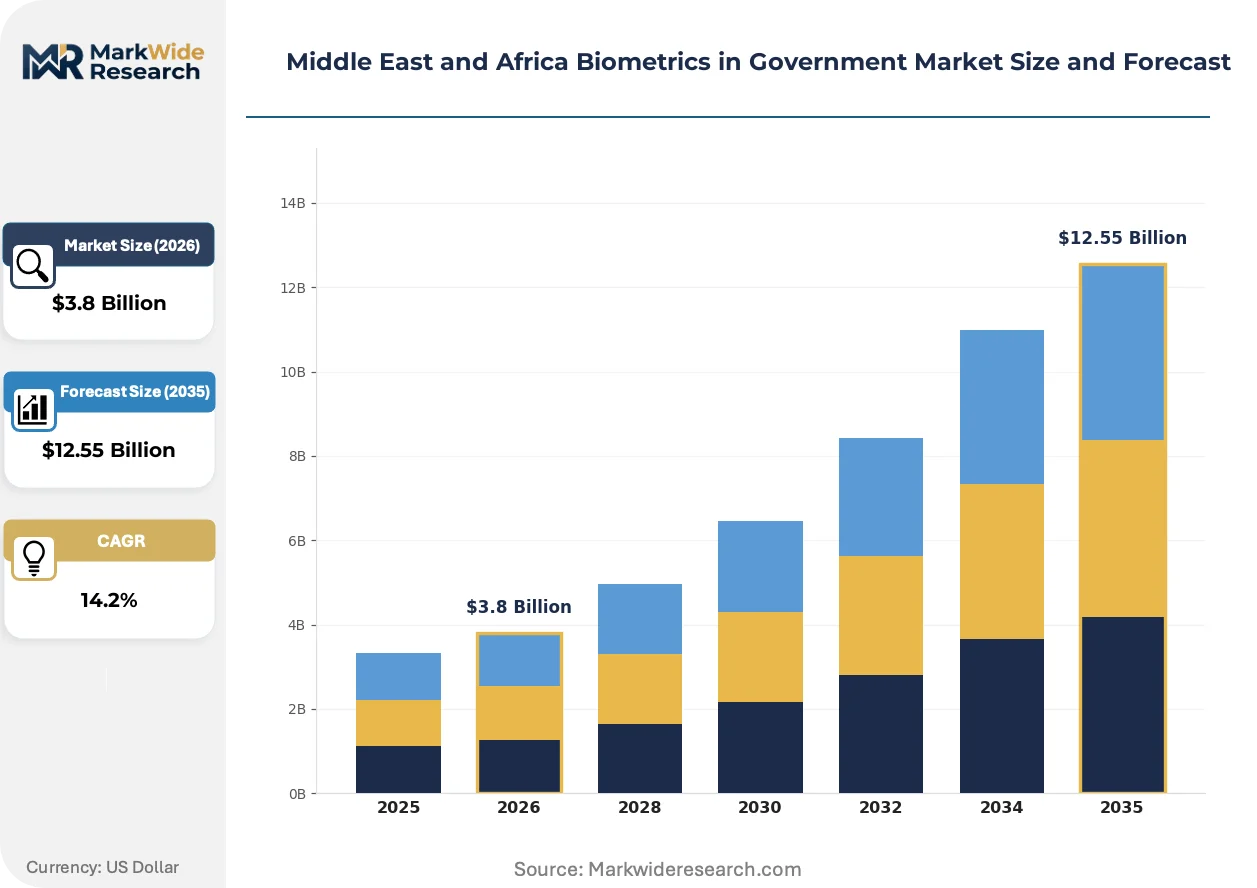
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fingerprint Recognition, Facial Recognition, Iris Recognition, Voice Recognition Application: Identity Verification, Access Control, Border Security, E-Government Services End User: Public Sector, Law Enforcement, Immigration, Defense Deployment: On-Premise, Cloud-Based, Hybrid Solutions, Mobile Biometrics |
| Companies Covered | NEC Corporation, HID Global Corporation, Fujitsu Limited, Aware Inc., IDEMIA, Gemalto N.V., Bio-Key International Inc., Iris ID Systems, Inc., M2SYS Technologies, Inc, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Biometrics in Government Market Shifts & Advancements
Contactless biometric modalities are displacing legacy fingerprint capture in high-throughput government environments, while regulatory pressure on algorithmic bias is reshaping vendor development priorities across the region.
Edge-based facial recognition hardware is modularizing deployment architectures for Saudi smart city projects. Municipal authorities in Riyadh are adopting containerized biometric processing units that reduce centralized data center dependency. This modularizing approach compresses infrastructure commissioning timelines from months to weeks while satisfying National Information Center data residency requirements.
South Africa's Information Regulator under POPIA is enforcing algorithmic fairness audits for biometric systems processing citizen data. Vendors must now submit independent bias assessment reports before contract award. Civil identity procurement specifications in Johannesburg and Cape Town are being rewritten to mandate demographic performance parity across racial categories.
Subscription-based biometric platform licensing is displacing perpetual license sales in Nigerian federal contracts. State-level identity management commissions in Lagos and Kano are piloting annual fee structures that bundle hardware, software, and maintenance. This model reduces upfront capital requirements for cash-constrained agencies while locking in vendor recurring revenue streams.
Middle East and Africa Biometrics in Government Market Segmentation
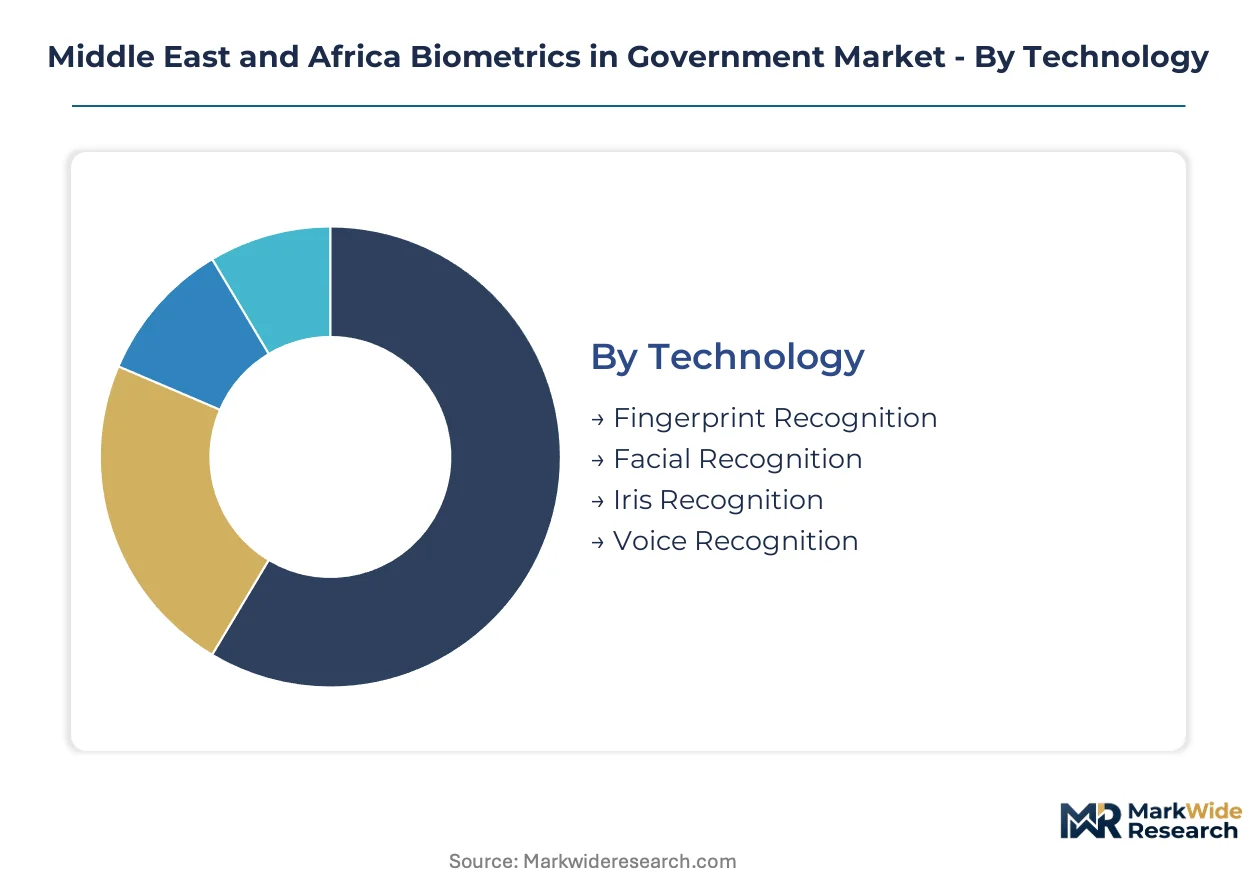
Procurement specifications across Middle East and Africa government agencies diverge sharply by deployment maturity and data sovereignty requirements. Segment-level differentiation determines vendor qualification cycles and contract margin structures.
Technology:
Agency budget cycles and legacy infrastructure compatibility dominate technology selection decisions.
- Facial Recognition:Contactless capture systems process templates through edge-based neural networks. Saudi Arabia's National Information Center mandates this modality for smart city corridors in Riyadh and Neom, driven by pandemic-era hygiene protocols and CCTV integration requirements.
- Fingerprint Recognition:Silicon-based sensors extract minutiae patterns for civil registration databases. Nigeria's National Identity Management Commission relies on this technology for rural enrollment campaigns, constrained by semiconductor supply concentration in East Asian foundries.
- Iris Recognition:Pattern-matching algorithms secure high-throughput border checkpoints. UAE seaport and airport authorities deploy NEC Corporation systems at Abu Dhabi and Dubai entry points.
- Voice Recognition:Spectral analysis authenticates remote service access. South African call center integrations for government helplines pilot speaker verification.
Fingerprint recognition leads on scale; facial recognition leads on momentum.
Application:
Security classification thresholds and citizen transaction volumes shape application prioritization.
- Border Security:Multimodal corridors combine iris and facial capture for passenger processing. UAE authorities modernize seaport and airport infrastructure with contactless throughput systems.
- Identity Verification:Civil registration systems enroll biometric templates into national databases. Nigeria's directive mandates universal coverage across state-level commissions.
- Access Control:Vascular pattern and fingerprint systems secure defense installations. Saudi military facilities specify palm vein authentication for classified zones.
- E-Government Services:Biometric login portals authenticate municipal service requests. Riyadh municipal authorities embed authentication into digital service delivery.
Identity verification dominates installed base; border security climbs the fastest.
End User:
Operational security clearance levels and procurement authority centralization determine end-user segmentation.
- Immigration:Border management agencies deploy multimodal enrollment at ports of entry. UAE and Saudi authorities drive contactless corridor procurement.
- Law Enforcement:Criminal biometric databases require AFIS integration and middleware development. South African police legacy systems demand costly multimodal upgrades.
- Defense:High-security installations specify vascular pattern recognition for access control. Saudi military contracts prioritize liveness detection and anti-spoofing.
- Public Sector:Civil identity programs mandate universal enrollment for service access. Nigeria's commission directs state-level implementation.
Public sector commands volume; immigration shows steepest expansion trajectory.
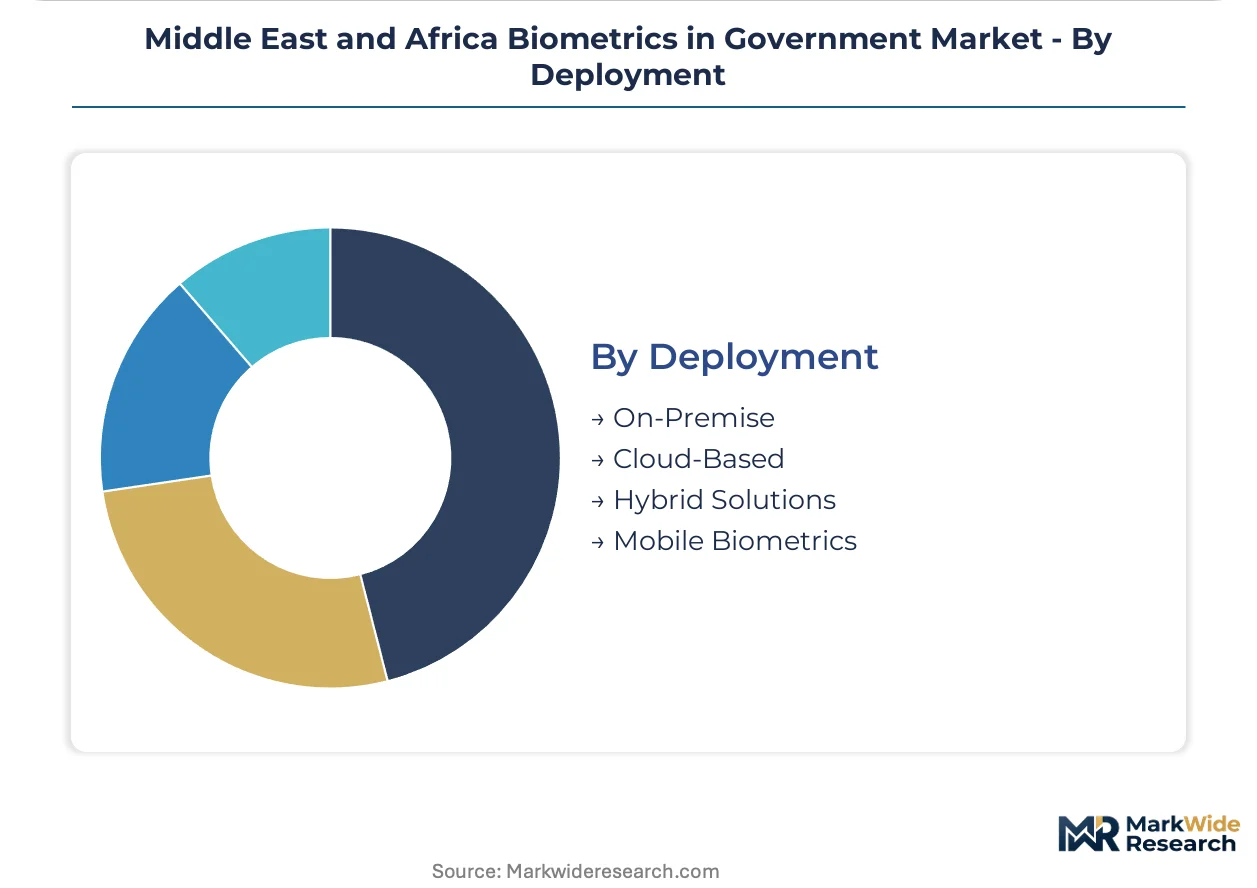
Deployment:
Data residency requirements and capital availability constrain deployment architecture selection.
- Hybrid Solutions:Distributed processing balances cloud scalability with local template storage. GCC data sovereignty frameworks favor this architecture for criminal database queries.
- On-Premise:Dedicated server infrastructure satisfies POPIA mandates in South Africa. Johannesburg and Cape Town specifications require in-country data centers.
- Cloud-Based:Scalable template matching reduces hardware capital requirements. Nigerian federal contracts pilot subscription licensing models.
- Mobile Biometrics:Capture units reach rural populations beyond fixed enrollment centers. Egypt's civil registry expansion targets untapped demographics with portable systems.
On-premise retains regulatory preference; hybrid solutions gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gulf Cooperation Council states anchor procurement momentum for multimodal biometric systems across national identity and border modernization programs. National Information Center directives in Saudi Arabia and Telecommunications and Digital Government Regulatory Authority mandates in the UAE compress vendor qualification timelines while elevating data sovereignty requirements. South Africa's Protection of Personal Information Act and Nigeria's National Identity Management Commission enrollment directives reshape compliance specifications across sub-Saharan procurement.
Saudi Arabia
Neom and Riyadh smart city corridors drive demand for edge-based facial recognition hardware and municipal service portal authentication. National Information Center data residency mandates require localized template storage for all civil identity systems. Eastern Province defense installations specify palm vein authentication for classified zone access control.
United Arab Emirates
Abu Dhabi and Dubai airport and seaport authorities deploy iris recognition corridors for contactless passenger throughput acceleration. Telecommunications and Digital Government Regulatory Authority interoperability standards determine vendor eligibility for cross-border identity verification. Dubai's logistics cluster concentrates procurement authority for multimodal border infrastructure.
South Africa
Johannesburg and Cape Town civil identity procurement specifications mandate algorithmic fairness audits under Information Regulator POPIA enforcement. Law enforcement legacy AFIS infrastructure requires costly middleware development for multimodal system integration. Western Cape biometric engineer scarcity elevates vendor technical support requirements.
Nigeria
Lagos and Kano state-level identity management commissions pilot subscription-based platform licensing to reduce upfront capital constraints. National Identity Management Commission enrollment directives expand rural civil registration infrastructure with mobile biometric capture units. Federal contracts favor bundled hardware-software-maintenance fee structures.
Egypt
Untapped rural populations beyond fixed enrollment centers create first-mover opportunities for portable biometric capture system deployment. General Authority for Government Services modernization programs embed authentication into digital service delivery. Cairo's administrative cluster concentrates procurement specification development for civil registry expansion.
Middle East and Africa Biometrics in Government Market Competitive Landscape
Global majors compete with regional champions across technology licensing and data sovereignty compliance dimensions. Market structure tilts toward consolidated procurement authority at national information centers, compressing vendor pools to Tier-1 system integrators. Three archetypes dominate: multimodal platform specialists, document personalization incumbents, and vascular pattern authentication innovators. Competitive moves center on strategic partnerships with local system integrators and portfolio diversification into cloud-edge hybrid architectures.
Within the multimodal platform tier, NEC Corporation and IDEMIA occupy anchor positions across Gulf Cooperation Council deployments. Fujitsu Limited exemplifies the high-security specialization archetype through palm vein authentication targeting defense installation contracts. HID Global Corporation represents the access control integration vector, while Aware Inc. and Bio-Key International Inc. sit within the software-centric authentication layer. These named entities serve as structural anchors for understanding how vendor selection criteria vary across civil identity, border security, and defense application segments.
| Leading Market Players |
|---|
| NEC Corporation |
| HID Global Corporation |
| Fujitsu Limited |
| Aware Inc. |
| IDEMIA |
| Gemalto N.V. |
| Bio-Key International Inc. |
| Iris ID Systems, Inc. |
| M2SYS Technologies, Inc |
| Others |
Supply & Pricing Matrix
Captive semiconductor fabrication within East Asian foundries anchors both sensor supply security and vendor pricing power across Middle East and Africa biometric procurement. This integration pattern shields NEC Corporation and IDEMIA from spot-market silicon volatility while compressing margin flexibility for second-tier vendors dependent on merchant wafer supply.
Pricing Analysis
Silicon wafer cost pass-through dominates hardware pricing across fingerprint sensor procurement for Nigerian civil registration campaigns. Three-tier pricing structure across premium multimodal platforms, standard single-modality systems, and economy mobile capture units differentiates vendor positioning. Cost compression in economy tiers intensifies because South African POPIA compliance mandates elevate localization overhead. Federal agencies in Lagos and Kano exhibit highest price sensitivity; Gulf Cooperation Council defense ministries demonstrate lowest sensitivity due to security classification requirements.
Supply Chain Analysis
Regional distribution centers in Dubai and Johannesburg coordinate hub-and-spoke fulfillment for biometric hardware across sub-Saharan and Gulf markets. Manufacturing concentrates in Taiwan, South Korea, and Japan for CMOS image sensors and neural processing units. Sensor fabrication rests on polycrystalline silicon wafers, specialized optical components, and edge-AI chipsets. Single-source vulnerability in advanced node semiconductor supply exposes procurement timelines to geopolitical disruption. Distribution runs through authorized system integrator networks with local certification mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a geographic-arbitrage play between Gulf Cooperation Council states with sovereign wealth-backed procurement budgets and cash-constrained sub-Saharan agencies requiring subscription financing structures.
For Market Incumbents: Lock in multimodal platform dominance through exclusive partnerships with Saudi Arabia's National Information Center and UAE Telecommunications and Digital Government Regulatory Authority certification pipelines. Threat from palm vein authentication specialists like Fujitsu Limited in defense verticals demands accelerated iris-recognition R&D investment. Channel control via local system integrator exclusivity agreements secures recurring revenue visibility. For New Entrants and Emerging Players: Enter via Egyptian civil registry expansion targeting untapped rural demographics with portable biometric capture units. White-space concentrates in mobile enrollment infrastructure for state-level commissions beyond Lagos and Kano. Cloud-edge hybrid architecture licensing to Nigerian federal agencies offers lowest competitive density. For Investors and Strategic Acquirers: Roll-up economics work for ISO/IEC 30107 certification specialists because algorithmic bias audit mandates are fragmenting vendor qualification timelines across South Africa and Nigeria. Long-term viability hinges on data sovereignty compliance capabilities rather than hardware differentiation. Signal to watch: POPIA enforcement intensity in Johannesburg and Cape Town procurement specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Edge Hybrid Architecture Deployment | Aligns with GCC data residency frameworks while enabling scalable criminal database queries for law enforcement. |
| ISO/IEC 30107 Certification Investment | Satisfies South Africa's Information Regulator mandates for presentation attack detection in civil identity contracts. |
| Mobile Biometric Capture Unit Expansion | Reaches Egyptian rural populations beyond fixed enrollment centers for civil registry modernization. |
| Local System Integrator Partnership | Compresses vendor qualification timelines for Saudi National Information Center procurement cycles. |
| Palm Vein Authentication R&D | Targets Saudi Eastern Province defense installation contracts requiring liveness detection capabilities. |
Research Methodology
Coverage spans Gulf Cooperation Council states, South Africa, Nigeria, and Egypt, with primary inputs from each jurisdiction combining executive interviews with biometric procurement officers and secondary validation. Stakeholder roles included National Information Center technology directors, state-level identity commission managers, airport authority operations heads, and defense ministry security architects. Secondary sources comprised Telecommunications and Digital Government Regulatory Authority procurement disclosures, South African Information Regulator enforcement bulletins, Nigerian federal budget appropriations, and customs import records for biometric hardware. Bottom-up enrollment volume estimates triangulated against top-down contract value aggregation.
Granularity-level modeling distinguished technology modality, application security tier, deployment architecture, and end-user classification across each geographic market. CAGRs derived from enrollment mandate timelines, hardware refresh cycles, and subscription licensing adoption curves. Industry-specific inputs included POPIA compliance cost modeling, semiconductor supply lead time assumptions, and biometric engineer labor market scarcity indices.
Inputs from regulatory filings and procurement databases were available through the study window; gaps in classified defense contract specifications introduce uncertainty bands around Saudi and UAE military segment projections. Forecasts reflect documented assumptions regarding enrollment mandate enforcement continuity and data localization policy stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biometrics & Identity Management
Gait Biometrics Market
Biometrics & Identity Management
Global Biometric Systems Market
Biometrics & Identity Management
FIDO Authentication Market
Biometrics & Identity Management
Mobile Biometric Security and Services Market
Biometrics & Identity Management
Latin America Biometrics Market
Biometrics & Identity Management
Global Biometric Technology Market
Biometrics & Identity Management
Face Voice Biometric Market
Biometrics & Identity Management
Fingerprint Biometrics Market
Biometrics & Identity Management
North America Government and Security Biometrics Market
Biometrics & Identity Management
Palm Vein Biometrics Market
Biometrics & Identity Management
Global Phone Based Authentication Solution Market
Biometrics & Identity Management
Germany Identity Verification and Authentication Market
Biometrics & Identity Management
E-Government Identity Management Market
Biometrics & Identity Management
Europe Government and Security Biometrics Market
Biometrics & Identity Management
Password Management Market
Biometrics & Identity Management
United States Biometrics Market