
 Global Pre-Shipment Inspection Market | 2026-2036
Global Pre-Shipment Inspection Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pre-Shipment Inspection Market Outlook
E-commerce retailers and direct-to-consumer brands is rotating toward pre-shipment inspection as a standard procurement discipline, displacing traditional trading companies that once intermediated quality control. SGS leverages its laboratory network across manufacturing clusters to anchor high-volume contracts in consumer goods. Bureau Veritas competes through specialized agricultural and food safety protocols that command premium positioning. Intertek Group differentiates via digital inspection platforms that compress report turnaround times for time-sensitive shipments.
Pre-shipment inspection encompasses systematic verification of product quality, quantity, labeling, and packaging conformity against purchase orders or regulatory standards prior to cargo release, typically involving randomized sampling under ISO 2859 methodologies and on-site functional testing where applicable. Its primary commercial purpose is to transfer quality assurance risk from buyers to independent third parties before title transfers at port. Quality control services within the service type dimension dominate current revenue pools, though remote inspection under the delivery model is expanding fastest as camera-enabled verification and blockchain-anchored documentation reduce travel-dependent costs. The pharmaceuticals vertical under industry vertical commands outsized margins due to stringent GDP and serialization requirements that demand specialized inspector training.
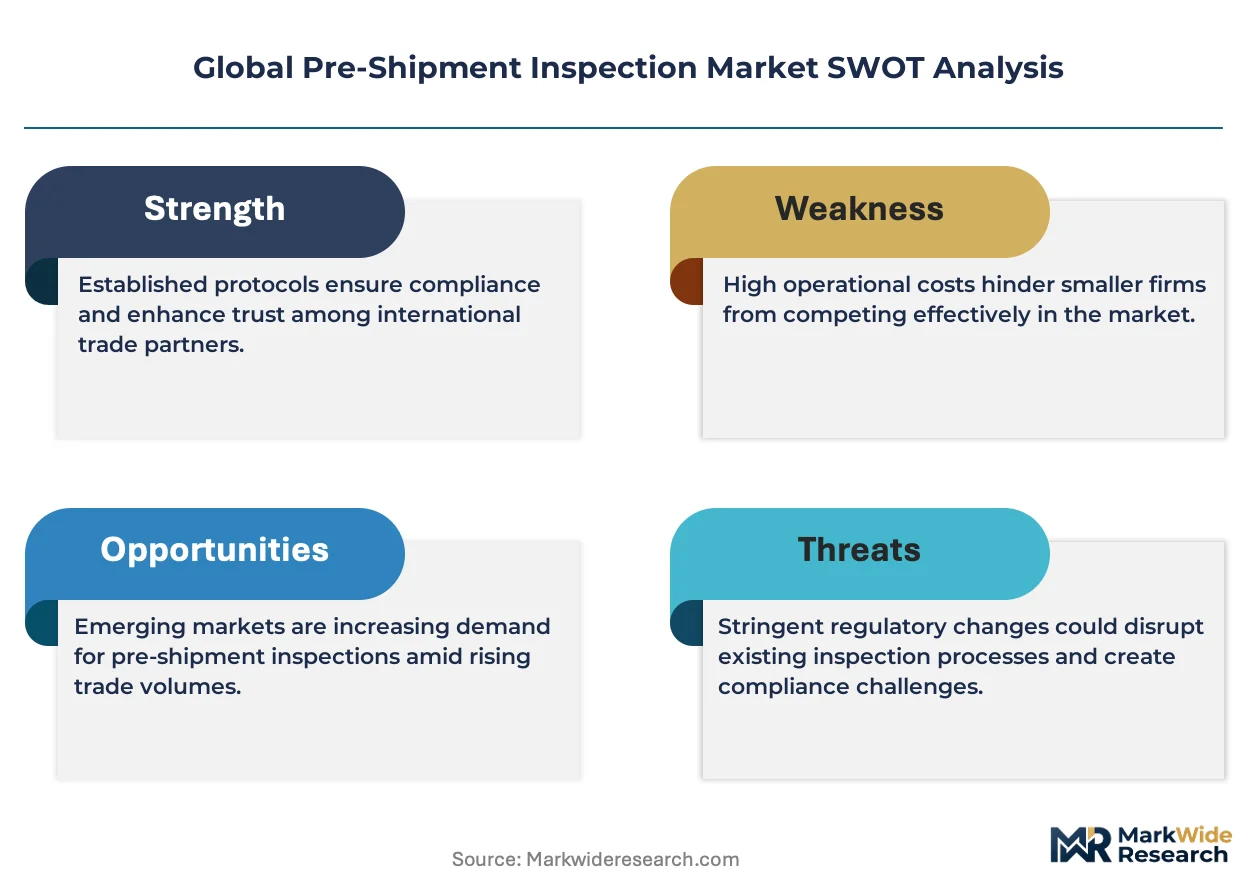
FDA rules on imported food and medical device prior notice, EU REACH and MDR conformity obligations, and China's GB standards enforced by SAMR collectively raise the cost of non-compliance and expand addressable demand for documented pre-shipment verification. ISO/IEC 17020 accreditation requirements further filter market access, concentrating procurement among accredited bodies. Stakeholders must monitor whether remote inspection protocols achieve permanent regulatory equivalence with on-site presence across major destination markets.
Market Dynamics
The pre-shipment inspection market is restructuring around remote verification technologies that compress inspection cycles and reduce travel-dependent cost structures, while regulatory fragmentation across destination markets multiplies compliance complexity for exporters.
Growth Catalysts
- EU CSRD supply chain disclosure mandates:Corporate sustainability reporting requirements now extend to upstream verification, compelling European importers to document third-party inspection before goods enter customs.
- Cross-border e-commerce volume concentration:Direct-to-consumer platforms operating from Chinese manufacturing clusters require systematic quality gates that bypass traditional trading company intermediaries.
- Blockchain-anchored documentation protocols:Immutable inspection records are reducing documentary fraud in agricultural and pharmaceutical exports subject to destination market traceability requirements.
Market Restraints
- Accreditation cost barriers:ISO/IEC 17020 conformity assessment requirements demand sustained capital investment in laboratory infrastructure and auditor training that filters smaller regional competitors from high-margin verticals.
- Inspector travel cost volatility:Fuel price fluctuations and aviation capacity constraints directly compress margins on traditional on-site inspection models dependent upon physical presence at manufacturing origin.
- Regulatory equivalence uncertainty:Permanent acceptance of remote inspection protocols by FDA, EMA, and NMPA remains unresolved, creating compliance risk for inspection bodies investing in camera-enabled verification systems.
Strategic Opportunities
- Indian pharmaceutical export corridor expansion:CDSCO serialization requirements and EU MDR conformity obligations are creating specialized demand for GDP-trained inspection capacity at Mumbai and Hyderabad manufacturing clusters.
- Carbon footprint verification integration:EU Green Deal border adjustment mechanisms and corporate net-zero commitments are extending inspection scope from quality to embodied emissions documentation.
- AI-augmented defect detection:Machine vision systems combined with standardized sampling protocols are enabling real-time quality assessment that compresses report generation from days to hours.
Industry Challenges
- Specialized inspector talent scarcity:GDP certification for pharmaceutical inspection and agricultural Phytosanitary expertise require multi-year training pipelines that lag current demand acceleration.
- Legacy system integration friction:ERP connectivity between inspection platforms and buyer procurement systems demands customized API development that extends contract implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pre-Shipment Inspection Market |
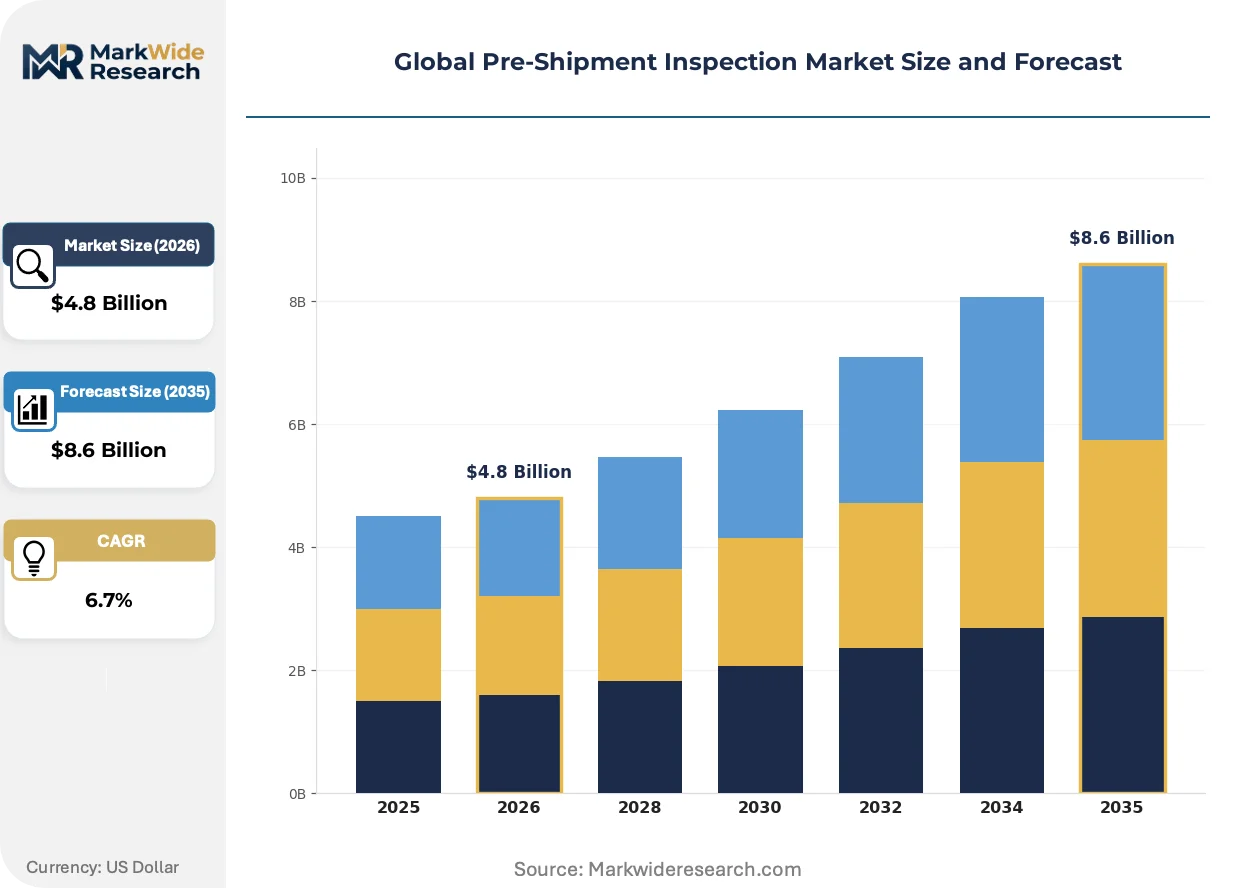
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Quality Control, Quantity Verification, Compliance Testing, Loading Supervision Industry Vertical: Manufacturing, Retail, Logistics, Pharmaceuticals End User: Importers, Exporters, Manufacturers, Third-Party Inspectors Delivery Model: On-Site Inspection, Remote Inspection, Certification Services, Consulting |
| Companies Covered | SGS, Bureau Veritas, Intertek Group, DEKRA, Cotecna, TÜV SÜD, TÜV Rheinland, QIMA, Applus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pre-Shipment Inspection Market Strategic Shifts
Digital inspection infrastructure is fragmenting traditional service delivery models while regulatory technology investments reshape compliance verification workflows across export manufacturing corridors.
Remote inspection technology is bifurcating market service tiers. Camera-enabled verification platforms with blockchain-anchored documentation now handle routine consumer goods sampling, compressing delivery timelines from seventy-two hours to same-day reporting. E-commerce retailers and fast-fashion importers are adopting these protocols fastest, forcing traditional inspection bodies to defend premium positioning through specialized laboratory testing that remote systems cannot replicate.
EU REACH enforcement expansion is intensifying chemical conformity verification requirements. The ECHA's updated substance restriction schedules now mandate third-party testing for SVHC content in consumer products before customs release, extending inspection scope from physical quality to material composition documentation. German and French chemical distributors are consolidating procurement with accredited bodies possessing in-house GC-MS laboratory capacity, compressing vendor selection to a narrow tier of vertically integrated providers.
Buyer organizational structures are rotating inspection accountability from procurement to compliance functions. Sustainability and ESG officers now own pre-shipment verification budgets at major European retailers, displacing traditional quality managers who prioritized defect detection over documentary traceability. This shift is most visible in German and Dutch apparel sourcing operations, where CSRD-aligned supply chain disclosure requirements override unit-cost minimization in vendor selection criteria.
Global Pre-Shipment Inspection Market Segmentation
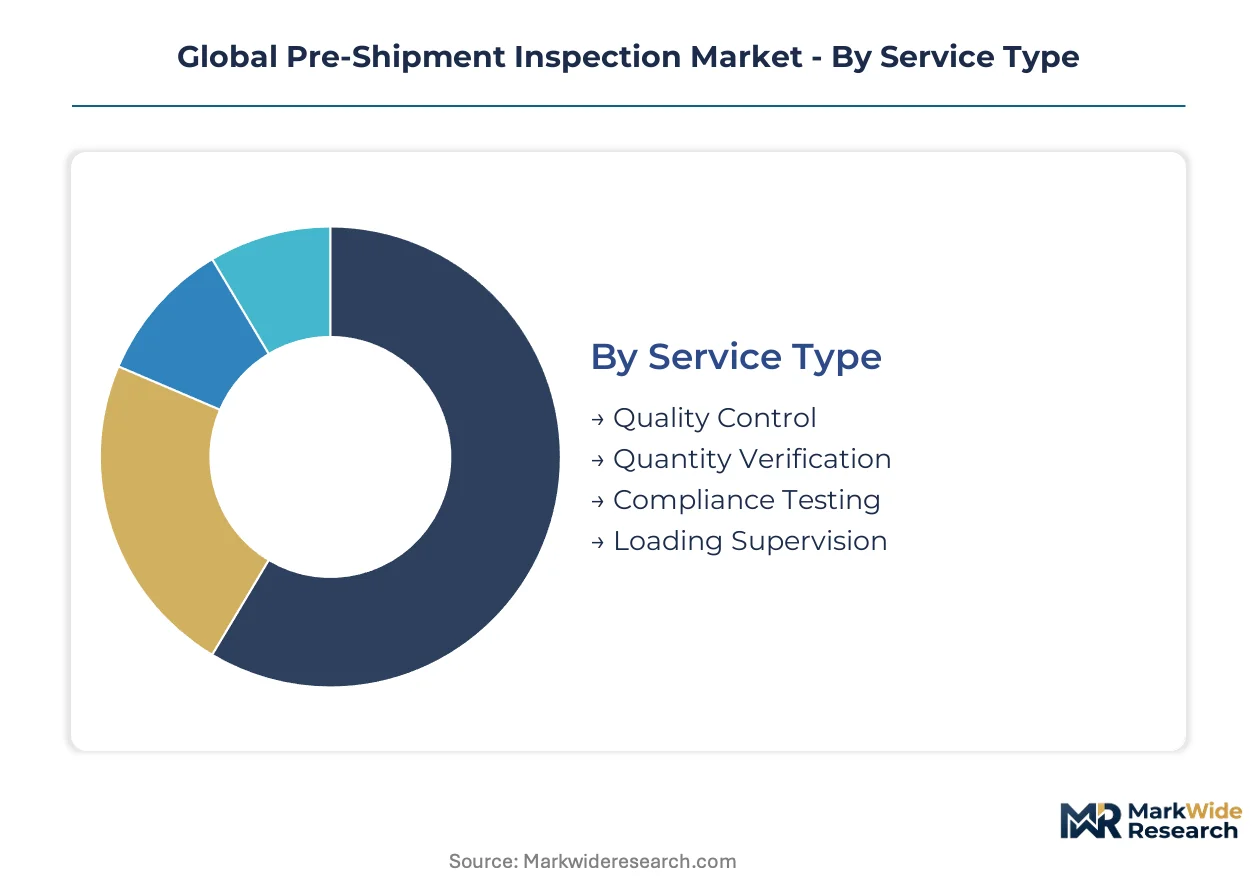
Pre-shipment inspection service procurement fragments across four structural dimensions. Regulatory complexity, supply chain configuration, and buyer organizational maturity determine which segments command premium pricing versus commodity positioning.
Service Type:
Regulatory differentiation separates quality assurance from documentary verification, with EU REACH and FDA prior notice rules elevating certain service tiers above routine sampling.
- Quality Control:Systematic randomized sampling under ISO 2859 methodologies combined with on-site functional testing. Manufacturing clusters in China and Vietnam generate concentrated demand as Western importers transfer defect liability to third parties before title transfer at port.
- Compliance Testing:Laboratory analysis for SVHC content under ECHA schedules, GDP certification for pharmaceutical cold chains, and phytosanitary verification for agricultural exports. EU MDR and CDSCO serialization requirements in India are accelerating specialized inspector training investments.
- Quantity Verification:Container stuffing audits and carton count reconciliation against purchase orders.
- Loading Supervision:Seal verification and damage documentation during cargo consolidation.
Established volume favors Quality Control; emerging adoption favors Compliance Testing.
Industry Vertical:
Margin concentration correlates with regulatory stringency, creating tiered pricing structures across verticals with divergent certification requirements.
- Pharmaceuticals:GDP-trained inspectors verify cold chain integrity and serialization compliance under EU MDR and FDA drug supply chain security mandates. Mumbai and Hyderabad manufacturing corridors in India command specialized capacity premiums due to CDSCO export certification requirements.
- Retail:Fast-fashion and consumer electronics importers deploy systematic quality gates that bypass traditional trading company intermediaries. Cross-border e-commerce volume from Chinese manufacturing clusters is rotating procurement accountability from procurement to ESG compliance functions.
- Manufacturing:Industrial component verification against GB standards and ISO specifications.
- Logistics:Freight forwarder-arranged inspection for consolidated container loads.
Pharmaceuticals capture the steepest margin expansion; Retail absorbs the highest absolute inspection volume.
End User:
Organizational buyer type determines service bundling preferences and price sensitivity thresholds across procurement maturity levels.
- Importers:European retailers subject to CSRD supply chain disclosure mandates now document third-party verification before customs release. German and Dutch apparel sourcing operations prioritize documentary traceability over unit-cost minimization in vendor selection criteria.
- Manufacturers:Factory-origin inspection remains the dominant procurement model for Chinese exporters seeking to pre-qualify for Western retail vendor lists.
- Exporters:Agricultural and food safety protocols command premium positioning for EU and Middle Eastern destination markets.
- Third-Party Inspectors:Subcontracted capacity for peak season volume surges.
Importer procurement is concentrating fastest; Manufacturer origin inspection retains structural volume dominance.
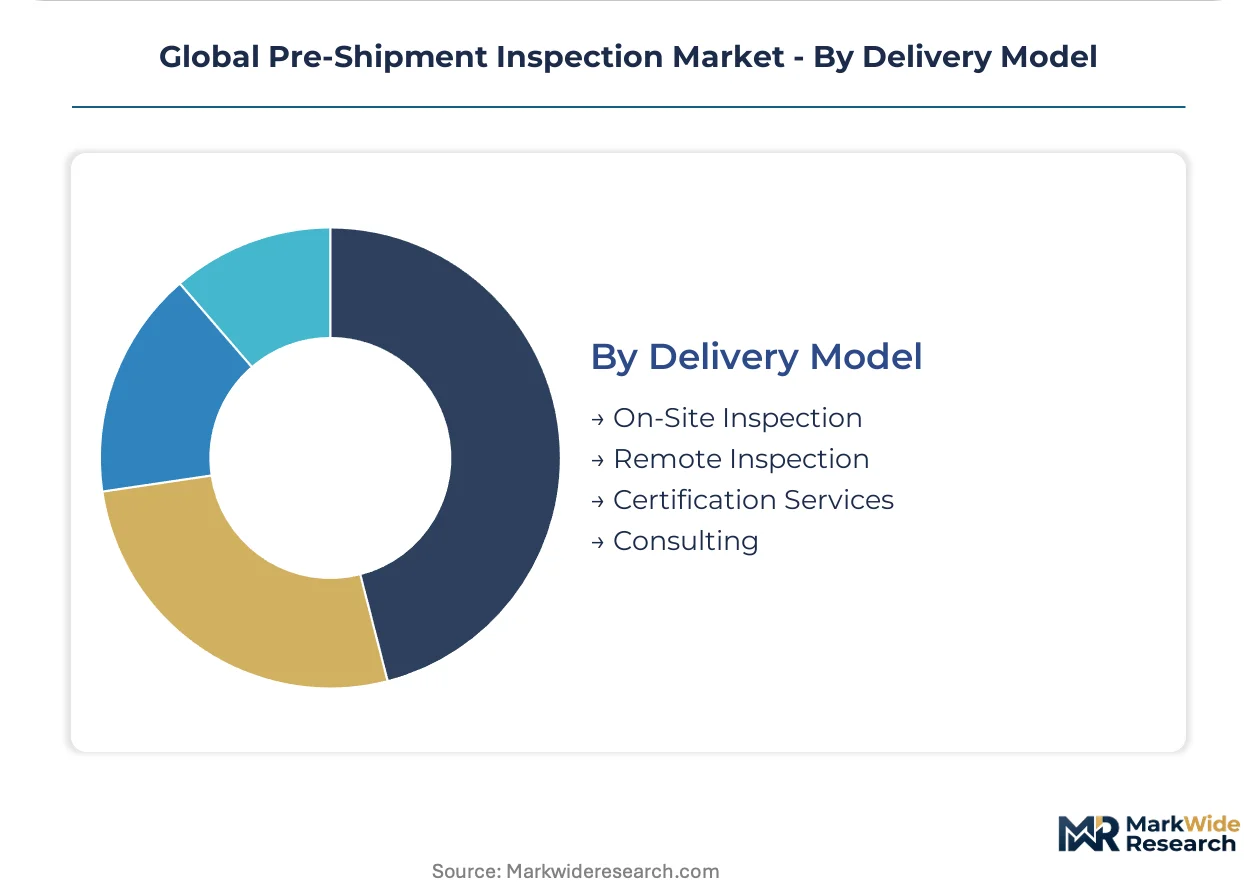
Delivery Model:
Technology-enabled verification is bifurcating service tiers between travel-dependent presence and camera-enabled remote protocols.
- Remote Inspection:Blockchain-anchored documentation with same-day reporting compression from seventy-two hour cycles. E-commerce retailers and fast-fashion importers adopt these protocols fastest, though permanent regulatory equivalence with FDA and EMA on-site requirements remains unresolved.
- On-Site Inspection:Physical presence at manufacturing origin with laboratory sample collection. Fuel price volatility and aviation capacity constraints directly compress margins on this traditional model.
- Certification Services:ISO/IEC 17020 accreditation issuance and renewal audits.
- Consulting:Supply chain risk mapping and inspector training program design.
On-Site Inspection maintains revenue concentration; Remote Inspection gains share fastest among digitally mature buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai anchors Asia's pre-shipment inspection volume, handling containerized exports that feed inspection demand across manufacturing clusters. Rotterdam's Maasvlakte terminals serve as Europe's primary inspection gateway for REACH-mandated verification. The Port of Los Angeles processes North American import flows where FDA prior notice rules trigger third-party documentation requirements.
China
Cross-border e-commerce exporters in the Yangtze River Delta require systematic quality gates before cargo release. SAMR enforces GB standards compliance through factory-origin inspection mandates. Shenzhen and Dongguan manufacturing corridors concentrate remote inspection platform adoption as camera-enabled verification displaces traditional trading company intermediaries.
Germany
CSRD supply chain disclosure obligations now extend to upstream verification for imported consumer goods. ECHA's REACH enforcement expansion mandates third-party SVHC testing before customs release. The Rhine-Ruhr industrial belt concentrates procurement consolidation with accredited bodies possessing in-house GC-MS laboratory capacity.
United States
FDA rules on imported food and medical device prior notice create documented verification demand at port of entry. EPA regulations intersect with state-level chemical disclosure requirements for consumer product imports. The Port of Long Beach processes inspection volume from Asia-Pacific manufacturing origins subject to multi-agency compliance protocols.
India
Pharmaceutical export corridors in Mumbai and Hyderabad generate specialized demand for GDP-trained inspection capacity. CDSCO serialization requirements and EU MDR conformity obligations accelerate inspector training investments. Gujarat's chemical manufacturing belt requires REACH-aligned documentation for European destination markets.
United Arab Emirates
Jebel Ali Port serves as transshipment hub where inspection documentation gets verified for Middle Eastern and African destination markets. MOHAP pharmaceutical import regulations mandate third-party cold chain verification. Dubai's logistics free zones concentrate inspection service providers serving re-export trade flows.
Global Pre-Shipment Inspection Market Competitive Environment
Concentration sits with diversified conformity assessment conglomerates that anchor multi-vertical service portfolios. The market structure tiers between global laboratory networks, specialized vertical specialists, and technology-enabled challengers. Three archetypes dominate: integrated testing-inspection-certification providers, sector-specific compliance specialists, and digital-first remote verification platforms. Competitive dynamics center on laboratory capacity expansion in manufacturing clusters and strategic partnerships with e-commerce platforms seeking embedded quality gates.
Within the integrated provider tier, SGS, Bureau Veritas, and Intertek Group exemplify scale-driven positioning across consumer goods and industrial verticals. These entities occupy positions anchored by geographic laboratory density and accreditation breadth. SGS represents the archetype of manufacturing-cluster proximity, Bureau Veritas exemplifies sector-specific protocol development, and Intertek Group sits within the digital platform integration vector. Their collective presence shapes procurement consolidation patterns among European retailers subject to CSRD disclosure mandates.
| Leading Market Players |
|---|
| SGS |
| Bureau Veritas |
| Intertek Group |
| DEKRA |
| Cotecna |
| TÜV SÜD |
| TÜV Rheinland |
| QIMA |
| Applus |
| Others |
Value Chain & Pricing Dynamics
Long-term capacity reservation contracts with accredited inspection bodies lock in laboratory access and cost predictability for European retailers facing CSRD disclosure mandates. These agreements tether pricing to inspector training pipelines and GC-MS equipment deployment schedules across manufacturing clusters.
Pricing Analysis
Volume-discount tiering structures stratify across premium, standard, and economy certification levels. Premium tiers capture EU MDR and GDP-trained pharmaceutical inspection with cold chain verification, while standard tiers handle routine consumer goods sampling under ISO 2859. Price differentiation rests on accreditation breadth and geographic laboratory density. Cost compression in remote inspection tiers is intensifying because camera-enabled platforms reduce travel-dependent overhead. E-commerce retailers and fast-fashion importers exhibit highest price sensitivity; pharmaceutical exporters demonstrate lowest sensitivity due to regulatory non-compliance penalties.
Supply Chain Analysis
Just-in-time inspector deployment dominates consumer goods verticals, while pharmaceutical exporters maintain strategic stockpiles of GDP-certified capacity at Mumbai and Hyderabad corridors. Geographic supply concentrates in China, India, and Germany, with laboratory infrastructure anchored in Dongguan manufacturing clusters, Mumbai pharmaceutical export zones, and Rhine-Ruhr industrial belt. Raw material dependencies include GC-MS equipment, cold chain monitoring sensors, and blockchain documentation platforms. Single-source vulnerability sits with specialized inspector talent pipelines that lag demand acceleration. Distribution runs through freight forwarder-arranged inspection for consolidated container loads and direct contracts with accredited bodies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among European retailers consolidating procurement with vertically integrated providers, fragmenting vendor selection to ISO/IEC 17020-accredited tier-one bodies.
For Market Incumbents: Fortify laboratory density in Chinese manufacturing clusters and Indian pharmaceutical corridors to defend against digital-first remote verification platforms. Expand in-house GC-MS capacity to capture EU REACH-mandated SVHC testing premiums. Certification investment in GDP and phytosanitary protocols anchors high-margin verticals. For New Entrants and Emerging Players: Anchor in remote inspection technology for e-commerce retailers and fast-fashion importers where regulatory equivalence uncertainty has slowed incumbent adoption. White-space targets include AI-augmented defect detection and carbon footprint verification integration for EU Green Deal compliance. Platform-as-a-service go-to-market angles bypass capital-intensive laboratory buildout. For Investors and Strategic Acquirers: Digital-first inspection platforms with blockchain-anchored documentation capabilities represent the priority acquisition archetype. Long-term viability hinges on permanent regulatory acceptance of remote protocols by FDA, EMA, and NMPA. Watch for CDSCO serialization requirement expansion in India as inflection indicator for pharmaceutical inspection demand.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Augmented Defect Detection Deployment | Machine vision systems compress report generation from days to hours for time-sensitive shipments. |
| GDP-Certified Inspector Training Expansion | CDSCO and EU MDR serialization requirements in India outpace current specialized talent pipelines. |
| Blockchain Documentation Platform Integration | Immutable inspection records reduce documentary fraud in agricultural and pharmaceutical exports. |
| Carbon Footprint Verification Service Launch | EU Green Deal border adjustment mechanisms extend inspection scope to embodied emissions documentation. |
| Remote Inspection Regulatory Equivalence Lobbying | Permanent FDA and EMA acceptance of camera-enabled protocols unlocks addressable demand expansion. |
Study Parameters
Desk research of customs trade databases, ISO/IEC accreditation registries, and ECHA substance restriction schedules preceded structured interviews with inspection body laboratory directors, pharmaceutical quality assurance heads, European retail ESG officers, and freight forwarder procurement managers. Primary fieldwork across manufacturing clusters in China, India, and Germany combined with secondary validation from SAMR enforcement bulletins and FDA prior notice guidance documents. Bottom-up service provider revenue estimates triangulated against top-down import volume projections.
Variance-decomposition framing separated volume growth drivers from pricing mix effects across the projection horizon. Segmentation dimensions modeled include service type, industry vertical, end user organizational type, and delivery model technology tier. CAGRs derived from inspection volume intensity per containerized trade dollar and accreditation expansion rates. Industry-specific forecast inputs encompass EU CSRD implementation timelines and CDSCO serialization rollout phases.
Material uncertainties — regulatory equivalence determinations by FDA, EMA, and NMPA, plus aviation capacity constraints affecting on-site inspector deployment — sit outside the modeled envelope. Forecasts reflect assumptions regarding permanent acceptance of remote inspection protocols and sustained REACH enforcement intensity. Revision becomes warranted when remote inspection regulatory equivalence crosses formal adoption thresholds in major destination markets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety & Security
Global Biometrics Middleware Market
Safety & Security
Europe Decentralized Identity Market
Safety & Security
Smart Helmet Market
Safety & Security
Global Emergency Medical Service (EMS) Products Market
Safety & Security
Latin America Surveillance Camera Market
Safety & Security
Smart Barrier Gate Market
Safety & Security
Padlock Smart Lock Market
Safety & Security
Research Department Explosive (RDX) Market
Safety & Security
Explosion Proof Devices Market
Safety & Security
Europe Home Security System Market
Safety & Security
North America Rockfall Radar Market
Safety & Security
Crime Risk Report Market
Safety & Security
Wireless Video Surveillance Market
Safety & Security
Africa Riot Control Equipment Market
Safety & Security
Europe Non-Lethal Weapons Market
Safety & Security
Airport Biometrics Market