
 Middle-East and Africa Anchors and Grouts Market | 2026-2036
Middle-East and Africa Anchors and Grouts Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Anchors and Grouts Market Foresight
Project finance tied to sovereign wealth-backed infrastructure programs is narrowing the competitive field to firms capable of bonding billion-dollar contracts. Sika AG leverages its integrated supply chain across cementitious and resin-based systems to secure specification on UAE transport megaprojects. MAPEI SpA anchors its position through localized blending facilities in Dubai Industrial City that reduce lead times for bulk grout orders. Saudi Vetonit Co. Ltd. dominates specification lists within Saudi Vision 2030 developments by aligning product certification with Saudi Standards, Metrology and Quality Organization requirements.
Anchors and grouts comprise mechanical fastening elements and cementitious or resinous fill materials engineered to bond structural loads to concrete, masonry, or rock substrates, typically achieving compressive strengths exceeding 50 MPa for structural grout applications. These products transfer tension, shear, and combined loads in commercial construction, tunnel linings, mining roof support, and offshore platform foundations. Chemical anchors now lead value generation across the product mix due to their superior performance in seismic and high-load conditions prevalent in Gulf skyscraper and bridge construction. The infrastructure application segment sustains the fastest trajectory as Egypt's New Administrative Capital, Nigeria's Lagos-Calabar coastal highway, and Morocco's high-speed rail extensions drive specification volume.
Saudi Standards, Metrology and Quality Organization mandates and UAE's Emirates Authority for Standardization and Metrology certification requirements are tightening product testing protocols for fire resistance and pull-out performance, effectively filtering out uncertified imports. South Africa's National Regulator for Compulsory Specifications enforces SANS-compliant structural fixings in public works, creating a dual-track market split between premium-certified and generic alternatives. Egypt's Housing and Building National Research Center is developing localized testing capacity that will reshape import dependency patterns. Stakeholders must monitor evolving conformity assessment timelines as these regulators expand scope from finished products to raw material traceability.
Market Dynamics
Sovereign wealth-backed infrastructure programs across the Gulf Cooperation Council are compressing supplier qualification timelines and favoring contractors with integrated product-service capabilities over pure material vendors.
Growth Catalysts
- Saudi Vision 2030 giga-projects:NEOM, the Red Sea Project, and Qiddiya entertainment city are generating concentrated demand for seismic-rated chemical anchoring systems in high-rise and bridge applications.
- Localization mandates:Saudi Standards, Metrology and Quality Organization certification requirements are redirecting procurement toward domestic manufacturing facilities.
- Epoxy vinyl ester resin technology:Advanced resin formulations are displacing traditional polyester systems in corrosive offshore platform environments.
Market Restraints
- Petrochemical feedstock volatility:Epoxy resin and hardener prices fluctuate with crude oil derivatives, compressing margin predictability for blended grout manufacturers.
- Import dependency for specialty additives:Curing agents and rheology modifiers concentrate supply in European and Asian chemical clusters, exposing Middle Eastern blenders to freight cost spikes.
- Fire resistance testing bottlenecks:Emirates Authority for Standardization and Metrology extended certification timelines are delaying product launches for non-structural fire-rated anchors.
Strategic Opportunities
- Nigeria's Lagos-Calabar coastal highway:This corridor project represents underpenetrated demand for bulk cementitious grouts in West African infrastructure.
- Egypt's New Administrative Capital:Massive concrete frame construction is creating specification volume for post-installed rebar connections and structural strengthening systems.
- Digital inventory integration:Contractor procurement platforms are enabling direct-to-site distribution that bypasses traditional distributor markups in UAE transport megaprojects.
Industry Challenges
- Specialized application engineering talent:Shortage of certified installers for high-load chemical anchors is constraining execution speed on Saudi giga-projects.
- Dual certification complexity:Products must simultaneously satisfy Saudi Building Code and project-specific international standards, extending technical documentation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Anchors and Grouts Market |
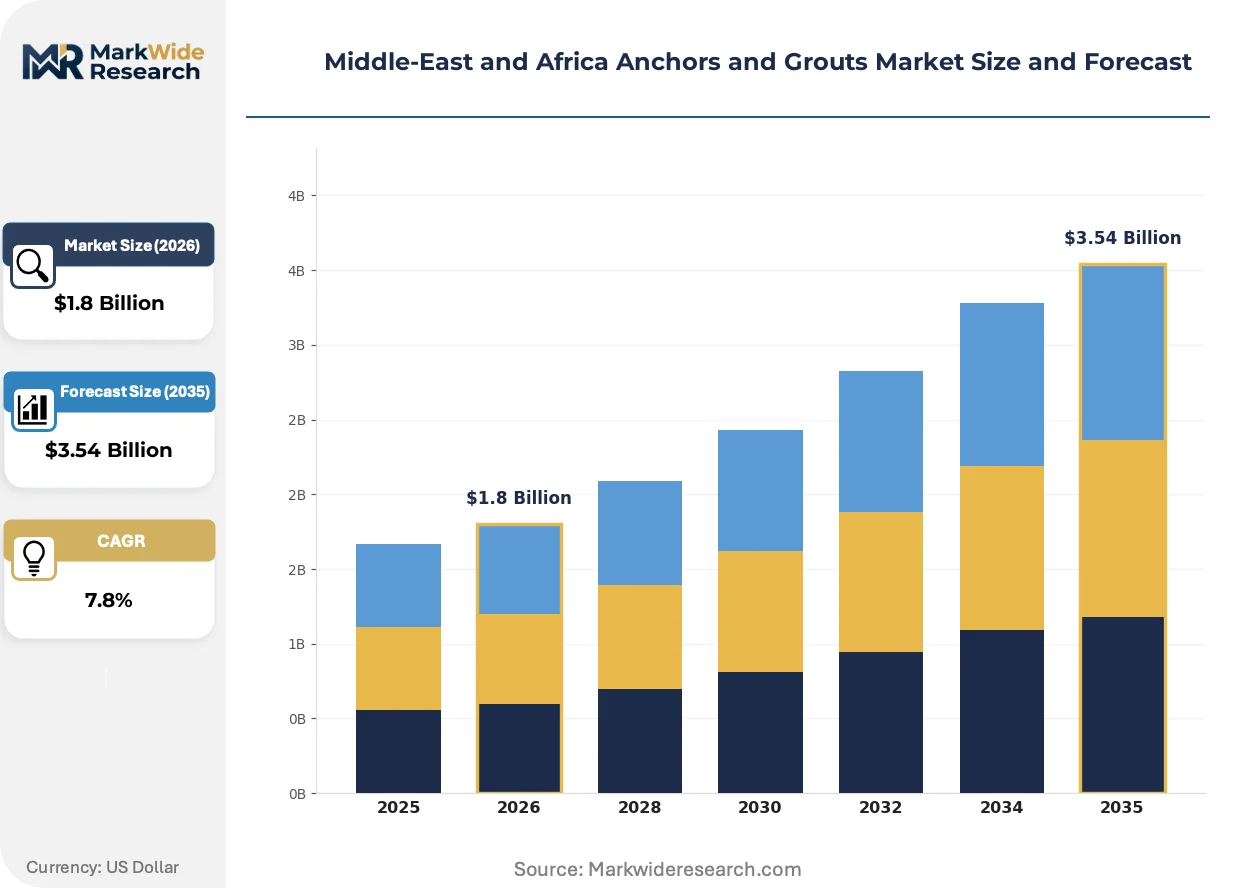
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.54 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Anchors, Chemical Anchors, Grout, Injection Grout Application: Construction, Infrastructure, Mining, Marine Delivery Mode: Chemical Delivery, Manual Application, Automated Dispensing, Bulk Delivery End User: Contractors, Civil Engineers, Government Agencies, Mining Companies |
| Companies Covered | Sika AG, MAPEI SpA, Saint-Gobain Weber, MBCC Group, Saudi Vetonit Co. Ltd., Bayshield International, LATICRETE Middle East LLC, Colmef Monneli, CIKO MIDDLE EAST, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Anchors and Grouts Market Shifts & Advancements
Product formulation priorities are pivoting toward performance-verified systems that reduce on-site variability, while regulatory frameworks increasingly mandate traceable supply chains from raw material through installation.
Hybrid epoxy-acrylate chemical anchors are migrating from pure epoxy systems in seismic zone applications. Saudi Aramco and NEOM contractors are specifying these compounds for their faster cure times in temperature-variable desert conditions. The technology is migrating from premium skyscraper projects toward standard commercial construction as price premiums compress.
Saudi Standards, Metrology and Quality Organization expanded its conformity assessment scope to include raw material traceability requirements. Manufacturers must now document resin and filler sourcing through certified supply chains. Cementitious grout producers serving Saudi Vision 2030 developments are restructuring supplier relationships to maintain specification eligibility.
Consolidated procurement through sovereign wealth fund project management offices is compressing vendor lists and extending contract durations. Single-source framework agreements now cover multi-year material supply across entire giga-project portfolios. This concentration is most visible in UAE transport infrastructure, where Etihad Rail and metro extensions bundle anchor and grout procurement with structural steel packages.
Middle-East and Africa Anchors and Grouts Market Segmentation
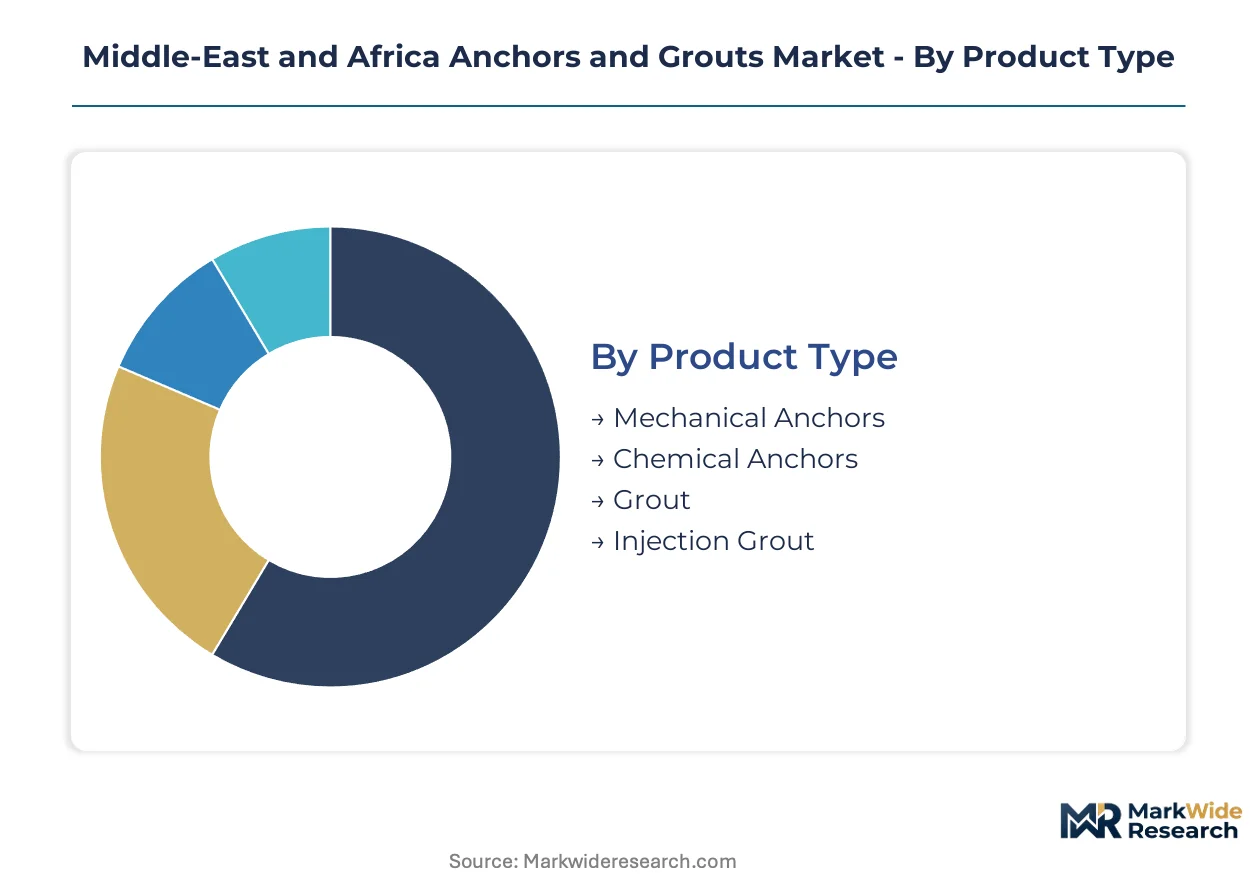
Segmentation in the Middle-East and Africa Anchors and Grouts Market reveals distinct procurement patterns across product technologies and project delivery models. Contractors in Saudi Arabia's giga-project corridor and Egypt's New Administrative Capital prioritize specification-grade systems that reduce on-site variability and accelerate certification timelines.
Product Type:
Mature mechanical systems coexist with rapidly advancing chemical formulations across Gulf Cooperation Council infrastructure programs.
- Chemical Anchors:Epoxy-acrylate and pure epoxy resin systems bond structural loads to concrete substrates with superior pull-out resistance in seismic conditions. Saudi Vision 2030 developments specify these compounds for high-rise steel connections and bridge bearings, displacing traditional mechanical alternatives in load-critical applications.
- Grout:Cementitious and resin-based fill materials achieve compressive strengths exceeding 50 MPa for structural load transfer. Bulk orders from UAE transport megaprojects and Egypt's concrete frame construction dominate procurement volume, with localized blending facilities reducing lead times for major contractors.
- Mechanical Anchors:Expansion and undercut anchors serve standard commercial construction with established installation protocols and lower material cost bases.
- Injection Grout:Low-viscosity formulations penetrate micro-cracks in tunnel linings and masonry restoration, finding specialized demand in Morocco's high-speed rail extensions and South African mining infrastructure.
Chemical anchors retain volume leadership; injection grout holds the steepest expansion curve.
Application:
Cost tier differentiation separates sovereign wealth-funded megaprojects from fragmented commercial construction across the region.
- Infrastructure:Bridge bearings, tunnel linings, and rail foundations require seismic-rated anchoring systems with documented fire resistance. Nigeria's Lagos-Calabar coastal highway and Morocco's high-speed rail extensions are generating concentrated specification volume for cementitious bulk grouts.
- Construction:Commercial and residential buildings utilize post-installed rebar connections and structural strengthening systems. Egypt's New Administrative Capital concrete frame construction is creating sustained demand for specification-grade chemical anchors in high-rise applications.
- Mining:Roof support systems and rock stabilization in South African and West African operations demand rapid-curing resin anchors for operational continuity.
- Marine:Offshore platform foundations in Red Sea developments specify epoxy vinyl ester systems for corrosion resistance in saltwater environments.
Infrastructure commands premium pricing tiers; construction maintains the broadest addressable base.
Delivery Mode:
Customer type segmentation tracks procurement centralization through sovereign wealth fund project management offices versus fragmented distributor networks.
- Bulk Delivery:Tanker and silo-based supply of cementitious grouts serves continuous pour operations on megaproject sites. Etihad Rail and Saudi giga-project contractors specify this mode for cost efficiency at scale.
- Automated Dispensing:Metered mixing systems reduce resin waste and cure time variability on high-load chemical anchor installations. NEOM contractors are piloting this technology for quality assurance in temperature-variable desert conditions.
- Manual Application:Cartridge-based systems dominate standard commercial construction with lower equipment investment requirements.
- Chemical Delivery:Two-component injection systems serve specialized repair and strengthening applications with precise ratio control.
Bulk delivery retains volume leadership; automated dispensing holds the steepest expansion curve.
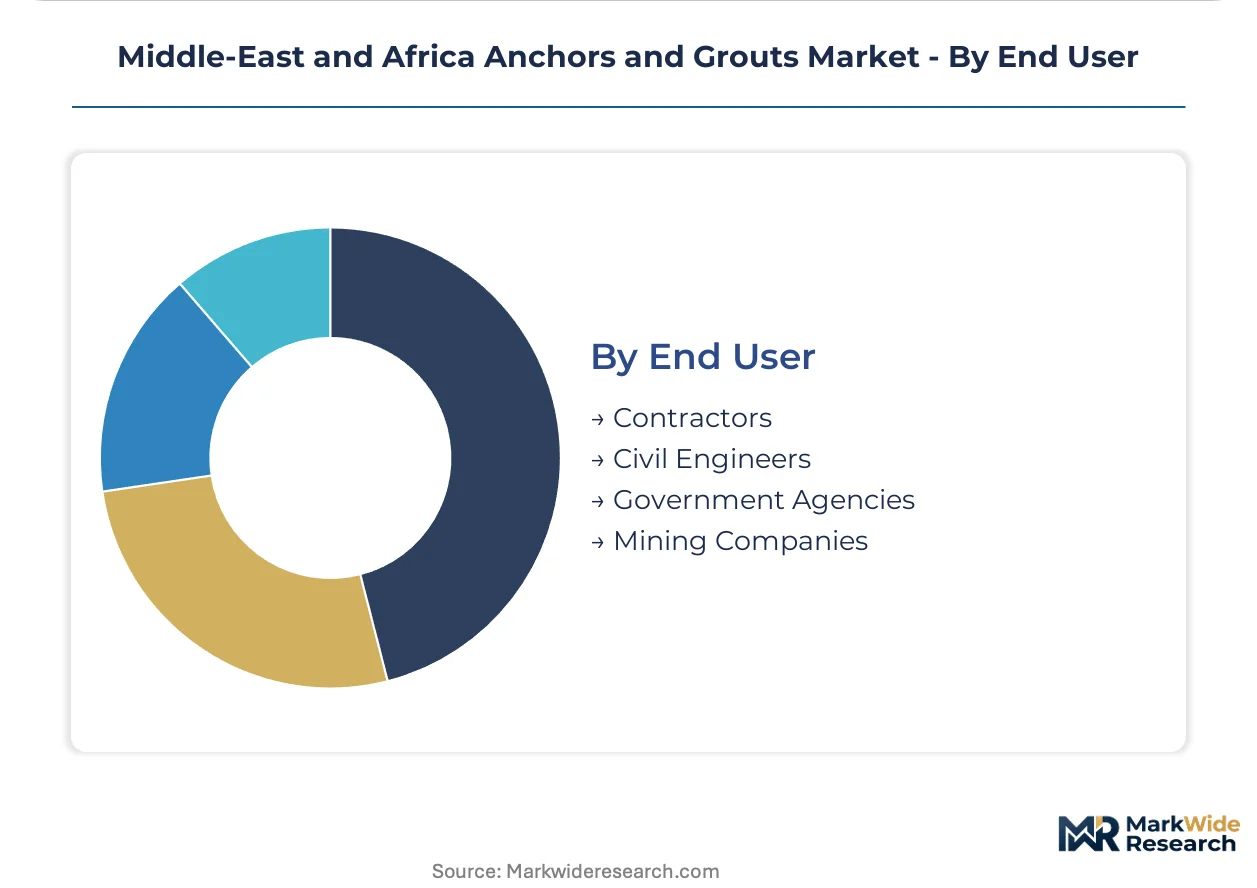
End User:
Geography concentrates demand in Saudi Arabia's giga-project corridor while Egypt and Nigeria emerge as volume growth nodes.
- Contractors:Megaproject general contractors and specialty subcontractors execute bonded billion-dollar contracts requiring integrated product-service capabilities. SABIC-driven localization mandates are redirecting procurement toward domestic manufacturing partnerships.
- Civil Engineers:Design consultants specify performance-verified systems with Saudi Standards, Metrology and Quality Organization or Emirates Authority for Standardization and Metrology certification for structural safety compliance.
- Government Agencies:Public works departments in South Africa enforce National Regulator for Compulsory Specifications compliance, creating dual-track market dynamics between premium-certified and generic alternatives.
- Mining Companies:Operational procurement teams prioritize rapid-curing systems that minimize stoppage time in extraction environments.
Contractors retain volume leadership; civil engineers hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency for specialty resins and curing agents defines trade flows across the region, while domestic blending capacity expansion in Saudi Arabia and the UAE is gradually reducing reliance on European and Asian chemical clusters for finished grout formulations.
Saudi Arabia
NEOM, the Red Sea Project, and Qiddiya entertainment city drive concentrated demand for seismic-rated chemical anchoring systems in high-rise steel connections. Saudi Standards, Metrology and Quality Organization mandates now require raw material traceability documentation from resin suppliers. The Eastern Province industrial corridor hosts expanding domestic manufacturing facilities serving SABIC-driven localization requirements.
United Arab Emirates
Etihad Rail extensions and metro megaprojects generate bulk cementitious grout procurement bundled with structural steel packages. Emirates Authority for Standardization and Metrology certification timelines for fire-rated anchors have extended, filtering product launches. Dubai Industrial City clusters localized blending operations that reduce lead times for major transport contractors.
Egypt
New Administrative Capital concrete frame construction creates sustained specification volume for post-installed rebar connections and structural strengthening systems. The Housing and Building National Research Center is developing localized testing capacity that will reshape import dependency patterns. Greater Cairo construction corridors concentrate demand for specification-grade chemical anchors in high-rise applications.
South Africa
Mining roof support systems in extraction environments demand rapid-curing resin anchors for operational continuity. The National Regulator for Compulsory Specifications enforces SANS-compliant structural fixings in public works, creating dual-track market dynamics. Johannesburg-Pretoria industrial clusters serve as distribution hubs for certified premium products versus generic alternatives.
Nigeria
Lagos-Calabar coastal highway corridor construction represents underpenetrated demand for bulk cementitious grouts in West African infrastructure. Federal Ministry of Works procurement protocols are gradually tightening material certification requirements. Lagos-Ibadan expressway construction zones concentrate early-phase anchor and grout specification activity.
Middle-East and Africa Anchors and Grouts Market Competitive Landscape
On the supply side, the industry is consolidating around integrated product-service capabilities rather than pure material vendors, with sovereign wealth-backed procurement offices compressing vendor lists into multi-year framework agreements. Three archetypes dominate: Swiss and Italian multinational specialists with regional blending networks, Saudi-domestic manufacturers leveraging localization mandates, and regional distributors with project-specific engineering support. Competitive moves center on backward integration into resin formulation and strategic partnerships with giga-project management offices.
Among European-headquartered specialists, Sika AG and MAPEI SpA exemplify the integrated supply chain archetype across cementitious and resin-based systems. Saudi Vetonit Co. Ltd. occupies a position within the domestic manufacturing tier, aligning product certification with Saudi Standards, Metrology and Quality Organization requirements. LATICRETE Middle East LLC represents the regional specialist model with localized blending facilities.
| Leading Market Players |
|---|
| Sika AG |
| MAPEI SpA |
| Saint-Gobain Weber |
| MBCC Group |
| Saudi Vetonit Co. Ltd. |
| Bayshield International |
| LATICRETE Middle East LLC |
| Colmef Monneli |
| CIKO MIDDLE EAST |
| Others |
Supply & Pricing Matrix
European resin and curing agent suppliers anchor the upstream cost structure, concentrating formulation margin pools with Gulf-based blenders who command specification premiums on Saudi Vision 2030 developments. This dependency creates asymmetric pricing power where feedstock volatility transmits rapidly through finished grout pricing while localization mandates compress import arbitrage opportunities.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure that bundles material supply with technical service across multi-year framework agreements. Price differentiation separates Saudi Standards, Metrology and Quality Organization-certified premium tiers from uncertified generic alternatives, with volume scale and after-sales engineering support as secondary drivers. Cost compression in standard commercial construction is intensifying because petrochemical feedstock volatility erodes blender margin predictability. Small-scale contractors in fragmented West African markets exhibit highest price sensitivity, while sovereign wealth-backed megaproject procurement offices prioritize certification compliance over unit cost.
Supply Chain Analysis
Extended payment terms through supply-chain finance facilities have become standard for major contractors bonding billion-dollar Saudi giga-project contracts, stretching working capital requirements for mid-tier blenders. Geographic supply concentration centers on Germany, Switzerland, and Italy for specialty epoxy resin formulations, with Saudi Arabia and the UAE expanding domestic blending capacity for cementitious systems. Raw material dependencies rest on epoxy resins, vinyl ester compounds, and rheology modifiers sourced from European chemical clusters. Single-source vulnerability in curing agent supply exposes regional manufacturers to freight cost spikes. Distribution runs through sovereign wealth fund project management offices that consolidate procurement across entire giga-project portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where digital procurement platforms are consolidating contractor-vendor relationships and enabling direct-to-site distribution that bypasses traditional distributor networks.
For Market Incumbents: Pre-empt specification displacement by hybrid epoxy-acrylate systems through accelerated certification investment with Saudi Standards, Metrology and Quality Organization and Emirates Authority for Standardization and Metrology. Backward integration into captive resin formulation capacity in the Eastern Province industrial corridor defends margin position against petrochemical feedstock volatility. Lock in multi-year framework agreements with NEOM and Red Sea Project management offices before procurement centralization further compresses vendor lists.
For New Entrants and Emerging Players: Nigeria's Lagos-Calabar coastal highway corridor offers the most penetrable infrastructure demand node for bulk cementitious grout supply, with Federal Ministry of Works procurement protocols still accommodating new certification pathways. Egypt's New Administrative Capital concrete frame construction presents secondary white-space for post-installed rebar connection systems as localized testing capacity develops. A technical partnership with established regional distributors provides the fastest go-to-market angle for navigating dual certification complexity.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with European-headquartered specialists holding regional blending networks but limited Gulf giga-project penetration. Five-to-ten year viability favors acquisition targets with Saudi domestic manufacturing footprints and Saudi Standards, Metrology and Quality Organization certification pipelines already established. Watch for inflection in Egypt's Housing and Building National Research Center testing capacity expansion as the signal for import dependency restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Formulation | Captive epoxy production in Saudi Arabia's Eastern Province insulates margin from European feedstock volatility. |
| Saudi Standards Certification Investment | Raw material traceability documentation secures eligibility for SABIC-driven localization mandates on giga-projects. |
| Digital Procurement Platform Integration | Direct-to-site distribution through contractor platforms bypasses traditional distributor markups in UAE transport megaprojects. |
| Hybrid Epoxy-Acrylate Capacity Expansion | Faster-cure systems capture seismic-rated specification volume as NEOM contractors migrate from pure epoxy compounds. |
| West African Distribution Partnership | Local blending presence in Nigeria addresses Federal Ministry of Works procurement for Lagos-Calabar highway construction. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs and trade data, Saudi Standards, Metrology and Quality Organization certification registries, and Emirates Authority for Standardization and Metrology filings. Primary interviews engaged procurement directors at megaproject contractors, technical sales leads at regional blending facilities, and civil engineering consultants specifying structural anchoring systems. Secondary validation drew from construction project databases, sovereign wealth fund procurement disclosures, and chemical industry feedstock price indices. Bottom-up demand modeling across product types and applications triangulated against top-down market sizing from regional production capacity assessments.
Forecast inputs include modeled segmentation across chemical anchor, grout, mechanical anchor, and injection grout product types; infrastructure, construction, mining, and marine applications; and bulk delivery, automated dispensing, manual application, and chemical delivery modes. The projection horizon incorporates cement consumption patterns in Egypt's New Administrative Capital, rail extension timelines for Etihad Rail, and offshore platform development schedules in Red Sea developments. CAGRs derive from regression analysis of historical specification volumes against construction value-added indicators and petrochemical feedstock cost trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Saudi-domestic manufacturers or accelerated certification timeline compression by regulators would shift outcomes. Macroeconomic deviation in oil price trajectories, regulatory scope expansion to raw material traceability, or breakthrough displacement of epoxy systems by alternative chemistries would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Used Backhoe Market
Construction Equipment
Asia-Pacific Completion Equipment and Services Market
Construction Equipment
Cable Winches Market
Construction Equipment
Philippines Construction Equipment Market
Construction Equipment
Europe Road Marking Machine Market
Construction Equipment
Truck Mounted Concrete Pump Market
Construction Equipment
South Korea Aerial Work Platform (AWP) Rental Market
Construction Equipment
Multi Attachment Loaders Market
Construction Equipment
China Fire Sprinklers Market
Construction Equipment
Cranes Rental Market
Construction Equipment
Europe Multi Attachment Loaders Market
Construction Equipment
Road Marking Equipment Market
Construction Equipment
Rotary Trommel Market
Construction Equipment
Welding and Cutting Equipment Market
Construction Equipment
Construction Equipment Market
Construction Equipment
India Construction Equipment Rental Market