
 Road Marking Equipment Market | 2026-2036
Road Marking Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Road Marking Equipment Market Insights
The capital-intensity divergence between automated machine specialists and manual equipment vendors is reorganizing competitive dynamics in road marking equipment. Graco Inc leverages its precision spray technology leadership to dominate North American highway contracts. Hofmann anchors European demand through its thermoplastic application systems engineered for dense urban networks. Borum A/S sustains its position via integrated manufacturing of self-propelled marking machines with extended operational ranges.
Road marking equipment comprises mobile machinery and handheld tools that apply retroreflective materials—thermoplastic compounds melting at 180–220°C, preformed tapes with embedded glass beads, or waterborne acrylic resins—to paved surfaces for traffic guidance and safety delineation. Thermoplastic application systems command the largest installed base among product types due to durability advantages on high-traffic corridors, while waterborne formulations are displacing solvent-based alternatives as environmental compliance tightens. Automated machine technology captures the fastest expansion trajectory as municipalities and contractors prioritize lane-closure minimization and application speed over manual methods.
EPA emissions standards and OSHA workplace exposure limits constrain solvent-based product viability in the United States, while REACH chemical restrictions and CE machinery directives govern European equipment certification and material composition. China's GB standards and MEE environmental enforcement are elevating domestic requirements for low-VOC road marking systems. Stakeholders must monitor regulatory divergence between jurisdictions to align R&D portfolios with diverging compliance timelines rather than assuming harmonization.
Market Dynamics
Automated machine technology is compressing lane-closure windows on high-traffic corridors, forcing contractors to retire manual spray systems faster than depreciation schedules allow. This capital-refresh cycle is redistributing market position toward precision-engineering specialists and away from legacy equipment lessors.
Growth Catalysts
- EU Green Deal implementation:The framework mandates low-VOC road marking systems across member states, accelerating waterborne acrylic substitution for solvent-based formulations on federal highway programs.
- Thermoplastic durability requirements:State transport departments in high-traffic corridors specify 180–220°C application systems for lane markings requiring three-year minimum retroreflectivity retention.
- China:Provincial transport bureaus are modernizing urban road networks at scale, concentrating demand for self-propelled marking machines with extended operational ranges.
Market Restraints
- Petroleum-based binder volatility:Thermoplastic compound feedstock costs fluctuate with crude indices, squeezing contractor margins on fixed-price municipal contracts.
- Equipment supply concentration:Automated machine manufacturing clusters in Northern Europe and the Upper Midwest, creating lead-time vulnerability for contractors in emerging markets.
- REACH chemical restrictions:ECHA substance evaluations are constraining legacy additive packages, forcing premature formulation obsolescence for inventory-heavy distributors.
Strategic Opportunities
- India:National highway expansion under the Bharatmala program remains underpenetrated by automated application technology, creating first-mover positioning for precision-spray system vendors.
- Preformed tape convergence:Embedded glass-bead technology combined with pressure-sensitive adhesives is opening airport tarmac and temporary work-zone applications previously served by liquid systems.
- MEE enforcement escalation:China's Ministry of Ecology and Environment is tightening VOC discharge permits, elevating compliance-grade equipment demand above commodity replacement cycles.
Industry Challenges
- Thermoplastic applicator technician scarcity:Skilled operators capable of calibrating 180–220°C melt kettles and maintaining spray uniformity are retiring faster than vocational programs replace them.
- CE machinery directive recertification:Revised safety standards for self-propelled equipment are compressing product development timelines and requiring redundant engineering validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Road Marking Equipment Market |
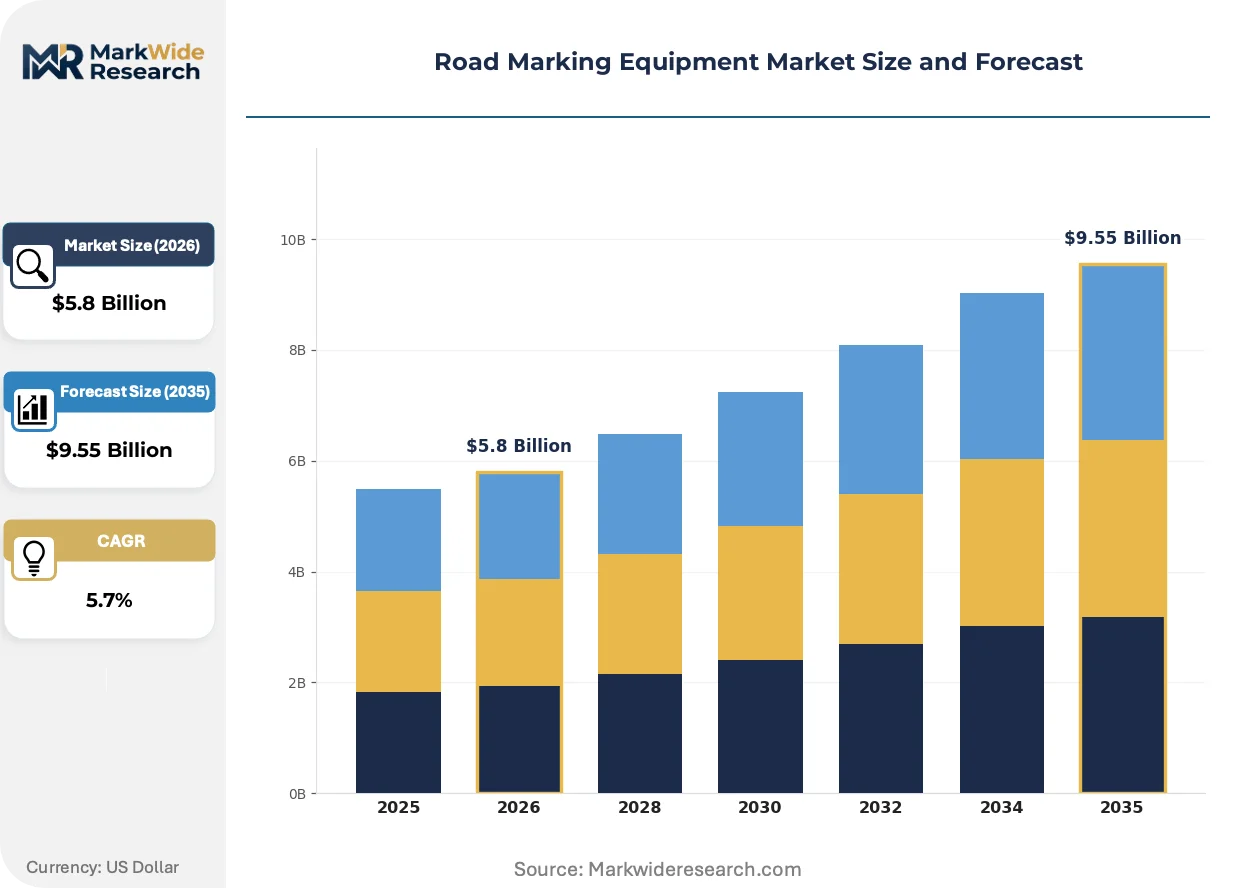
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoplastic, Preformed Tape, Waterborne, Solvent-based Application: Highways, Airports, Parking Lots, Urban Roads End User: Government Agencies, Contractors, Municipalities, Private Sector Technology: Manual Application, Automated Machines, Laser Technology, Spray Techniques |
| Companies Covered | Graco Inc, Borum A/S, Hofmann, TATU Group, STiM Group, RME Road Marking Equipment, Automark Industries (India) Pvt Ltd, Vogel Traffic Services, M-B Companies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Road Marking Equipment Market Trends and Innovations
Retroreflective material formulation is splitting into performance-optimized and compliance-minimum tracks, with equipment architecture following divergent paths. This schism is rewriting vendor R&D priorities and distributor stocking strategies simultaneously.
Waterborne acrylic resin technology is bifurcating the installed base of application equipment. Municipal fleet managers in Germany and the United States are specifying low-VOC-compatible spray systems on new procurements, while solvent-capable legacy machines face accelerated obsolescence. The technology is compressing secondary market residual values and forcing rental fleet operators into premature capital redeployment.
REACH chemical restrictions and EPA emissions standards are tightening in parallel, eliminating cross-Atlantic regulatory arbitrage for formulation suppliers. Equipment vendors must now engineer for dual-jurisdiction compliance from prototype stage, raising development overhead. Thermoplastic application systems face less friction than waterborne alternatives, as their high-temperature process sidesteps many VOC constraints.
Contractor procurement is consolidating around performance-guarantee contracts rather than equipment ownership. Large infrastructure funds in Australia and Canada now lease integrated marking systems with bundled material supply and retroreflectivity warranties. This shift transfers technical risk to OEMs and compresses distributor margins on standalone machine sales.
Road Marking Equipment Market Segmentation
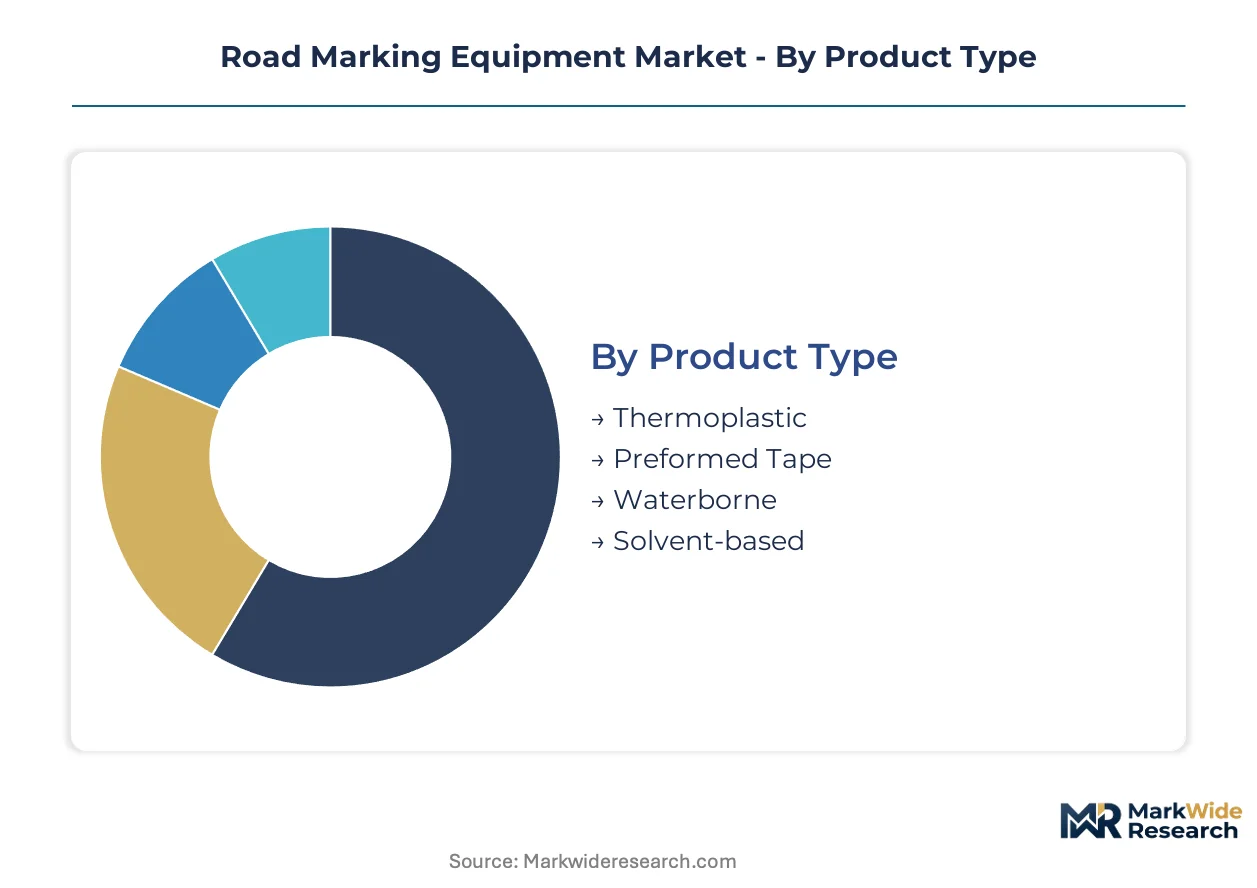
Road marking equipment procurement diverges sharply by institutional buyer type and regulatory environment. Segmentation reveals where capital deployment concentrates and which technology pathways face obsolescence pressure.
Product Type:
Thermoplastic systems dominate domestic highway programs across Germany and the United States, while waterborne formulations capture export-led growth into Asian markets facing VOC enforcement.
- Thermoplastic:These systems apply compounds at 180–220°C through heated melt kettles, producing lane markings with three-year minimum retroreflectivity retention. State transport departments in high-traffic U.S. corridors specify thermoplastic for federal highway contracts, though petroleum-based binder costs fluctuate with crude indices and squeeze contractor margins on fixed-price municipal agreements.
- Waterborne:Acrylic resin formulations displace solvent-based alternatives as EPA emissions standards and EU Green Deal mandates tighten. Municipal fleet managers in Germany and the United States now specify low-VOC-compatible spray systems on new procurements, accelerating obsolescence of solvent-capable legacy machines.
- Preformed Tape:Embedded glass-bead technology combined with pressure-sensitive adhesives serves airport tarmac and temporary work-zone applications.
- Solvent-based:REACH chemical restrictions and OSHA workplace exposure limits constrain viability in regulated jurisdictions.
Thermoplastic commands the established base. The steepest expansion runs through waterborne systems.
Application:
Highway contracts absorb the heaviest equipment investment, while parking lot and urban road segments fragment across smaller contractor bases with diverging specification standards.
- Highways:Federal programs demand automated application systems that compress lane-closure windows on high-traffic corridors. Contractors face capital-refresh cycles faster than depreciation schedules allow, redistributing position toward precision-engineering specialists.
- Urban Roads:Dense network maintenance in European cities favors thermoplastic systems engineered for frequent intersection restriping. Hofmann anchors European demand through application systems purpose-built for constrained urban geometries.
- Airports:Preformed tape convergence with embedded glass-bead technology opens tarmac applications requiring rapid curing and minimal operational disruption.
- Parking Lots:Smaller-scale projects tolerate manual spray methods, though automated machines gain share where facility managers bundle marking with sealcoating contracts.
Highways concentrate the premium equipment base. Urban roads generate the most fragmented procurement patterns.
End User:
Government agencies drive specification standards through federal highway programs, while contractors and municipalities diverge on ownership versus leasing models.
- Government Agencies:Federal and state transport departments in Germany and the United States set material specifications and equipment performance standards. The EU Green Deal and EPA emissions frameworks flow through agency procurement mandates, accelerating technology substitution.
- Contractors:Large infrastructure funds in Australia and Canada now lease integrated marking systems with bundled material supply and retroreflectivity warranties, transferring technical risk to OEMs and compressing distributor margins on standalone machine sales.
- Municipalities:Urban fleet managers balance equipment utilization rates against seasonal demand peaks, favoring rental arrangements for specialized application systems.
- Private Sector:Commercial parking and industrial facility operators prioritize lowest-first-cost solutions, sustaining residual demand for manual equipment.
Government agencies anchor specification authority. Contractors are shifting fastest toward outcome-based procurement.
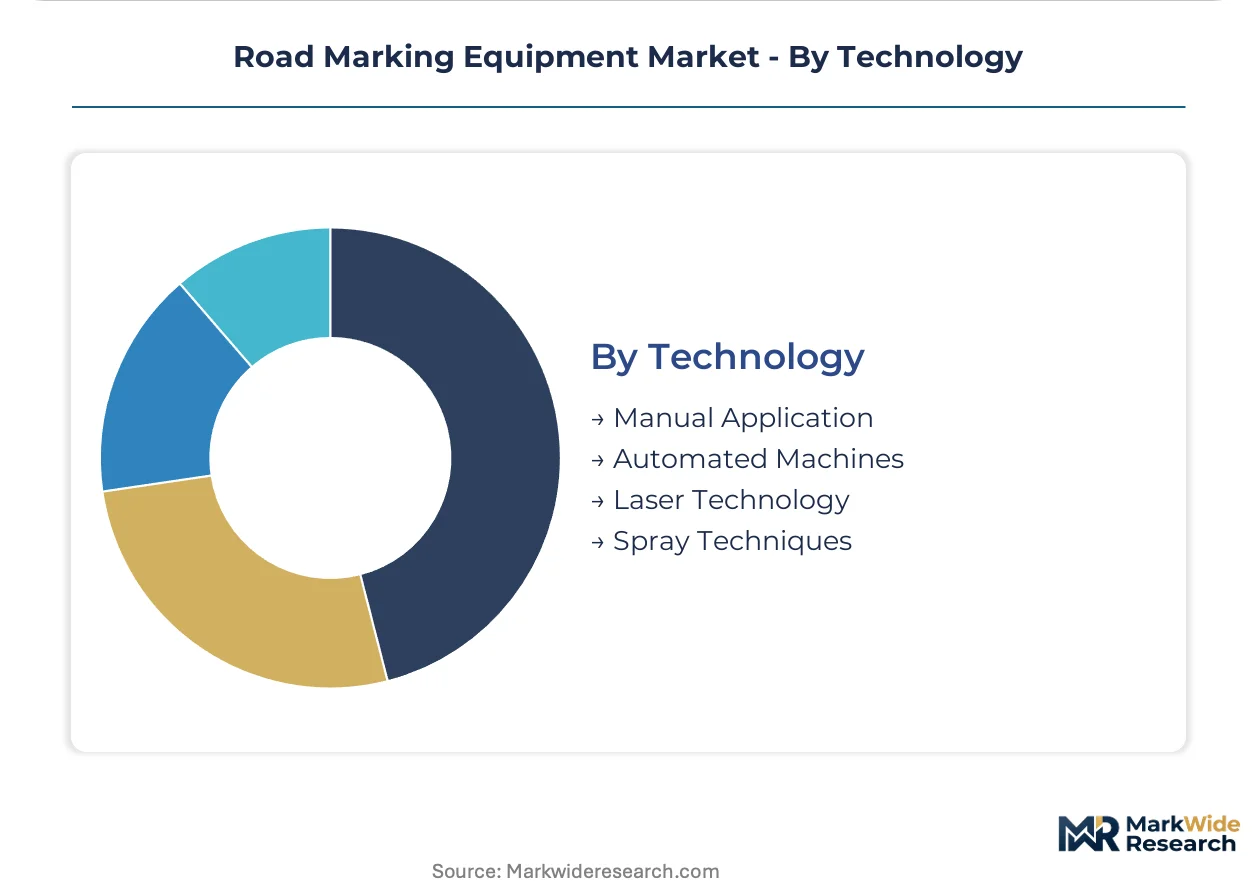
Technology:
Automated machine manufacturing clusters in Northern Europe and the Upper Midwest, creating lead-time vulnerability for contractors in emerging markets while manual methods persist where labor costs permit.
- Automated Machines:Self-propelled marking machines with extended operational ranges command the fastest expansion trajectory as municipalities prioritize lane-closure minimization. Borum A/S sustains position through integrated manufacturing of these systems.
- Manual Application:Handheld spray systems face accelerated retirement where automated alternatives prove cost-effective on lifecycle basis, though technician scarcity for 180–220°C melt kettle operation constrains thermoplastic deployment.
- Laser Technology:Precision guidance systems integrate with automated platforms for complex intersection geometries and premarking applications.
- Spray Techniques:Graco Inc leverages precision spray technology leadership to dominate North American highway contracts through engineered nozzle and pump systems.
Automated machines gain share fastest. Manual application retains residual position where capital constraints dominate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with German precision-engineering clusters while Chinese provincial transport bureaus drive volume absorption at compressed margins. Equipment procurement in the United States commands premium specifications through federal highway programs. Emerging market contractors face lead-time vulnerability from concentrated Northern European manufacturing.
United States
Federal highway programs specify automated thermoplastic systems for high-traffic corridors. EPA emissions standards and OSHA workplace exposure limits constrain solvent-based equipment viability. State transport departments in Texas and California anchor demand for precision spray technology through multi-year infrastructure contracts.
Germany
Dense urban networks require thermoplastic systems engineered for frequent intersection restriping. EU Green Deal mandates accelerate waterborne acrylic substitution across federal highway programs. Manufacturing clusters in Bavaria and Baden-Württemberg supply precision-engineered application systems to domestic and export markets.
China
Provincial transport bureaus modernize urban road networks at unprecedented scale. MEE environmental enforcement tightens VOC discharge permits, elevating compliance-grade equipment requirements. Yangtze River Delta municipalities concentrate procurement for self-propelled marking machines with extended operational ranges.
India
National highway expansion under the Bharatmala program remains underpenetrated by automated application technology. BIS standards and CDSCO equipment certification govern import and domestic manufacturing requirements. Gujarat and Maharashtra state highway authorities generate concentrated demand for thermoplastic durability on high-traffic corridors.
Australia
Large infrastructure funds lease integrated marking systems with bundled material supply and retroreflectivity warranties. TGA-equivalent equipment safety standards align with CE machinery directives for import certification. Queensland and New South Wales transport authorities prioritize lane-closure minimization through automated procurement.
Road Marking Equipment Market Competitive Landscape
Concentration sits with precision-engineering specialists and integrated self-propelled machine manufacturers. The vendor base splits between automated system architects and legacy manual equipment lessors facing accelerated obsolescence. Three archetypes dominate: thermoplastic application specialists, waterborne spray technology leaders, and integrated manufacturing-scale producers. Competitive moves center on strategic partnerships for emerging market distribution and portfolio diversification into preformed tape convergence.
Among Northern European fabricators, Borum A/S and Hofmann exemplify the integrated manufacturing archetype through self-propelled system production. Graco Inc anchors North American positioning through precision spray technology leadership. These three occupy the premium-tier vector where federal highway specifications concentrate procurement authority and compress distributor margins on standalone sales.
| Leading Market Players |
|---|
| Graco Inc |
| Borum A/S |
| Hofmann |
| TATU Group |
| STiM Group |
| RME Road Marking Equipment |
| Automark Industries (India) Pvt Ltd |
| Vogel Traffic Services |
| M-B Companies |
| Others |
Pricing and Supply Chain Analysis
Fourteen-to-eighteen-week lead times for automated thermoplastic systems from Northern European fabricators concentrate pricing power with integrated manufacturers while compressing contractor margins on fixed-price municipal awards. This inventory-to-delivery gap amplifies cost pass-through volatility for petroleum-based binder feedstocks and shapes procurement behavior toward bundled leasing arrangements.
Pricing Analysis
The customization-premium spread separates configured-to-order automated machines from standard manual spray systems by a factor driven by CE machinery directive certification tiers and after-sales service bundling. Project-based contract pricing dominates federal highway programs, though large infrastructure funds in Australia and Canada now favor outcome-based leasing with retroreflectivity warranties. Cost compression in the manual equipment tier intensifies as rental fleet operators face accelerated obsolescence of solvent-capable legacy machines. Municipalities exhibit highest price sensitivity due to seasonal utilization constraints, while federal transport departments absorb premium specifications with lower elasticity.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg port corridors fluctuate with container availability on Asia-Europe trade lanes, elevating landed costs for Chinese-sourced glass beads and Korean pressure-sensitive adhesive components. Manufacturing gravity centers on Germany, Denmark, and the United States Upper Midwest for precision-engineered application systems. Raw material dependencies encompass petroleum-derived thermoplastic binders, titanium dioxide pigments, and embedded glass bead retroreflective media. Single-source vulnerability concentrates in automated machine control systems sourced from Northern European electronics clusters. Distribution runs through authorized dealer networks with factory-trained service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Road marking equipment sits in early-cycle expansion as automated machine adoption penetrates highway programs previously served by manual methods, with VOC regulatory enforcement accelerating fleet refresh timelines beyond standard depreciation schedules.
For Market Incumbents: Shield installed base position by deepening backward integration into melt kettle fabrication and glass bead supply agreements. Prioritize CE machinery directive recertification investment ahead of revised safety standards. Counter emerging Asian equipment vendors through channel control of aftermarket parts distribution in North American federal highway corridors.
For New Entrants and Emerging Players: CE marking fast-track through notified body partnerships in Germany opens European federal program access before full type-approval completion. Target India's Bharatmala highway expansion with thermoplastic durability specifications unmatched by local manual equipment vendors. Pursue joint venture positioning with provincial transport bureaus in China's Yangtze River Delta for compliance-grade equipment demand.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because VOC enforcement trajectories in North America, Europe, and China are structurally elevating equipment replacement cycles independent of traffic volume growth. Acquisition focus should center on precision-spray technology specialists with EPA and MEE certification portfolios. Monitor MEE permit enforcement escalation as the signal for accelerated Chinese market premiumization.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Melt Kettle Manufacturing | Captive production of 180–220°C application systems reduces lead-time exposure for Borum A/S and Hofmann. |
| CE Machinery Directive Recertification | Early compliance with revised safety standards for self-propelled equipment secures German federal highway eligibility. |
| Waterborne Spray System Portfolio Expansion | Low-VOC-compatible machine lines align with EU Green Deal procurement mandates across member state transport departments. |
| Preformed Tape Technology Convergence | Embedded glass-bead pressure-sensitive adhesives open airport tarmac applications previously served by liquid thermoplastic systems. |
| Outcome-Based Leasing Model Deployment | Integrated marking systems with bundled material supply and retroreflectivity warranties transfer technical risk from contractors to OEMs. |
Research Methodology
Cross-validation between equipment procurement databases and regulatory filing records anchors the qualitative findings on technology substitution trajectories. Primary interviews with state transport department specification engineers, municipal fleet managers, thermoplastic applicator technicians, and OEM distribution channel heads combined with secondary validation through EPA emissions enforcement data, ECHA substance evaluation registers, and MEE VOC discharge permit records. Bottom-up triangulation across contractor equipment ownership surveys and top-down reconciliation against federal highway program expenditure reports ensures segmentation integrity.
Sensitivity analysis on petroleum-based binder cost indices and automated machine adoption curves tests forecast robustness across the projection horizon. The analytical framework models equipment demand by product type, application segment, technology tier, and end-user procurement model, with additional dimensioning by regional regulatory cluster alignment. CAGRs derive from equipment replacement cycle analysis and penetration rate modeling for automated systems. Industry-specific inputs include thermoplastic durability specification adherence rates and waterborne formulation displacement curves under tightening VOC constraints.
Decision-makers should treat outputs as directional under base assumptions of sustained federal highway program funding and progressive VOC enforcement escalation; material deviation in crude price volatility or regulatory delay would warrant model refresh. Practitioners should keep alternative scenarios live as MEE enforcement intensity and EU Green Deal implementation timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Hydraulic Shearing Machine Market
Construction Equipment
Solid Control Equipment Market
Construction Equipment
Global Mobile Concrete Mixer Market
Construction Equipment
Americas Hydraulic Submersible Pumps Market
Construction Equipment
Boom Lifts Market
Construction Equipment
Press Fit Machines Market
Construction Equipment
Autonomous Construction Equipment Market
Construction Equipment
Yard Crane Market
Construction Equipment
US Welding Consumables Market
Construction Equipment
Global Industrial Parts Washer Market
Construction Equipment
Fully Automatic Metal Band Saw Machine Market
Construction Equipment
Stud Welding Guns Market
Construction Equipment
Hydraulic Breaker for Excavator Market
Construction Equipment
Global Crane and Hoist Market
Construction Equipment
Australia Concrete Pump Market
Construction Equipment
Mill Pulverizer Market