
 Truck Mounted Concrete Pump Market | 2026-2036
Truck Mounted Concrete Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Truck Mounted Concrete Pump Market Analysis
Telematics-enabled fleet management is decoupling hardware sales from pure equipment transactions across the truck mounted concrete pump sector. SANY Heavy Industry leverages its integrated telematics platform to sustain aftermarket revenue streams beyond initial unit sales. Zoomlion Heavy Industry anchors its competitive stance through vertical control over hydraulic component production. Putzmeister differentiates via specialized boom engineering for extreme-reach high-rise applications.
A truck mounted concrete pump integrates a concrete pumping unit, articulating boom assembly, and truck chassis into a mobile system capable of delivering ready-mix concrete at pressures exceeding 80 bar through pipelines extending 50+ meters vertically. The equipment serves as the primary mechanized solution for placing concrete in structures where direct truck access proves impractical or elevation exceeds mixer-delivery limits. Diesel configurations retain dominant installed-base share across emerging markets, though hybrid architectures are gaining fastest traction where urban emission zones restrict conventional engine operation. Infrastructure Projects command the deepest margin pools due to extended fleet utilization cycles and bulk procurement terms, while Residential Development segments operate on shorter replacement horizons. Rental Services channels are expanding fastest in North American and European markets as contractors prioritize operational flexibility over capital deployment.
EPA Tier 4 Final and EU Stage V emission frameworks are elevating powertrain compliance costs and compressing diesel-model viability timelines in regulated markets. China's MIIT implements parallel emission tiers through GB standards that manufacturers must satisfy for domestic sales certification. OSHA crane and concrete placement safety directives in the United States mandate operator certification and equipment inspection protocols that shape training and service attach rates. Stakeholders must evaluate powertrain portfolio exposure against regulatory phase-out schedules and emerging battery-electric feasibility for heavy-boom configurations.
Market Dynamics
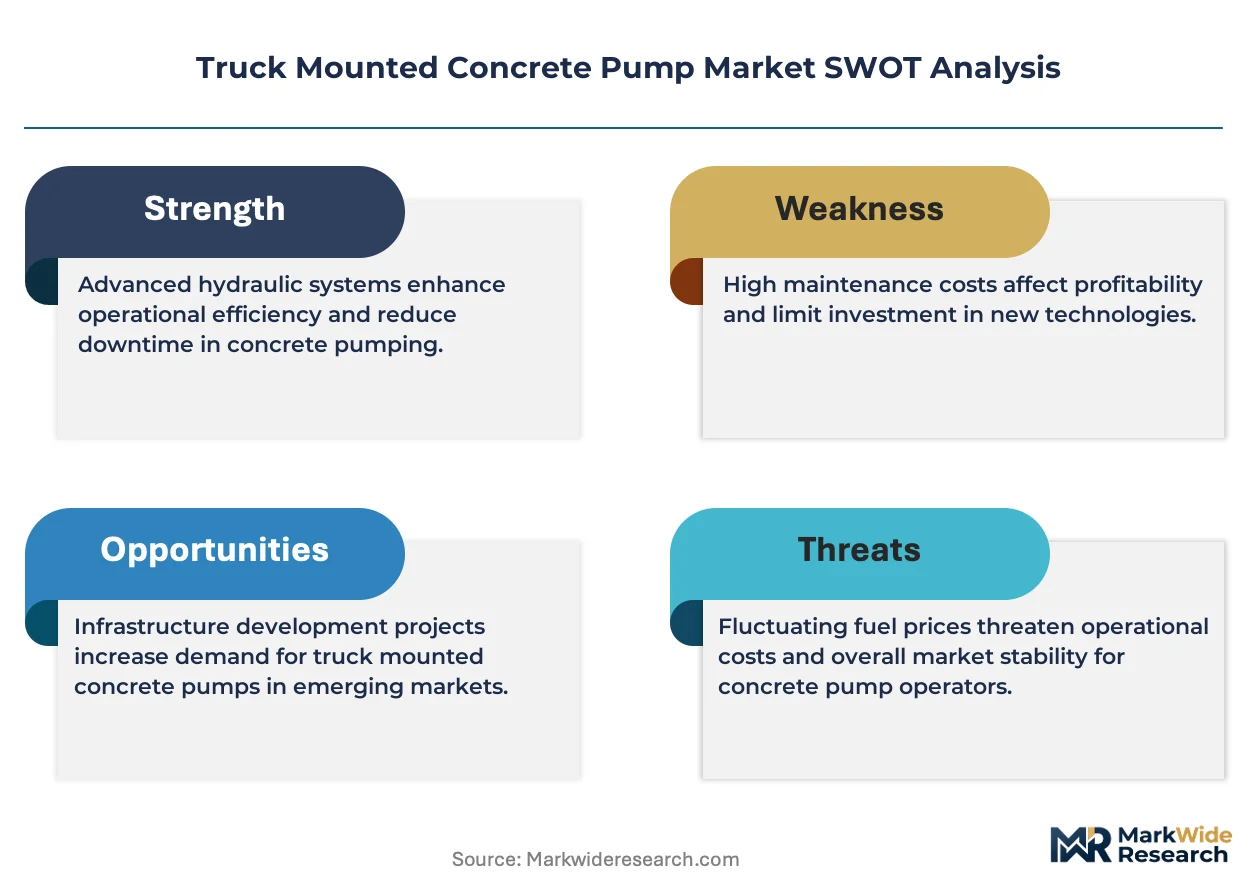
Telematics-enabled fleet management is decoupling hardware sales from pure equipment transactions, forcing manufacturers to build recurring revenue streams through data services and predictive maintenance contracts rather than one-time unit sales.
Growth Catalysts
- Giga-project construction in Saudi Arabia:NEOM, Red Sea Project, and Qiddiya developments are reshaping concrete logistics requirements with specialized high-reach boom specifications and extended fleet utilization cycles.
- China MIIT emission standards:Accelerating diesel-to-hybrid transitions in equipment manufacturing through GB certification requirements that favor electrified powertrains for urban deployment zones.
- Modular boom engineering:Lightweight composite materials and articulated joint designs are extending vertical reach capabilities beyond 70 meters for high-rise construction applications.
Market Restraints
- Steel and hydraulic component cost volatility:Specialized high-pressure pumps and articulating cylinders face input price swings that compress margin predictability for OEMs.
- EPA Tier 4 Final compliance costs:Aftertreatment systems and exhaust fluid infrastructure add capital intensity to diesel configurations in regulated North American markets.
- Battery-electric range limitations:Energy density constraints in heavy-boom configurations restrict pure electric viability for remote infrastructure sites lacking charging infrastructure.
Strategic Opportunities
- Rental services channel expansion:North American contractors are prioritizing operational flexibility over capital deployment through equipment-as-a-service models.
- EU Stage V regulatory tailwind:Urban emission zones in German and French metropolitan areas are creating preferential market access for hybrid and electric configurations.
- Telematics-converged maintenance:IoT sensor networks and predictive algorithms are enabling outcome-based service contracts that lock in long-term customer relationships.
Industry Challenges
- Certified boom operator scarcity:OSHA crane and concrete placement safety directives mandate specialized training programs that lag behind fleet expansion rates in active construction markets.
- Legacy fleet integration complexity:Retrofitting telematics and emission controls onto installed diesel bases requires engineering resources that divert from new product development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Truck Mounted Concrete Pump Market |
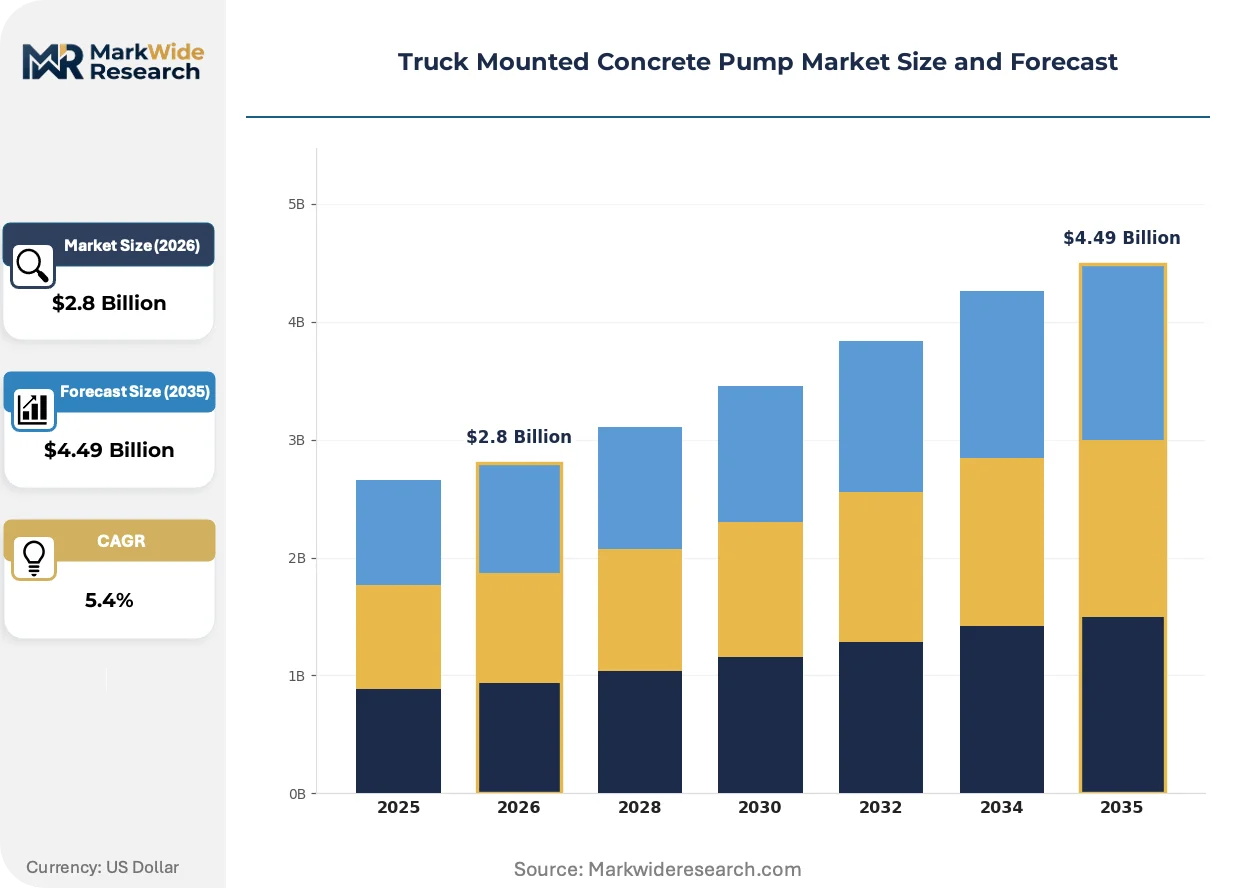
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Diesel, Hybrid, Boom End User: Construction Companies, Infrastructure Projects, Ready-Mix Concrete Suppliers, Residential Development Application: High-Rise Buildings, Road Construction, Bridge Works, Industrial Construction Distribution Channel: Direct Sales, Distributors, Online Sales, Rental Services |
| Companies Covered | SANY Heavy Industry, Zoomlion Heavy Industry, Putzmeister, Schwing GmbH, Liebherr Concrete Technology, XCMG Group, CIFA S.p.A., Concord Concrete Pumps, KCP Heavy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Truck Mounted Concrete Pump Market Emerging Trajectories
Powertrain electrification and digital service models are converging to redefine equipment economics, compressing traditional ownership cycles while opening recurring revenue streams for technology-enabled suppliers.
Hybrid diesel-electric architectures are integrating modular battery packs with downsized combustion engines to enable zero-emission operation in urban zones while maintaining diesel range for remote sites. Infrastructure contractors in European metropolitan areas are specifying these configurations to secure work permits in low-emission zones. This technology is integrating operational flexibility with regulatory compliance, compressing the viability window for conventional diesel-only offerings.
China's MIIT is enforcing parallel emission tiers through GB standards that manufacturers must satisfy for domestic sales certification, effectively mandating hybrid or electric options for new equipment registrations. Domestic OEMs are accelerating R&D allocation toward electrified platforms to maintain market access. The domestic Chinese market is responding with rapid product portfolio transitions that exceed the pace of voluntary adoption in export markets.
Contractor procurement preferences are rotating toward bundled service contracts that unbundle maintenance, telematics, and operator training from hardware acquisition. Rental services channels in North America are capturing this shift through multi-year agreements that transfer utilization risk from contractors to fleet operators. This behavioral change is most visible in US metropolitan construction markets where project volatility discourages capital commitment to specialized equipment.
Truck Mounted Concrete Pump Market Segmentation
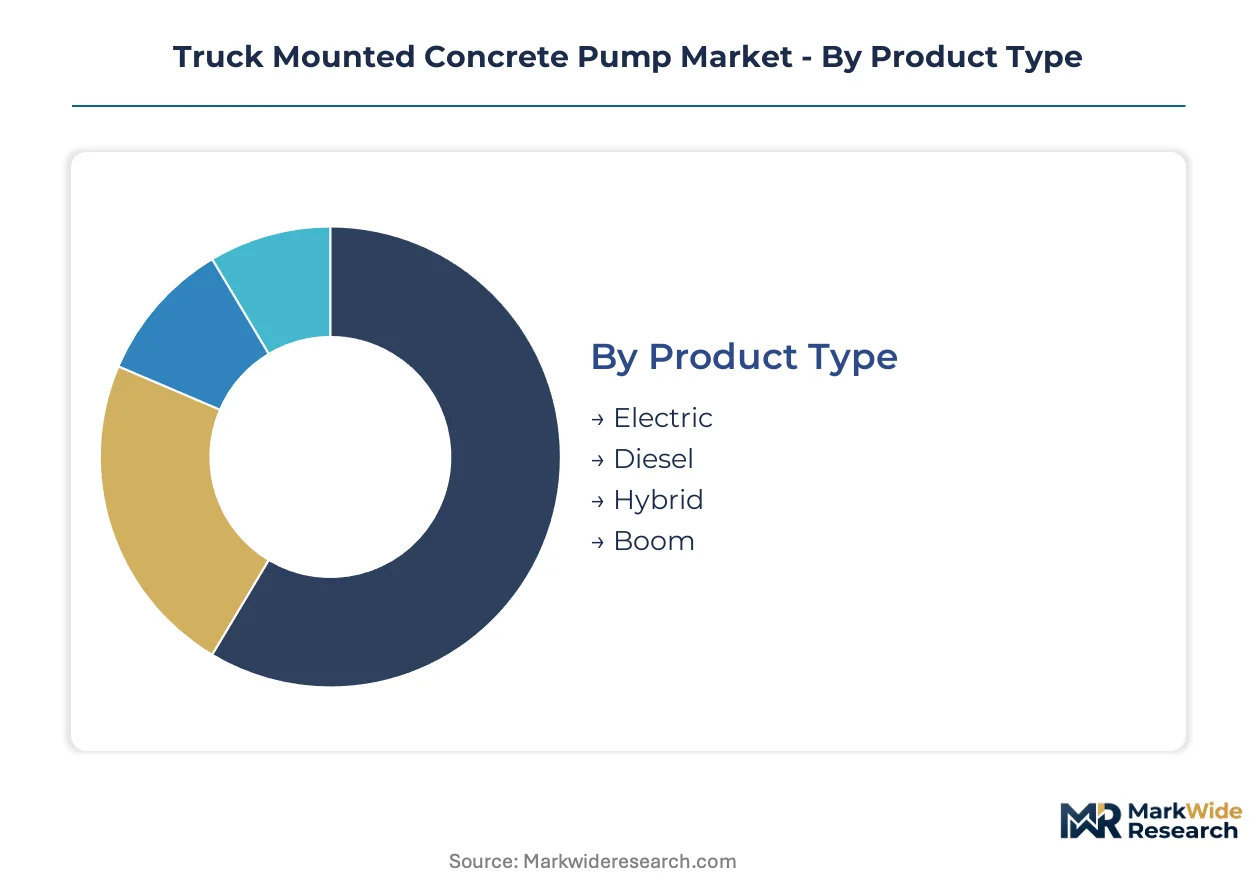
Segmentation in the truck mounted concrete pump market reveals distinct technology-performance-cost tradeoffs that shape procurement patterns across construction verticals. Equipment specification directly determines project eligibility, utilization economics, and regulatory compliance pathways for fleet operators.
Product Type:
Powertrain architecture defines operational flexibility, emission compliance boundaries, and total cost of ownership across deployment scenarios.
- Diesel:High-pressure pumps exceeding 80 bar deliver concrete through pipelines extending 50+ meters vertically, serving remote infrastructure sites lacking grid connectivity. Demand concentrates in Saudi Arabia's NEOM and Red Sea Project developments where giga-project scale requires proven range reliability beyond battery-electric feasibility.
- Hybrid:Modular battery packs integrate with downsized combustion engines to enable zero-emission operation in urban zones while maintaining diesel range for remote sites. European metropolitan contractors specify these configurations to secure work permits in German and French low-emission zones.
- Electric:Battery-electric architectures face energy density constraints in heavy-boom configurations, restricting viability to urban residential sites with established charging infrastructure.
- Boom:Articulating boom assemblies with lightweight composite materials extend vertical reach capabilities beyond 70 meters for specialized high-rise applications.
Mature deployment sits with Diesel configurations across emerging market infrastructure corridors. Newer deployment is concentrated in Hybrid architectures where EU Stage V and China MIIT GB standards restrict conventional engine operation.
End User:
Customer scale and project duration create diverging margin profiles and service attachment opportunities for equipment suppliers.
- Infrastructure Projects:Extended fleet utilization cycles spanning multi-year developments generate the deepest margin pools through bulk procurement terms and integrated maintenance contracts. Saudi Arabia's Qiddiya and Red Sea developments exemplify this segment's demand concentration.
- Construction Companies:Diverse project portfolios require operational flexibility, driving North American rental services adoption to transfer utilization risk from capital balance sheets.
- Ready-Mix Concrete Suppliers:Fleet standardization around pumping capability extends service reach beyond mixer-delivery limits for urban high-rise placements.
- Residential Development:Shorter replacement horizons and project volatility discourage capital commitment, favoring rental channels or used equipment procurement.
Revenue concentration aligns with Infrastructure Projects due to fleet scale and contract duration. Fastest volume expansion is occurring in Construction Companies adopting equipment-as-a-service models.
Application:
Structural height and site accessibility dictate boom specification, pumping pressure requirements, and mobility constraints.
- High-Rise Buildings:Vertical reach demands exceeding 70 meters require specialized boom engineering with articulated joint designs and high-pressure delivery systems. Putzmeister anchors competitive positioning through extreme-reach capabilities in this segment.
- Bridge Works:Span placement challenges and remote access requirements favor diesel configurations with extended pipeline reach and independent power generation.
- Road Construction:Linear project geometry and ground-level placement reduce boom complexity requirements, opening price-competitive standard configurations.
- Industrial Construction:Heavy foundation pours and concentrated volume placement prioritize pumping capacity over vertical reach specification.
Technical complexity peaks in High-Rise Buildings demanding specialized engineering. Volume scale concentrates in Road Construction where standard specifications dominate procurement.
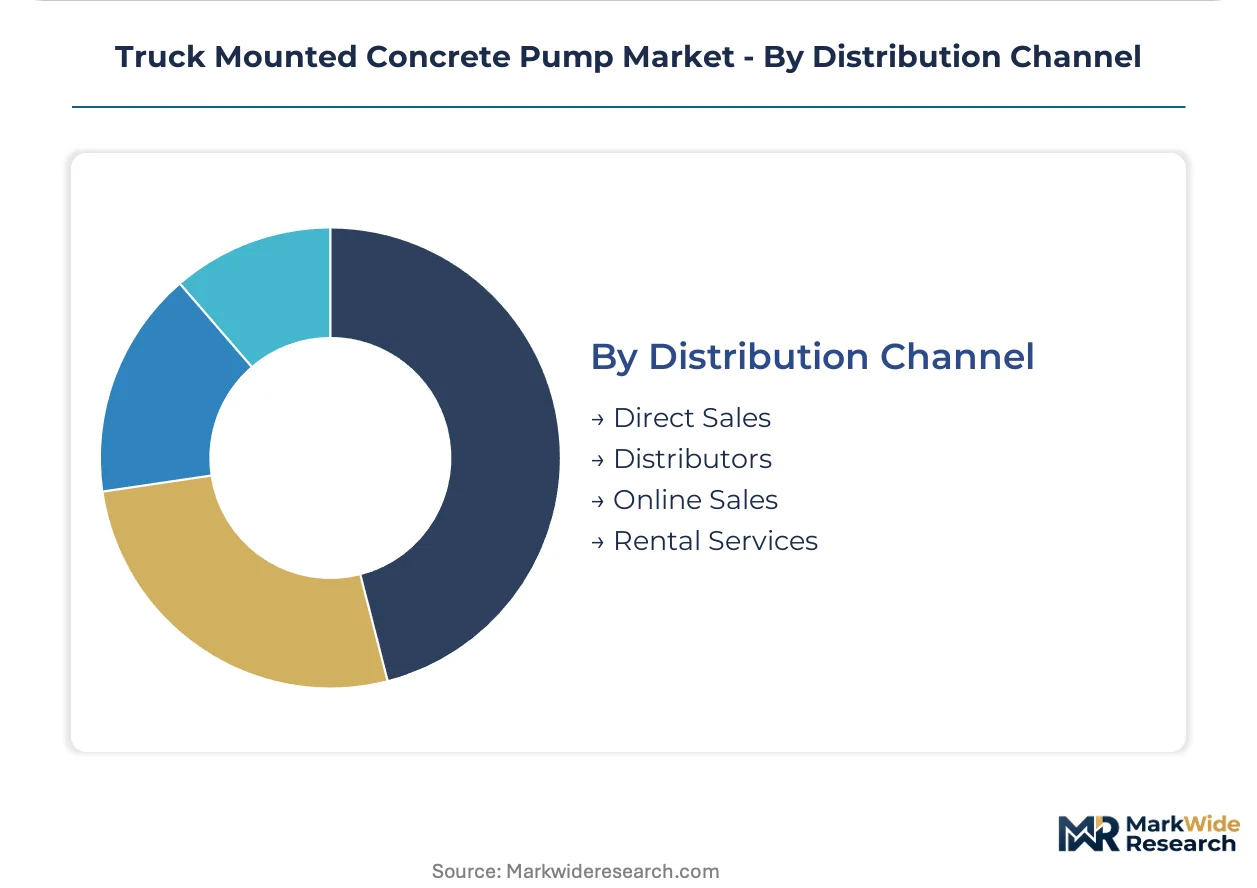
Distribution Channel:
Channel structure determines customer relationship depth, financing integration, and aftermarket service attach rates.
- Rental Services:North American contractors prioritize operational flexibility through multi-year agreements transferring utilization risk to fleet operators. Telematics-enabled predictive maintenance contracts lock in recurring revenue streams beyond initial equipment access.
- Direct Sales:Large infrastructure developers negotiate bulk procurement terms with integrated training and service packages for captive fleet deployment.
- Distributors:Regional coverage networks provide localized service support and financing intermediation for mid-scale construction companies.
- Online Sales:Digital procurement channels facilitate used equipment transactions and standard specification comparisons for price-sensitive buyers.
Channel investment is concentrating in Rental Services where outcome-based contracts reshape equipment economics. Direct Sales retains dominance in giga-project corridors with government-backed procurement authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of truck mounted concrete pumps consumed worldwide, while Saudi Arabia and the United States absorb the highest unit volumes for infrastructure deployment. Domestic OEMs in China supply both local construction markets and export corridors across Asia and Africa.
China
MIIT enforces GB emission standards that mandate hybrid or electric powertrains for new equipment registrations in urban zones. Domestic OEMs accelerate R&D toward electrified platforms to maintain certification access. The Yangtze River Delta manufacturing cluster around Shanghai anchors production capacity for boom assemblies and hydraulic systems serving both domestic and export demand.
Saudi Arabia
NEOM, the Red Sea Project, and Qiddiya developments drive bulk fleet procurement with specialized high-reach specifications. The national investment fund channels capital into construction equipment leasing vehicles to support giga-project timelines. Riyadh-based fleet operators negotiate multi-year service contracts with integrated maintenance and operator training packages.
United States
EPA Tier 4 Final compliance elevates powertrain costs and compresses diesel-model viability timelines in regulated markets. OSHA mandates operator certification and equipment inspection protocols that shape training attach rates. Texas and Florida metropolitan construction corridors concentrate rental services adoption as contractors prioritize operational flexibility over capital deployment.
Germany
EU Stage V frameworks and urban low-emission zones in metropolitan areas create preferential market access for hybrid configurations. The KBA enforces type-approval standards for mobile machinery that shape powertrain engineering requirements. Bavaria's industrial machinery ecosystem around Munich supports specialized hydraulic component production for extreme-reach boom applications.
India
Central government infrastructure spending on highways and urban transit expands fleet procurement across state-level contractors. BIS certification requirements for construction equipment safety shape product specifications for domestic sales. Maharashtra and Gujarat construction corridors concentrate demand for standard-reach diesel configurations serving road and residential projects.
Truck Mounted Concrete Pump Market Vendor Landscape
Capital-heavy chassis integrators compete with asset-light boom engineering specialists across distinct value chain positions. The vendor base consolidates around three strategic tiers: full-system manufacturers with captive hydraulic production, specialized boom engineers licensing chassis platforms, and regional assemblers sourcing standardized components. Dominant competitive moves include backward integration into high-pressure pump manufacturing and geographic expansion through rental services partnerships in North American markets.
Among Chinese full-system manufacturers, SANY Heavy Industry and Zoomlion Heavy Industry occupy positions defined by integrated telematics platforms and vertical control over component supply. Putzmeister, a German GmbH-structured entity, anchors the specialized engineering tier through extreme-reach boom configurations. These three exemplify the strategic divergence between scale-driven integrated production and precision-focused niche engineering that shapes procurement decisions across infrastructure and residential verticals.
| Leading Market Players |
|---|
| SANY Heavy Industry |
| Zoomlion Heavy Industry |
| Putzmeister |
| Schwing GmbH |
| Liebherr Concrete Technology |
| XCMG Group |
| CIFA S.p.A. |
| Concord Concrete Pumps |
| KCP Heavy Industries |
| Others |
Supply Flow & Price Mechanics
EU Stage V emission mandates gate qualified supply access and premium-tier pricing power for truck mounted concrete pump manufacturers, compressing diesel-model viability while elevating hybrid configurations to price-parity or premium positioning in German and French metropolitan markets.
Pricing Analysis
Margin tightening in diesel configurations reflects EPA Tier 4 Final aftertreatment costs and exhaust fluid infrastructure investments that OEMs struggle to pass through to price-sensitive residential contractors. Three-tier pricing structure across premium hybrid, standard diesel, and economy refurbished units stratifies procurement decisions, with infrastructure developers absorbing premium tiers for fleet standardization while rental channels optimize capital efficiency through mid-tier specifications. Cost-down pressure on standard diesel models accelerates because Chinese MIIT GB standards favor electrified platforms for domestic certification. Residential Development segments exhibit highest price sensitivity, whereas Infrastructure Projects prioritize total cost of ownership and uptime guarantees over unit acquisition cost.
Supply Chain Analysis
Regional distribution centers in Germany, China, and Saudi Arabia anchor hub-and-spoke fulfillment patterns for boom assemblies and hydraulic systems serving adjacent construction corridors. Manufacturing gravity draws from the Yangtze River Delta cluster for high-pressure pump production, Bavaria's industrial ecosystem for specialized hydraulic components, and Riyadh-based leasing vehicles for giga-project fleet deployment. Steel and specialized cylinder sourcing faces commodity price volatility that compresses margin predictability for OEMs lacking captive supply. Distribution runs through rental services partnerships in North America, direct sales channels for Saudi infrastructure developments, and regional distributor networks for mid-scale construction companies across India and Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into high-pressure pump manufacturing and telematics platform development defines the vertical-integration race in truck mounted concrete pumps, with captive component supply separating margin leaders from assembly-dependent competitors.
For Market Incumbents: Deepen captive hydraulic component production to defend margin position against Chinese OEMs expanding through integrated cost structures. Invest in telematics-converged service contracts that lock in recurring revenue beyond hardware transactions, countering rental channel disintermediation. Prioritize certification engineering for EU Stage V and China MIIT GB standards to maintain market access as emission frameworks tighten diesel-model viability. For New Entrants and Emerging Players: The mid-tier pricing gap between premium hybrid configurations and refurbished diesel units creates white-space opportunity for standardized electric architectures targeting urban residential sites with established charging infrastructure. Target North American rental services channels through equipment-as-a-service models that transfer utilization risk from capital-constrained contractors. Pursue telematics-enabled predictive maintenance partnerships as the primary go-to-market angle to differentiate from hardware-focused incumbents. For Investors and Strategic Acquirers: Chinese MIIT enforcement actions accelerating domestic R&D allocation toward electrified platforms is the leading indicator that hybrid powertrain engineering capability will command acquisition premiums across the analysis window. Prioritize targets with captive boom manufacturing and installed telematics subscriber bases over pure assembly operations. Watch for Saudi giga-project contract awards as the signal for fleet procurement inflection and regional partnership valuation step-ups.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydraulic Components | Captive pump and cylinder production insulates Zoomlion and SANY from steel price volatility. |
| Telematics Platform Development | SANY's integrated data services sustain aftermarket revenue beyond initial unit sales transactions. |
| Hybrid Powertrain Certification | EU Stage V compliance secures work permits in German and French low-emission urban zones. |
| Rental Services Channel Partnership | North American equipment-as-a-service models transfer utilization risk from contractors to fleet operators. |
| Extreme-Reach Boom Engineering | Putzmeister's specialized articulating designs anchor competitive positioning in high-rise applications. |
Methodological Framework
Multi-period observation of fleet procurement patterns, emission standard phase-out schedules, and telematics adoption rates anchored the trend analysis, supplemented by interviews with maintenance directors at infrastructure contractors, aftermarket service heads at rental fleet operators, OEM procurement teams at chassis integrators, and plant engineers at ready-mix concrete suppliers. Secondary validation drew from MIIT GB certification databases, EPA Tier 4 Final compliance filings, EU Stage V type-approval records, and customs trade data for hydraulic component flows. Bottom-up unit shipment estimates triangulated against top-down construction spending allocations across the analysis window.
Segment-weighting approaches distributed volume and value projections across powertrain architecture, end-user vertical, boom specification, and regional regulatory cluster dimensions throughout the forecast period. CAGRs derived from fitted growth curves incorporating fleet replacement cycles, giga-project timeline commitments, and urban emission zone expansion trajectories. Industry-specific inputs included Saudi Public Investment Fund capital deployment schedules for construction equipment leasing and OSHA operator certification mandate enforcement patterns affecting training attach rates.
Inputs from primary stakeholder interviews and secondary regulatory databases were available through the study window; gaps in real-time fleet utilization telemetry and project-level concrete placement volume data introduce uncertainty bands around demand concentration estimates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Rotational Moulding Machines Market
Construction Equipment
Global Wheel Trenchers Market
Construction Equipment
GCC Mini Cranes Market
Construction Equipment
Truck Crane Market
Construction Equipment
Separation Machinery Market
Construction Equipment
Oxy-Fuel Welding Equipment Market
Construction Equipment
Global Mobile Concrete Mixer Market
Construction Equipment
Indonesia Construction Equipment Market
Construction Equipment
Pressure Washer Market
Construction Equipment
Stud Welding Guns Market
Construction Equipment
Construction Equipment Attachments Market
Construction Equipment
Laser Cutting Machines Market
Construction Equipment
Concrete Grinder Market
Construction Equipment
Compact Excavator Market
Construction Equipment
Vertical Grinding Mills Market
Construction Equipment
Thermal Spray Equipment Market