
 South Korea Aerial Work Platform (AWP) Rental Market | 2026-2036
South Korea Aerial Work Platform (AWP) Rental Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Aerial Work Platform (AWP) Rental Market Intelligence
Domestic equipment manufacturers is recalibrating production schedules to match rental fleet renewal cycles across South Korea's industrial corridors. Hyundai Rental Corporation leverages its construction-affiliate network to secure long-term municipal infrastructure contracts. SK Rental Co., Ltd. anchors its position through specialized boom lift offerings for telecommunications tower maintenance. Sambo EWP Co., Ltd. differentiates by sustaining a project-based rental model tailored to shipyard overhaul schedules in Busan and Ulsan.
An aerial work platform rental operation supplies temporary access equipment—scissor lifts with platform heights ranging from 19 to 50 feet and boom lifts extending to 150 feet—on contracted terms rather than outright purchase, serving industries where capital expenditure avoidance and operational flexibility outweigh ownership economics. Scissor lifts dominate the product mix due to standardized deployment across warehousing and retail construction sites where vertical reach requirements remain moderate. Boom lifts command premium rental rates in telecommunications and maintenance services where horizontal outreach and rough-terrain capability justify differential pricing. Project-based rental duration structures are gaining share as semiconductor plant construction timelines create concentrated demand spikes that short-term arrangements accommodate more efficiently than fleet ownership.
The Ministry of Employment and Labor enforces KOSHA certification standards that mandate periodic safety inspections and operator qualification verification, directly shaping equipment retirement timelines and replacement procurement patterns. MFDS equipment safety notifications and Ministry of Land, Infrastructure and Transport construction machinery registration requirements further constrain market entry for non-compliant rental providers. Stakeholders must monitor how forthcoming carbon emission regulations for diesel-powered access equipment reshape fleet composition decisions between electric scissor platforms and hybrid boom configurations.
Market Dynamics
KOSHA certification mandates from the Ministry of Employment and Labor are compressing equipment replacement cycles across South Korea's rental fleet operators, forcing capital redeployment toward compliant electric and hybrid platforms ahead of diesel-phase timelines.
Growth Catalysts
- Semiconductor fabrication construction:Samsung and SK Hynix facility builds in Gyeonggi Province and Yongin generate concentrated demand spikes for boom lifts with 100+ foot vertical reach and rough-terrain chassis.
- MFDS equipment safety notifications:Strengthened inspection protocols accelerate retirement of pre-2018 scissor lift fleets, creating replacement procurement windows for certified rental providers.
- Telecommunications tower densification:5G small-cell deployment schedules across Seoul, Busan, and Daegu sustain premium rental rates for articulated boom configurations with horizontal outreach exceeding 60 feet.
Market Restraints
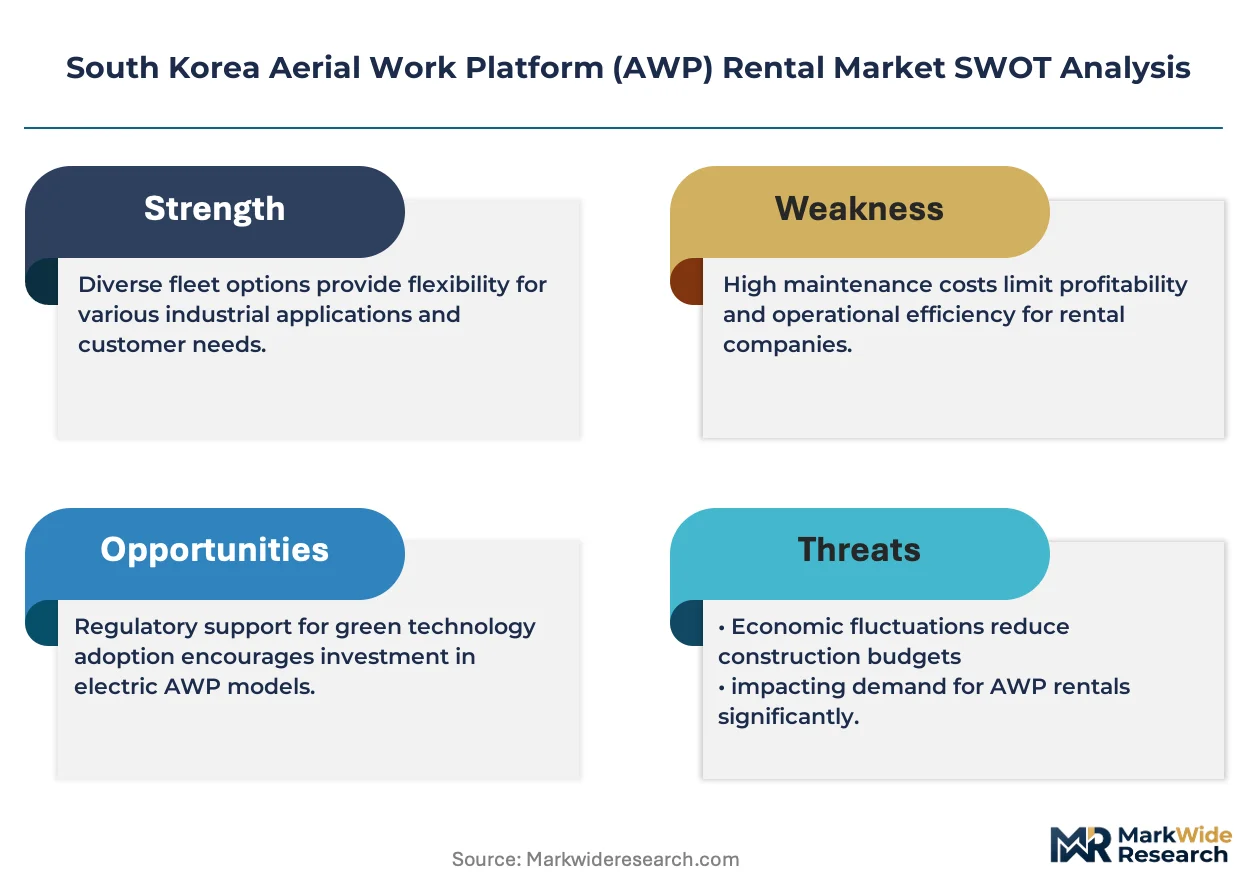
- Steel and lithium-ion battery input costs:Volatility in Korean steel plate pricing and imported battery cell costs compress margin structures for fleet expansion programs.
- Geographic demand concentration:Greater Seoul metropolitan area absorbs over 60% of national rental volume, leaving Busan-Ulsan-Gwangju corridors with underutilized fleet capacity during non-shipyard maintenance windows.
- Scissor lift commoditization:Standardized 19-26 foot platform specifications face pricing pressure from construction-affiliate rental arms offering bundled equipment packages.
Strategic Opportunities
- Carbon emission regulations for diesel equipment:Forthcoming Ministry of Environment standards create first-mover advantage for electric scissor and hybrid boom fleet operators in Incheon Free Economic Zone logistics hubs.
- Shipyard maintenance outsourcing:Hyundai Heavy Industries and DSME shift from captive crane fleets to third-party AWP rental for hull inspection and coating operations in Ulsan and Geoje.
- Telematics-integrated fleet management:Real-time utilization tracking and predictive maintenance platforms enable outcome-based rental pricing models for municipal infrastructure contractors.
Industry Challenges
- KOSHA-certified operator shortages:Rental operators struggle to staff boom lift deployments as training pipeline capacity lags fleet expansion rates in Gyeonggi and Chungcheong provinces.
- Construction machinery registration timelines:Ministry of Land, Infrastructure and Transport approval delays extend equipment commissioning cycles by 4-8 weeks, compressing effective rental yield per unit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Aerial Work Platform (AWP) Rental Market |
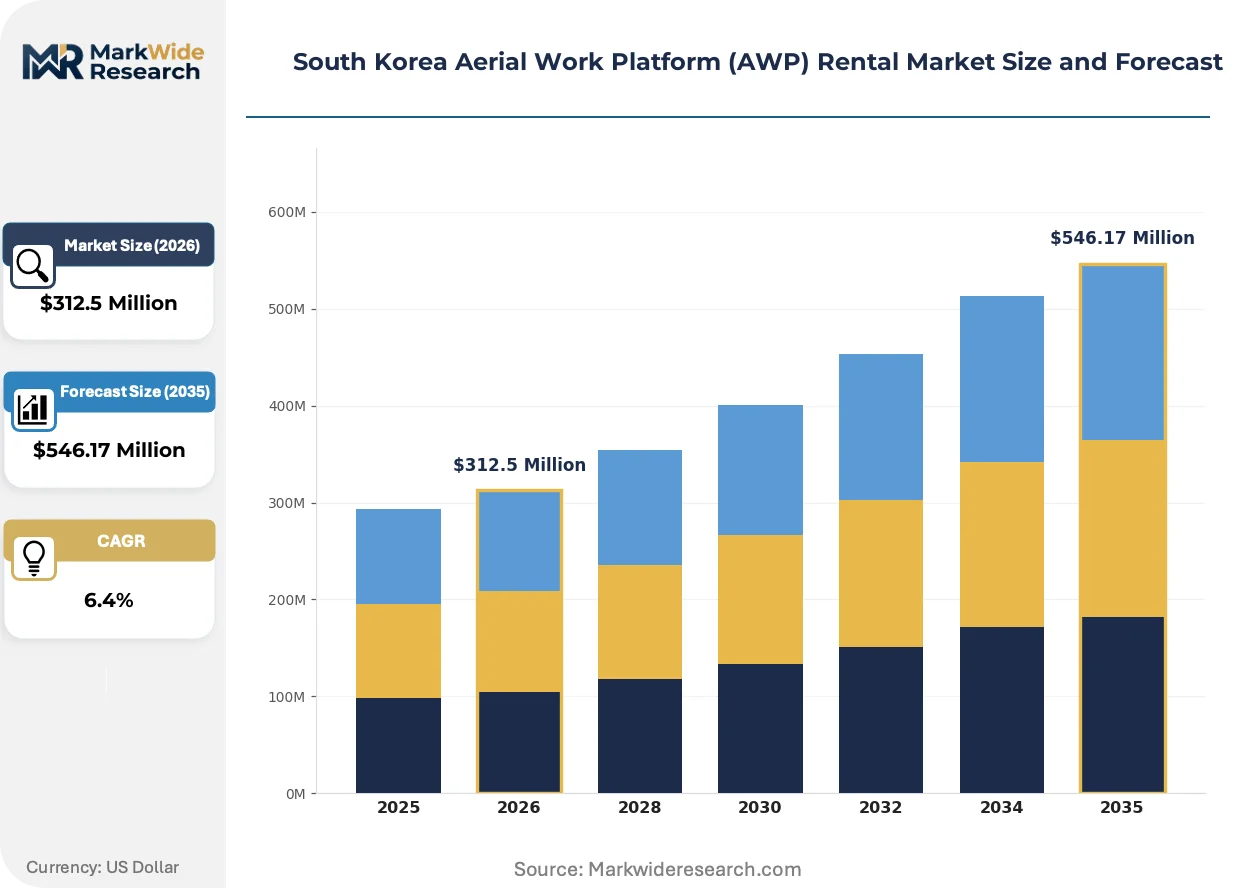
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scissor Lifts, Boom Lifts, Vertical Mast Lifts, Trailer Mounted Lifts Industry Application: Construction, Warehousing, Telecommunications, Maintenance Services Rental Duration: Short Term, Long Term, Project Based, Seasonal Customer Type: Contractors, Facility Managers, Event Organizers, Government Agencies |
| Companies Covered | Korea EWP Co., Ltd., Hyundai Rental Corporation, SK Rental Co., Ltd., Sambo EWP Co., Ltd., Hanjin Rental System Co., Ltd., Korea Rental Corporation, Doosan Mecatec Co., Ltd., Kosin EWP Co., Ltd., Jeil Rental Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Aerial Work Platform (AWP) Rental Market Strategic Shifts & Innovations
Electrification and telematics integration are rewriting competitive differentiation in South Korea's AWP rental sector, shifting procurement criteria from hourly rate to total cost of access including carbon compliance and uptime guarantees.
Lithium-ion battery packs with fast-charge capability are rewriting equipment deployment economics for indoor warehousing and retail construction sites. E-Mart and Coupang fulfillment center contractors specify all-electric scissor fleets to eliminate ventilation requirements and reduce charging downtime. The structural consequence is compressing rental rate premiums previously commanded by diesel units, forcing fleet operators to amortize higher acquisition costs through utilization optimization software.
The Ministry of Environment's forthcoming diesel equipment emission standards are accelerating hybrid boom lift adoption for outdoor telecommunications and utility maintenance applications. Tier 4 Final equivalent engine requirements increase capital outlays by 15-25% versus legacy diesel configurations, favoring rental models over ownership for mid-sized electrical contractors. Gyeonggi Province infrastructure agencies now specify low-emission equipment in municipal tender documentation, redirecting procurement toward compliant rental providers.
Project-based rental duration structures are displacing annual fleet leases among semiconductor construction general contractors. Samsung Engineering and SK E&C negotiate milestone-triggered equipment availability contracts tied to cleanroom steel erection and HVAC installation phases, transferring utilization risk to rental operators while preserving balance sheet flexibility. This pattern concentrates most intensely in Pyeongtaek and Yongin fab construction corridors where construction timelines compress and extend unpredictably.
South Korea Aerial Work Platform (AWP) Rental Market Segmentation
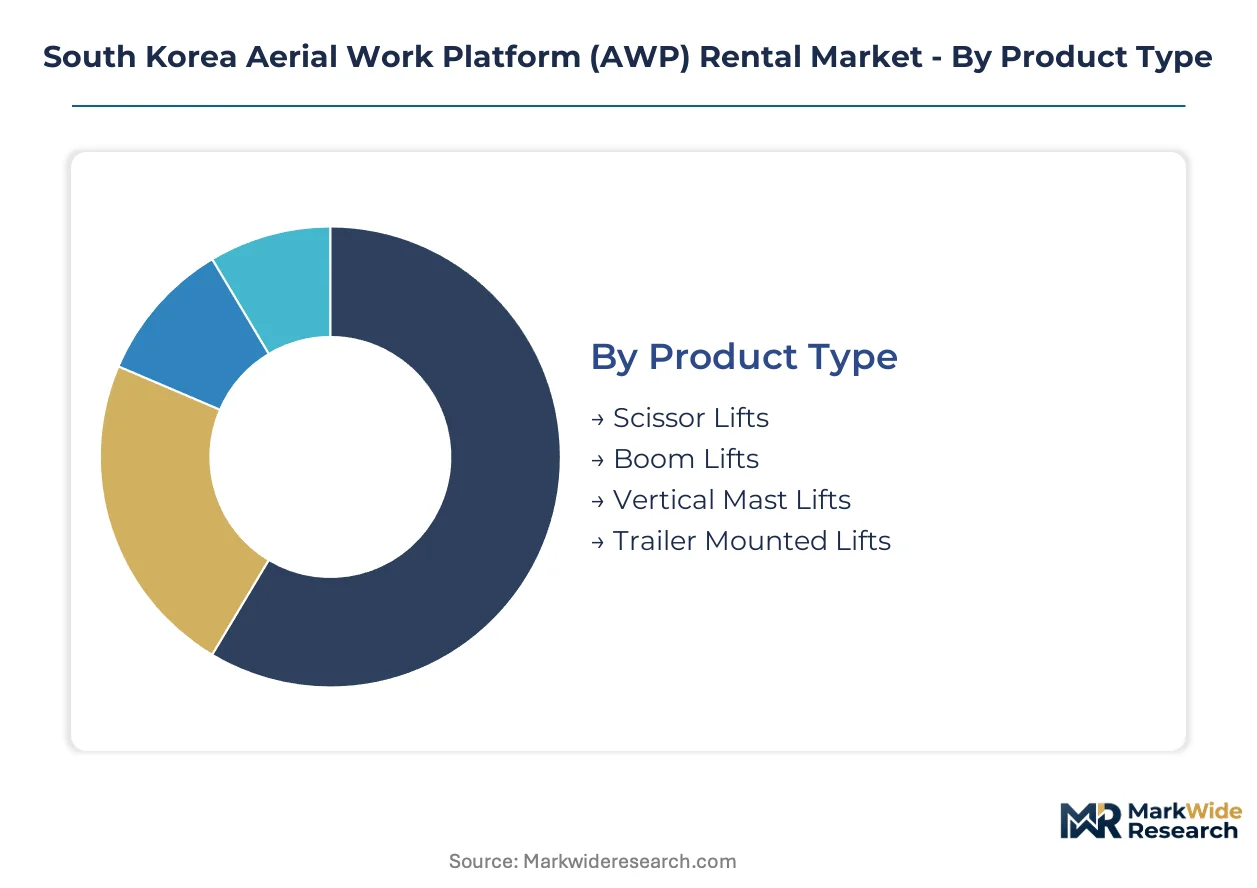
AWP rental procurement patterns in South Korea diverge sharply across equipment configurations and contract structures. Semiconductor construction timelines, KOSHA compliance windows, and municipal tender specifications each reshape how rental operators configure fleet composition and pricing architecture.
Product Type:
Supply concentration clusters around scissor lift platforms where domestic assembly lines achieve scale economies, while boom lift fleets require imported components that constrain fleet expansion velocity.
- Scissor Lifts:Standardized platform heights from 19 to 50 feet dominate indoor warehousing deployments across Coupang and E-Mart fulfillment networks. Electric configurations with lithium-ion fast-charge capability are displacing diesel units in Gyeonggi Province logistics hubs as ventilation requirements tighten.
- Boom Lifts:Articulated and telescopic configurations extending to 150 feet command premium rental rates for Samsung and SK Hynix fab construction in Yongin and Pyeongtaek. Rough-terrain chassis specifications address semiconductor plant site conditions where graded surfaces remain unfinished during steel erection phases.
- Vertical Mast Lifts:Narrow-aisle designs serve retail renovation contractors in Seoul commercial districts where floor loading limits restrict heavier equipment.
- Trailer Mounted Lifts:Highway-towable units address intermittent maintenance needs for telecommunications tower clusters in Busan and Daegu where permanent fleet deployment proves uneconomical.
Today's leader: Scissor Lifts. Tomorrow's challenger: Boom Lifts.
Industry Application:
Customer procurement maturity varies dramatically across end-use sectors, with construction general contractors negotiating milestone-based contracts while warehousing operators prioritize standardized rate cards.
- Construction:Semiconductor fabrication facility builds generate concentrated demand spikes for 100+ foot vertical reach equipment. Samsung Engineering and SK E&C negotiate project-based availability contracts tied to cleanroom steel erection schedules.
- Warehousing:E-commerce fulfillment center construction across Incheon Free Economic Zone specifies all-electric scissor fleets to eliminate diesel ventilation infrastructure. Operators amortize higher acquisition costs through utilization optimization platforms.
- Telecommunications:5G small-cell densification schedules sustain premium rental rates for articulated boom configurations with horizontal outreach exceeding 60 feet across Seoul metropolitan infrastructure.
- Maintenance Services:Shipyard hull inspection outsourcing at Hyundai Heavy Industries and DSME shifts from captive crane fleets to third-party AWP rental for coating operations in Ulsan and Geoje.
Construction absorbs the dominant share of rental value. Telecommunications is climbing the fastest as tower densification accelerates.
Rental Duration:
Contract structure selection reflects balance sheet priorities, with semiconductor contractors transferring utilization risk to rental operators while municipal agencies favor predictable annual commitments.
- Short Term:Daily and weekly arrangements address emergency maintenance windows and unplanned construction delays. MFDS safety notification compliance drives replacement demand spikes that short-term contracts accommodate without fleet ownership.
- Project Based:Milestone-triggered equipment availability contracts are displacing annual leases among fab construction general contractors. Cleanroom steel erection and HVAC installation phases create unpredictable timeline compression and extension patterns.
- Long Term:Annual fleet leases persist among municipal infrastructure agencies in Gyeonggi Province where budget predictability outweighs flexibility premiums.
- Seasonal:Quarterly arrangements align with shipyard maintenance windows in Busan-Ulsan corridors where dry-dock scheduling concentrates demand into discrete periods.
Project Based structures are gaining share fastest. Long Term contracts defend residual volume.
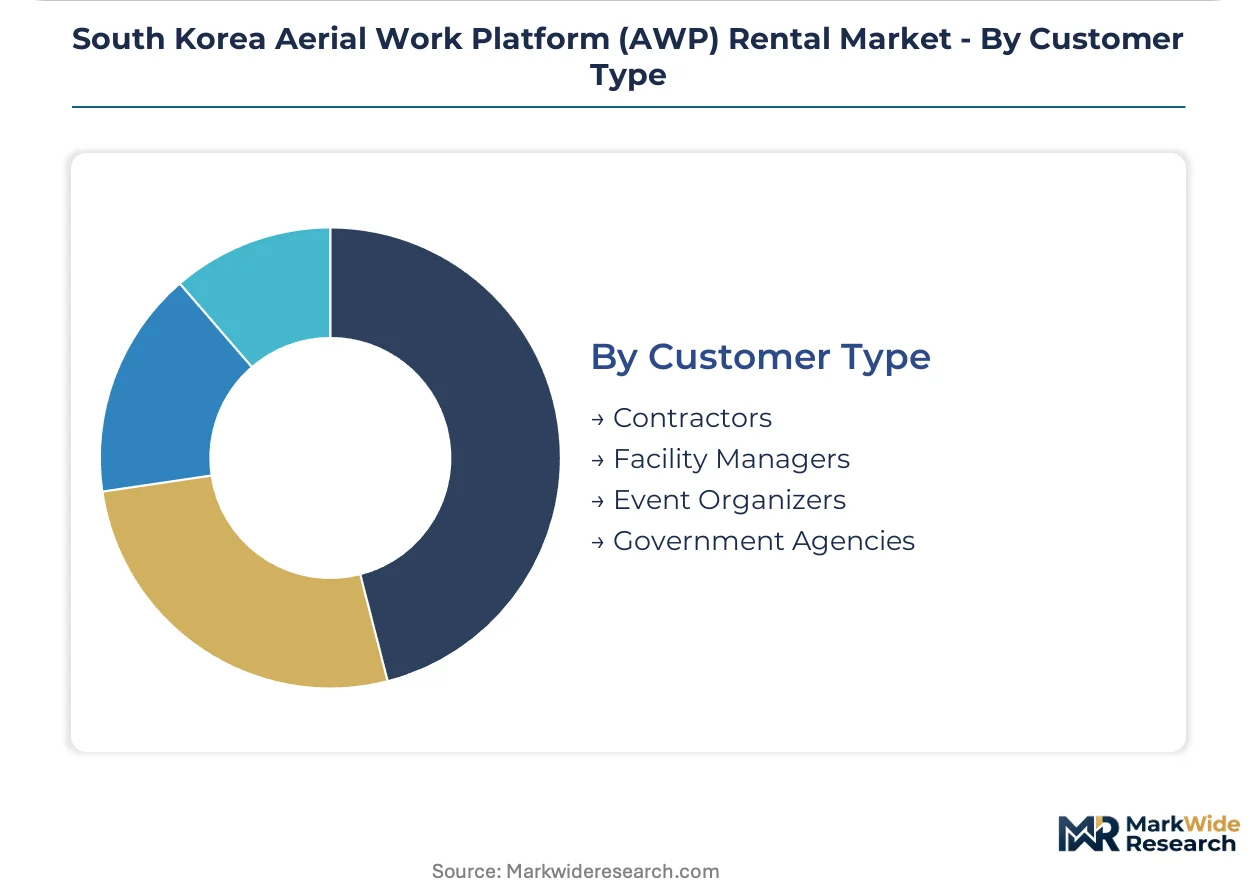
Customer Type:
Procurement authority concentration varies, with facility managers consolidating specifications across multi-site portfolios while event organizers fragment demand into episodic, price-sensitive transactions.
- Contractors:Construction general contractors command volume leverage in semiconductor and municipal infrastructure segments. Bundled equipment packages from construction-affiliate rental arms compress standalone scissor lift pricing.
- Facility Managers:Multi-site warehousing operators in Incheon and Gyeonggi specify standardized electric fleet configurations across Coupang and E-Mart networks, consolidating procurement authority.
- Event Organizers:Episodic demand for stage and lighting access equipment concentrates in Seoul entertainment districts where price sensitivity limits contract duration and equipment specification.
- Government Agencies:Ministry of Land, Infrastructure and Transport construction machinery registration requirements constrain vendor qualification, favoring established rental providers with compliance infrastructure.
Contractors dominate current rental value. Facility Managers are expanding most quickly as e-commerce fulfillment construction accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping fleet deployment patterns as rental operators migrate equipment toward jurisdictions with compressed compliance timelines, capturing replacement windows before KOSHA mandates harden.
Seoul Capital Area
Semiconductor fabrication construction in Yongin and Pyeongtaek drives concentrated demand for 100+ foot vertical reach boom lifts. Gyeonggi Province infrastructure agencies now specify low-emission equipment in municipal tender documentation. Rental fleets serving Samsung Engineering and SK E&C cleanroom projects cluster along the Seoul-Suwon corridor where utilization rates sustain premium pricing.
Busan-Ulsan
Shipyard maintenance outsourcing at Hyundai Heavy Industries and DSME shifts from captive crane fleets to third-party AWP rental for hull inspection operations. MFDS equipment safety notifications accelerate retirement of pre-2018 scissor lift fleets in Ulsan industrial zones. Geoje dry-dock scheduling concentrates demand into discrete quarterly windows that favor project-based rental structures.
Daegu-Gyeongbuk
5G small-cell densification schedules sustain premium rental rates for articulated boom configurations with horizontal outreach exceeding 60 feet. Telecommunications tower maintenance contractors face KOSHA-certified operator shortages as training pipeline capacity lags fleet expansion rates. Equipment deployment concentrates around Daegu metropolitan infrastructure where tower clusters require intermittent high-reach access.
Daejeon-Sejong
Government agency procurement from Ministry of Land, Infrastructure and Transport construction machinery registration requirements constrains vendor qualification, favoring established rental providers with compliance infrastructure. Administrative city development projects generate steady demand for standardized electric scissor fleets. Sejong smart city construction specifications prioritize telematics-integrated equipment for real-time utilization tracking.
Gwangju-Honam
Underutilized fleet capacity during non-shipyard maintenance windows creates pricing pressure across the southwestern corridor. Regional rental operators struggle to match capital redeployment rates of Seoul-based competitors toward compliant electric and hybrid platforms. Honam industrial zone logistics hubs present first-mover opportunity for electric scissor fleet operators as carbon emission regulations for diesel equipment approach.
South Korea Aerial Work Platform (AWP) Rental Market Key Industry Players
Seoul Capital Area operators anchor the premium tier; Busan-Ulsan specialists hold project-based positions in shipyard maintenance. The vendor base separates into construction-affiliate rental arms with bundled equipment packages, independent fleet operators with telematics-integrated platforms, and regional specialists serving discrete industrial corridors. Strategic moves concentrate on fleet electrification ahead of Ministry of Environment diesel standards and milestone-triggered availability contracts that transfer utilization risk from semiconductor contractors.
Among construction-affiliate rental operators, Hyundai Rental Corporation and SK Rental Co., Ltd. exemplify the integrated model leveraging parent-company networks to secure long-term municipal infrastructure contracts. Sambo EWP Co., Ltd. occupies a position within the regional specialist tier, sustaining project-based arrangements tailored to shipyard overhaul schedules. These three entities represent divergent competitive archetypes: affiliate-captive, technology-integrated, and corridor-focused respectively.
| Leading Market Players |
|---|
| Korea EWP Co., Ltd. |
| Hyundai Rental Corporation |
| SK Rental Co., Ltd. |
| Sambo EWP Co., Ltd. |
| Hanjin Rental System Co., Ltd. |
| Korea Rental Corporation |
| Doosan Mecatec Co., Ltd. |
| Kosin EWP Co., Ltd. |
| Jeil Rental Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Lithium-ion battery platform electrification is simultaneously elevating fleet acquisition costs and consolidating procurement power among domestic assembly lines with scale economies in scissor lift manufacturing. This dual transformation compresses margin structures for rental operators while rewarding capital redeployment toward compliant electric configurations ahead of KOSHA-mandated diesel phase timelines.
Pricing Analysis
Construction-affiliate rental margins absorb bundled equipment package discounts that standalone fleet operators cannot match, forcing independent providers toward telematics-integrated premium positioning. Price differentiation separates KOSHA-certified electric fleets from pre-2018 diesel units facing accelerated retirement. Cost compression in standardized scissor configurations is intensifying because construction-affiliate arms leverage parent-company volume leverage. Municipal infrastructure agencies demonstrate lowest price sensitivity due to budget predictability requirements, while event organizers in Seoul entertainment districts exhibit highest sensitivity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Samsung Engineering and SK E&C for 100+ foot vertical reach boom lifts with rough-terrain chassis specifications. Geographic supply concentration clusters in South Korea for scissor lift domestic assembly, China for lithium-ion battery cell imports, and Japan for precision hydraulic component sourcing. Raw material dependencies include Korean steel plate pricing volatility, imported battery cell costs, and specialized hydraulic systems. Single-source vulnerability in battery cell supply creates exposure to input cost spikes. Distribution runs through construction-affiliate captive networks, independent telematics-integrated operators, and regional specialists serving Busan-Ulsan shipyard corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's AWP rental market functions as a stable compounder anchored by semiconductor fabrication facility construction cycles that generate predictable replacement demand spikes across Gyeonggi Province.
For Market Incumbents: Extend telematics-integrated fleet management capabilities to capture outcome-based pricing contracts from municipal infrastructure agencies in Sejong smart city developments. Deepen backward integration into lithium-ion battery maintenance infrastructure to offset imported cell cost volatility. Defend against construction-affiliate bundled pricing by anchoring premium positioning through KOSHA certification compliance and real-time utilization guarantees. For New Entrants and Emerging Players: Mid-sized electrical contractors in Daegu-Gyeongbuk telecommunications maintenance represent an underserved buyer archetype with unmet demand for hybrid boom configurations. First-mover positioning in Gwangju-Honam electric scissor fleet deployment ahead of Ministry of Environment diesel standards offers white-space entry. Project-based rental duration structures with milestone-triggered availability contracts provide the most penetrable go-to-market angle against incumbent annual lease dominance. For Investors and Strategic Acquirers: Valuations sit cheapest among regional specialists with established shipyard maintenance relationships in Ulsan-Geoje corridors. Long-term viability over a 5-10 year window rests on fleet electrification completion ahead of regulatory deadlines. Target acquisition archetypes include telematics-integrated mid-cap operators with KOSHA compliance infrastructure. Carbon emission regulation enforcement timing serves as the critical inflection indicator for electric fleet adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Fleet Conversion | MFDS safety notifications and Ministry of Environment standards accelerate diesel retirement timelines across Gyeonggi Province rental fleets. |
| Telematics Platform Integration | Real-time utilization tracking enables outcome-based pricing models for Samsung Engineering cleanroom construction contractors. |
| Project-Based Contract Structuring | Milestone-triggered availability transfers utilization risk from semiconductor general contractors to rental operators. |
| Regional Corridor Specialization | Shipyard maintenance outsourcing at Hyundai Heavy Industries creates captive demand in Busan-Ulsan dry-dock windows. |
| Certification Infrastructure Investment | KOSHA compliance capabilities constrain vendor qualification for Ministry of Land, Infrastructure and Transport tenders. |
Research Approach
Direct dialogue with rental fleet operations directors, construction procurement managers at Samsung Engineering and SK E&C, KOSHA certification auditors, and lithium-ion battery supply specialists grounded qualitative assessment. Secondary validation drew from Ministry of Employment and Labor enforcement bulletins, Ministry of Environment emission standard drafts, construction machinery registration databases, and semiconductor facility construction permit filings. Bottom-up equipment deployment counts triangulated against top-down regional construction spend estimates.
Bottom-up modeling segmented the market by product type, rental duration structure, industry application, and customer procurement authority across the projection horizon. Analytical frameworks incorporated KOSHA compliance window timing, semiconductor fab construction phase sequencing, and telecommunications tower densification schedules. CAGRs were derived from equipment replacement cycle compression rates and fleet electrification capital redeployment patterns. Forecast inputs included lithium-ion battery cost curves and diesel emission regulation enforcement probability.
Underlying measurement precision varies by segment; scissor lift deployment in warehousing applications carries tighter precision than boom lift demand in project-based semiconductor construction. Forecasts reflect assumptions regarding KOSHA inspection enforcement intensity and Ministry of Environment diesel standard implementation sequencing. Regulatory timeline delays, battery supply disruptions, or construction schedule compression could revise projections. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
UK Heavy Construction Equipment Rental Market
Construction Equipment
Electrofusion Welding Machines Market
Construction Equipment
Bucket Elevator Market
Construction Equipment
Demolition Vessels Market
Construction Equipment
Tower Crane Market
Construction Equipment
Road Roller Market
Construction Equipment
Europe Used Construction Machinery Market
Construction Equipment
Drilling Machine Market
Construction Equipment
Europe Forklift Rental Market
Construction Equipment
Japan Heavy Construction Equipment Rental Market
Construction Equipment
Manhole Housing Lifter Hook Market
Construction Equipment
Hydroforming Press Market
Construction Equipment
Europe Construction Equipment Rental Market
Construction Equipment
Dozer Tire Market
Construction Equipment
Plastic Molding Machine Market
Construction Equipment
Global Compact Construction Equipment Market