
 Cable Winches Market | 2026-2036
Cable Winches Market Size, Share, and Industry Trends Forecast 2026-2036
Cable Winches Market Insights
OSHA's updated crane and derrick safety standards are broadening the compliance burden for winch manufacturers serving North American construction and industrial sites. Ingersoll Rand leverages its vertical integration into motor and gearbox production to control lead times across electric winch lines. WARN Industries anchors its position in the automotive recovery segment through specialized vehicle-mounted systems for off-road and emergency applications. Columbus McKinnon differentiates via its overhead material handling portfolio that integrates winches into broader lifting ecosystems.
A cable winch is a mechanical device that pulls or lifts loads through the winding of a steel cable or synthetic rope onto a rotating drum, typically driven by electric, hydraulic, pneumatic, or manual power sources and rated by line pull capacity measured in pounds or tons. Its primary industrial purpose centers on horizontal pulling, vertical lifting, and load positioning across construction rigging, marine mooring, vehicle recovery, and factory material handling operations. Electric winches command the largest share of product type revenue due to their plug-and-deploy flexibility and lower total cost of ownership in fixed industrial installations. Hydraulic winches lead in marine and heavy-construction applications where continuous duty cycles and explosion-proof operation justify higher capital outlay. The vehicle-mounted deployment category is expanding fastest as utility fleets and emergency response operators standardize on integrated winch systems for field readiness.
FERC guidelines on infrastructure resilience and the EU Machinery Directive's updated conformity assessment procedures are reshaping product design cycles and testing documentation requirements for winch suppliers seeking multi-jurisdiction market access. Japan's METI industrial safety standards and China's GB standards for lifting machinery add further certification layers for exporters targeting Asia-Pacific project demand. Stakeholders must monitor evolving interoperability mandates between winch controls and broader site automation networks as construction and marine operators digitize equipment fleets.
Market Dynamics
Heavy-lift electric winch systems for offshore wind installation vessels are concentrating procurement power among a handful of European port clusters, reshaping supplier access and certification requirements across the value chain.
Growth Catalysts
- EU Machinery Directive:Tightened safety certification requirements for industrial lifting equipment are accelerating replacement cycles in Germany's North Sea port infrastructure.
- Offshore wind vessel fleets:Specialized installation ships are scaling deployment of high-capacity electric winch systems for turbine component handling.
- FERC infrastructure resilience guidelines:Grid hardening mandates in the United States are expanding winch procurement for utility-scale transmission and substation construction.
Market Restraints
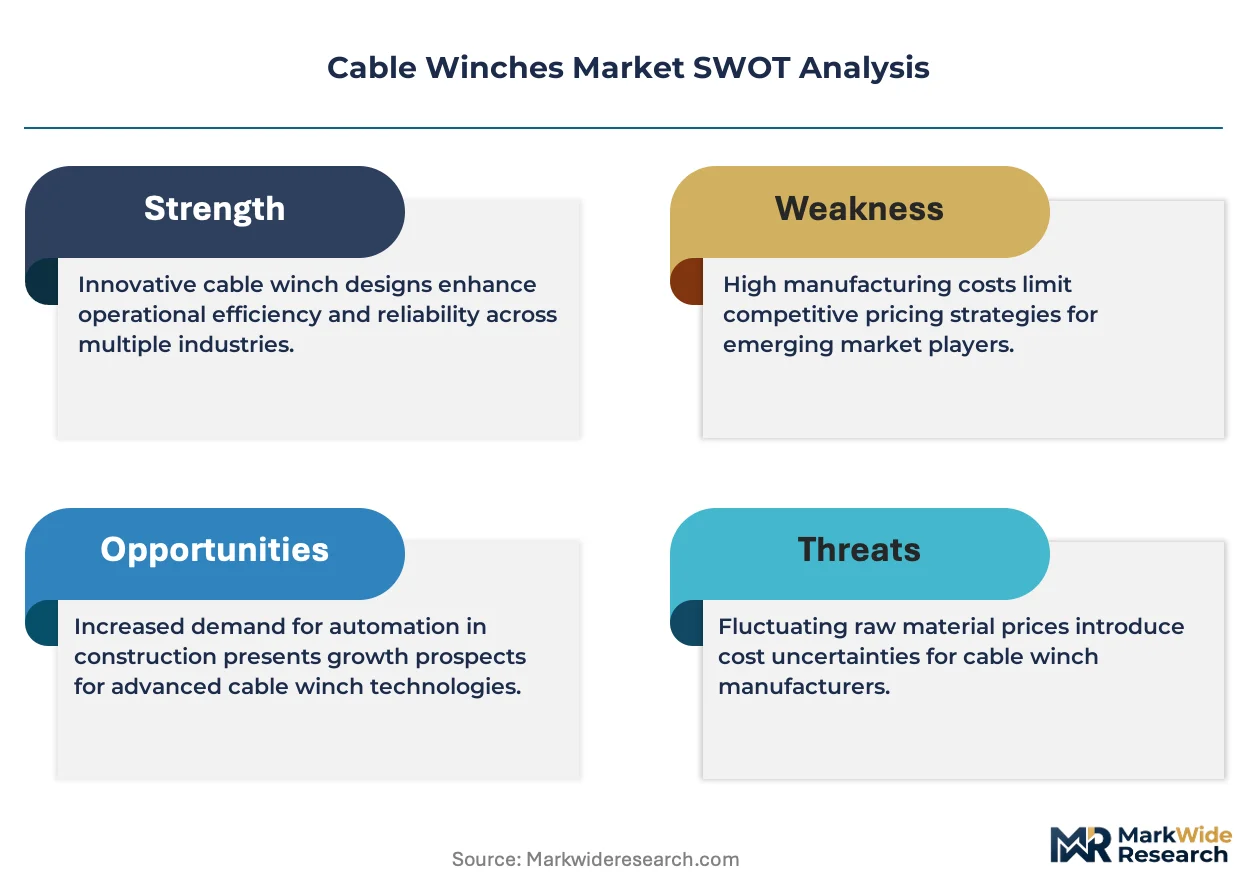
- Steel and copper input volatility:Drum fabrication and motor winding costs fluctuate with commodity markets, compressing margin visibility for mid-tier manufacturers.
- Specialized foundry concentration:Gearbox casting capacity clusters in China's industrial heartland, creating single-source vulnerability for precision components.
- Electromechanical substitution ceiling:Hydraulic systems retain irreplaceable advantages in explosion-proof marine environments, limiting electric winch penetration in offshore oil and gas.
Strategic Opportunities
- Japan's METI industrial safety standards:Updated conformity assessment procedures create first-mover advantage for certified suppliers in Asia-Pacific project markets.
- Vehicle-mounted integration:Utility fleets and emergency response operators are standardizing on factory-installed winch systems for field readiness.
- GB standards alignment:China's lifting machinery certification convergence with international norms opens export pathways for compliant European manufacturers.
Industry Challenges
- Multi-jurisdiction certification timelines:OSHA, EU Machinery Directive, and METI documentation requirements run in parallel, extending product launch cycles.
- Site automation interoperability:Construction and marine operators digitizing equipment fleets demand winch control integration with broader SCADA networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cable Winches Market |
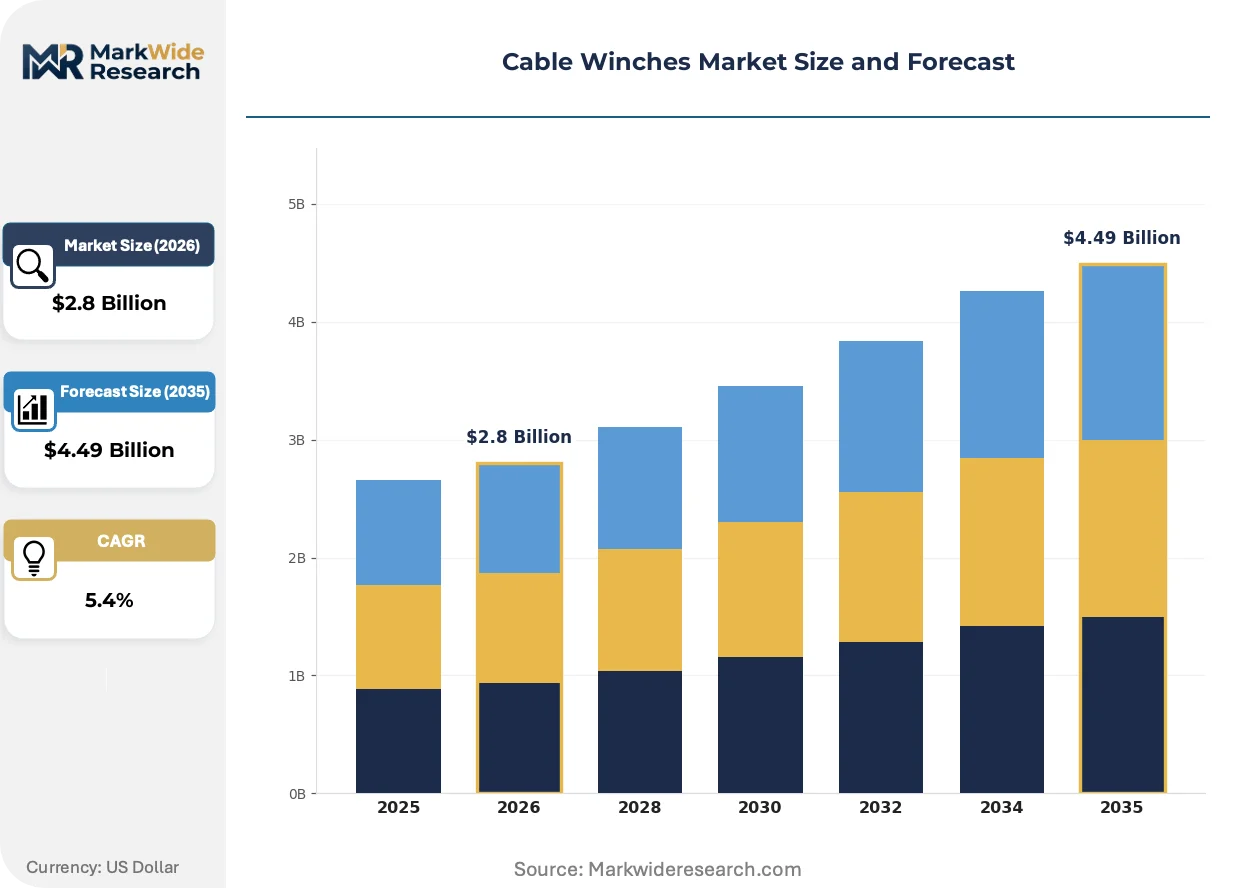
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Winches, Hydraulic Winches, Pneumatic Winches, Manual Winches End User: Construction, Marine, Automotive, Industrial Deployment: Portable, Stationary, Vehicle-Mounted, Custom-Built Capacity: 500 lbs, 1000 lbs, 2000 lbs, 5000 lbs |
| Companies Covered | Ingersoll Rand, WARN Industries, Ramsey Winch, Columbus McKinnon, COMEUP Industries, Rotzler, Superwinch, Thern, TWG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cable Winches Market Trends and Innovations
Digitalization of winch control systems and synthetic rope materials are compressing maintenance intervals while expanding load-handling capabilities in harsh environments.
Synthetic high-modulus polyethylene rope is overtaking traditional steel cable in offshore wind applications. Installation vessel operators are adopting fiber-based systems to reduce topside weight and eliminate corrosion-related downtime. This material transition is overtaking established steel cable specification standards and forcing recalibration of drum design and fleet replacement schedules.
REACH chemical substance restrictions are compelling reformulation of hydraulic fluids and surface coatings used in winch manufacturing. Industrial consequence includes accelerated R&D spend on bio-based lubricants and powder-coat alternatives. Marine and heavy-construction equipment categories face the steepest compliance burden, with suppliers front-loading certification testing to maintain CE marking validity.
Specification consolidation among EPC contractors is compressing vendor qualification pools. Tier-one construction groups are narrowing approved supplier lists to three to five winch manufacturers per equipment category, displacing fragmented procurement across regional distributors. This concentration is most visible in German and Danish offshore wind project clusters, where developer consortiums enforce unified technical standards across vessel charters.
Cable Winches Market Segmentation
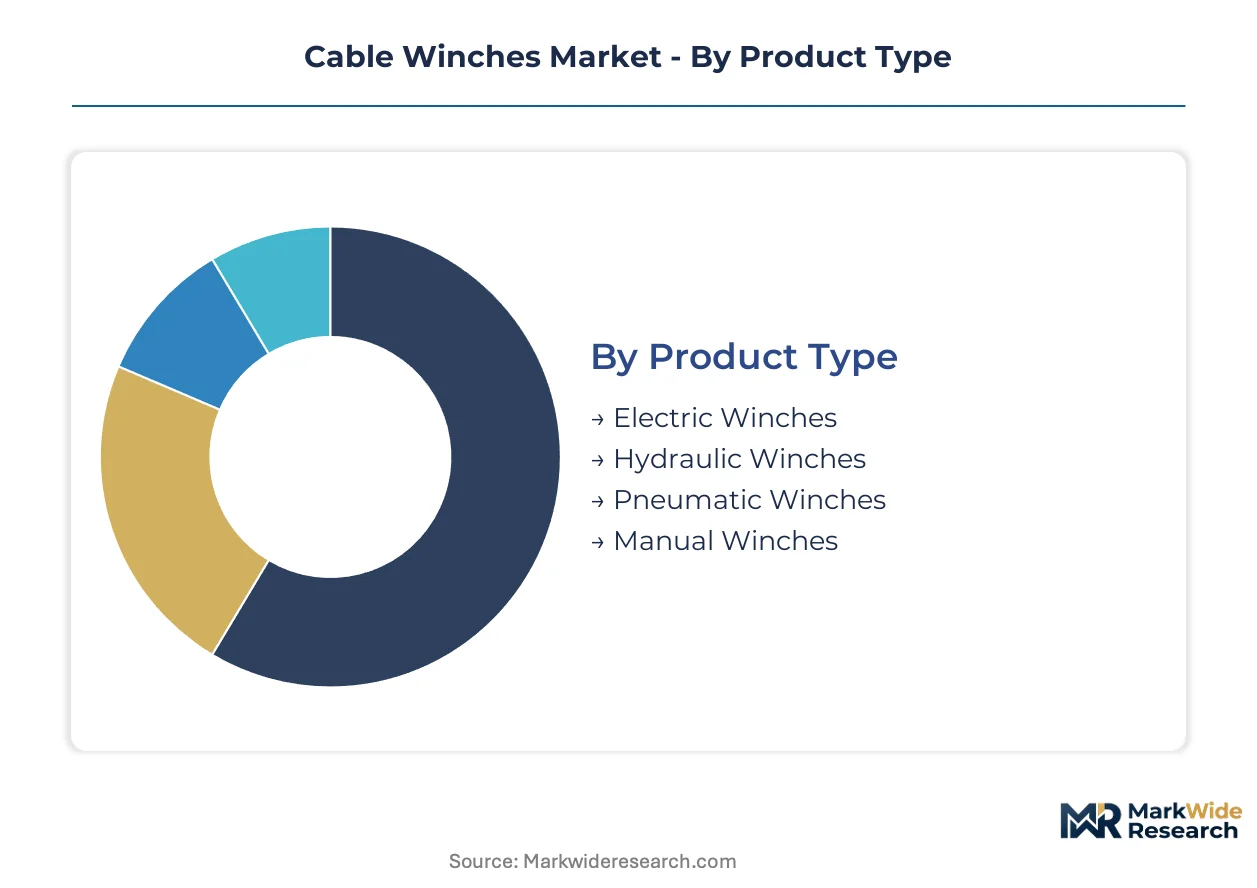
Segmentation in the cable winches market reveals how specification requirements diverge across power sources, duty cycles, and installation constraints. Procurement patterns cluster around standardized electric units for industrial facilities while custom-engineered systems dominate offshore marine applications. Understanding these divides clarifies where manufacturers can leverage platform economics versus project engineering margins.
Product Type:
Standardized electric platforms compete against application-specific hydraulic and pneumatic systems across this category, with customization depth inversely correlated with production volume economics.
- Electric Winches:AC and DC motor-driven systems with integrated variable frequency drives enable precise load control in fixed industrial installations. Demand concentrates in Germany's North Sea port clusters serving offshore wind logistics, driven by grid-hardening procurement under FERC infrastructure resilience guidelines. Plug-and-deploy flexibility and lower total cost of ownership sustain volume leadership.
- Hydraulic Winches:Continuous-duty systems powered by closed-loop hydrostatic drives deliver explosion-proof operation in marine and heavy-construction environments. Offshore oil and gas platforms in the US Gulf Coast and North Sea anchor procurement, where electromechanical substitution hits regulatory and safety ceilings. Higher capital outlay is justified by duty cycle intensity.
- Pneumatic Winches:Compressed-air systems for hazardous atmosphere operations where spark suppression is mandatory.
- Manual Winches:Hand-cranked mechanical units for light-duty applications and emergency backup scenarios.
Most installed capacity flows through Electric Winches. Expansion is steepest in Hydraulic Winches.
End User:
Customer archetypes range from price-sensitive construction contractors to specification-driven marine operators with diverging service and certification requirements.
- Construction:Rigging contractors deploy winches for horizontal pulling and vertical lifting across infrastructure and building projects. US utility-scale transmission and substation construction is expanding procurement under FERC grid-hardening mandates, with OSHA crane and derrick standards tightening compliance documentation. Specification consolidation among EPC contractors is narrowing approved supplier pools.
- Marine:Mooring, anchoring, and deck machinery operations on vessels and offshore platforms. Installation vessel operators in Danish and German offshore wind clusters are scaling high-capacity electric systems, with synthetic rope adoption reducing topside weight and corrosion downtime. EU Machinery Directive certification requirements filter vendor access.
- Automotive:Vehicle recovery and off-road applications including emergency response and recreational use.
- Industrial:Factory material handling and overhead lifting systems integrated into broader automation networks.
Construction absorbs the largest equipment volume. Marine applications are gaining share fastest.
Deployment:
Physical integration depth determines margin structure, from commodity portable units to engineered vehicle-mounted and custom-built systems with embedded control electronics.
- Vehicle-Mounted:Factory-integrated winch systems installed on utility trucks, emergency response vehicles, and off-road equipment. US utility fleets and European emergency operators are standardizing these configurations for field readiness, with procurement shifting from aftermarket retrofit to OEM specification. Control integration with vehicle electrical systems raises technical barriers.
- Stationary:Fixed industrial installations with permanent power and control infrastructure. Manufacturing facilities and port terminals anchor demand, with digitization driving SCADA network interoperability requirements. Long replacement cycles concentrate revenue in new capacity additions.
- Portable:Mobile units with temporary power connections for construction and maintenance tasks.
- Custom-Built:Engineered-to-order systems for unique load, space, or environmental constraints.
Stationary configurations retain the largest installed base. Vehicle-Mounted deployment is climbing the fastest.
Capacity:
Load rating tiers separate commodity replacement markets from engineered heavy-lift procurement with diverging margin and certification intensity.
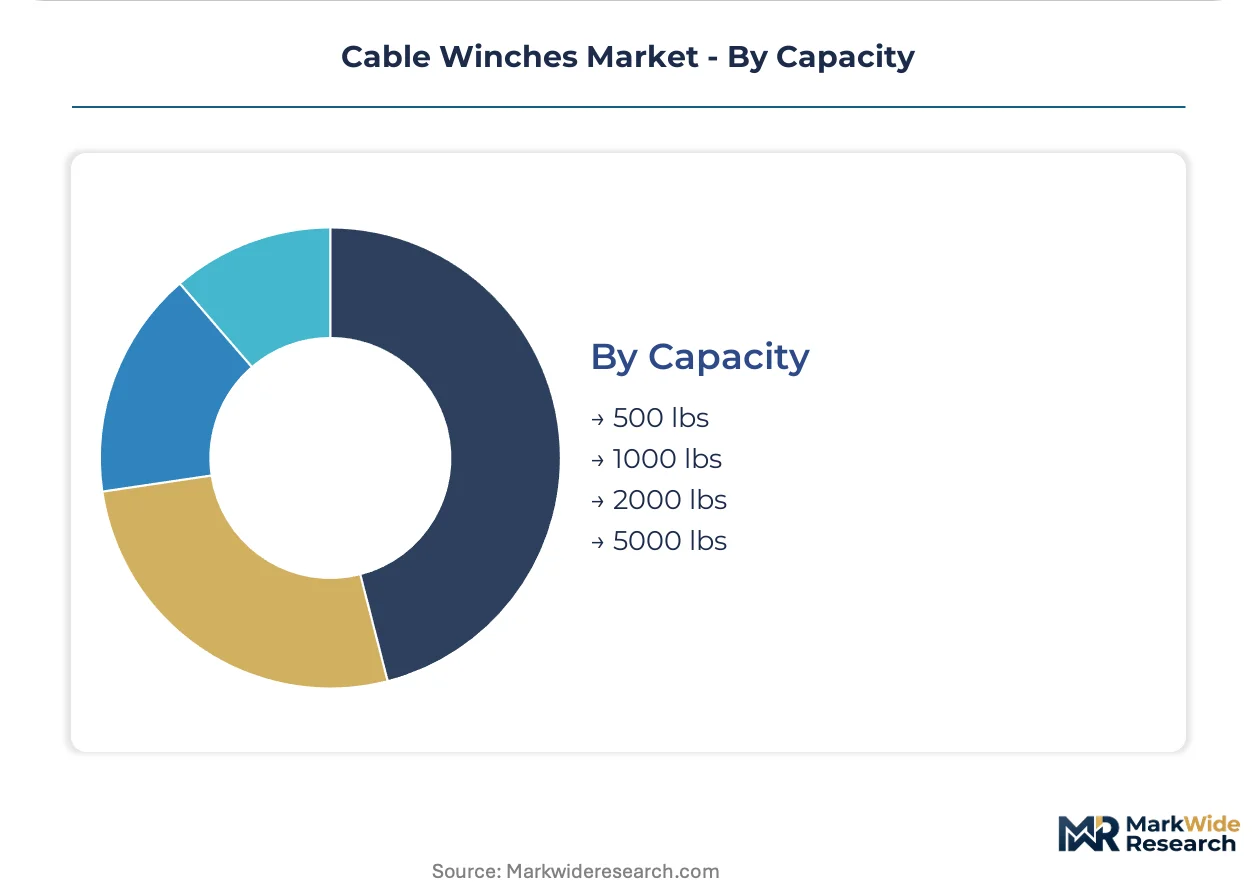
- 5000 lbs:Heavy-lift systems for industrial and marine applications requiring precision load control and redundant braking. Offshore wind installation vessels in European port clusters are scaling procurement of these high-capacity electric systems for turbine component handling. EU Machinery Directive conformity assessment procedures extend lead times and documentation requirements.
- 2000 lbs:Mid-capacity workhorses for construction rigging and industrial maintenance with balanced duty cycles.
- 1000 lbs:Light-industrial and commercial applications with standardized mounting configurations.
- 500 lbs:Entry-level capacity for portable and consumer-grade applications with minimal customization.
2000 lbs capacity handles the broadest installation volume. 5000 lbs systems show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized marine engineers and offshore construction technicians cluster around North Sea port infrastructure, anchoring regional procurement patterns for heavy-lift winch systems.
Germany
Offshore wind installation fleets in Bremerhaven and Cuxhaven are scaling electric winch procurement for turbine component handling. EU Machinery Directive conformity assessment procedures tighten certification timelines for industrial lifting equipment. North Sea port clusters concentrate demand among vessel operators serving renewable energy logistics.
United States
Utility-scale transmission construction and Gulf Coast offshore platforms sustain dual demand tracks for electric and hydraulic systems. FERC infrastructure resilience guidelines and OSHA crane standards expand compliance documentation requirements. Houston and New Orleans anchor marine procurement, while Midwest substation projects drive industrial demand.
China
Domestic port modernization and shipyard expansion absorb high volumes of mid-capacity winch systems. GB standards for lifting machinery are converging with international norms, streamlining export pathways for compliant manufacturers. Yangtze River Delta shipyards concentrate precision gearbox casting capacity.
Japan
Industrial safety upgrades and marine equipment replacement cycles sustain steady procurement. METI updated conformity assessment procedures create certification barriers for uncertified suppliers. Nagoya and Osaka industrial corridors concentrate demand from factory automation and coastal shipping operators.
Denmark
Offshore wind developer consortiums enforce unified technical standards across vessel charters, consolidating vendor qualification pools. REACH chemical restrictions compel hydraulic fluid reformulation for marine applications. Esbjerg port infrastructure anchors North Sea installation vessel deployment.
Cable Winches Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with captive component supply. Mid-tier specialists and regional fabricators occupy fragmented niches below the top tier. Three archetypes dominate: vertically integrated motor-and-gearbox producers, marine-focused system integrators, and automotive recovery specialists. Consolidation pressure is accelerating through specification consolidation among EPC contractors and tier-one construction groups narrowing approved supplier lists.
Among US-based industrial conglomerates, Ingersoll Rand and Columbus McKinnon occupy positions reflecting diversified manufacturing footprints. WARN Industries exemplifies the automotive recovery specialist archetype. These three represent distinct strategic postures: captive supply chain control, overhead material handling ecosystem integration, and vehicle-mounted system specialization respectively.
| Leading Market Players |
|---|
| Ingersoll Rand |
| WARN Industries |
| Ramsey Winch |
| Columbus McKinnon |
| COMEUP Industries |
| Rotzler |
| Superwinch |
| Thern |
| TWG |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between EU Machinery Directive-compliant systems and commodity-grade units creates parallel pricing tracks that map onto fragmented versus integrated supply chain architectures. Premium electric winch systems for German North Sea offshore wind fleets command substantial premiums through captive motor-and-gearbox production, while mid-tier construction winches compete on spot-market steel and copper inputs with minimal service bundling.
Pricing Analysis
Service bundling splits the market between turnkey installation-and-maintenance contracts and bare-equipment transactions. Premium-mid-economy pricing differentiation rests on EU Machinery Directive certification status and aftermarket service depth, with explosion-proof marine systems capturing the highest tier. Cost compression in standard electric winches is intensifying because steel drum fabrication and copper motor winding costs fluctuate with commodity markets. Construction contractors show greatest price sensitivity, while offshore wind vessel operators prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and China anchor hub-and-spoke patterns for aftermarket parts and service deployment. Precision gearbox casting capacity concentrates in China's Yangtze River Delta, with motor winding supply anchored in Germany and the United States. Raw material dependencies include high-grade steel for drums, copper for windings, and synthetic high-modulus polyethylene for emerging rope applications. Single-source vulnerability in Chinese foundry capacity creates structural risk for mid-tier manufacturers lacking alternative sourcing. Distribution runs through OEM-direct channels for vehicle-mounted systems and specialized industrial distributors for construction and marine procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge from regulatory cost differentials between EU Machinery Directive compliance requirements and China's GB standards convergence trajectory, enabling certified European manufacturers to access Asia-Pacific project demand at lower certification overhead than full EU-equivalent systems.
For Market Incumbents: Cement market position through backward integration into precision gearbox production and synthetic rope material supply, countering margin pressure from steel and copper commodity volatility. Prioritize certification investment in Japan's METI industrial safety standards to capture first-mover advantage in Asia-Pacific offshore wind procurement. Channel control through exclusive vessel charter partnerships in German and Danish port clusters reinforces specification consolidation among EPC contractors.
For New Entrants and Emerging Players: Digital control system integration with SCADA networks offers a technology-first wedge into stationary industrial installations where incumbent systems lack interoperability. Target vehicle-mounted deployment for utility fleets in the United States, where procurement is shifting from aftermarket retrofit to OEM specification with less entrenched supplier relationships. Go-to-market through direct fleet operator partnerships bypasses consolidated distributor channels.
For Investors and Strategic Acquirers: Consolidation pressure builds where specification consolidation among tier-one construction groups has narrowed approved supplier lists to three to five manufacturers per equipment category, displacing fragmented regional distributors. Long-term viability favors vertically integrated producers with captive motor and gearbox capacity over assembly-only operations. Acquisition target archetype: mid-tier specialists with EU Machinery Directive certification and established relationships in German North Sea port infrastructure. Watch synthetic rope adoption rates in offshore wind installation vessels as inflection indicator for material transition winners.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Gearbox Production | Captive precision casting capacity insulates margins from Chinese foundry concentration risk. |
| EU Machinery Directive Certification Investment | CE marking validity opens procurement channels in German and Danish offshore wind clusters. |
| Synthetic Rope Material Transition | Fiber-based systems reduce topside weight for installation vessels in North Sea operations. |
| SCADA Control Integration Development | Interoperability with site automation networks addresses digitizing construction and marine fleets. |
| Vehicle-Mounted OEM Partnership Program | Factory-installed specification captures utility fleet procurement shifting from aftermarket retrofit. |
Research Methodology
Coverage spans Germany, the United States, China, Japan, and Denmark, with primary inputs from each market cluster obtained through structured interviews. Plant engineers at German North Sea port terminals, OEM procurement teams at offshore wind vessel operators, maintenance directors at US utility fleet operators, aftermarket service heads at marine equipment distributors, and EPC contractor equipment specification leads provided operational demand perspectives. Secondary validation drew from EU Machinery Directive conformity assessment databases, FERC infrastructure resilience guideline filings, Japan METI industrial safety standard updates, China GB standards documentation, and customs trade records for winch component flows. Bottom-up equipment deployment estimates triangulated against top-down market sizing from port modernization budgets and offshore wind vessel fleet expansion plans.
Rate-of-change decomposition framed volume and value trajectories across the projection horizon by power source, deployment configuration, and end-use sector, with additional modeling of capacity tier and regional regulatory cluster effects. CAGRs were derived from segmented growth rate aggregation weighted by baseline equipment stock. Industry-specific forecast inputs included offshore wind installation vessel order books, US utility transmission construction pipelines under FERC guidelines, and REACH chemical restriction compliance timelines affecting hydraulic fluid formulations.
The model holds under stable commodity price assumptions for steel and copper; deviation in input cost volatility or accelerated synthetic rope adoption would shift equipment replacement cycle timing and margin distribution across manufacturer tiers. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Excavator Wheels Market
Construction Equipment
Americas Hydraulic Submersible Pumps Market
Construction Equipment
Welding Fume Extraction Equipment Market
Construction Equipment
US Waterjet Cutting Machines Market
Construction Equipment
Japan Heavy Construction Equipment Rental Market
Construction Equipment
Earthmover Market
Construction Equipment
Concrete Testers Market
Construction Equipment
3-Wheel Sit-Down Counterbalance Forklift Market
Construction Equipment
Snow Pushers Market
Construction Equipment
TBR Hydraulic Curing Press Market
Construction Equipment
Plasma Cutting Machine Market
Construction Equipment
Tray Dryers Market
Construction Equipment
Global Concrete Curing Equipment Market
Construction Equipment
Stamping Machines Market
Construction Equipment
Yard Crane Market
Construction Equipment
Concrete Pumps Market