
 Paint Buckets Market | 2026-2036
Paint Buckets Market Size, Share, and Industry Trends Forecast 2026-2036
Paint Buckets Market Outlook
Professional painting contractors is rotating toward higher-capacity containers as project scale expands across commercial and industrial sites. Sherwin-Williams leverages captive distribution networks to secure placement with large contractor accounts. PPG Industries anchors its position through specialized industrial-grade metal pails engineered for solvent-based coatings. Ball Corporation competes on manufacturing scale, supplying standardized steel buckets to multinational paint manufacturers.
Paint buckets are rigid containers, typically manufactured from high-density polyethylene, tinplate steel, or fiber-composite materials, designed to store, transport, and dispense liquid coatings with capacities ranging from one quart to ten gallons; they incorporate sealed or snap-on closures to prevent spillage, evaporation, and contamination during handling and storage. Plastic pails dominate volume due to corrosion resistance and lightweight logistics, while metal containers retain preference for flammable solvent-based formulations where static discharge protection matters. The 5-gallon segment leads value contribution because it matches standard commercial project sizing and minimizes per-unit logistics cost. Snap-on lid configurations are gaining fastest in residential applications where resealability and ease of opening drive contractor preference.
EPA regulations under the National Emission Standards for Hazardous Air Pollutants constrain volatile organic compound permeation through container walls, pushing manufacturers toward multi-layer barrier plastics. REACH compliance in Europe mandates disclosure of Substances of Very High Concern in bucket resins and coatings, elevating testing burden for exporters. OSHA workplace safety standards govern pail labeling and handling protocols for flammable contents. Stakeholders must monitor evolving extended producer responsibility frameworks that could mandate recycled content thresholds without clear secondary feedstock availability.
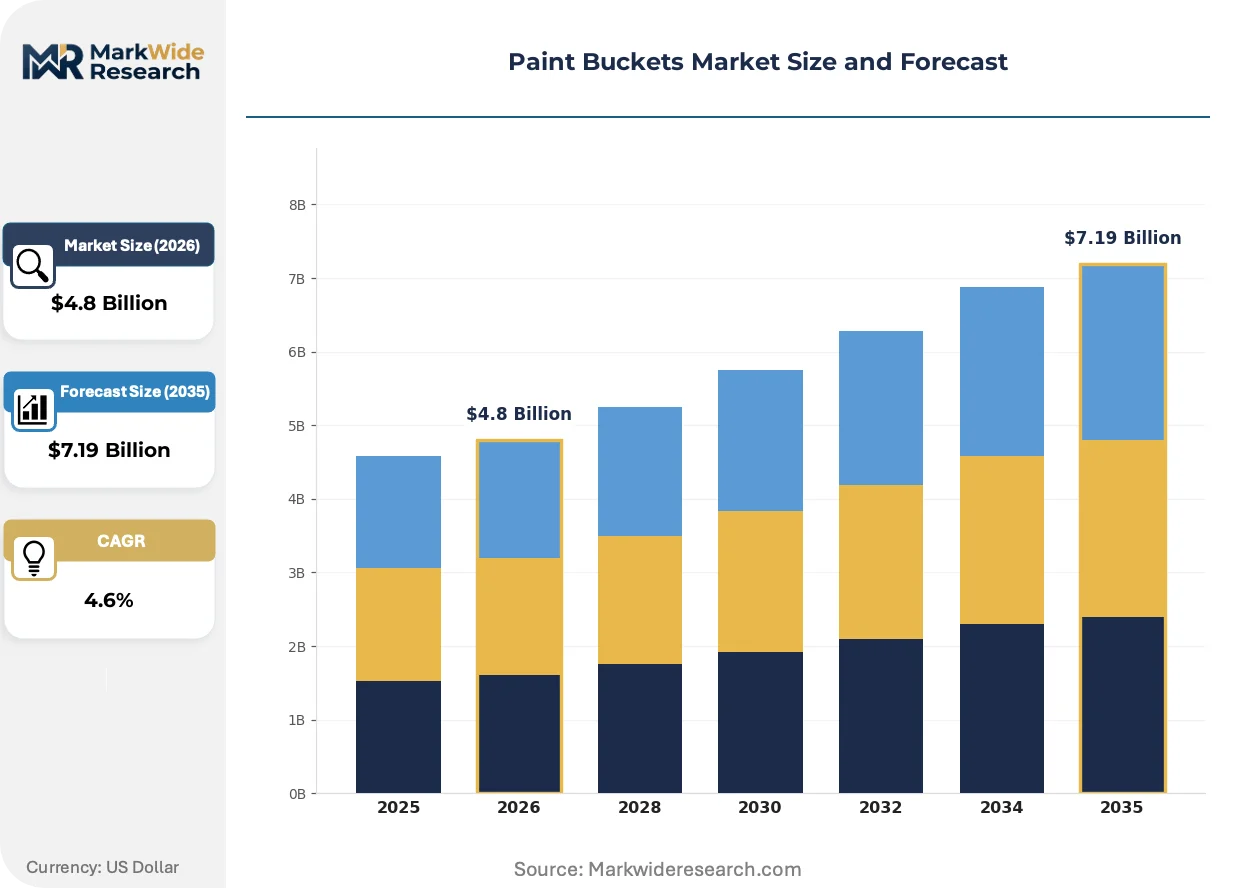
Market Dynamics
Sealed-lid plastic pails are displacing traditional metal containers as residential contractors prioritize resealability and transport safety, while REACH and EPA constraints on volatile compound permeation force material specification upgrades across supplier bases.
Growth Catalysts
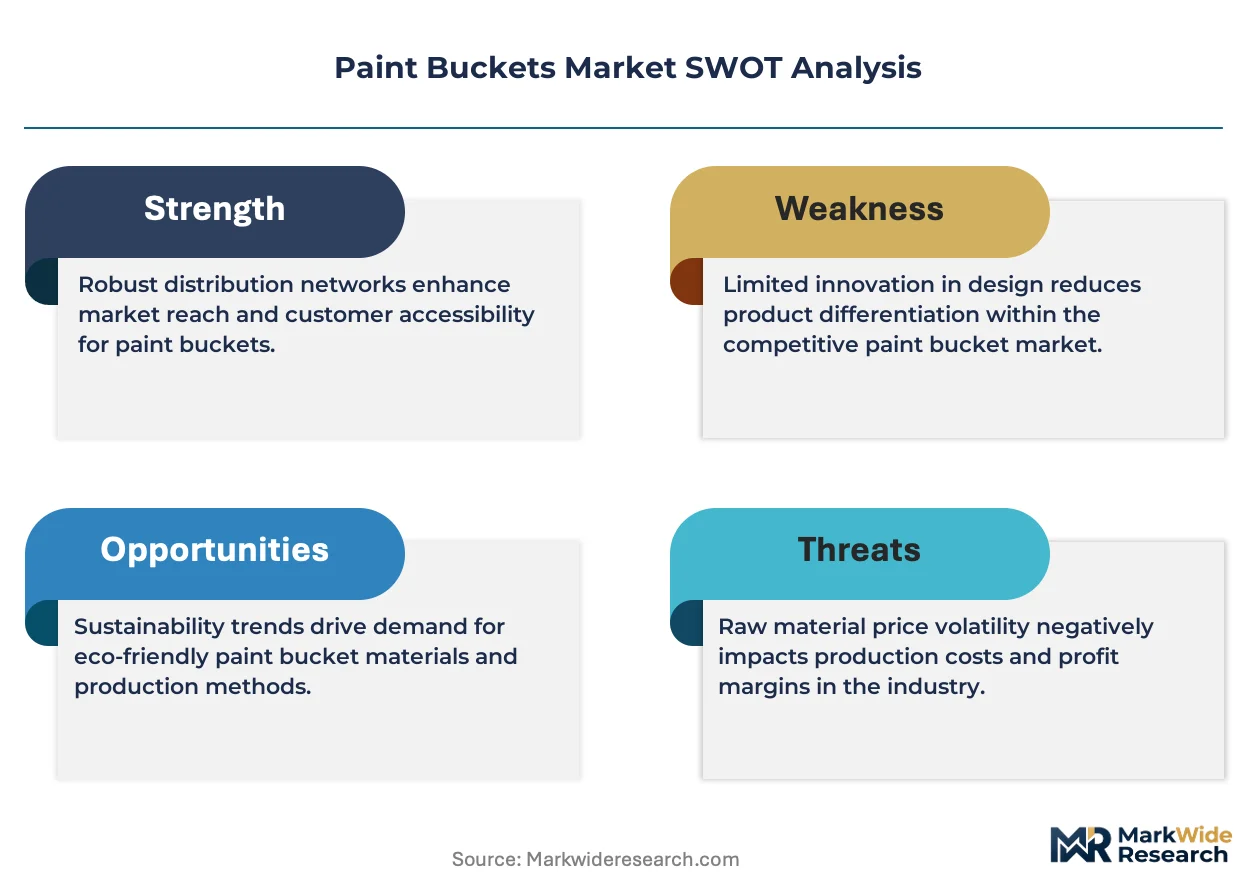
- India infrastructure spending:Central government outlays on urban housing and road networks are accelerating paint consumption and bucket turnover rates among project contractors.
- REACH Substances of Very High Concern disclosure mandates:European compliance requirements are elevating testing protocols for resin formulations, favoring suppliers with certified material traceability systems.
- Multi-layer barrier plastics:Advanced co-extrusion technologies are enabling thinner-wall containers to meet EPA National Emission Standards for Hazardous Air Pollutants permeation thresholds.
Market Restraints
- HDPE resin price volatility:Feedstock fluctuations tied to crude oil markets compress margin predictability for plastic pail manufacturers.
- Tinplate steel supply concentration:Domestic steel capacity constraints in select geographies elevate lead times for solvent-grade metal container procurement.
- Recycled content feedstock scarcity:Extended producer responsibility frameworks are mandating post-consumer resin inclusion without mature secondary material sorting infrastructure.
Strategic Opportunities
- Commercial project scale expansion:Large-format 10-gallon pail demand is rising among industrial coating applicators seeking reduced handling labor.
- OSHA flammable labeling compliance services:Value-added pail pre-labeling partnerships with safety consultants create differentiation for contractor-facing distributors.
- Snap-on lid aftermarket attachment:Retrofit sealing systems for legacy open-head containers address resealability gaps in existing installed bases.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous EPA, REACH, and BIS compliance testing extends product launch cycles by 8-14 months.
- Legacy metal-to-plastic line conversion:Capital equipment for barrier co-extrusion requires reconfiguration of existing injection molding footprints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paint Buckets Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Plastic, Metal, Fiber, Rubber Application: Residential, Commercial, Industrial, Automotive Size: 1 Gallon, 5 Gallon, Quart, 10 Gallon Closure Type: Sealed Lid, Snap-On Lid, Screw Top, Others |
| Companies Covered | Sherwin-Williams, PPG Industries, AkzoNobel, Ball Corporation, RPM International, BWAY Corporation, Berry Global, Ardagh Group, Silgan Containers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paint Buckets Market Strategic Shifts
Container technology is bifurcating between commodity logistics optimization and specialized barrier performance, with regulatory chemistry constraints and contractor workflow preferences driving divergent R&D investment priorities.
Co-extruded nylon-EVOH barrier layers are fragmenting the traditional single-wall HDPE standard by enabling thinner-gauge pails to meet EPA volatile organic compound permeation limits. Commercial painting contractors in the United States are specifying these configurations for solvent-based enamel storage, compressing demand for conventional thick-wall commodity plastics that fail emission thresholds.
REACH Article 33 disclosure obligations for Substances of Very High Concern are forcing resin suppliers to requalify base polymers and eliminate legacy plasticizers from bucket formulations. European paint manufacturers are now requiring full material passports from container vendors, with industrial coating segments most affected due to stricter substance thresholds for workplace chemical exposure.
Contractor purchasing consortiums are consolidating procurement authority for 5-gallon pail volumes, displacing fragmented job-site ordering through distributor mobile platforms. Large residential renovation networks in India are mandating direct-to-warehouse delivery scheduling, bypassing traditional retail hardware channels and compressing distributor margin structures.
Paint Buckets Market Segmentation
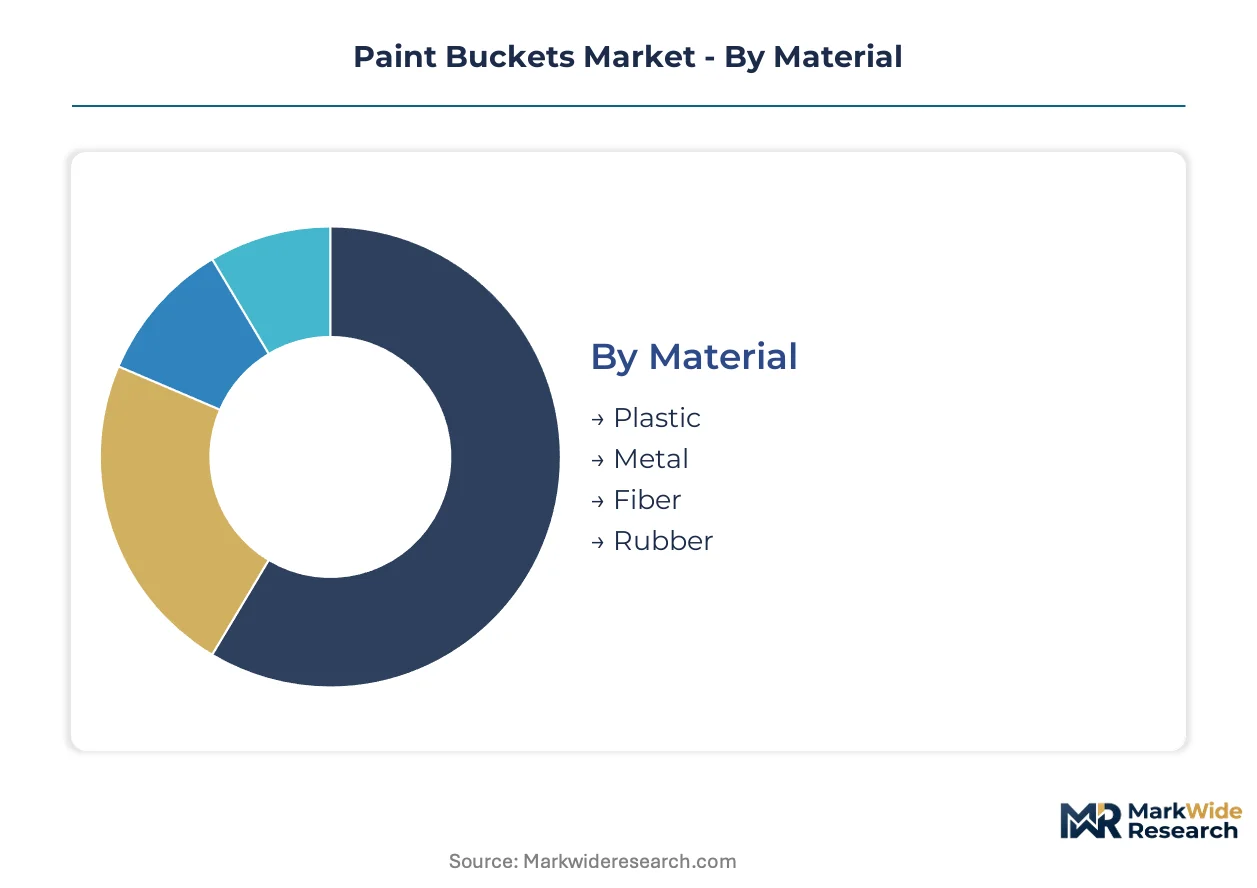
Paint bucket procurement patterns diverge sharply across material grades and closure specifications, with regulatory chemistry constraints and contractor workflow preferences driving divergent sourcing strategies. Segmentation clarity enables suppliers to align co-extrusion investments and lid-system R&D with specific end-use permeation and handling requirements.
Material:
Plastic pails face intensifying substitution pressure from advanced barrier composites as EPA volatile organic compound limits tighten, while metal retains defensive positioning in solvent-based formulations where static discharge protection remains non-negotiable.
- Plastic:High-density polyethylene and co-extruded nylon-EVOH barrier formulations dominate residential and commercial volumes. REACH Article 33 disclosure mandates in Europe and EPA National Emission Standards for Hazardous Air Pollutants in the United States are accelerating multi-layer adoption among exporters to these jurisdictions.
- Metal:Tinplate steel pails engineered with internal linings serve flammable solvent-based coatings where electrical grounding matters. Supply concentration in domestic steel capacity creates procurement lead time vulnerability for industrial coating applicators in India.
- Fiber:Molded fiber-composite containers offer biodegradable positioning for specialty eco-formulation brands. Limited moisture resistance constrains deployment to water-based interior applications.
- Rubber:Flexible rubber buckets address niche portable mixing and cleanup tasks on job sites. Durability limitations prevent adoption for primary storage and transport functions.
Plastic retains volume leadership; fiber-composite holds the steepest expansion curve as sustainability procurement criteria harden.
Application:
Cost tier stratification separates specification-intensive industrial coatings from price-sensitive residential renovation, with commercial projects occupying a middle ground where logistics efficiency and resealability trade off.
- Residential:Snap-on lid plastic pails in 1-gallon and 5-gallon formats dominate renovation contractor procurement. Direct-to-warehouse delivery scheduling through purchasing consortiums is displacing traditional hardware retail channels in India.
- Commercial:Large-format 5-gallon and 10-gallon containers minimize per-unit logistics cost across multi-site projects. Mobile distributor platforms are consolidating fragmented job-site ordering authority.
- Industrial:Solvent-grade metal pails with sealed closures meet OSHA workplace safety standards for flammable contents. Specialized industrial-grade specifications anchor supplier relationships through certified material traceability systems.
- Automotive:Refinish coating storage demands chemical resistance and precise pouring control. Smaller quart and 1-gallon formats align with batch-mixing protocols in collision repair facilities.
Residential commands absolute volume; industrial maintains the highest specification barrier and margin capture.
Size:
Volume concentration around the 5-gallon standard creates manufacturing scale advantages, while peripheral sizes serve workflow-specific handling constraints that resist commoditization.
- 1 Gallon:Compact format suits touch-up work, color sampling, and automotive refinish applications. Retail hardware placement drives brand visibility among DIY consumers.
- 5 Gallon:Industry-standard capacity matches commercial project sizing and minimizes per-unit logistics cost. Co-extruded barrier configurations in this format are displacing thick-wall commodity plastics for solvent-based enamel storage.
- Quart:Smallest standard capacity serves specialty coatings, tinting bases, and precision automotive work. Higher per-ounce packaging cost limits scale economics.
- 10 Gallon:Emerging large-format demand among industrial coating applicators seeks reduced handling labor. Capital equipment for barrier co-extrusion at this scale requires reconfiguration of existing injection molding footprints.
5-gallon formats anchor manufacturing scale; 10-gallon is climbing the fastest as commercial project dimensions expand.
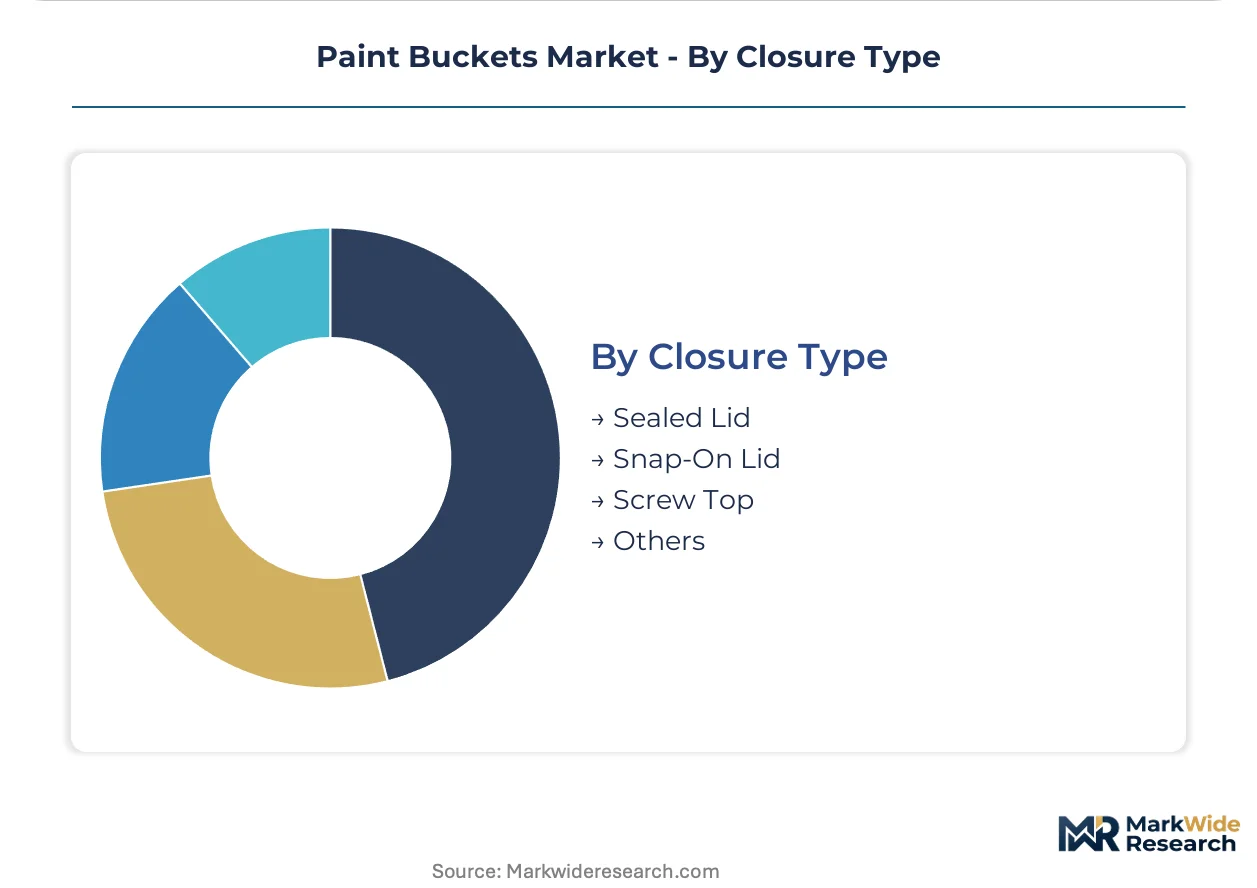
Closure Type:
Customer type segmentation separates contractor-facing resealability requirements from industrial sealed-system imperatives, with aftermarket retrofit opportunities bridging legacy installed bases.
- Sealed Lid:Hermetic closure systems meet EPA volatile organic compound containment mandates for solvent-based formulations. Metal pail configurations with crimped or lever-lock seals serve industrial chemical storage.
- Snap-On Lid:Press-fit plastic closures dominate residential applications where resealability and ease of opening drive contractor preference. Procurement of sealed-lid plastic pails is accelerating among renovation contractors prioritizing transport safety.
- Screw Top:Threaded closure precision suits laboratory and specialty coating applications requiring controlled dispensing. Higher unit cost constrains adoption in volume commercial segments.
- Others:Lever-lock, friction-fit, and custom closure mechanisms address niche regulatory or ergonomic specifications. Limited standardization elevates supplier switching costs.
Snap-on lid configurations dominate unit volume; sealed-lid systems are gaining share fastest as emission regulations tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jawaharlal Nehru Port Trust near Mumbai underwrites India's role as the dominant demand center for paint buckets, handling bulk resin imports and finished container exports across South Asia.
United States
Residential renovation networks and commercial painting contractors drive procurement of sealed-lid plastic pails. EPA National Emission Standards for Hazardous Air Pollutants constrain volatile organic compound permeation through container walls. Houston-Gulf Coast chemical corridor hosts co-extrusion facilities supplying barrier-grade pails to solvent-based coating distributors.
India
Central government infrastructure outlays on urban housing and road networks accelerate paint consumption and bucket turnover rates. BIS certification mandates for plastic containers used in construction materials tighten material specifications. Maharashtra industrial zones near Pune and Nashik concentrate injection molding capacity serving Western India project contractors.
Germany
Industrial coating applicators specify REACH-compliant containers with full material passports for Substances of Very High Concern disclosure. ECHA enforcement elevates testing protocols for resin formulations across exporter supply chains. Ruhr Valley manufacturing clusters produce specialized metal pails for solvent-based automotive refinish coatings.
China
Domestic paint production scale and export-oriented manufacturing sustain demand for standardized 5-gallon formats. NMPA-equivalent standards for chemical packaging materials govern wall thickness and closure integrity requirements. Yangtze River Delta petrochemical corridors feed HDPE resin to container fabricators serving Asia-Pacific distribution.
Brazil
Urban housing programs and commercial construction expansion drive 5-gallon pail consumption among regional paint manufacturers. ANVISA chemical packaging regulations align with Mercosur technical standards for hazardous material containment. São Paulo state industrial districts concentrate blow-molding operations for plastic pail supply to Latin American markets.
Paint Buckets Market Competitive Environment
Concentration sits with diversified packaging conglomerates and captive paint manufacturer channels. The vendor base spans three tiers: multinational steel and plastic container specialists, regional injection molding fabricators, and paint manufacturers with in-house pail production. Strategic moves center on co-extrusion capacity expansion for barrier-grade plastics and direct-to-contractor distribution partnerships bypassing traditional hardware retail.
Within the multinational packaging tier, Ball Corporation and Berry Global exemplify scale-driven manufacturing archetypes. Sherwin-Williams anchors the captive distribution model, securing placement with large contractor accounts through vertically controlled supply chains. PPG Industries occupies a specialized industrial-grade position, with metal pail configurations serving solvent-based coating segments where material traceability systems create switching costs.
| Leading Market Players |
|---|
| Sherwin-Williams |
| PPG Industries |
| AkzoNobel |
| Ball Corporation |
| RPM International |
| BWAY Corporation |
| Berry Global |
| Ardagh Group |
| Silgan Containers |
| Others |
Value Chain & Pricing Dynamics
Forty-five to sixty-day resin procurement lead times in Western India concentrate pricing power with integrated petrochemical suppliers while compressing margin buffers for independent injection molders serving project contractors. This inventory band reveals how raw material access shapes tiered supplier economics across the value chain.
Pricing Analysis
Three-tier pricing structure across premium barrier-grade, standard co-extruded, and economy single-wall levels separates contractor-facing distributors from commodity jobbers. Price differentiation hinges on EPA compliance certification and volume scale, with 5-gallon contract volumes commanding steepest discounts. Cost compression in the economy tier is intensifying because HDPE feedstock volatility transmits directly to thin-margin operators. Residential renovation contractors exhibit highest price sensitivity, while industrial coating applicators prioritize permeation performance over unit cost.
Supply Chain Analysis
Sixty-day tinplate steel order backlogs from domestic Indian mills expose procurement vulnerability for solvent-grade metal pail fabricators. Manufacturing gravity centers on China, India, and Germany, with each node feeding distinct regulatory jurisdictions. HDPE resin, tinplate steel, and EVOH barrier films constitute critical input dependencies. Single-source vulnerability concentrates in European EVOH supply for multi-layer co-extrusion. Distribution runs through contractor purchasing consortiums and direct-to-warehouse platforms, bypassing legacy hardware retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across EPA, REACH, and BIS jurisdictions fragments procurement standards, creating niche openings for certified specialty suppliers. This demand-side complexity rewards focused compliance investment over scale commodity plays.
For Market Incumbents: Fortify barrier co-extrusion capacity in Maharashtra and Texas Gulf Coast corridors to preempt emerging multi-layer demand from solvent-based coating distributors. Backward integration into certified resin sourcing anchors margin defense against feedstock volatility. Secure captive placement with large contractor purchasing consortiums before distributor mobile platforms consolidate ordering authority. For New Entrants and Emerging Players: Anchor in the 10-gallon industrial segment where capital equipment barriers deter commodity competitors and project scale expansion sustains premium capture. Retrofit snap-on lid systems for legacy open-head metal containers address immediate resealability gaps without co-extrusion investment. Partner with OSHA compliance consultants for pre-labeled pail offerings that differentiate on workflow integration. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across barrier-grade plastic fabrication as co-extrusion equipment upgrades outpace single-wall depreciation schedules. Acquisition targets with certified REACH material traceability systems and established contractor direct-delivery relationships offer durable positioning. Monitor BIS enforcement intensity in India as the inflection signal for compliance-premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Co-Extrusion Capacity Expansion | Enables EPA-compliant thinner-wall containers that displace thick commodity plastics in solvent-based segments. |
| Backward Integration into Resin Sourcing | Reduces HDPE price volatility exposure for independent molders serving price-sensitive residential contractors. |
| Direct-to-Contractor Distribution Partnerships | Bypasses hardware retail margin compression from purchasing consortium consolidation in India and North America. |
| REACH Material Passport Certification | Creates switching costs with European industrial coating manufacturers facing Article 33 disclosure mandates. |
| OSHA Pre-Labeling Service Integration | Differentiates distributor offerings through workflow-embedded safety compliance for flammable contents handling. |
Study Parameters
Operator-level perspectives from plant managers at injection molding facilities, procurement leads at paint manufacturers, distributor channel heads, and contractor purchasing consortium coordinators anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through customs trade records, BIS certification databases, SEC filings of listed packaging conglomerates, and EPA enforcement action logs. Bottom-up capacity assessments triangulated against top-down paint consumption estimates.
Sensitivity analysis around resin price scenarios and regulatory enforcement intensity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include material grade, closure type, application tier, and regional regulatory cluster. CAGRs derived from installed capacity expansion schedules, project pipeline visibility, and substitution elasticity between metal and barrier plastic formats. Coating formulation shifts toward water-based versus solvent-based systems constituted a critical demand-side input.
Decision-makers should treat outputs as directional under stable regulatory enforcement and resin supply continuity assumptions; material deviation would warrant model refresh. Specific risk factors include abrupt BIS specification changes, EVOH supply disruptions, and contractor purchasing platform consolidation beyond forecasted rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Qatar Paints and Coatings Market
Paints & Coatings
South America Paints and Coatings Additives Market
Paints & Coatings
Solar Paint Market
Paints & Coatings
Global Paints and Coatings Fillers Market
Paints & Coatings
Middle East and Africa Floor Coatings Market
Paints & Coatings
Paint Mixing Market
Paints & Coatings
Floor Paints Market
Paints & Coatings
India Automotive Paints and Coatings Market
Paints & Coatings
Hybrid Paint Cans Market
Paints & Coatings
GCC Paints and Coatings Market
Paints & Coatings
Architectural Coatings Market
Paints & Coatings
Global Texture Paint Market
Paints & Coatings
Water Color Market
Paints & Coatings
Faux Finish Coatings Market
Paints & Coatings
Industrial Paint Booth Market
Paints & Coatings
Europe Architectural Coatings Market