
 Asia-Pacific Paint Thinner Market | 2026-2036
Asia-Pacific Paint Thinner Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Paint Thinner Market Analytics
Buyer concentration in the Asia-Pacific paint thinner supply chain is consolidating, as large construction and automotive OEMs reduce vendor counts and demand bulk supply agreements. Nippon Paint Holdings Co. Ltd leverages its integrated distribution network across Japan and Southeast Asia to secure long-term solvent contracts. Asian Paints anchors South Asian demand through captive blending facilities and direct-to-contractor channels. Kansai Paint Co. Ltd competes on specialty thinner formulations for automotive refinish applications.
Paint thinner comprises volatile organic solvent blends—typically aliphatic hydrocarbons, ketones, or esters—with evaporation rates between 0.5 and 5.0 relative to n-butyl acetate, formulated to reduce coating viscosity for spray or brush application. Acetone and ethyl acetate segments lead volume due to their compatibility with waterborne and high-solids coatings gaining preference in regulated markets. Toluene and xylene categories retain share in industrial maintenance and marine coating sectors where strong solvency power commands premium positioning. Surface preparation and paint thinning applications together dominate the application matrix, though cleaning formulations for equipment maintenance represent the fastest-growing margin pool as workshops face stricter workplace chemical exposure rules.
China's MEE enforces GB standards limiting benzene and aromatic content in commercial thinners, while India's BIS certification mandates flash point and purity testing for imported solvent blends. Japan's METI chemical management framework pushes manufacturers toward toluene-free alternatives through supply chain disclosure requirements. Stakeholders must monitor divergence between national solvent regulations and the cost economics of reformulation versus import substitution across the region's fragmented compliance landscape.
Market Dynamics
China's dual carbon goals and updated GB standards on solvent emissions are forcing reformulation across the Asia-Pacific paint thinner supply chain, compressing aromatic content while elevating bio-based and low-VOC alternatives.
Growth Catalysts
- Construction sector procurement:Large contractors across India and Southeast Asia are consolidating vendor relationships and demanding bulk supply agreements for low-VOC thinners on green building projects.
- GB standards enforcement:China's MEE is tightening benzene and aromatic content limits, accelerating technical substitution toward acetone and ethyl acetate formulations.
- Automotive refinish specialization:Premium thinner blends for collision repair shops are commanding sustained demand as vehicle parc expansion continues across Indonesia and Thailand.
Market Restraints
- Aromatic feedstock volatility:Toluene and xylene input costs fluctuate with crude refining margins, squeezing blenders dependent on petroleum-derived solvents.
- Supply concentration risk:India's western industrial corridor from Gujarat through Maharashtra hosts disproportionate solvent production capacity, creating geographic vulnerability.
- Technical substitution ceiling:Marine coating and industrial maintenance segments retain strong solvency requirements that bio-based alternatives cannot yet satisfy.
Strategic Opportunities
- Equipment cleaning formulations:Workshop chemical exposure rules under Japan's METI framework are opening margin pools for specialized maintenance thinners with reduced toxicity profiles.
- Waterborne coating compatibility:Thinner lines engineered for high-solids and waterborne systems are capturing preference as India's BIS certification expands purity testing mandates.
- Direct-to-contractor channels:Captive blending facilities integrated with distribution networks can bypass traditional chemical distributors in South Asian markets.
Industry Challenges
- Reformulation capex intensity:Blending equipment upgrades and R&D facilities require significant capital outlay to meet divergent national solvent regulations.
- Compliance timeline fragmentation:China's GB standards, India's BIS certification, and Japan's METI disclosure requirements operate on asynchronous implementation schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Paint Thinner Market |
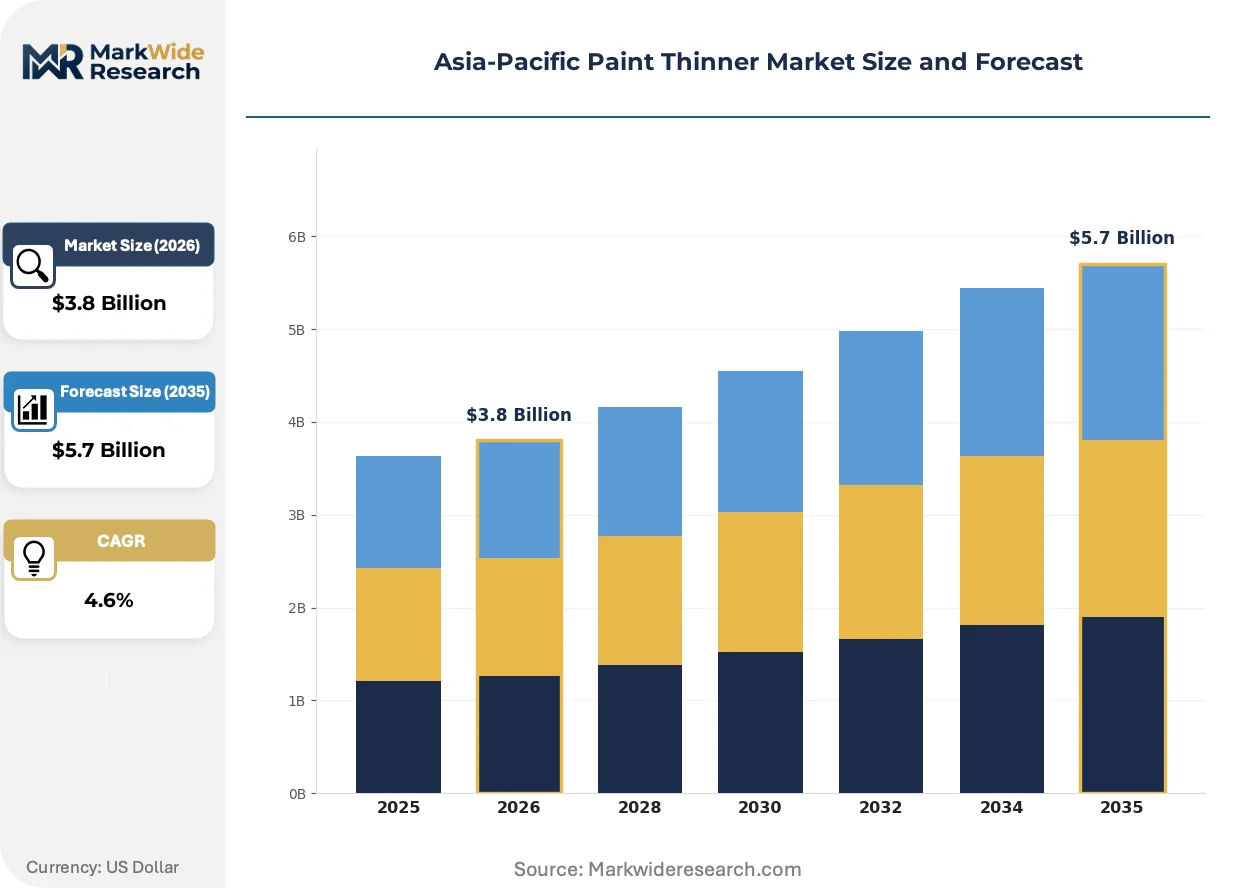
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acetone, Ethyl Acetate, Toluene, Xylene End User: Construction, Automotive, Furniture, Industrial Distribution Channel: Online, Offline, Direct Sales, Retail Application: Surface Preparation, Paint Thinning, Cleaning, Coating |
| Companies Covered | Nippon Paint Holdings Co. Ltd, Kansai Paint Co. Ltd, Asian Paints, PPG Industries Inc., Akzo Nobel N.V., Jotun, Hempel A/S, Axalta Coating Systems, KCC Corp., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Paint Thinner Market Evolving Landscape
Formulation chemistry and distribution architecture are converging to reshape competitive positioning across the Asia-Pacific paint thinner landscape. Three developments are compressing traditional supply relationships.
Hybrid solvent systems combining bio-derived esters with conventional aliphatic hydrocarbons are unifying performance and sustainability requirements for automotive OEM coating lines. Japanese and South Korean manufacturers are adopting these blends at accelerated rates to satisfy METI supply chain disclosure mandates. The technology is unifying previously separate premium and standard product tiers into single-platform formulations.
China's MEE enforcement of updated GB standards on benzene content is eliminating high-aromatic thinners from commercial construction applications. Industrial blenders must recertify product lines or exit the regulated segment entirely. Automotive refinish shops in coastal provinces are responding fastest, switching to toluene-free alternatives ahead of compliance deadlines.
Buyer concentration among large construction and automotive OEMs is compressing procurement cycles and demanding integrated supply contracts. Traditional chemical distributors are losing share to direct manufacturer relationships in India's western industrial corridor. Gujarat and Maharashtra-based contractors are most visible in this shift, negotiating multi-year solvent agreements with captive blending facilities.
Asia-Pacific Paint Thinner Market Segmentation
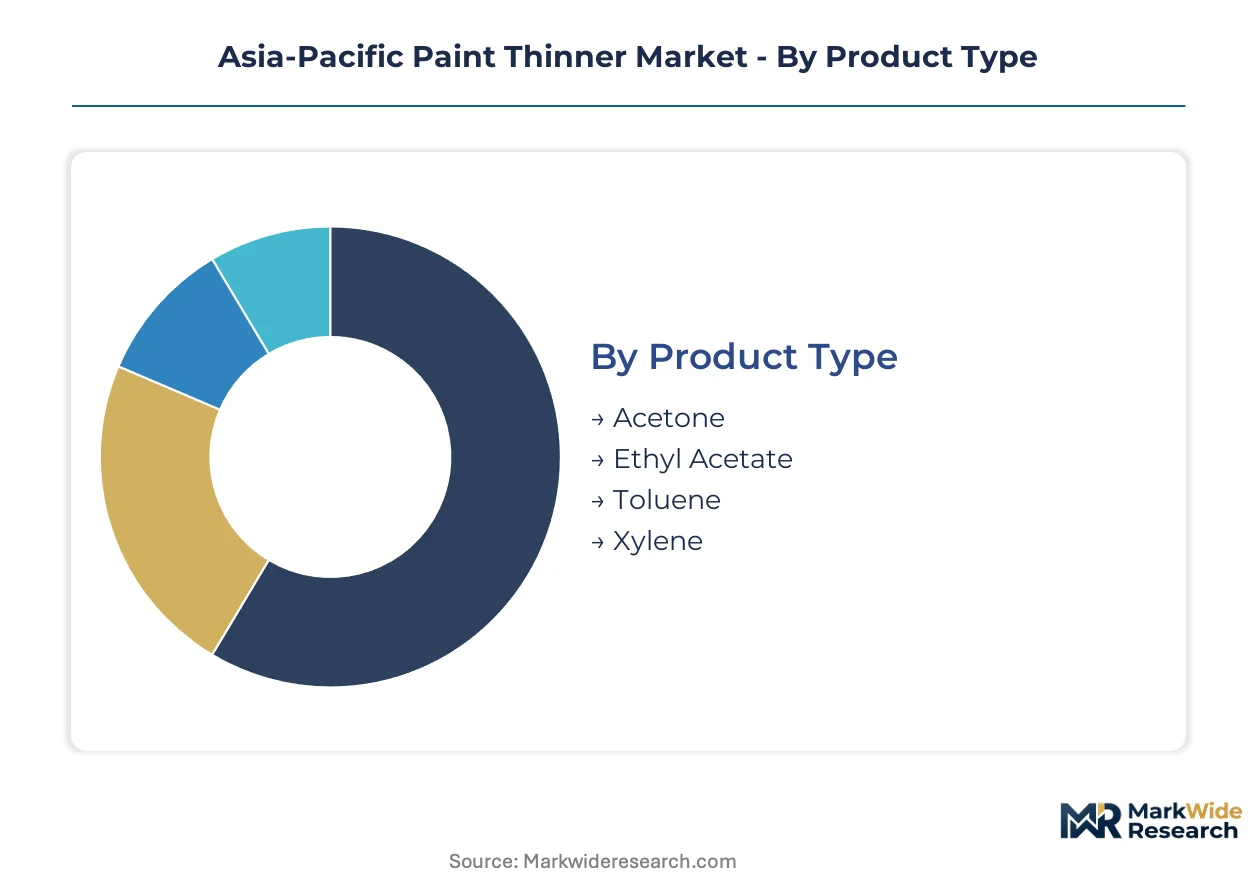
Segmentation in the Asia-Pacific paint thinner market reveals how formulation chemistry, procurement channels, and end-use specifications fragment demand across incompatible technical requirements. Each dimension carries distinct margin structures and regulatory exposure that shape competitive positioning.
Product Type:
Customization intensity varies sharply across solvent chemistries, with oxygenated compounds demanding precise moisture control while aromatic hydrocarbons compete on bulk purity grades.
- Acetone:This ketone solvent delivers rapid evaporation with complete water miscibility, making it indispensable for waterborne coating systems. Demand concentrates in China's automotive OEM coating lines where MEE enforcement of GB standards on benzene content accelerates technical substitution away from aromatic alternatives.
- Ethyl Acetate:A medium-evaporation ester prized for its mild odor and broad resin compatibility, particularly with acrylic and nitrocellulose binders. India's western industrial corridor from Gujarat through Maharashtra drives procurement volume as furniture manufacturers and automotive refinish shops seek BIS-certified low-toxicity formulations.
- Toluene:High solvency power positions this aromatic for industrial maintenance and marine coating segments where coating performance trumps VOC constraints.
- Xylene:Slower evaporation profile suits high-build industrial coatings; demand persists in Southeast Asian shipyard maintenance despite regulatory pressure.
Leading the category by volume: Acetone. Growing fastest: Ethyl Acetate.
End User:
Margin capture diverges by buyer scale, with large contractors extracting volume discounts while small workshops pay premiums for specialized packaging.
- Construction:Large contractors across India and Southeast Asia consolidate vendor relationships for bulk supply agreements on green building projects. India's BIS certification mandates on flash point and purity testing filter out informal blenders from formal procurement channels.
- Automotive:Collision repair shops in Indonesia and Thailand command premium thinner blends with controlled evaporation profiles for metallic and pearl finishes. Japan's METI chemical management framework pushes refinish networks toward toluene-free alternatives through supply chain disclosure requirements.
- Furniture:Nitrocellulose lacquer thinners dominate this segment, with demand clustering in Vietnam and Malaysia export manufacturing zones.
- Industrial:Marine coating and heavy equipment maintenance retain strong solvency requirements that bio-based alternatives cannot yet satisfy.
Construction leads procurement volume. Automotive climbs fastest on refinish specialization.
Distribution Channel:
Channel selection reflects buyer technical sophistication and order scale, with direct relationships displacing traditional distributors among large accounts.
- Online:Digital procurement platforms gain traction among small contractors and independent workshops seeking transparent pricing on standard grades.
- Offline:Traditional chemical distributors retain relevance for technical consultation and just-in-time delivery to mid-sized users.
- Direct Sales:Captive blending facilities integrated with manufacturer distribution networks bypass intermediaries in South Asian markets. Asian Paints anchors this channel through direct-to-contractor relationships across India.
- Retail:Hardware store and specialty coating outlets serve the consumer DIY and small professional segments with packaged liter and gallon formats.
Direct sales commands the largest revenue share. Online channels expand most quickly on SME buyer digitization.
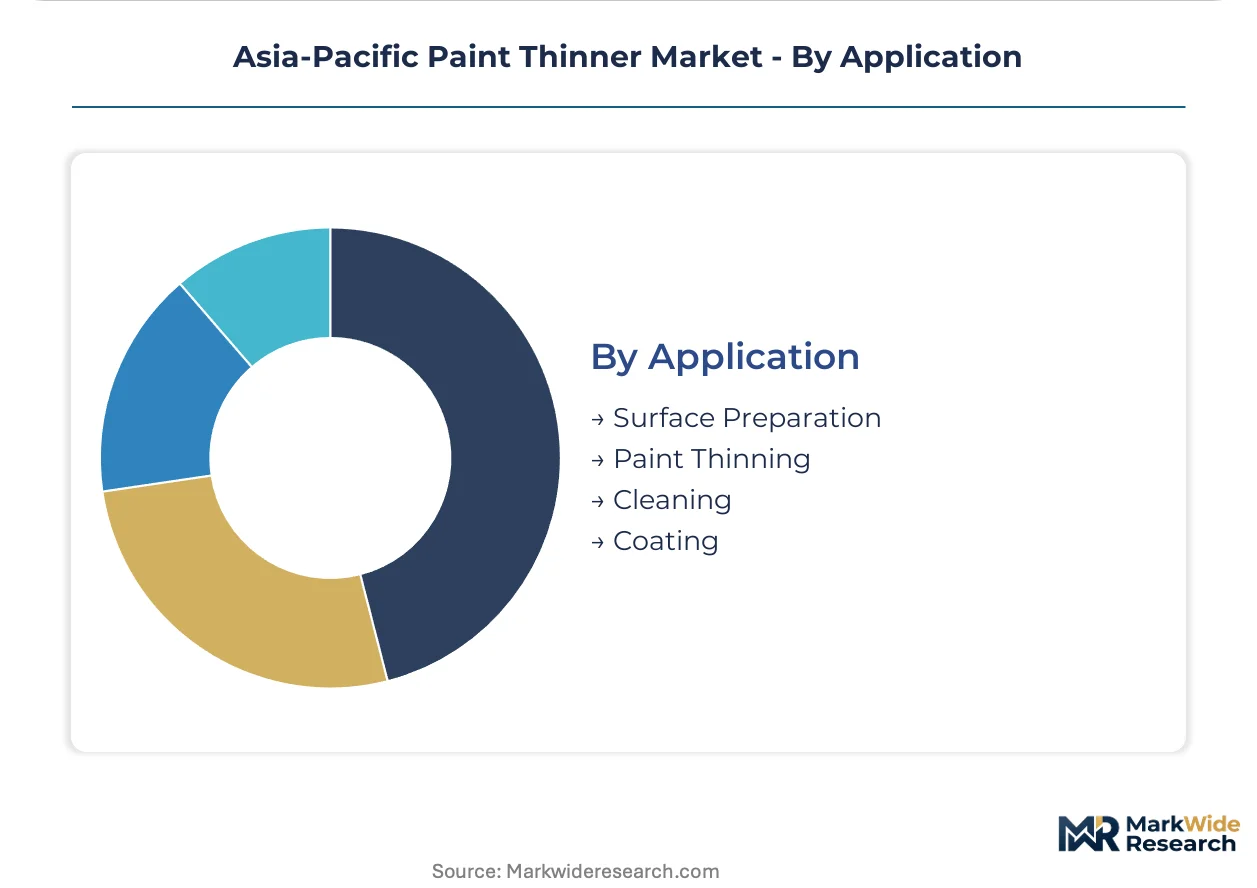
Application:
Application-specific formulations separate commodity thinners from value-added blends with technical service attachments.
- Surface Preparation:Degreasing and substrate cleaning formulations require controlled evaporation to prevent moisture entrapment. Japan's METI framework on workshop chemical exposure rules opens margin pools for specialized maintenance thinners with reduced toxicity profiles.
- Paint Thinning:Core viscosity reduction function spans all coating chemistries, with formulation precision determining spray transfer efficiency and film appearance.
- Cleaning:Equipment maintenance thinners face the steepest expansion trajectory as workshops confront stricter workplace chemical exposure regulations across the region.
- Coating:Specialized carrier solvents for high-solids and powder coating systems command premium positioning in automotive OEM lines.
Paint thinning dominates absolute volume. Cleaning applications gain share fastest on regulatory compliance spending.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical feedstock availability along China's eastern seaboard and the Arabian Gulf underpins solvent production economics across the Asia-Pacific. Refinery integration in these zones determines regional supply responsiveness to formulation shifts. Construction and automotive OEM demand clusters then dictate where blending capacity concentrates.
China
Automotive OEM coating lines and commercial construction drive acetone-based thinner consumption. The Ministry of Ecology and Environment enforces updated GB standards limiting benzene and aromatic content, forcing reformulation across industrial blenders. Yangtze River Delta refineries and chemical parks near Shanghai supply the oxygenated solvents displacing legacy aromatic formulations.
India
Furniture manufacturing in Gujarat and automotive refinish shops across Maharashtra anchor ethyl acetate procurement. The Bureau of Indian Standards mandates flash point and purity testing for imported solvent blends, filtering informal suppliers from formal channels. The western industrial corridor from Ahmedabad through Mumbai hosts disproportionate blending capacity and direct-to-contractor distribution experiments.
Japan
Collision repair networks and specialty automotive coating operations sustain demand for controlled-evaporation thinner blends. The Ministry of Economy, Trade and Industry chemical management framework pushes refinish shops toward toluene-free alternatives through supply chain disclosure requirements. Kansai and Chubu manufacturing zones adopt hybrid bio-derived ester formulations fastest to satisfy METI mandates.
South Korea
Automotive OEM coating lines and electronics manufacturing propel ketone and ester solvent consumption. The Ministry of Food and Drug Safety and national chemical management frameworks align with broader East Asian regulatory trajectories on VOC reduction. Daegu-Gyeongbuk and Busan-Ulsan industrial corridors concentrate blending capacity serving both domestic OEMs and export coating operations.
Vietnam
Export-oriented furniture manufacturing and shipyard maintenance operations split demand between nitrocellulose lacquer thinners and high-solvency marine formulations. National chemical safety regulations evolve toward ASEAN harmonization while enforcement capacity lags industrial growth. Ho Chi Minh City and surrounding manufacturing zones absorb reformulated solvent imports as domestic blending infrastructure develops.
Asia-Pacific Paint Thinner Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-based and low-VOC formulation spaces where technical differentiation commands premium positioning. The vendor base clusters around three strategic archetypes: integrated paint manufacturers with captive solvent operations, independent chemical blenders serving industrial maintenance segments, and regional distributors consolidating procurement for mid-sized contractors. Capacity expansion and direct channel development dominate competitive moves as large buyers reduce vendor counts.
Among Japan-based coating specialists, Nippon Paint Holdings Co. Ltd and Kansai Paint Co. Ltd exemplify integrated manufacturer archetypes with solvent supply tied to core coating operations. Asian Paints occupies a position representing South Asian market anchoring through distribution network control. These three entities represent contrasting geographic and structural approaches to securing feedstock access and end-user relationships across the region's fragmented regulatory landscape.
| Leading Market Players |
|---|
| Nippon Paint Holdings Co. Ltd |
| Kansai Paint Co. Ltd |
| Asian Paints |
| PPG Industries Inc. |
| Akzo Nobel N.V. |
| Jotun |
| Hempel A/S |
| Axalta Coating Systems |
| KCC Corp. |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between BIS-validated formulations and uncertified commodity blends splits the Asia-Pacific paint thinner market into incompatible procurement tiers. This bifurcation concentrates pricing power with Gujarat and Maharashtra-based blenders who control direct-to-contractor channels, while informal suppliers face margin compression from purity testing mandates and flash point compliance costs.
Pricing Analysis
Warranty and technical service bundling separate premium acetone and ethyl acetate formulations from unassured commodity toluene blends. Three-tier pricing structure across certified premium, standard industrial, and economy solvent tiers reflects BIS certification status, volume commitment scale, and after-sales technical support inclusion. Pricing pressure stems from aromatic feedstock volatility tied to crude refining margins, squeezing blenders dependent on petroleum-derived xylene and toluene. Small furniture workshops and independent collision repair shops exhibit highest price sensitivity, while automotive OEM coating lines accept premium positioning for guaranteed compliance documentation.
Supply Chain Analysis
BIS certification and METI supply chain disclosure requirements gate formal market access, filtering out uncertified importers and informal blenders. Feedstock concentration centers on China's Yangtze River Delta refineries for oxygenated solvents and India's western industrial corridor for blending capacity, with secondary sourcing from South Korean petrochemical complexes. Raw material dependencies rest on naphtha cracking outputs, bio-derived ester feedstocks, and catalytic reforming byproducts. Single-source vulnerability runs through concentrated aromatics production in coastal China. Distribution feeds from captive blending facilities integrated with manufacturer networks, bypassing traditional chemical distributors in South Asian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where China's MEE enforcement of updated GB standards on benzene content erects capital-intensive barriers that favor incumbent blenders with existing certification infrastructure and captive R&D facilities.
For Market Incumbents: To counter feedstock volatility and aromatic substitution pressure, deepen backward integration into bio-derived ester supply chains and expand captive blending capacity in India's western industrial corridor. Lock in multi-year solvent agreements with construction contractors consolidating vendor relationships for green building procurement. For New Entrants and Emerging Players: Begin with specialized equipment cleaning formulations for Japanese collision repair networks facing METI chemical exposure rule compliance, where premium positioning and reduced toxicity profiles command margin pools underserved by commodity blenders. Target direct-to-contractor digital procurement platforms in Vietnam's furniture export manufacturing zones. For Investors and Strategic Acquirers: Re-rating potential sits with BIS-certified mid-cap blenders possessing Gujarat or Maharashtra production assets given India's expanding purity testing mandates and western corridor demand concentration. Watch for inflection when China's MEE accelerates GB standards enforcement timelines, forcing recertification waves that eliminate subscale competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Derived Feedstocks | Secures supply chain resilience against petroleum aromatic volatility and MEE regulatory substitution mandates. |
| Captive Blending Facility Expansion | Asian Paints and integrated manufacturers bypass distributor margins through direct-to-contractor channels in Maharashtra. |
| BIS Certification Investment | Flash point and purity testing compliance filters informal competitors from India's formal procurement channels. |
| Long-term Supply Agreement Structuring | Multi-year solvent contracts with consolidated construction vendors reduce procurement cycle volatility. |
| Joint Venture with Automotive Refinish Networks | Indonesia and Thailand collision repair shops demand controlled-evaporation blends for metallic finish applications. |
Research Methodology
Multi-period observation of solvent import volumes, refinery integration patterns, and certification compliance rates anchored the trend analysis, supplemented by interviews with plant managers at blending facilities, procurement leads at automotive OEM coating lines, distribution channel partners, and technical R&D directors. Secondary validation drew from customs and trade data, BIS certification registries, MEE enforcement disclosures, and SEC filings of listed coating manufacturers. Bottom-up demand modeling triangulated against top-down petrochemical feedstock availability assessments.
Segment-weighting across product type, end user, distribution channel, and application dimensions shaped the analytical framework across the projection horizon. CAGRs derived from solvent consumption intensity by coating chemistry, construction sector green building certification trajectories, and automotive parc expansion rates in Indonesia and Thailand. Modeled inputs included refinery capacity additions in China's eastern seaboard and India's western industrial corridor.
Underlying measurement precision varies by segment; BIS-certified and METI-disclosed product categories carry tighter precision than informal commodity trade. Forecasts reflect assumptions on regulatory enforcement timelines and feedstock cost trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Middle-East Paints and Coatings Additives Market
Paints & Coatings
UAE Architectural Paints and Coatings Market
Paints & Coatings
Paint Defoamers Market
Paints & Coatings
Bio-Based and Low VOC Paints Market
Paints & Coatings
Global Decorative Coatings Market
Paints & Coatings
Acrylic Paints Market
Paints & Coatings
Qatar Paints and Coatings Market
Paints & Coatings
Asia-Pacific Paints and Coatings Additives Market
Paints & Coatings
Asia-Pacific Paint Spray Guns Market
Paints & Coatings
Saudi Arabia Architectural Paints Market
Paints & Coatings
Core Plate Varnishes Market
Paints & Coatings
Bituminous Paints Market
Paints & Coatings
Global Anti-Formaldehyde Paint Market
Paints & Coatings
Oman Paints and Coatings Market
Paints & Coatings
Automotive Paints and Coatings Market
Paints & Coatings
Wall Putty Powder Market