
 India Automotive Paints and Coatings Market | 2026-2036
India Automotive Paints and Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
India Automotive Paints and Coatings Market Foresight
Multi-source procurement from global chemical suppliers is decoupling from traditional single-source resin agreements across India's automotive coating value chain. Asian Paints leverages its domestic distribution network to sustain volume leadership in OEM supply contracts. Kansai Nerolac Paints anchors its position through backward integration into key resin intermediates. BASF competes on technology leadership in waterborne basecoat systems for premium vehicle programs.
Automotive paints and coatings constitute formulated liquid or powder systems comprising binders, pigments, solvents, and functional additives, applied to vehicle body panels and components to provide corrosion protection, aesthetic finish, and surface durability against environmental degradation. Their primary purpose spans new vehicle manufacturing, collision damage repair, and aftermarket refinishing across passenger cars, commercial vehicles, and two-wheelers. Waterborne technology commands expanding share as environmental compliance tightens, while solventborne systems retain dominance in commercial vehicle and refinish segments where performance requirements remain stringent. Powder coating applications are penetrating underbody and wheel components where edge coverage and chip resistance justify capital-intensive application equipment.
BIS standards govern coating formulation compliance for domestic automotive applications, while the Automotive Research Association of India enforces emission and durability testing protocols that directly shape product development cycles. The PLI scheme for automobile and auto component manufacturing is redirecting coating demand toward localized supply chains as OEMs expand domestic assembly capacity. Stakeholders must monitor how REACH-aligned chemical restrictions propagate through Indian import regulations and whether waterborne technology investments keep pace with OEM sustainability commitments.
Market Dynamics
Waterborne coating technology is displacing solventborne systems across India's passenger vehicle OEM segment as BIS emission norms tighten and Maruti Suzuki, Tata Motors, and Hyundai Motor India scale domestic production capacity.
Growth Catalysts
- PLI scheme for automobile manufacturing:Production-linked incentives are redirecting coating procurement toward localized supply chains as OEMs expand assembly capacity in Gujarat and Tamil Nadu.
- Maharashtra and Gujarat production clusters:Concentration of major OEM body shops in these states is generating dense demand pockets for just-in-time coating supply contracts.
- Waterborne basecoat technology:Environmental compliance mandates from BIS and state pollution control boards are accelerating specification shifts in premium vehicle programs.
Market Restraints
- Petrochemical resin price volatility:Crude-linked raw material costs for acrylic and polyurethane intermediates compress formulation margins unpredictably.
- Import dependency for specialty additives:Concentrated supply from German and Japanese chemical majors creates forex exposure and delivery risk.
- Solventborne performance floor in commercial vehicles:BIS durability standards for heavy-duty applications maintain technology lock-in despite environmental pressure.
Strategic Opportunities
- Two-wheeler refinish underpenetration:India's vast independent repair sector offers white space for organized coating distribution networks.
- Powder coating wheel and underbody applications:Chip resistance requirements in these segments justify capital investment in electrostatic application lines.
- REACH-aligned chemical pre-registration:Early compliance with anticipated Indian import restrictions on hazardous substances creates first-mover positioning.
Industry Challenges
- Waterborne application technician scarcity:Humidity-controlled spray booth operation and flash-off management require specialized training absent in India's current workforce.
- BIS certification timeline compression:Extended approval cycles for new formulations delay product launches and contract renewals.
- Legacy solventborne inventory stranding:OEMs face write-down risk on existing coating stocks during technology transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Automotive Paints and Coatings Market |
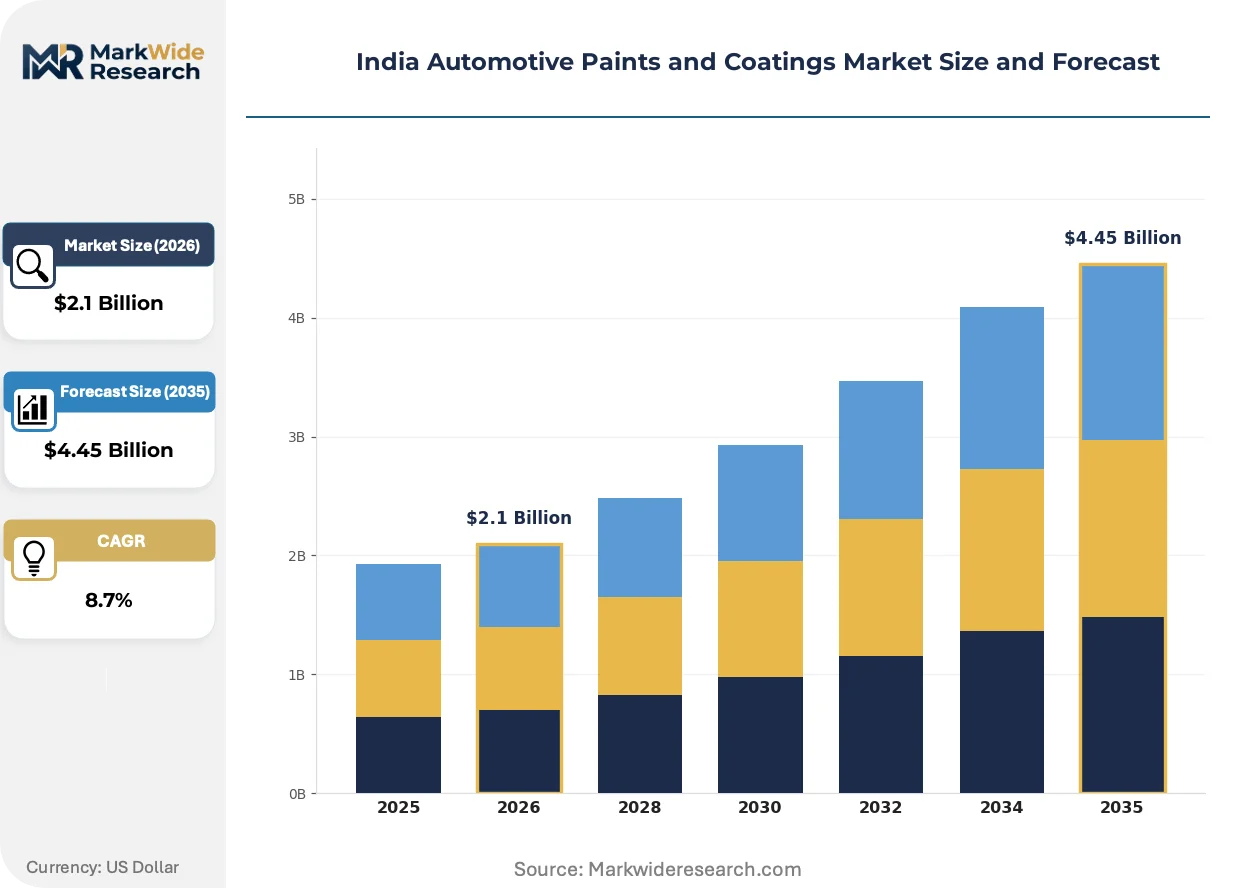
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pearlescent, Matte, Glossy, Metallic Application: OEM, Aftermarket, Collision Repair, Specialty Technology: Waterborne, Solventborne, Powder Coating, UV-Cured Delivery Mode: Direct Sales, Distributors, Retailers, Online |
| Companies Covered | JSW Paints, Axalta Coating Systems, Asian Paints, PPG Industries, BASF, Kansai Nerolac Paints, Nippon Paint Holdings, Jotun, Berger Paints India, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Automotive Paints and Coatings Market Shifts & Advancements
Coating formulation and application technology is fragmenting across multiple performance tiers as OEM sustainability commitments diverge from commercial vehicle cost floors and refinish channel economics.
Self-healing clearcoat chemistry is modularizing repair cost structures across India's premium passenger vehicle segment. Maruti Suzuki's Nexa dealerships and Hyundai's premium outlets are specifying these formulations for scratch-resistant topcoats. The technology is modularizing aftermarket service revenue models by extending repaint intervals and compressing warranty claim exposure.
BIS certification mandates for automotive coatings are tightening volatile organic compound thresholds in alignment with state-level pollution control directives. The Automotive Research Association of India is enforcing accelerated weathering protocols that extend product development cycles by 8-12 months. Passenger vehicle OEMs are responding with dedicated compliance teams and pre-submission testing partnerships.
Multi-brand collision repair networks are consolidating procurement authority previously dispersed across thousands of independent body shops. Mahindra First Choice Services and Carnation Auto are centralizing coating specification and volume contracting. This concentration is most visible in Delhi-NCR and Bengaluru where organized chains now capture 35-40 percent of insured repair volume.
India Automotive Paints and Coatings Market Segmentation
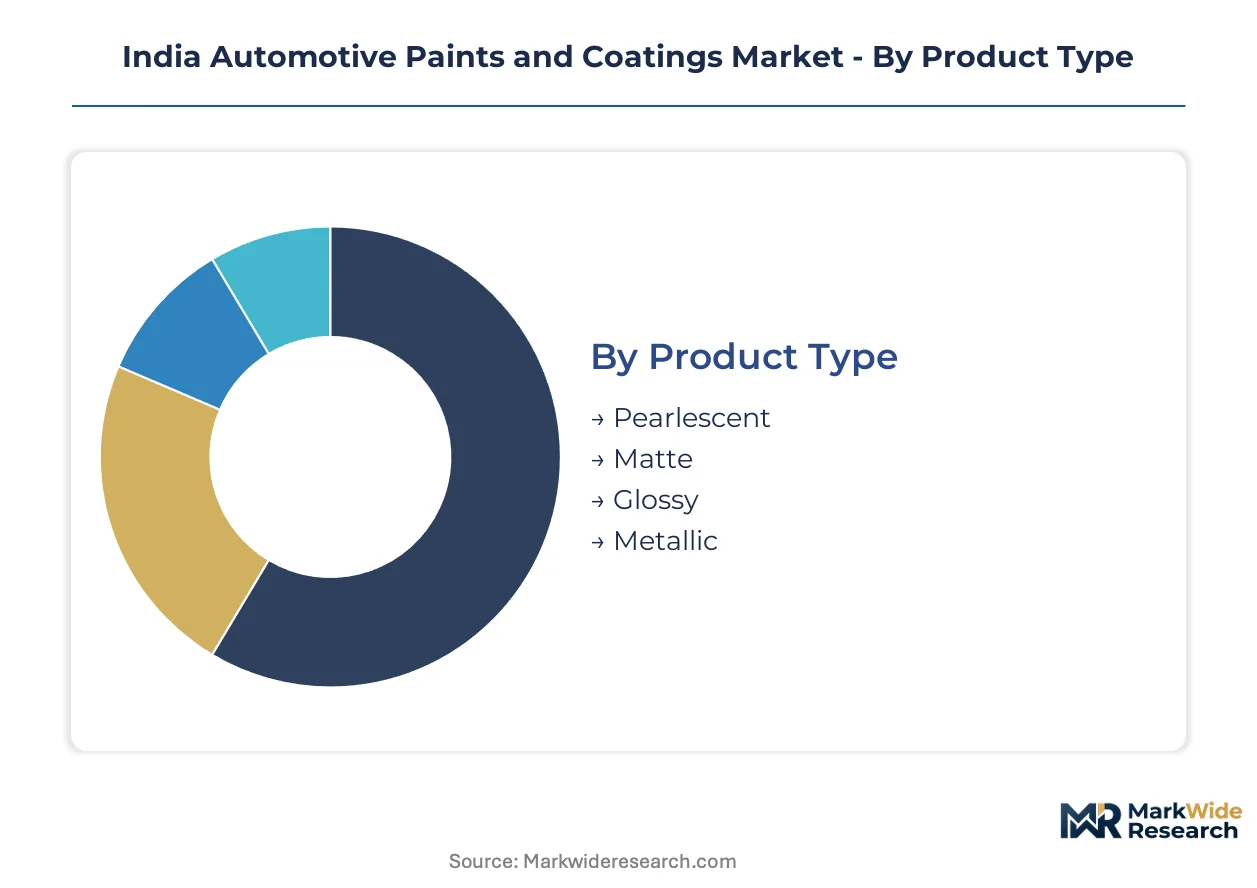
Automotive coating procurement in India fragments across performance tiers, application environments, and regulatory compliance levels. Each segmentation axis reveals distinct margin structures and supplier capability requirements that shape competitive positioning.
Product Type:
Finish customization spans from standardized solid colors to premium effect coatings with layered optical properties and specialized application protocols.
- Metallic:Aluminum flake suspensions in acrylic or polyurethane binders create depth and light reflection. Passenger vehicle OEMs in Maharashtra and Gujarat specify metallic finishes for 60-70 percent of premium sedan and SUV programs, driven by consumer preference for visual differentiation in congested urban traffic conditions.
- Pearlescent:Mica-based interference pigments generate color-shift effects through thin-film optical interference. Demand concentrates in Hyundai Motor India and Tata Motors luxury variants where showroom appeal justifies 15-20 percent formulation cost premiums and extended spray booth cycle times.
- Glossy:High-solids clearcoat systems dominate mass-market vehicle production with standardized application parameters and rapid line speeds.
- Matte:Silica-modified topcoats with controlled surface roughness require specialized masking protocols and restricted repair accessibility.
Leading the category by volume: Glossy finishes. Expanding most quickly: Pearlescent coatings.
Application:
Channel economics diverge sharply between integrated OEM body shops and fragmented independent repair networks with disparate technical capabilities.
- OEM:Original equipment manufacturing consumes formulated coatings through automated electrostatic spray lines with robotic application and integrated curing ovens. Maruti Suzuki's Gurugram and Ahmedabad facilities anchor procurement volume, with just-in-time delivery contracts specifying 4-6 hour replenishment windows.
- Aftermarket:Independent refinishing channels purchase coatings through distributor networks serving thousands of unorganized body shops. Tamil Nadu and Karnataka generate dense demand pockets where vehicle parc age exceeds national averages and cosmetic refurbishment cycles compress.
- Collision Repair:Insurance-driven repair networks centralize specification authority through multi-brand service chains.
- Specialty:Custom vehicle modification and commercial fleet rebranding operate outside standard warranty channels.
Dominant by revenue: OEM direct supply. Gaining share fastest: Organized collision repair procurement.
Technology:
Environmental compliance timelines are forcing specification shifts that strand capital equipment and reconfigure supplier technical service requirements.
- Waterborne:Acrylic-polyurethane dispersions with volatile organic compound content below BIS mandated thresholds. Passenger vehicle OEMs in Delhi-NCR and Mumbai metropolitan regions have converted 70-80 percent of basecoat capacity to waterborne systems following state pollution control board enforcement actions.
- Solventborne:High-solids alkyd and polyurethane formulations retain specification for commercial vehicle applications where BIS durability standards for heavy-duty corrosion resistance remain unmatched by aqueous alternatives.
- Powder Coating:Thermoset epoxy-polyester hybrids applied through fluidized bed or electrostatic spray to wheel rims and underbody components.
- UV-Cured:Acrylate oligomer systems with photoinitiator packages enabling instant polymerization for plastic component finishing.
Highest volume position: Solventborne systems. Steepest expansion trajectory: Waterborne technology.
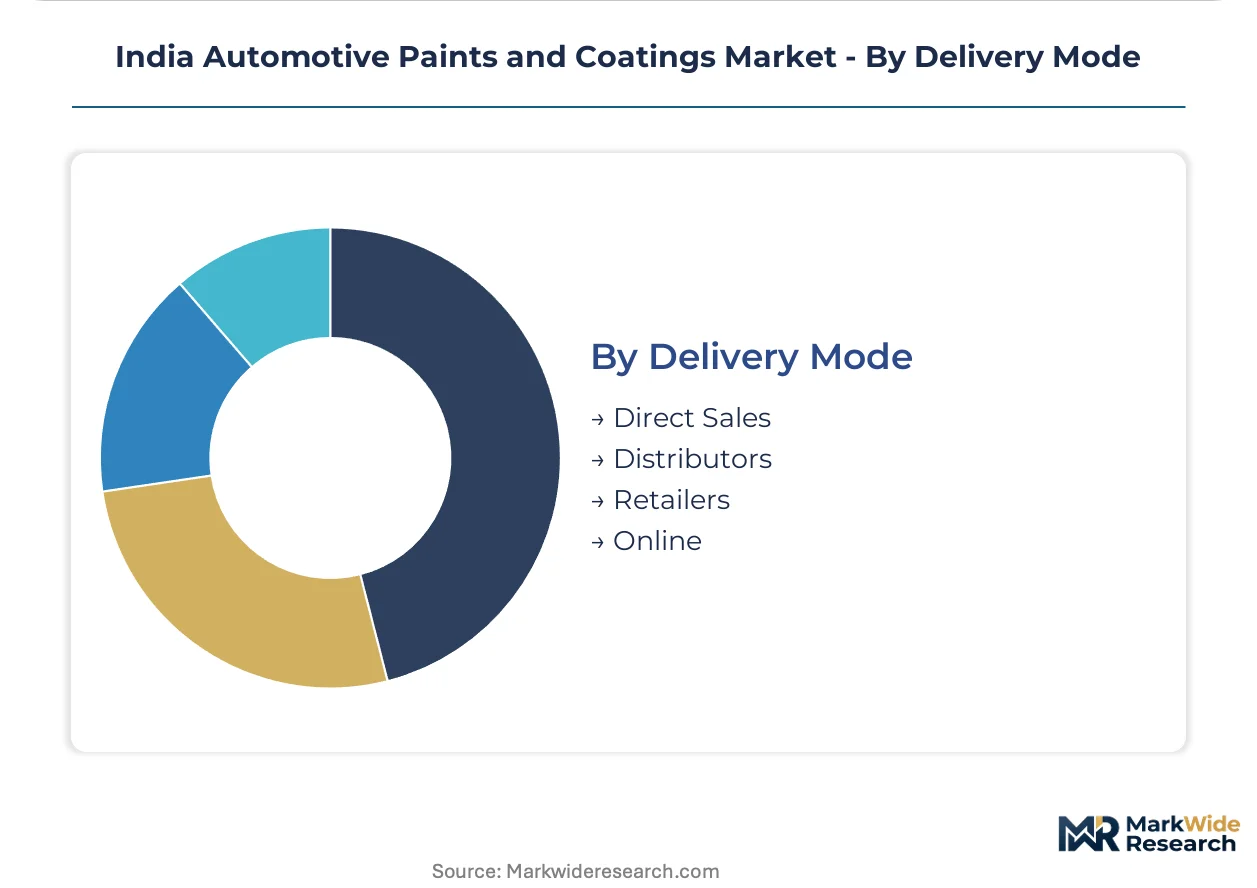
Delivery Mode:
Supply chain configuration varies from direct mill-to-plant relationships for high-volume OEMs to fragmented retail distribution serving dispersed refinish operators.
- Distributors:Regional stocking points maintain 15-30 day coating inventories with technical support staff for color matching and application troubleshooting. Gujarat and Maharashtra host the densest distributor networks, co-located with OEM assembly clusters and major port facilities.
- Direct Sales:Annual framework agreements link coating manufacturers directly to OEM procurement teams with dedicated logistics lanes and formulation co-development programs.
- Retailers:Counter sales to independent body shops and vehicle owners for touch-up and minor repair applications.
- Online:Emerging digital channels for standardized color codes and accessory coatings with limited technical service content.
Primary volume channel: Distributor networks. Fastest-growing modality: Direct OEM sales with embedded technical service.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive coating procurement concentrates in manufacturing corridors where OEM assembly plants cluster near port infrastructure and component supplier ecosystems. State-level pollution control enforcement and PLI scheme disbursements are redrawing regional demand intensity maps.
Maharashtra
Maruti Suzuki's Gurugram operations and Tata Motors' Pune facilities anchor coating consumption volume in this western state. BIS emission norms enforced by the Maharashtra Pollution Control Board have accelerated waterborne basecoat conversions in Mumbai metropolitan body shops. The Mumbai-Pune industrial corridor hosts dense distributor networks serving just-in-time OEM supply contracts.
Gujarat
Hyundai Motor India's Ahmedabad assembly plant and Suzuki Motor Gujarat's Hansalpur facility generate concentrated procurement demand for electrocoat and basecoat systems. The state's pollution control board has mandated volatile organic compound thresholds that align with BIS automotive coating standards. Sanand and Halol industrial zones attract coating manufacturers establishing technical service centers adjacent to OEM plants.
Tamil Nadu
Hyundai's Sriperumbudur complex and Renault-Nissan's Oragadam facility drive specification authority for premium finish coatings in this southern state. The Tamil Nadu Pollution Control Board enforces ambient air quality standards that restrict solventborne spray booth operations in Chennai metropolitan areas. Sri City and Oragadam automotive clusters concentrate distributor warehousing capacity for southeastern OEM supply.
Haryana
Maruti Suzuki's Manesar and Hero MotoCorp's Gurgaon operations sustain high-volume coating demand for passenger vehicles and two-wheelers. The Haryana State Pollution Control Board monitors compliance with BIS certification requirements for automotive refinishing operations. The Delhi-Mumbai Industrial Corridor segment passing through Manesar supports logistics infrastructure for coating raw material distribution.
Karnataka
Tata Motors' commercial vehicle plant in Dharwad and Toyota Kirloskar's Bidadi facility generate differentiated demand across heavy-duty and passenger vehicle coating segments. The Karnataka State Pollution Control Board regulates emissions from automotive paint application facilities in Bengaluru urban and rural districts. The Bengaluru-Tumkur industrial belt attracts specialty coating distributors serving the organized collision repair networks expanding across southern India.
India Automotive Paints and Coatings Market Competitive Landscape
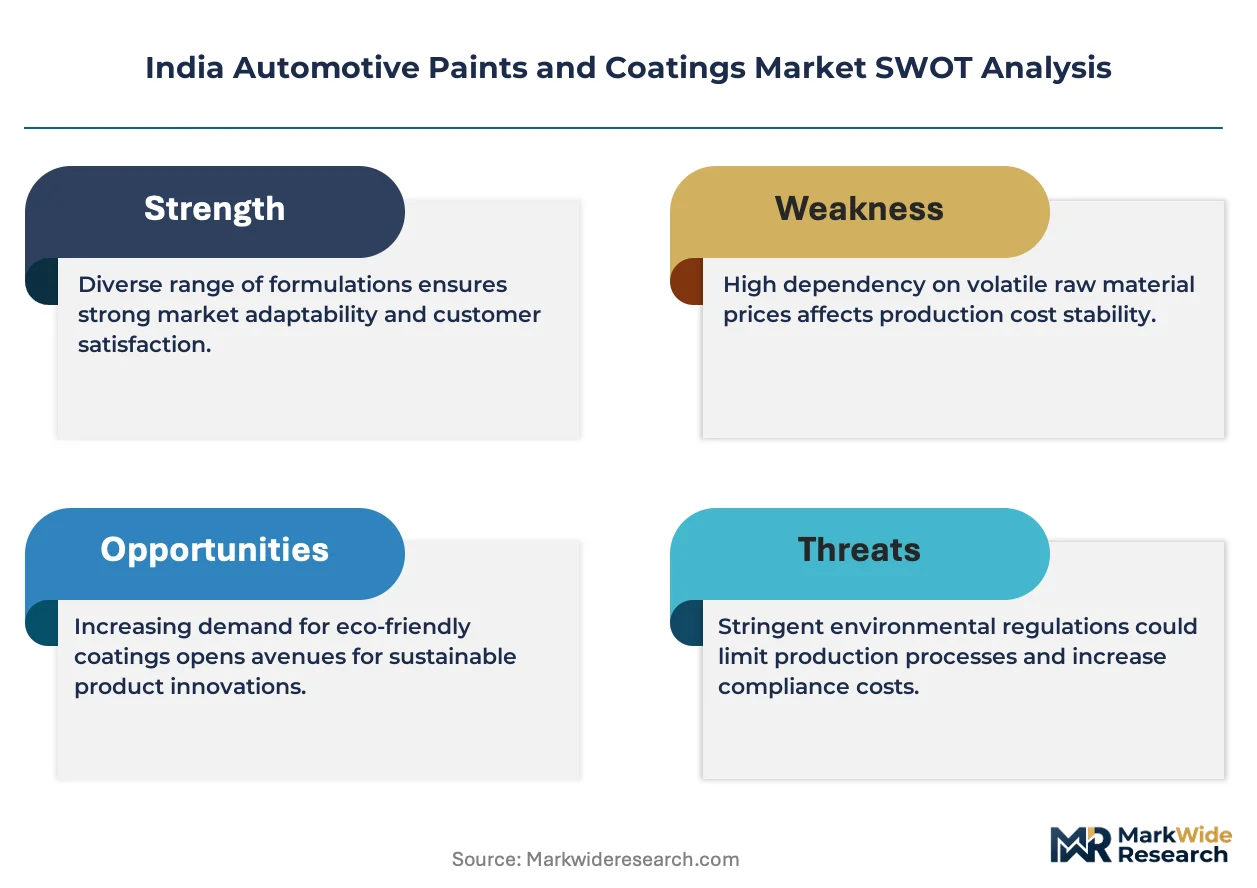
Backward integration into resin intermediates dominates the current landscape as manufacturers seek margin protection against petrochemical volatility. The vendor base separates into three functional tiers: integrated chemical conglomerates with captive raw material supply, domestic formulation specialists leveraging distribution density, and global technology licensors competing on specification authority. Strategic archetypes include resin-integrated formulators, application-technology licensors, and regional distribution consolidators. Capacity expansion in waterborne production lines and technology licensing partnerships for humidity-controlled application systems represent the dominant competitive moves.
Among domestic formulation specialists, Asian Paints and Kansai Nerolac Paints occupy positions anchored by extensive distribution networks and backward integration into key resin production. BASF represents the technology-licensor archetype, competing through specification authority in waterborne basecoat systems for premium vehicle programs. These three companies exemplify the strategic segmentation between volume-driven domestic supply and technology-driven premium positioning.
| Leading Market Players |
|---|
| JSW Paints |
| Axalta Coating Systems |
| Asian Paints |
| PPG Industries |
| BASF |
| Kansai Nerolac Paints |
| Nippon Paint Holdings |
| Jotun |
| Berger Paints India |
| Others |
Supply & Pricing Matrix
BIS volatile organic compound thresholds gate qualified supply access and premium-tier pricing power for automotive coating manufacturers serving India's passenger vehicle OEMs. Compliance investment separates waterborne-capable suppliers from commodity solventborne competitors locked out of metropolitan body shop contracts.
Pricing Analysis
Volume-mass contracts for Maruti Suzuki and Tata Motors compress per-liter margins while pearlescent effect coatings for Hyundai premium programs sustain formulation premiums. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and application complexity. Cost compression in basecoat supply is intensifying because petrochemical resin volatility feeds through acrylic and polyurethane intermediates. Independent collision repair channels exhibit acute price sensitivity versus OEM direct procurement teams prioritizing technical service and just-in-time reliability.
Supply Chain Analysis
Specialty additive supply rests on German and Japanese chemical majors for photoinitiator packages and mica-based interference pigments. Acrylic resin feedstock draws from Saudi and South Korean petrochemical complexes, while epoxy intermediates source from China and Taiwan. Single-source vulnerability concentrates in humidity-controlled application equipment for waterborne conversion. Distribution runs through regional stocking points in Gujarat and Maharashtra co-located with OEM assembly clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India automotive coatings market reads as a cost-of-compliance story where BIS certification timelines create a barrier-to-entry moat favoring incumbents with dedicated regulatory affairs teams and pre-submission testing partnerships.
For Market Incumbents: Lock in resin intermediate supply through backward integration or long-term offtake agreements with Saudi and South Korean petrochemical suppliers. Expand technical service center footprint in Sanand and Halol industrial zones adjacent to Hyundai and Suzuki assembly plants to defend against emerging waterborne specialists from China. Certification investment represents the priority defensive lever as BIS approval cycles extend product development timelines. For New Entrants and Emerging Players: Humidity-controlled waterborne application systems offer a technology-first wedge into the two-wheeler refinish segment where organized distribution remains underdeveloped. Tamil Nadu and Karnataka generate dense demand pockets where vehicle parc age exceeds national averages. A distributor partnership model with embedded color-matching technical service unlocks penetration of thousands of independent body shops outside Delhi-NCR and Mumbai metropolitan clusters. For Investors and Strategic Acquirers: PLI scheme disbursement acceleration for automobile manufacturing is the leading indicator that coating procurement will concentrate further in Gujarat and Tamil Nadu production corridors. Acquisition targets should screen for resin-integrated formulators with captive acrylic or polyurethane intermediate supply. Watch for waterborne conversion capex announcements from Maruti Suzuki and Tata Motors as the signal that specification authority is shifting decisively toward environmental compliance.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Intermediates | Captive acrylic supply from Saudi petrochemical feedstock insulates margin compression from crude volatility. |
| Waterborne Production Capacity Expansion | Gujarat facility investments align with Maharashtra Pollution Control Board enforcement timelines for Mumbai metropolitan OEMs. |
| Technical Service Center Establishment | Sanand and Halol proximity to Hyundai and Suzuki plants secures just-in-time contract renewal positioning. |
| Long-term Supply Agreement with OEMs | Maruti Suzuki framework contracts with 4-6 hour replenishment windows lock out distributor-dependent competitors. |
| Joint Venture for Application Equipment | Humidity-controlled spray booth partnerships address technician scarcity constraining waterborne conversion speed. |
Research Methodology
Independent corroboration across OEM procurement executives, coating manufacturer technical directors, and Maharashtra Pollution Control Board enforcement officers underwrites the qualitative findings in this study. Primary interviews with Tier 1 supplier procurement teams, aftermarket distributor network heads, and automotive refinery plant managers combined with secondary validation from BIS certification records, Automotive Research Association of India test protocols, and PLI scheme disbursement filings. Bottom-up coating volume estimates triangulated against top-down OEM production capacity data.
Rate-of-change decomposition across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions structured the analytical framework. CAGRs derived from segment-level growth trajectories weighted by OEM capacity expansion announcements and pollution control board enforcement timelines. Forecast inputs incorporated BIS volatile organic compound threshold compliance schedules and REACH-aligned chemical restriction propagation through Indian import regulations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under petrochemical price volatility and extended BIS certification delays. A small set of named triggers warrants ongoing watch: waterborne technician training program scale-up, state pollution control board enforcement intensity variation, and specialty additive import restriction announcements aligned with REACH pre-registration requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Automotive Paints and Coatings Market
Paints & Coatings
United Arab Emirates (UAE) Paints and Coatings Market
Paints & Coatings
Sri Lanka Paints and Coatings Market
Paints & Coatings
Morocco Paints and Coatings Market
Paints & Coatings
Decorative Paints Market
Paints & Coatings
GCC Paints and Coatings Market
Paints & Coatings
Cellulose Paints Market
Paints & Coatings
Epoxy Paint Thinner Market
Paints & Coatings
Middle East and Africa Paints and Coatings Market
Paints & Coatings
Industrial Paint Booth Market
Paints & Coatings
Paint Mixing Market
Paints & Coatings
Asia-Pacific Paint Spray Guns Market
Paints & Coatings
Alkyd Coatings Market
Paints & Coatings
Global Aerosol Paints Market
Paints & Coatings
Road Marking Paints and Coatings Market
Paints & Coatings
Paint Buckets Market