
 Acrylic Paints Market | 2026-2036
Acrylic Paints Market Size, Share, and Industry Trends Forecast 2026-2036
Acrylic Paints Market Outlook
The EU Green Deal is pivoting European acrylic paint procurement toward low-VOC and bio-based formulations, forcing reformulation investments across the supply base. Sherwin-Williams Company leverages its architectural coatings infrastructure to distribute compliant acrylic systems through professional contractor channels. Golden Artist Colors anchors its competitive position through pigment dispersion technology developed for heavy body professional grades. PPG Industries competes on industrial scale, extending waterborne acrylic capacity to serve OEM and specialty coating segments simultaneously.
Acrylic paints are thermoplastic dispersions of acrylic polymer emulsions, typically containing pigment concentrations between 10% and 45% by volume, manufactured through batch emulsion polymerization at controlled temperatures between 70°C and 90°C. These formulations serve as the dominant binder system for water-based decorative and artistic coatings due to rapid drying, ultraviolet stability, and adhesion across porous substrates. Professional acrylic commands premium pricing and loyalty among gallery-exhibiting artists, while student acrylic occupies volume leadership through educational institution procurement contracts. Heavy body acrylic sustains margin pools in specialty retail, where viscosity and pigment load differentiate performance tiers. Soft body acrylic is gaining application share in illustration and airbrush work, where flow characteristics override impasto requirements.
EPA VOC regulations under 40 CFR Part 59 constrain solvent content in architectural coatings, directly shaping acrylic emulsion R&D priorities in the United States. REACH and the EU F-Gas Regulation impose substance restrictions and disclosure obligations that increase compliance costs for imported pigment and additive packages. India's BIS certification requirements for decorative paints create market access thresholds that favor domestic manufacturers with established testing relationships. Stakeholders must monitor evolving chemical hazard classifications under ECHA and state-level California Air Resources Board amendments, as these frameworks increasingly determine which acrylic formulations qualify for public and commercial project specifications.
Market Dynamics
Water-based acrylic substitution is compressing solvent-borne capacity across decorative and industrial coating segments as EPA VOC standards and REACH compliance tighten permissible solvent thresholds.
Growth Catalysts
- Urban art infrastructure:Government-funded cultural projects in India are scaling domestic acrylic paint consumption through public mural programs and institutional procurement.
- REACH substance restrictions:ECHA hazard classifications are accelerating reformulation investments toward low-VOC acrylic emulsions in European architectural coatings.
- Heavy body viscosity tiers:Specialty retail channels are capturing margin pools through pigment load differentiation in professional artist-grade formulations.
Market Restraints
- Titanium dioxide volatility:Pigment input costs fluctuate with mining concentration in China and South Africa, compressing formulation margins.
- BIS certification thresholds:India's mandatory testing relationships favor established domestic manufacturers and delay foreign market entry.
- Alkyd substitution in industrial:Solvent-borne alkyds retain share in metal protection where acrylic adhesion remains technically inferior.
Strategic Opportunities
- Experiential retail spaces:Hospitality and commercial outlets are expanding acrylic procurement for interior branding and immersive environments.
- Bio-based binder convergence:Acrylic-polyurethane hybrid systems are opening premium positioning in furniture and automotive refinish segments.
- Airbrush application expansion:Soft body acrylic flow characteristics are displacing gouache in illustration and digital-physical hybrid workflows.
Industry Challenges
- Emulsion polymerization scale-up:Batch temperature control between 70°C and 90°C demands specialized reactor capex that fragments producer capabilities.
- California Air Resources Board amendments:State-level VOC thresholds create compliance complexity for national distribution networks serving public project specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acrylic Paints Market |
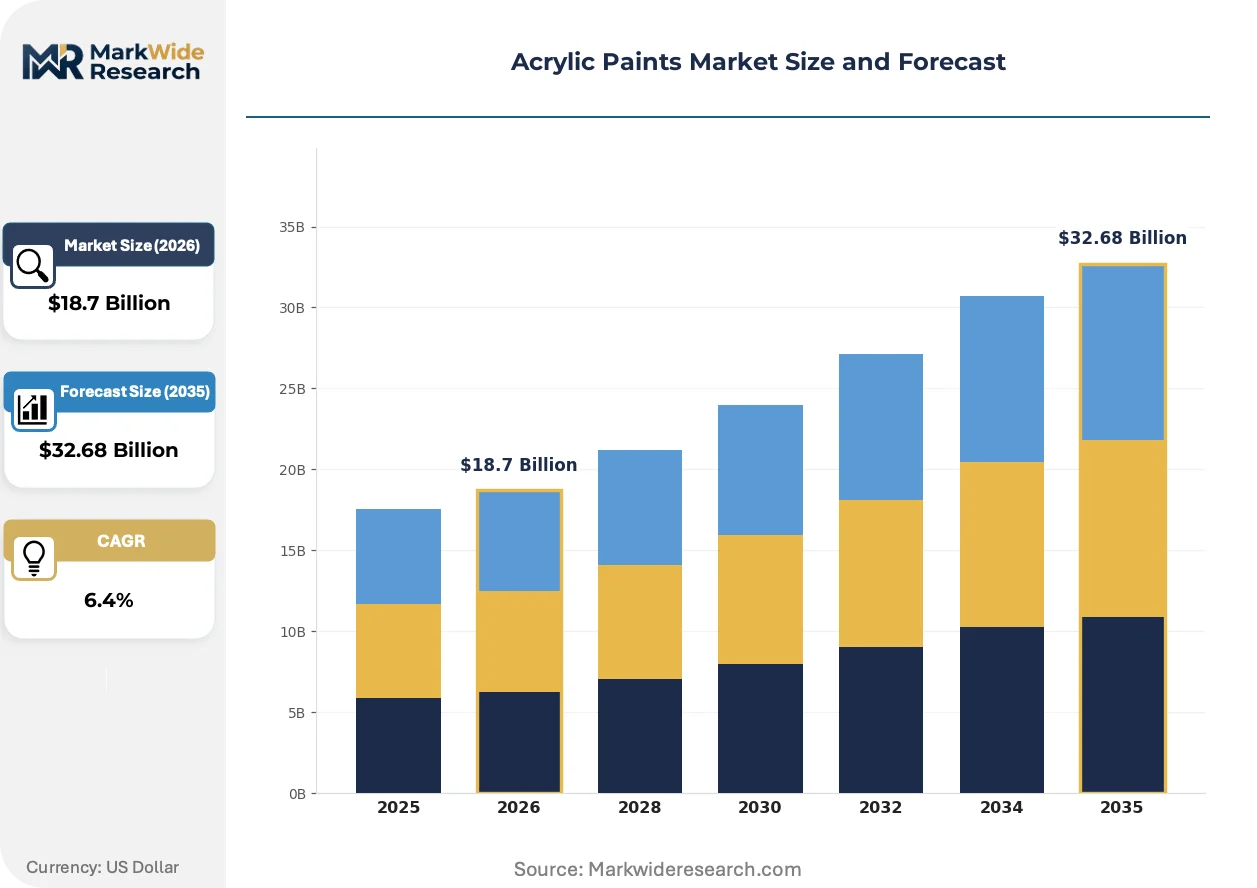
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Professional Acrylic, Student Acrylic, Heavy Body Acrylic, Soft Body Acrylic End User: Artists, Hobbyists, Educational Institutions, Commercial Outlets Application: Canvas Painting, Mural Art, Illustration, Craft Projects Packaging Type: Tubes, Jars, Bottles, Sets |
| Companies Covered | Asian Paints India, Liquitex, Sherwin-Williams Company, Nova Color, Golden Artist Colors, PPG Industries, Berger Paints India, Gamblin Artists Colors, AkzoNobel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acrylic Paints Market Strategic Shifts
Formulation chemistry and distribution architecture are undergoing parallel transformation as regulatory pressure and professional user expectations converge on performance-validated waterborne systems.
Nano-pigment dispersion technology is absorbing ultraviolet stabilizer functions into single-particle architectures, reducing additive package complexity. Gallery-exhibiting artists are adopting these systems for outdoor mural commissions where color permanence determines professional reputation. The structural consequence is premium tier consolidation around suppliers with captive dispersion capabilities.
EPA regulations under 40 CFR Part 59 are constraining solvent content in architectural coatings and redirecting R&D budgets toward emulsion stability improvements. Industrial-scale producers are responding with dedicated waterborne acrylic capacity expansions serving OEM specification requirements. The United States market is experiencing the most pronounced shift as state-level amendments compound federal baseline restrictions.
Educational institution procurement is consolidating around volume-contract suppliers with certified non-toxic formulations. Traditional art supply distributors are losing share to direct-manufacturer relationships that guarantee batch consistency for district-level purchasing. This concentration is most visible in North American K-12 systems where liability concerns drive specification centralization.
Acrylic Paints Market Segmentation
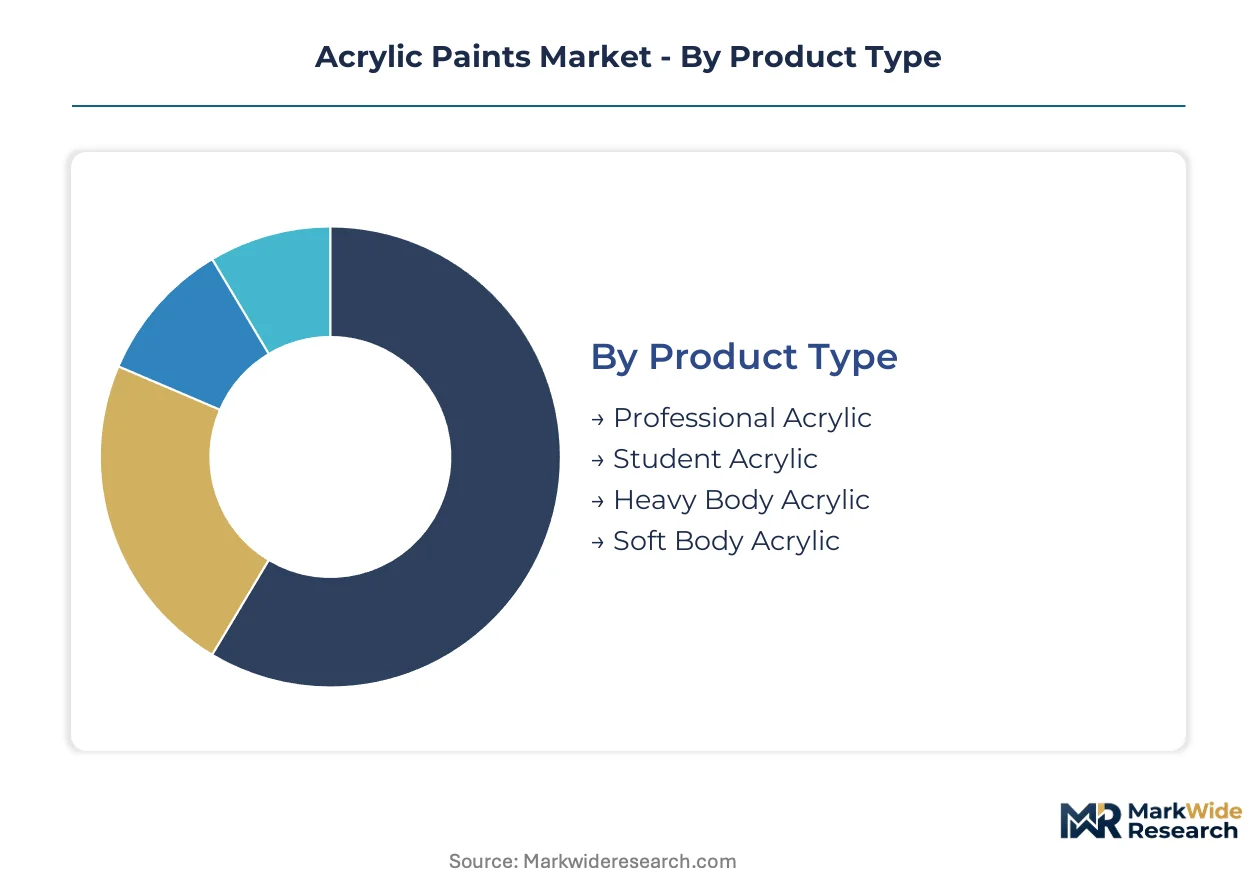
Acrylic paint purchasing decisions split across performance grade, user sophistication, and project scale. Manufacturers configure formulation chemistry, pigment load, and distribution channels differently for each segment intersection.
Product Type:
Price-performance expectations separate gallery professionals from institutional bulk buyers.
- Professional Acrylic:Pigment concentrations reach 45% by volume with single-particle nano-dispersion architectures. Gallery-exhibiting artists in India and Europe drive specification for outdoor mural permanence and color stability under ultraviolet exposure.
- Heavy Body Acrylic:Viscosity above 12,000 centipoise enables impasto techniques and textured surface builds. Specialty retail channels in North America and Western Europe capture margin pools through viscosity tier differentiation and limited pigment series.
- Student Acrylic:Lower pigment loads and extended filler content serve educational volume procurement. BIS certification requirements in India favor domestic manufacturers with established testing relationships for institutional contracts.
- Soft Body Acrylic:Flow characteristics between 2,000 and 5,000 centipoise suit airbrush application and illustration workflows. Digital-physical hybrid artists in commercial design studios are displacing traditional gouache specifications.
Student acrylic leads on scale through educational institution contracts; soft body acrylic leads on momentum through illustration segment expansion.
End User:
Procurement authority and volume predictability shape supplier relationship structures.
- Artists:Individual professionals prioritize batch consistency and lightfastness ratings for commissioned work. REACH-compliant low-VOC formulations are becoming non-negotiable for European gallery representation.
- Educational Institutions:District-level purchasing in North American K-12 systems consolidates around certified non-toxic formulations with guaranteed batch consistency. Liability concerns drive specification centralization toward direct-manufacturer relationships.
- Hobbyists:Price-sensitive occasional users purchase through mass retail and online marketplaces. Product discovery happens through social media tutorial content and influencer supply recommendations.
- Commercial Outlets:Hospitality and retail sector interior branding projects specify custom color matching and bulk volume pricing. Experiential space designers in urban India are scaling procurement for immersive environment builds.
Educational institutions lead on scale through multi-year volume contracts; commercial outlets lead on momentum through experiential retail expansion.
Application:
Substrate requirements and environmental exposure determine binder system specifications.
- Canvas Painting:Traditional stretched canvas applications demand adhesion across cotton and linen weaves with flexibility after drying. Professional artists specify for crack resistance during transport and exhibition.
- Mural Art:Large-scale exterior applications require ultraviolet stabilizers and moisture barrier properties. Government-funded cultural infrastructure in India is scaling public wall procurement with permanence specifications.
- Illustration:Smooth paper and board substrates favor flow characteristics over body and texture. Airbrush-compatible soft body formulations are gaining specification in publishing and advertising studios.
- Craft Projects:Mixed-media and decorative applications tolerate wider formulation variance. Hobbyist segment price sensitivity drives private label and entry-grade product placement.
Canvas painting leads on scale through established artist supply channels; mural art leads on momentum through public infrastructure investment.
Packaging Type:
Usage rate and storage conditions determine container format economics.
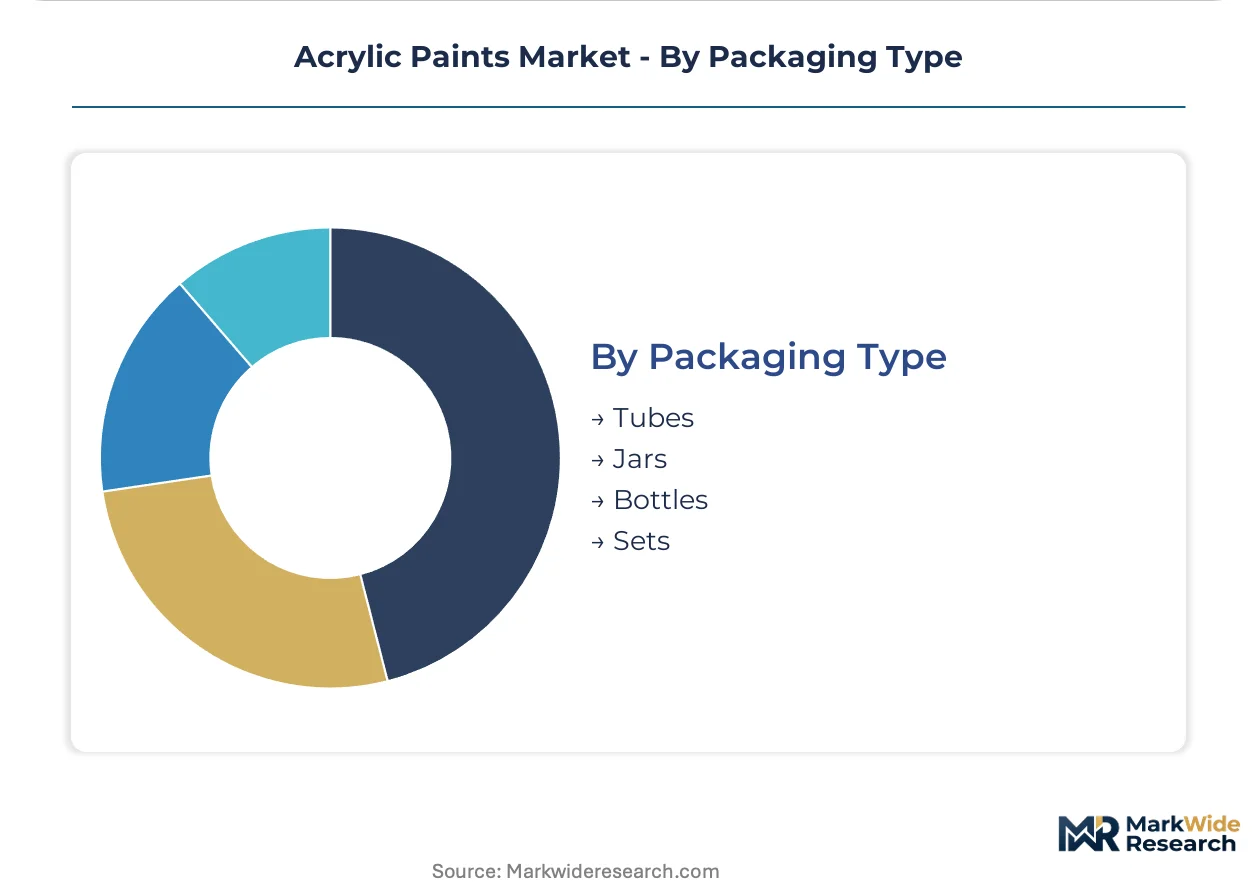
- Tubes:Aluminum squeeze tubes preserve freshness for intermittent users and travel applications. Professional artists favor single-pigment tubes for palette control and color mixing precision.
- Jars:Wide-mouth containers suit heavy body viscosity and palette knife techniques. Studio-based professionals purchase volume sizes for reduced per-milliliter cost.
- Bottles:Flip-top and pump dispensers serve soft body and fluid acrylic flow requirements. Illustration and airbrush workflows favor controlled dispensing mechanisms.
- Sets:Curated color assortments reduce decision friction for gift purchases and beginner entry. Educational procurement specifications often mandate set configurations for classroom standardization.
Tubes lead on scale through professional artist preference; sets lead on momentum through educational contract standardization and gift segment growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized polymer chemists and formulation engineers concentrate in Germany, the United States, and India, anchoring regional innovation clusters for acrylic emulsion development.
United States
Professional artist supply channels and architectural coatings distributors drive formulation demand across California and New York. EPA regulations under 40 CFR Part 59 constrain solvent content and redirect R&D toward waterborne emulsion stability. Los Angeles mural artists specify low-VOC acrylics for outdoor commissions requiring ultraviolet permanence.
Germany
Gallery-exhibiting professionals and industrial OEM specifiers prioritize REACH-compliant low-emission systems. ECHA substance restrictions under REACH and the EU F-Gas Regulation accelerate reformulation investments toward bio-based binders. Cologne and Düsseldorf host specialty retail clusters serving professional-grade heavy body formulations.
India
Urban art infrastructure and government-funded cultural projects scale domestic consumption through public mural programs. BIS certification requirements for decorative paints favor established domestic manufacturers with testing relationships. Mumbai and Delhi institutional procurement consolidates around certified non-toxic student acrylic contracts.
United Kingdom
Illustration studios and commercial design agencies specify soft body acrylics for airbrush workflows displacing traditional gouache. ECHA-aligned hazard classifications through post-Brexit retained EU law maintain disclosure obligations for imported pigment packages. London's experiential retail designers procure bulk volumes for immersive environment builds.
China
Titanium dioxide processing clusters and acrylic monomer production capacity concentrate raw material supply. MEE environmental standards tighten emissions controls on emulsion polymerization facilities operating at 70°C to 90°C batch temperatures. Pearl River Delta manufacturers supply both domestic artists and export-oriented private label distributors.
Acrylic Paints Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the acrylic paint value chain. Integrated chemical conglomerates with captive polymer emulsion capacity face specialty formulators sourcing binders through merchant markets. Three archetypes dominate: industrial-scale coatings manufacturers extending waterborne acrylic capacity, professional-grade artistic supply specialists leveraging pigment dispersion technology, and regional decorative paint champions securing institutional procurement contracts through certification relationships. Consolidation pressure intensifies as REACH compliance costs and BIS testing thresholds favor established players with dedicated regulatory affairs infrastructure.
Within the industrial-scale tier, Sherwin-Williams Company and PPG Industries occupy positions anchored by architectural coatings distribution infrastructure. Golden Artist Colors exemplifies the professional-grade specialist archetype through heavy body formulation expertise. Asian Paints India and Berger Paints India represent regional champions leveraging domestic certification relationships for institutional contract capture.
| Leading Market Players |
|---|
| Asian Paints India |
| Liquitex |
| Sherwin-Williams Company |
| Nova Color |
| Golden Artist Colors |
| PPG Industries |
| Berger Paints India |
| Gamblin Artists Colors |
| AkzoNobel |
| Others |
Value Chain & Pricing Dynamics
Specialized polymer chemists in Germany and India anchor formulation development clusters, creating labor-cost differentials that widen spreads between premium artist-grade and economy student-tier pricing. European REACH compliance investments compress margins on low-VOC emulsions while Indian domestic manufacturers exploit BIS certification relationships to capture institutional volume at compressed price points.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates gallery-exhibiting professionals from educational bulk buyers and hobbyist segments. Price differentiation rests on pigment load concentration and REACH certification tier, with nano-dispersion professional grades commanding substantial premiums over student formulations. Cost compression in the student tier is intensifying because titanium dioxide volatility from Chinese and South African mining concentration squeezes formulation margins. Educational institutions exhibit highest price sensitivity through multi-year procurement contracts, while gallery professionals prioritize batch consistency over unit cost.
Supply Chain Analysis
Ocean freight cost volatility from acrylic monomer production centers in China to formulation facilities in Europe and North America shapes inventory positioning and working capital requirements. Raw material supply concentrates in China for titanium dioxide processing and acrylic monomer production, with Germany and the United States hosting specialized emulsion polymerization reactor clusters. The supply chain draws from petrochemical feedstocks and mined pigment ores, exposing producers to commodity price swings. Single-source vulnerability around Chinese titanium dioxide concentration presents structural risk. Distribution runs through professional artist supply channels, architectural coatings distributors, and direct-manufacturer institutional relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acrylic paints market functions as a stable compounder sustained by recurring educational procurement cycles and professional artist brand loyalty that resists substitution.
For Market Incumbents: Deploy captive pigment dispersion capabilities to defend professional-grade margin pools against merchant-sourced binder competitors. Sherwin-Williams and PPG Industries should extend waterborne acrylic capacity expansions toward OEM specification capture. Golden Artist Colors must deepen nano-dispersion R&D to maintain heavy body viscosity differentiation against emerging Asian specialists. Regulatory compliance infrastructure represents the critical defensive moat as REACH and BIS thresholds rise. For New Entrants and Emerging Players: Experiential retail designers in Indian urban centers present an underserved buyer archetype with accelerating procurement momentum and limited established supplier relationships. Soft body acrylic formulations for airbrush illustration workflows offer the most penetrable application segment with lower capital barriers than heavy body production. Direct-manufacturer relationships bypassing traditional art supply distributors provide the optimal go-to-market angle for institutional contract capture. For Investors and Strategic Acquirers: Valuations sit cheapest among regional decorative paint champions with established BIS certification relationships and underutilized emulsion polymerization capacity. The five-to-ten year viability window favors producers with backward integration into acrylic monomer supply or captive titanium dioxide sourcing. Acquisition targets should display professional-grade formulation expertise alongside institutional contract books. The signal to watch is EPA state-level amendment acceleration that would force solvent-borne capacity conversions and strand non-compliant assets.| Strategic Initiative | Industry Significance |
|---|---|
| Waterborne Capacity Expansion | PPG Industries extends reactor infrastructure to serve OEM specification requirements under tightening EPA VOC thresholds. |
| Backward Integration into Monomer Supply | Captive acrylic monomer production hedges against petrochemical feedstock volatility and secures formulation margin control. |
| REACH Compliance Certification Investment | European gallery representation now requires documented low-emission formulations under ECHA substance restrictions. |
| Direct Institutional Contract Capture | Asian Paints India leverages BIS testing relationships to bypass distributor markups in educational procurement consolidation. |
| Nano-Pigment Dispersion R&D Partnership | Golden Artist Colors anchors competitive position through ultraviolet stabilizer integration into single-particle architectures. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at emulsion polymerization facilities, procurement leads at educational institutions, distribution channel partners in artist supply retail, and technical R&D directors at coatings manufacturers with secondary validation. Secondary sources included customs and trade data on acrylic monomer flows, SEC 10-K filings from coatings conglomerates, BIS certification registries, and ECHA substance restriction databases. Bottom-up volume modeling triangulated against top-down market sizing from architectural coatings and artist supply channel estimates.
Segment-weighting approaches distributed value across product type, end user sophistication, application substrate, and packaging format dimensions. Professional acrylic, heavy body, student, and soft body tiers each carried distinct volume and pricing assumptions. Canvas painting, mural art, illustration, and craft project applications modeled separately for binder specification differences. CAGRs derived from regression analysis against historical educational procurement cycles and public infrastructure investment trajectories. Forecast inputs incorporated EPA regulatory amendment schedules and Indian urban art program budget allocations.
Underlying measurement precision varies by segment; student acrylic educational contracts carry tighter precision than hobbyist retail estimates due to consolidated procurement visibility. Forecasts reflect assumptions about REACH enforcement intensity and titanium dioxide supply stability that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Road Marking Paint Market
Paints & Coatings
Global Aerosol Paints Market
Paints & Coatings
Automotive Paints Market
Paints & Coatings
Metal Paint Tray Market
Paints & Coatings
Global Anti-Formaldehyde Paint Market
Paints & Coatings
US Paints and Coatings Market
Paints & Coatings
Paint Thinner Market
Paints & Coatings
Water-Borne Latex Paints Market
Paints & Coatings
South Africa Paints and Coatings Market
Paints & Coatings
Bahrain Paints and Coatings Market
Paints & Coatings
Nano Paints and Coatings Market
Paints & Coatings
Food Grade Epoxy Paint Market
Paints & Coatings
Anti-Fungal and Anti-Bacterial Paints Market
Paints & Coatings
Global Thinners and Paint Strippers Market
Paints & Coatings
Water Color Market
Paints & Coatings
Middle East & Africa Corrosion Protection Coating Market