
 South America Paints and Coatings Market | 2026-2036
South America Paints and Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
South America Paints and Coatings Market Analytics
A skilled formulator shortage across Brazil and Argentina is collapsing expansion timelines for mid-sized producers. PPG Industries, Inc. leverages its São Paulo technical center to sustain localized color-matching capabilities. Akzo Nobel N.V. anchors its regional position through marine and protective coatings specialization. Renner Herrmann S.A. dominates Brazilian architectural demand through deep distributor relationships.
Paints and coatings constitute liquid or powder formulations comprising binders, pigments, solvents, and additives that cure to form adherent protective or decorative films on substrates. Water-based acrylic emulsions now represent the primary architectural technology due to lower volatile organic compound release during application and drying. Solvent-based alkyd and polyurethane systems retain structural importance in automotive refinish and industrial maintenance where humidity resistance and chemical durability prove critical. Powder coating adoption is accelerating among Brazilian appliance and furniture manufacturers seeking zero-VOC compliance without sacrificing film performance.
Brazil's CONAMA standards on air emissions, Argentina's Secretariat of Environment and Sustainable Development protocols, and Colombia's Ministry of Environment resolutions collectively mandate VOC thresholds that reformulation investments must satisfy. Product registration requirements under ANVISA for coatings with biocidal additives create additional compliance layers affecting market access timelines. Stakeholders must monitor regulatory divergence between Mercosur harmonization efforts and national implementation schedules to anticipate formulation portfolio requirements.
Market Dynamics
Water-based acrylic emulsions are compressing solvent-borne capacity across Brazil's southeastern industrial corridor as CONAMA VOC thresholds tighten formulation requirements and force capital reallocation toward compliant resin systems.
Growth Catalysts
- Residential construction velocity:Brazil's Minha Casa Minha Vida program and private housing starts in São Paulo state are pulling architectural coatings volume through distributor networks serving the southeastern corridor.
- CONAMA Resolution 491:Brazil's federal air quality standards on VOC emissions are mandating water-borne technology conversion, creating replacement demand for compliant primer and topcoat systems across industrial maintenance applications.
- Powder coating penetration:Brazilian appliance manufacturers in Santa Catarina and São Paulo are adopting zero-VOC powder systems for metal furniture and refrigerator cabinets, bypassing solvent-based compliance costs entirely.
Market Restraints
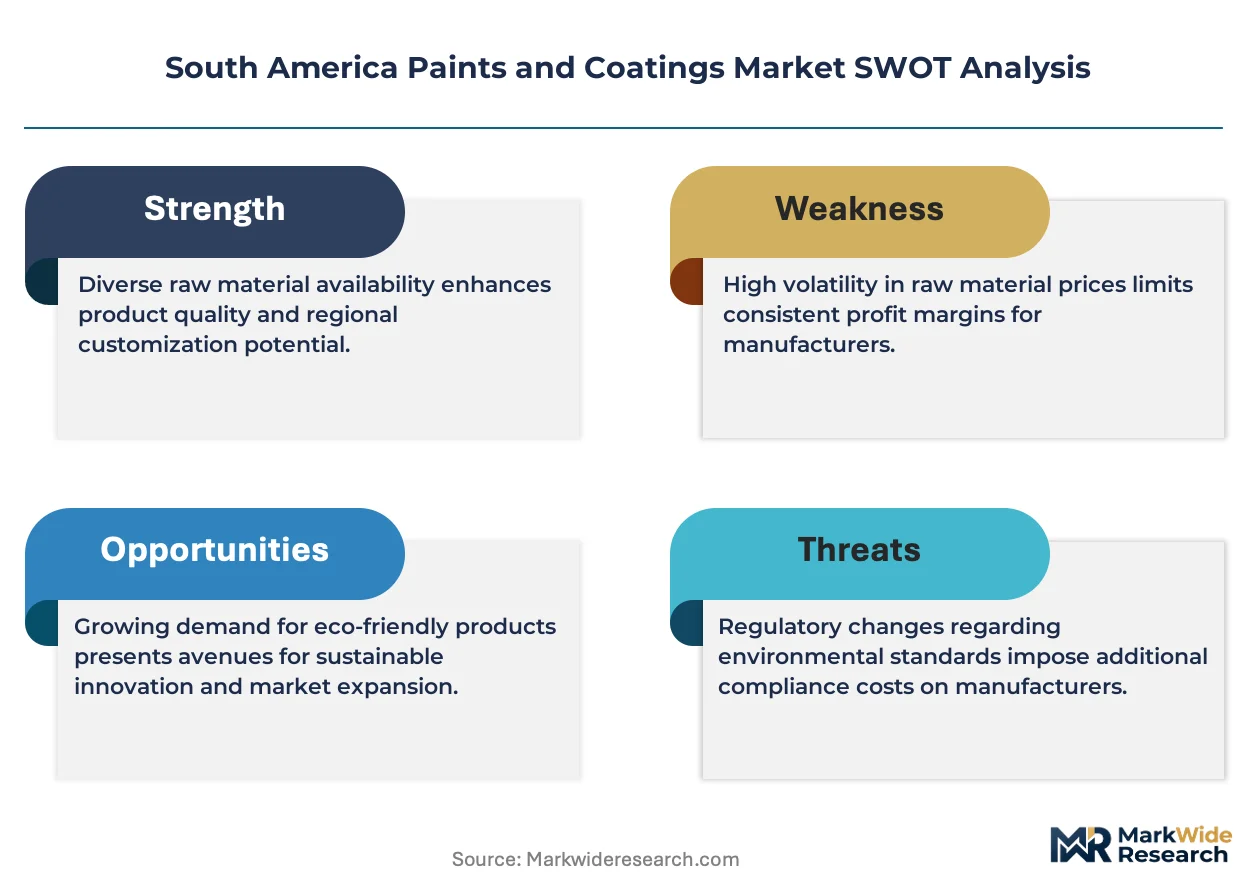
- Titanium dioxide feedstock concentration:Pigment supply concentrates among Chinese sulfate-process producers, exposing Brazilian formulators to freight cost volatility and currency mismatch against the real.
- Specialized resin import dependency:Water-borne alkyd and polyurethane dispersions for automotive refinish rely on European and North American suppliers, extending lead times for Argentine and Chilean coaters.
- Humidity performance ceiling:Water-borne acrylics face technical limitations in Amazon basin industrial applications where ambient moisture exceeds 85% year-round, preserving solvent-borne niche demand.
Strategic Opportunities
- Colombian infrastructure buildout:Bogotá's metro expansion and Pacific port modernization are generating protective coatings demand for steel structures in a market with limited domestic high-performance supply.
- Brazilian offshore wind pre-positioning:Búzios and Santos basin platform maintenance schedules are opening marine coatings specifications for suppliers with NORSOK M-501 equivalent certification.
- Biocidal additive registration acceleration:ANVISA's streamlined evaluation pathway for in-can preservatives is shortening market access timelines for antimicrobial architectural coatings targeting humid coastal markets.
Industry Challenges
- Formulation chemist scarcity:Brazil's technical universities produce insufficient polymer science graduates, forcing producers to recruit from Argentine and Mexican talent pools at premium compensation.
- Multi-jurisdiction registration burden:Separate biocidal approvals under ANVISA, Argentina's Secretariat of Environment protocols, and Colombia's ICA create 18-24 month compliance timelines for regional product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Paints and Coatings Market |
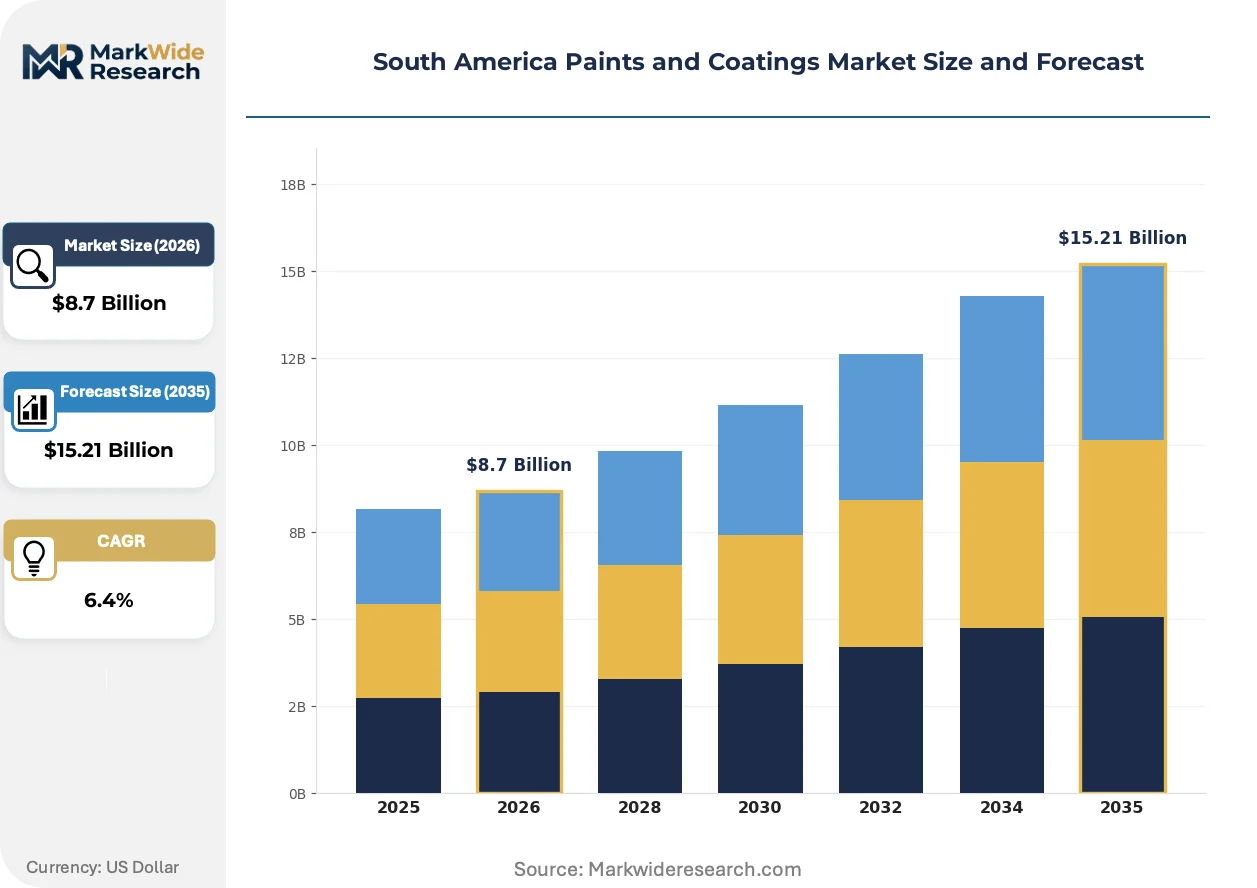
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Architectural, Automotive, Industrial, Protective Application: Residential, Commercial, Infrastructure, Marine Technology: Water-Based, Solvent-Based, Powder Coating, UV-Cured Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesale |
| Companies Covered | PPG Industries, Inc., Akzo Nobel N.V., The Sherwin-Williams Company, BASF SE, Renner Herrmann S.A., Axalta Coating Systems, Jotun, Hempel, Lanco Paints, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Paints and Coatings Market Evolving Landscape
Digital color-matching infrastructure and low-temperature cure chemistries are restructuring how coatings are specified, applied, and validated across South American industrial and architectural segments.
Self-crosslinking acrylic emulsions are miniaturizing the performance gap between water-borne and solvent-borne industrial coatings. Brazilian automotive parts suppliers in São Paulo's ABC region are qualifying these systems for plastic substrate priming. The technology is miniaturizing the capital barrier to VOC compliance by eliminating external crosslinker handling and reducing booth ventilation requirements.
Argentina's Secretariat of Environment and Sustainable Development is tightening volatile organic compound limits for architectural coatings under revised urban air quality protocols. Industrial consequences include mandatory reformulation of alkyd wood preservatives and solvent-borne masonry sealers. Buenos Aires province manufacturers are responding by accelerating water-borne silicone-acrylic hybrid development for exterior durability.
Project-based procurement consolidation is compressing specification autonomy for mid-sized Brazilian contractors. Large residential developers in Campinas and Curitiba are centralizing coatings purchasing through approved vendor lists, displacing traditional distributor relationships. This concentration is most visible in São Paulo state's high-rise residential segment where single-source agreements now cover 60% of new unit completions.
South America Paints and Coatings Market Segmentation
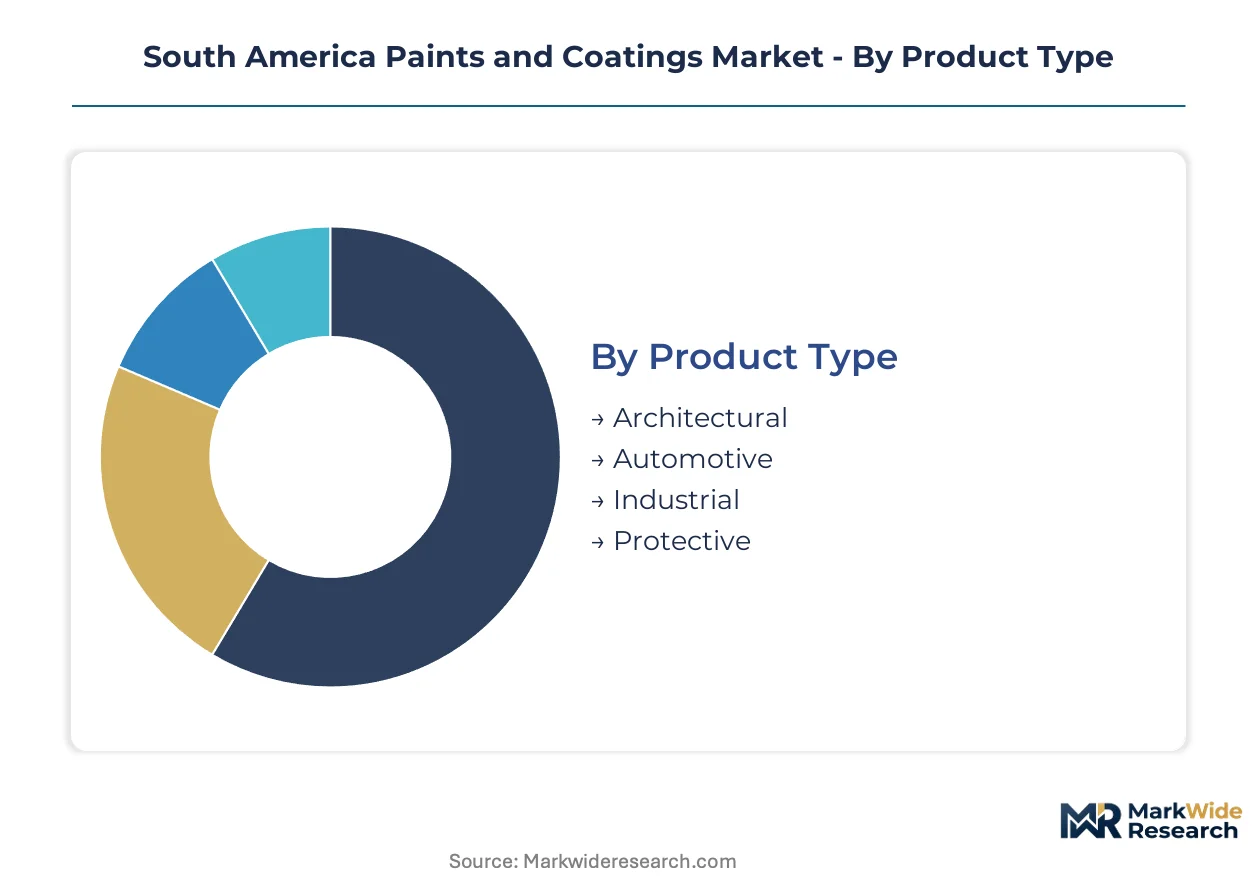
South American coatings demand fragments across distinct performance specifications and regulatory compliance tiers. Architectural primacy in Brazil's southeastern corridor contrasts with specialized industrial requirements in Argentina and Colombia. Technology choices increasingly bifurcate between water-borne regulatory compliance and solvent-borne durability in high-humidity zones.
Product Type:
Architectural coatings concentrate margin pools through distributor network control and color-matching service premiums. Industrial and protective segments command higher per-liter pricing but face longer specification cycles and certification barriers.
- Architectural:Water-based acrylic emulsions dominate interior and exterior residential applications across Brazil's Minha Casa Minha Vida developments. São Paulo state's high-rise construction pulls volume through deep distributor relationships controlled by Renner Herrmann and regional specialists. CONAMA VOC thresholds are accelerating reformulation investments toward zero-emission interior grades.
- Industrial:Solvent-borne polyurethane and epoxy systems retain structural importance in manufacturing equipment, metal fabrication, and factory infrastructure throughout Minas Gerais and São Paulo industrial corridors. Humidity resistance requirements in Amazon basin operations preserve solvent-borne niche demand despite regulatory pressure.
- Automotive:Refinish coatings for collision repair and OEM supply concentrate in São Paulo's ABC region automotive parts cluster. Water-borne basecoat technology is penetrating premium refinish segments under pressure from Brazil's air quality protocols.
- Protective:Marine and offshore platforms in Búzios and Santos basins specify high-performance epoxies and polyurethane topcoats with NORSOK-equivalent certification. Colombian port modernization is generating steel structure coatings demand with limited domestic high-performance supply.
Architectural holds installed capacity. Protective is rotating up the share rankings.
Application:
Residential construction velocity in Brazil's southeastern states determines volume allocation across formulation portfolios. Infrastructure and marine applications concentrate specification power among engineering procurement contractors with centralized vendor approval systems.
- Residential:Private housing starts in Campinas, Curitiba, and São Paulo metropolitan zones pull decorative coatings through consolidated developer procurement. Single-source agreements now govern coatings selection for 60% of new high-rise completions in São Paulo state.
- Commercial:Office and retail developments in Bogotá, Buenos Aires, and Santiago specify durable exterior acrylics and elastomeric coatings for concrete and masonry substrates. Project-based procurement consolidation is compressing specification autonomy for mid-sized contractors.
- Infrastructure:Colombia's Pacific port modernization and Bogotá metro expansion generate protective coatings demand for steel structures. Brazilian highway maintenance programs sustain industrial maintenance coating volumes across federal and state procurement channels.
- Marine:Offshore platform maintenance schedules in Brazil's pre-salt basins open specifications for suppliers with international certification equivalence. Argentine maritime repair facilities in Buenos Aires province concentrate yacht and commercial vessel refinish demand.
Infrastructure commands specification premiums. Residential anchors volume scale.
Technology:
Water-based systems capture regulatory-driven replacement demand while powder coating eliminates VOC compliance costs entirely for metal substrate manufacturers. Solvent-borne technology defends position in humidity-critical applications where water-borne performance ceilings persist.
- Water-Based:Acrylic emulsions and polyurethane dispersions now represent the primary architectural technology due to lower VOC release during application. Self-crosslinking acrylic emulsions are miniaturizing the performance gap with solvent-borne industrial coatings in São Paulo automotive parts priming applications.
- Solvent-Based:Alkyd and polyurethane systems retain structural importance in automotive refinish and industrial maintenance where chemical durability and humidity resistance prove critical. Amazon basin industrial applications with ambient moisture exceeding 85% year-round preserve this technology niche.
- Powder Coating:Zero-VOC thermoset powders are accelerating among Brazilian appliance manufacturers in Santa Catarina and São Paulo for metal furniture and refrigerator cabinet finishing. The technology bypasses solvent-based compliance costs while maintaining film performance.
- UV-Cured:Rapid-cure ultraviolet systems penetrate specialized wood coating and graphic arts applications with limited South American domestic resin supply. Import dependency from European and North American suppliers constrains regional adoption scale.
Water-based holds formulation investment priority. Powder coating is climbing the fastest.
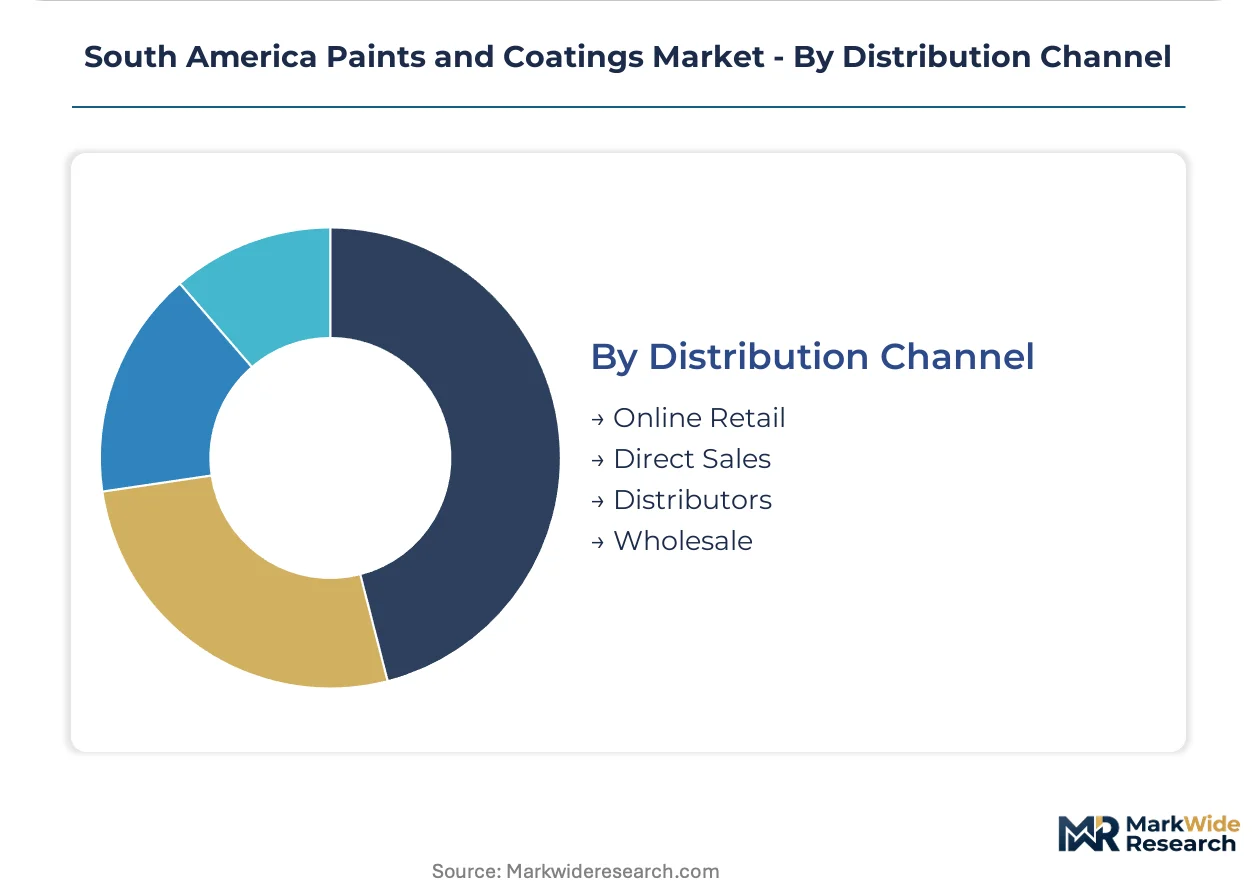
Distribution Channel:
Distributor networks concentrate market access for architectural coatings through color-matching infrastructure and credit relationships with mid-sized painting contractors. Direct sales capture industrial specification power while online retail remains nascent.
- Distributors:Regional specialists with tinting equipment and technical service capabilities control architectural coatings access across Brazil's southeastern corridor. Deep relationships with painting contractors and small construction firms sustain this channel's dominance.
- Direct Sales:Industrial and protective coatings specifications route through manufacturer technical representatives engaging directly with engineering procurement contractors and asset owners. Large residential developers in Campinas and Curitiba are centralizing purchasing through approved vendor lists.
- Wholesale:Bulk volume transactions for standard-grade architectural products serve cash-flow sensitive mid-tier contractors and government procurement programs. Price competition intensifies as product commoditization advances.
- Online Retail:Digital platforms capture DIY consumer demand and small contractor replenishment orders with limited color-matching service attachment. Logistics constraints on liquid coatings shipment restrict category expansion.
Distributors defend channel share. Direct sales is gaining specification control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA's biocidal registration protocols and CONAMA's VOC thresholds anchor Brazil's regulatory framework, shaping formulation requirements across the continent's largest coatings market.
Brazil
Minha Casa Minha Vida housing programs and private high-rise construction in São Paulo state drive architectural coatings consumption through consolidated developer procurement channels. CONAMA Resolution 491 mandates water-borne technology conversion, forcing capital reallocation toward compliant resin systems. The southeastern industrial corridor spanning São Paulo and Minas Gerais concentrates manufacturing capacity and distributor network control.
Argentina
Buenos Aires province manufacturers accelerate water-borne silicone-acrylic hybrid development for exterior durability under tightening urban air quality protocols. The Secretariat of Environment and Sustainable Development revises VOC limits for architectural coatings, mandating reformulation of alkyd wood preservatives. Maritime repair facilities in Buenos Aires province concentrate yacht and commercial vessel refinish demand for protective coatings.
Colombia
Bogotá's metro expansion and Pacific port modernization generate protective coatings demand for steel structures in a market with limited domestic high-performance supply. The Ministry of Environment resolutions mandate VOC thresholds that reformulation investments must satisfy for market access. Engineering procurement contractors with centralized vendor approval systems concentrate specification power for infrastructure applications.
Chile
Mining equipment maintenance and industrial infrastructure sustain solvent-borne polyurethane demand in high-altitude, low-humidity operating environments. The country's national environmental regulator enforces air quality standards that parallel Mercosur harmonization efforts without full regulatory convergence. Santiago's commercial construction specifies durable exterior acrylics and elastomeric coatings for concrete and masonry substrates.
Peru
Lima's coastal humidity drives specification of moisture-resistant coating systems for residential and commercial building envelopes. The national environmental authority implements product registration requirements that create compliance layers affecting market access timelines. Northern mining regions concentrate industrial maintenance coatings demand for extraction equipment and processing infrastructure.
South America Paints and Coatings Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the South American paints and coatings market. The vendor base clusters around three strategic tiers: multinational chemical conglomerates with integrated resin supply, regional specialists with deep distributor relationships, and mid-sized formulators serving niche industrial segments. Two dominant competitive moves define current positioning: portfolio diversification into water-borne and powder coating technologies to satisfy CONAMA compliance requirements, and geographic expansion through technical center investments to sustain localized color-matching capabilities.
Among multinational coating specialists, PPG Industries, Inc., Akzo Nobel N.V., and Renner Herrmann S.A. exemplify distinct archetype strategies. PPG Industries, Inc. occupies a position anchored by technical infrastructure investment. Akzo Nobel N.V. represents the marine and protective coatings specialization vector. Renner Herrmann S.A. sits within the regional distributor relationship tier, exemplifying deep channel control in architectural segments.
| Leading Market Players |
|---|
| PPG Industries, Inc. |
| Akzo Nobel N.V. |
| The Sherwin-Williams Company |
| BASF SE |
| Renner Herrmann S.A. |
| Axalta Coating Systems |
| Jotun |
| Hempel |
| Lanco Paints |
| Others |
Value Network & Pricing Analysis
Capacity utilization rates above 85% across Brazil's southeastern resin manufacturing corridor concentrate pricing power among integrated producers while establishing hard price floors for water-borne acrylic emulsions. This scale concentration shapes both supply-side consolidation incentives and the cost structure that mid-sized formulators face when sourcing compliant resin systems under CONAMA-mandated conversion timelines.
Pricing Analysis
Brazil-to-Argentina price spreads of 12-18% for standard architectural emulsions reflect freight cost differentials and import tariff layering rather than formulation quality variance. Three-tier pricing structure across premium, standard, and economy levels separates certified low-VOC grades from commodity architectural products, with certification tier and volume scale as primary differentiation drivers. Cost compression in economy-grade architectural coatings is intensifying because Chinese titanium dioxide feedstock volatility transmits directly into Brazilian formulator margins. Cash-flow sensitive mid-tier contractors exhibit highest price sensitivity, while engineering procurement contractors for infrastructure projects demonstrate lowest sensitivity due to specification-locked procurement.
Supply Chain Analysis
Port congestion at Santos and Paranaguá container terminals elevates inbound logistics costs for European water-borne alkyd and polyurethane dispersions by 8-14% relative to landed resin prices. Geographic supply concentrates in China for titanium dioxide pigment, Germany for specialty automotive refinish resins, and the United States for epoxy curing agents. Raw material dependencies center on sulfate-process TiO2, aromatic isocyanates, and epoxy novolac resins. Single-source vulnerability in Chinese pigment supply exposes Brazilian formulators to currency mismatch against the real. Distribution runs through regional specialists with tinting infrastructure across São Paulo and Minas Gerais states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. ANVISA biocidal registration timelines and CONAMA compliance certification create 18-24 month barriers that protect incumbent positions against rapid competitive displacement.
For Market Incumbents: Fortify distributor network control in Brazil's southeastern corridor through exclusive tinting equipment deployment and technical service embedding. Deepen backward integration into water-borne resin production to capture margin compression from European import dependency. Capacity addition in Santa Catarina powder coating feedstock production addresses appliance manufacturer zero-VOC demand acceleration.
For New Entrants and Emerging Players: Differentiate on ANVISA registration acceleration capabilities for antimicrobial architectural coatings targeting Colombia's Pacific coast humidity exposure. Colombian infrastructure protective coatings present the most penetrable segment given limited domestic high-performance supply. Direct technical representative engagement with Bogotá engineering procurement contractors offers the clearest go-to-market angle.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors regional specialists with captive distributor relationships and CONAMA-compliant formulation portfolios. Long-term viability hinges on water-borne conversion completion and powder coating infrastructure access. Acquisition target archetype: mid-sized Brazilian formulators with ANVISA-registered biocidal additive pipelines. NORSOK M-501 certification attainment among Brazilian marine coatings suppliers signals inflection toward offshore wind pre-positioning viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Water-Borne Resin Production | Captures margin from European import dependency while securing CONAMA compliance feedstock. |
| ANVISA Biocidal Registration Acceleration | Shortens 18-24 month compliance timelines for antimicrobial architectural coatings in humid coastal markets. |
| NORSOK M-501 Equivalent Certification Investment | Unlocks marine coatings specifications for Búzios and Santos basin platform maintenance schedules. |
| Powder Coating Capacity Expansion | Serves Santa Catarina appliance manufacturers seeking zero-VOC compliance without film performance sacrifice. |
| Distributor Network Technical Service Embedding | Defends architectural share against project-based procurement consolidation by large residential developers. |
Research Methodology
A standing panel of formulation chemists, distributor operations managers, engineering procurement contractors, and ANVISA regulatory consultants provided ongoing calibration across the analysis window. Primary interviews with plant managers at São Paulo industrial coatings facilities, procurement leads at Argentine maritime repair yards, and technical R&D directors at Colombian protective coatings specialists combined with secondary validation. Secondary sources included Brazilian customs/trade data for resin and pigment imports, CONAMA regulatory filings, ANVISA biocidal registration databases, and SEC 10-K disclosures from multinational coating manufacturers. Bottom-up volume estimates from distributor channel checks triangulated against top-down construction activity indices and industrial production metrics.
Consistency checks against external benchmarks validated volume and value outputs across the modeling period. The analytical framework segmented demand by product type, application, technology, and distribution channel, with additional dimensioning by regional regulatory cluster reflecting CONAMA, Argentina's Secretariat of Environment protocols, and Colombia's Ministry of Environment resolutions. CAGRs derived from regression-based trend extrapolation incorporating construction velocity indices, industrial capacity utilization, and compliance-driven technology substitution rates. Forecast inputs included Minha Casa Minha Vida program execution timelines and Brazilian offshore wind development pre-positioning activity.
Material uncertainties — regulatory implementation schedule slippage, currency volatility effects on imported resin costs, and construction sector credit availability constraints — sit outside the modeled envelope. Forecasts reflect assumptions regarding CONAMA Resolution 491 enforcement consistency and ANVISA evaluation pathway throughput. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Insulating Paints and Coatings Market
Paints & Coatings
Saudi Arabia Architectural Paints Market
Paints & Coatings
Global Exterior Architectural Coatings Market
Paints & Coatings
Small Paint Pail Market
Paints & Coatings
United Arab Emirates (UAE) Paints and Coatings Market
Paints & Coatings
Aircraft Paint Market
Paints & Coatings
Paint Thinner Market
Paints & Coatings
India Automotive Paints and Coatings Market
Paints & Coatings
Asia-Pacific Paints and Coatings Additives Market
Paints & Coatings
Middle-East and Africa Wood Coatings Market
Paints & Coatings
Acrylic Paints Market
Paints & Coatings
Canvas Primer Market
Paints & Coatings
Global Aerosol Paints Market
Paints & Coatings
South America Paints and Coatings Additives Market
Paints & Coatings
Polyurethane Resins Paints and Coatings Market
Paints & Coatings
Architectural Coatings Market