
 Epoxy Paint Thinner Market | 2026-2036
Epoxy Paint Thinner Market Size, Share, and Industry Trends Forecast 2026-2036
Epoxy Paint Thinner Market Foresight
Waterborne epoxy dispersion technology is narrowing the performance gap between solvent-based and low-emission systems in heavy-duty applications. PPG Industries leverages its automotive refinish footprint to anchor distribution networks across North American OEM channels. BASF SE sustains R&D intensity in hybrid thinner formulations that bridge flash-point control with volatile organic compound reduction. Nippon Paint Holdings Co., Ltd. dominates marine-grade epoxy systems in East Asian shipyard corridors.
Epoxy paint thinner denotes a formulated solvent blend designed to reduce viscosity of epoxy resin systems, typically comprising aromatic hydrocarbons, ketones, or glycol ethers with evaporation rates between 0.3 and 3.0 relative to n-butyl acetate, enabling spray application and film leveling in protective coatings. Its primary industrial purpose centers on enabling proper flow and cure characteristics for high-build epoxy primers and topcoats in corrosion protection. Solvent-based formulations still occupy the largest value share in marine and heavy industrial settings where humidity tolerance and recoat windows matter most. Water-based thinners represent the fastest-expanding product category as automotive OEMs and construction specifiers tighten volatile organic compound budgets. Bio-based alternatives command premium positioning where cradle-to-gate carbon metrics influence procurement decisions.
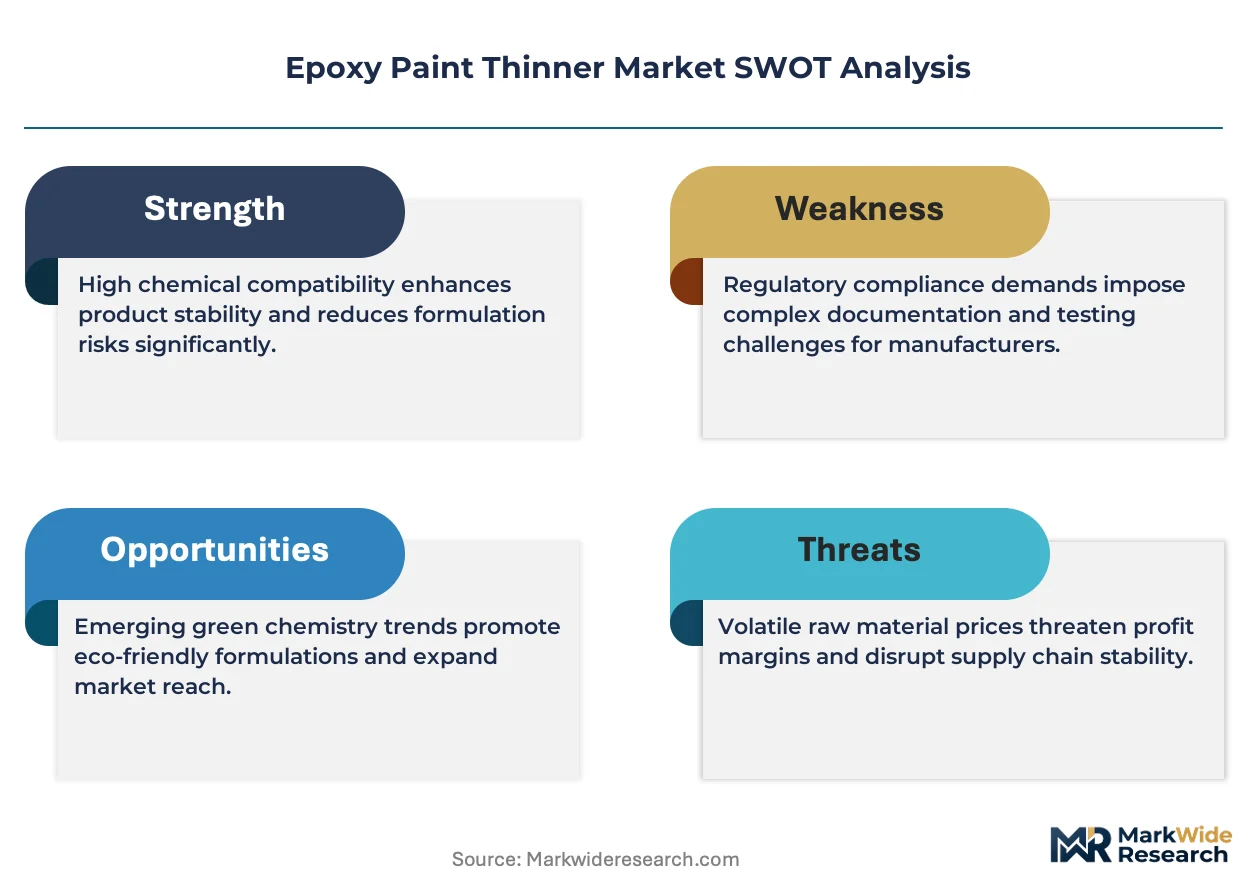
EPA NESHAP standards for hazardous air pollutants constrain solvent selection in US manufacturing and repair operations, while REACH registration requirements in Europe phase out certain aromatic diluents from consumer-facing applications. China's MEE enforces increasingly stringent VOC content limits in architectural and industrial coatings across key manufacturing provinces. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and reformulation costs.
Market Dynamics
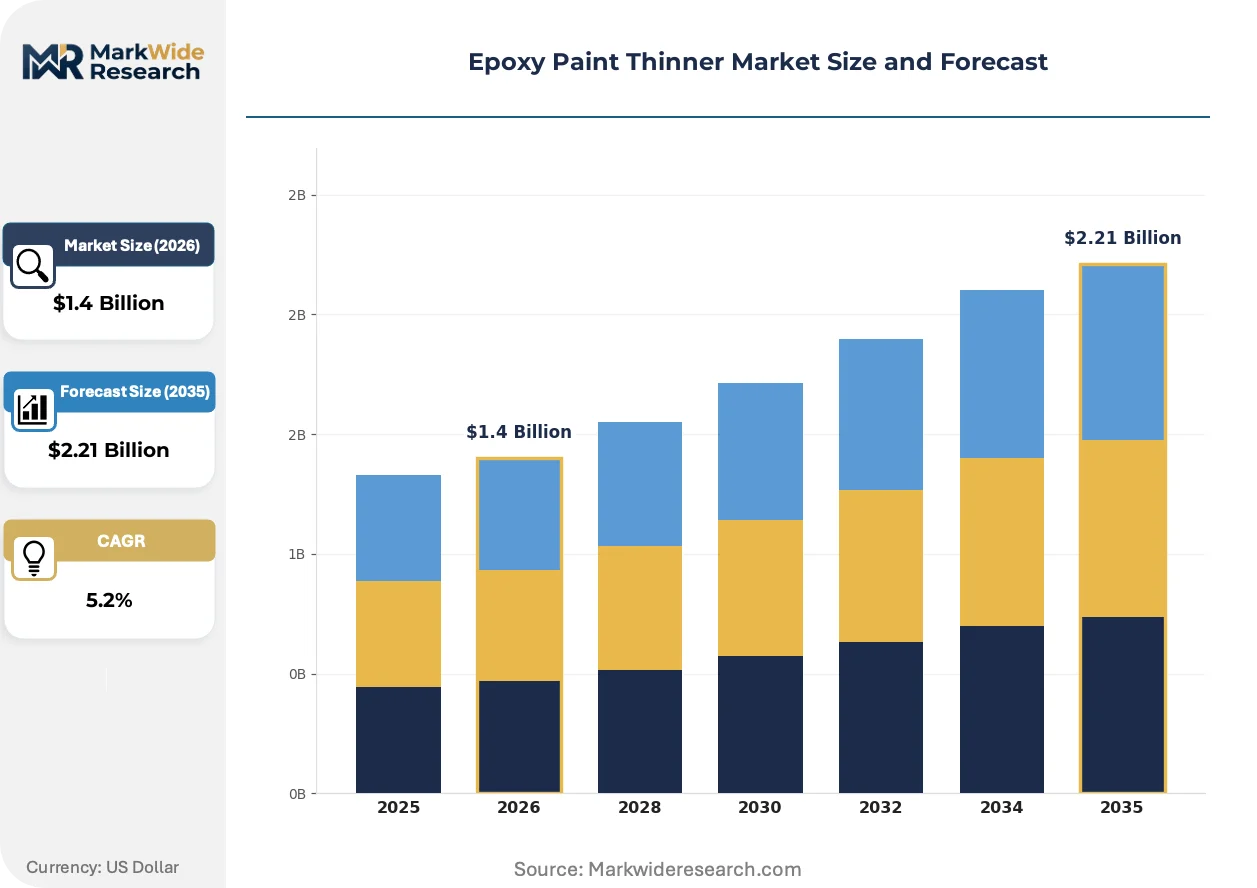
REACH registration requirements in Europe are forcing systematic phase-out of aromatic diluents, while China's MEE enforces tightening VOC limits across manufacturing provinces, creating simultaneous reformulation pressure across multiple jurisdictions.
Growth Catalysts
- MEE VOC enforcement:China's Ministry of Ecology and Environment mandates stricter volatile organic compound limits in architectural and industrial coatings, accelerating demand for compliant thinner formulations in Shanghai and Jiangsu manufacturing clusters.
- Marine maintenance cycles:Shipyard corridors in South Korea and Japan drive consumption of humidity-tolerant solvent systems for corrosion protection during dry-dock maintenance windows.
- Hybrid dispersion technology:Waterborne epoxy systems achieve flash-point control comparable to solvent-based alternatives, enabling adoption in automotive refinish operations previously restricted to conventional thinners.
Market Restraints
- Feedstock volatility:Aromatic hydrocarbon prices fluctuate with crude oil derivatives, compressing margin stability for formulated solvent blenders dependent on naphtha-derived inputs.
- East Asian supply concentration:Manufacturing of key glycol ether intermediates clusters in China's coastal chemical zones, exposing buyers to single-source geographic risk during port disruptions.
- Performance ceiling:Water-based thinners fail to achieve equivalent recoat windows in high-humidity marine environments, limiting substitution in heavy-duty protective coatings.
Strategic Opportunities
- EU Green Deal procurement:Public infrastructure tenders across Germany and France increasingly weight cradle-to-gate carbon metrics, creating premium positioning for bio-based solvent alternatives with verified lifecycle assessments.
- India industrial expansion:PLI scheme incentives for domestic manufacturing attract protective coating investments in Gujarat and Maharashtra chemical corridors, building localized thinner demand.
- Digital formulation platforms:AI-driven solvent selection tools enable custom blending for specific humidity and temperature conditions, opening technical services revenue beyond commodity sales.
Industry Challenges
- Formulation chemist scarcity:Expertise in balancing flash-point control with VOC compliance spans multiple regulatory regimes, creating recruitment bottlenecks for mid-sized blenders.
- Dual certification timelines:Simultaneous EPA NESHAP and REACH registration processes extend product launch cycles by 18-24 months for multi-jurisdictional suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Epoxy Paint Thinner Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.21 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Coatings, Adhesives, Sealants, Industrial Cleaning Product Type: Solvent-based, Water-based, Bio-based, Hybrid End User: Construction, Automotive, Marine, Aerospace Packaging Type: Cans, Drums, Pails, Bulk |
| Companies Covered | AkzoNobel N.V., PPG Industries, Inc., Sherwin-Williams Company, BASF SE, Nippon Paint Holdings Co., Ltd., Axalta Coating Systems, Jotun, Hempel A/S, Kansai Paint Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Epoxy Paint Thinner Market Shifts & Advancements
Formulation science is hybridizing solvent and waterborne chemistries to bridge performance gaps, while regulatory divergence between jurisdictions forces parallel product development tracks.
Reactive diluent technology is hybridizing with conventional solvent blends to reduce volatile organic compound emissions without sacrificing pot-life stability. Automotive OEM coating lines in Germany and Japan adopt these systems at pilot scale. The structural consequence is compressing the performance advantage historically held by pure solvent-based thinners in high-build applications.
EPA NESHAP standards for hazardous air pollutants constrain aromatic solvent selection in US manufacturing and repair operations. Metal fabrication shops face equipment retrofit costs or reformulation switches. Marine maintenance facilities in Gulf Coast states respond by segregating solvent inventories to comply with overlapping federal and state air quality rules.
Specification-driven procurement now dominates large infrastructure projects, with engineering firms mandating certified low-VOC systems before bid qualification. Distributor relationships fragment as buyers source directly from formulators with verified environmental product declarations. This pattern concentrates in Nordic public works and Dutch water management infrastructure tenders.
Epoxy Paint Thinner Market Segmentation
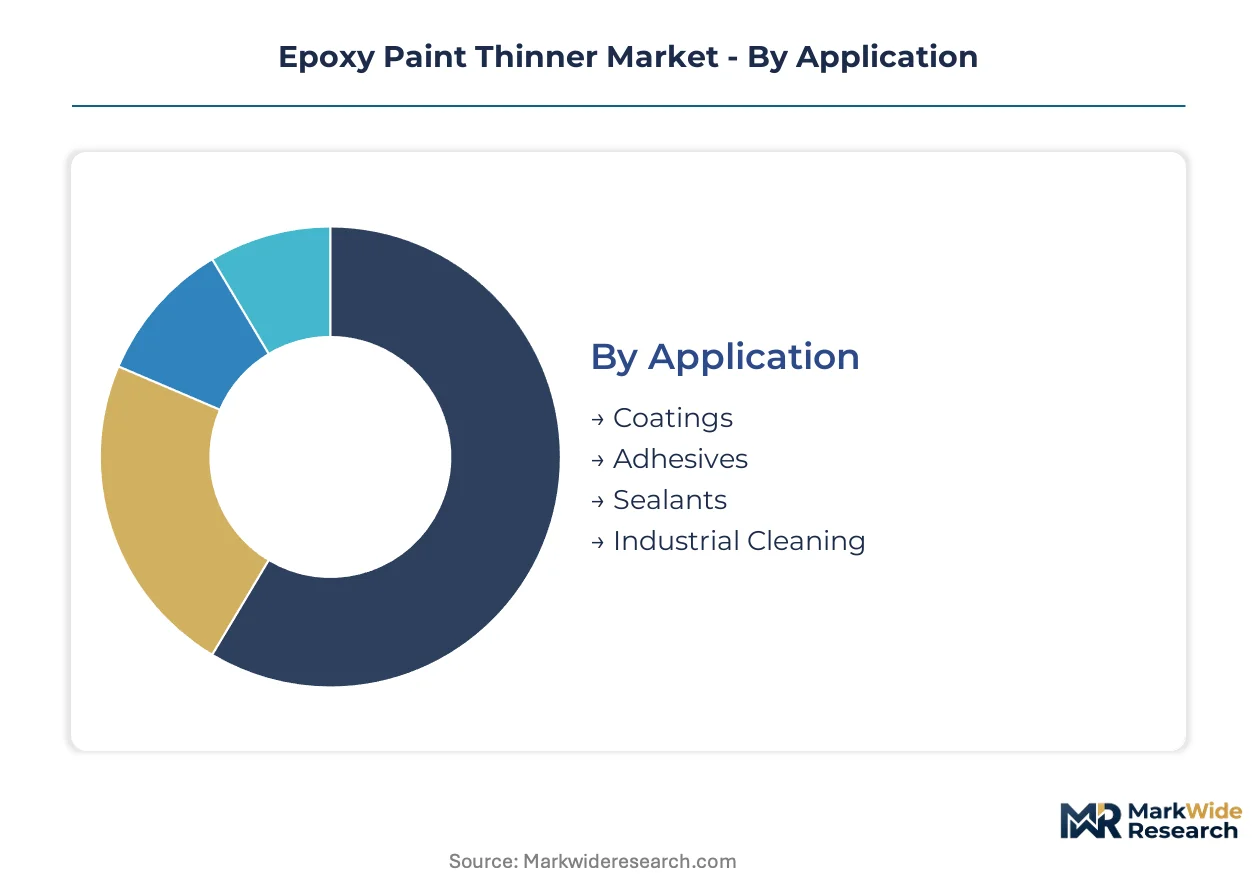
Epoxy paint thinner formulations diverge sharply across application environments and regulatory jurisdictions, with solvent chemistry choices directly determining compliance eligibility in marine, automotive, and construction end-uses. Segmentation reveals how formulation trade-offs between performance and emissions govern procurement decisions across protective coating supply chains.
Application:
Mature industrial uses anchor volume demand while emerging specialty applications reshape technical requirements for thinner systems.
- Coatings:High-build epoxy primers and topcoats in corrosion protection consume aromatic hydrocarbon blends with controlled evaporation rates between 0.3 and 3.0 relative to n-butyl acetate. Shipyard maintenance corridors in South Korea and Japan specify humidity-tolerant solvent systems for dry-dock recoat windows.
- Adhesives:Structural bonding applications require low-viscosity formulations that enable substrate wetting without compromising cure kinetics. Automotive assembly plants in Germany and Japan adopt reactive diluent hybrids at pilot scale to meet VOC budgets.
- Sealants:Joint-filling compounds utilize slower-evaporating glycol ether blends to extend working time in construction expansion joints.
- Industrial Cleaning:Equipment degreasing operations favor fast-flash ketone formulations for rapid resin residue removal in composite manufacturing facilities.
Coatings retains volume leadership; industrial cleaning holds the steepest expansion curve as equipment maintenance cycles accelerate.
Product Type:
Cost tier stratification separates commodity solvent blends from premium bio-based alternatives with verified lifecycle assessments.
- Solvent-based:Aromatic hydrocarbon and ketone formulations maintain performance dominance in high-humidity marine environments where waterborne systems fail to achieve equivalent recoat windows. EPA NESHAP standards constrain aromatic selection in US metal fabrication shops.
- Water-based:Epoxy dispersions achieve flash-point control comparable to solvent systems, enabling adoption in automotive refinish operations previously restricted to conventional thinners. China's MEE VOC enforcement accelerates formulation switches in Shanghai manufacturing clusters.
- Bio-based:Cradle-to-gate carbon metrics influence procurement in EU Green Deal infrastructure tenders across Germany and France.
- Hybrid:Reactive diluent technology bridges VOC reduction with pot-life stability in high-build protective coatings.
Solvent-based formulations retain volume leadership; water-based alternatives gain share fastest as regulatory pressure intensifies across East Asian and European coating clusters.
End User:
Customer type determines specification stringency, with aerospace and marine buyers imposing certification requirements that commodity construction markets rarely match.
- Construction:Architectural and infrastructure projects specify low-VOC systems for compliance with China's MEE standards in Jiangsu province and EU Green Deal procurement rules. Engineering firms mandate certified environmental product declarations before bid qualification.
- Automotive:OEM coating lines in Germany and Japan pilot hybrid dispersion systems to meet tightening volatile organic compound budgets without sacrificing humidity tolerance.
- Marine:Shipyard corridors in Busan and Yokohama drive consumption of solvent-based systems for corrosion protection during maintenance windows.
- Aerospace:Precision application requirements favor tightly controlled evaporation rate specifications for film leveling in protective topcoats.
Construction commands volume leadership; automotive represents the steepest expansion trajectory as OEM compliance timelines compress.
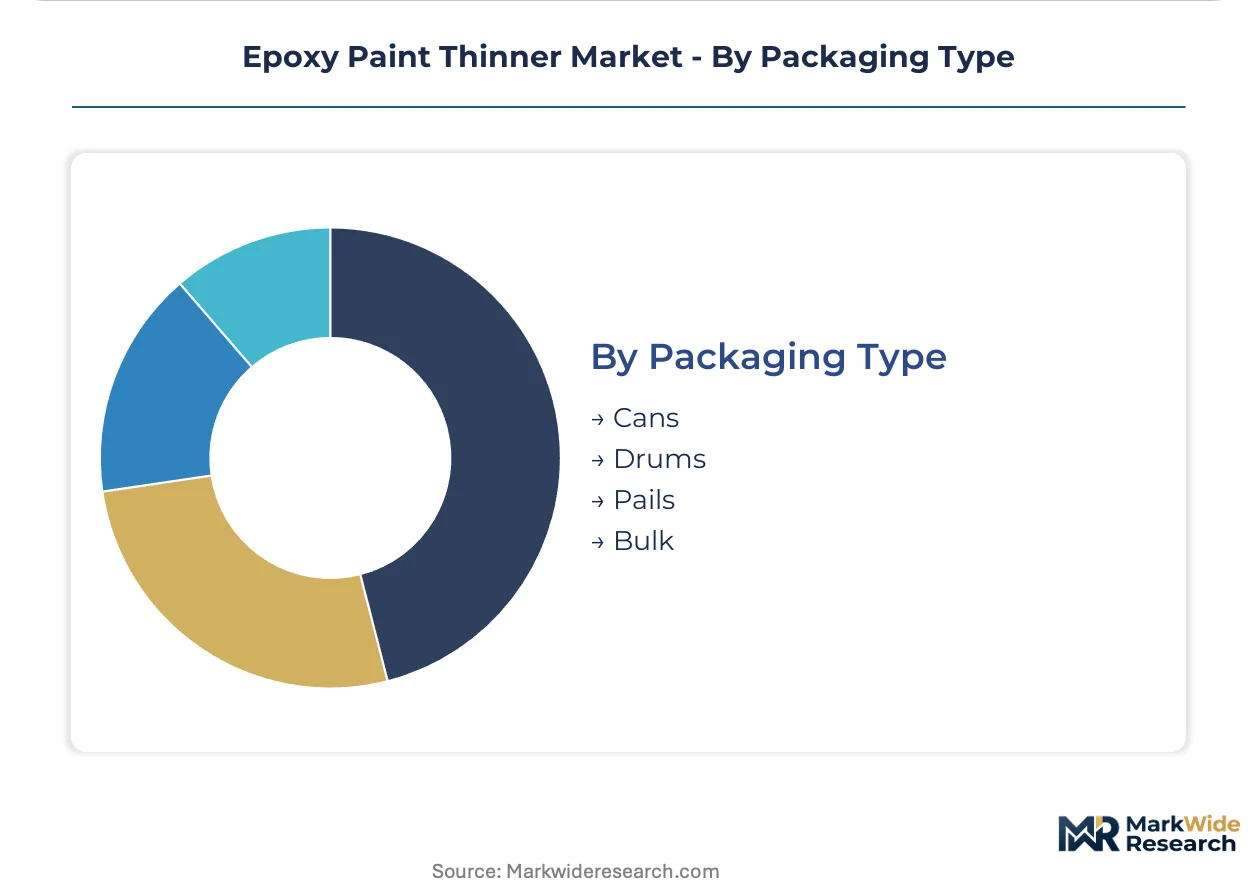
Packaging Type:
Volume scale and handling logistics differentiate procurement patterns across job-site, workshop, and industrial production environments.
- Cans:Retail-scale containers serve automotive refinish shops and small contractors requiring precise batch control for spot repairs.
- Drums:Standard industrial packaging dominates mid-volume protective coating operations in metal fabrication and equipment maintenance facilities.
- Pails:Open-head containers facilitate dip-and-brush application methods in construction sealant and adhesive workflows.
- Bulk:Tanker and tote deliveries supply continuous production lines at automotive OEM plants and marine coating formulators with captive blending capacity.
Drums retain volume leadership; bulk delivery climbs fastest as direct procurement from formulators displaces distributor intermediaries in large infrastructure tenders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean formulators export marine-grade solvent systems to shipyards in Japan and Southeast Asia, while Chinese manufacturers supply waterborne alternatives to domestic automotive clusters facing MEE enforcement.
China
Shanghai and Jiangsu province manufacturing corridors drive demand for low-VOC epoxy thinners as automotive OEMs retool coating lines. The Ministry of Ecology and Environment enforces tightening volatile organic compound limits across industrial coatings. Yangtze River Delta chemical zones concentrate glycol ether intermediate production, exposing buyers to port disruption risks during peak shipping seasons.
South Korea
Busan-Ulsan shipyard maintenance cycles sustain consumption of humidity-tolerant solvent formulations for corrosion protection. The national environmental regulator aligns industrial air quality standards with tightening international maritime conventions. Daegu-Gyeongbuk industrial zones host specialized blenders serving dry-dock recoat windows in East Asian marine corridors.
Germany
Automotive OEM coating operations in Bavaria and Baden-Württemberg pilot hybrid dispersion systems to meet EU Green Deal procurement criteria. REACH registration requirements systematically phase out aromatic diluents from consumer-facing applications. North Rhine-Westphalia chemical clusters sustain R&D intensity in cradle-to-gate carbon metric verification for bio-based alternatives.
United States
Gulf Coast marine maintenance facilities and Midwest metal fabrication shops drive demand for compliant solvent systems. EPA NESHAP standards for hazardous air pollutants constrain aromatic solvent selection in manufacturing and repair operations. Texas and Louisiana industrial corridors face overlapping federal and state air quality enforcement, forcing inventory segregation strategies.
India
Gujarat and Maharashtra chemical corridors attract protective coating investments under PLI scheme incentives for domestic manufacturing. The Bureau of Indian Standards develops VOC content benchmarks for architectural and industrial coatings. Mumbai-Pune industrial zones emerge as localized demand centers as infrastructure spending accelerates port and refinery maintenance cycles.
Epoxy Paint Thinner Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered market structure where scale advantages separate multinational coating formulators from regional solvent blenders. Consolidation concentrates around integrated resin-thinner systems, while fragmentation persists in commodity aromatic blending. Three archetypes dominate: vertically integrated coating giants with captive thinner production, independent specialty chemical blenders serving custom formulation niches, and regional distributors capturing specification-driven infrastructure tenders. Competitive moves center on backward integration into glycol ether intermediates and strategic partnerships with marine classification societies for certified product approvals.
Among diversified chemical conglomerates, BASF SE and AkzoNobel N.V. occupy positions spanning resin synthesis through formulated solvent systems. PPG Industries, Inc. exemplifies the channel-controlling archetype, leveraging automotive refinish distribution networks to anchor thinner placement in OEM specification chains. Nippon Paint Holdings Co., Ltd. sits within the Asia-Pacific specialist tier, with geographic naming indicating Japanese origin and corporate limited structure.
| Leading Market Players |
|---|
| AkzoNobel N.V. |
| PPG Industries, Inc. |
| Sherwin-Williams Company |
| BASF SE |
| Nippon Paint Holdings Co., Ltd. |
| Axalta Coating Systems |
| Jotun |
| Hempel A/S |
| Kansai Paint Co., Ltd. |
| Others |
Supply & Pricing Matrix
Overcapacity in China's Yangtze River Delta glycol ether corridors compresses supplier pricing power while simultaneously accelerating consolidation among mid-sized blenders seeking feedstock security. This utilization dynamic forces thinner formulators toward long-term offtake contracts with coastal petrochemical complexes, reshaping procurement risk profiles across East Asian coating clusters.
Pricing Analysis
Cost-plus contracts indexed to naphtha derivatives dominate aromatic hydrocarbon thinner procurement, with BASF and AkzoNobel leveraging volume scale to secure preferential terms from Yangtze River Delta producers. Price differentiation hinges on certification tier—REACH-registered formulations command substantial premiums over unregistered commodity blends—and geographic delivery cost to inland manufacturing zones. Pricing pressure stems from MEE VOC enforcement compressing demand for conventional solvent-based systems in Shanghai automotive clusters. Small automotive refinish shops exhibit highest price sensitivity, while marine classification society-certified buyers prioritize performance consistency over unit cost.
Supply Chain Analysis
Contract manufacturing capacity concentrates with Yangtze River Delta petrochemical complexes, Ulsan-based Korean blenders, and Antwerp-Rotterdam chemical corridor operators serving European formulation demand. Raw material flows draw from naphtha-derived aromatic hydrocarbons, propylene oxide-based glycol ethers, and acetone feedstocks. Single-source vulnerability runs through China's coastal port infrastructure, where typhoon season disruptions strand glycol ether intermediates for weeks. Distribution runs through integrated coating formulators with captive blending capacity, bypassing traditional chemical distributor networks in large infrastructure tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Epoxy paint thinner demand sits in early-cycle expansion as waterborne dispersion technology penetrates automotive refinish operations previously restricted to solvent systems. China's MEE enforcement timeline accelerates this substitution curve beyond prior adoption forecasts.
For Market Incumbents: Insulate formulation expertise through captive R&D investment in hybrid reactive diluent technology, countering waterborne substitution threats in high-humidity marine environments. Deepen backward integration into glycol ether intermediates by securing long-term offtake agreements with Yangtze River Delta producers, mitigating feedstock volatility exposure. Prioritize REACH registration maintenance for aromatic diluent portfolios to preserve European infrastructure tender eligibility. For New Entrants and Emerging Players: Mid-tier automotive coating operations in India's Maharashtra chemical corridor represent the most penetrable entry point, as PLI scheme incentives attract protective coating investments without entrenched incumbent relationships. Bio-based solvent alternatives with verified cradle-to-gate carbon metrics offer differentiation in EU Green Deal procurement channels where established players lack certified offerings. Lead with technical services revenue—AI-driven solvent selection platforms for custom humidity conditions—rather than commodity volume competition. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated coating-thinner system providers serving marine classification society certification requirements, generating multi-year dry-dock maintenance contracts. Long-term viability across the analysis window favors targets with dual EPA NESHAP and REACH registration capabilities, avoiding stranded inventory risk from regulatory divergence. Monitor MEE enforcement intensity in Jiangsu province as the critical inflection signal for waterborne adoption acceleration versus sustained solvent-based demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glycol Ethers | Captive supply of Yangtze River Delta intermediates insulates margin from naphtha volatility. |
| Hybrid Formulation Development | Reactive diluent technology bridges VOC compliance with marine humidity tolerance requirements. |
| REACH Registration Investment | Systematic aromatic diluent phase-out in EU infrastructure tenders demands compliant portfolios. |
| Digital Formulation Platforms | AI-driven solvent selection opens technical services revenue beyond commodity thinner sales. |
| Marine Classification Partnerships | Certified product approvals with Korean Register lock in Busan-Ulsan dry-dock maintenance cycles. |
Research Methodology
Initial hypotheses were tested against primary input from plant managers at East Asian petrochemical complexes, procurement leads at German automotive OEM coating operations, distribution channel partners serving Gulf Coast marine maintenance facilities, and technical R&D directors at integrated coating formulators, then refined against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from listed chemical conglomerates, and MEE regulatory enforcement disclosures. Bottom-up demand estimates from end-use consumption patterns were triangulated with top-down supply-side capacity assessments across Yangtze River Delta and Ulsan chemical corridors.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon, with segmentation modeled by product chemistry tier, end-use industry application, packaging format scale, and regional production hub concentration. CAGRs were derived from fitted growth curves calibrated to historical substitution elasticities between solvent-based and waterborne systems. Forecast inputs incorporated MEE VOC limit enforcement trajectories, REACH registration phase-out timelines, and marine maintenance cycle frequencies at East Asian shipyard corridors.
Practitioners should monitor regulatory enforcement intensity, feedstock price volatility, and waterborne technology performance breakthroughs for early signals of forecast revision. Quarterly review of MEE inspection disclosures, naphtha derivative futures spreads, and marine classification society certification updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Morocco Paints and Coatings Market
Paints & Coatings
Bahrain Paints and Coatings Market
Paints & Coatings
Fluorescent Paint Market
Paints & Coatings
Mosquito-Repellent Paints Market
Paints & Coatings
Middle East and Africa Floor Coatings Market
Paints & Coatings
Metal Paint Tray Market
Paints & Coatings
Radar Absorbing Paint Market
Paints & Coatings
India Automotive Paints and Coatings Market
Paints & Coatings
Paint Curing Lamp Market
Paints & Coatings
South America Architectural Coatings Market
Paints & Coatings
Global Primer Market
Paints & Coatings
Middle East and Africa Paints and Coatings Market
Paints & Coatings
Refinish Paint Market
Paints & Coatings
Cellulose Paints Market
Paints & Coatings
Paint Rollers Market
Paints & Coatings
Small Paint Pail Market