
 Morocco Paints and Coatings Market | 2026-2036
Morocco Paints and Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Morocco Paints and Coatings Market Foresight
Residential construction is recalibrating demand patterns across Morocco's paints and coatings sector, pulling volume toward water-based decorative formulations. Akzo Nobel N.V. leverages its European formulation heritage to anchor premium architectural lines in urban centers. Jotun Morocco dominates marine and protective coatings through its coastal manufacturing footprint. ATLAS PEINTURES competes on proximity, sustaining strong distribution control across northern Morocco through localized production.
Paints and coatings encompass liquid, powder, and film-forming materials engineered from binders, pigments, solvents, and additives to protect substrates and deliver aesthetic or functional surface properties. Industrial formulations typically require corrosion resistance ratings and chemical hardness parameters for machinery and infrastructure longevity. Water-based technology leads residential uptake due to lower volatile organic compound emissions and alignment with tightening environmental standards. Solvent-based coatings retain share in industrial and marine applications where durability under salt spray and chemical exposure remains critical. Powder coatings represent the fastest-growing technology segment, expanding as Moroccan automotive and metal fabrication OEMs adopt electrostatic application lines.
Morocco's national building energy efficiency codes, administered by the country's construction and urban planning regulator, now mandate reflective and insulating coatings for new public buildings. The Moroccan Standardization Institute (IMANOR) enforces product labeling and VOC thresholds that shape importer compliance costs and domestic formulation priorities. Stakeholders must monitor how upcoming green building certifications and EU-equivalent chemical registration requirements will reshape raw material sourcing and local manufacturing investment decisions.
Market Dynamics
Residential construction in Morocco is pulling volume decisively toward water-based decorative formulations as building energy efficiency codes tighten across the Casablanca-Settat corridor and northern industrial zones.
Growth Catalysts
- IMANOR VOC thresholds:The Moroccan Standardization Institute's emission ceilings accelerate domestic reformulation toward low-solvent technologies. Local producers retool binders and pigment systems to maintain market access.
- Reflective roof mandates:National building energy efficiency codes now require solar-reflective coatings on new public buildings. Public procurement channels absorb premium architectural grades at scale.
- Industrial clustering:Concentrated manufacturing zones near Tangier-Med and Jorf Lasfar compress logistics costs for marine and protective coatings destined for port infrastructure and offshore assets.
Market Restraints
- Titanium dioxide import dependency:Morocco lacks domestic TiO2 production. Price volatility in Chinese and European feedstock markets transmits directly into formulation costs.
- Solvent-based legacy infrastructure:Industrial coating facilities in Kenitra and Mohammedia carry sunk capital in high-VOC lines. Conversion timelines lag regulatory phase-outs.
- Technical workforce scarcity:Electrostatic powder application and advanced corrosion testing require specialized technicians. Training pipelines through vocational institutes remain underdeveloped.
Strategic Opportunities
- Green building certification expansion:Emerging LEED-equivalent standards in Moroccan commercial real estate create specification pull for low-emission, high-durability architectural systems.
- Automotive OEM electrostatic lines:Renault-Nissan and Stellantis supplier parks near Tangier seek captive powder coating capacity. Localized pretreatment and application equipment investment unlocks tier-one supplier status.
- Southern corridor logistics:Marrakesh-Safi and Draa-Tafilalet regions show construction acceleration with thin distribution coverage. Proximity production or satellite mixing depots capture underserved volume.
Industry Challenges
- IMANOR certification timelines:Product registration and label compliance require 8-14 month validation cycles. Importers face working capital strain and launch delays.
- Legacy distributor inventory systems:Traditional trade channels in Fez and Meknes operate on paper-based reordering. Digital integration for demand forecasting and SKU rationalization demands upfront IT investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Morocco Paints and Coatings Market |
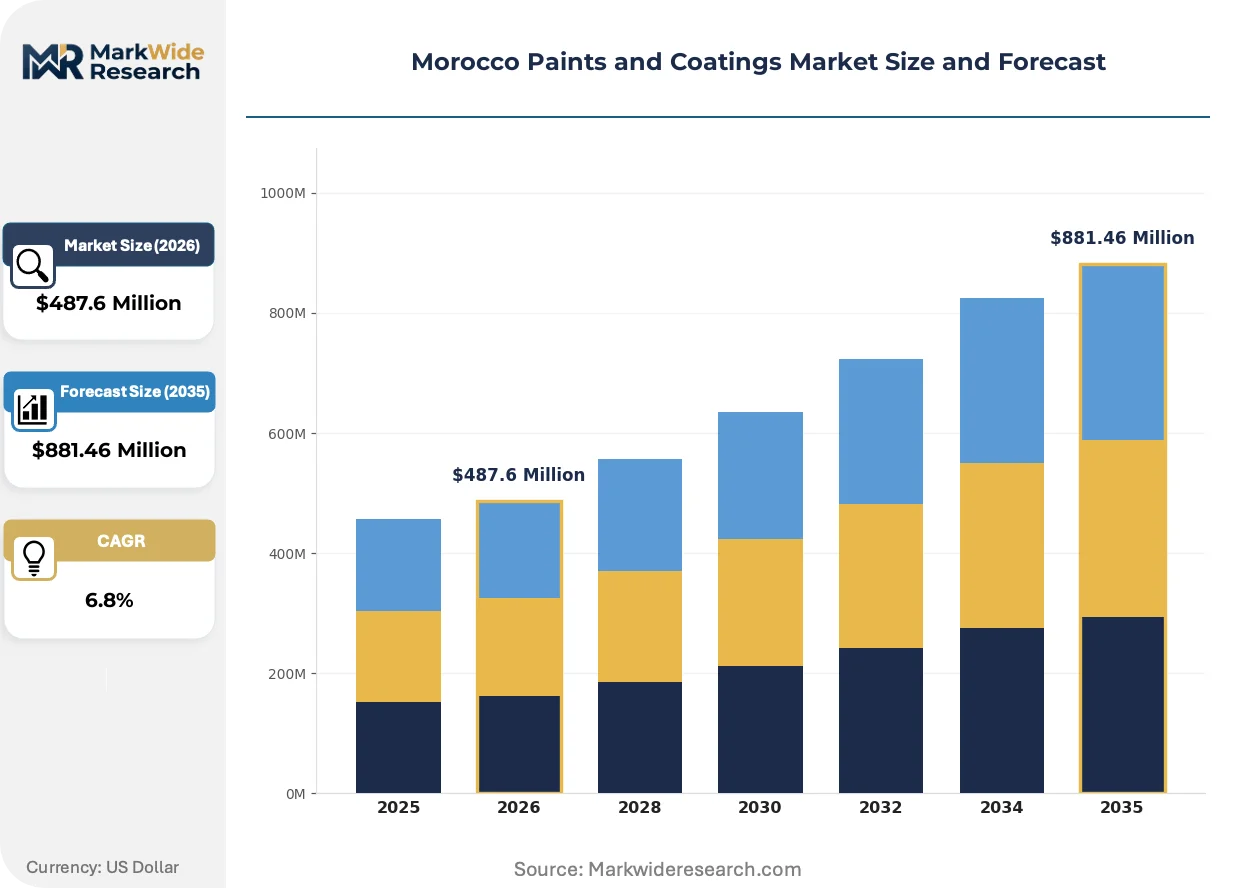
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Architectural, Industrial, Marine, Protective Application: Residential, Commercial, Infrastructure, Automotive Technology: Water-based, Solvent-based, Powder, UV-cured End User: Contractors, Manufacturers, DIY Consumers, Retailers |
| Companies Covered | FACOP, Kansai Paint Co. Ltd., Akzo Nobel N.V., The Sherwin-Williams Company, ATLAS PEINTURES, PPG Industries, Inc., Jotun Morocco, Sika Morocco, Colorado SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Morocco Paints and Coatings Market Shifts & Advancements
Formulation chemistry and application technology are converging to compress coating lifecycle costs while Moroccan regulators tighten the link between building performance standards and material specification.
Nano-engineered self-cleaning coatings are converging with photocatalytic titanium dioxide surface treatments to reduce maintenance intervals on high-rise facades and infrastructure. Commercial developers in Casablanca and Rabat specify these systems for rental properties where tenant turnover demands rapid unit refurbishment. The technology is converging with automated spray application robotics to cut labor content per square meter.
IMANOR's alignment with EU REACH substance restrictions is forcing reformulation of chromate-based corrosion inhibitors and certain isocyanate hardeners. Industrial protective coatings for offshore platforms and chemical processing equipment face the steepest substitution curves. Importers and domestic blenders are accelerating bio-based epoxy development to preempt compliance cliffs.
Project developers are consolidating specification authority away from general contractors toward retained architectural firms and engineering consultancies. Large residential and hospitality projects in the Casablanca-Settat corridor now route coating selection through performance-based tender documents rather than open material substitution. This concentrates volume with formulation houses capable of warranty-backed system proposals and certified applicator networks.
Morocco Paints and Coatings Market Segmentation
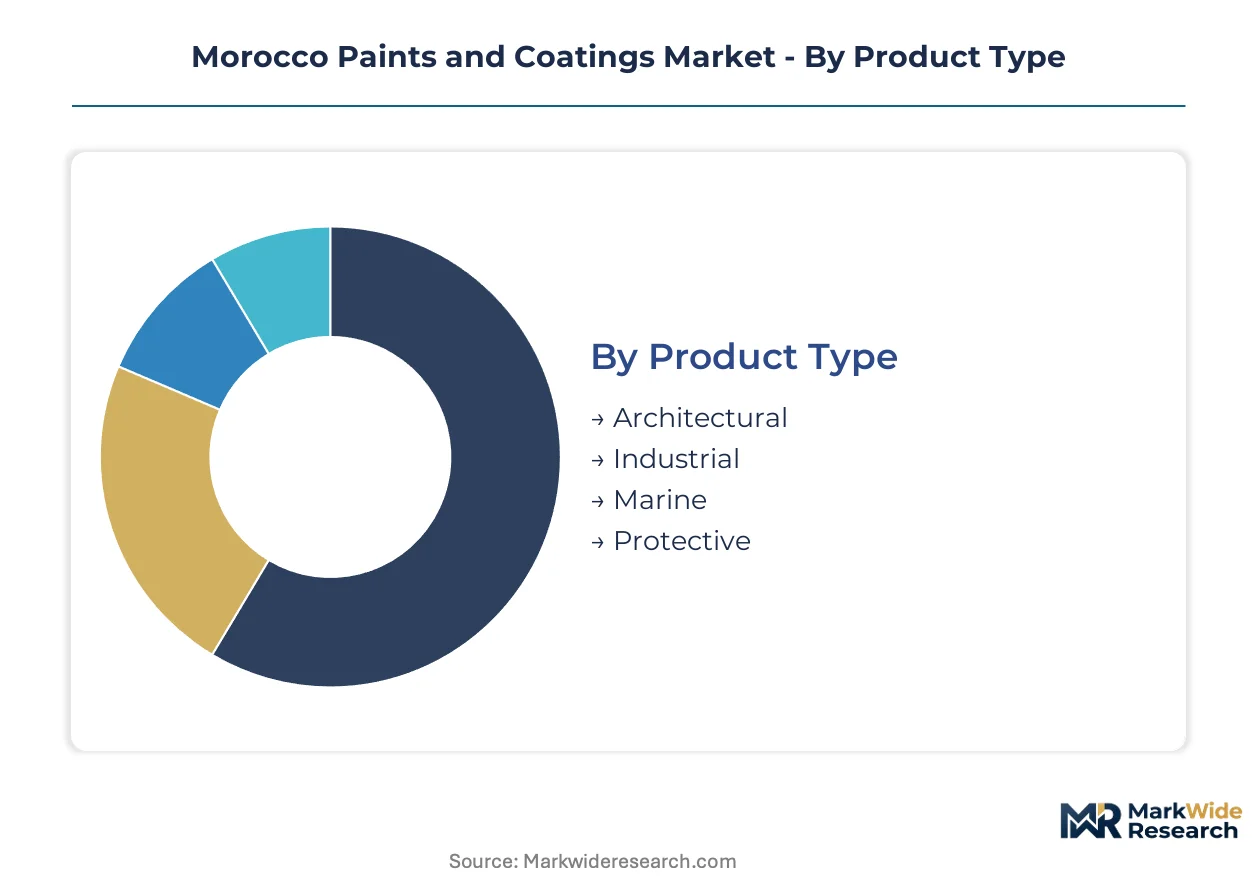
Morocco's paints and coatings market fragments across four critical dimensions that determine formulation priorities, distribution channels, and regulatory exposure. Understanding where segments intersect—such as water-based architectural coatings sold through retail DIY channels versus solvent-based marine systems procured by industrial contractors—shapes competitive positioning and investment decisions.
Product Type:
Architectural and industrial formulations operate as standalone procurement categories with distinct specification chains, while marine and protective coatings embed within larger infrastructure and asset maintenance programs.
- Architectural:Decorative coatings formulated from acrylic, alkyd, or vinyl binders with pigment loadings optimized for UV resistance and color retention. Demand concentrates in Casablanca-Settat residential developments where IMANOR VOC thresholds are pulling specification toward low-emission water-based systems.
- Industrial:High-performance coatings engineered for machinery, metal fabrication, and OEM finishing with hardness ratings and chemical resistance parameters. Procurement clusters around Tangier-Med automotive supplier parks where Renault-Nissan and Stellantis operations require captive pretreatment and electrostatic application capacity.
- Marine:Anti-corrosive and anti-fouling systems for vessel hulls, decks, and offshore structures exposed to salt spray and immersion.
- Protective:Heavy-duty formulations for bridges, pipelines, storage tanks, and chemical processing equipment requiring extended lifecycle under aggressive environments.
Architectural leads volumes today; industrial is gaining share fastest.
Application:
Residential and commercial construction dominate unit demand, while infrastructure and automotive applications concentrate value through specialized specification and certified applicator networks.
- Residential:Interior and exterior decorative coatings applied to single-family homes, multi-unit dwellings, and renovation projects. Volume concentrates in northern Morocco's urban corridors where building energy efficiency codes mandate reflective roof coatings on new developments.
- Commercial:High-traffic interior systems and facade treatments for offices, retail, and hospitality properties. Procurement in Rabat and Casablanca increasingly routes through retained architectural firms demanding warranty-backed performance specifications.
- Infrastructure:Bridge, tunnel, highway, and utility coatings requiring extended durability under mechanical stress and environmental exposure.
- Automotive:OEM finishing lines and refinish coatings for vehicle production and aftermarket repair, primarily serving Tangier-Med export manufacturing.
Residential commands absolute volume; automotive shows the steepest expansion trajectory.
Technology:
Water-based and solvent-based technologies split the market by regulatory exposure, while powder and UV-cured systems represent capital-intensive upgrades requiring electrostatic lines or specialized curing equipment.
- Water-based:Acrylic and polyurethane dispersions with reduced volatile organic compound content, compliant with IMANOR emission ceilings. Adoption accelerates in residential and commercial architectural segments where indoor air quality standards tighten.
- Solvent-based:Traditional alkyd and epoxy formulations delivering superior hardness and chemical resistance for marine, protective, and select industrial applications. Legacy production infrastructure in Kenitra and Mohammedia creates conversion friction against regulatory phase-outs.
- Powder:Thermosetting resin systems applied electrostatically and cured thermally, eliminating solvent emissions entirely. Moroccan automotive OEMs and metal fabricators are adopting captive lines to meet export market environmental requirements.
- UV-cured:Rapid-curing systems for wood coatings, graphic arts, and specialty industrial applications requiring minimal drying time and high throughput.
Solvent-based retains industrial dominance; powder is climbing the fastest.
End User:
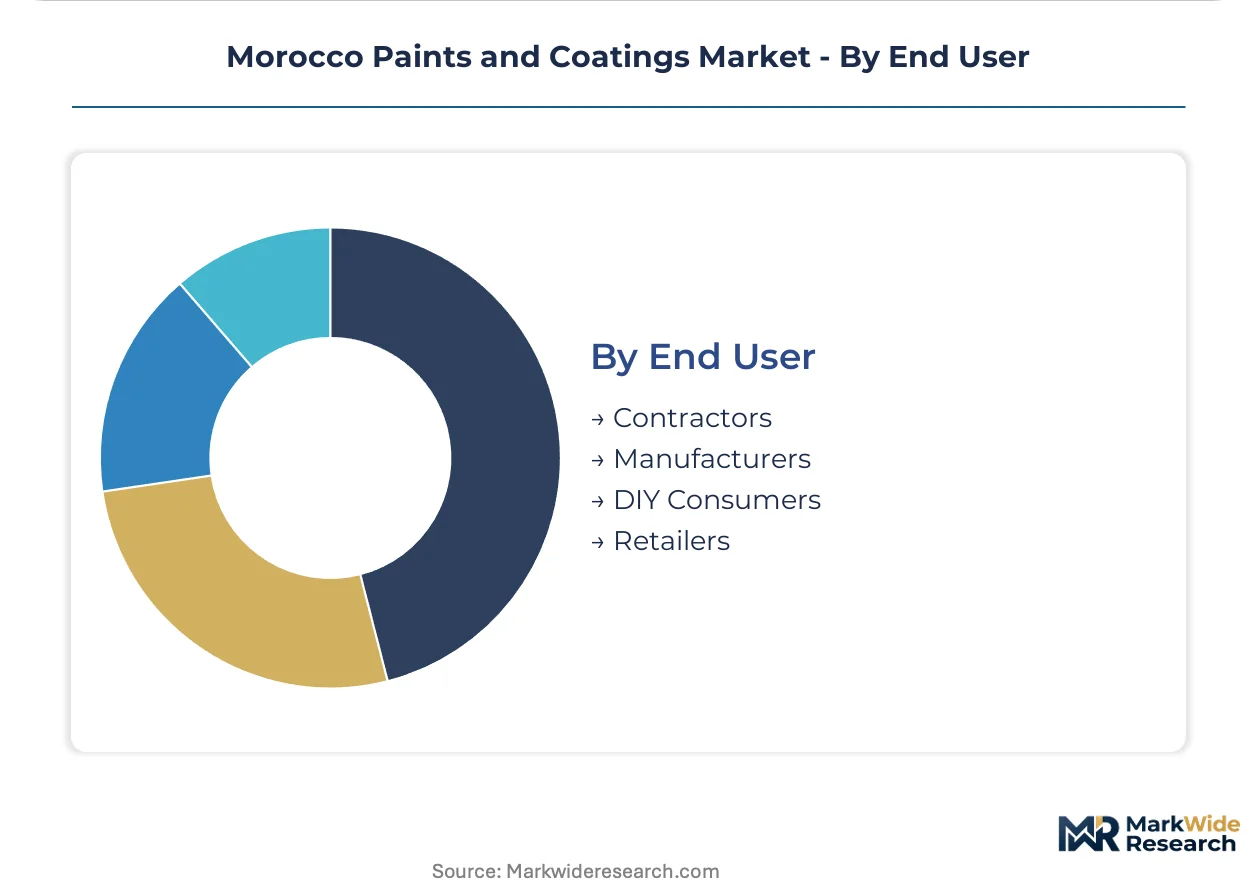
Contractors and manufacturers drive specification authority through performance-based procurement, while DIY consumers and retailers shape volume through price-sensitive, brand-recognition purchasing.
- Contractors:Professional applicators and construction firms executing residential, commercial, and infrastructure projects with certified workforce and equipment. Concentration in Casablanca-Settat corridor where large developers consolidate coating selection through engineering consultancies.
- Manufacturers:Industrial OEMs, automotive assemblers, and metal fabricators operating captive coating lines or sourcing pretreatment and finishing as tier-one supply. Renault-Nissan and Stellantis supplier parks near Tangier represent the most concentrated manufacturing demand.
- DIY Consumers:Homeowners and small-scale renovators purchasing through retail channels for interior and exterior maintenance projects.
- Retailers:Distributors, hardware chains, and specialized paint stores controlling last-mile access in Fez, Meknes, and secondary cities with legacy paper-based inventory systems.
Contractors lead volumes today; manufacturers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between Moroccan IMANOR standards and European REACH compliance is redirecting formulation investment toward Tangier-Med and Jorf Lasfar, where lower cost-of-compliance meets export market access.
Casablanca-Settat Corridor
Residential construction and commercial real estate development concentrate coating demand in Morocco's economic heartland. IMANOR's building energy efficiency codes mandate reflective roof coatings on new public buildings, pulling specification toward premium architectural grades. Industrial clustering around Mohammedia compresses logistics costs for marine and protective coatings serving port infrastructure.
Tangier-Tetouan-Al Hoceima
Automotive OEM finishing lines and export-oriented manufacturing dominate coating procurement patterns. Renault-Nissan and Stellantis supplier parks seek captive electrostatic powder capacity to meet EU environmental requirements for export vehicles. Jorf Lasfar's chemical processing zone anchors heavy-duty protective coating demand for offshore assets and industrial infrastructure.
Rabat-Sale-Kenitra
Government construction programs and administrative building refurbishment sustain steady architectural coating volumes. The region's legacy industrial facilities carry sunk capital in high-VOC solvent-based lines, creating conversion friction against IMANOR phase-out timelines. Public procurement channels absorb premium grades through performance-based tender documents.
Marrakesh-Safi
Tourism-driven hospitality construction and residential expansion accelerate coating consumption with thin distribution coverage. Southern corridor logistics gaps create openings for satellite mixing depots or proximity production investments. Local distributors operate on paper-based inventory systems, delaying demand signal transmission to manufacturers.
Fez-Meknes
Traditional trade channels and artisan construction practices sustain mid-tier decorative coating demand. Retail hardware networks control last-mile access but lack digital integration for SKU rationalization. Regional vocational training institutes remain underdeveloped for electrostatic application and advanced corrosion testing technician pipelines.
Morocco Paints and Coatings Market Competitive Landscape
Capacity expansion dominates the current landscape as international formulation houses and domestic producers retool for water-based and powder technologies. The vendor base splits between European heritage multinationals with premium architectural positioning and regional specialists controlling distribution density in northern Morocco. Three archetypes anchor competitive positioning: technology licensors with formulation patents, proximity producers with localized manufacturing, and distribution-integrated blenders with retail channel control. M&A activity and strategic partnerships concentrate around automotive supplier park adjacencies and green building certification capabilities.
Within the European heritage tier, Akzo Nobel N.V. and PPG Industries, Inc. occupy positions tied to premium architectural and industrial specification authority. Jotun Morocco exemplifies the coastal manufacturing archetype, leveraging marine and protective coating specialization through port-proximate production. ATLAS PEINTURES represents the proximity-producer model, sustaining distribution control across northern Morocco through localized formulation and retail network integration.
| Leading Market Players |
|---|
| FACOP |
| Kansai Paint Co. Ltd. |
| Akzo Nobel N.V. |
| The Sherwin-Williams Company |
| ATLAS PEINTURES |
| PPG Industries, Inc. |
| Jotun Morocco |
| Sika Morocco |
| Colorado SA |
| Others |
Supply & Pricing Matrix
IMANOR's reflective roof coating mandates gate both qualified supply access and premium-tier pricing power, as compliance-certified formulations command architectural specification authority while non-compliant imports face 8-14 month validation delays that freeze working capital.
Pricing Analysis
Distributor margins in northern Morocco compress pricing flexibility for water-based architectural grades, while direct-to-OEM channels around Tangier-Med negotiate volume discounts on powder coating systems. Three-tier pricing structure across premium certified, standard compliant, and economy import levels separates specification-grade projects from residential renovation volume. Price differentiation rests on IMANOR certification status and applicator warranty backing. Cost compression in economy tiers is intensifying because Chinese TiO2 feedstock volatility transmits directly into formulation costs. DIY consumers through Fez-Meknes retail channels show highest price sensitivity; automotive OEMs at Tangier-Med supplier parks prioritize total-applied-cost over unit pricing.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale powder coating demand from Renault-Nissan and Stellantis operations, while retail distribution runs through ATLAS PEINTURES' northern Morocco network and traditional hardware channels in secondary cities. Geographic supply concentration draws from China for titanium dioxide feedstock, Spain for acrylic resin intermediates, and Germany for specialty corrosion inhibitors. Raw material dependencies hinge on TiO2 pigment systems, epoxy resin binders, and isocyanate hardeners facing REACH-aligned substitution pressures. Single-source vulnerability in Chinese TiO2 creates formulation cost volatility that Moroccan blenders cannot hedge domestically.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Morocco's paints and coatings market reads as a late-cycle quality story where residential procurement consolidation toward retained architectural firms pulls specification authority away from price-competitive general contractors.
For Market Incumbents: Deepen applicator certification networks in the Casablanca-Settat corridor to defend specification control against emerging low-cost water-based entrants from southern Europe. Anchor backward integration into TiO2 alternative sourcing through African mineral partnerships to offset Chinese feedstock volatility. Prioritize green building certification pre-positioning before LEED-equivalent standards harden compliance cliffs for legacy formulations. For New Entrants and Emerging Players: E-commerce direct-to-contractor platforms unlock white-space access in Marrakesh-Safi and Draa-Tafilalet where paper-based distributor systems delay demand signal transmission. Target satellite mixing depot investments to capture southern corridor construction acceleration with thin incumbent coverage. Lead with water-based architectural grades priced below IMANOR-certified premiums but above economy imports to occupy the specification-sensitive mid-tier. For Investors and Strategic Acquirers: Valuations sit cheapest among regional proximity producers with captive distribution but lacking powder coating technology licenses. Long-term viability favors blenders with automotive OEM adjacency and electrostatic application equipment ownership. Watch for Stellantis supplier park expansion announcements as the inflection signal for captive coating capacity demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into TiO2 Alternatives | African mineral partnerships reduce Chinese feedstock dependency for Moroccan formulators. |
| Electrostatic Powder Line Investment | Tangier-Med automotive OEMs require EU-compliant captive coating capacity for export vehicles. |
| Green Building Certification Pre-Positioning | LEED-equivalent standards in commercial real estate will specify low-emission architectural systems. |
| Applicator Network Certification | Warranty-backed installation separates specification-grade projects from commodity competition. |
| Southern Corridor Distribution Expansion | Marrakesh-Safi construction acceleration outpaces incumbent logistics coverage. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at Mohammedia and Kenitra facilities, procurement leads at Tangier-Med automotive suppliers, distribution channel partners in Fez-Meknes, and technical R&D directors at IMANOR-compliant blenders. Secondary validation drew from Moroccan customs trade data, IMANOR regulatory filings, ACC regional coatings reports, and SEC 10-K disclosures of multinational formulation houses. Bottom-up segment sizing and top-down macroeconomic anchoring were triangulated to constrain projection variance.
Historical reference periods spanning pre-regulatory and post-IMANOR enforcement phases anchored the forecast window to observable demand elasticity around code implementation. The analytical framework modeled product type, application, technology, and end-user dimensions across the projection horizon. CAGRs were derived from segment-level volume trajectories and value-per-unit trends. Forecast inputs incorporated building permit data from the Casablanca-Settat corridor and automotive production schedules at Tangier-Med.
The model assumes a particular technology adoption path; alternative pathways for powder coating penetration in automotive finishing would alter the outlook. Forecasts reflect base-case assumptions around IMANOR enforcement continuity and EU REACH alignment timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Interior Architectural Coatings Market
Paints & Coatings
Low VOC Paint Market
Paints & Coatings
Cellulose Paints Market
Paints & Coatings
Europe Paints and Coatings Market
Paints & Coatings
Saudi Arabia Paints and Coatings Market
Paints & Coatings
Paint Mixing Market
Paints & Coatings
Automotive Coatings Market
Paints & Coatings
Europe Automotive Paints and Coatings Market
Paints & Coatings
Acrylic Paints Market
Paints & Coatings
Iraq Paints and Coatings Market
Paints & Coatings
Middle-East Paints and Coatings Market
Paints & Coatings
Canvas Primer Market
Paints & Coatings
ASEAN Paints and Coatings Market
Paints & Coatings
India Paints and Coatings Market
Paints & Coatings
Insulating Paints and Coatings Market
Paints & Coatings
Paints and Coatings Market