
 Middle-East and Africa Wood Coatings Market | 2026-2036
Middle-East and Africa Wood Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Wood Coatings Market Foresight
Market Context
Saudi Arabia is tilting toward expanded wood coatings capacity as Vision 2030 construction targets multiply. Akzo Nobel N.V. leverages its regional distribution network to serve mega-project contractors across the Gulf. PPG Industries Inc. anchors its position through specialized finishes for high-humidity climates. Jotun competes with marine-grade durability technology adapted for interior wood applications.
Technical Definition and Segment Structure
Middle-East and Africa wood coatings encompass protective and decorative film-forming systems applied to timber substrates, typically comprising resin binders, pigments, solvents or water carriers, and functional additives that confer UV resistance, moisture barrier properties, and aesthetic enhancement for interior and exterior wood surfaces. Water-based polyurethane and acrylic dispersions now displace solvent-borne alkyd systems in commercial furniture finishing across the region due to tightening volatile organic compound limits. Varnishes dominate value capture in the premium architectural segment where deep gloss retention commands price premiums, while UV-curable coatings represent the fastest-growing technology category as Saudi and UAE panel manufacturers install electron-beam and ultraviolet curing lines to accelerate throughput. The contractor end-user channel sustains the largest volume throughput, though DIY enthusiast demand expands through retail hardware chains in South Africa and Nigeria.
Regulatory Framework and Outlook
Saudi Standards, Metrology and Quality Organization (SASO) technical regulations and UAE's Emirates Authority for Standardization and Metrology (ESMA) product conformity schemes determine market access for imported coatings formulations. South Africa's National Regulator for Compulsory Specifications (NRCS) enforces SANS standards limiting hazardous substance content in consumer-grade wood finishes. Stakeholders must monitor evolving Gulf Cooperation Council harmonization of chemical registration requirements and decide whether to localize blending operations or maintain import-dependent supply models.
Market Dynamics
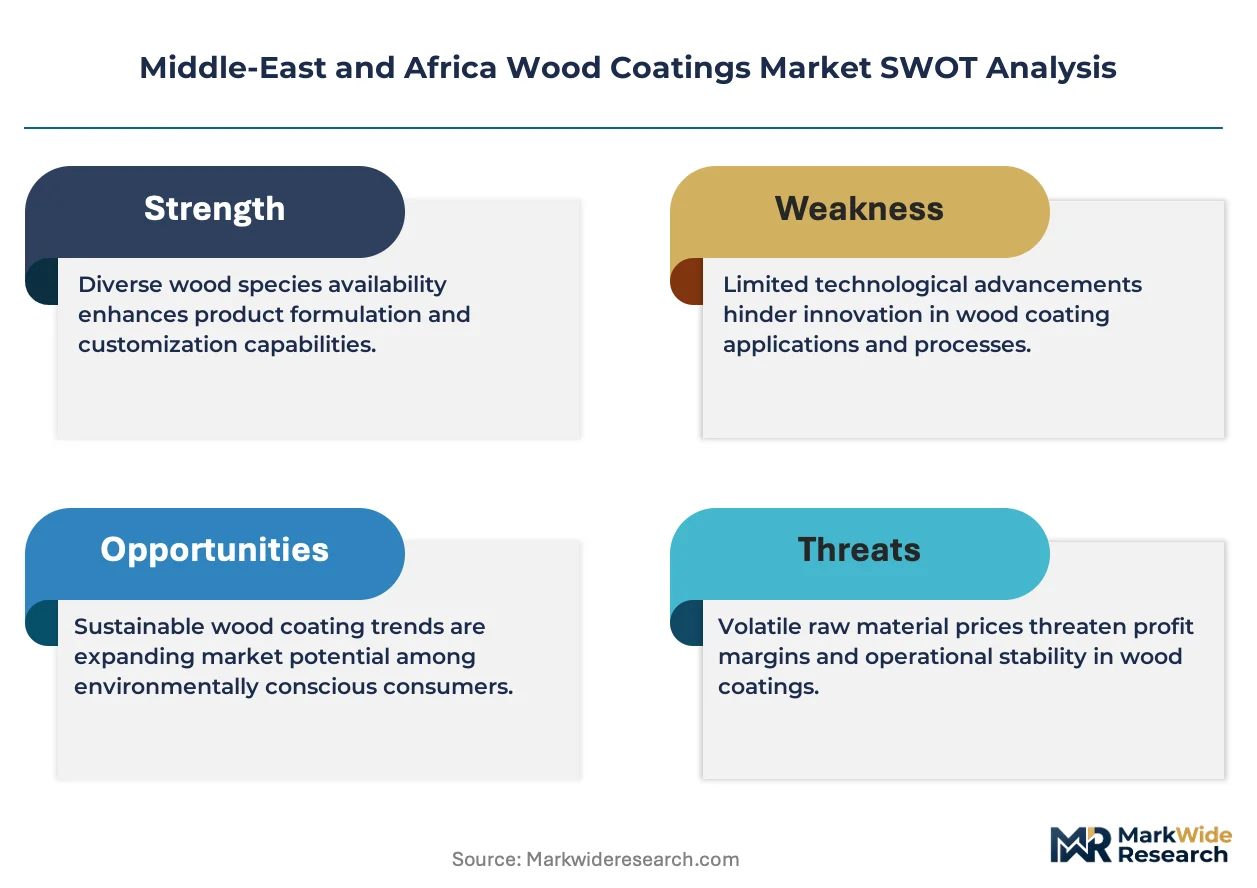
Water-based polyurethane systems are displacing solvent-borne alkyds across Saudi furniture factories as SASO volatile organic compound limits tighten and mega-project contractors demand faster-curing finishes for interior fit-out schedules.
Growth Catalysts
- SASO Technical Regulations:Saudi Arabia's tightening VOC ceilings for architectural coatings force reformulation toward low-emission waterborne systems, accelerating domestic blending capacity investments.
- UAE Green Building Codes:Emirates Authority for Standardization and Metrology mandates for sustainable materials in commercial developments pull premium wood finishes into luxury hospitality fit-outs.
- UV-Curable Technology:Panel manufacturers in Dubai Industrial City install electron-beam curing lines to compress coating-to-shipping cycles from days to hours.
Market Restraints
- Petrochemical Feedstock Volatility:Acrylic resin and isocyanate precursor costs fluctuate with Gulf refinery output, compressing margin predictability for regional formulators.
- Import Concentration Risk:Specialty additives and photoinitiators for UV systems flow through Rotterdam and Singapore transshipment hubs, exposing supply continuity to Red Sea routing disruptions.
- Humidity Performance Ceiling:Water-based systems struggle to match solvent-borne moisture barriers in coastal Saudi and UAE exterior applications without extended drying protocols.
Strategic Opportunities
- Nigeria's Retail Hardware Expansion:DIY enthusiast demand concentrates in Lagos and Abuja retail chains underserved by premium wood finish distribution.
- South Africa SABS Certification:National Regulator for Compulsory Specifications standards for hazardous substance limits create first-mover advantage for compliant importers.
- Digital Color Matching:Spectrophotometer-integrated tinting systems converge with e-commerce platforms to enable contractor-specified custom finishes without batch minimums.
Industry Challenges
- Formulation Chemistry Expertise Gap:Regional technical talent shortages in waterborne resin stabilization and UV photoinitiator selection delay product qualification timelines.
- Dual Certification Burden:Manufacturers serving both Saudi SASO and UAE ESMA conformity schemes face redundant testing costs and incompatible documentation requirements.
- Legacy Equipment Stranding:Solvent-borne spray booths and thermal curing ovens require capital-intensive retrofit or replacement to handle water-based viscosity profiles and UV line speeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Wood Coatings Market |
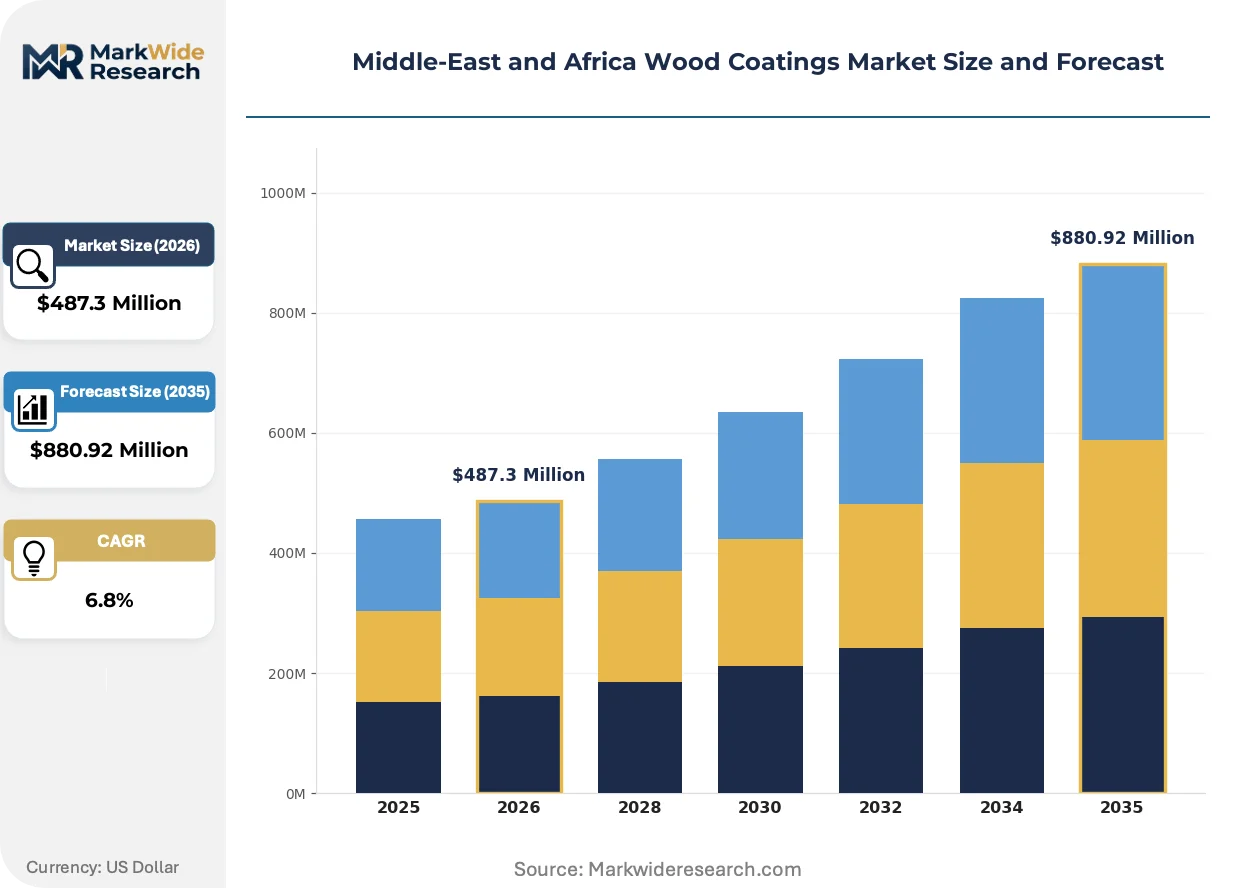
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Varnishes, Stains, Primers, Sealers Application: Furniture, Flooring, Cabinets, Musical Instruments Coating Technology: Solvent-Based, Water-Based, UV-Curable, Powder Coating End User: Manufacturers, Contractors, DIY Enthusiasts, Distributors |
| Companies Covered | Akzo Nobel N.V., PPG Industries Inc., The Sherwin-Williams Company, National Paints Factories Co. Ltd., Jotun, Nippon Paint Holdings Co. Ltd., Kansai Paint Co. Ltd., RPM International Inc., Ritver, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Wood Coatings Market Shifts & Advancements
Coating chemistry, regulatory enforcement mechanisms, and procurement behaviors are simultaneously shifting across the Middle-East and Africa wood finishes landscape. These three movements reshape competitive requirements for formulators and applicators alike.
UV-curable acrylate oligomers deliver instant surface hardness through photopolymerization without thermal energy input. Saudi panel producers adopt these systems to triple throughput on architectural millwork lines. The technology is migrating from European machinery imports to localized blending operations as Dubai-based distributors stock bulk photoinitiators.
UAE's Emirates Authority for Standardization and Metrology now requires third-party conformity assessment for wood coatings in government-contracted projects. Industrial consequence: importers must maintain ESMA-certified testing relationships or forfeit specification eligibility. High-gloss architectural varnishes face the steepest compliance burden as aesthetic performance claims require documented durability validation.
Contractor procurement of wood coatings consolidates toward approved vendor lists managed by mega-project developers. Small-batch custom color requests previously handled through distributor tinting stations now route through centralized specification offices in Riyadh and Dubai. This concentration is most visible in Saudi Vision 2030 hospitality and residential tower developments where single-source coating agreements reduce site-level quality variance.
Middle-East and Africa Wood Coatings Market Segmentation
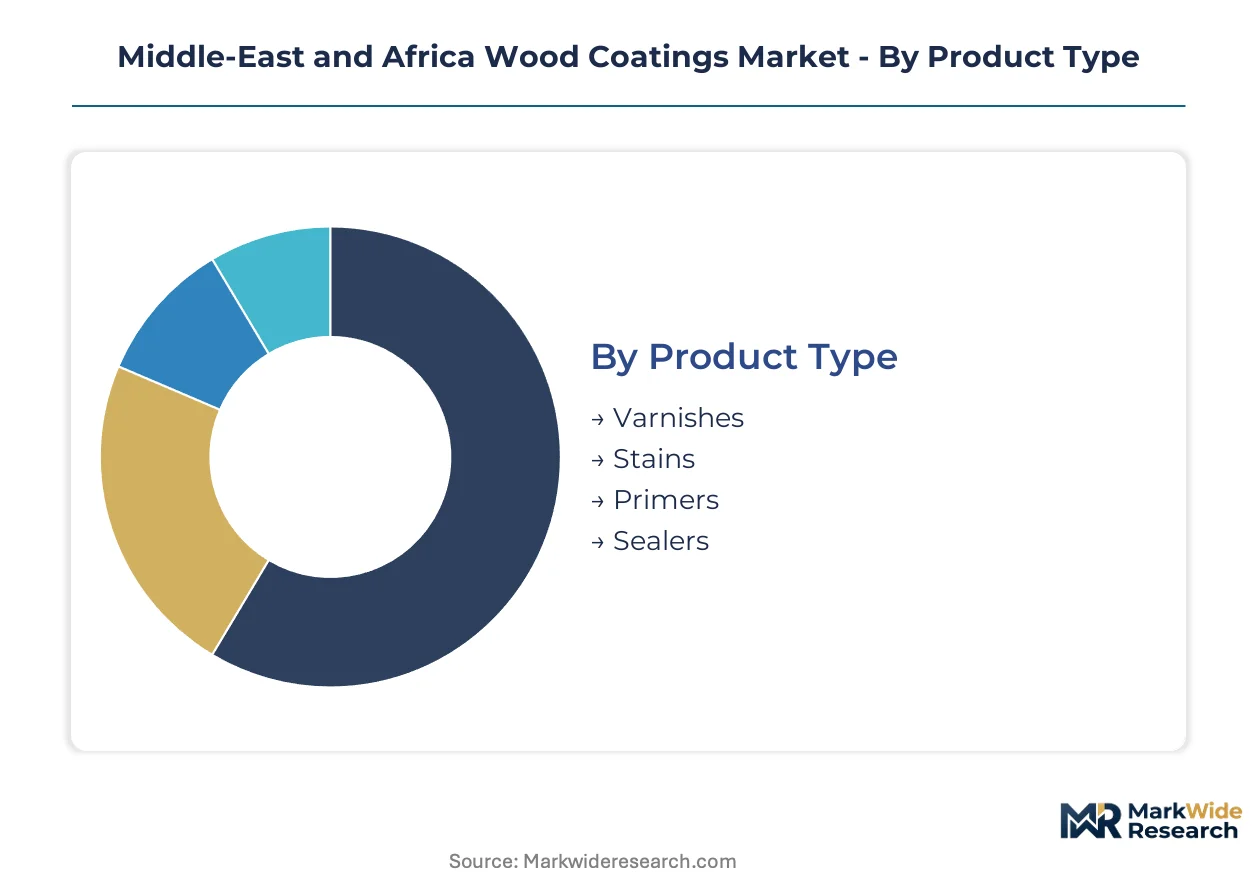
Wood coatings segmentation across the Middle-East and Africa reflects divergent technical requirements between Saudi mega-project contractors and South African retail DIY channels. Understanding these splits enables suppliers to align formulation investments with specific compliance and performance demands.
Product Type:
Cost tier differentiation separates commodity sealers from premium varnishes in regional procurement patterns.
- Varnishes:High-build alkyd and polyurethane film-forming systems deliver deep gloss retention and UV stability for luxury architectural millwork. Demand concentrates in UAE hospitality fit-outs where Emirates Authority for Standardization and Metrology mandates documented durability validation for government-contracted projects.
- Stains:Pigmented penetrating formulations combine colorants with oil or water carriers to enhance timber grain visibility without surface film buildup. Saudi furniture manufacturers specify low-VOC waterborne variants as SASO technical regulations tighten emission ceilings for interior applications.
- Primers:Sealer formulations optimize adhesion between raw timber and topcoats in high-humidity Gulf climates.
- Sealers:Penetrating resin systems provide moisture barrier foundations for exterior decking and cladding in coastal UAE and Saudi installations.
Varnishes hold installed capacity. Stains is rotating up the share rankings.
Application:
Volume concentration tracks construction cycle intensity across Vision 2030 developments and residential retrofit markets.
- Furniture:Factory-applied finishes on residential, office, and hospitality case goods demand rapid-curing systems to match just-in-time delivery schedules. Saudi panel producers in Riyadh and Jeddah install UV-curable lines to compress coating-to-shipping cycles from days to hours.
- Flooring:Abrasion-resistant polyurethane and oil-modified systems protect hardwood and engineered plank surfaces in high-traffic commercial environments. UAE luxury residential towers specify premium two-component waterborne finishes for scratch resistance and low odor during tenant occupancy.
- Cabinets:Kitchen and bath millwork requires moisture-barrier coatings with thermal stability near cooking zones.
- Musical Instruments:Niche nitrocellulose and shellac traditions persist in handcrafted production with minimal regional volume.
Furniture holds installed capacity. Flooring is rotating up the share rankings.
Coating Technology:
Maturity curves separate legacy solvent systems from emerging waterborne and radiation-cure platforms in regional compliance planning.
- Water-Based:Acrylic and polyurethane dispersions displace solvent-borne alkyds as SASO VOC limits tighten and mega-project contractors demand faster-curing finishes for interior fit-out schedules. Dubai-based distributors now stock bulk resin components to support localized blending operations.
- UV-Curable:Acrylate oligomer systems photopolymerize through electron-beam or ultraviolet exposure to deliver instant surface hardness without thermal energy input. Panel manufacturers in Dubai Industrial City adopt these systems to triple throughput on architectural millwork lines.
- Solvent-Based:Traditional alkyd and nitrocellulose systems retain share in exterior applications where humidity performance ceilings constrain waterborne adoption without extended drying protocols.
- Powder Coating:Thermoset epoxy and polyester systems remain marginal for wood substrates due to cure temperature requirements incompatible with timber thermal limits.
Solvent-Based holds installed capacity. UV-Curable is rotating up the share rankings.
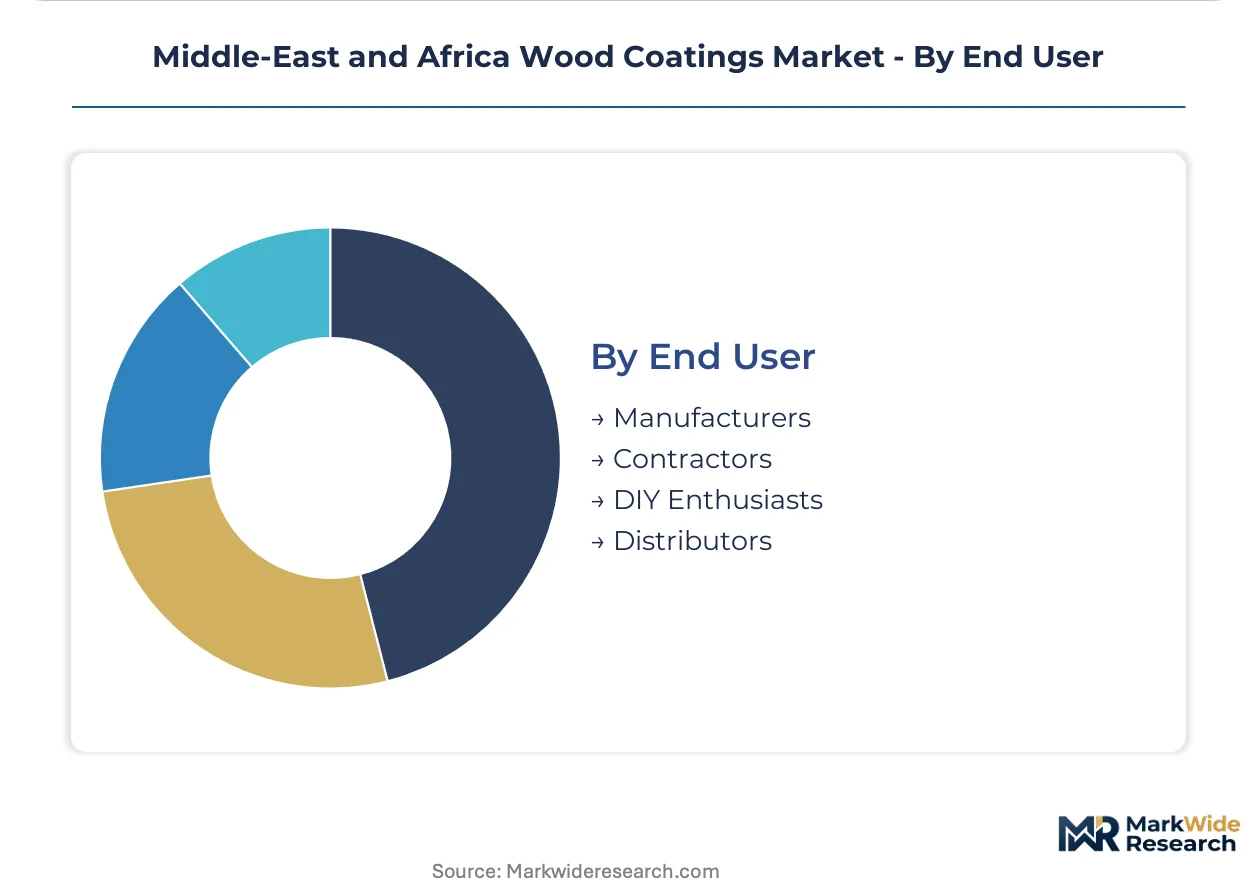
End User:
Customer type determines batch size, specification complexity, and service intensity across the value chain.
- Contractors:Mega-project finishers in Saudi Arabia and UAE consolidate procurement through approved vendor lists managed by Vision 2030 developers. Single-source coating agreements reduce site-level quality variance in hospitality and residential tower developments.
- Manufacturers:Industrial furniture and panel producers in Riyadh, Jeddah, and Dubai Industrial City specify bulk formulations with integrated color matching and technical support.
- DIY Enthusiasts:Lagos and Abuja retail hardware chains drive consumer-grade demand for ready-to-use brush and spray products.
- Distributors:Regional stockists manage inventory and tinting services between formulators and application endpoints.
Contractors holds installed capacity. Manufacturers is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation capacity clusters around Jeddah and Dubai where resin distributors stock bulk polyurethane dispersions and photoinitiators for localized blending. Mega-project contractors in both cities consolidate procurement through approved vendor lists tied to Vision 2030 and UAE green building timelines.
Saudi Arabia
Vision 2030 hospitality and residential tower developments generate concentrated demand for low-VOC interior finishes. SASO technical regulations tighten volatile organic compound ceilings annually, forcing domestic furniture manufacturers toward waterborne system reformulation. Riyadh-based panel producers install UV-curable lines to compress coating-to-shipping cycles from days to hours.
United Arab Emirates
Luxury hospitality fit-outs in Dubai and Abu Dhabi specify premium architectural varnishes with documented durability validation. ESMA mandates third-party conformity assessment for wood coatings in government-contracted projects. Dubai Industrial City anchors regional UV-curable adoption as panel manufacturers triple throughput on architectural millwork lines.
South Africa
Retail hardware chains in Johannesburg and Cape Town drive DIY enthusiast demand for ready-to-use brush and spray products. The National Regulator for Compulsory Specifications enforces SANS standards limiting hazardous substance content in consumer-grade wood finishes. Durban-based distributors manage inventory and tinting services between formulators and application endpoints.
Nigeria
Lagos and Abuja construction activity concentrates demand for contractor-grade sealers and primers in high-humidity coastal applications. The country's national standards body maintains import conformity requirements for architectural coatings. Ikeja industrial zones host emerging furniture manufacturing clusters seeking localized finish supply.
Israel
High-end residential renovation markets in Tel Aviv and Jerusalem sustain niche demand for premium penetrating stains and oil-modified systems. The national standards institute regulates chemical content in interior architectural finishes. Haifa Bay chemical processing infrastructure supports regional resin precursor availability.
Middle-East and Africa Wood Coatings Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in resin and photoinitiator supply. The vendor base separates into three functional layers: multinational coating formulators with regional distribution networks, national blending operations serving mega-project contractors, and specialty chemical distributors managing bulk additive imports. Consolidation pressure intensifies as approved vendor lists shrink specification eligibility. Dominant competitive moves include backward integration into resin blending capacity and strategic partnerships with electron-beam curing equipment suppliers.
Among Netherlands-based multinationals, Akzo Nobel N.V. exemplifies the integrated formulator archetype with regional distribution depth. Pittsburgh-based PPG Industries Inc. occupies a position emphasizing climate-specialized finish development. Norwegian Jotun A/S anchors the durability-focused tier with marine-grade technology adaptation. Together these three represent distinct competitive vectors: network scale, application engineering, and performance heritage.
| Leading Market Players |
|---|
| Akzo Nobel N.V. |
| PPG Industries Inc. |
| The Sherwin-Williams Company |
| National Paints Factories Co. Ltd. |
| Jotun |
| Nippon Paint Holdings Co. Ltd. |
| Kansai Paint Co. Ltd. |
| RPM International Inc. |
| Ritver |
| Others |
Supply & Pricing Matrix
Jeddah's resin blending capacity expansion anchors regional pricing power as Saudi furniture manufacturers negotiate volume contracts against UAE import-dependent distributors. SASO compliance costs and Rotterdam transshipment premiums feed into a three-tier pricing structure across premium, standard, and economy levels.
Pricing Analysis
SASO technical regulations dictate the pricing tier structure across the Middle-East and Africa wood coatings market. Premium architectural varnishes with ESMA-certified durability validation command substantial markups over commodity sealers lacking third-party conformity assessment. Price differentiation hinges on certification grade and volume scale, with mega-project contractors securing favorable terms through single-source agreements. Cost compression in the standard tier is intensifying because petrochemical feedstock volatility erodes margin predictability for regional formulators. DIY enthusiasts in Lagos retail chains exhibit highest price sensitivity, while Saudi Vision 2030 hospitality developers prioritize performance validation over unit cost.
Supply Chain Analysis
Red Sea routing disruptions between Rotterdam and Jeddah dominate supply chain risk exposure for specialty additives and photoinitiators. Manufacturing concentration rests on Germany, the Netherlands, and Saudi Arabia for resin precursors, with Singapore serving as secondary transshipment hub for UV-curable components. Raw material dependencies center on acrylic monomers, isocyanate precursors, and photoinitiator packages. Single-source vulnerability from Rotterdam-Jeddah corridors threatens supply continuity during regional instability. Distribution runs through Dubai-based bulk distributors stocking localized blending inputs for Riyadh and Jeddah panel producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water-based polyurethane systems threaten solvent-borne alkyd incumbents as SASO VOC ceilings tighten annually, forcing established suppliers to defend formulation portfolios against substitution.
For Market Incumbents: Insulate core revenue streams by securing backward integration into Jeddah resin blending capacity and accelerating ESMA certification investments for premium varnish lines. Solvent-borne equipment stranding poses existential risk to legacy thermal curing operations unable to handle water-based viscosity profiles.
For New Entrants and Emerging Players: Pursue Nigeria's retail hardware expansion in Lagos and Abuja chains underserved by premium wood finish distribution. The DIY enthusiast segment offers lowest competitive density, with digital color matching platforms enabling market entry without batch minimum commitments.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory arbitrage play because Gulf Cooperation Council harmonization of chemical registration requirements will reward localized blending operations over import-dependent models. Target regional distributors with captive ESMA-certified testing relationships. The signal to watch is SASO-VOC alignment speed with EU REACH standards.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Blending | Jeddah-based polyurethane dispersion capacity reduces Rotterdam transshipment exposure for Saudi panel producers. |
| ESMA Certification Investment | Third-party conformity assessment unlocks specification eligibility for UAE government-contracted hospitality fit-outs. |
| UV-Curable Line Installation | Dubai Industrial City electron-beam curing adoption triples architectural millwork throughput without thermal energy input. |
| Digital Color Matching Platform | Spectrophotometer-integrated tinting converges with e-commerce to serve contractor-specified custom finishes. |
| Nigeria Distribution Partnership | Lagos and Abuja retail hardware chains capture DIY enthusiast demand absent premium wood finish supply. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with coating formulators, mega-project procurement managers, and Dubai-based resin distributors; and secondary validation through SASO technical regulation filings, ESMA conformity assessment records, and customs trade data for acrylic resin imports. Plant managers at Riyadh panel producers and technical R&D directors at UAE blending operations provided formulation transition timelines. Bottom-up volume builds from contractor vendor lists triangulated against top-down petrochemical feedstock consumption patterns.
Forecast inputs span water-based technology penetration curves, UV-curable line installation rates, and SASO regulatory enforcement intensity across the projection horizon. Segmentation dimensions modeled include coating technology maturity, end-user procurement concentration, and regional compliance cluster. CAGRs derive from installed capacity expansion schedules and substitution elasticity between solvent-borne and waterborne systems. Feedstock cost volatility and Red Sea logistics risk factor explicitly into margin compression scenarios.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese resin exporters or European UV-equipment suppliers would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Acrylic Paints Market
Paints & Coatings
Global Construction Paints and Coatings Market
Paints & Coatings
Paint and Coating Stripper Market
Paints & Coatings
Europe Architectural Coatings Market
Paints & Coatings
North America Paints and Coatings Market
Paints & Coatings
Road Marking Paint Market
Paints & Coatings
Water Color Market
Paints & Coatings
Paint Defoamers Market
Paints & Coatings
Automotive Paints and Coatings Market
Paints & Coatings
Automotive Coatings Market
Paints & Coatings
Bituminous Paints Market
Paints & Coatings
GCC Paints and Coatings Market
Paints & Coatings
United Arab Emirates (UAE) Paints and Coatings Market
Paints & Coatings
Nano Paints and Coatings Market
Paints & Coatings
Asia-Pacific Paint Thinner Market
Paints & Coatings
Iran Paints and Coatings Market