
 North America Construction Adhesives Market | 2026-2036
North America Construction Adhesives Market Size, Share, and Industry Trends Forecast 2026-2036
North America Construction Adhesives Market Analytics
The US EPA low-VOC adhesive standards is realigning procurement criteria across commercial construction. H.B. Fuller Company leverages its water-based polymer portfolio to capture specification-driven contracts. Henkel AG anchors its position through direct distributor relationships with national homebuilders. Sika AG dominates the infrastructure channel with cementitious hybrid systems for bridge and tunnel applications.
Construction adhesives are formulated bonding agents that cure through chemical reaction, moisture activation, or solvent evaporation to join structural and non-structural building materials; typical formulations achieve shear strengths from 1,000 to 4,000 psi and operate across temperature ranges of minus 40 to 300 degrees Fahrenheit, serving primary functions in load distribution, sealing, and substrate compatibility within residential, commercial, and civil engineering assemblies. Polyurethane adhesives lead the product type landscape due to their flexibility and moisture-cure versatility across climate zones, while epoxy systems command premium positioning in structural anchoring and composite bonding where tensile performance dictates specification. The residential end user segment generates the highest volume throughput, though infrastructure projects yield superior margin pools through performance-grade certification requirements and extended warranty terms.
The US EPA regulates volatile organic compound emissions under 40 CFR Part 59, while OSHA sets workplace exposure limits for isocyanates and solvent vapors in adhesive manufacturing and application environments. Canada's PMRA oversees biocide preservation claims in fungicidal adhesive formulations, creating dual-compliance obligations for cross-border suppliers. Stakeholders must monitor evolving state-level amendments to California's CARB standards and emerging federal procurement preferences for bio-based content certification.
Market Dynamics
The US EPA 40 CFR Part 59 low-VOC mandate is forcing wholesale reformulation across solvent-based adhesive portfolios, compressing product development cycles while opening specification windows for water-based and moisture-cure alternatives in commercial and residential channels.
Growth Catalysts
- Modular housing expansion:Factory-built residential units in Texas and California megaprojects are specifying polyurethane adhesives for structural panel bonding, creating volume pull-through for moisture-cure systems.
- 40 CFR Part 59 compliance:The EPA's volatile organic compound emission limits are disqualifying legacy solvent formulations from federal and state procurement contracts, redirecting specification authority toward compliant alternatives.
- Infrastructure warranty terms:Bridge and tunnel applications with extended performance guarantees are cementing demand for cementitious hybrid systems that meet certification-driven durability thresholds.
Market Restraints
- Isocyanate input volatility:Polyurethane feedstock costs fluctuate with crude-derived MDI and TDI pricing, compressing margin predictability for moisture-cure formulation specialists.
- Canadian dual-compliance burden:Cross-border suppliers face PMRA biocide preservation oversight alongside EPA requirements, lengthening registration timelines for fungicidal adhesive lines.
- Epoxy substitution ceiling:Structural anchoring applications above 4,000 psi shear requirements remain locked into epoxy systems, limiting polyurethane penetration in high-load civil engineering.
Strategic Opportunities
- CARB amendment anticipation:California's evolving state-level VOC standards are creating first-mover advantage for suppliers pre-positioning ultra-low-emission formulations ahead of federal adoption.
- Texas Gulf Coast petrochemical integration:Proximity to upstream polymer feedstock clusters enables backward integration opportunities for adhesive manufacturers seeking captive MDI supply security.
- Bio-based certification alignment:Emerging federal procurement preferences for renewable content are opening specification pathways for soy- and lignin-derived binder systems in institutional construction.
Industry Challenges
- Formulation chemist scarcity:The specialized expertise required to balance VOC compliance with cure-speed performance in hybrid systems is concentrating among a narrow talent pool, inflating R&D compensation costs.
- OSHA isocyanate exposure protocols:Workplace vapor monitoring and respiratory protection mandates are adding operational complexity to manufacturing facilities and field application environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Construction Adhesives Market |
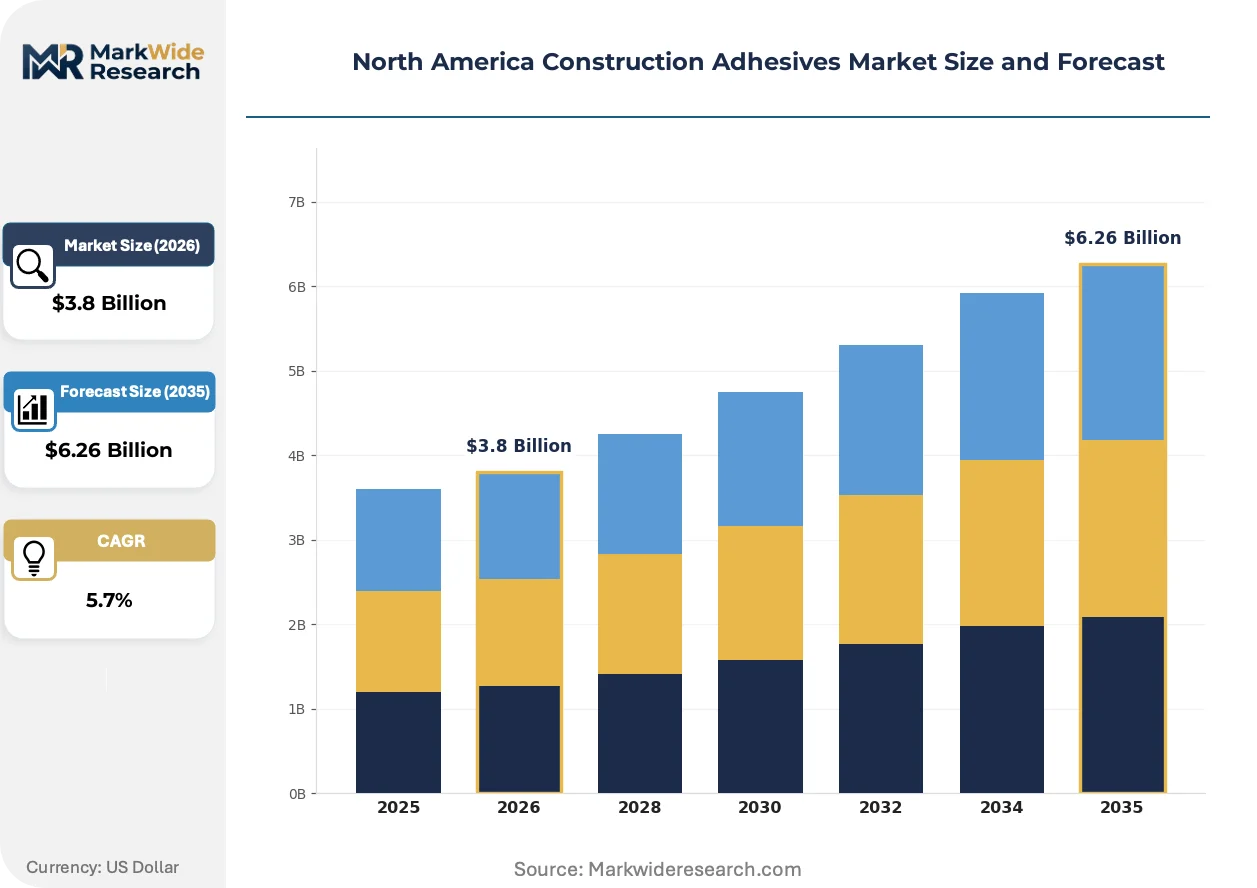
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Epoxy, Acrylic, Silicone Application: Woodworking, Construction, Automotive, Aerospace End User: Residential, Commercial, Industrial, Infrastructure Distribution Channel: Retail, Online, Wholesalers, Direct Sales |
| Companies Covered | 3M, Henkel AG, Sika AG, H.B. Fuller Company, Dow, Arkema Group, Avery Dennison Corporation, RPM International, Huntsman International LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Construction Adhesives Market Evolving Landscape
Adhesive platforms are fragmenting across performance tiers as specification authority migrates from general contractors to certified installers, while regulatory compliance becomes a technical differentiator rather than a baseline requirement.
Moisture-activated polyurethane systems with ambient-temperature cure capability are decentralizing application control from climate-controlled factory environments to field-based installation crews. Residential builders in Texas and California are adopting these systems for on-site modular panel bonding, reducing dependency on fixed production facilities. The technology is decentralizing supply chain power toward distributor networks capable of technical field support.
The US EPA 40 CFR Part 59 framework is tightening volatile organic compound thresholds for architectural coatings and adhesives, eliminating solvent-based products from federal procurement eligibility. Commercial construction specifications are pivoting toward water-based polymer alternatives that meet sub-100 g/L VOC limits. California CARB standards are extending these requirements to state-level contracts, forcing reformulation investments across North American manufacturing footprints.
Certification-driven procurement is displacing price-first buying patterns in institutional and infrastructure segments. State transportation departments and federal agencies are embedding performance-grade adhesive specifications into bid requirements, filtering supplier pools by warranty-backed durability data. Texas Department of Transportation and California DOT projects are prioritizing pre-qualified material lists over open competitive bidding for structural bonding applications.
North America Construction Adhesives Market Segmentation
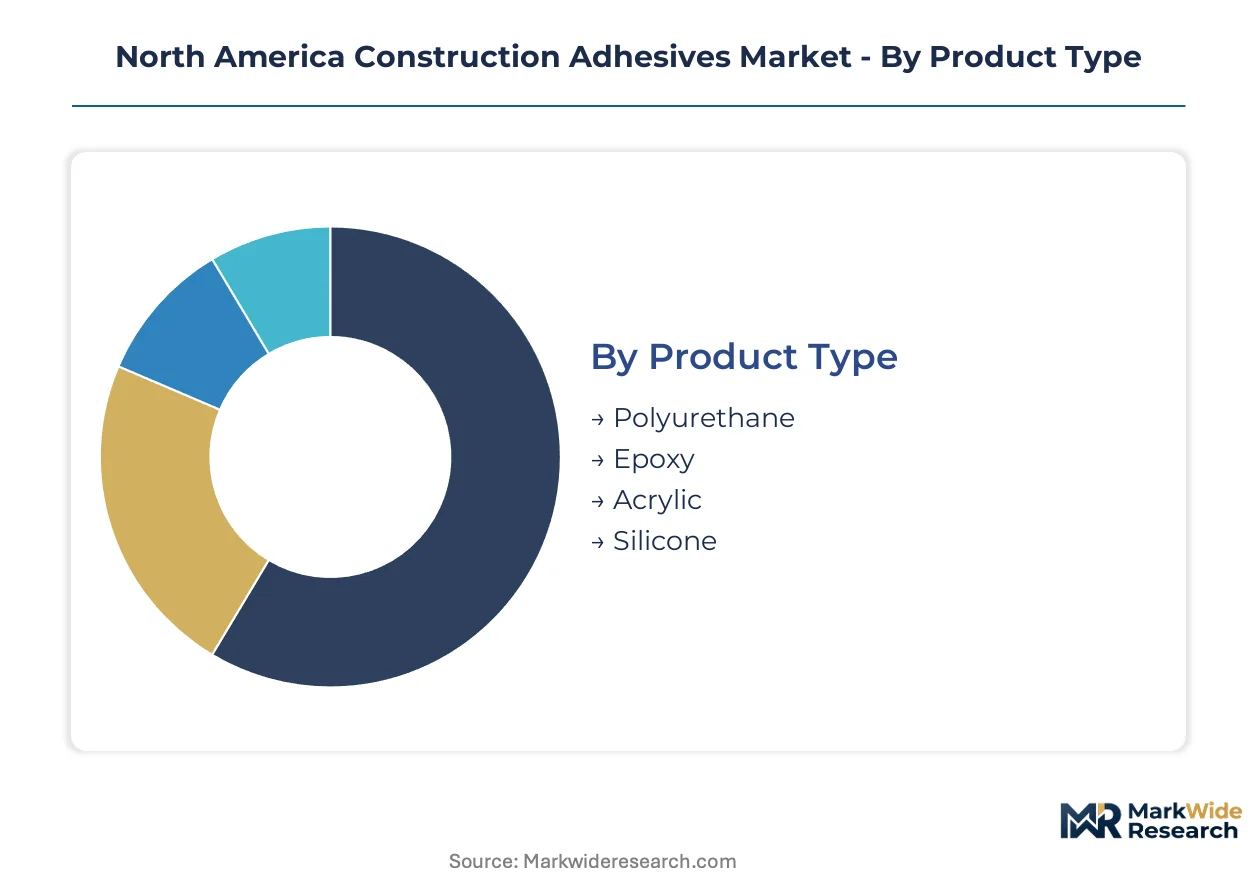
Construction adhesive segmentation in North America reflects divergent technical requirements across load-bearing and non-structural applications. Specification authority varies sharply by end-use, with infrastructure and commercial channels demanding certified performance while residential markets prioritize cost efficiency and application speed.
Product Type:
Polyurethane and epoxy formulations function as standalone structural systems, while acrylic and silicone chemistries typically embed within broader assembly specifications.
- Polyurethane:Moisture-cure systems achieve shear strengths between 1,000 and 4,000 psi with ambient-temperature cure capability. Factory-built residential units in Texas and California megaprojects specify these adhesives for structural panel bonding, driven by modular housing expansion and field-installation flexibility.
- Epoxy:Two-part thermosetting systems command premium positioning in structural anchoring and composite bonding applications. Bridge and tunnel projects with extended warranty terms cement demand for these systems, though shear requirements above 4,000 psi limit substitution by alternative chemistries.
- Acrylic:Water-based and solvent-borne formulations serve interior finishing and trim applications with rapid skinning properties.
- Silicone:Neutral-cure and acetoxy systems dominate joint sealing and weatherproofing where movement accommodation exceeds structural load requirements.
Polyurethane leads volumes today; epoxy is gaining share fastest in specification-driven infrastructure channels.
Application:
Volume concentration tilts toward field-installed building assemblies, with factory-applied bonding representing a smaller but higher-margin tier.
- Construction:Structural panel bonding, curtain wall attachment, and flooring underlayment represent the dominant demand pool. The US EPA 40 CFR Part 59 low-VOC mandate is disqualifying legacy solvent formulations from federal procurement, redirecting specification toward compliant water-based and moisture-cure alternatives.
- Woodworking:Engineered wood products and mass timber assemblies require adhesives with creep resistance and moisture durability. Cross-laminated timber manufacturing in the Pacific Northwest and Southeastern US is pulling through specialized polyurethane formulations for lamination lines.
- Automotive:Lightweighting initiatives in electric vehicle platforms specify structural adhesives for multi-material bonding.
- Aerospace:Composite primary structure bonding demands traceable cure profiles and out-time tolerance.
Construction absorbs the highest absolute volumes; woodworking is expanding most quickly behind mass timber code adoption.
End User:
Margin structures invert across the end-user spectrum, with infrastructure and industrial segments capturing premium pricing against residential volume throughput.
- Residential:Single-family and multifamily construction generates the highest volume throughput through distributor and retail channels. National homebuilders in Texas and California are standardizing polyurethane adhesive specifications for modular panel systems, consolidating procurement around moisture-cure platforms.
- Infrastructure:State transportation departments and federal agencies embed performance-grade specifications into bid requirements. Texas Department of Transportation and California DOT projects prioritize pre-qualified material lists over open competitive bidding for structural bonding applications.
- Commercial:Office, retail, and institutional construction faces compressed product development cycles as 40 CFR Part 59 compliance windows narrow.
- Industrial:Manufacturing facility construction and equipment anchoring require specialized formulations for chemical resistance and dynamic loading.
Residential leads absolute volumes; infrastructure commands the steepest margin premiums through certification requirements.
Distribution Channel:
Channel power is fragmenting as specification authority migrates from general contractors to certified installers and technical distributor networks.
- Wholesalers:Regional and national distributors with field technical support capabilities are capturing specification influence in commercial and infrastructure channels. Direct relationships with national homebuilders anchor volume security for moisture-cure polyurethane lines.
- Direct Sales:Large-scale infrastructure and industrial projects with performance-grade certification requirements bypass distribution intermediaries. Cementitious hybrid systems for bridge and tunnel applications typically flow through manufacturer-direct channels with embedded warranty terms.
- Retail:Big-box and specialty building material outlets serve residential repair, renovation, and small-scale new construction.
- Online:E-commerce platforms capture specification-grade product sales with technical documentation and batch traceability.
Wholesalers dominate residential and commercial volumes; direct sales is climbing fastest in infrastructure procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Construction adhesive manufacturing in North America traces its industrial lineage to post-war chemical expansion along the US Gulf Coast, where petrochemical feedstock access enabled polyurethane and epoxy formulation scale. Canadian production developed through Ontario-based automotive supplier networks, while Mexican capacity concentrated around border maquiladoras serving cross-border assembly operations.
United States
Texas and California megaprojects are driving polyurethane specification for modular housing panel bonding. The US EPA 40 CFR Part 59 low-VOC mandate is disqualifying legacy solvent formulations from federal procurement contracts. Houston's petrochemical corridor provides captive MDI feedstock access for moisture-cure adhesive manufacturers.
Canada
Cross-laminated timber manufacturing in British Columbia and engineered wood production in Quebec are pulling specialized polyurethane formulations for lamination lines. Health Canada's PMRA oversees biocide preservation claims, creating dual-compliance obligations alongside EPA requirements. Ontario's automotive supplier heritage anchors industrial adhesive formulation expertise.
Mexico
Border state maquiladoras in Nuevo León and Tamaulipas specify construction adhesives for assembly facility construction and equipment anchoring. Mexican environmental regulations under SEMARNAT are tightening VOC thresholds for imported formulations. Mexico City Metro's infrastructure expansion is cementing demand for cementitious hybrid systems in tunnel applications.
North America Construction Adhesives Market Competitive Landscape
Capital-heavy producers with captive petrochemical feedstock compete with asset-light formulators sourcing specialty polymers through distributor networks. The market structure tilts toward consolidation at the formulation level, with mid-tier specialists occupying niche certification channels. Three archetypes dominate: integrated chemical conglomerates with backward polymer control, pure-play adhesive specialists with specification authority, and diversified industrials leveraging construction cross-selling. Competitive moves center on CARB pre-positioning for California regulatory windows and distributor technical support capacity expansion.
Among Swiss and German chemical conglomerates, Sika AG and Henkel AG exemplify the specification-driven archetype through direct relationships with national homebuilders and infrastructure agencies. H.B. Fuller Company represents the pure-play specialist model with water-based polymer portfolio positioning for EPA compliance windows.
| Leading Market Players |
|---|
| 3M |
| Henkel AG |
| Sika AG |
| H.B. Fuller Company |
| Dow |
| Arkema Group |
| Avery Dennison Corporation |
| RPM International |
| Huntsman International LLC |
| Others |
Value Network & Pricing Analysis
EPA 40 CFR Part 59 low-VOC procurement mandates are forcing adhesive buyers toward certified water-based and moisture-cure formulations, compelling suppliers to absorb reformulation costs while passing compliance premiums through to specification-driven infrastructure channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates warranty-backed infrastructure grades from residential volume products and commodity retail lines. Price differentiation rests on certification tier and volume scale, with Texas DOT pre-qualified materials commanding substantial premiums over uncertified alternatives. Cost compression in standard-tier residential channels is intensifying because national homebuilders are consolidating procurement around moisture-cure polyurethane platforms. Residential repair and renovation buyers exhibit highest price sensitivity; infrastructure agencies with extended warranty requirements show least.
Supply Chain Analysis
Specialized formulation chemist shortages in the US Gulf Coast and Ontario manufacturing corridors are constraining R&D throughput for hybrid system development. Supply concentrates in the United States, Canada, and Mexico, with production anchored in Houston's petrochemical corridor, Ontario's automotive supplier networks, and Nuevo León border maquiladoras. Feedstock draws from crude-derived MDI and TDI streams, bio-based soy and lignin sources, and cementitious additive imports. Single-source vulnerability runs through concentrated MDI supplier networks. Distribution runs through technical-capable wholesalers for commercial and infrastructure channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Construction Adhesives Market functions as a regulatory compounder where EPA 40 CFR Part 59 compliance windows continuously reshape procurement eligibility and specification authority.
For Market Incumbents: Deepen captive MDI supply security through Texas Gulf Coast petrochemical integration to offset isocyanate input volatility threatening margin predictability. Expand field technical support capacity within distributor networks to capture specification influence migrating from general contractors toward certified installers. Prioritize CARB pre-positioning investments ahead of California state-level VOC amendments. For New Entrants and Emerging Players: E-commerce platforms with embedded technical documentation and batch traceability offer the most penetrable route for specification-grade product sales bypassing established wholesaler relationships. Target woodworking applications behind mass timber code adoption in the Pacific Northwest and Southeastern US where specialized polyurethane formulation demand outpaces incumbent capacity. Pursue direct relationships with regional cross-laminated timber manufacturers as entry wedge. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play adhesive specialists possessing EPA-compliant water-based portfolios and infrastructure certification authority. Long-term viability over the analysis window favors manufacturers with backward integration into polymer feedstock and established DOT pre-qualification status. Watch for CARB amendment finalization as inflection signal accelerating consolidation around ultra-low-emission formulation leaders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MDI Feedstock | Houston petrochemical corridor proximity secures captive supply against isocyanate price volatility. |
| CARB Pre-Positioning Investment | Ultra-low-emission formulation readiness captures first-mover advantage ahead of federal adoption. |
| Distributor Technical Support Expansion | Field-capable networks capture specification authority migrating from general contractors. |
| Mass Timber Formulation Development | Cross-laminated timber code adoption in Pacific Northwest and Southeast creates specialized demand pool. |
| Infrastructure Certification Investment | Texas DOT and California DOT pre-qualification unlocks warranty-backed premium pricing tiers. |
Research Methodology
Multiple input streams — primary interviews with adhesive formulators, distributor technical directors, and state DOT materials engineers, alongside secondary validation through EPA regulatory filings, ACC industry reports, and SEC 10-K disclosures — were reconciled through bottom-up and top-down triangulation to construct market estimates.
Data-stream reconciliation across the projection horizon applied segmentation dimensions spanning product chemistry, application channel, end-user vertical, and regional regulatory cluster. CAGRs were derived from modeled volume trajectories calibrated against historical procurement patterns and compliance-driven specification shifts. Forecast inputs incorporated MDI feedstock pricing volatility assumptions and modular housing construction permits.
The model assumes a particular technology adoption path; alternative pathways for moisture-activated ambient-cure systems would alter the outlook if field-installation reliability diverges from factory-controlled benchmarks. Forecasts embed assumptions regarding EPA enforcement continuity and state-level CARB harmonization timing. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Waterproofing Admixture Market
Adhesives & Sealants
Tobacco and Cigarette Adhesives Market
Adhesives & Sealants
Adhesive Resin Market
Adhesives & Sealants
UV Cured Adhesives Market
Adhesives & Sealants
Windscreen Adhesive Market
Adhesives & Sealants
Asia-Pacific Reactive Adhesives Market
Adhesives & Sealants
Global MS Polymer Adhesives Market
Adhesives & Sealants
Timber Laminating Adhesives Market
Adhesives & Sealants
Global Anti-Tack Agents Market
Adhesives & Sealants
Rubber-Based Adhesives Market
Adhesives & Sealants
Asia-Pacific Waterborne Adhesives Market
Adhesives & Sealants
Reactive Adhesives Market
Adhesives & Sealants
Spray Glue Market
Adhesives & Sealants
Germany Sealants Market
Adhesives & Sealants
Light Curing Adhesives Market
Adhesives & Sealants
Urea Formaldehyde Concrete Market