
 Asia-Pacific Pressure Sensitive Adhesives (PSA) Market | 2026-2036
Asia-Pacific Pressure Sensitive Adhesives (PSA) Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Pressure Sensitive Adhesives (PSA) Market Outlook
Multi-source procurement for key raw materials is realigning supply strategies across the Asia-Pacific PSA value chain. Henkel AG & Co. KGaA leverages its acrylic formulation expertise to dominate electronics bonding applications in East Asia. 3M sustains technology leadership in medical-grade adhesive tapes through intensive R&D spending. Nitto Denko Corporation anchors regional production capacity with extensive manufacturing footprints across Japan and Southeast Asia.
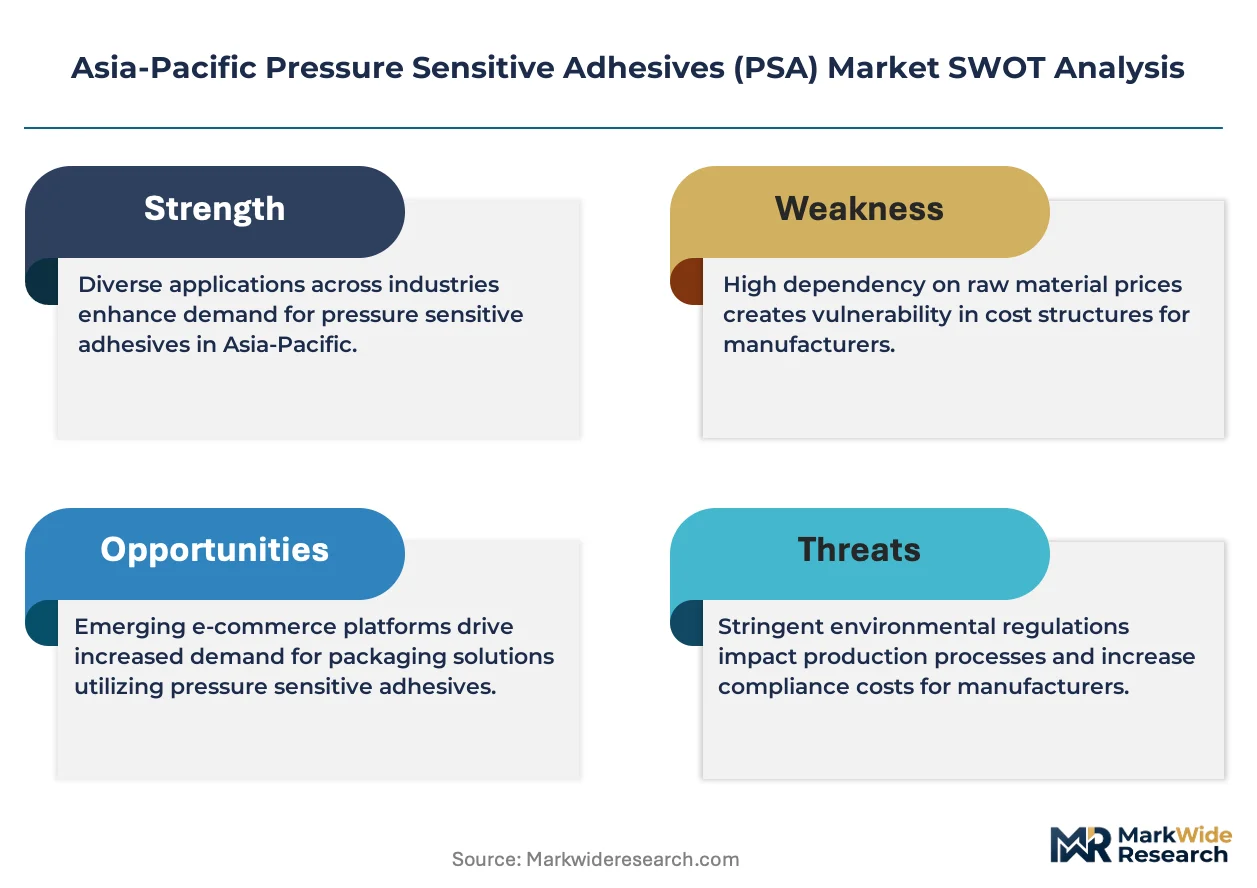
Pressure sensitive adhesives are materials that bond to surfaces upon application of light pressure without solvent activation or heat curing, typically formulated with tackifying resins, elastomers, and plasticizers in viscoelastic compositions that achieve immediate wet-out and peel adhesion measured in Newtons per 25 millimeters. These adhesives serve primary industrial functions in temporary holding, permanent assembly, surface protection, and information labeling across automated manufacturing environments. Water-based acrylic formulations command the largest volume share due to favorable environmental profiles and compatibility with paper label substrates, while hot melt systems represent the fastest-expanding category as packaging converters seek elimination of drying energy and VOC emissions. Solvent-based rubber systems retain niche dominance in heavy-duty tape applications where aggressive tack and shear resistance justify higher regulatory compliance costs.
China's Ministry of Ecology and Environment enforces progressively stringent VOC emission limits that directly constrain solvent-based PSA production volumes and compel reformulation investments. Japan's METI oversees chemical substance reporting under CSCL frameworks that affect silicone and polyurethane raw material sourcing transparency for regional manufacturers. India's BIS certification requirements for adhesive products used in food packaging and medical applications create incremental market access barriers for imported formulations. Stakeholders must monitor evolving substance restriction lists across these jurisdictions to anticipate reformulation timelines and secure first-mover positioning in compliant adhesive platforms.
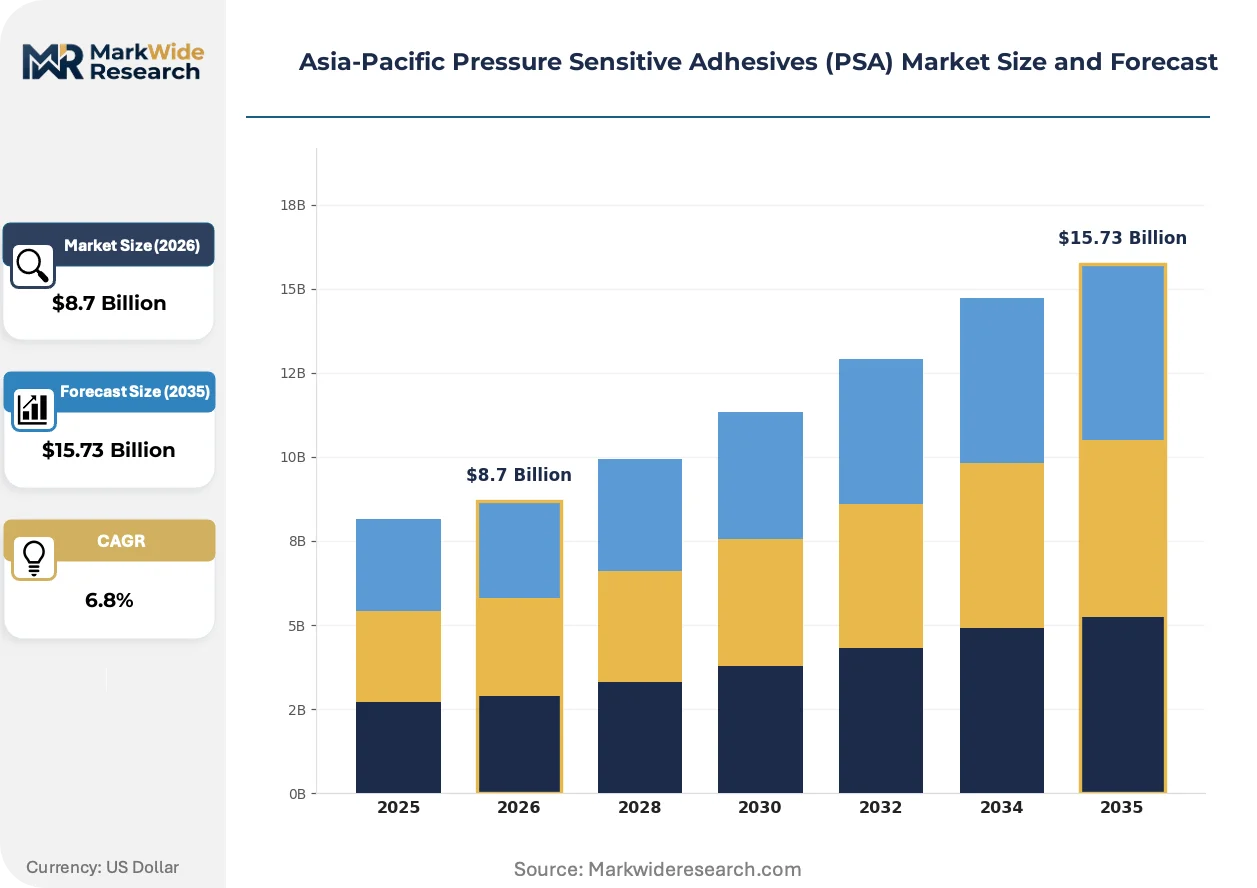
Market Dynamics
China's MEE emission standards are forcing wholesale formulation shifts from solvent-based to water-based and hot-melt PSA systems, compressing margins for legacy producers while rewarding early movers in compliant chemistries.
Growth Catalysts
- MEE VOC Limits:China's tightening volatile organic compound standards under Ministry of Ecology and Environment oversight are accelerating solvent-to-water formulation conversions across adhesive manufacturing clusters.
- Flexible Display Bonding:Electronics assemblers in South Korea and Taiwan are expanding acrylic PSA consumption for foldable smartphone and tablet display lamination.
- Semiconductor Packaging:Die-attach films and thermal interface materials utilizing silicone and modified acrylic PSAs are gaining traction in advanced packaging operations.
Market Restraints
- Petrochemical Feedstock Volatility:Acrylic monomer and tackifying resin prices fluctuate with naphtha and propylene markets, squeezing formulation margins unpredictably.
- Japanese Silicone Concentration:Regional dependence on Shin-Etsu and Dow silicone raw materials creates supply vulnerability for high-performance PSA segments.
- Hot-Melt Temperature Limitations:Polyolefin and EVA-based hot-melt PSAs exhibit reduced shear resistance above 60°C, restricting automotive underhood applications.
Strategic Opportunities
- Vietnam Electronics Manufacturing:Samsung and Apple supplier relocations to Bac Ninh and Hai Phong industrial zones are creating greenfield PSA demand for device assembly.
- India Medical Device Packaging:CDSCO regulatory harmonization with EU MDR standards is opening certified medical-grade tape markets previously dominated by imports.
- UV-Curable Formulations:Convergence of photoinitiator chemistry with PSA viscoelastic design enables instant curing for electronics precision bonding without thermal damage.
Industry Challenges
- Formulation Chemist Scarcity:Shortage of specialists trained in rheology, polymer synthesis, and regulatory compliance slows product development cycles across the region.
- Reformulation Capital Burden:Shifting solvent-based lines to water-based or hot-melt systems requires reactor modifications, drying equipment, and emissions controls exceeding $5 million per facility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Pressure Sensitive Adhesives (PSA) Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, Hot Melt, Rubber-Based End Use Industry: Automotive, Packaging, Electronics, Construction Formulation: Acrylic, Silicone, Polyurethane, Ethylene Vinyl Acetate Application: Labels, Tapes, Surface Protection, Medical |
| Companies Covered | 3M, Arkema Group, H.B. Fuller Company, Dow, Henkel AG & Co. KGaA, Avery Dennison Corporation, Nitto Denko Corporation, Pidilite Industries Ltd., Sika AG, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Pressure Sensitive Adhesives (PSA) Market Strategic Shifts
Active chemistry redesign and manufacturing process intensification are compressing development cycles while expanding application boundaries for pressure-sensitive adhesives across Asia-Pacific industrial verticals.
UV-LED curable PSA technology is absorbing development resources from major Japanese and Korean suppliers seeking elimination of thermal ovens in electronics assembly lines. Display manufacturers in Taiwan are piloting these systems for OLED panel bonding where heat-sensitive substrates dominate. The technology is absorbing market share from conventional thermal-cure silicones in premium electronics segments by reducing cure energy and floor space requirements.
China's GB standards for adhesive VOC content are tightening measurement protocols and maximum thresholds for formaldehyde, benzene, and toluene emissions in consumer goods applications. Manufacturers in Jiangsu and Guangdong provinces face mandatory third-party testing and labeling requirements effective across domestic and export production. Water-based acrylic suppliers are capturing volume from solvent-based rubber competitors in packaging and labeling segments where brand owners demand supply chain transparency.
Direct mill procurement of acrylic monomers and tackifying resins is displacing traditional distributor relationships among mid-sized PSA converters in India and Southeast Asia. Large packaging houses in Maharashtra and Tamil Nadu are negotiating backward integration into emulsion polymerization to secure margin control and formulation customization. This pattern concentrates most visibly in India's western and southern states where food and pharmaceutical labeling demand is outpacing adhesive supply infrastructure.
Asia-Pacific Pressure Sensitive Adhesives (PSA) Market Segmentation
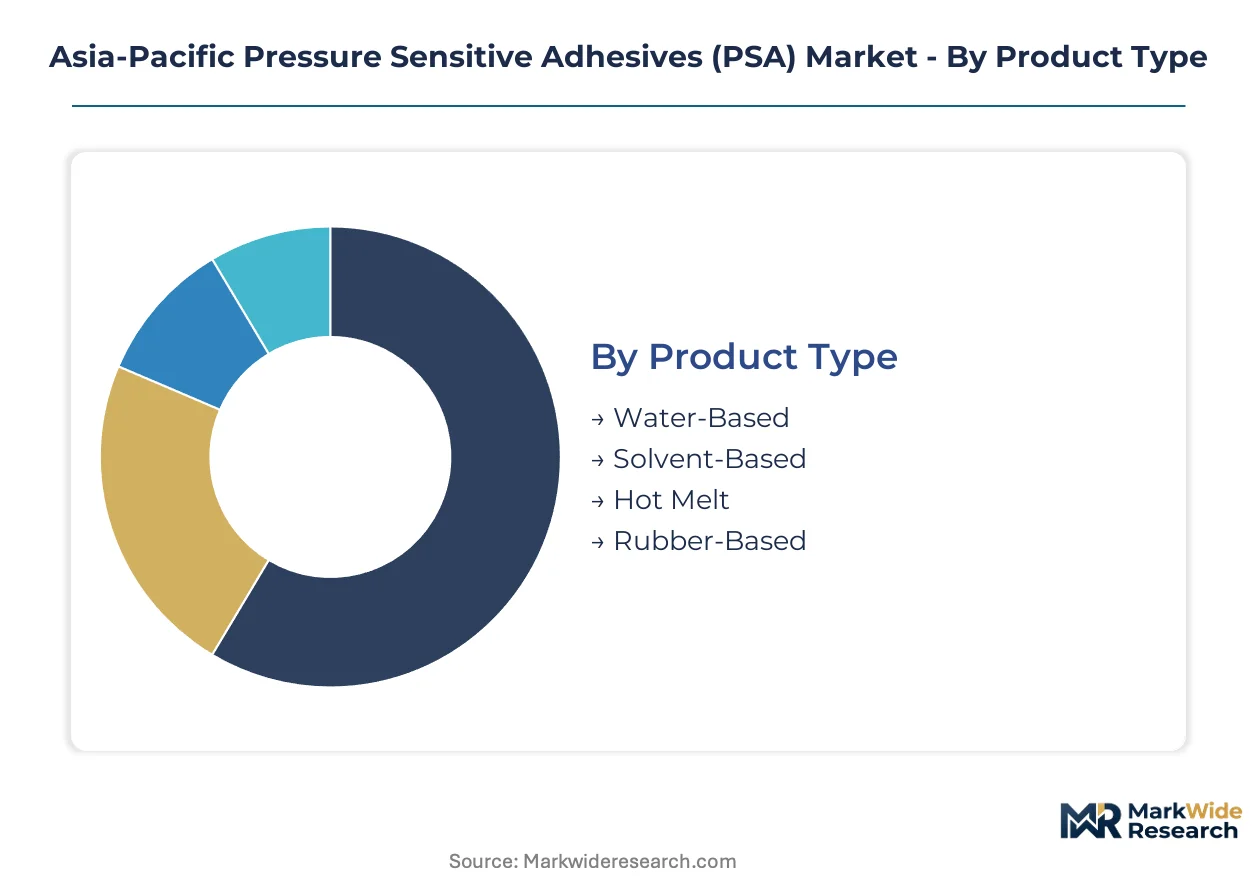
Segmentation in the Asia-Pacific PSA market reveals divergent formulation strategies across regulatory environments and end-use specifications. Water-based acrylics dominate volume in packaging and labeling, while silicone formulations command premium positioning in electronics and medical applications. Understanding these segment boundaries enables targeted capital allocation for reformulation investments and geographic expansion.
Product Type:
Integration depth varies sharply across these chemistries, with water-based systems serving standalone coating operations while hot-melt and solvent-based lines demand embedded extrusion or lamination equipment.
- Water-Based:Acrylic emulsion polymers suspended in aqueous carriers achieve immediate wet-out on paper and film substrates without VOC emissions. Jiangsu and Guangdong packaging converters are absorbing capacity expansions as MEE emission audits intensify scrutiny of solvent alternatives. This chemistry rewards producers with existing emulsion polymerization infrastructure.
- Solvent-Based:Rubber and acrylic solutions in toluene or ethyl acetate carriers deliver aggressive tack and shear resistance for heavy-duty industrial tapes. Shanghai automotive suppliers continue limited procurement where performance specifications override compliance costs, though volumes are compressing under MEE enforcement timelines.
- Hot Melt:Thermoplastic block copolymers applied molten eliminate drying energy and solvent recovery equipment. Bac Ninh electronics assemblers are piloting these systems for device component bonding.
- Rubber-Based:Natural and synthetic rubber formulations with tackifying resins serve masking and splicing applications in industrial manufacturing clusters.
Volume placements concentrate in Water-Based; the faster expansion belongs to Hot Melt.
End Use Industry:
Cost tier stratification separates these verticals, with Electronics and Automotive commanding formulation premiums while Packaging and Construction compete on throughput efficiency.
- Automotive:PSAs enable interior trim assembly, wire harness bundling, and exterior badge attachment across temperature ranges from -40°C to 120°C. Tamil Nadu and Maharashtra vehicle assembly plants are specifying acrylic foam tapes for lightweighting initiatives. NVH damping applications absorb increasing formulation development resources.
- Electronics:Display lamination, battery bonding, and thermal interface materials demand ultra-clean, low-outgassing adhesive platforms. Samsung and Apple supplier ecosystems in South Korea and Taiwan are qualifying silicone and modified acrylic PSAs for foldable device architectures. Die-attach films represent the highest-value application subset.
- Packaging:Carton sealing, label stock, and flexible food packaging drive commodity volume consumption across India and Southeast Asia.
- Construction:HVAC insulation bonding, flooring installation, and window sealing tapes serve building envelope applications in urbanizing provinces.
Electronics captures the steepest expansion trajectory; Packaging retains the dominant volume position.
Formulation:
Application specificity determines formulation selection, with Acrylic and Silicone serving precision bonding while Polyurethane and EVA address cost-sensitive temporary holding.
- Acrylic:Photochemically stable polymers with tunable glass transition temperatures enable permanent or removable adhesion across paper, film, and metal substrates. Water-based acrylics are displacing solvent alternatives in China's eastern coastal label markets as GB VOC standards tighten measurement protocols. UV-curable acrylic variants are gaining traction in Taiwan OLED panel bonding.
- Silicone:Polydimethylsiloxane backbones deliver thermal stability from -50°C to 200°C and chemical resistance for medical and electronics applications. Regional dependence on Shin-Etsu and Dow raw materials creates supply vulnerability for high-performance segments.
- Polyurethane:Reactive systems cure to structural strength for load-bearing assembly applications in transportation equipment.
- Ethylene Vinyl Acetate:Copolymer hot-melt bases serve low-temperature packaging and bookbinding with rapid set speeds.
Silicone commands the premium tier; Acrylic absorbs the broadest volume deployment.
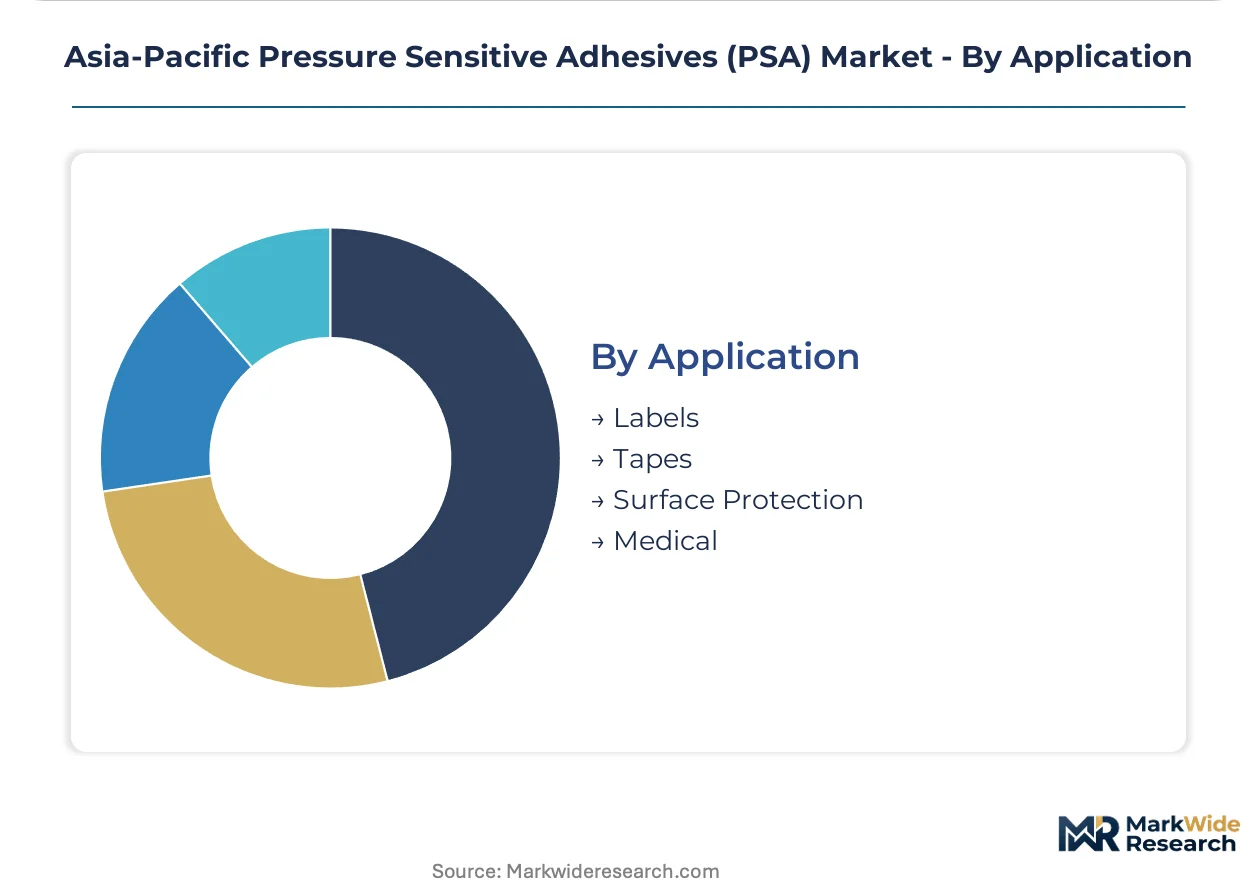
Application:
Customer type segmentation separates industrial converters from OEM direct users, with Labels and Tapes serving merchant markets while Medical and Surface Protection demand certified supply relationships.
- Labels:Pressure-sensitive facestocks combined with release liners enable information display and logistics tracking across retail and industrial supply chains. Maharashtra food and pharmaceutical labeling demand is outpacing adhesive supply infrastructure, prompting backward integration investments.
- Tapes:Single-coated and double-coated constructions serve masking, splicing, mounting, and electrical insulation functions. Automotive OEMs in Shanghai and Jiangsu are specifying acrylic foam tapes for exterior component bonding.
- Surface Protection:Temporary films shield delicate substrates from scratch and contamination during fabrication and transport. Electronics manufacturers in Hai Phong industrial zones are qualifying these systems for display panel handling.
- Medical:Hypoallergenic, breathable adhesives for wound care, device attachment, and transdermal drug delivery require ISO 10993 biocompatibility certification. CDSCO regulatory harmonization with EU MDR standards is opening certified markets previously dominated by imports.
Labels retain the volume concentration; Medical is climbing the fastest as certification barriers reward qualified regional producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical feedstock availability in Northeast Asia anchors the regional PSA value chain. China's propylene derivative capacity and Japan's silicone monomer production concentrate raw material sourcing. Formulation plants cluster near these feedstock nodes to minimize logistics exposure.
China
Automotive OEMs and consumer electronics assemblers in Shanghai, Jiangsu, and Guangdong drive acrylic PSA consumption for lightweighting and display bonding. MEE VOC emission audits intensify scrutiny of solvent-based production lines. Packaging converters in Jiangsu province are absorbing water-based capacity expansions as GB standards tighten formaldehyde and toluene thresholds.
Japan
Silicone PSA production for medical and high-temperature electronics applications concentrates around Shin-Etsu and Dow supply relationships. METI oversees chemical substance reporting under CSCL frameworks affecting raw material sourcing transparency. Kanto and Kansai industrial corridors host precision coating operations serving regional semiconductor packaging demand.
South Korea
Samsung and LG supplier ecosystems qualify modified acrylic and silicone PSAs for foldable smartphone display lamination. MFDS regulates medical-grade adhesive certification for wound care and device attachment applications. Gyeonggi-do and Incheon manufacturing clusters absorb die-attach film volumes for advanced semiconductor packaging.
India
Food and pharmaceutical labeling demand in Maharashtra and Tamil Nadu outpaces adhesive supply infrastructure. BIS certification requirements for packaging adhesives create incremental market access barriers for imported formulations. Western and southern states see packaging houses negotiating backward integration into emulsion polymerization.
Vietnam
Samsung and Apple supplier relocations to Bac Ninh and Hai Phong industrial zones generate greenfield PSA demand for device assembly. Electronics manufacturers in Hai Phong are qualifying surface protection films for display panel handling. Northern industrial provinces attract coating operation investments to serve export-oriented electronics assembly.
Asia-Pacific Pressure Sensitive Adhesives (PSA) Market Competitive Environment
Capacity expansion dominates the current landscape as regional players respond to formulation shift mandates. The market structure consolidates around diversified chemical conglomerates with captive resin supply, mid-sized specialists with vertical integration into emulsion polymerization, and electronics-focused coating houses with cleanroom capabilities. Three archetypes define competitive positioning: feedstock-integrated majors, application-specific formulators, and regional packaging converters. M&A activity and geographic expansion represent the dominant competitive moves as players secure compliant chemistry platforms and proximity to electronics manufacturing clusters.
Among diversified chemical conglomerates, 3M, Henkel AG & Co. KGaA, and Nitto Denko Corporation exemplify the feedstock-integrated archetype. 3M represents technology leadership in medical-grade platforms. Henkel AG & Co. KGaA occupies a position anchoring electronics bonding applications through acrylic formulation depth. Nitto Denko Corporation sits within the regional production capacity tier with extensive manufacturing footprints across Japan and Southeast Asia. These three names illustrate how scale and chemistry breadth translate into defensive positioning against regulatory-driven reformulation cycles.
| Leading Market Players |
|---|
| 3M |
| Arkema Group |
| H.B. Fuller Company |
| Dow |
| Henkel AG & Co. KGaA |
| Avery Dennison Corporation |
| Nitto Denko Corporation |
| Pidilite Industries Ltd. |
| Sika AG |
| Others |
Value Chain & Pricing Dynamics
China's MEE VOC emission standards gate qualified supply and premium-tier pricing access, forcing solvent-based producers to absorb reformulation costs while water-based and hot-melt specialists capture margin premiums from compliant buyers in Shanghai and Jiangsu packaging clusters.
Pricing Analysis
Warranty and technical service bundling separates premium PSA suppliers from commodity converters across the Asia-Pacific value chain. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with medical-grade silicone PSAs commanding the highest tier due to ISO 10993 compliance costs. Price differentiation stems from after-sales formulation support and regulatory documentation packages. Cost compression in solvent-based tiers is intensifying because MEE enforcement timelines accelerate line conversions. Mid-sized packaging converters in Maharashtra exhibit the highest price sensitivity, while Samsung and Apple supplier ecosystems in South Korea show least sensitivity for qualified electronics bonding platforms.
Supply Chain Analysis
Dual-sourcing mandates from automotive OEMs in Tamil Nadu and electronics assemblers in Taiwan require multi-supplier qualification for acrylic monomers and silicone raw materials. Supply concentration rests on China for propylene derivatives, Japan for silicone monomers through Shin-Etsu and Dow relationships, and South Korea for specialty tackifying resins. Raw material dependencies center on naphtha-cracker outputs, rosin ester tackifiers, and photoinitiator chemicals. Single-source vulnerability in Japanese silicone feedstocks creates structural risk for high-temperature PSA segments. Distribution runs through regional coating converters and direct mill procurement relationships displacing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive resin supply and in-house emulsion polymerization determine margin defense against reformulation cost shocks.
For Market Incumbents: Lock in acrylic monomer supply through long-term offtake agreements with Northeast Asian petrochemical complexes to hedge against naphtha price volatility. Defend position by accelerating water-based capacity additions in Jiangsu and Guangdong ahead of MEE audit intensification. Secure Shin-Etsu and Dow silicone allocation commitments for medical-grade segments where substitution risk runs lowest. For New Entrants and Emerging Players: Enter via CDSCO-certified medical-grade tape production in Maharashtra and Tamil Nadu, where BIS barriers have suppressed import competition and domestic supply lags demand. Target Vietnam's Bac Ninh electronics corridor for greenfield PSA coating operations serving Samsung and Apple supplier relocations. Pursue qualification partnerships with regional label stock converters seeking backward integration alternatives. For Investors and Strategic Acquirers: MEE enforcement timeline acceleration is the leading indicator that solvent-to-water reformulation capacity will command scarcity premiums. Position for five-to-ten year viability by acquiring mid-sized Indian packaging converters with emulsion polymerization infrastructure and BIS certification pathways. Monitor GB standard VOC threshold announcements as the primary inflection signal for compliance-driven consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Monomer Supply | Captive feedstock secures margin control against naphtha volatility for Jiangsu coating operations. |
| Water-Based Capacity Expansion | Jiangsu and Guangdong facility additions capture volume shifting from solvent-based competitors under MEE audits. |
| CDSCO Medical-Grade Certification Investment | ISO 10993 pathway opens Maharashtra and Tamil Nadu markets previously dominated by imports. |
| UV-Curable Formulation Development | Taiwan OLED panel bonding demand absorbs instant-cure systems eliminating thermal oven requirements. |
| Joint Venture with Vietnamese Electronics Cluster | Bac Ninh and Hai Phong proximity reduces logistics exposure for Samsung and Apple supplier ecosystems. |
Study Parameters
Multi-period observation of MEE enforcement intensity, acrylic monomer price spreads, and electronics assembly relocation patterns anchored the trend analysis, supplemented by interviews with adhesive formulation chemists, procurement leads at automotive OEMs, plant managers at Jiangsu coating facilities, and technical R&D directors at Japanese silicone suppliers. Secondary validation drew from customs and trade data, ACC regional reports, SEC 10-K disclosures from listed chemical conglomerates, and GB standard publication records. Bottom-up capacity assessments across 15 coating clusters triangulated with top-down petrochemical feedstock demand models.
Input-output matrices mapped acrylic monomer supply to water-based PSA output across formulation tiers, with segmentation modeling across chemistry type, end-use vertical, and regional production hub. CAGRs derived from elasticity-adjusted demand projections over the analysis window, incorporating semiconductor packaging content-per-device trajectories and automotive lightweighting penetration curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under MEE enforcement acceleration or Shin-Etsu supply disruption scenarios. Deviation in naphtha-cracker operating rates or propylene derivative export quotas would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Wearable Skin Adhesives Market
Adhesives & Sealants
Europe Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Adhesive Dispensing Systems Market
Adhesives & Sealants
South America Reactive Adhesives Market
Adhesives & Sealants
Epoxy Putty and Construction Chemicals Market
Adhesives & Sealants
Flooring Adhesive Market
Adhesives & Sealants
Global Concrete Bonding Agents Market
Adhesives & Sealants
Solvent Based Laminating Adhesives Market
Adhesives & Sealants
South America Contact Adhesives Market
Adhesives & Sealants
Fabric Glue Market
Adhesives & Sealants
Lignin for Adhesives Market
Adhesives & Sealants
US Adhesives and Sealants Market
Adhesives & Sealants
Europe Contact Adhesives Market
Adhesives & Sealants
Optically Clear Adhesives Market
Adhesives & Sealants
Global Vascular Sealant Market
Adhesives & Sealants
Heat Resistant Sealant Market