
 Water Based Adhesive Market | 2026-2036
Water Based Adhesive Market Size, Share, and Industry Trends Forecast 2026-2036
Water Based Adhesive Market Intelligence
Expertise in polymer science and sustainable formulation is reorganizing the competitive landscape for water-based adhesives. Henkel AG & Co. KGaA leverages its scale and R&D to develop low-VOC products for diverse applications. H.B. Fuller Company specializes in customized solutions for the high-volume paper and packaging industries. Meanwhile, Sika AG focuses on high-performance adhesives for the demanding construction and automotive sectors.
Water-based adhesives are formulations where polymers are suspended in water as the carrier vehicle. These systems, which often utilize acrylics or polyvinyl acetate, form a bond as the water evaporates or is absorbed by the substrate. The packaging end-use industry represents the largest segment by volume, driven by paper and board applications. In contrast, the automotive and construction industries demand specialized polyurethane formulations that offer superior durability and heat resistance.
Regulatory frameworks such as the European Union's REACH and the US Environmental Protection Agency's (EPA) standards on volatile organic compounds (VOCs) steer the market. These rules restrict the use of solvent-borne adhesives, creating a direct advantage for water-based alternatives in many applications. Formulators must now balance the technical challenge of enhancing performance with the commercial need to meet evolving environmental mandates and cost pressures.
Market Dynamics
Regulatory pressure from environmental agencies like the US EPA and the EU's ECHA is the central force reconfiguring the market. These mandates against volatile organic compounds directly favor water-based systems over solvent-borne alternatives, especially in consumer-facing industries.
Growth Catalysts
- Sustainable Packaging Demand:The transition by consumer goods companies to recyclable and repulpable packaging materials, particularly paper and board, creates direct demand for compatible water-based adhesives.
- Stringent VOC Regulations:Rules like the European Union's REACH framework and US EPA standards actively restrict solvent-based products, creating a regulatory tailwind for water-based formulations in industrial applications.
- Asia-Pacific Manufacturing Growth:Concentrated manufacturing and export activity, especially within China's packaging and footwear sectors, requires high volumes of cost-effective and compliant adhesive solutions.
Market Restraints
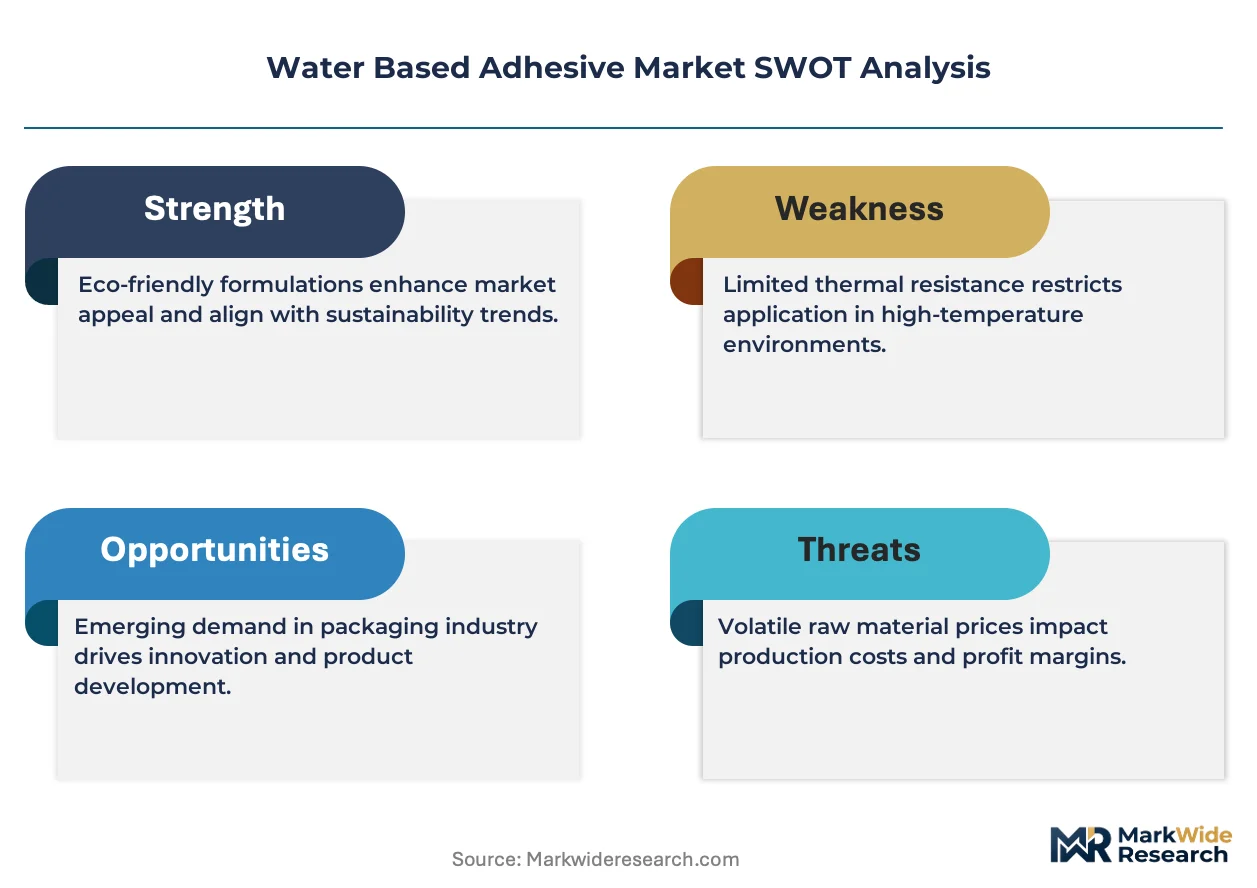
- Performance Limitations:Certain water-based adhesives exhibit lower resistance to heat and moisture compared to solvent-based or reactive counterparts, limiting use in demanding automotive or outdoor applications.
- Raw Material Volatility:The cost and supply of key polymers, such as acrylic and vinyl acetate monomers derived from petrochemical feedstocks, are subject to global commodity market fluctuations.
- Slower Curing Speeds:The evaporation of water as a curing mechanism is inherently slower than solvent evaporation, which can create bottlenecks on high-speed manufacturing and assembly lines.
Strategic Opportunities
- Bio-Based Formulations:Developing adhesives from renewable feedstocks like starches or bio-derived polymers presents an opportunity to meet corporate sustainability goals and circular economy principles.
- Flexible Packaging Applications:Formulating advanced adhesives for multi-layer flexible food packaging that improve barrier properties and are compatible with recycling streams addresses a key industry need.
- Electric Vehicle Battery Assembly:The assembly of battery packs in electric vehicles requires specialized adhesives for thermal management and bonding, a high-value niche for performance-tuned water-based systems.
Industry Challenges
- Formulation Complexity:Balancing performance attributes like tack and open time with regulatory compliance and cost targets requires significant R&D expertise in polymer science and additive chemistry.
- Substrate Compatibility:Ensuring consistent adhesion to a widening array of substrates, including coated papers, recycled plastics, and composite materials, demands continuous product testing and customization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Based Adhesive Market |
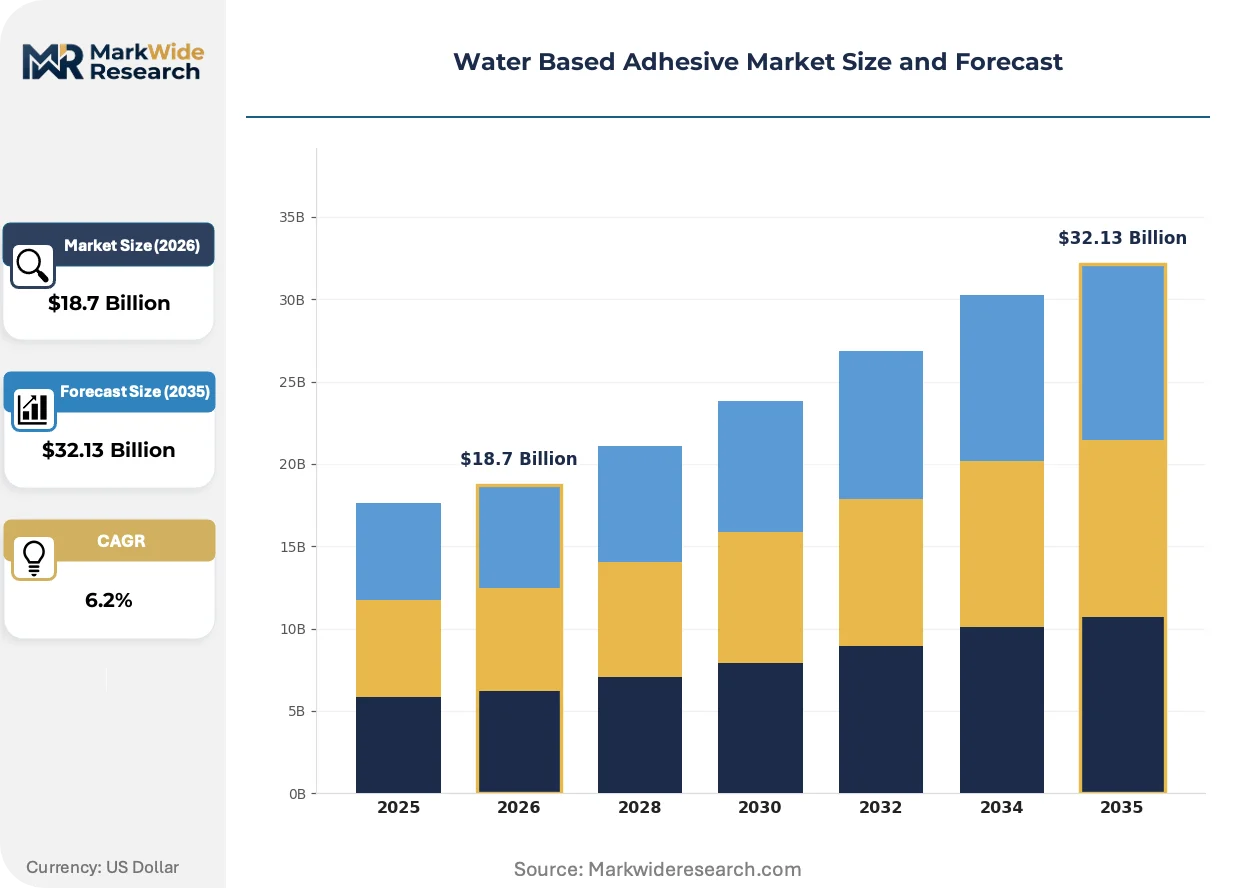
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.13 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyvinyl Acetate, Acrylics, Polyurethane, Ethylene Vinyl Acetate End Use Industry: Packaging, Construction, Automotive, Furniture Technology: Waterborne, Spray Adhesives, Roller Coating, Hot Melt Application: Wood Bonding, Paper Bonding, Textile Bonding, Floor Covering |
| Companies Covered | 3M, Sika AG, Henkel AG & Co. KGaA, PPG Industries, Ashland, H.B. Fuller Company, Dow, Avery Dennison Corporation, Arkema, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Based Adhesive Market Strategic Shifts & Innovations
The pursuit of circularity is reshaping product development, pushing formulators beyond simple VOC reduction. This shift prioritizes adhesives that not only perform during use but also enhance the end-of-life recyclability of the final product, particularly within the packaging sector.
Advanced polymer dispersion technology allows for precise control over particle size and film formation. This capability is being adopted by manufacturers in automotive and electronics for high-strength bonds. Consequently, the market for polyurethane dispersions is bifurcating, with high-solid, performance-driven formulations for industrial use separating from lower-cost vinyl acetate ethylene emulsions for packaging.
European Union regulations under REACH are evolving to scrutinize specific monomers and additives within water-based systems themselves, not just VOCs. This forces a continuous cycle of reformulation to remove substances of very high concern (SVHCs). The packaging and consumer goods sectors are most affected, needing to ensure compliance for market access in Europe.
Brand owner specifications increasingly mandate adhesives that facilitate recycling and repulping. This disrupts traditional procurement, which focused primarily on bond strength and cost. The paper and corrugated board industries are seeing the fastest change, as demand for certified "recycling-friendly" adhesives becomes a prerequisite for supplier contracts in North America and Europe.
Water Based Adhesive Market Segmentation
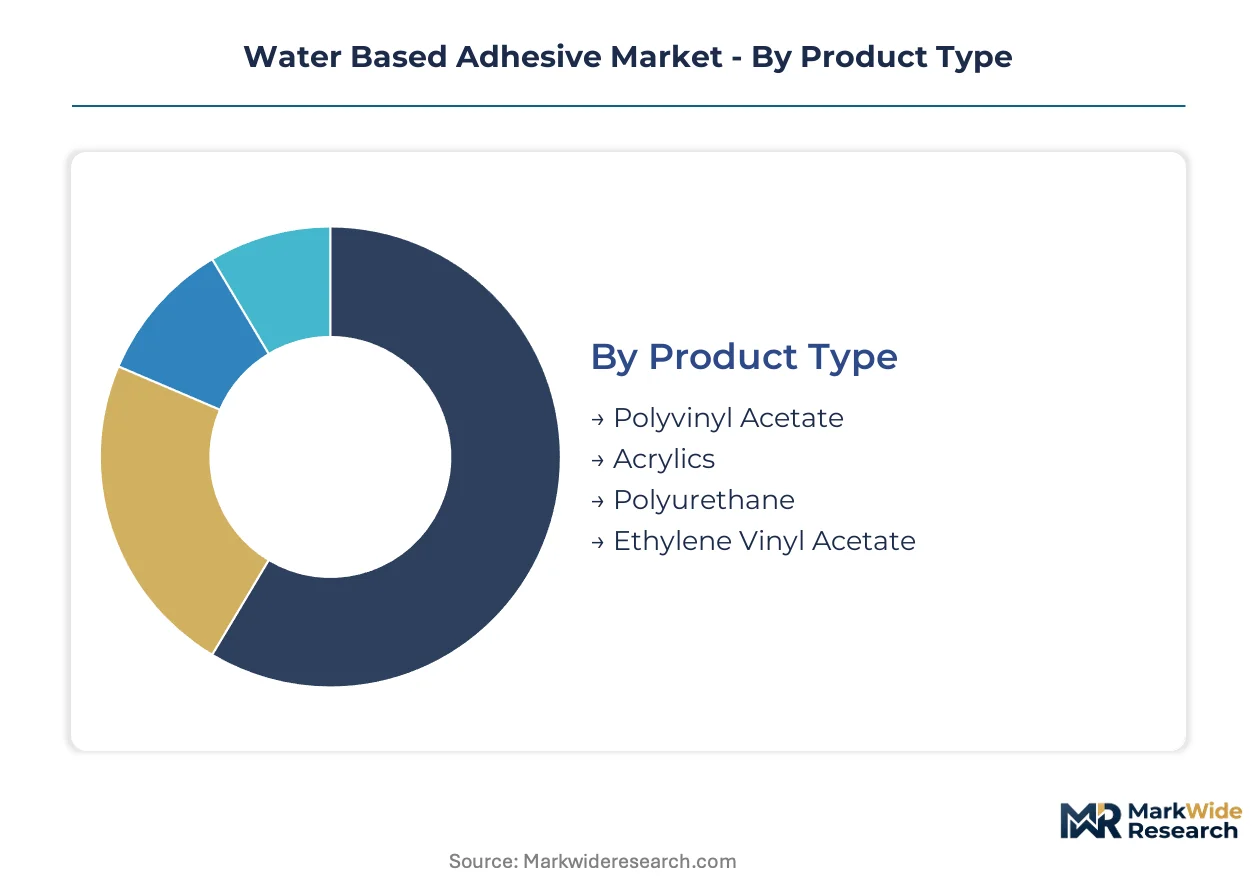
Understanding the segmentation of the water-based adhesive market reveals how diverse formulations meet specific industrial demands. This granular view highlights the interplay between polymer chemistry, application methods, and end-use requirements. Each segment reflects distinct performance needs and regulatory compliance pathways.
Product Type:
The product type segmentation reveals how different polymer chemistries are channeled through various distribution networks to serve distinct industrial users.
- Acrylics:These versatile polymers form strong, flexible bonds and are widely used in pressure-sensitive adhesives and packaging. Demand concentrates in consumer goods packaging due to their balance of performance and cost-effectiveness.
- Polyurethane:Known for superior durability, heat resistance, and strong adhesion, these formulations are critical in demanding applications. The automotive and construction sectors drive demand for high-performance polyurethane dispersions for structural bonding.
- Polyvinyl Acetate:PVAc adhesives are cost-effective and common in wood bonding, paper, and packaging applications.
- Ethylene Vinyl Acetate:EVA emulsions offer good adhesion to various substrates, finding use in packaging and textile applications.
Polyvinyl Acetate dominates the installed base for general purpose applications. Acrylics are where expansion concentrates due to their versatility and environmental profile.
End Use Industry:
This segmentation illustrates how different end-use industries dictate the performance requirements and volume demands for water-based adhesive solutions.
- Packaging:This segment represents the largest volume consumer, driven by extensive use in paper, board, and flexible packaging applications. The shift to sustainable and recyclable materials by consumer goods companies fuels significant demand.
- Construction:Adhesives in construction require robust performance, including weather resistance and durability for flooring, roofing, and structural components. Strict building codes and the need for low-VOC products drive specialized formulation development in this sector.
- Automotive:Water-based adhesives support interior trim, headliners, and battery assembly in the automotive sector.
- Furniture:Adhesives for furniture bonding include applications in wood assembly, laminates, and upholstery.
Packaging applications drive the largest current volumes. The automotive sector is climbing fastest, particularly with electric vehicle battery assembly needs.
Technology:
The technology segmentation reflects the varying cost structures and application complexities associated with different adhesive delivery and curing mechanisms.
- Waterborne:This core technology encompasses liquid formulations where polymers are dispersed in water, forming bonds as the water evaporates. Its broad applicability across packaging and general assembly makes it a foundational segment.
- Hot Melt:While traditionally solvent-based, water-based hot melts are emerging, offering rapid setting times and strong bonds for high-speed manufacturing lines. Packaging and product assembly leverage their efficiency for throughput.
- Spray Adhesives:These adhesives are applied via spray systems, offering broad coverage for applications like insulation and upholstery.
- Roller Coating:Roller coating methods efficiently apply adhesives to flat substrates, common in laminating and panel bonding.
Waterborne formulations underpin the majority of current adhesive applications. Hot melt technologies are on the steepest expansion trajectory for speed-sensitive industrial processes.
Application:
This application-based segmentation highlights how specific bonding requirements drive volume and specialized product development within the water-based adhesive market.
- Paper Bonding:This application segment is crucial for the packaging industry, encompassing corrugated board, flexible packaging, and labeling. Demand for repulpable and recyclable adhesives drives innovation within this high-volume area.
- Wood Bonding:Adhesives for wood bonding are essential in furniture manufacturing, construction, and flooring, requiring strong, durable, and often water-resistant bonds. Polyvinyl acetate and polyurethane formulations are widely used for their performance characteristics.
- Textile Bonding:Adhesives in textile bonding are used for lamination, non-wovens, and garment assembly, requiring flexibility and wash resistance.
- Floor Covering:Floor covering adhesives secure various materials like vinyl, carpet, and wood, needing strong, long-lasting bonds.
Paper Bonding applications currently consume the highest volumes. Floor Covering is gaining share fastest as construction activity increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Ministry of Ecology and Environment (MEE) mandates for green manufacturing are shaping the water-based adhesive market. These regulations push for reduced solvent use across various industrial applications. This emphasis on environmental compliance and sustainable production drives demand for water-based alternatives globally.
China
China's extensive manufacturing and export sectors create immense demand for water-based adhesives, particularly in packaging and footwear production. The country's dual carbon goals and national GB standards actively promote eco-friendly industrial practices. In the Yangtze River Delta, manufacturers are rapidly adopting water-based formulations for high-volume, compliant product assembly.
United States
United States demand for water-based adhesives stems from sustainable packaging initiatives and growing construction projects. The US EPA's stringent standards on volatile organic compounds directly favor these non-solvent alternatives. Across the Midwest, packaging companies are rapidly integrating advanced water-based systems into their high-speed production lines.
Germany
Germany's automotive and construction industries require high-performance water-based adhesives for structural bonding and assembly applications. The EU's REACH framework and CE marking enforce strict environmental and safety standards across the supply chain. In Bavaria, specialized polyurethane dispersions are developing for demanding industrial and automotive applications.
India
India's rapid infrastructure development and expanding consumer goods packaging sector fuel significant demand for water-based adhesives. BIS standards are increasingly influencing product formulations for quality and safety across various end-uses. Manufacturers in Maharashtra are expanding production capacity for cost-effective packaging and construction materials.
Japan
Japanese electronics assembly and automotive lightweighting initiatives drive demand for precision water-based adhesives. JIS standards and national environmental performance targets guide product development for advanced materials. In the Kanto region, suppliers are advancing high-strength water-based systems for high-tech industrial applications.
Water Based Adhesive Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the water-based adhesive market. This tiered structure reflects the diverse performance needs across various end-use industries, from high-volume packaging to specialized automotive applications. Key archetypes include global chemical conglomerates offering a wide product range, niche solution providers focusing on specific performance attributes, and regional manufacturers emphasizing cost-effectiveness. Strategic partnerships and targeted M&A activity are dominant competitive moves shaping the market.
Global chemical conglomerates like Henkel AG & Co. KGaA, a German AG, exemplify market leadership through extensive R&D and diversified product portfolios spanning multiple applications. H.B. Fuller Company, a US-based entity, anchors the high-volume paper and packaging industries with customized, cost-effective solutions. Swiss-based Sika AG occupies a position in high-performance adhesives for demanding construction and automotive sectors, focusing on specialized formulations. These companies represent distinct strategic approaches within the competitive landscape, catering to varied industrial requirements and regulatory pressures.
| Leading Market Players |
|---|
| 3M |
| Sika AG |
| Henkel AG & Co. KGaA |
| PPG Industries |
| Ashland |
| H.B. Fuller Company |
| Dow |
| Avery Dennison Corporation |
| Arkema |
| Others |
Cost & Logistics Intelligence
Long-term contract arrangements underwrite supply access and price visibility for major water-based adhesive consumers. These agreements are essential for industrial buyers needing consistent material flow and cost predictability over extended periods.
Pricing Analysis
Contract-based long-term offtake dominates pricing for high-volume industrial water-based adhesive procurement. Customization level for specialized applications and certification level, such as EU REACH compliance, drive significant price differentiation. Volume scale also impacts per-unit cost, favoring large buyers in packaging. Pricing pressure stems from raw material volatility, particularly for petrochemical feedstocks like acrylic and vinyl acetate monomers. Packaging end-users demonstrate high price sensitivity due to their extensive volume requirements, while automotive and construction sectors prioritize performance and durability over the lowest possible cost.
Supply Chain Analysis
Commodity price volatility for petrochemical feedstocks presents a structural risk across the water-based adhesive supply chain. China, the United States, and Germany are significant production hubs for these materials and finished adhesives. Acrylic and vinyl acetate monomers are critical inputs, often sourced globally. Distribution runs through a mix of direct sales to large industrial users like Henkel AG & Co. KGaA and specialized chemical distributors serving smaller accounts. Regulatory changes in one major producing region, such as new GB standards in China, can ripple through global supply networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The water-based adhesive market is in a cyclical recovery, driven by renewed infrastructure investment and consumer goods packaging demand. Environmental regulations further accelerate this shift towards sustainable formulations.
For Market Incumbents: Secure long-term raw material contracts to mitigate commodity price volatility, particularly for petrochemical-derived polymers. Invest in advanced R&D for bio-based formulations to counter regulatory shifts from bodies like the US EPA and EU ECHA. Certification investment in "recycling-friendly" adhesives strengthens market position against solvent-based alternatives. Expand manufacturing capacity in strategic regions like the Yangtze River Delta to meet concentrated demand.
For New Entrants and Emerging Players: Anchor in flexible packaging applications requiring improved barrier properties and compatibility with recycling streams. Focus on electric vehicle battery assembly for specialized thermal management adhesives, a high-value niche. The high-performance segment within automotive and construction offers penetrable entry points. Offer customized, application-specific solutions with rapid prototyping for original equipment manufacturers.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-sized specialists with proprietary polymer dispersion technology or unique bio-based formulation expertise. The market shows long-term viability over the next decade, supported by persistent sustainability mandates and regulatory tailwinds. Watch the rapid adoption rate of bio-based adhesive solutions in mainstream packaging as an inflection indicator for broader market transformation.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Reduces environmental footprint and ensures compliance with China's MEE mandates. |
| Capacity Expansion | Meets growing demand from China's export sectors and US sustainable packaging. |
| Long-term Supply Agreement | Stabilizes raw material costs against petrochemical feedstock fluctuations. |
| Joint Venture | Accesses specialized polymer science expertise for high-performance polyurethane formulations. |
| Product Launch | Introduces advanced adhesives for flexible food packaging, addressing recycling needs. |
Research Approach
A spread of perspectives from R&D directors, procurement leads at packaging companies, automotive engineers, and regulatory compliance officers converged on the working assumptions for this study. Primary interviews with these industry stakeholders were complemented by secondary validation. Industry association reports, national environmental agency disclosures (e.g., US EPA, EU ECHA), and corporate sustainability reports informed the analysis. Bottom-up data collection from market participants and top-down validation against macroeconomic indicators ensured data integrity.
Product type, end-use industry, technology, and application were the primary segmentation dimensions modeled. Compound annual growth rates were derived from historical data trends and projected demand forecasts across the analysis window. Evolving VOC regulations and packaging material shifts served as key industry-specific forecast inputs. The analytical framework also considered regional regulatory frameworks such as EU REACH and China's GB standards for market progression.
Decision-makers should treat outputs as directional under current regulatory stability and raw material supply assumptions; material deviation would warrant model refresh. Geopolitical events or unforeseen technological breakthroughs could alter market trajectories. Practitioners should keep alternative scenarios live as global trade policies and environmental mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Global Engineering Adhesives Market
Adhesives & Sealants
Anti-Tacking Agents Market
Adhesives & Sealants
Anaerobic Adhesives and Sealants Market
Adhesives & Sealants
Global Spray Adhesive Market
Adhesives & Sealants
South America Cyanoacrylate Adhesives Market
Adhesives & Sealants
Global Underfill Material Market
Adhesives & Sealants
Waterproof Tapes Market
Adhesives & Sealants
Europe Flock Adhesives Market
Adhesives & Sealants
Wood Adhesives and Binders Market
Adhesives & Sealants
Asia-Pacific Waterproofing Products Market
Adhesives & Sealants
Global Isononyl Acrylate Market
Adhesives & Sealants
Curing Adhesives Market
Adhesives & Sealants
Epoxy Curing Agents Market
Adhesives & Sealants
South Africa Sealants Market
Adhesives & Sealants
United Kingdom Hot-Melt Adhesives Market