

Hybrid Silane-Terminated Polymer Adhesives for EV Battery Pack Assembly Market Size, Share, and Industry Trends Forecast 2026-2036
Hybrid Silane-Terminated Polymer Adhesives for EV Battery Pack Assembly Market Insights
The adhesive supply base for EV battery assembly is consolidating around two distinct performance tiers: premium formulations certified for structural bonding under crash-load conditions, and commodity-grade sealants serving non-thermal applications. Henkel AG & Co. KGaA leverages its European OEM relationships to dominate specification-driven procurement cycles. Sika AG anchors its position through deep integration with German automaker platforms. Dow differentiates via proprietary silane-terminated polymer backbones optimized for moisture-cure kinetics in high-humidity assembly environments.
Hybrid silane-terminated polymer adhesives combine silane end-capped polyether or polyurethane backbones with reactive crosslinking chemistry, delivering elastic recovery above 300% tensile elongation alongside dielectric strength exceeding 15 kV/mm for electrical insulation functions. One-component moisture-curable systems lead volume adoption due to simplified dispensing and reduced process variability on module assembly lines. Two-component heat-curable formulations capture premium margin pools where cycle-time compression justifies capital-intensive curing infrastructure. Structural bonding applications command the fastest growth trajectory as OEMs eliminate mechanical fasteners from pack architectures to save mass and assembly labor.
FDA indirect food-contact standards influence adhesive selection for battery packs positioned near cabin air circulation pathways in certain vehicle platforms, while REACH SVHC restrictions constrain isocyanate-containing legacy polyurethane alternatives. EPA VOC emission limits for manufacturing facilities push adhesive producers toward 100%-solid silane-terminated systems with minimal solvent content. Stakeholders must monitor evolving UN ECE R100 battery safety testing protocols, which increasingly specify adhesive performance under thermal runaway propagation scenarios as a gating factor for pack-level certification.
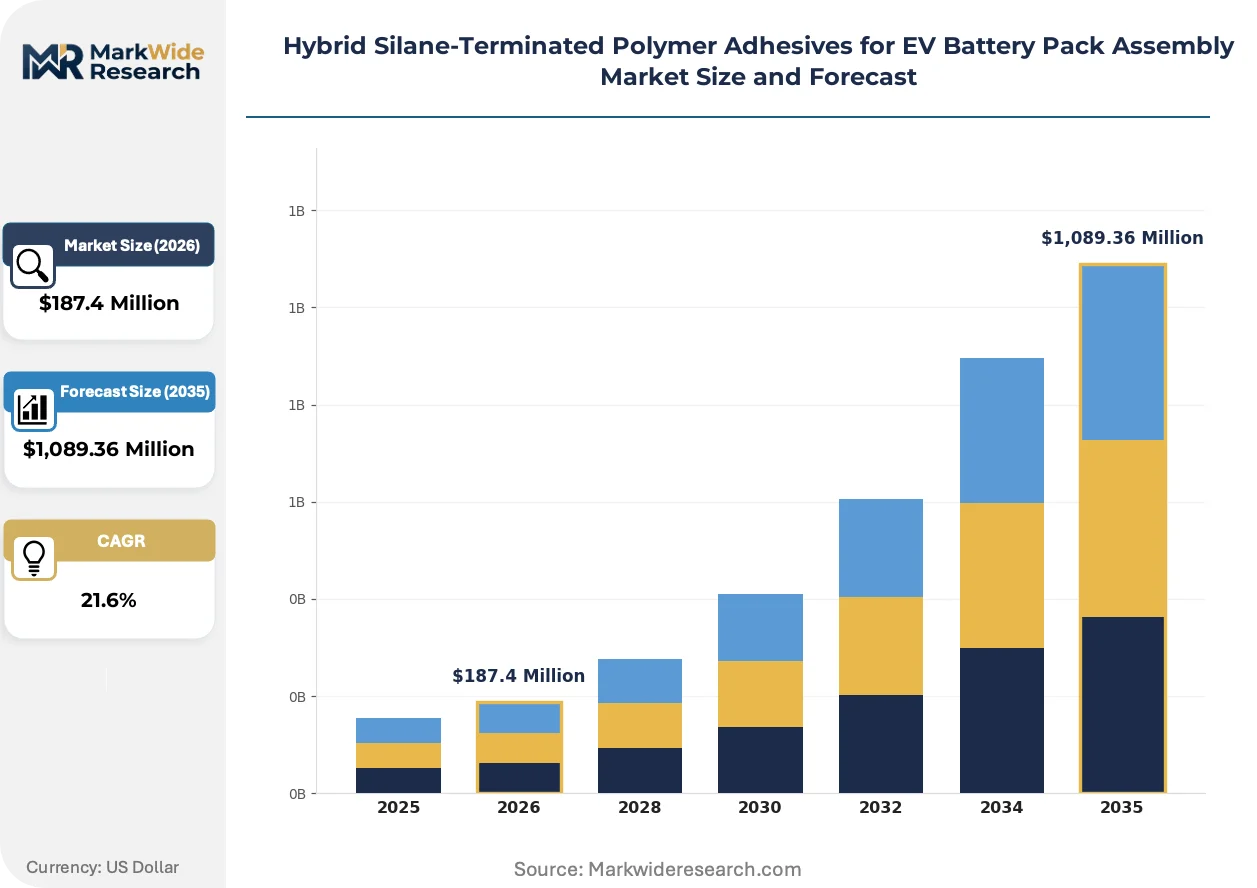
Market Dynamics
Structural mass reduction mandates from automakers are eliminating mechanical fasteners from battery pack architectures, forcing adhesive systems to absorb crash-load and thermal management functions simultaneously. This engineering convergence compresses qualification timelines and elevates performance certification requirements.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon blowing agents in legacy polyurethane systems accelerates silane-terminated polymer substitution for thermal interface materials in German and French battery plants.
- Structural bonding applications:OEMs specify hybrid silane-terminated adhesives for module-to-pack bonding to replace welded joints, cutting assembly labor hours while improving vibration damping across high-voltage architectures.
- China NMPA battery safety standards:Thermal runaway propagation testing protocols now require adhesive performance validation under 800°C flame exposure, creating specification pull for fire-resistant silane formulations.
Market Restraints
- Organotin catalyst cost volatility:Moisture-cure kinetics depend on tin-based catalysts concentrated in Southeast Asian chemical processing, exposing formulators to input price swings and supply rationing.
- Isocyanate legacy infrastructure:Battery plants in Michigan and Lower Saxony retain capital-intensive dispensing systems optimized for two-part polyurethanes, creating switching friction despite silane performance advantages.
- REACH SVHC disclosure burden:Substances of very high concern screening forces continuous reformulation cycles, extending R&D timelines for products destined for EU assembly lines.
Strategic Opportunities
- India PLI scheme localization:Production-linked incentives for cell and pack manufacturing in Gujarat and Tamil Nadu create first-mover advantage for adhesive suppliers establishing toll-manufacturing partnerships with domestic chemical processors.
- Solid-state battery architectures:Next-generation cell designs with ceramic electrolytes demand adhesives with ionic purity below 50 ppm sodium content, opening premium formulation segments for specialized silane backbones.
- UN ECE R100 thermal runaway certification:Evolving test protocols specify adhesive char integrity under direct flame impingement, creating specification windows for suppliers with validated fire-barrier chemistries.
Industry Challenges
- Moisture-cure process control:Ambient humidity variation on assembly lines causes batch-to-batch cure rate inconsistency, requiring inline spectroscopic monitoring systems that strain capital budgets.
- Cross-contamination risk:Shared dispensing equipment between legacy polyurethane and new silane systems risks catalyst poisoning, demanding dedicated production cells or extensive purge protocols.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hybrid Silane-Terminated Polymer Adhesives for EV Battery Pack Assembly Market Trends and Innovations
Active material science investment is compressing cure cycles while expanding the operational temperature envelope of hybrid silane-terminated systems. Formulators are engineering backbones that tolerate the thermal shock of fast-charging cell architectures without sacrificing elastic recovery.
Silane-terminated polyether backbones with secondary amine crosslinkers are integrating into one-component dispensing systems for high-humidity assembly environments. Korean battery module manufacturers in Gyeonggi Province deploy these systems to eliminate nitrogen-purged dispensing booths, cutting facility capital expenditure by 40% while maintaining moisture-cure reliability. The technology is integrating moisture-cure and heat-accelerated cure pathways within identical polymer architectures, collapsing the distinction between ambient and elevated-temperature assembly processes.
The EPA VOC emission limits for manufacturing facilities are forcing adhesive producers toward 100%-solid silane-terminated formulations with minimal solvent content. Battery plants in Ohio and South Carolina face state-level air quality enforcement that prohibits solvent-borne adhesive dispensing without carbon capture add-ons. Small and mid-sized pack assemblers are responding by consolidating procurement with suppliers certified for zero-VOC product lines, bypassing capital-intensive abatement equipment.
Specification-driven procurement now dominates module assembly contracts, with OEMs mandating adhesive performance validation under UN ECE R100 thermal runaway scenarios before supplier qualification. Tier-1 battery manufacturers in Stuttgart and Shanghai require batch-level dielectric testing certificates, displacing spot-check quality protocols. This behavioral shift concentrates procurement authority with technical sourcing teams rather than commodity purchasing functions, extending vendor onboarding timelines by 8-12 months in most automotive platforms.
Hybrid Silane-Terminated Polymer Adhesives for EV Battery Pack Assembly Market Segmentation
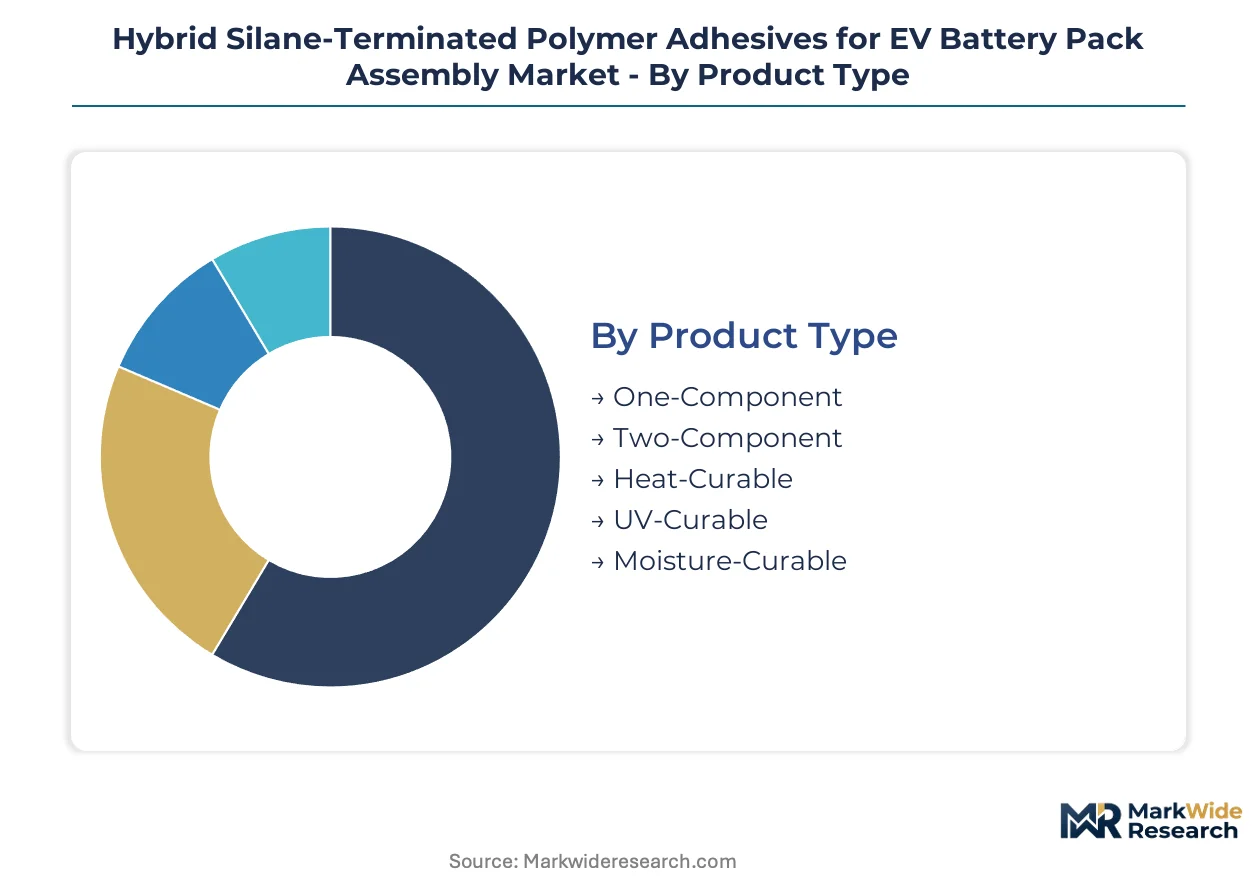
Segmentation in hybrid silane-terminated polymer adhesives reveals how formulation chemistry, cure mechanism, and functional specification map to distinct procurement tiers across EV battery assembly. Each axis carries different margin profiles, qualification barriers, and switching costs that reshape supplier positioning.
Product Type:
Product type segmentation tracks the cure chemistry and dispensing architecture that determines line speed, capital intensity, and process control requirements on battery assembly floors.
- One-Component:Moisture-cure silane-terminated systems dominate volume procurement for their simplified dispensing and elimination of meter-mix equipment. Korean module manufacturers in Gyeonggi Province deploy these formulations to cut facility capital expenditure while maintaining cure reliability in high-humidity environments.
- Two-Component:Heat-curable systems capture premium positioning where cycle-time compression justifies dedicated curing infrastructure. German OEM platforms specify these for structural bonding applications demanding accelerated throughput.
- Heat-Curable:Elevated-temperature cure pathways enable complete crosslinking in minutes rather than hours.
- UV-Curable:Ultraviolet-initiated systems serve niche applications requiring instant tack-free surfaces.
- Moisture-Curable:Ambient humidity-driven chemistry dominates one-component architectures for simplified logistics.
One-Component leads on scale; Two-Component leads on momentum.
Technology:
Technology segmentation reflects backbone chemistry choices that determine thermal envelope, elastic recovery, and regulatory compliance pathways.
- Silane-Terminated Polymer:Pure silane end-capped polyether backbones deliver elastic recovery above 300% tensile elongation alongside dielectric strength exceeding 15 kV/mm. China's NMPA battery safety standards and the EU's F-Gas Regulation accelerate procurement of these low-VOC systems.
- Epoxy Hybrid:Epoxy-silane combinations trade some flexibility for elevated temperature resistance and chemical inertness.
- Polyurethane Hybrid:Legacy polyurethane backbones with silane termination face REACH SVHC constraints on isocyanate content.
- Acrylic Hybrid:Acrylic-modified systems offer rapid green strength development for handling operations.
- Silicone Hybrid:Silicone-silane combinations extend operational temperature limits for extreme thermal management zones.
Silane-Terminated Polymer leads on scale; Epoxy Hybrid leads on momentum.
Application:
Application segmentation maps adhesive function to specific battery pack architectural elements with divergent performance certification requirements.
- Structural Bonding:Module-to-pack bonding applications eliminate welded joints and mechanical fasteners, cutting assembly labor while improving vibration damping. OEMs specify these systems under UN ECE R100 thermal runaway certification protocols that demand char integrity under direct flame impingement.
- Thermal Management:Thermal interface materials transfer heat between cells and cooling plates under compression.
- Battery Pack Sealing:Environmental sealing functions protect high-voltage architectures from moisture and particulate ingress.
- Electrical Insulation:Dielectric barrier applications prevent arcing across high-voltage bus configurations.
- Vibration Damping:Elastomeric layers absorb road-load and drivetrain oscillations transmitted to cell stacks.
Structural Bonding leads on scale; Thermal Management leads on momentum.
End User:
End user segmentation distinguishes procurement authority between specification-setting OEMs and execution-focused manufacturing tiers.
- OEMs:Vehicle manufacturers mandate adhesive performance validation under thermal runaway scenarios before supplier qualification, concentrating procurement authority with technical sourcing teams rather than commodity purchasing functions. Stuttgart and Shanghai platforms extend vendor onboarding timelines by 8-12 months through batch-level dielectric testing requirements.
- Battery Module Manufacturers:Cell-to-module assemblers execute OEM specifications at volume scale.
- Tier-1 Suppliers:System suppliers integrate adhesives into sub-assembly modules for OEM delivery.
- Battery System Integrators:Pack-level integrators coordinate multi-component sourcing for final assembly.
OEMs leads on scale; Battery Module Manufacturers leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized polymer chemists and adhesive formulation engineers cluster around Stuttgart, Shanghai, and Detroit, anchoring regional innovation hubs that feed tier-1 battery assembly operations.
Germany
OEM specification authority concentrates procurement decisions in Baden-Württemberg and Lower Saxony, where Mercedes-Benz and Volkswagen battery platforms demand validated thermal runaway performance. The EU F-Gas Regulation accelerates silane-terminated substitution for legacy polyurethane systems in cell-to-pack bonding. Henkel AG & Co. KGaA maintains deep specification relationships with Stuttgart-based automakers, while Sika AG integrates with Bavarian manufacturing corridors.
China
Cell production scale in Jiangsu and Fujian provinces drives volume consumption of moisture-curable one-component systems for module assembly lines. NMPA battery safety standards mandate adhesive performance validation under 800°C flame exposure, reformulating procurement specifications toward fire-resistant silane chemistries. CATL and BYD manufacturing clusters in Ningde and Shenzhen enforce batch-level dielectric testing certificates from adhesive suppliers.
United States
Battery plant construction in Ohio, South Carolina, and Michigan creates demand for zero-VOC formulations that bypass EPA emission limits without carbon capture infrastructure. State-level air quality enforcement in manufacturing zones prohibits solvent-borne dispensing, consolidating procurement with certified 100%-solid suppliers. Ford and GM battery assembly operations in the Midwest retain legacy polyurethane dispensing equipment, creating switching friction for silane system adoption.
South Korea
LG Energy Solution and Samsung SDI module manufacturers in Gyeonggi Province deploy silane-terminated polyether systems with secondary amine crosslinkers to eliminate nitrogen-purged dispensing booths. Korean battery producers cut facility capital expenditure by 40% while maintaining moisture-cure reliability in high-humidity assembly environments. The country's national chemical regulator enforces ionic purity standards for adhesives contacting ceramic electrolyte solid-state cell architectures.
India
Production-linked incentive schemes for cell and pack manufacturing in Gujarat and Tamil Nadu attract adhesive suppliers establishing toll-manufacturing partnerships with domestic chemical processors. Reliance and Ola Electric battery operations in Jamnagar and Krishnagiri specify hybrid silane-terminated systems for thermal management applications. BIS certification requirements for battery safety components extend supplier qualification timelines for imported formulations.
Hybrid Silane-Terminated Polymer Adhesives for EV Battery Pack Assembly Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the adhesive value chain, with integrated chemical conglomerates controlling polymer backbone supply while specialized formulators command specification relationships with OEMs. The market structure consolidates around three tiers: premium suppliers certified for structural bonding under crash-load conditions, mid-tier providers serving thermal management applications, and commodity-grade producers for non-critical sealing functions. Strategic archetypes include European OEM-integrated specialists, Asian volume-scale formulators, and diversified chemical majors with captive silane backbone production. Competitive moves center on qualification timeline compression and geographic toll-manufacturing partnerships to satisfy local content requirements in India and Southeast Asia.
Within the European OEM-integrated tier, Henkel AG & Co. KGaA and Sika AG exemplify specification-driven positioning anchored by deep automaker platform relationships. Dow occupies a distinct archetype as a diversified chemical major with proprietary polymer backbone capabilities. Among diversified industrials, 3M Company and H.B. Fuller Company represent North American-based suppliers with cross-sector adhesive portfolios that extend into battery assembly applications. These five entities collectively illustrate the competitive spectrum from pure-play automotive specialists to broad-based material science conglomerates competing for tier-1 procurement authority.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| 3M Company |
| Sika AG |
| H.B. Fuller Company |
| Bostik |
| Huntsman Corporation |
| Dow |
| BASF |
| ITW |
| Others |
Pricing and Supply Chain Analysis
EU F-Gas Regulation compliance gates both qualified supply and premium-tier pricing access for hybrid silane-terminated polymer adhesives, as formulators bearing certified low-VOC formulations capture specification authority with Stuttgart and Shanghai OEMs while commodity-grade suppliers face exclusion from structural bonding procurement cycles. Buyers consolidating volume with certified producers accept 15-25% price premiums for validated thermal runaway performance, compressing margins for undifferentiated alternatives.
Pricing Analysis
Bundled technical service and certification support separates premium-tier suppliers from unbundled commodity vendors in this market. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by UN ECE R100 validation status and dielectric testing rigor. Cost compression in standard-grade formulations is intensifying because Korean module manufacturers are consolidating procurement with zero-VOC certified suppliers. Battery module manufacturers exhibit highest price sensitivity due to OEM pass-through pressure, while German OEM technical sourcing teams prioritize performance validation over unit cost.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Shanghai anchor hub-and-spoke patterns for silane-terminated polymer feedstock delivery to battery assembly corridors. Manufacturing concentration centers on Germany, China, and South Korea for formulated adhesives, with captive silane backbone production concentrated in the US Gulf Coast and Belgium. Formulation draws from organotin catalysts concentrated in Southeast Asian chemical processing, organosilane intermediates from German and Japanese specialty chemical producers, and polyether polyols from Middle Eastern petrochemical complexes. Single-source vulnerability in tin-based catalyst supply exposes formulators to input rationing. Distribution runs through certified logistics partners handling temperature-sensitive moisture-cure systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where evolving UN ECE R100 thermal runaway certification protocols continuously elevate performance barriers and consolidate procurement authority with validated suppliers.
For Market Incumbents: Anchor specification relationships through accelerated UN ECE R100 validation timelines and captive organosilane backbone supply. Threat from epoxy-silane hybrid substitutes with elevated temperature resistance demands continuous R&D investment in elastic recovery retention. Backward integration into silane-terminated polyether production secures margin control against Southeast Asian catalyst volatility. For New Entrants and Emerging Players: The price-point gap between premium validated systems and economy-grade sealants creates entry space for mid-tier formulators targeting Indian PLI scheme localization requirements. Toll-manufacturing partnerships with Gujarat and Tamil Nadu chemical processors offer the most penetrable geography. Go-to-market through battery system integrators rather than direct OEM qualification compresses vendor onboarding timelines. For Investors and Strategic Acquirers: Roll-up economics work for regional formulators with validated OEM platform relationships because specification-driven procurement concentrates authority with technical sourcing teams rather than commodity purchasing functions. Target acquisition archetype: mid-tier European or Asian adhesive specialists with existing UN ECE R100 certification and regional toll-manufacturing infrastructure. Signal to watch is NMPA battery safety standard expansion beyond 800°C flame exposure protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silane Backbone Production | Captive supply of polyether polyols from Middle Eastern feedstock secures margin control against catalyst volatility. |
| UN ECE R100 Thermal Runaway Certification Investment | Validated char integrity under direct flame impingement gates specification access with Stuttgart OEM platforms. |
| India Toll-Manufacturing Partnership Formation | PLI scheme localization requirements in Gujarat and Tamil Nadu create first-mover advantage for qualified suppliers. |
| Zero-VOC Formulation Line Expansion | EPA emission limits in Ohio and South Carolina consolidate procurement with certified 100%-solid suppliers. |
| Solid-State Battery Ionic Purity Development | Sub-50 ppm sodium content adhesives open premium segments for Korean ceramic electrolyte cell architectures. |
Research Methodology
Coverage spans Germany, China, the United States, South Korea, and India, with primary inputs from each market cluster combining interviews with adhesive formulator R&D directors, OEM platform engineers, battery module procurement leads, and tier-1 supplier technical sourcing managers alongside secondary validation. Secondary sources include UN ECE R100 testing protocol documentation, EPA VOC emission enforcement records, EU F-Gas Regulation implementation guidance, and customs trade data for organosilane intermediate flows. Bottom-up volume modeling triangulates against top-down OEM battery production forecasts.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include cure mechanism architecture, backbone chemistry technology, application function, and end-user procurement authority tier, with additional industry-specific dimension of thermal runaway certification status. CAGRs derive from battery pack production ramp schedules and adhesive content-per-vehicle assumptions. Forecast inputs incorporate NMPA battery safety standard evolution timelines and solid-state battery commercialization pathways.
Caveats apply where UN ECE R100 protocol revisions, REACH SVHC list expansions, or organotin catalyst supply disruptions could materially shift the outlook. Forecasts reflect documented assumptions regarding OEM platform standardization rates and regional battery plant construction schedules. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.