
 Middle East & Africa Construction Adhesives & Sealants Market | 2026-2036
Middle East & Africa Construction Adhesives & Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East & Africa Construction Adhesives & Sealants Market Insights
Multi-source procurement among EPC contractors is shifting toward regional blending facilities that shorten lead times for cementitious and hybrid polymer systems. Sika AG leverages its Jeddah and Dubai manufacturing bases to sustain just-in-time delivery for façade contractors. BASF SE anchors technical service teams in Doha and Cairo to compete on specification support for polyurethane sealants. Dow differentiates through siliconized acrylic formulations tailored to Gulf humidity cycles.
Construction adhesives and sealants comprise formulated polymer systems—polyurethanes, silicones, epoxies, and hybrid silyl-modified polymers—engineered to bond dissimilar substrates and seal joints against moisture, air, and thermal movement, typically specified by elongation at break, Shore A hardness, and movement accommodation factor. Reactive adhesives dominate value pools in structural glazing and precast panel assembly where load-bearing performance commands premium positioning. Infrastructure projects represent the fastest-growing end-user category as Saudi NEOM, UAE Al Maktoum Airport expansion, and Egyptian new capital developments specify high-movement sealants for seismic and thermal cycling resistance.
SFDA and MOHAP chemical registration requirements in Saudi Arabia and the UAE mandate VOC disclosure and indoor air quality compliance for adhesives used in occupied buildings, steering formulation away from solvent-borne systems. Egypt's ECOA green building guidelines and South Africa's SANS 10400-XA energy efficiency standards extend similar constraints across North and Sub-Saharan Africa. Stakeholders must monitor how Gulf standardization bodies harmonize product certification with EU REACH-like substance restrictions to anticipate reformulation costs and qualification timelines.
Market Dynamics
Gulf megaproject pipelines are concentrating specification authority among a shrinking pool of EPC contractors, forcing adhesive suppliers to co-locate technical service teams near Riyadh, Dubai, and Cairo to secure just-in-time qualification.
Growth Catalysts
- Estidama Pearl Rating System:The UAE's green building framework mandates low-VOC materials in occupied structures, redirecting procurement toward water-borne and silyl-modified polymer formulations across commercial and healthcare verticals.
- NEOM and Red Sea giga-projects:Saudi Arabia's coastal developments specify high-movement structural sealants for seismic zones and thermal cycling resistance, concentrating demand for polyurethane and hybrid polymer systems.
- Hybrid polymer technology:Silyl-terminated polyether (STPE) and silyl-modified polyurethane (SMP) chemistries combine silicone weatherability with paintability, capturing specification share from conventional silicones in façade applications.
Market Restraints
- Petrochemical feedstock volatility:Polyol and isocyanate prices track crude oil and natural gas benchmarks, compressing margin visibility for formulators serving fixed-price EPC contracts.
- SFDA and MOHAP registration timelines:Saudi and Emirati chemical disclosure requirements extend product qualification cycles by 8-14 months for imported sealants, favoring regional blending facilities with established dossiers.
- Cementitious grout substitution:Cost-driven infrastructure contractors in Egypt and South Africa default to traditional mortar systems for non-structural bonding, limiting adhesive penetration in mass housing.
Strategic Opportunities
- Egyptian new capital developments:Administrative city construction outside Cairo creates first-mover advantage for suppliers establishing local blending capacity ahead of import tariff adjustments.
- Modular and prefabricated construction:Off-site panel manufacturing demands factory-applied structural adhesives with controlled cure profiles, opening specification channels distinct from field-applied sealants.
- SANS 10400-XA energy efficiency compliance:South Africa's building envelope standards drive demand for air-tight sealant systems in climate zones with high heating and cooling loads.
Industry Challenges
- Formulation chemist scarcity:Gulf-based manufacturers compete for polymer scientists capable of customizing hybrid systems for extreme humidity and salt-air exposure.
- Multi-jurisdiction certification burden:Suppliers serving both Saudi SFDA and UAE MOHAP must maintain parallel technical dossiers with divergent VOC testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East & Africa Construction Adhesives & Sealants Market |
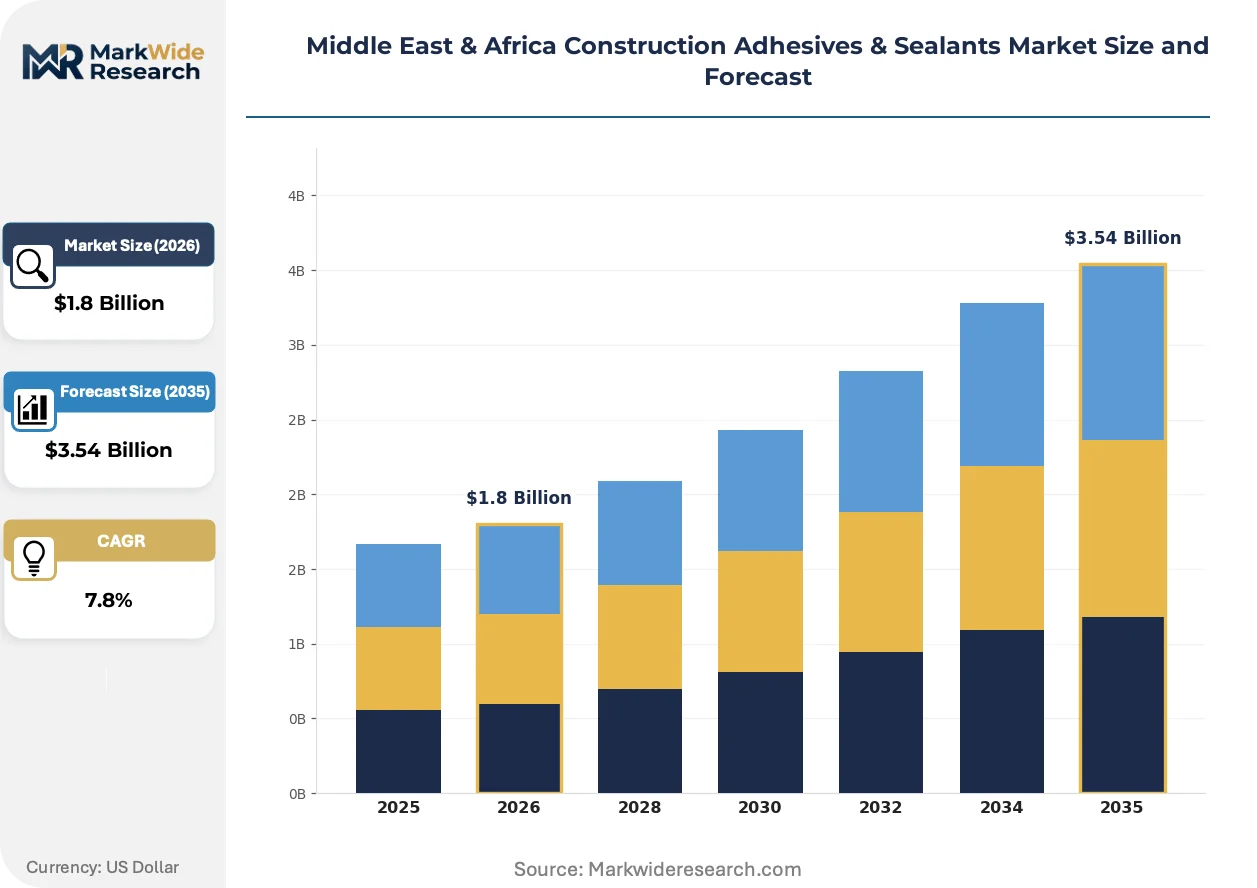
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.54 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reactive Adhesives, Pressure-Sensitive Adhesives, Construction Sealants, Epoxy Adhesives Application: Flooring, Wall Covering, Roofing, Insulation End User: Residential Buildings, Commercial Properties, Infrastructure Projects, Industrial Facilities Distribution Channel: Direct Sales, Online Retail, Distributors, Specialty Stores |
| Companies Covered | Henkel AG & Co. KGaA, Sika AG, Dow, Arkema, H.B. Fuller Company, BASF SE, 3M Company, Wacker Chemie AG, MAPEI S.p.A., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East & Africa Construction Adhesives & Sealants Market Trends and Innovations
Reactive adhesive platforms are displacing mechanical fasteners across structural glazing and precast assembly, while regulatory disclosure requirements accelerate regional formulation capabilities.
Hybrid silyl-modified polymers are consolidating specification share in high-movement façade joints. STPE and SMP chemistries bond dissimilar substrates—aluminum, concrete, coated glass—without primers. Façade contractors in Dubai and Riyadh specify these systems for 50-year durability warranties. The technology is consolidating supplier margins by reducing callback liability and enabling single-source warranty coverage.
SFDA chemical registration mandates now parallel EU REACH substance disclosure thresholds for adhesives used in occupied Saudi buildings. The regulation forces reformulation away from certain phthalate plasticizers and tin catalysts. Healthcare and education verticals face the steepest compliance timelines, with project specifications beginning to exclude non-registered products from Q3 2024 tender cycles.
Multi-source procurement among EPC contractors is fragmenting into regional blending partnerships. Contractors now qualify local facilities in Jeddah, Dubai, and Cairo for just-in-time cementitious and hybrid polymer supply. Infrastructure megaprojects in Saudi Arabia and the UAE drive this pattern most visibly, where 72-hour lead time requirements exclude European and Asian import supply chains.
Middle East & Africa Construction Adhesives & Sealants Market Segmentation
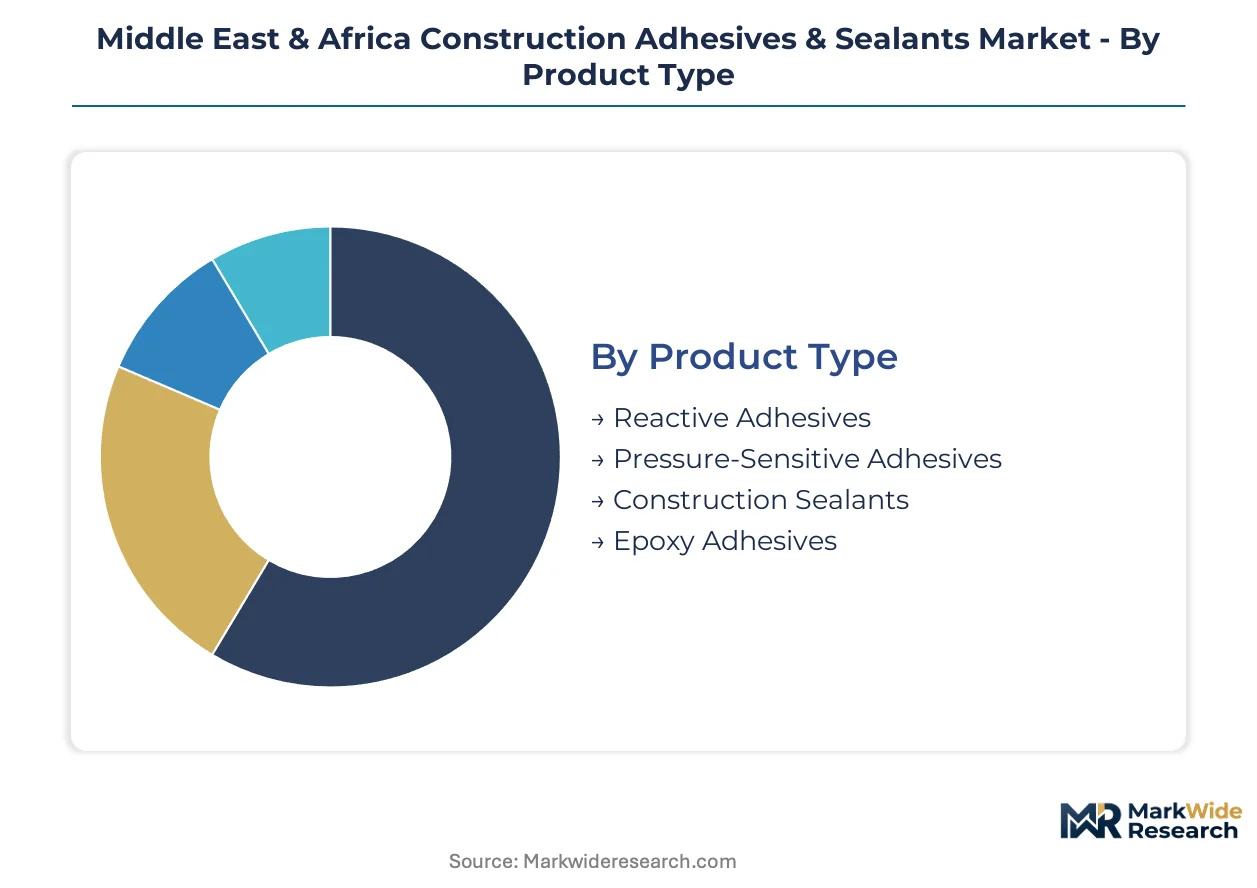
Product specification authority in Middle East & Africa construction adhesives concentrates among EPC contractors managing giga-project timelines. Segmentation reveals how certification requirements, substrate compatibility, and procurement channels reshape competitive positioning across reactive, sealant, and pressure-sensitive platforms.
Product Type:
SFDA and MOHAP chemical registration requirements in Saudi Arabia and the UAE impose divergent VOC disclosure thresholds across adhesive chemistries, with reactive systems facing the steepest compliance timelines for indoor air quality certification.
- Reactive Adhesives:Two-component polyurethane and epoxy systems cure through chemical reaction to deliver structural load-bearing capacity. NEOM and Red Sea coastal developments specify these for precast panel assembly and structural glazing where 50-year durability warranties are mandatory. SFDA registration timelines extend 8-14 months for imported formulations, favoring regional blending facilities with established dossiers.
- Construction Sealants:Single-component moisture-cure silicones, polyurethanes, and hybrid silyl-modified polymers accommodate joint movement while sealing against Gulf humidity and salt-air exposure. Façade contractors in Dubai and Riyadh specify high-movement grades for thermal cycling resistance in curtain wall applications. Estidama Pearl Rating System mandates steer procurement toward low-VOC water-borne and STPE formulations in occupied commercial and healthcare structures.
- Pressure-Sensitive Adhesives:Solvent-free acrylic and rubber-based tapes bond flooring membranes and temporary protection sheets without cure time.
- Epoxy Adhesives:Rigid two-component systems anchor rebar and repair concrete spalls in infrastructure rehabilitation.
Construction Sealants sits at the top of the volume ranking, with Reactive Adhesives climbing the fastest.
Application:
Substrate exposure conditions and warranty terms fragment specification across vertical building envelopes, with coastal humidity and seismic zones demanding distinct movement accommodation factors.
- Flooring:Moisture-cure polyurethanes and pressure-sensitive tapes bond vinyl, carpet, and ceramic tile across commercial and residential developments. Egyptian new capital construction specifies rapid-cure systems to compress installation schedules for administrative buildings.
- Roofing:Liquid-applied polyurethane and silicone membranes seal flat roofs against Gulf thermal extremes and sporadic rainfall. SANS 10400-XA energy efficiency compliance in South Africa drives air-tight specification for climate zones with high cooling loads.
- Wall Covering:Heavy-duty pastes and dispersion adhesives bond interior finishes in hospitality and healthcare verticals.
- Insulation:Spray polyurethane foam and board adhesives secure thermal barriers to concrete and masonry substrates.
Flooring commands the largest installed base, while Roofing gains specification share fastest on green building envelope mandates.
End User:
Project scale and specification authority determine whether procurement flows through EPC contractors with technical service requirements or fragmented subcontractor channels.
- Infrastructure Projects:Megaprojects including NEOM, UAE Al Maktoum Airport expansion, and Egyptian new capital developments concentrate demand for high-movement structural sealants. 72-hour lead time requirements exclude European and Asian import supply chains, favoring regional blending partnerships in Jeddah, Dubai, and Cairo.
- Commercial Properties:Office, retail, and hospitality construction under Estidama and ECOA green building codes mandate low-VOC formulations. Healthcare and education verticals face the steepest SFDA compliance timelines, with specifications excluding non-registered products from tender cycles.
- Residential Buildings:Mass housing in Egypt and South Africa defaults to cost-driven cementitious grout substitution for non-structural bonding.
- Industrial Facilities:Chemical-resistant epoxy and polyurethane systems protect processing floors and containment areas.
Infrastructure Projects anchor premium specification value, with Commercial Properties expanding most quickly on regulatory compliance deadlines.
Distribution Channel:
Lead time compression and technical qualification requirements are restructuring channel economics toward localized blending and direct EPC relationships.
- Distributors:Regional stockists in Jeddah, Dubai, and Cairo aggregate cementitious and hybrid polymer supply for just-in-time delivery to megaproject sites. Multi-source procurement patterns fragment into blending partnerships that shorten logistics cycles.
- Direct Sales:Sika AG and BASF SE anchor technical service teams in Doha and Cairo to compete on specification support for polyurethane sealants and reactive adhesives. Direct relationships secure qualification ahead of fixed-price EPC contract awards.
- Online Retail:E-commerce platforms serve maintenance, repair, and small contractor segments with standardized commodity formulations.
- Specialty Stores:Professional trade outlets stock application equipment and consumables for field-applied sealants.
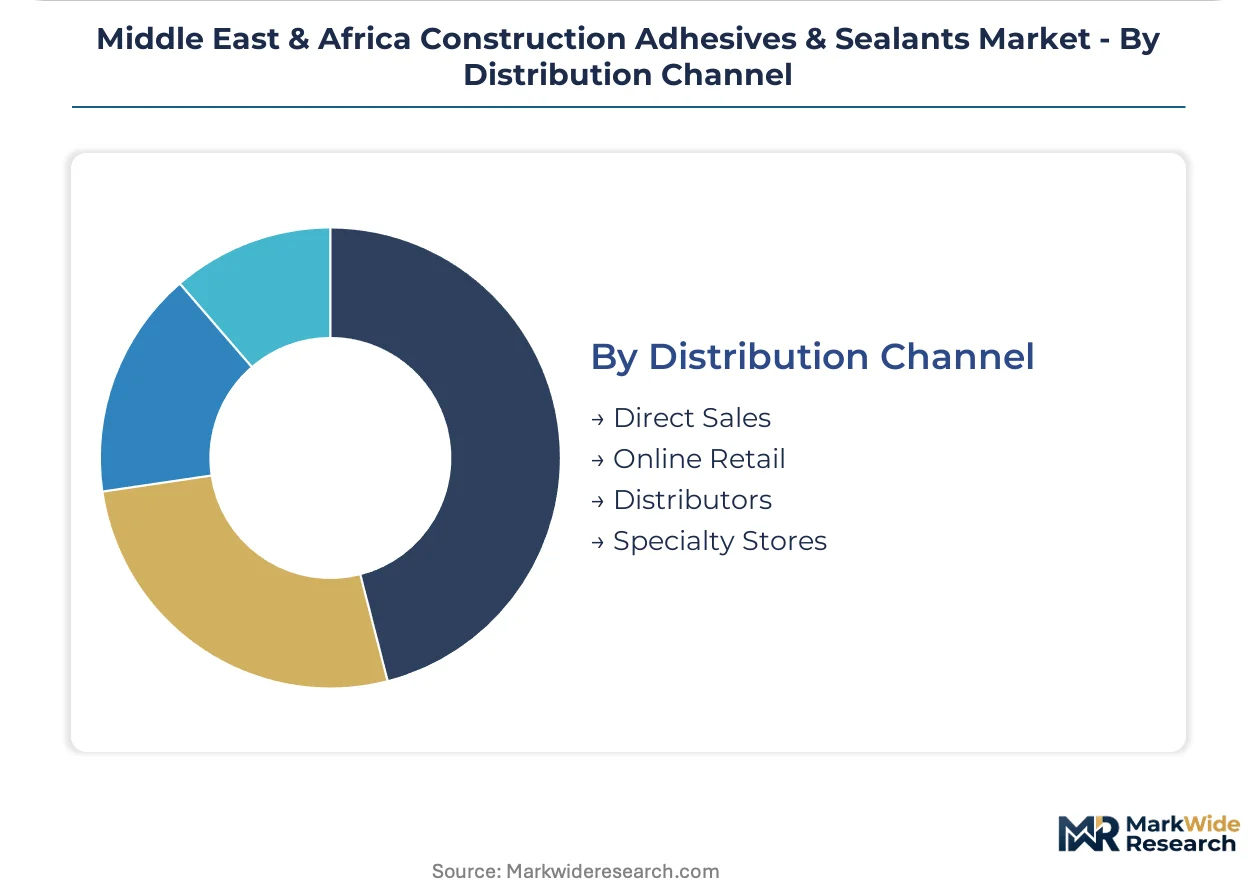
Distributors retain the deepest volume footprint, with Direct Sales gaining share fastest on technical service co-location mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gulf Cooperation Council construction corridors concentrate specification demand for high-performance bonding systems. Megaproject pipelines across Saudi Arabia and the UAE redirect procurement toward regional blending facilities. Egyptian and South African markets follow distinct regulatory and cost-driven trajectories.
Saudi Arabia
NEOM and Red Sea coastal developments concentrate demand for structural sealants with seismic resistance specifications. SFDA chemical registration mandates parallel EU REACH substance disclosure thresholds for adhesives used in occupied buildings. Riyadh and the Western Region anchor blending capacity expansion to serve 72-hour lead time requirements for giga-project contractors.
United Arab Emirates
Dubai's façade contractor ecosystem specifies hybrid silyl-modified polymers for 50-year durability warranties on curtain wall applications. MOHAP indoor air quality compliance steers procurement toward low-VOC water-borne formulations under the Estidama Pearl Rating System. Jebel Ali and Dubai Industrial City host manufacturing bases supplying just-in-time delivery to megaproject sites.
Egypt
New capital administrative city construction creates concentrated demand for rapid-cure flooring adhesives in compressed installation schedules. ECOA green building guidelines extend VOC constraints across commercial and healthcare verticals. Cairo periphery developments attract regional suppliers establishing local blending capacity ahead of anticipated import tariff adjustments.
South Africa
Building envelope retrofit programs drive specification of air-tight sealant systems in climate zones with high heating and cooling loads. SANS 10400-XA energy efficiency standards mandate thermal barrier performance in residential and commercial construction. Gauteng and Western Cape provinces concentrate distributor networks serving cost-sensitive mass housing segments.
Qatar
World Cup legacy infrastructure maintenance sustains demand for high-movement joint sealants in stadium and transportation assets. Local content requirements in public procurement favor suppliers with established Gulf manufacturing footprints. Doha technical service teams from multinational formulators compete on specification support for polyurethane systems.
Middle East & Africa Construction Adhesives & Sealants Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue regional blending partnerships to compress lead times for cementitious and hybrid polymer systems. Market structure concentrates specification authority among EPC contractors managing giga-project timelines, forcing adhesive suppliers to co-locate technical service capabilities near project clusters. Three archetypes dominate: multinational chemical conglomerates with Gulf manufacturing bases, regional blending specialists serving just-in-time procurement, and construction-focused formulators with façade application expertise. Competitive dynamics center on qualification speed and registration dossier depth rather than price alone.
Among multinational chemical suppliers, Sika AG, BASF SE, and Dow exemplify distinct positioning strategies within the regional market. Sika AG leverages established manufacturing infrastructure to sustain proximity-based delivery models. BASF SE anchors technical service presence to compete on specification support capabilities. Dow differentiates through formulation chemistry tailored to regional environmental exposure conditions. These three represent how global players adapt organizational footprints to Gulf procurement patterns without altering core technology platforms.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Sika AG |
| Dow |
| Arkema |
| H.B. Fuller Company |
| BASF SE |
| 3M Company |
| Wacker Chemie AG |
| MAPEI S.p.A. |
| Others |
Pricing and Supply Chain Analysis
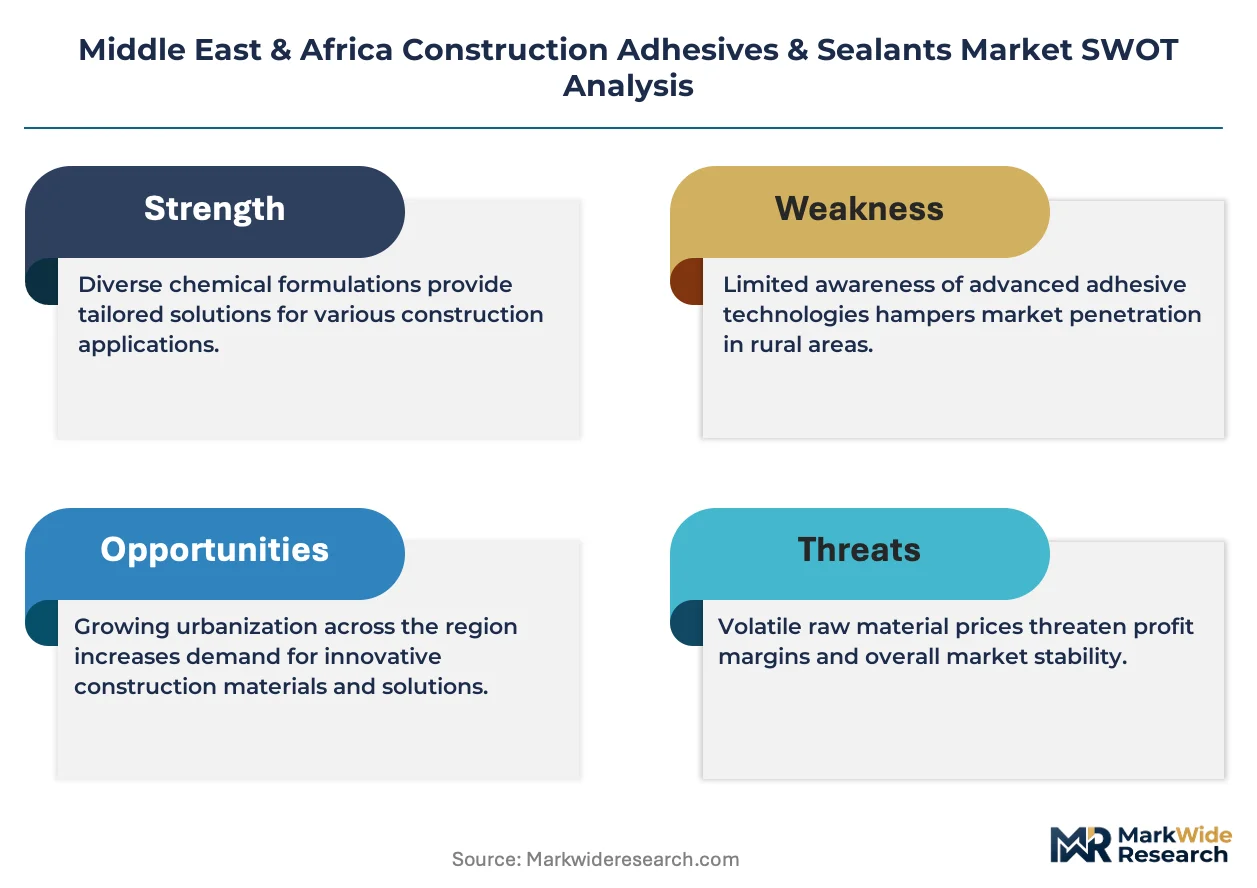
Estidama Pearl Rating System compliance gates qualified supply access and premium-tier pricing power across UAE commercial construction. SFDA registration timelines in Saudi Arabia concentrate procurement among regional blenders with established dossiers, compressing margin visibility for import-dependent formulators serving fixed-price EPC contracts.
Pricing Analysis
Petrochemical feedstock pass-through from crude oil and natural gas benchmarks shapes contract pricing for polyurethane and hybrid polymer systems. Three-tier pricing structure across premium, standard, and economy levels separates SFDA-registered structural sealants from commodity water-borne formulations and unregistered imports. Cost compression in economy tiers intensifies because Egyptian and South African mass housing contractors default to cementitious grout substitution. Infrastructure EPC contractors show least price sensitivity due to warranty and lead time requirements, while residential subcontractors in North Africa exhibit highest sensitivity to per-kilogram differentials.
Supply Chain Analysis
Reverse-logistics flows for unused sealant returns and expired product refurbishment remain underdeveloped across Gulf construction corridors, creating working capital inefficiencies for distributors. Manufacturing concentrates in Saudi Arabia, the UAE, and Egypt, with polyol and isocyanate feedstocks drawing from Asian petrochemical complexes. Single-source vulnerability characterizes specialty tin catalyst and silyl-terminated polyether resin supply. Distribution runs through Jeddah, Dubai, and Cairo blending hubs serving just-in-time megaproject requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where Egyptian and South African cost structures undercut Gulf premium pricing by 30-40% on comparable water-borne formulations, creating margin capture opportunities for regional blenders with multi-plant footprints.
For Market Incumbents: To counter formulation chemist scarcity across Gulf manufacturing bases, anchor technical service teams in Riyadh and Cairo to accelerate qualification cycles ahead of competitor dossier submissions. Backward integration into captive silyl-modified polymer resin production reduces exposure to Asian specialty chemical supply disruptions.
For New Entrants and Emerging Players: The 40% price-point gap between premium SFDA-registered structural sealants and economy cementitious grouts in Egyptian mass housing creates white-space opportunity for rapid-cure hybrid polymer systems. Target South African building envelope retrofit programs where SANS 10400-XA compliance mandates air-tight specification absent established local supply. Partner with Cairo-periphery distributors to bypass import tariff exposure on European formulations.
For Investors and Strategic Acquirers: Roll-up economics work for regional blending specialists with established SFDA/MOHAP dossiers because registration timelines create 14-month competitive moats against new import qualification. Mid-cap targets with Jeddah or Dubai manufacturing footprints and healthcare vertical certification offer strongest 5-10 year viability. Monitor Gulf standardization body harmonization announcements with EU REACH-like substance restrictions as inflection signal for reformulation capex requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Regional Blending Capacity Expansion | Jeddah and Dubai facilities compress lead times to 72 hours for NEOM contractors. |
| SFDA Registration Dossier Investment | Established chemical disclosure files accelerate qualification ahead of Q3 tender exclusions. |
| Hybrid Polymer Technology Licensing | STPE and SMP chemistries capture 50-year warranty specification from conventional silicones. |
| Technical Service Team Co-location | Doha and Cairo presence secures EPC contractor relationships before contract awards. |
| Backward Integration into Resin Supply | Captive silyl-terminated polyether production reduces Asian import dependency and margin volatility. |
Research Methodology
Direct dialogue with EPC procurement directors, formulation chemists at regional manufacturers, façade contractor technical leads, and SFDA registration consultants grounded qualitative findings in operational reality. Secondary validation drew from customs trade data on polyol and isocyanate imports, Saudi Standards, Metrology and Quality Organization bulletins, and UAE Ministry of Health and Prevention chemical disclosure filings. Bottom-up project pipeline tracking across NEOM, Al Maktoum Airport expansion, and Egyptian new capital developments triangulated with top-down petrochemical feedstock demand modeling.
Bottom-up segmentation analysis across reactive adhesives, construction sealants, pressure-sensitive tapes, and epoxy systems combined with end-user splits between infrastructure, commercial, residential, and industrial verticals. Application dimensions spanned flooring, roofing, wall covering, and insulation with regional production hub clustering. CAGRs derived from project award velocity, green building code implementation timelines, and import substitution patterns across the analysis window. Feedstock price elasticity and registration timeline probability distributions informed scenario-weighted outputs.
Caveats apply where SFDA-MOHAP harmonization delays or Egyptian tariff regime adjustments could materially shift the outlook for regional blending economics. Practitioners should monitor Gulf Cooperation Council standardization body announcements and Egyptian Ministry of Finance import duty consultations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
South America Sealants Market
Adhesives & Sealants
Wearable Skin Adhesives Market
Adhesives & Sealants
Asia-Pacific Construction Adhesives and Sealants Market
Adhesives & Sealants
Europe Adhesives and Sealants Market
Adhesives & Sealants
Co-Polymer Sealants Market
Adhesives & Sealants
Flock Binder Market
Adhesives & Sealants
India Waterproofing Solutions Market
Adhesives & Sealants
Floor Adhesive Market
Adhesives & Sealants
Solvent-Borne Adhesives Market
Adhesives & Sealants
Emulsion Pressure Sensitive Adhesives Market
Adhesives & Sealants
Metal Bonding Adhesives Market
Adhesives & Sealants
Global Isononyl Acrylate Market
Adhesives & Sealants
Middle-East and Africa Hot-Melt Adhesives Market
Adhesives & Sealants
Europe Sealants Market
Adhesives & Sealants
North America Adhesives and Sealants Market
Adhesives & Sealants
Italy Adhesives Market