
 Tissue Sealants and Tissue Adhesive Market | 2026-2036
Tissue Sealants and Tissue Adhesive Market Size, Share, and Industry Trends Forecast 2026-2036
Tissue Sealants and Tissue Adhesive Market Outlook
Surgical-grade biocompatibility certification is rotating toward the center of procurement decisions in developed health systems. Baxter International Inc. leverages its plasma-derived fibrin platform to sustain supply relationships with major hospital networks. Johnson & Johnson anchors its position through broad surgical portfolio integration across wound closure and hemostasis. CryoLife specializes in cryopreserved biologic adhesives for cardiac and vascular reconstruction, occupying a defensible niche in specialized surgical theaters.
Tissue sealants and tissue adhesives comprise biologic and synthetic formulations engineered to achieve hemostasis, tissue approximation, or barrier function through polymerization, fibrin clot formation, or synthetic cross-linking, with activation times typically ranging from seconds to minutes depending on composition and pH environment. Their primary commercial purpose centers on reducing operative time, minimizing suture-related trauma, and improving wound healing outcomes across inpatient and ambulatory surgical settings. Fibrin sealants command the deepest clinical validation and established reimbursement pathways, while synthetic adhesives represent the fastest-expanding formulation class as manufacturers engineer cyanoacrylate and polyethylene glycol variants with tunable degradation profiles. Hospitals remain the dominant end-user channel by volume, though ambulatory surgical centers are capturing disproportionate growth as procedure migration accelerates.
The FDA regulates these products through distinct pathways for biologics, devices, and combination products, creating compliance complexity that favors established manufacturers with dedicated regulatory affairs infrastructure. The EU Medical Device Regulation and REACH chemical safety standards impose additional biocompatibility and traceability requirements on synthetic adhesive components sold in European markets. Health Canada and the Pharmaceuticals and Medical Devices Agency in Japan maintain parallel but non-harmonized review frameworks that delay market entry for novel formulations. Stakeholders must monitor evolving reimbursement thresholds for sealant-assisted procedures versus conventional closure methods, as payer policy will determine commercial viability more than technical performance alone.
Market Dynamics
Integrated delivery networks in the United States are consolidating surgical supply procurement around biocompatibility certification tiers, compressing vendor margins while elevating compliance infrastructure requirements for sealant manufacturers.
Growth Catalysts
- FDA Hemostatic Reclassification:The agency's updated guidance on biologic-device combination products is accelerating portfolio revalidation investments among established manufacturers.
- Minimally Invasive Surgery Expansion:General surgery departments are standardizing fibrin sealant protocols for laparoscopic procedures, creating volume pull-through for adjacent adhesive formulations.
- Cyanoacrylate Engineering:Tunable degradation profiles in synthetic adhesives are opening reimbursement pathways previously reserved for biologic sealants.
Market Restraints
- Plasma Supply Concentration:Fibrin sealant production depends on concentrated plasma fractionation capacity, with supply vulnerability concentrated in North American collection networks.
- REACH Compliance Burden:The EU's chemical safety standards impose traceability requirements on polyethylene glycol components that extend European market entry timelines.
- Suture Substitution Economics:Conventional mechanical closure maintains cost advantage in price-sensitive hospital segments, limiting sealant penetration in emergent markets.
Strategic Opportunities
- Ambulatory Surgical Center Channel:Procedure migration to outpatient settings creates demand for rapid-setting adhesive formulations with simplified application protocols.
- Cardiac Reconstruction Specialization:Cryopreserved biologic adhesives command premium positioning in thoracic surgery suites where tissue integration performance outweighs cost considerations.
- Japan PMDA Harmonization:Convergence review pathways with FDA standards are reducing redundant clinical trial requirements for novel synthetic formulations.
Industry Challenges
- Regulatory Affairs Talent Scarcity:Combination product expertise spanning biologics and device pathways commands premium compensation, constraining mid-tier manufacturer expansion.
- Biocompatibility Testing Backlogs:ISO 10993 cytotoxicity validation queues at contracted laboratories are extending product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tissue Sealants and Tissue Adhesive Market |
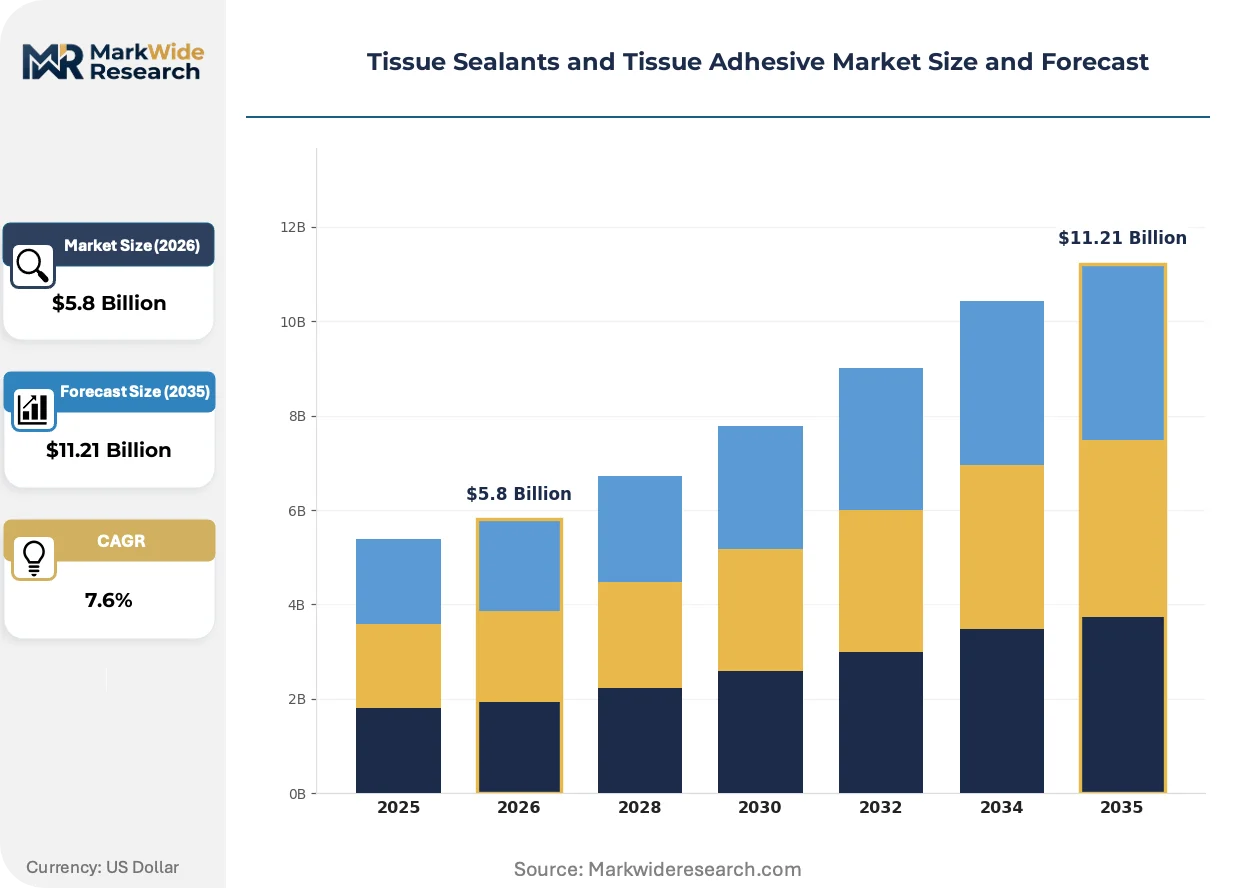
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.21 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologic Sealants, Synthetic Adhesives, Tissue Adhesives, Fibrin Sealants End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions Formulation Type: Aqueous Formulations, Spray Formulations, Gel Formulations, Solid Formulations Application Area: Wound Closure, Surgical Procedures, Trauma Treatment, Cosmetic Surgery |
| Companies Covered | Baxter International Inc., Johnson & Johnson, Integra LifeSciences Corporation, CryoLife, C.R. Bard, B. Braun Melsungen AG, Smith & Nephew, Luna Innovations Incorporated, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tissue Sealants and Tissue Adhesive Market Strategic Shifts
Synthetic adhesive platforms are engineering performance parity with biologic sealants while compressing manufacturing complexity, reshaping competitive positioning across hospital procurement tiers.
Polyethylene glycol-based synthetic sealants is supplanting fibrin formulations in abdominal closure applications where degradation kinetics favor predictable absorption profiles. Ambulatory surgical centers are adopting these formulations at accelerated rates due to reduced cold-chain requirements. The shift is compressing margin structures for plasma-derived product lines while expanding addressable procedure volumes.
REACH chemical safety standards are mandating expanded toxicological dossiers for cyanoacrylate monomers used in tissue adhesive formulations. Manufacturers are reformulating compositions to eliminate residual formaldehyde precursors. European market entrants face extended notification timelines, advantaging incumbents with established substance registrations.
Centralized procurement contracts are displacing decentralized hospital purchasing autonomy across United States integrated delivery networks. Supply agreements now bundle sealant categories with broader wound closure portfolios, compressing standalone vendor access. This concentration is most visible in multi-hospital systems negotiating three-year surgical supply commitments.
Tissue Sealants and Tissue Adhesive Market Segmentation
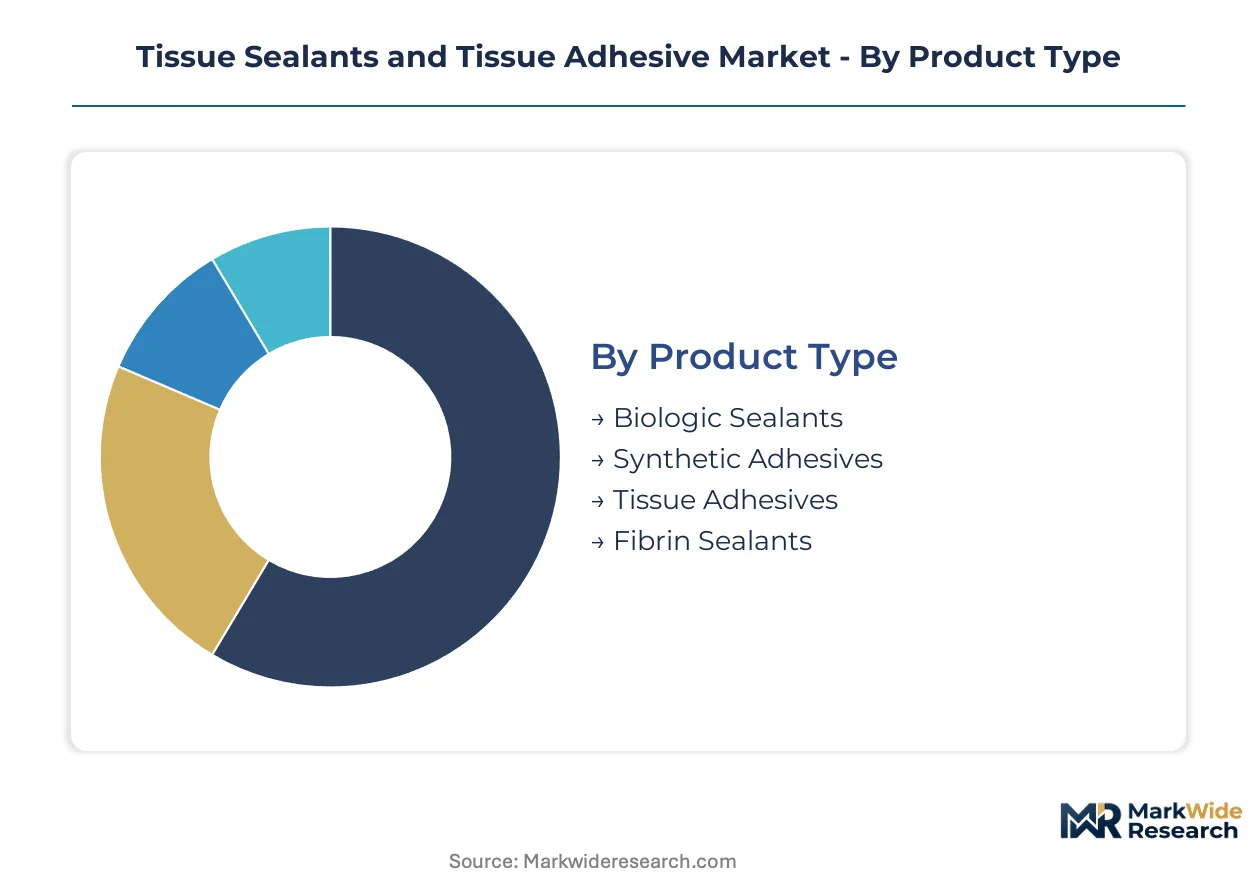
Tissue sealants and tissue adhesives fragment across formulation chemistry, delivery mechanism, and care setting economics. Procurement patterns diverge sharply between capital-intensive hospital systems and volume-driven ambulatory channels, reshaping how manufacturers configure product portfolios and pricing architectures.
Product Type:
Margin pools concentrate in biologic formulations where plasma fractionation creates supply scarcity and pricing power, while synthetic platforms compete on manufacturing scalability.
- Fibrin Sealants:These plasma-derived formulations leverage thrombin and fibrinogen clotting cascades to achieve hemostasis within seconds of application. United States hospital networks prioritize fibrin sealants for cardiac and vascular reconstruction where tissue integration performance justifies premium positioning.
- Synthetic Adhesives:Cyanoacrylate and polyethylene glycol variants offer tunable degradation kinetics without cold-chain dependencies. Ambulatory surgical centers in Germany and Japan are adopting these formulations fastest as procedure migration accelerates and reimbursement pathways mature for synthetic-assisted closures.
- Biologic Sealants:Collagen-based and albumin-crosslinked alternatives serve niche applications where religious or clinical contraindications restrict fibrin use.
- Tissue Adhesives:Medical-grade cyanoacrylates dominate superficial wound closure with instant polymerization properties suited for emergency department throughput demands.
The dominant share belongs to Fibrin Sealants, while Synthetic Adhesives is closing the gap fastest.
End User:
Volume concentration tracks procedure migration patterns, with procurement autonomy shifting from individual surgeons toward centralized supply committees.
- Hospitals:Integrated delivery networks in the United States negotiate multi-year surgical supply bundles spanning sealants, sutures, and staplers. General surgery departments drive fibrin sealant standardization for laparoscopic protocols.
- Ambulatory Surgical Centers:Outpatient facilities in Texas, Florida, and California prioritize rapid-setting synthetic formulations with simplified application training. Reduced cold-chain requirements compress operational overhead.
- Specialty Clinics:Dermatology and ophthalmology practices in South Korea and Switzerland utilize precision applicator systems for cosmetic and microsurgical applications.
- Research Institutions:Academic medical centers in Massachusetts and Basel conduct comparative effectiveness trials that shape future reimbursement determinations.
Hospitals retain the volume anchor position, though Ambulatory Surgical Centers is expanding its share most steeply.
Formulation Type:
Delivery mechanism selection correlates with procedure invasiveness and operative field access constraints.
- Spray Formulations:Aerosolized delivery systems achieve uniform coverage across large surface areas in thoracic and abdominal procedures. United States trauma centers deploy spray fibrin sealants for rapid hemostasis in penetrating injury protocols.
- Gel Formulations:Viscous consistencies maintain position in confined anatomical spaces during spinal and neurological surgeries. Japanese manufacturers engineer gel adhesives with pH-responsive setting times tailored to specific tissue environments.
- Aqueous Formulations:Low-viscosity solutions penetrate porous tissue structures in dental and otolaryngology applications.
- Solid Formulations:Pre-formed sheets and patches serve barrier functions in dural and pleural reconstruction where mechanical strength requirements exceed liquid adhesive capabilities.
Spray Formulations commands the installed base, yet Gel Formulations is gaining adoption velocity fastest in specialized surgical theaters.
Application Area:
Clinical validation depth and reimbursement density vary substantially across procedure categories.
- Surgical Procedures:Minimally invasive techniques in German and United States hospital systems standardize sealant protocols for laparoscopic cholecystectomy and hernia repair. Fibrin sealants reduce operative time and conversion rates to open procedures.
- Wound Closure:Emergency departments in Australia and Canada deploy tissue adhesives for pediatric laceration repair, eliminating needle trauma and reducing parental anxiety. Cyanoacrylate formulations achieve cosmetic outcomes comparable to sutures for linear wounds under tension.
- Trauma Treatment:Military medical research programs in the United States and Israel accelerate hemostatic dressing development for battlefield hemorrhage control.
- Cosmetic Surgery:Aesthetic clinics in Brazil and South Korea utilize biologic sealants to minimize scarring in rhinoplasty and blepharoplasty procedures where patient satisfaction metrics drive referral economics.
Surgical Procedures maintains the revenue core, while Wound Closure is scaling fastest as emergency medicine protocols disseminate globally.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of plasma-derived fibrin sealants concentrate in North American fractionation networks, while European and Asian markets absorb synthetic adhesive imports to bypass cold-chain dependencies. Trade balances tilt toward deficit in Japan and South Korea, where domestic biologics capacity lags surgical demand expansion.
United States
Integrated delivery networks in Texas and Florida drive fibrin sealant procurement through centralized surgical supply contracts. FDA guidance on biologic-device combination products is accelerating portfolio revalidation timelines for manufacturers serving hospital networks. The Greater Boston corridor anchors academic medical center demand for cryopreserved biologic adhesives in cardiac reconstruction protocols.
Germany
Ambulatory surgical centers in Bavaria and Baden-Württemberg are adopting polyethylene glycol sealants fastest among European markets. REACH compliance requirements for cyanoacrylate monomers are extending notification timelines for new synthetic formulations entering the EU. The Rhine-Main industrial cluster concentrates sterile adhesive manufacturing capacity serving Central European hospital networks.
Japan
PMDA convergence with FDA review standards is reducing redundant clinical trial requirements for novel synthetic sealants entering the market. Gel formulation demand concentrates in Tokyo and Osaka surgical theaters where pH-responsive setting times match specific tissue environments. Domestic production of fibrin sealants remains insufficient, creating import dependence on North American plasma fractionators.
China
Minimally invasive surgery expansion in Shanghai and Beijing hospital systems is standardizing sealant protocols for laparoscopic procedures. NMPA biocompatibility certification requirements are elevating compliance infrastructure investments for market entrants. The Yangtze River Delta cluster concentrates domestic manufacturing of cyanoacrylate tissue adhesives for wound closure applications.
Brazil
Cosmetic surgery clinics in São Paulo and Rio de Janeiro utilize biologic sealants for rhinoplasty and blepharoplasty procedures where patient satisfaction metrics drive referral economics. ANVISA regulatory pathways for biologic-device combination products lag FDA timelines, delaying novel formulation market entry. The Southeast region anchors surgical supply distribution networks serving Latin American export markets.
Tissue Sealants and Tissue Adhesive Market Competitive Environment
Listed leaders compete with private specialists across regulatory compliance infrastructure, where public company scale advantages clash with private specialist agility in niche surgical applications. The market structure tilts toward consolidation among plasma-derived fibrin sealant producers, while synthetic adhesive segments retain fragmentation due to lower capital barriers. Three archetypes dominate: diversified medical device conglomerates with broad surgical portfolios, plasma fractionation specialists with captive biologics supply, and synthetic chemistry houses engineering tunable polymer platforms. Competitive moves center on M&A activity to secure plasma collection networks and strategic partnerships to accelerate regulatory harmonization across FDA, EMA, and PMDA pathways.
Within the diversified conglomerate tier, Baxter International Inc. and Johnson & Johnson occupy positions exemplifying broad surgical portfolio integration. CryoLife represents the specialized biologics archetype, with its name signaling cryopreserved tissue engineering focus. These three companies anchor competitive dynamics across hospital procurement tiers, with their distinct positioning reflecting divergent bets on biologic versus synthetic formulation dominance in minimally invasive surgery expansion.
| Leading Market Players |
|---|
| Baxter International Inc. |
| Johnson & Johnson |
| Integra LifeSciences Corporation |
| CryoLife |
| C.R. Bard |
| B. Braun Melsungen AG |
| Smith & Nephew |
| Luna Innovations Incorporated |
| Medtronic |
| Others |
Value Chain & Pricing Dynamics
Plasma fractionation scale economies in North America create dual concentration effects: supply scarcity elevates fibrin sealant price floors while synthetic adhesive manufacturers exploit manufacturing scalability to compress margins at the mid-tier. Integrated delivery networks in the United States leverage procurement volume to extract tiered concessions, forcing biologic suppliers to defend premium positioning through clinical validation investments.
Pricing Analysis
Hospital procurement committees anchor pricing stratification across premium, standard, and economy certification tiers. Price differentiation stems from biocompatibility grade (ISO 10993 cytotoxicity tier) and cold-chain logistics burden. Cost compression in synthetic segments is intensifying because polyethylene glycol manufacturers achieve formulation parity with reduced production complexity. Ambulatory surgical centers exhibit highest price sensitivity due to reimbursement rate constraints, while cardiac surgery suites in academic medical centers demonstrate lowest sensitivity where tissue integration performance dominates procurement criteria.
Supply Chain Analysis
The United States and Germany anchor plasma fractionation capacity for fibrin sealant production, while China and South Korea concentrate cyanoacrylate monomer synthesis for tissue adhesives. Raw material dependencies include human plasma collections, thrombin concentrates, and medical-grade polyethylene glycol polymers. Single-source vulnerability concentrates in North American plasma collection networks subject to donor availability fluctuations. Distribution runs through integrated delivery network centralized procurement contracts displacing hospital-level purchasing autonomy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through integrated delivery network procurement consolidation, compressing vendor margins while elevating compliance infrastructure requirements for sealant manufacturers.
For Market Incumbents: Consolidate plasma collection network control through captive supply agreements or fractionation capacity acquisitions to defend fibrin sealant margin structures against synthetic substitution. Deepen ISO 10993 biocompatibility certification investments to maintain premium tier access as procurement committees standardize compliance scorecards. Channel control through multi-year surgical supply bundles spanning sealants, sutures, and staplers creates switching cost barriers against standalone synthetic adhesive vendors. For New Entrants and Emerging Players: Rapid-setting formulation service gaps in ambulatory surgical centers offer white-space penetration where simplified application protocols reduce training overhead. Target wound closure applications in emergency medicine where cyanoacrylate instant polymerization eliminates needle trauma and accelerates patient throughput. Specialty clinic channels in cosmetic and microsurgical applications present alternative entry vectors with less procurement committee concentration than hospital networks. For Investors and Strategic Acquirers: Synthetic chemistry houses with tunable polymer platforms represent the priority acquisition archetype as formulation engineering displaces plasma dependence in abdominal closure applications. Long-term viability centers on regulatory harmonization capabilities spanning FDA, EMA, and PMDA pathways. Monitor PMDA-FDA convergence milestones as inflection indicators for reduced clinical trial redundancy and accelerated novel formulation market entry.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Collection Network Acquisition | Captive supply secures fibrin sealant production capacity against donor availability volatility. |
| ISO 10993 Biocompatibility Certification | Elevated cytotoxicity validation opens premium procurement tiers in integrated delivery networks. |
| Synthetic Formulation R&D Expansion | Tunable degradation profiles in polyethylene glycol variants compress cold-chain dependencies. |
| Ambulatory Surgical Center Channel Partnership | Simplified application protocols align with outpatient procedure migration trends in Texas and Florida. |
| PMDA Regulatory Harmonization Investment | Convergence with FDA standards reduces redundant clinical trial requirements for Japan market entry. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital procurement managers, biomedical engineers, GPO contracts specialists, and regulatory affairs directors at sealant manufacturers. Secondary validation drew from FDA 510(k) filings, EMA medical device registration databases, hospital procurement contract repositories, and CMS Medicare reimbursement schedules. Bottom-up procedure volume modeling triangulated against top-down plasma fractionation capacity estimates.
Across the analysis window, forecasts incorporate segmentation dimensions spanning formulation chemistry, delivery mechanism, care setting economics, and regional regulatory cluster. CAGRs derive from procedure migration rates, reimbursement pathway maturation, and synthetic-biologic substitution elasticities. Industry-specific inputs include laparoscopic protocol standardization timelines and REACH chemical safety notification queue lengths.
Underlying assumptions cover plasma collection stability, regulatory pathway convergence, and reimbursement rate continuity, with deviation risk concentrated in donor availability shocks and biocompatibility testing backlog extensions. Recalibration cycles align with material shifts in FDA guidance issuance and integrated delivery network contract renewal windows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Indonesia Sealants Market
Adhesives & Sealants
Middle-East and Africa Hot-Melt Adhesives Market
Adhesives & Sealants
Europe Construction Adhesives and Sealants Market
Adhesives & Sealants
Global Contact Adhesives Market
Adhesives & Sealants
Active Metal Brazing (AMB) Paste Market
Adhesives & Sealants
Middle-East and Africa Cyanoacrylate Adhesives Market
Adhesives & Sealants
Debonding-on-Demand Adhesive Tapes for Electronics Dismantling Market
Adhesives & Sealants
Europe Human Fibrin Glue Market
Adhesives & Sealants
Global Solvent Pressure Sensitive Adhesives Market
Adhesives & Sealants
Global Human Fibrin Glue Market
Adhesives & Sealants
Global Hygiene Adhesives Market
Adhesives & Sealants
Cold Seal Adhesives Market
Adhesives & Sealants
Global Epoxy Tooling Board Market
Adhesives & Sealants
North America Bone Glue Market
Adhesives & Sealants
Anti-Corrosion Tape Market
Adhesives & Sealants
India Construction Chemicals Market