
 Automotive Adhesives and Sealants Market | 2026-2036
Automotive Adhesives and Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Adhesives and Sealants Market Analysis
Tier-1 suppliers is unwinding the historical dominance of OEM captive operations in adhesive procurement for structural body assembly. Henkel AG & Co. KGaA leverages its European manufacturing footprint to supply polyurethane platforms to German automotive clusters. Sika AG anchors its position through specialized expertise in acoustic damping and exterior sealing systems. Dow competes on thermosetting chemistry breadth across North American and Asian OEM programs.
Automotive adhesives and sealants comprise formulated polymer systems—typically epoxy, polyurethane, silicone, or acrylic bases—engineered to achieve specified shear strengths, cure profiles, and thermal stability across temperature ranges from minus forty to one hundred fifty degrees Celsius for vehicle assembly and sealing applications. Their primary commercial purpose is to bond dissimilar substrates, seal against moisture and noise, and replace mechanical fasteners to reduce vehicle weight. Polyurethane formulations lead volume consumption in body assembly due to established crash-performance certification, while silicone commands premium positioning in exterior sealing where thermal cycling resistance defines specification compliance. Structural technology segments concentrate margin pools as OEMs qualify fewer suppliers for load-bearing adhesive applications.
EPA regulates VOC emissions from adhesive manufacturing and application facilities in the United States, pushing formulators toward waterborne and hot-melt alternatives. ECHA administers REACH restrictions on isocyanates and hazardous substance thresholds across European supply chains, directly affecting polyurethane product development cycles. China's MEE enforces GB standards on formaldehyde and solvent content in automotive interior applications. Stakeholders must monitor regulatory divergence between jurisdictions to avoid reformulation costs that fragment supply chain economics.
Market Dynamics
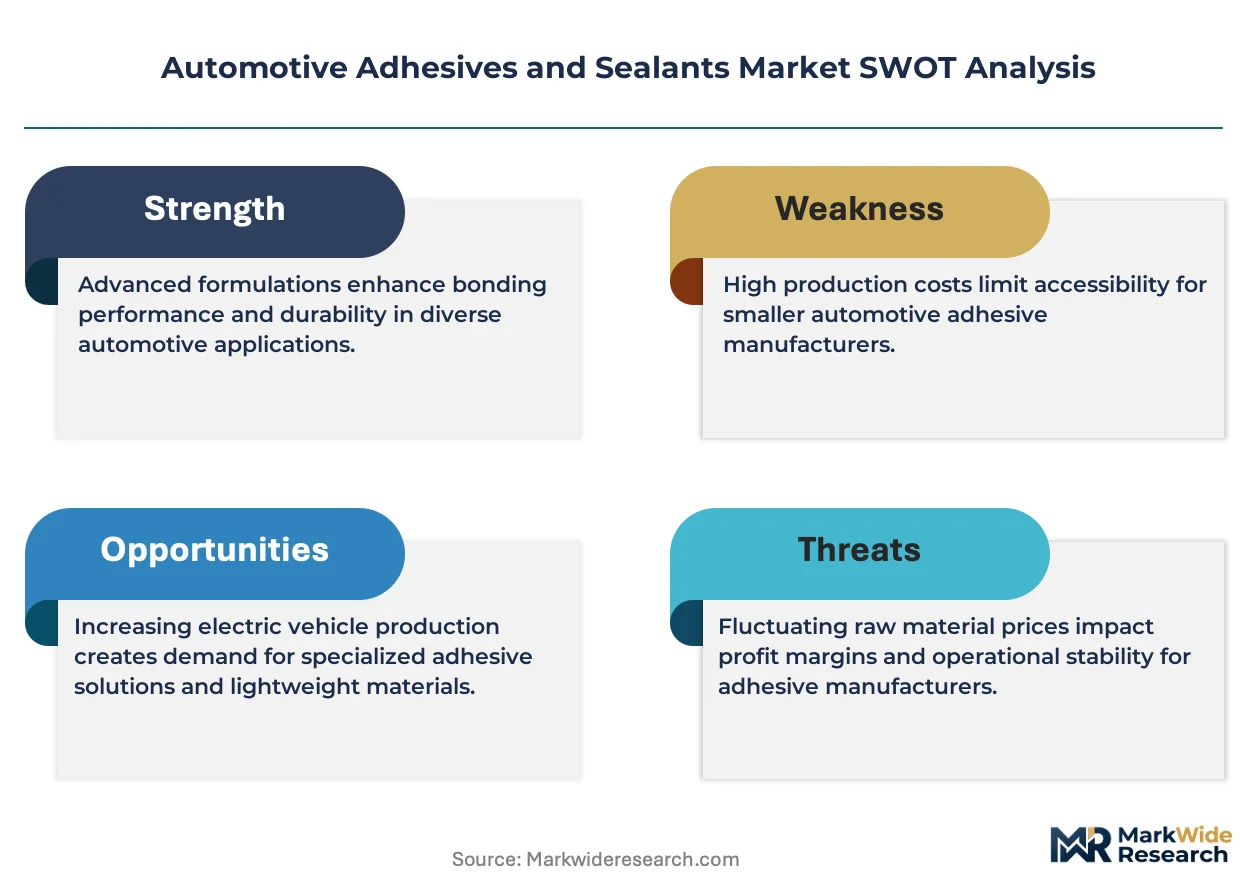
Electric vehicle battery pack assembly is forcing material specification upgrades across structural bonding applications, as thermal management requirements and crash safety standards exceed the performance envelope of legacy mechanical fastening systems. OEMs now qualify fewer suppliers for load-bearing adhesive programs, concentrating margin pools among formulators with certified polyurethane and epoxy platforms.
Growth Catalysts
- ELV Directive compliance:Europe's End-of-Life Vehicle regulations mandate design-for-recycling protocols that favor adhesives enabling multi-material joining without permanent welds, accelerating disassembly-friendly bonding specifications.
- Battery thermal interface materials:EV manufacturers specify thermally conductive adhesives for cell-to-pack bonding, creating specification pull for silicone and modified acrylic platforms with dielectric stability.
- German automotive cluster concentration:Stuttgart, Munich, and Wolfsburg anchor OEM demand for structural polyurethane systems, with Tier-1 suppliers locating formulation facilities adjacent to final assembly plants.
Market Restraints
- MDI price volatility:Methylene diphenyl diisocyanate feedstock costs fluctuate with crude oil and benzene markets, compressing margins for polyurethane formulators locked into annual OEM supply contracts.
- REACH isocyanate restrictions:ECHA classification of diisocyanates as respiratory sensitizers triggers mandatory training requirements and workplace exposure limits, adding compliance overhead to European manufacturing operations.
- Spot-weld substitution limits:High-strength steel grades in A and B pillar structures retain mechanical fastening for crash energy management, capping adhesive penetration in primary safety-critical joints.
Strategic Opportunities
- India PLI scheme for EVs:Production-linked incentive frameworks for electric vehicle manufacturing create localized demand for battery pack adhesives as domestic OEMs scale cell assembly operations.
- Two-component silicone convergence:Rapid-cure silicone formulations meeting both thermal cycling and acoustic damping specifications enable single-material solutions replacing separate sealant and adhesive layers.
- Direct-to-battery OEM procurement:Cell manufacturers bypass Tier-1 module suppliers to specify thermal interface materials directly, opening channel access for specialized formulators with battery chemistry expertise.
Industry Challenges
- Crash certification timelines:OEM structural adhesive qualifications require 24-36 month sled test and real-world collision validation cycles, freezing supplier rosters and delaying new entrant market access.
- Paint shop integration complexity:Adhesive cure profiles must synchronize with e-coat bake cycles, requiring formulators to customize rheology for specific OEM paint line temperatures and conveyor speeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Adhesives and Sealants Market |
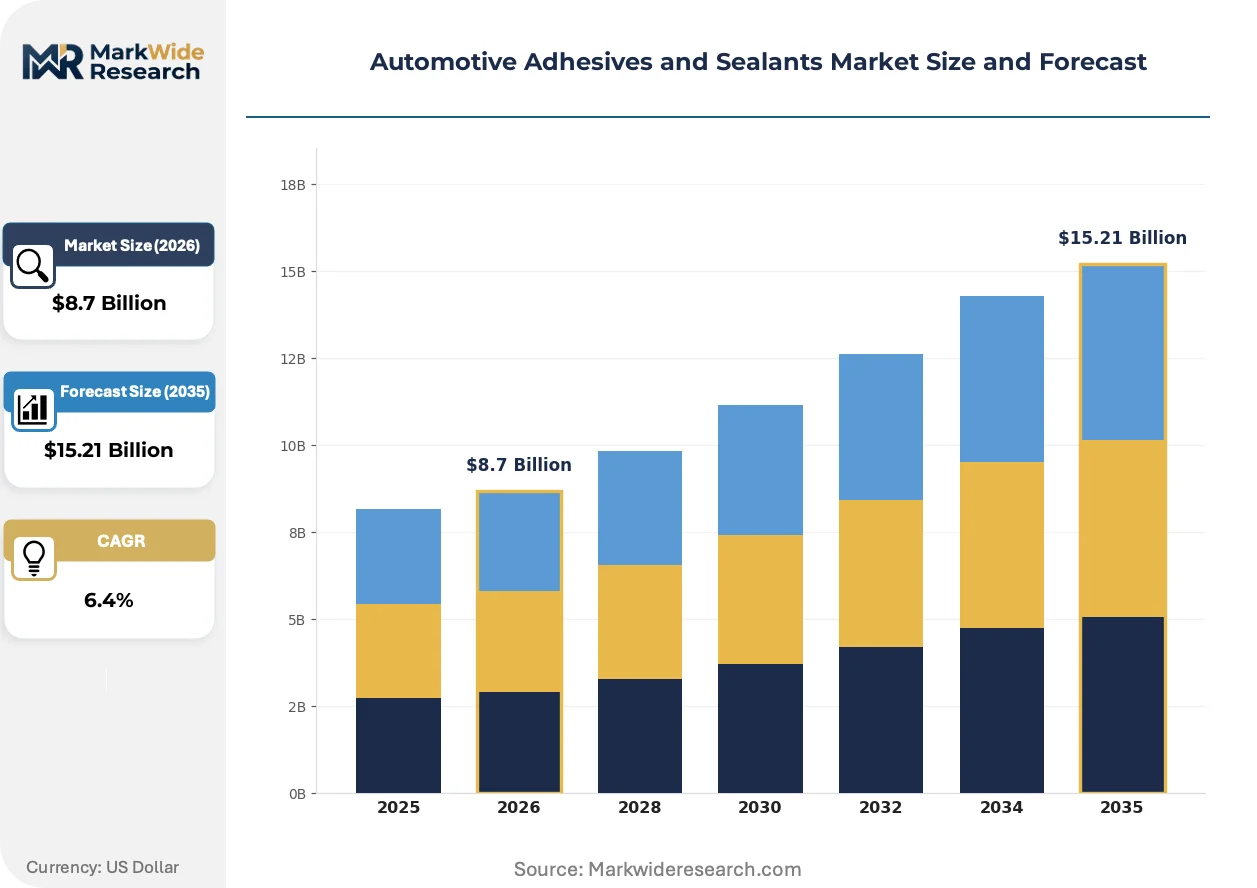
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Silicone, Acrylic End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Dealerships Application: Body Assembly, Interior Components, Exterior Sealing, Chassis Technology: Reactive, Thermosetting, Thermoplastic, Structural |
| Companies Covered | Henkel AG & Co. KGaA, 3M, Sika AG, H.B. Fuller Company, Dow, BASF SE, Arkema, Huntsman Corporation, PPG Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Adhesives and Sealants Market Emerging Trajectories
Formulation chemistry is pivoting toward waterborne and hot-melt platforms as regulatory pressure compounds with OEM sustainability scorecard requirements. Material scientists now engineer cure-on-demand systems that decouple application timing from final assembly line speed.
Structural acrylic adhesives are displacing spot welds in aluminum-intensive body-in-white assemblies, with European luxury OEMs adopting two-component systems for closure panel bonding. The shift enables multi-material vehicle architectures combining steel, aluminum, and composites while maintaining crash performance ratings. This displacement is compressing capital expenditure requirements for new stamping plant equipment.
REACH Annex XVII restrictions on microplastics and SVHC candidate list expansions are forcing reformulation of solvent-based sealants across European supply chains. Formulators accelerate waterborne polyurethane development cycles to maintain product registrations. Exterior sealing applications face the steepest compliance burden, driving premium pricing for silicone alternatives with verified substance safety profiles.
Cell manufacturers now specify thermal interface materials through direct procurement channels rather than delegating to module integrators. This disintermediation concentrates technical dialogue between adhesive formulators and battery engineering teams, bypassing historical Tier-1 supplier intermediaries. China and South Korea display the most advanced procurement model evolution, with CATL and LG Energy Solution maintaining captive material qualification laboratories.
Automotive Adhesives and Sealants Market Segmentation
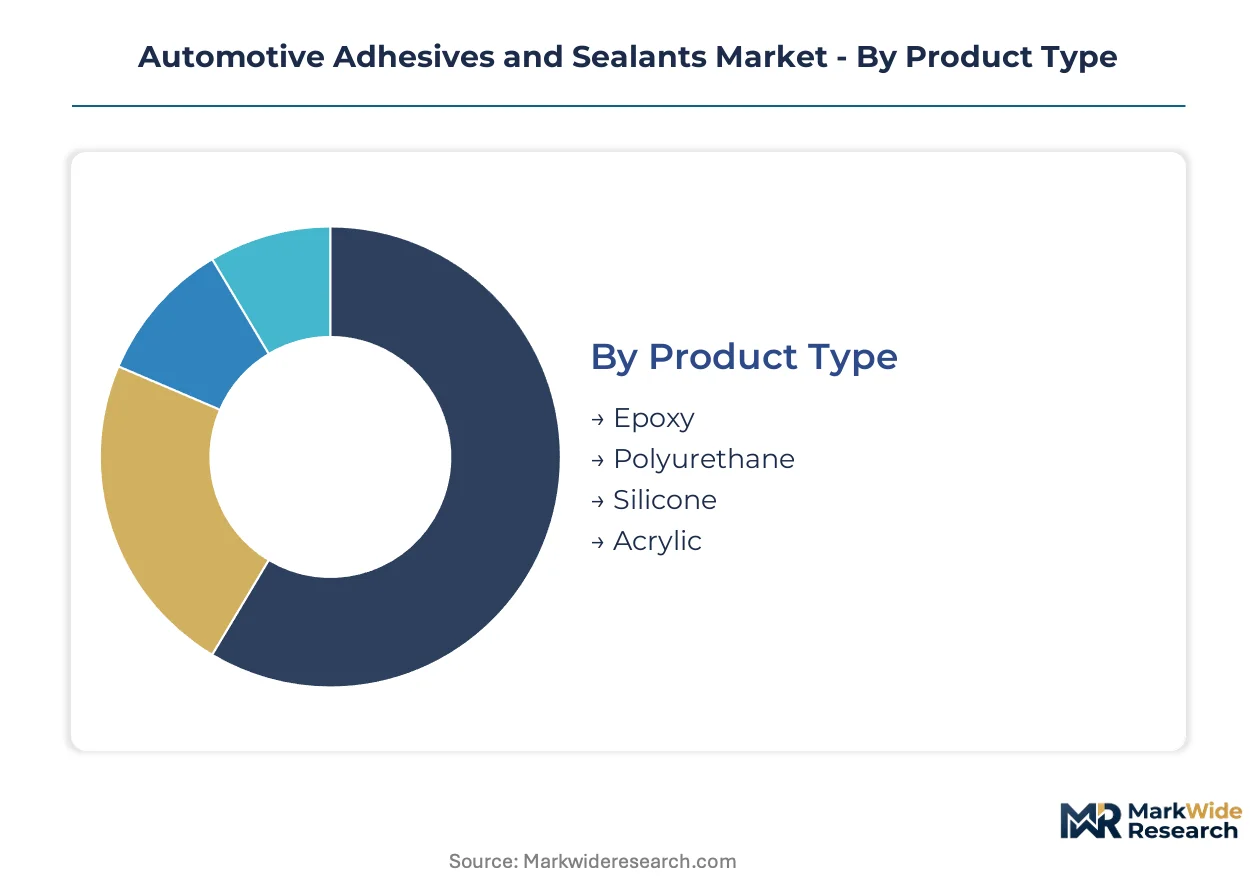
Material selection in automotive bonding follows a rigid qualification hierarchy where crash-performance certification and thermal stability specifications filter available options. Segmentation reveals how polyurethane and epoxy platforms concentrate structural applications while silicone and acrylic formulations serve specialized sealing and interior roles.
Product Type:
Polyurethane faces the strongest substitution pressure from structural acrylics in aluminum body-in-white applications, while silicone maintains defensive positioning through thermal cycling performance that competing chemistries cannot replicate.
- Polyurethane:Formulated from MDI and polyol prepolymers, these systems achieve shear strengths exceeding 15 MPa with controlled cure profiles compatible with OEM paint shop bake cycles. German automotive clusters in Stuttgart and Wolfsburg specify polyurethane for closure panel bonding where crash energy absorption defines qualification. MDI price volatility compresses margins for formulators locked into annual supply contracts.
- Epoxy:Two-component systems deliver superior adhesion to untreated metal substrates and composite reinforcements. EV battery pack manufacturers specify thermally conductive epoxy variants for cell-to-pack bonding where dielectric stability and thermal management converge. REACH isocyanate restrictions accelerate epoxy substitution in European structural applications.
- Silicone:Rapid-cure formulations meeting thermal cycling and acoustic damping specifications enable single-material solutions replacing separate sealant layers.
- Acrylic:Structural grades displace spot welds in multi-material architectures combining steel, aluminum, and composites.
Polyurethane anchors the volume base while acrylic gains share at the steepest rate.
End User:
Procurement authority is migrating downstream as battery cell manufacturers bypass traditional intermediaries to specify thermal interface materials directly.
- OEMs:Captive operations historically dominated structural adhesive procurement for body-in-white assembly. BMW, Volkswagen, and Ford maintain internal specification teams that qualify adhesive platforms through 24-36 month sled test validation cycles. OEMs now consolidate supplier rosters to reduce qualification overhead.
- Tier-1 Suppliers:Magna, Continental, and Bosch source adhesives for module assembly where paint shop integration complexity requires customized rheology. These suppliers face margin compression from dual pressure: OEM price-down schedules and raw material volatility.
- Aftermarket Providers:Independent distributors serve collision repair and refurbishment demand with standardized polyurethane and silicone formulations.
- Dealerships:Authorized service networks consume OEM-approved sealants for warranty-compliant repairs.
OEMs retain specification authority while Tier-1 suppliers capture expanding procurement volume.
Application:
Body assembly commands the highest performance thresholds where crash certification requirements freeze supplier rosters, while exterior sealing faces the steepest regulatory compliance burden under REACH microplastics restrictions.
- Body Assembly:Structural bonding of closure panels, roof modules, and floor pans demands shear strengths sustaining collision loads without substrate failure. European luxury OEMs specify two-component acrylic systems for aluminum-intensive architectures. Paint shop integration requires cure profiles synchronized with e-coat bake cycles.
- Interior Components:Dashboard assembly, headliner attachment, and trim bonding utilize hot-melt and waterborne formulations to meet China's GB standards on formaldehyde emissions. MEE enforcement drives specification upgrades for cabin air quality compliance.
- Exterior Sealing:Windshield bonding, seam sealing, and underbody coating require thermal cycling resistance across temperature ranges from minus forty to one hundred fifty degrees Celsius. Silicone alternatives command premium pricing with verified substance safety profiles under REACH Annex XVII.
- Chassis:Suspension component bonding and NVH damping applications favor polyurethane platforms with established durability certification.
Body assembly concentrates margin pools while exterior sealing climbs the fastest on regulatory-driven specification upgrades.
Technology:
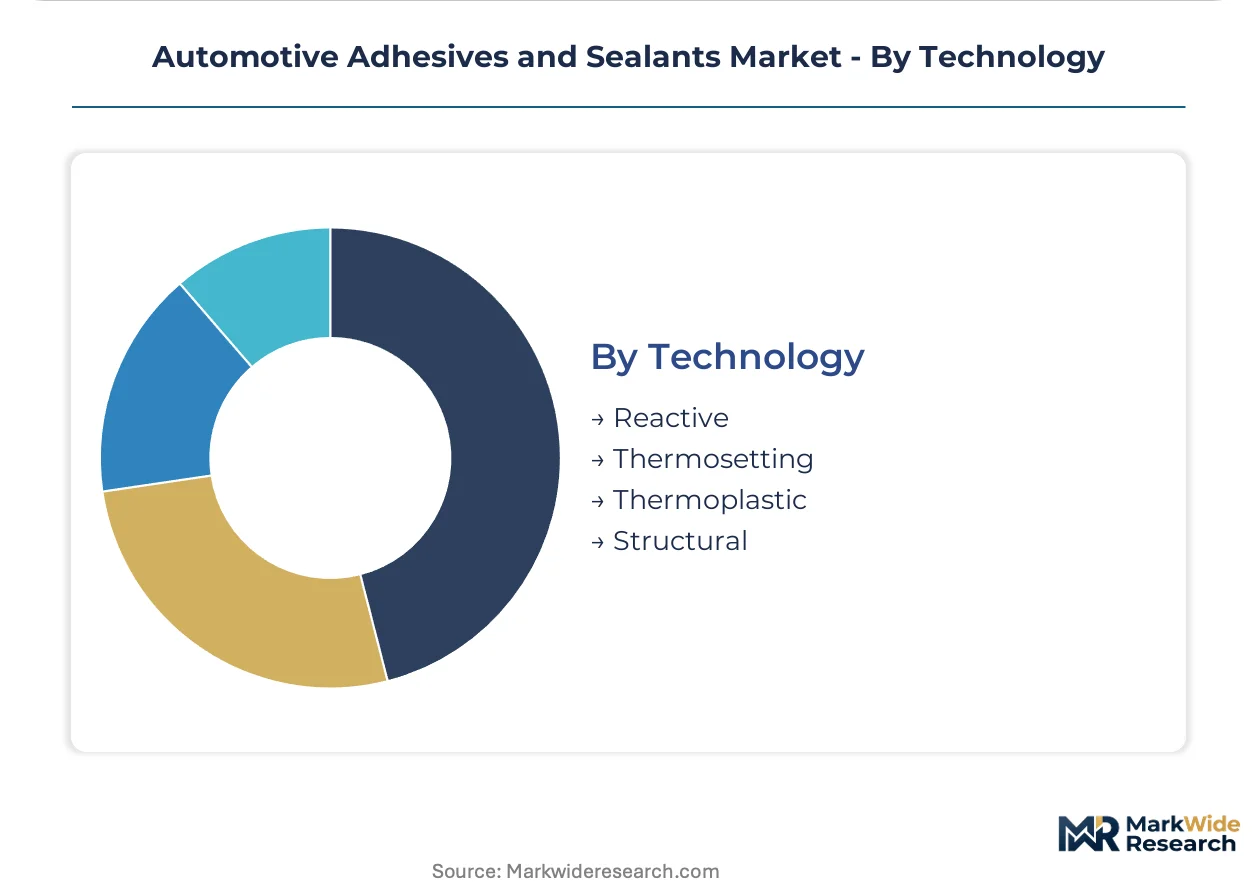
Reactive systems face displacement pressure from thermoplastic alternatives in interior applications where recyclability and disassembly-friendly design gain priority under Europe's ELV Directive.
- Reactive:Two-component polyurethane and epoxy systems cure through chemical crosslinking to form permanent bonds. These platforms dominate structural applications where load-bearing performance is non-negotiable. OEMs qualify fewer suppliers for reactive adhesive programs, concentrating margin pools.
- Thermosetting:Heat-activated cure systems integrate with OEM paint line temperatures and conveyor speeds. Formulators customize rheology for specific e-coat bake cycles. Dow competes on thermosetting chemistry breadth across North American and Asian OEM programs.
- Thermoplastic:Hot-melt formulations enable rework and recycling compatibility favored by ELV compliance protocols. These systems expand in interior trim applications where disassembly-friendly bonding accelerates end-of-life vehicle processing.
- Structural:Load-bearing adhesives qualified for primary safety-critical joints where mechanical fastening retains dominance in A and B pillar structures.
Reactive technology anchors specification compliance while thermoplastic expands most quickly on sustainability-driven design protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors Germany's chemical export infrastructure, distributing polyurethane precursors to Stuttgart and Wolfsburg automotive clusters. This maritime throughput underwrites European supply chain reliability for structural bonding platforms.
China
CATL and BYD scale battery pack assembly drives specification pull for thermally conductive adhesives. MEE enforces GB standards on formaldehyde emissions in cabin applications. Yangtze River Delta concentration around Shanghai hosts formulation facilities supplying Tesla Shanghai and NIO.
Germany
Stuttgart, Munich, and Wolfsburg clusters specify polyurethane systems for closure panel bonding. REACH Annex XVII restricts microplastics in exterior sealants. BASF Ludwigshafen complex supplies MDI feedstock to captive formulators serving BMW and Volkswagen programs.
United States
EPA VOC regulations push waterborne formulation adoption across Michigan and Ohio assembly plants. IRA clean vehicle tax credits accelerate EV adhesive demand. Detroit Three OEMs consolidate supplier rosters for battery thermal interface materials.
South Korea
LG Energy Solution and Samsung SDI maintain captive qualification laboratories for cell-to-pack bonding. MFDS substance safety protocols align with REACH substance restrictions. Gyeonggi-do concentration anchors domestic formulation capacity for Hyundai-Kia programs.
India
PLI scheme for EV manufacturing creates localized demand for battery pack adhesives. BIS certification requirements filter import-dependent supply chains. Tamil Nadu and Maharashtra host emerging Tier-1 formulation facilities adjacent to Tata Motors and Mahindra assembly plants.
Automotive Adhesives and Sealants Market Vendor Landscape
Concentration sits with diversified chemical conglomerates and specialized adhesive formulators competing across qualification-intensive OEM programs. Three to five suppliers typically dominate structural adhesive rosters per major automotive platform. Strategic archetypes include European polyurethane specialists, North American thermosetting chemistry broadliners, and Asian battery-focused thermal interface material developers. Competitive moves center on paint shop integration partnerships and direct-to-cell-manufacturer procurement channel development.
Among European-based formulators, Henkel AG & Co. KGaA and Sika AG occupy positions exemplifying the polyurethane platform archetype, while Dow represents North American thermosetting chemistry breadth. These three names anchor supplier consolidation trends as OEMs reduce qualification overhead for load-bearing adhesive programs.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| 3M |
| Sika AG |
| H.B. Fuller Company |
| Dow |
| BASF SE |
| Arkema |
| Huntsman Corporation |
| PPG Industries |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts with German OEMs lock in MDI supply access and price visibility for polyurethane formulators serving Stuttgart and Wolfsburg clusters, insulating qualified suppliers from spot market volatility while freezing out new entrants lacking certification track records.
Pricing Analysis
Volume-discount tiering separates crash-certified structural grades from commodity interior formulations, with OEM direct procurement commanding steeper discounts than Tier-1 module supplier channels. Price differentiation hinges on REACH compliance certification and thermal cycling test documentation. Cost compression in standard-grade polyurethane is intensifying because MDI feedstock volatility squeezes margins on annual contracts. Aftermarket distributors exhibit highest price sensitivity, while battery cell manufacturers show lowest sensitivity for qualified thermal interface materials.
Supply Chain Analysis
BASF Ludwigshafen MDI production anchors European supply security for German automotive clusters. Feedstock draws from crude oil and benzene derivatives, with formulation output feeding captive Henkel and Sika facilities. Single-source vulnerability concentrates around Chinese MEE-regulated silicone precursor supply. Distribution runs through Port of Hamburg maritime throughput to Stuttgart and Wolfsburg assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a substitution defense against structural acrylic displacement in aluminum body-in-white applications, requiring incumbents to navigate crash-certification barriers that slow substitute penetration.
For Market Incumbents: Fortify paint shop integration partnerships with BMW and Volkswagen to deepen e-coat bake cycle customization moats. Accelerate captive MDI supply through backward integration into Ludwigshafen precursor networks. Structural acrylic qualification timelines at European luxury OEMs represent the primary substitute threat requiring defensive patent positioning.
For New Entrants and Emerging Players: OEM sled-test fast-track programs for battery thermal interface materials offer the most penetrable entry vector, bypassing 24-36 month structural adhesive validation cycles. Target direct-to-cell procurement channels at CATL and LG Energy Solution with silicone-based dielectric platforms. Go-to-market leverage rests on maintaining captive qualification laboratory partnerships.
For Investors and Strategic Acquirers: Battery-focused thermal interface material specialists with CATL or Samsung SDI qualification records command premium positioning. Long-term viability across the analysis window hinges on EV production scaling and adhesive substitution rates in multi-material architectures. Watch for MDI price inflection signals as benzene derivative cost pressure indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| Paint Shop Integration Partnership | Henkel and Sika customize rheology for BMW e-coat bake cycles, locking in specification compliance. |
| Direct-to-Cell Procurement Channel | Specialized formulators bypass Magna and Continental to supply CATL thermal interface materials directly. |
| Backward Integration into MDI Feedstock | BASF Ludwigshafen complex secures precursor supply for captive polyurethane formulation serving Volkswagen. |
| REACH-Compliant Waterborne Development | Formulators accelerate polyurethane reformulation to maintain registrations under Annex XVII microplastics restrictions. |
| Thermal Cycling Certification Investment | Silicone specialists validate dielectric stability for LG Energy Solution cell-to-pack bonding specifications. |
Methodological Framework
A standing panel of OEM platform engineers, Tier-1 supplier procurement leads, adhesive formulator R&D directors, and aftermarket distribution managers provided ongoing calibration across primary interview cycles. Secondary validation drew from EPA VOC emission filings, ECHA REACH substance registrations, MEE GB standard enforcement records, and vehicle production databases. Bottom-up segmentation modeling triangulated against top-down chemical consumption estimates from trade flow data.
Consistency checks validated volume and value outputs against IHS Markit registration data and ACC sector reports across the projection horizon. Segmentation dimensions spanned material chemistry, application tier, end-user procurement authority, and regional regulatory cluster. CAGRs derived from adhesive content-per-vehicle trajectories and EV production scaling assumptions, with thermal management specification intensity serving as a key sensitivity input.
Underlying assumptions cover OEM qualification timeline stability and MDI feedstock cost normalization, with deviation risk concentrated in REACH isocyanate restriction enforcement and battery cell manufacturer procurement model evolution. Practitioners should keep alternative scenarios live as ELV Directive recycling protocol adoption and spot-weld substitution limits in high-strength steel structures evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Soft Skin Adhesives Market
Adhesives & Sealants
Nigeria Tile Adhesive Market
Adhesives & Sealants
Correction Fluid and Tape Market
Adhesives & Sealants
Adhesive Primer Market
Adhesives & Sealants
Craft Glue Market
Adhesives & Sealants
Structural Adhesives Market
Adhesives & Sealants
Rubber-Based Adhesives Market
Adhesives & Sealants
Europe Flock Adhesives Market
Adhesives & Sealants
Water Based Adhesive Market
Adhesives & Sealants
Global MS Polymer Adhesives Market
Adhesives & Sealants
North America Acrylic Adhesives Market
Adhesives & Sealants
South Korea Sealants Market
Adhesives & Sealants
Vietnam Construction Chemicals Market
Adhesives & Sealants
China Adhesives Market
Adhesives & Sealants
Ocular Adhesives and Sealants Market
Adhesives & Sealants
High Strength Laminated Adhesives Market