
 Frozen Skin Graft Market | 2026-2036
Frozen Skin Graft Market Size, Share, and Industry Trends Forecast 2026-2036
Frozen Skin Graft Market Analytics
North American tissue banking infrastructure is reconfiguring frozen skin graft distribution networks to reduce cold-chain transit times. MTF Biologics leverages its nonprofit tissue recovery model to sustain broad hospital access across multiple states. LifeNet Health Inc. anchors cryopreservation capacity through vertically integrated donor services and processing facilities. AlloSource competes on specialized allograft formulations for complex wound indications.
Frozen skin graft denotes cryopreserved human allogeneic dermis maintained at sub-zero temperatures, typically processed as split-thickness or full-thickness sections measuring 0.15 to 0.60 mm depth, serving as biological wound coverage for patients with insufficient autograft donor sites. Meshed graft variants dominate procurement volumes due to expansion ratios that maximize surface coverage per donor tissue unit, while sheet graft configurations command premium positioning in facial and hand reconstruction where cosmetic outcomes determine selection. Burn treatments represent the largest application segment by institutional procurement value, though surgical procedure adoption accelerates in oncologic reconstruction and complex hernia repair where biologic integration timelines influence clinical protocol design.
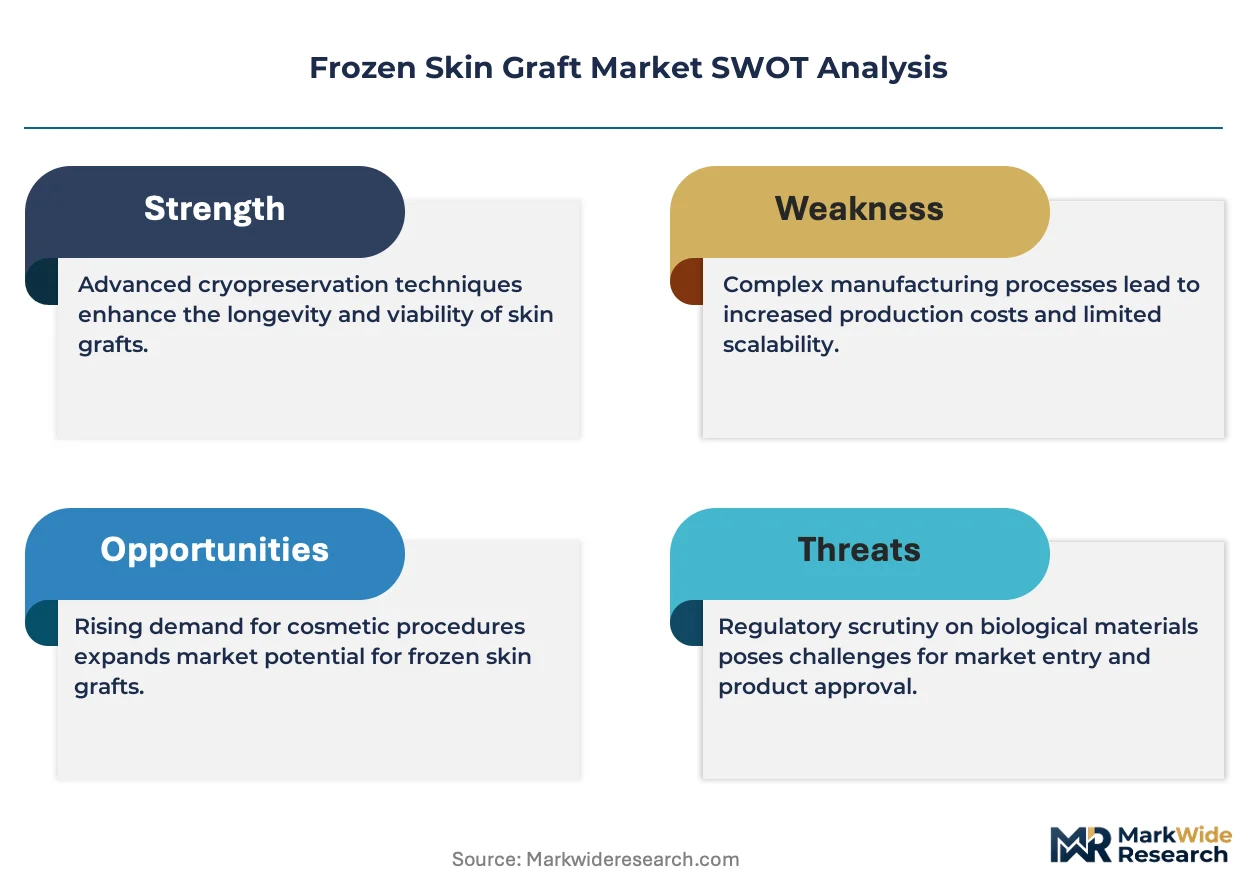
FDA HCT/P regulations, AATB accreditation standards, and state tissue bank licensure collectively govern donor eligibility, processing validation, and distribution record-keeping that shapes market access barriers for new processors. The EU Tissue and Cells Directive imposes parallel requirements for any manufacturer seeking European hospital contracts, creating dual-compliance cost structures for expansion-minded suppliers. Stakeholders must monitor evolving CMS reimbursement determinations for skin substitute application in outpatient settings, as coverage policy shifts will directly alter site-of-care economics and procurement channel preferences across hospital and ambulatory surgical center segments.
Market Dynamics
Cryopreservation protocol standardization across tissue banks is compressing allograft viability variance and forcing processors to recalibrate cold-chain logistics around extended shelf-life claims rather than expedited turnover.
Growth Catalysts
- FDA HCT/P Framework Expansion:The FDA's clarified donor screening protocols for dermal allografts reduce institutional liability exposure and accelerate hospital credentialing timelines for new tissue sources.
- Burn Center Capacity Concentration:Regional trauma network consolidation in the United States concentrates procurement authority within fewer purchasing committees, streamlining vendor selection for high-volume allograft contracts.
- Meshed Graft Processing Automation:Computer-controlled meshing systems reduce technician-dependent variability and expand viable donor tissue yield per recovery event.
Market Restraints
- Donor Tissue Supply Volatility:Seasonal fluctuations in cadaveric donation rates constrain processor inventory buffers and force spot-market purchasing from competing tissue banks.
- Dual-Jurisdiction Compliance Burden:Simultaneous FDA HCT/P and EU Tissue and Cells Directive adherence imposes redundant quality system documentation that disadvantages smaller processors.
- Synthetic Substitute Encroachment:Advanced collagen matrices and acellular dermal scaffolds compete for wound coverage indications where allograft immunogenicity concerns persist.
Strategic Opportunities
- Ambulatory Surgical Center Penetration:CMS reimbursement pathway expansion for skin substitute application in outpatient settings opens procurement channels beyond traditional hospital burn units.
- Oncologic Reconstruction Protocol Adoption:Mastectomy and Mohs surgery reconstruction protocols increasingly specify cryopreserved allograft for complex wound bed preparation.
- Decellularization Technology Convergence:Integration of cryopreservation with enzymatic basement membrane preservation enables next-generation allograft products with enhanced biointegration profiles.
Industry Challenges
- Specialized Tissue Recovery Technician Scarcity:Qualified procurement personnel capable of aseptic donor site preparation remain concentrated within established organ procurement organizations.
- AATB Accreditation Timeline Compression:Accelerated facility inspection schedules strain quality documentation systems without proportional staffing expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frozen Skin Graft Market |
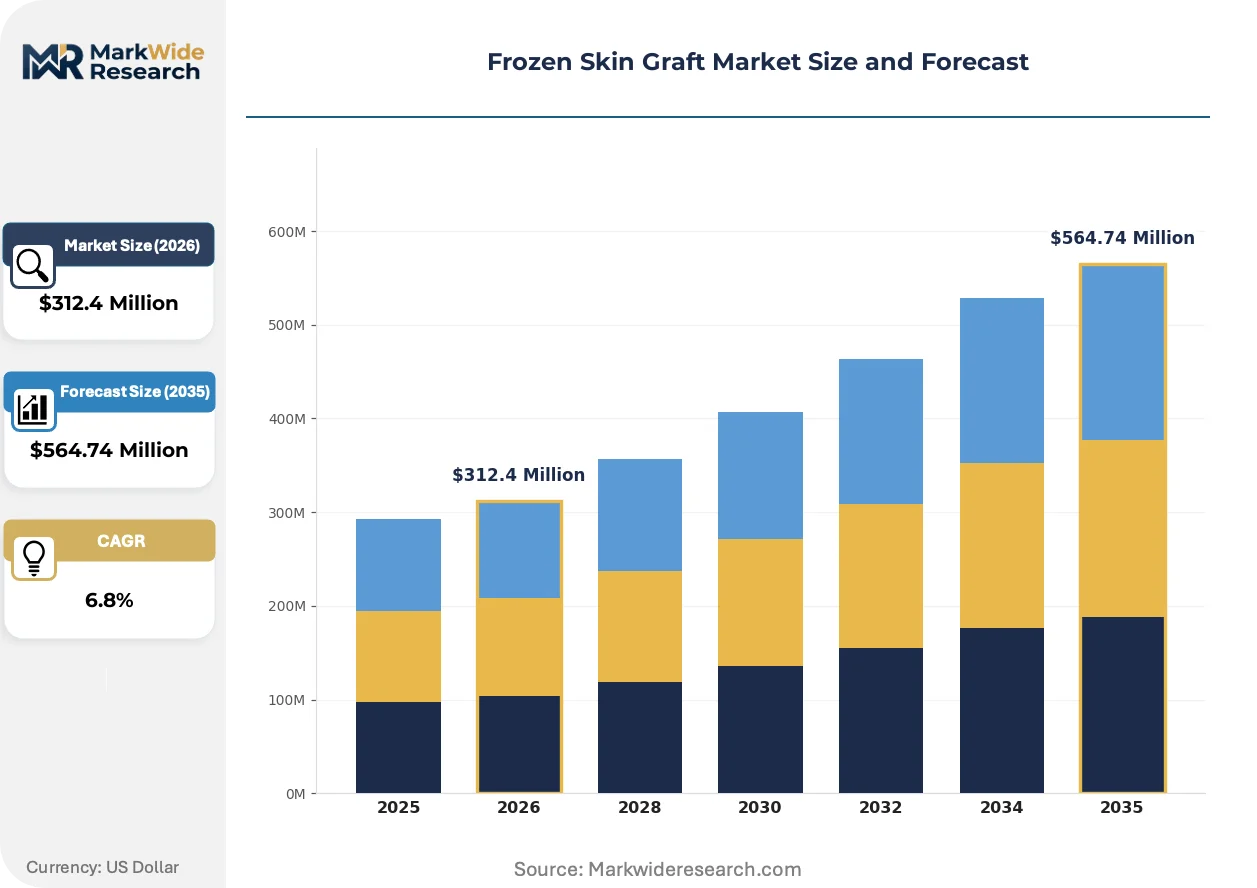
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meshed Graft, Sheet Graft, Split-Thickness Graft, Whole Graft Application: Burn Treatments, Surgical Procedures, Wound Care, Aesthetic Procedures End User: Hospitals, Ambulatory Surgical Centers, Dermatology Clinics, Home Healthcare Delivery Mode: Direct Delivery, Telehealth Services, Pre-packaged Solutions, On-site Application |
| Companies Covered | MTF Biologics, LifeNet Health Inc., AlloSource, Tissue Regenix Group Plc, Organogenesis Inc., Kerecis, MIMEDX Group, Inc., Integra LifeSciences, Zimmer Biomet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frozen Skin Graft Market Evolving Landscape
Processing technology convergence and procurement model rationalization are reconfiguring competitive advantage around cold-chain reliability rather than donor network scale alone.
Lyophilization alternatives for dermal preservation are rendering obsolete the traditional dependency on vapor-phase liquid nitrogen storage infrastructure. Burn centers in the southeastern United States are piloting ambient-stable processed allograft inventory that eliminates mechanical freezer maintenance burden. This shift compresses capital requirements for tissue bank expansion and is rendering obsolete the geographic radius constraints that historically limited allograft distribution to regional procurement zones.
The EU Medical Device Regulation reclassification of certain processed allograft products imposes notified body oversight requirements that previously applied only to synthetic substitutes. Manufacturers with dual US-EU distribution footprints must reconcile FDA HCT/P quality system documentation with MDR technical file structures. This regulatory friction most acutely affects meshed graft product lines where processing methodology determines classification boundary.
Hospital value analysis committees now mandate total cost-of-ownership documentation that incorporates graft take rate, reoperation frequency, and nursing labor intensity rather than unit price alone. This purchasing behavior shift elevates processors with validated clinical outcome databases over commodity tissue suppliers. The phenomenon concentrates most visibly within integrated delivery networks in Texas and Florida where burn service line consolidation has centralized procurement authority.
Frozen Skin Graft Market Segmentation
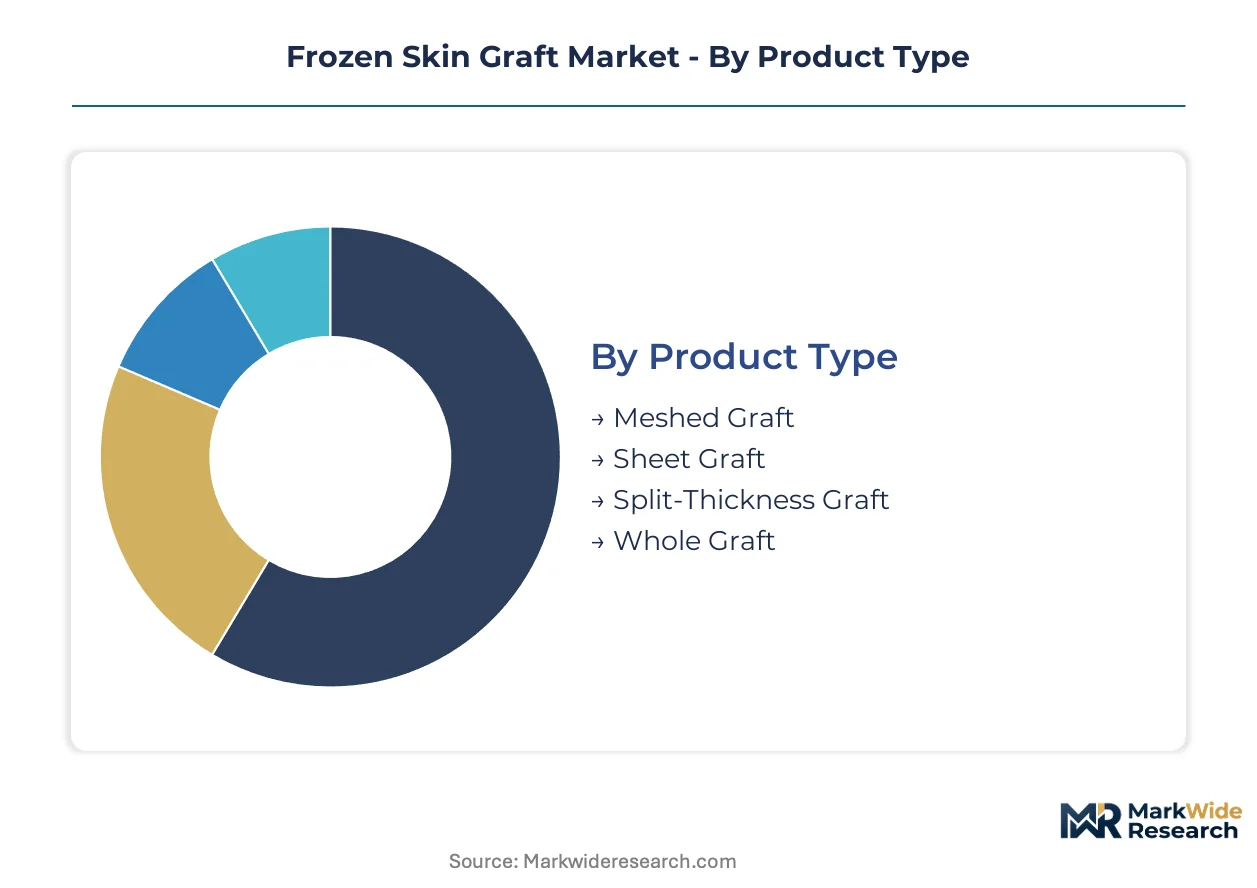
Segmentation in frozen skin graft markets reveals how clinical requirements reshape procurement patterns across wound coverage applications. Product form factors, care settings, and delivery logistics each create distinct margin profiles and compliance obligations for tissue processors.
Product Type:
Product architecture determines expansion ratios, handling protocols, and reimbursement coding complexity across institutional purchasing.
- Meshed Graft:Perforated configurations achieve expansion ratios from 1:1.5 to 1:9, maximizing surface coverage from limited donor tissue. Demand concentrates in regional burn centers across Texas and Florida where mass casualty protocols require rapid wound coverage scalability.
- Sheet Graft:Unmeshed dermal sections preserve continuous epithelial architecture for cosmetic-critical zones. Facial reconstruction units at specialized trauma centers in California and New York command premium positioning due to outcome visibility in exposed anatomical areas.
- Split-Thickness Graft:Partial dermis sections balance donor site healing with graft viability for intermediate wound beds.
- Whole Graft:Full-thickness configurations retain complete dermal and epidermal layers for deep wound reconstruction.
Meshed graft holds installed capacity. Sheet graft is rotating up the share rankings.
Application:
Clinical indication severity dictates cold-chain urgency, surgeon specialization requirements, and site-of-care economics.
- Burn Treatments:Acute thermal and chemical injury coverage demands immediate allograft availability with validated viability windows. Procurement authority clusters within American Burn Association-verified centers where CMS reimbursement pathways anchor institutional purchasing volumes.
- Surgical Procedures:Oncologic reconstruction and complex hernia repair integrate cryopreserved dermis for wound bed preparation. Mohs surgery units and mastectomy reconstruction programs in academic medical centers drive protocol adoption where biointegration timelines influence surgical scheduling.
- Wound Care:Chronic ulcer management extends allograft utility beyond acute intervention into outpatient settings.
- Aesthetic Procedures:Cosmetic reconstruction applications specify processed allograft for scar revision and tissue augmentation.
Burn treatments hold installed capacity. Surgical procedures are climbing the fastest.
End User:
Facility type determines regulatory oversight intensity, inventory holding capacity, and reimbursement mechanism structure.
- Hospitals:Integrated delivery networks maintain vapor-phase liquid nitrogen infrastructure and specialized wound care nursing protocols. Burn service line consolidation across southeastern United States health systems concentrates procurement authority within value analysis committees demanding total cost-of-ownership documentation.
- Ambulatory Surgical Centers:Outpatient surgical facilities expand skin substitute application as CMS reimbursement determinations clarify coverage eligibility. Freestanding centers in Texas and Arizona pilot ambient-stable allograft inventory eliminating mechanical freezer capital requirements.
- Dermatology Clinics:Specialized outpatient settings manage chronic wound populations with limited cold-chain infrastructure.
- Home Healthcare:Residential care delivery extends wound coverage into post-acute settings with portable storage requirements.
Hospitals hold installed capacity. Ambulatory surgical centers are gaining share fastest.
Delivery Mode:
Logistics architecture shapes tissue viability risk, inventory carrying costs, and emergency response capability.
- Direct Delivery:Temperature-controlled courier networks transport cryopreserved units from tissue bank to clinical site within validated cold-chain windows. MTF Biologics leverages nonprofit recovery infrastructure to sustain broad hospital access across multiple states through direct distribution.
- Pre-packaged Solutions:Standardized graft configurations with documented viability data reduce site-of-care preparation burden. Processing facilities in Virginia and Colorado ship pre-meshed units to burn centers requiring immediate application capability.
- Telehealth Services:Remote clinical consultation guides graft selection without physical inventory proximity.
- On-site Application:Tissue bank personnel perform graft preparation and placement at clinical facilities.
Direct delivery holds installed capacity. Pre-packaged solutions are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA HCT/P regulations anchor procurement protocols in the United States, while parallel tissue frameworks in Europe and procurement expansions across Asia-Pacific reshape distribution economics for cryopreserved allografts.
United States
Burn center consolidation across Texas and Florida concentrates institutional purchasing authority within value analysis committees demanding total cost-of-ownership documentation. CMS reimbursement determinations for skin substitute application in outpatient settings alter site-of-care economics. Specialized trauma networks in California and New York anchor premium sheet graft demand for facial reconstruction protocols.
Germany
Academic medical centers in Bavaria and North Rhine-Westphalia integrate cryopreserved dermis into oncologic reconstruction workflows. The EU Tissue and Cells Directive imposes quality system documentation requirements that parallel FDA HCT/P standards. Processing facilities in Baden-Württemberg develop specialized allograft formulations for complex wound indications.
United Kingdom
NHS procurement frameworks standardize allograft sourcing across regional burn networks. The Human Tissue Authority regulates donor consent and tissue traceability standards. Research clusters in London and Manchester advance decellularization technology convergence with cryopreservation protocols.
Japan
PMDA oversight of processed allografts shapes import licensing timelines for foreign tissue banks. Academic medical centers in Tokyo and Osaka pilot meshed graft automation for mass casualty preparedness. Domestic tissue banking infrastructure remains concentrated within university-affiliated hospital networks.
Australia
TGA classification determinations for cryopreserved dermal products influence reimbursement eligibility in public hospital systems. Burn units in New South Wales and Victoria expand allograft procurement for acute wound coverage. Tissue banking infrastructure development concentrates in Melbourne and Sydney metropolitan corridors.
Frozen Skin Graft Market Competitive Landscape
Capability concentration sits with specialized tissue processors; scale advantage sits with vertically integrated recovery organizations. The market structures around three tiers: nonprofit organ procurement organizations with donor network control, commercial processors with formulation specialization, and diversified medical device manufacturers with distribution reach. Competitive moves center on cold-chain logistics consolidation and decellularization technology licensing.
Within the nonprofit procurement tier, MTF Biologics and LifeNet Health occupy positions defined by donor recovery infrastructure and hospital access breadth. AlloSource exemplifies the specialized processor archetype competing on allograft formulation diversity. These three entities represent distinct strategic positions: broad network coverage, integrated cryopreservation capacity, and indication-specific product development.
| Leading Market Players |
|---|
| MTF Biologics |
| LifeNet Health Inc. |
| AlloSource |
| Tissue Regenix Group Plc |
| Organogenesis Inc. |
| Kerecis |
| MIMEDX Group, Inc. |
| Integra LifeSciences |
| Zimmer Biomet |
| Others |
Value Network & Pricing Analysis
Donor recovery networks concentrated within established organ procurement organizations in the United States anchor procurement economics, directing margin pools toward processors with captive tissue supply rather than formulation-only competitors. Cryopreservation infrastructure ownership determines pricing power across institutional contracts.
Pricing Analysis
Price spreads between meshed and sheet graft configurations widen in coastal metropolitan markets where cosmetic outcome visibility drives premium positioning. Three-tier pricing structure across premium, standard, and economy levels reflects AATB accreditation tier, processing methodology complexity, and cold-chain reliability documentation. Cost compression in standard-tier meshed grafts is intensifying because synthetic substitute manufacturers are expanding wound coverage indications. Ambulatory surgical centers exhibit highest price sensitivity due to capital-constrained inventory models, while academic burn centers prioritize total cost-of-ownership metrics over unit pricing.
Supply Chain Analysis
Contract manufacturing concentration for cryopreservation services sits with MTF Biologics, LifeNet Health, and AlloSource operating dedicated processing facilities. Geographic supply concentration clusters in the United States, Germany, and Australia where tissue banking infrastructure draws from cadaveric donation networks, vapor-phase liquid nitrogen storage systems, and specialized recovery technician labor pools. Single-source vulnerability permeates donor tissue procurement where seasonal donation fluctuations constrain inventory buffers. Distribution runs through temperature-controlled courier networks with validated cold-chain windows from processing facility to clinical site.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Frozen skin graft markets operate as a regulatory-moat industry where FDA HCT/P compliance timelines and AATB accreditation requirements create entrenched switching costs for institutional buyers. Network effects concentrate within established tissue banks possessing donor recovery infrastructure.
For Market Incumbents: Build certification-depth moats by accelerating AATB accreditation for specialized allograft formulations before EU MDR reclassification tightens notified body oversight. Defensive consolidation should prioritize backward integration into ambient-stable processing technology to neutralize synthetic substitute encroachment. Capacity addition in Texas and Florida burn center corridors secures procurement committee relationships against emerging regional competitors. For New Entrants and Emerging Players: Pursue white-space penetration in ambulatory surgical center channels where CMS reimbursement pathway expansion has outpaced incumbent distribution adaptation. The most penetrable segment lies in oncologic reconstruction protocols at freestanding Mohs surgery units lacking vapor-phase liquid nitrogen infrastructure. Go-to-market execution should lead with pre-packaged ambient-stable graft configurations eliminating capital requirements for mechanical freezer installation. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed commercial processors possessing formulation specialization but lacking donor network control. Long-term viability over the mid-decade horizon hinges on decellularization technology licensing positions and EU MDR technical file readiness. Acquisition targets should display dual US-EU quality system documentation capabilities. The signal to watch is CMS outpatient reimbursement determination frequency for skin substitute application.| Strategic Initiative | Industry Significance |
|---|---|
| Decellularization Technology Licensing | Enzymatic basement membrane preservation commands premium positioning in facial reconstruction protocols. |
| Ambulatory Surgical Center Distribution Partnership | Pre-packaged ambient-stable inventory eliminates mechanical freezer capital barriers in outpatient settings. |
| EU MDR Technical File Preparation | Notified body oversight requirements for processed allografts demand parallel quality system structures. |
| Meshed Graft Processing Automation | Computer-controlled meshing systems reduce technician-dependent variability and expand donor tissue yield. |
| Burn Center Value Analysis Committee Engagement | Total cost-of-ownership documentation elevates processors with validated clinical outcome databases. |
Research Methodology
The analysis maps cryopreserved dermal substitute procurement, meshed graft processing automation, and ambient-stable preservation technology, each validated through tissue bank procurement directors, burn center value analysis committee members, and biomedical engineers. Primary interviews with AATB accreditation specialists, hospital purchasing managers, and organ procurement organization executives combined with secondary validation against FDA HCT/P guidance documents, EU Tissue and Cells Directive implementations, and CMS reimbursement determinations. Bottom-up triangulation across institutional procurement volumes and top-down validation against tissue bank processing capacity estimates anchored market sizing.
Assumption sets held cryopreservation protocol standardization and cold-chain logistics consolidation as fixed conditions while varying CMS outpatient reimbursement expansion pace and EU MDR reclassification timeline uncertainty. The analytical framework modeled product type, application indication, end-user facility category, and delivery logistics architecture across the projection horizon. CAGRs derived from segmented volume trajectories weighted by institutional procurement value and site-of-care economics. Forecast inputs incorporated burn center capacity concentration trends and synthetic substitute competitive intensity indices.
Sensitivities concentrate around CMS reimbursement determination reversals, EU MDR notified body inspection backlog delays, and cadaveric donation rate seasonal volatility. Forecasts reflect documented assumptions regarding regulatory pathway stability and tissue banking infrastructure investment continuity. Quarterly review of hospital value analysis committee purchasing criteria evolution and ambient-stable product pilot program outcomes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Europe Nerve Repair and Regeneration Market
Medical Treatment
Encephalitis Treatment Market
Medical Treatment
Morquio Syndrome Treatment Market
Medical Treatment
Menstrual Cramps Treatment Market
Medical Treatment
Global Fabry Disease Treatment Market
Medical Treatment
ALAD Porphyria Treatment Market
Medical Treatment
Yellow Fever Treatment Market
Medical Treatment
Cleft Lip Surgery Market
Medical Treatment
Global Thyroid Disorder Treatment Market
Medical Treatment
Migraine Treatment Market
Medical Treatment
Transarterial Chemoembolization (TACE) Market
Medical Treatment
Motion Sickness Treatment Market
Medical Treatment
Squamous Cell Carcinoma Treatment Market
Medical Treatment
Allergic Rhinitis Treatment Market
Medical Treatment
Burns Treatment Market
Medical Treatment
Avian Flu Treatment Market