
 Single Dose Radiotherapy Services Market | 2026-2036
Single Dose Radiotherapy Services Market Size, Share, and Industry Trends Forecast 2026-2036
Single Dose Radiotherapy Services Market Outlook
Equipment leasing and managed service contracts are reshaping competitive entry in single-dose radiotherapy, allowing mid-size oncology networks to deploy linear accelerators without capital ownership. Varian Medical Systems leverages its installed base of TrueBeam platforms to sustain recurring service revenue across hospital systems. Elekta AB anchors European market presence through specialized intraoperative radiotherapy configurations. GenesisCare competes via asset-light partnership models that reduce upfront facility investment for cancer treatment centers.
Single dose radiotherapy services deliver targeted radiation in one fraction using precise dose planning and image guidance, with treatments typically ranging from 8 to 24 Gy depending on tumor site and surrounding tissue tolerance, primarily eliminating malignant cells while sparing healthy structures. Stereotactic body radiotherapy dominates clinical volume for lung and liver lesions where ablative dosing achieves local control comparable to surgery. Intraoperative radiotherapy occupies a narrower but high-margin niche in breast-conserving protocols, with mobile radiotherapy units representing the fastest-growing delivery modality as regional hospitals seek decentralized access without fixed bunker construction.
The FDA regulates device clearance and clinical trial design for novel radiotherapy systems, while the EU MDR framework imposes stricter post-market surveillance and clinical evidence requirements on linear accelerator manufacturers seeking CE marking. State-level certificate-of-need laws in the United States restrict capital-intensive radiation facility expansion, directly shaping where single-dose services can proliferate. Stakeholders must monitor reimbursement coding evolution for hypofractionated protocols versus conventional fractionation, as payer policy will determine which delivery technologies achieve sustainable utilization.
Market Dynamics
Hypofractionation protocols are compressing treatment calendars from weeks to single sessions, forcing cancer centers to restructure staffing models and bunker utilization around throughput efficiency rather than appointment volume.
Growth Catalysts
- EU MDR Streamlining:The Medical Device Regulation's consolidated clinical evidence pathways accelerate CE marking for linear accelerator upgrades, reducing time-to-market for stereotactic platforms across German, French, and Italian hospital networks.
- Mobile Delivery Expansion:Truck-mounted intraoperative radiotherapy units eliminate fixed infrastructure requirements, enabling community hospitals in rural Texas and Bavaria to offer single-dose breast protocols without capital construction.
- Oncology Workforce Shortages:Radiation therapist staffing gaps in the United States and United Kingdom push treatment centers toward single-fraction alternatives that reduce total patient chair time and personnel hours per case.
Market Restraints
- Cobalt-60 Supply Concentration:Two Canadian and Russian suppliers control isotope production for legacy teletherapy units, exposing European centers to geopolitical disruption and price volatility for source replacement.
- Certificate-of-Need Regimes:Thirty-five U.S. states maintain CON laws that block new radiation facility construction, capping addressable market expansion regardless of patient demand or payer willingness.
- Tissue Tolerance Limits:Serial organ constraints prevent single-dose escalation beyond 24 Gy for most abdominal sites, restricting ablative radiotherapy to selected histologies and tumor sizes.
Strategic Opportunities
- India's Tier-2 City Penetration:Metro-level cancer incidence in Lucknow, Jaipur, and Kochi lacks proportional radiation infrastructure, creating first-mover advantage for mobile single-dose deployment without competing against established academic centers.
- Artificial Intelligence Planning:Machine learning auto-segmentation converges with Monte Carlo dose calculation to compress planning time from days to hours, enabling same-day treatment initiation for urgent palliative cases.
- Japan's Accelerated Approval Pathway:PMDA's Sakigake designation for breakthrough medical devices offers priority review for novel radiotherapy platforms, compressing regulatory timelines for manufacturers targeting the world's fastest-aging oncology population.
Industry Challenges
- Medical Physics Talent Pipeline:Board-certified dosimetrists and radiation physicists require 5-7 years of specialized training, creating recruitment bottlenecks that limit single-dose program expansion regardless of equipment availability.
- Legacy PACS Integration:Picture archiving systems at mid-size oncology networks run on decade-old DICOM standards that resist seamless incorporation of real-time MRI-guided delivery workflows, forcing expensive middleware development or complete replacement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single Dose Radiotherapy Services Market |
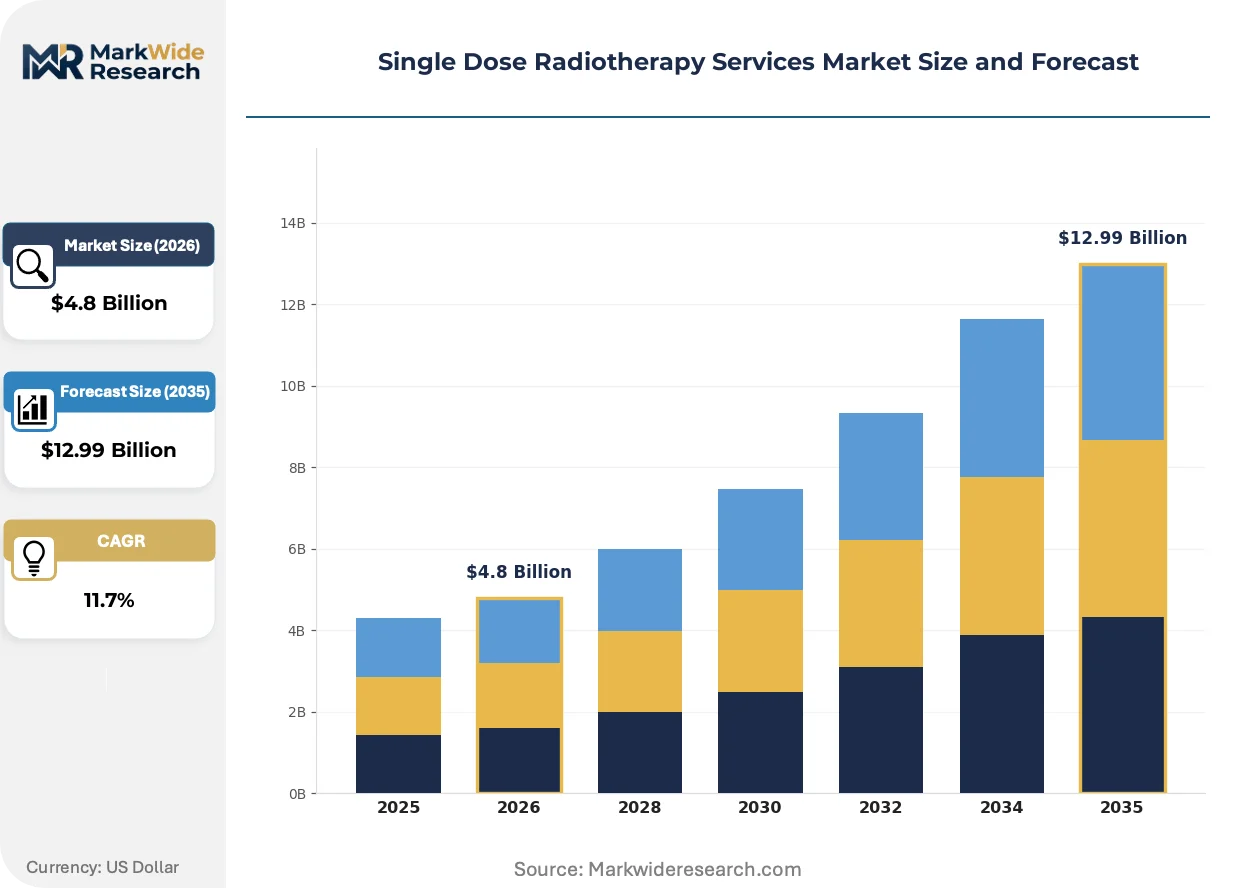
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Intraoperative Radiotherapy, Stereotactic Body Radiotherapy, Brachytherapy, High Dose Rate Therapy Application: Oncology, Pain Management, Palliative Care, Skin Disorders End User: Hospitals, Clinics, Cancer Treatment Centers, Rehabilitation Facilities Technology: Linear Accelerators, CyberKnife, Mobile Radiotherapy Units, Image-Guided Systems |
| Companies Covered | Varian Medical Systems, Elekta AB, Accuray Incorporated, GenesisCare, ViewRay Inc., Hitachi Ltd., Ion Beam Applications, Panacea Medical Technologies, IsoRay Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single Dose Radiotherapy Services Market Strategic Shifts
Digital twin technology and adaptive planning algorithms are collapsing the gap between simulation and treatment, enabling same-day delivery that redefines patient throughput expectations across academic and community settings alike.
Magnetic resonance-guided linear accelerators combine soft-tissue visualization with beam delivery, allowing clinicians to track tumor motion and adapt margins in real time. Community cancer centers in Florida and North Carolina are prioritizing these installations over conventional CT-guided platforms despite higher capital requirements. The technology is virtualizing the traditional simulation appointment, compressing care pathways from multi-week courses into single-visit experiences.
The FDA's breakthrough device designation pathway grants prioritized review and enhanced pre-submission feedback for novel radiotherapy systems demonstrating substantial advantage over approved alternatives. Manufacturers targeting lung and prostate applications leverage this status to accelerate 510(k) clearance timelines and secure early payer coverage determinations. Academic medical centers in Boston and Houston structure clinical trial partnerships around designated platforms to secure first-access positioning.
Hospital procurement departments are unbundling equipment purchase from service contracts and software licensing, treating linear accelerators as modular technology stacks rather than integrated capital purchases. This fragmentation pressures vendors to defend recurring revenue through exclusive planning software ecosystems rather than hardware lock-in. The shift is most visible in the southeastern United States, where health system consolidation has concentrated purchasing authority within centralized supply chain functions that benchmark total cost of ownership across multi-year horizons.
Single Dose Radiotherapy Services Market Segmentation
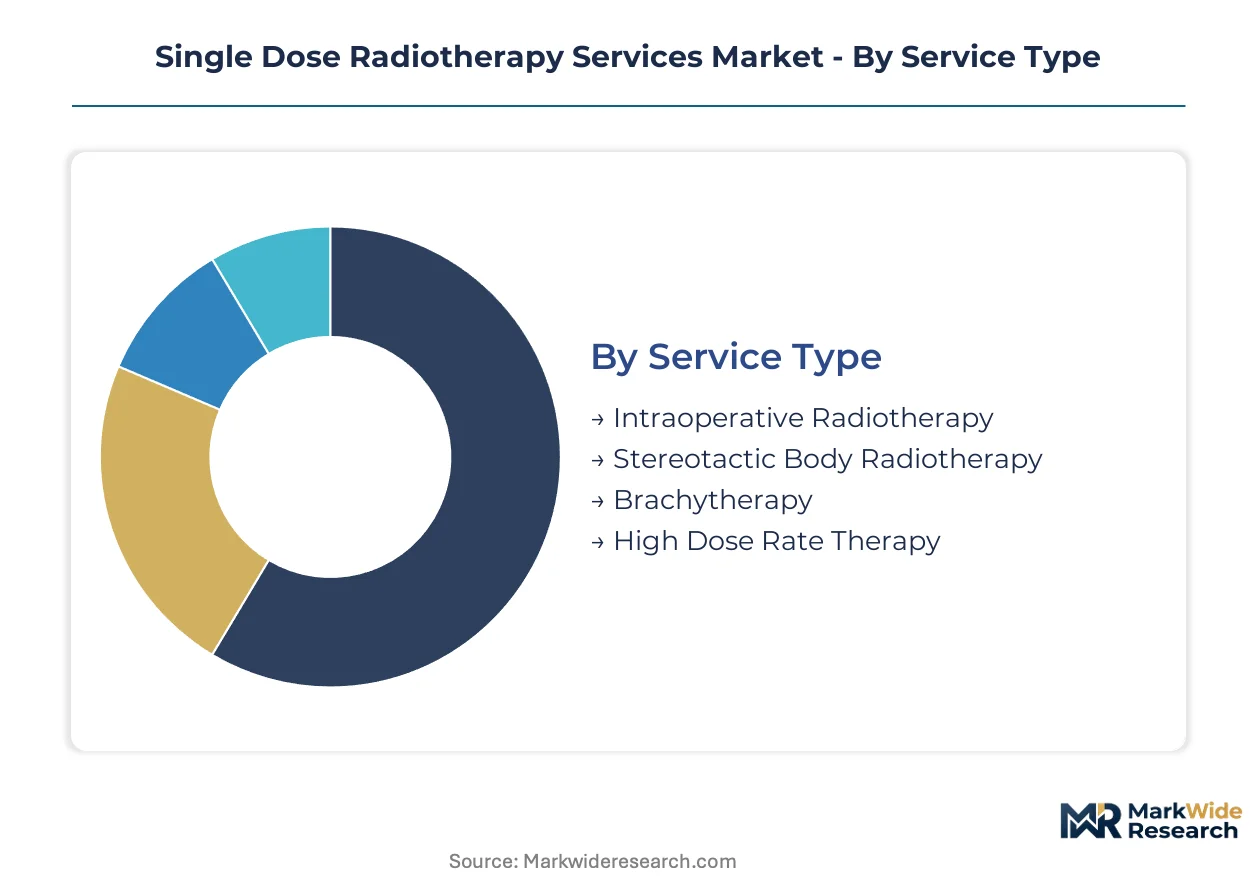
Single-dose radiotherapy services fragment across four distinct dimensions that determine reimbursement pathways, capital deployment cycles, and patient throughput economics. Each segmentation layer reveals different competitive moats and margin structures for service providers.
Service Type:
Cycle times vary dramatically — intraoperative delivery compresses treatment into surgical windows measured in minutes, while stereotactic protocols demand days of planning despite single-fraction execution.
- Intraoperative Radiotherapy:Delivers radiation directly to the tumor bed during surgical resection using mobile or fixed units, with dose delivery completed before wound closure. German breast centers in Munich and Hamburg anchor European demand for IORT, driven by intraoperative margin assessment protocols that confirm eligibility in real time.
- Stereotactic Body Radiotherapy:Employs precise external beam delivery with ablative dose escalation to extracranial targets, requiring advanced motion management and image guidance. United States academic medical centers in Boston and Houston concentrate SBRT volume for lung and liver lesions, constrained by physicist staffing bottlenecks that limit program expansion.
- Brachytherapy:Places radioactive sources directly within or adjacent to tumor tissue for localized dose deposition.
- High Dose Rate Therapy:Uses remote afterloading systems to deliver concentrated radiation through temporarily placed applicators.
Stereotactic body radiotherapy dominates installed base. Intraoperative radiotherapy is where expansion concentrates.
Application:
Margin structures diverge sharply — curative oncology commands premium reimbursement while palliative indications compete on cost efficiency and chair-time minimization.
- Oncology:Encompasses curative-intent treatment of primary and metastatic malignancies using ablative single-fraction protocols. United States cancer centers prioritize prostate and early-stage lung applications, with Medicare coverage determinations for hypofractionated schedules expanding addressable case volume.
- Pain Management:Targets vertebral compression and bone metastases with rapid pain relief as the primary endpoint. Community hospitals in Florida and North Carolina deploy single-dose protocols for spinal metastases, driven by emergency department referral pathways that demand same-day treatment initiation.
- Palliative Care:Focuses on symptom relief and quality-of-life preservation for advanced disease.
- Skin Disorders:Applies superficial radiation for non-melanoma skin cancers and keloid management.
Oncology dominates installed base. Pain management is climbing the fastest as emergency pathways mature.
End User:
Capital intensity separates the tiers — hospitals absorb full infrastructure costs while clinics and mobile operators pursue asset-light models.
- Hospitals:Maintain comprehensive radiation oncology departments with fixed bunkers, multidisciplinary tumor boards, and residency training programs. Academic medical centers in the United States anchor demand for MR-guided linear accelerators, constrained by certificate-of-need laws in thirty-five states that block facility expansion regardless of patient demand.
- Cancer Treatment Centers:Specialize exclusively in oncology service lines with streamlined pathways and dedicated patient volumes. GenesisCare operates across Australia and Spain with partnership models that reduce upfront capital requirements for regional hospital systems.
- Clinics:Deliver focused outpatient services with limited scope and lower overhead structures.
- Rehabilitation Facilities:Integrate radiation services into broader recovery and supportive care programs.
Hospitals dominate installed base. Cancer treatment centers are gaining share fastest through partnership structures.
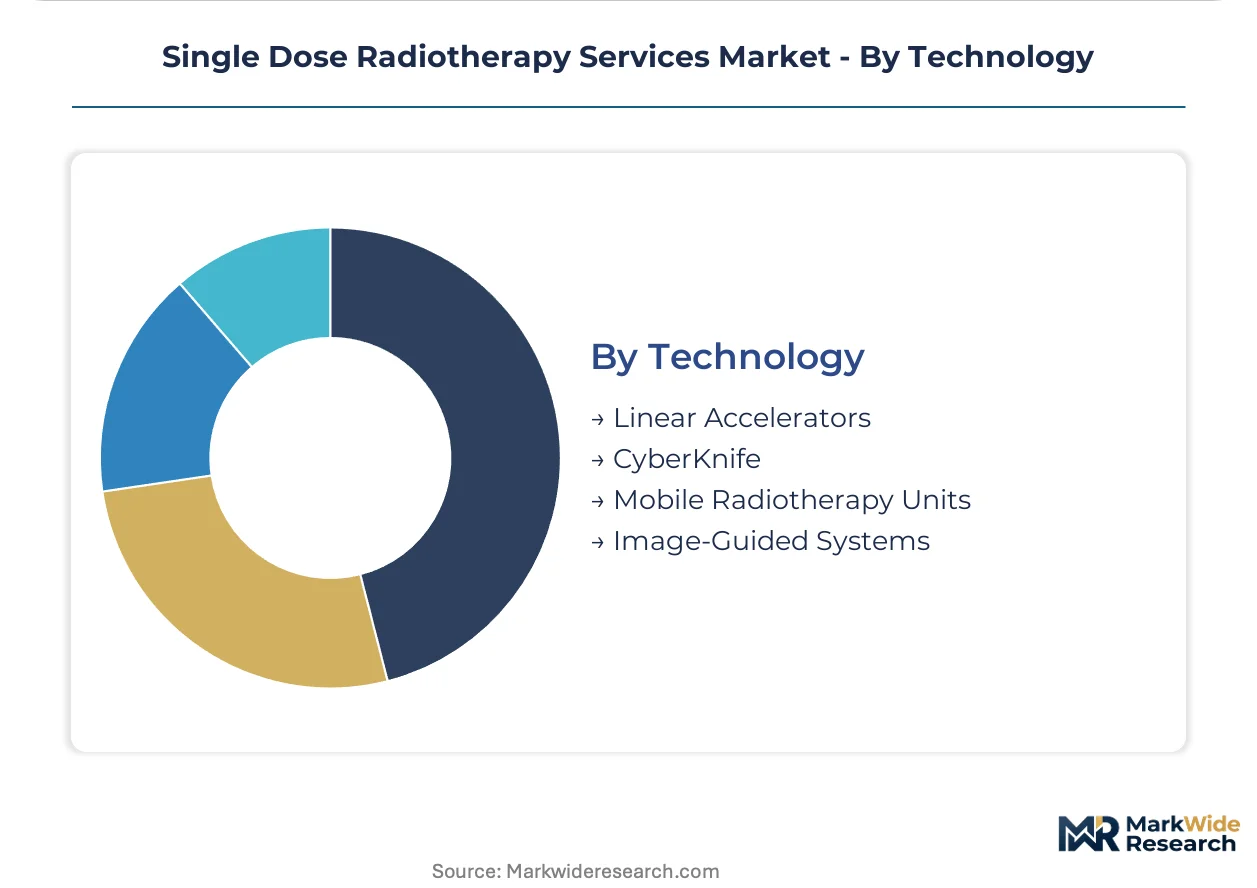
Technology:
Replacement cycles accelerate at the top tier — linear accelerators depreciate over ten to fifteen years while mobile units turn over faster due to mechanical wear and transport stress.
- Linear Accelerators:Generate megavoltage X-ray beams with multi-leaf collimation for conformal dose shaping, representing the foundational platform for external beam delivery. Varian Medical Systems sustains recurring service revenue across United States hospital networks through its installed base of TrueBeam platforms, with software licensing now unbundled from hardware purchase.
- Mobile Radiotherapy Units:Deploy truck-mounted linear accelerators or intraoperative systems to community hospitals without fixed bunkers. Rural Texas and Bavaria anchor European and United States demand, eliminating capital construction requirements and enabling decentralized access to single-dose breast protocols.
- CyberKnife:Employs robotic arm-mounted delivery with real-time tumor tracking for intracranial and extracranial targets.
- Image-Guided Systems:Integrate CT or MRI visualization directly into treatment delivery for adaptive margin management.
Linear accelerators dominate installed base. Mobile radiotherapy units represent the steepest expansion trajectory as regional hospitals seek decentralized access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic medical centers in the United States concentrate single-dose program development, while German breast centers and Japanese aging-population facilities drive protocol adoption across distinct reimbursement environments.
United States
Certificate-of-need laws in thirty-five states restrict radiation facility expansion, capping addressable market growth regardless of patient demand. The FDA's breakthrough device designation pathway accelerates clearance for novel stereotactic platforms. Boston and Houston academic medical centers structure clinical trial partnerships around designated systems to secure first-access positioning for lung and prostate applications.
Germany
Cancer treatment centers in Munich and Hamburg anchor European demand for intraoperative radiotherapy, driven by real-time margin assessment protocols during breast-conserving surgery. The EU MDR framework imposes stricter post-market surveillance requirements on linear accelerator manufacturers seeking CE marking. Bavarian hospital networks are expanding mobile radiotherapy deployment to rural communities without fixed bunker infrastructure.
Japan
The world's fastest-aging oncology population creates urgent demand for compressed treatment calendars that reduce patient mobility burdens. PMDA's Sakigake designation for breakthrough medical devices offers priority review for novel radiotherapy platforms. Tokyo and Osaka metropolitan hospitals are prioritizing MR-guided linear accelerator installations despite higher capital requirements.
India
Metro-level cancer incidence in Lucknow, Jaipur, and Kochi lacks proportional radiation infrastructure, creating first-mover opportunity for mobile single-dose deployment. The country's national pharmaceutical regulator oversees device import licensing while state governments control hospital accreditation. Tier-2 city penetration avoids direct competition against established academic centers in Delhi and Mumbai.
Australia
GenesisCare operates partnership models that reduce upfront capital requirements for regional hospital systems seeking stereotactic capability. The TGA regulates medical device registration with convergence toward EU MDR standards for clinical evidence requirements. Sydney and Melbourne cancer networks are restructuring staffing models around throughput efficiency rather than appointment volume.
Single Dose Radiotherapy Services Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented service delivery tiers. Equipment manufacturers with installed base advantages extract recurring service revenue through unbundled software licensing. Three archetypes dominate: integrated platform vendors with linear accelerator ecosystems, mobile service operators with asset-light partnership models, and specialized intraoperative system providers. Consolidation pressures favor strategic partnerships over outright acquisition, while geographic licensing agreements accelerate market entry without direct capital deployment.
Within the integrated platform tier, Varian Medical Systems and Elekta AB exemplify contrasting geographic anchors. Varian sustains recurring revenue across United States hospital networks through its installed base service infrastructure. Elekta anchors European market presence through specialized configurations aligned with regional protocol preferences. Accuray Incorporated occupies a position among robotic delivery specialists, representing the precision-tracking archetype for intracranial and extracranial applications. These three manufacturers collectively illustrate how hardware lock-in has shifted toward software ecosystem defense as procurement departments unbundle technology stacks.
| Leading Market Players |
|---|
| Varian Medical Systems |
| Elekta AB |
| Accuray Incorporated |
| GenesisCare |
| ViewRay Inc. |
| Hitachi Ltd. |
| Ion Beam Applications |
| Panacea Medical Technologies |
| IsoRay Medical |
| Others |
Value Chain & Pricing Dynamics
Canadian and Russian suppliers controlling Cobalt-60 isotope production for legacy teletherapy units concentrate upstream pricing power, forcing European cancer centers to absorb source replacement volatility while margin pools accrue to equipment manufacturers with installed base service infrastructure.
Pricing Analysis
Certification level creates the primary spread between premium FDA-breakthrough-designated platforms and standard CE-marked configurations. Three-tier pricing structure across premium, standard, and economy levels reflects software ecosystem bundling rather than hardware differentiation alone. Cost compression in mid-tier linear accelerator segments is intensifying because hospital procurement departments now unbundle equipment purchase from service contracts. Community cancer networks in the southeastern United States demonstrate highest price sensitivity, while academic medical centers in Boston and Houston prioritize first-access positioning over unit economics.
Supply Chain Analysis
Tariff exposure between North American and European component suppliers dominates supply chain risk planning for linear accelerator manufacturers. Manufacturing concentrates in Germany, the United States, and Sweden for precision gantry assemblies and multi-leaf collimator systems. Critical inputs draw from specialized cobalt-60 sources, high-purity tungsten for beam collimation, and superconducting magnet components for MR-guided platforms. Single-source vulnerability in isotope supply chains forces inventory buffering strategies. Distribution runs through hospital procurement departments and group purchasing organizations that benchmark total cost of ownership across multi-year horizons.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The five-to-seven-year training pipeline for board-certified medical physicists and dosimetrists creates a binding constraint that limits program expansion regardless of capital availability, making human capital the scarcest deployable asset in this market.
For Market Incumbents: Pre-empt physicist staffing bottlenecks by embedding training partnerships with university radiation oncology programs directly into equipment service contracts. Backward integration into AI-powered auto-segmentation software reduces planning time dependency on scarce specialist labor. Defend recurring revenue through exclusive planning software ecosystems rather than hardware lock-in as procurement departments unbundle technology stacks. For New Entrants and Emerging Players: Pursue mobile radiotherapy unit deployment in India's Tier-2 cities where metro-level cancer incidence lacks proportional infrastructure. Lucknow, Jaipur, and Kochi offer first-mover positioning without competing against established academic centers in Delhi and Mumbai. Asset-light partnership models that eliminate upfront bunker construction requirements resonate with regional hospital systems seeking stereotactic capability without capital ownership. For Investors and Strategic Acquirers: Capital is best deployed toward service operators with embedded physicist training pipelines and established hospital system partnerships rather than pure equipment manufacturers facing software unbundling pressure. Long-term viability hinges on recurring revenue visibility through managed service contracts. Watch for Medicare coverage determination shifts for hypofractionated protocols as the inflection indicator for addressable case volume expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Prioritized review accelerates 510(k) clearance timelines for stereotactic platforms targeting lung and prostate applications. |
| EU MDR CE Marking Pathway | Consolidated clinical evidence requirements reduce time-to-market for linear accelerator upgrades across German hospital networks. |
| Hospital System Partnership | GenesisCare's asset-light models reduce upfront facility investment for regional cancer treatment centers in Australia and Spain. |
| Software Companion Development | Machine learning auto-segmentation converges with Monte Carlo dose calculation to compress planning time for urgent palliative cases. |
| Reimbursement Strategy | Medicare coverage determinations for hypofractionated schedules directly shape which delivery technologies achieve sustainable utilization. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with radiation oncologists, medical physicists, hospital procurement managers, and biomedical engineers at academic medical centers and community cancer networks. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation, CMS Medicare coverage determinations, and hospital procurement databases. Bottom-up case volume estimates across service type, application, and technology segments were triangulated against top-down equipment installed base and replacement cycle analysis.
Calibration across the analysis window employed scenario-weighted projections for mobile delivery expansion, AI planning adoption curves, and physicist workforce pipeline constraints. Segmentation dimensions modeled include service type, application, end user, and technology tier alongside regional regulatory cluster variations. CAGRs were derived from equipment replacement cycles, protocol adoption trajectories, and reimbursement policy evolution rather than extrapolated from historical growth rates. Forecast inputs incorporated EU MDR implementation timelines, PMDA Sakigake designation uptake, and certificate-of-need law variations across U.S. states.
Sensitivities concentrate around Medicare reimbursement coding evolution for hypofractionated protocols, physicist training program graduation rates, and geopolitical disruption to Cobalt-60 isotope supply chains. Forecasts reflect assumptions regarding regulatory pathway efficiency and payer policy stability. Material shifts in breakthrough device designation criteria or CON law repeal in key U.S. states would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Congenital Hyperinsulinism Treatment Market
Medical Treatment
Persistent Epithelial Defect Management Market
Medical Treatment
North America Chronic Disease Management Market
Medical Treatment
Spain Hair Transplant Market
Medical Treatment
Radioactive Iodine Ablation Therapy Market
Medical Treatment
Precocious Puberty Treatment Market
Medical Treatment
Global Sex Reassignment Surgery Market
Medical Treatment
Dyspareunia Treatment Market
Medical Treatment
Cervical Cancer Treatment Market
Medical Treatment
Tetanus Treatment Market
Medical Treatment
Migraine Treatment Market
Medical Treatment
Histoplasmosis Treatment Market
Medical Treatment
Mercury Poisoning Treatment Market
Medical Treatment
Hyperammonemia Treatment Market
Medical Treatment
Basal Cell Carcinoma Treatment Market
Medical Treatment
Surgical Procedures Volume Market