
 Middle East and Africa HIV Diagnosis and Treatment Market | 2026-2036
Middle East and Africa HIV Diagnosis and Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa HIV Diagnosis and Treatment Market Outlook
Buyer concentration among public hospital networks is hardening across the Middle East and Africa. Gilead Sciences leverages its portfolio of fixed-dose antiretroviral combinations to sustain long-term supply agreements with national treatment programs. Roche anchors its position through automated viral load monitoring platforms deployed in reference laboratories from Johannesburg to Casablanca. Abbott Laboratories differentiates via point-of-care molecular diagnostics that extend reach into peripheral clinic settings with limited infrastructure.
HIV diagnosis and treatment encompasses the clinical identification of human immunodeficiency virus infection through serological, molecular, or antigen-based assays, paired with sustained administration of antiretroviral drug regimens to suppress viral replication and preserve immune function. Antiretroviral Therapy commands the dominant value share due to lifelong treatment requirements and patent-protected fixed-dose combinations, while Diagnostic Kits represent the fastest-expanding segment as countries decentralize testing from centralized labs to community sites. Testing Services generate stable recurring revenue through government-funded screening campaigns, though margin pools increasingly shift toward integrated service-delivery models that bundle diagnostics with adherence monitoring.
South Africa's SAHPRA and Nigeria's NAFDAC enforce registration standards that filter out uncertified diagnostic kits, while WHO prequalification serves as the de facto gateway for donor-funded procurement across the region. The EU AI Act and MDR frameworks indirectly shape expectations for automated diagnostic platforms imported from European suppliers. Stakeholders must monitor how national health insurance expansions in Ghana and Ethiopia alter reimbursement pathways and procurement centralization.
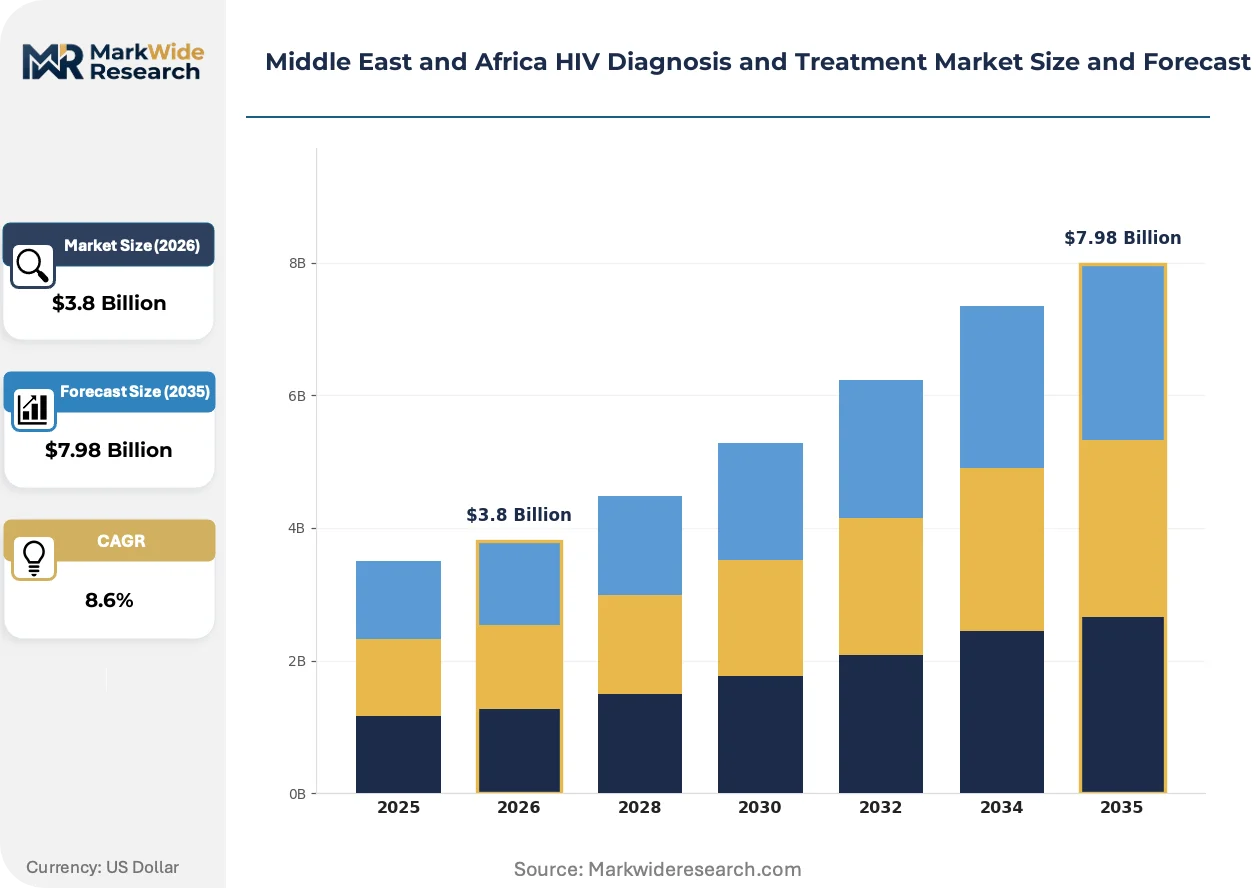
Market Dynamics
Decentralization of HIV testing from centralized reference laboratories to peripheral clinic networks is compressing equipment footprints and reconfiguring procurement specifications across the Middle East and Africa.
Growth Catalysts
- WHO Prequalification Pathway:The WHO prequalification program for in-vitro diagnostics accelerates supplier eligibility for Global Fund and PEPFAR procurement channels across East African community health programs.
- Point-of-Care Molecular Platforms:Cartridge-based nucleic acid testing technologies eliminate cold-chain dependencies and enable same-day treatment initiation in rural Nigerian health posts.
- South Africa's National Health Insurance:The phased NHI rollout consolidates antiretroviral procurement under national tendering, creating volume commitments that stabilize manufacturer supply planning.
Market Restraints
- Reagent Import Dependence:Diagnostic consumables and control materials rely on European and North American manufacturing hubs, exposing East African laboratory networks to currency volatility and shipping disruptions.
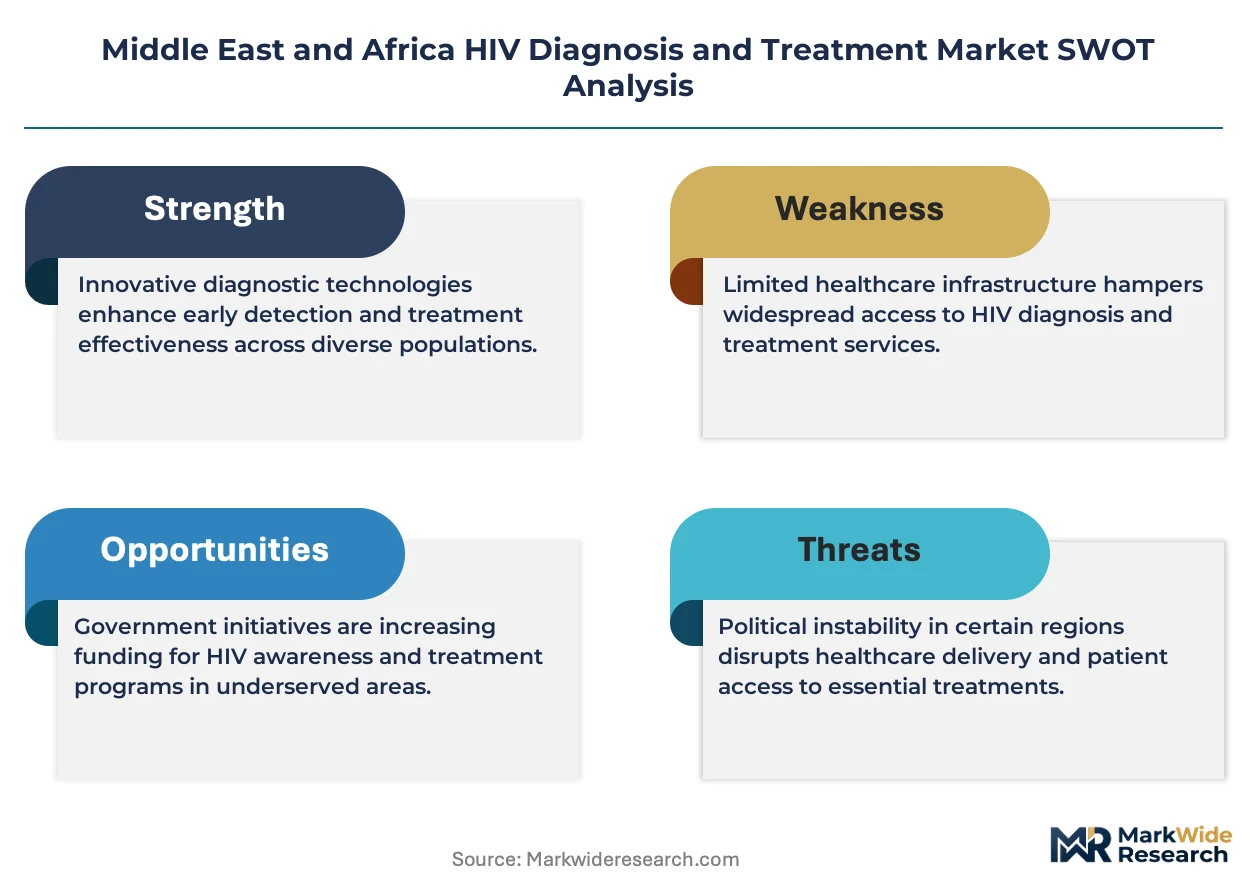
- Patent-Protected Fixed-Dose Combinations:Gilead Sciences' tenofovir alafenamide formulations maintain exclusivity through 2030 in multiple Middle East and Africa jurisdictions, limiting generic substitution.
- Power Infrastructure Gaps:Automated viral load platforms require stable electricity and climate control unavailable in 40% of Ethiopian primary health centers, constraining deployment scope.
Strategic Opportunities
- Drone-Enabled Sample Transport:Rwanda's Zipline network and emerging Kenyan programs create cold-chain bypass options for dried blood spot collection from remote clinics to reference laboratories.
- Self-Testing Regulatory Expansion:SAHPRA's 2023 approval framework for HIV oral self-tests opens direct-to-consumer channels previously restricted to clinical settings.
- Integration with Maternal Health:PMTCT programs in Nigeria and Kenya create bundled procurement opportunities combining HIV diagnostics with syphilis and hepatitis B screening.
Industry Challenges
- Biomedical Engineering Shortage:Maintenance and calibration of Roche and Abbott automated platforms outpaces trained technician supply in Ghana and Tanzania, extending equipment downtime.
- Multi-Disease Platform Validation:COVID-19 repurposing of molecular diagnostic infrastructure created validation backlogs for HIV assay integration, delaying dual-use deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa HIV Diagnosis and Treatment Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiretroviral Therapy, Diagnostic Kits, Testing Services, Monitoring Tools Service Type: In-Hospital Care, Outpatient Services, Home Healthcare, Telemedicine End User: Hospitals, Clinics, Laboratories, Community Health Organizations Delivery Mode: Oral, Injectable, Intravenous, Novel Formulations |
| Companies Covered | Gilead Sciences, ViiV Healthcare, Roche, AbbVie, Bristol-Myers Squibb, Johnson & Johnson, Merck & Co., Abbott Laboratories, Thermo Fisher Scientific, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa HIV Diagnosis and Treatment Market Strategic Shifts
Convergence of portable molecular diagnostics with digital adherence monitoring is restructuring service delivery models across the Middle East and Africa, compressing the gap between diagnosis and viral suppression.
Cartridge-based point-of-care viral load testing is consolidating previously fragmented testing workflows. Ministries of health in Uganda and Mozambique are embedding these platforms in nurse-staffed facilities lacking laboratory infrastructure. The technology is consolidating demand for centralized reference laboratory capacity into distributed same-day result generation.
WHO's 2022 guidance on HIV self-testing and the subsequent SAHPRA and NAFDAC implementation frameworks are mandating quality assurance protocols that filter uncertified suppliers from national tenders. Manufacturers must now submit stability data under tropical temperature conditions. Diagnostic kit suppliers are responding by reformulating buffer compositions and extending shelf-life claims for ambient storage.
Community health worker deployment models are displacing facility-based screening as the primary case-finding channel. Ethiopia's Health Extension Program and Nigeria's Ward Development Committees now account for majority first-time diagnoses in rural catchments. Kenya's differentiated service delivery models demonstrate the most advanced integration, linking mobile testing to decentralized drug distribution through accredited community pharmacies.
Middle East and Africa HIV Diagnosis and Treatment Market Segmentation
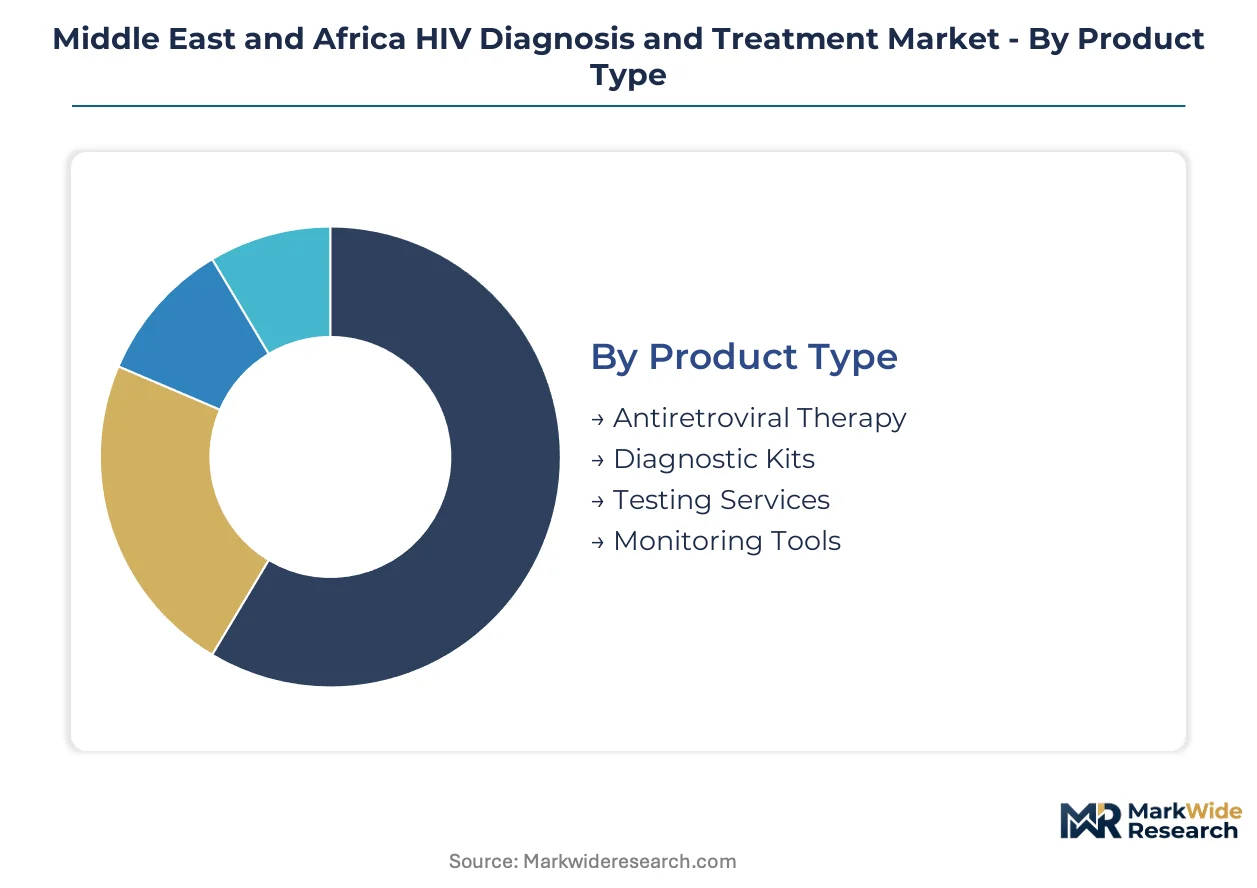
Segmentation in the Middle East and Africa HIV diagnosis and treatment market reveals how procurement flows split between centralized national tenders and decentralized community channels. Understanding these divisions illuminates where volume concentrates versus where margins expand.
Product Type:
Product differentiation tracks the shift from reference laboratory dependence toward point-of-care deployment across East and West African health networks.
- Antiretroviral Therapy:Fixed-dose combinations of tenofovir, lamivudine, and dolutegravir constitute first-line regimens. South Africa's national tendering absorbs the majority of regional volume, with Nigeria's public hospital networks representing the second-largest procurement pool.
- Diagnostic Kits:Rapid serological assays and nucleic acid test cartridges enable same-day diagnosis in peripheral clinics. Kenya's community health programs and Ethiopia's Health Extension Program drive demand for heat-stable formulations that bypass cold-chain requirements.
- Testing Services:Government-funded screening campaigns generate recurring revenue through mobile testing units and door-to-door outreach.
- Monitoring Tools:Viral load platforms and CD4 counters support treatment adherence tracking in reference laboratories.
Antiretroviral Therapy leads on scale; Diagnostic Kits lead on momentum.
Service Type:
Service configuration reflects infrastructure gaps that push care delivery toward lower-cost settings as countries expand health insurance coverage.
- Outpatient Services:Nurse-led differentiated service delivery models in Kenya and Mozambique handle stable patients without physician visits. These programs reduce facility congestion while maintaining viral suppression rates through community pharmacy drug distribution.
- Home Healthcare:Community health workers in Ethiopia and Nigeria manage adherence support and symptom monitoring for patients with advanced disease or mobility constraints.
- In-Hospital Care:Tertiary facilities manage opportunistic infections and treatment failure cases requiring specialist intervention.
- Telemedicine:Mobile-based appointment scheduling and adherence reminders extend reach into remote catchments with provider shortages.
Outpatient Services captures the dominant patient volume; Home Healthcare shows the steepest expansion trajectory as community health worker programs scale.
End User:
End-user concentration tracks the decentralization mandate from national treatment programs toward peripheral access points.
- Hospitals:Public hospital networks in South Africa and Nigeria anchor procurement of automated viral load platforms and second-line antiretroviral regimens.
- Community Health Organizations:Ethiopia's Health Extension Program and Nigeria's Ward Development Committees now account for majority first-time diagnoses in rural catchments. These entities drive demand for portable diagnostics and simplified treatment protocols.
- Clinics:Primary health centers handle initiation of first-line therapy and routine follow-up.
- Laboratories:Reference laboratories in Johannesburg, Nairobi, and Casablanca perform confirmatory testing and resistance genotyping.
Hospitals retain the highest per-site expenditure; Community Health Organizations are gaining share fastest as case-finding shifts to the periphery.
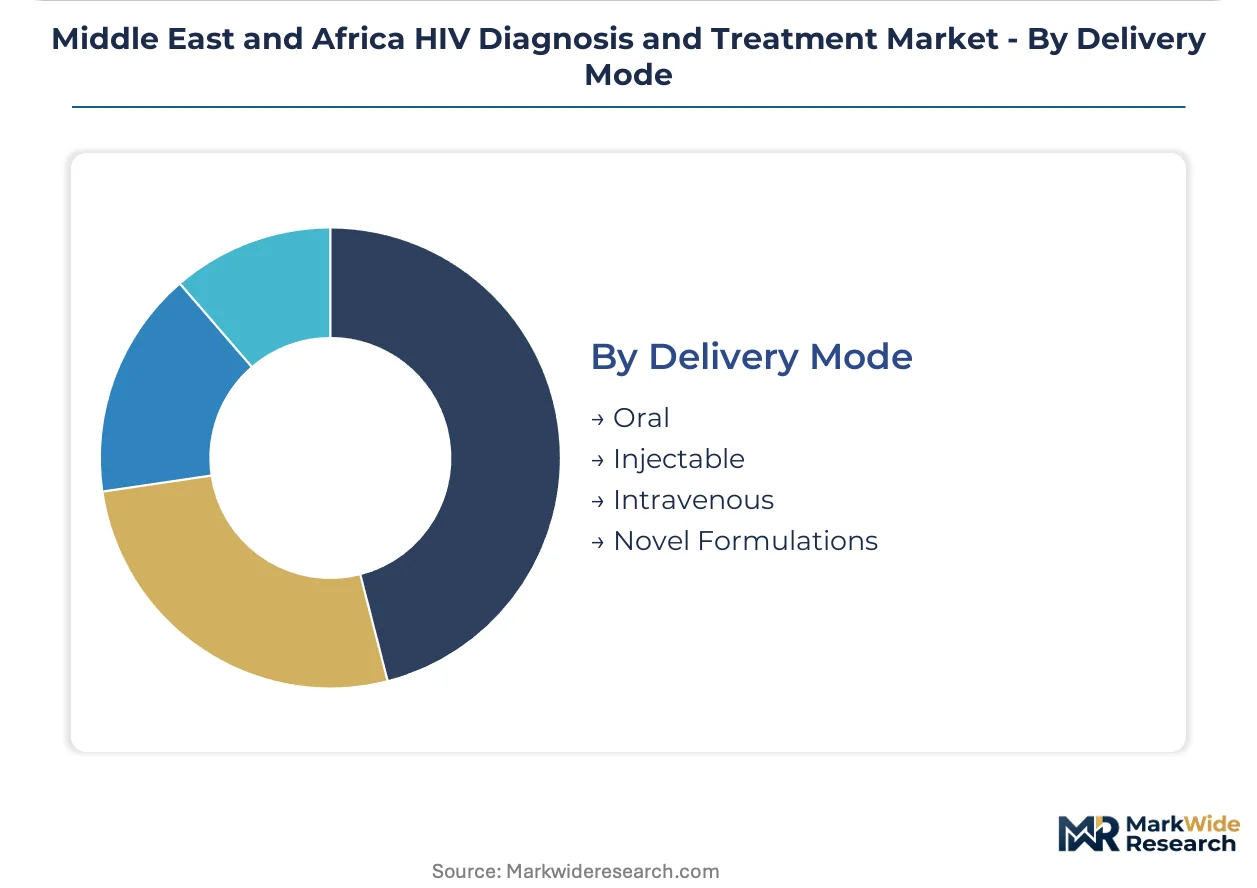
Delivery Mode:
Delivery innovation centers on reducing dosing frequency and eliminating cold-chain dependencies for last-mile distribution.
- Oral:Once-daily fixed-dose tablets dominate first-line therapy across all national programs. Heat-stable formulations from multiple suppliers compete on tender price in South Africa and Nigeria.
- Injectable:Long-acting cabotegravir and rilpivirine formulations are entering pilot programs in Kenya and South Africa for treatment-experienced patients seeking adherence support alternatives.
- Intravenous:Reserved for hospitalized patients with severe opportunistic infections or those unable to tolerate oral intake.
- Novel Formulations:Implantable devices and transdermal patches remain in early development with limited regional availability.
Oral formulations command absolute volume dominance; Injectable options are climbing the fastest as implementation science programs mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa absorbs the largest procurement volume while Nigeria scales community health infrastructure fastest, revealing divergent national strategies across the region.
South Africa
SAHPRA registration requirements filter uncertified diagnostic kits from national tenders. The National Health Insurance rollout consolidates antiretroviral procurement under centralized contracting. Johannesburg and Cape Town anchor automated viral load platform deployment in reference laboratories.
Nigeria
NAFDAC enforcement of WHO prequalification standards reshapes supplier eligibility for Global Fund channels. Ward Development Committees now drive majority first-time diagnoses in rural catchments. Lagos and Abuja concentrate point-of-care molecular diagnostic procurement for peripheral clinic networks.
Kenya
Community health programs generate demand for heat-stable diagnostic formulations that bypass cold-chain requirements. National tendering reforms under the Ministry of Health streamline supplier qualification pathways. Nairobi anchors reference laboratory capacity while Mombasa handles regional distribution logistics.
Ethiopia
The Health Extension Program displaces facility-based screening as the primary case-finding channel in rural areas. Power infrastructure gaps constrain deployment of automated platforms in 40% of primary health centers. Addis Ababa concentrates confirmatory testing and resistance genotyping services.
Uganda
Ministry of Health embedding of cartridge-based viral load platforms in nurse-staffed facilities accelerates same-day result generation. WHO prequalification serves as the de facto gateway for PEPFAR-funded procurement. Kampala anchors regional training programs for community health worker deployment.
Middle East and Africa HIV Diagnosis and Treatment Market Competitive Environment
North American pharmaceutical producers anchor the antiretroviral tier; European diagnostic specialists hold the testing and monitoring segment. The market structure bifurcates between patent-protected drug portfolios and technology-differentiated diagnostic platforms. Three archetypes dominate: fixed-dose combination suppliers, automated platform manufacturers, and point-of-care specialists. Competitive moves center on long-term supply agreements with national treatment programs and geographic expansion through WHO prequalification pathways.
Within the pharmaceutical tier, Gilead Sciences and ViiV Healthcare occupy positions defined by antiretroviral portfolio breadth. Among diagnostic specialists, Roche exemplifies the automated platform archetype through reference laboratory anchoring. Abbott Laboratories represents the point-of-care expansion vector, with cartridge-based technologies extending into peripheral clinic settings. These three entities collectively illustrate how competitive positioning splits between centralized laboratory dependence and decentralized community access.
| Leading Market Players |
|---|
| Gilead Sciences |
| ViiV Healthcare |
| Roche |
| AbbVie |
| Bristol-Myers Squibb |
| Johnson & Johnson |
| Merck & Co. |
| Abbott Laboratories |
| Thermo Fisher Scientific |
| Others |
Value Chain & Pricing Dynamics
Donor-backed procurement consortia concentrate purchasing power across East and West African national treatment programs, compressing supplier margins while extending payment cycles that strain working capital for diagnostic kit manufacturers.
Pricing Analysis
Capacity additions in South Africa's domestic pharmaceutical packaging sector are reshaping price floors for heat-stable antiretroviral formulations. Three-tier pricing structure across premium, standard, and economy levels separates originator fixed-dose combinations from licensed generics and regional tender winners. Price differentiation rests on WHO prequalification status and cold-chain exemption certification. Cost compression in rapid diagnostic kits is intensifying because Kenyan and Ethiopian community health programs are consolidating procurement under national insurance expansions. Public hospital networks exhibit highest price sensitivity due to budget caps; private clinic chains in Nigeria's urban corridors show lowest sensitivity when same-day result guarantees are bundled.
Supply Chain Analysis
Direct-to-laboratory channels handle automated platform demand from Johannesburg and Casablanca reference facilities, while distributor-mediated routes serve peripheral clinic networks lacking procurement capacity. Geographic supply concentration centers on India for active pharmaceutical ingredients, Ireland for diagnostic reagent formulations, and Singapore for cartridge-based nucleic acid testing consumables. Raw material dependencies include tenofovir alafenamide intermediates, lyophilized enzyme preparations, and temperature-stable buffer matrices. Single-source vulnerability runs through European Union manufacturing hubs for control materials and calibrators. Distribution runs through regional logistics partners in Nairobi and Lagos that manage last-mile cold-chain exceptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as lifelong antiretroviral treatment requirements generate recurring revenue streams insulated from short-term procurement cycles.
For Market Incumbents: Lock in long-term supply agreements with South Africa's National Health Insurance consolidated tendering before Nigeria's NAFDAC completes its supplier registry overhaul. Deepen backward integration into heat-stable formulation manufacturing to offset reagent import dependence exposure. Prioritize biomedical engineering training partnerships in Ghana and Tanzania to reduce equipment downtime penalties that threaten reference laboratory contracts. For New Entrants and Emerging Players: Community health organizations in Ethiopia's Health Extension Program represent the most penetrable channel for point-of-care molecular diagnostics lacking laboratory infrastructure. Drone-enabled sample transport networks in Rwanda and Kenya offer partnership entry points for dried blood spot logistics specialists. Pursue WHO prequalification as the primary go-to-market credential; SAHPRA and NAFDAC implementation frameworks now mandate this pathway for national tender eligibility. For Investors and Strategic Acquirers: Valuations sit cheapest among point-of-care diagnostic specialists with tropical stability data packages but incomplete African distributor networks. The five-to-ten-year viability window favors platforms integrating viral load testing with digital adherence monitoring. Acquisition targets should demonstrate cartridge-based nucleic acid technologies with ambient storage claims. The signal to monitor is SAHPRA's expanding self-testing regulatory framework, which could unlock direct-to-consumer channels previously restricted to clinical settings.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway | Unlocks Global Fund and PEPFAR procurement channels across East African community health programs. |
| Heat-Stable Formulation Development | Eliminates cold-chain dependencies that constrain deployment in Ethiopian primary health centers. |
| Biomedical Engineering Training Partnership | Addresses technician shortages that extend Roche and Abbott platform downtime in Ghana and Tanzania. |
| Drone-Enabled Logistics Integration | Creates cold-chain bypass options for Zipline networks serving remote Rwandan and Kenyan clinics. |
| Self-Testing Regulatory Expansion | Opens direct-to-consumer channels through SAHPRA's 2023 HIV oral self-test approval framework. |
Study Parameters
Coverage spans the Middle East and Africa region, with primary inputs from each national market cluster. The research combines structured interviews with antiretroviral procurement officers at South Africa's national tendering authority, diagnostic platform biomedical engineers in Nairobi and Casablanca reference laboratories, and community health program directors in Ethiopia's Health Extension Program. Secondary validation draws from WHO prequalification listings, Global Fund procurement disclosures, SAHPRA and NAFDAC registration databases, and national health insurance expansion policy documents. Bottom-up patient volume modeling and top-down pharmaceutical procurement value triangulation anchor the analytical framework.
Granularity-level modeling disaggregates volume and value across product type, service configuration, end-user setting, and delivery mode dimensions. Segmentation tracks antiretroviral therapy line position, diagnostic kit platform technology, outpatient versus home healthcare service models, hospital versus community organization end-user concentration, and oral versus injectable administration routes. CAGRs derive from patient enrollment trajectories, treatment initiation rates, and diagnostic testing frequency assumptions. Forecast inputs include national health insurance coverage expansion timelines and WHO prequalification approval velocities for new diagnostic platforms.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to South Africa's NHI implementation pace and Ethiopian power infrastructure investment cycles. The analysis reflects assumptions regarding sustained donor funding commitments and stable currency convertibility for reagent import financing. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Global Predictive and Presymptomatic Testing Market
Diagnostics
Critical Care Diagnostics Market
Diagnostics
Argentina in Vitro Diagnostics Market
Diagnostics
Connected Diagnostics Market
Diagnostics
Global Phytopathological Disease Diagnostics Market
Diagnostics
Fructosamine Test Market
Diagnostics
DNA and RNA Probes Market
Diagnostics
Tuberculosis (TB) Diagnostics Market
Diagnostics
Global Serological Testing Market
Diagnostics
Global Paper Diagnostics Market
Diagnostics
Diagnostic Enzymes Market
Diagnostics
Europe Molecular Diagnostics Market
Diagnostics
Poultry Diagnostics Market
Diagnostics
Europe Kidney Cancer Diagnostics Market
Diagnostics
Global Syphilis Immunoassay Diagnostics Market
Diagnostics
Thrombosis and Hemostasis Biomarkers Market