
 Japan Industrial Insulation Market | 2026-2036
Japan Industrial Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Industrial Insulation Market Insights
Project finance for energy-efficiency retrofits is fragmenting the competitive landscape, allowing mid-scale contractors to bid on insulation packages previously reserved for integrated engineering firms. NICHIAS Corporation leverages its ceramic fiber expertise to dominate high-temperature petrochemical applications. IBIDEN Co., Ltd. anchors its position through captive supply of specialty glass wool to captive power plants and semiconductor fabs. A&A Material Corporation differentiates via deep technical service relationships with regional chemical processors.
Japan industrial insulation encompasses engineered materials—fiberglass, mineral wool, cellular glass, and rigid foam—designed to reduce thermal bridging, attenuate noise, and prevent fire propagation in facilities operating above 200°C. These systems integrate with cladding, vapor barriers, and expansion joints to maintain process temperatures and protect personnel across continuous-duty industrial environments. Fiberglass and mineral wool command the largest installed base due to cost efficiency and broad temperature compatibility, while cellular glass gains traction in cryogenic and sub-sea applications where moisture resistance commands premium positioning. Thermal insulation and pipe insulation together represent the dominant revenue pool, though acoustic insulation is expanding fastest around Osaka Bay manufacturing clusters facing stricter noise ordinances.
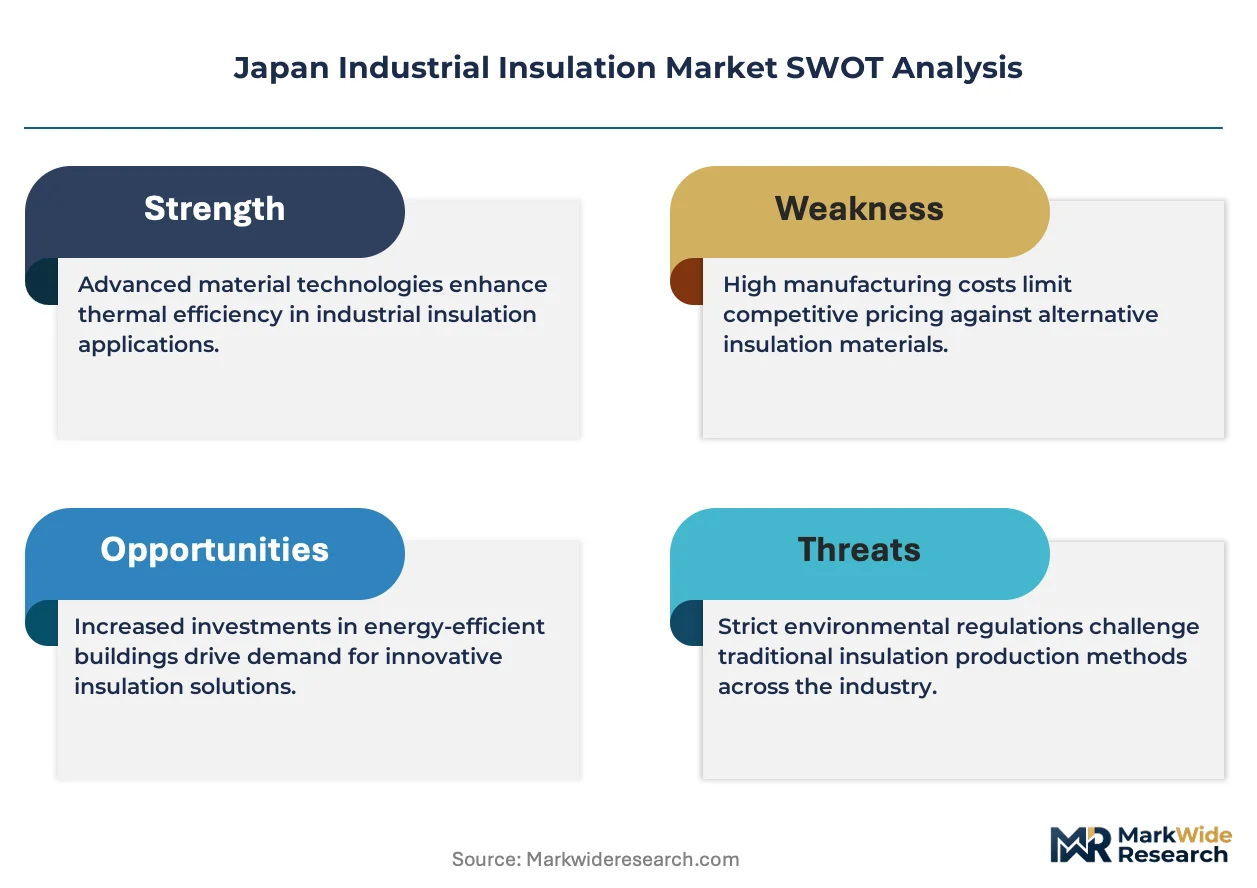
METI enforces the Energy Conservation Act and associated Top Runner standards that mandate periodic energy audits and retrofit obligations for designated factories, directly stimulating insulation replacement cycles. JIS standards govern material fire performance and thermal conductivity ratings, creating compliance barriers for uncertified imports and favoring domestic producers with established testing relationships. PMDA and local fire authorities coordinate on industrial facility safety inspections, embedding insulation integrity into broader hazard assessments. Stakeholders must track how anticipated carbon border adjustments and facility decarbonization pledges will reshape specification priorities and supplier qualification requirements.
Market Dynamics
METI's amended Energy Conservation Act is compressing replacement cycles for thermal insulation systems across designated factories, forcing facility managers to prioritize high-performance materials over legacy specifications.
Growth Catalysts
- Top Runner Standards:Japan's efficiency mandates require periodic energy audits and retrofit obligations, directly stimulating insulation replacement demand in petrochemical and power generation facilities.
- Semiconductor Fab Expansion:Specialty glass wool demand accelerates from captive power plants and advanced semiconductor manufacturing clusters in Kyushu and Tohoku regions.
- Keihin Corridor Concentration:Dense industrial infrastructure spanning Tokyo and Kanagawa Prefecture creates sustained demand for thermal and acoustic insulation systems.
Market Restraints
- Alumina-Silica Raw Material Volatility:Ceramic fiber production depends on refined alumina and silica feedstock subject to energy-intensive processing costs and import dependency.
- JIS Certification Barriers:Domestic fire performance and thermal conductivity standards create compliance friction for uncertified imports, limiting supplier diversification.
- Rigid Foam Substitution Pressure:Polyisocyanurate and phenolic foam systems compete for mid-temperature applications below 400°C, eroding mineral wool's cost advantage.
Strategic Opportunities
- Osaka Bay Noise Ordinance Compliance:Stricter acoustic regulations around manufacturing clusters create expansion potential for sound-attenuation insulation packages.
- Hydrogen Economy Infrastructure:Cryogenic pipeline networks for liquid hydrogen transport require cellular glass systems with proven moisture resistance at sub-zero temperatures.
- Carbon Border Adjustment Preparation:Anticipated trade mechanisms reward domestic producers with verified lifecycle emissions data, favoring localized supply chains.
Industry Challenges
- Certified Installer Shortage:Complex integration with cladding, vapor barriers, and expansion joints demands skilled technicians familiar with JIS-compliant application protocols.
- Legacy System Retrofit Complexity:Continuous-duty industrial environments require phased installation without production shutdowns, extending project timelines and coordination costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Industrial Insulation Market |
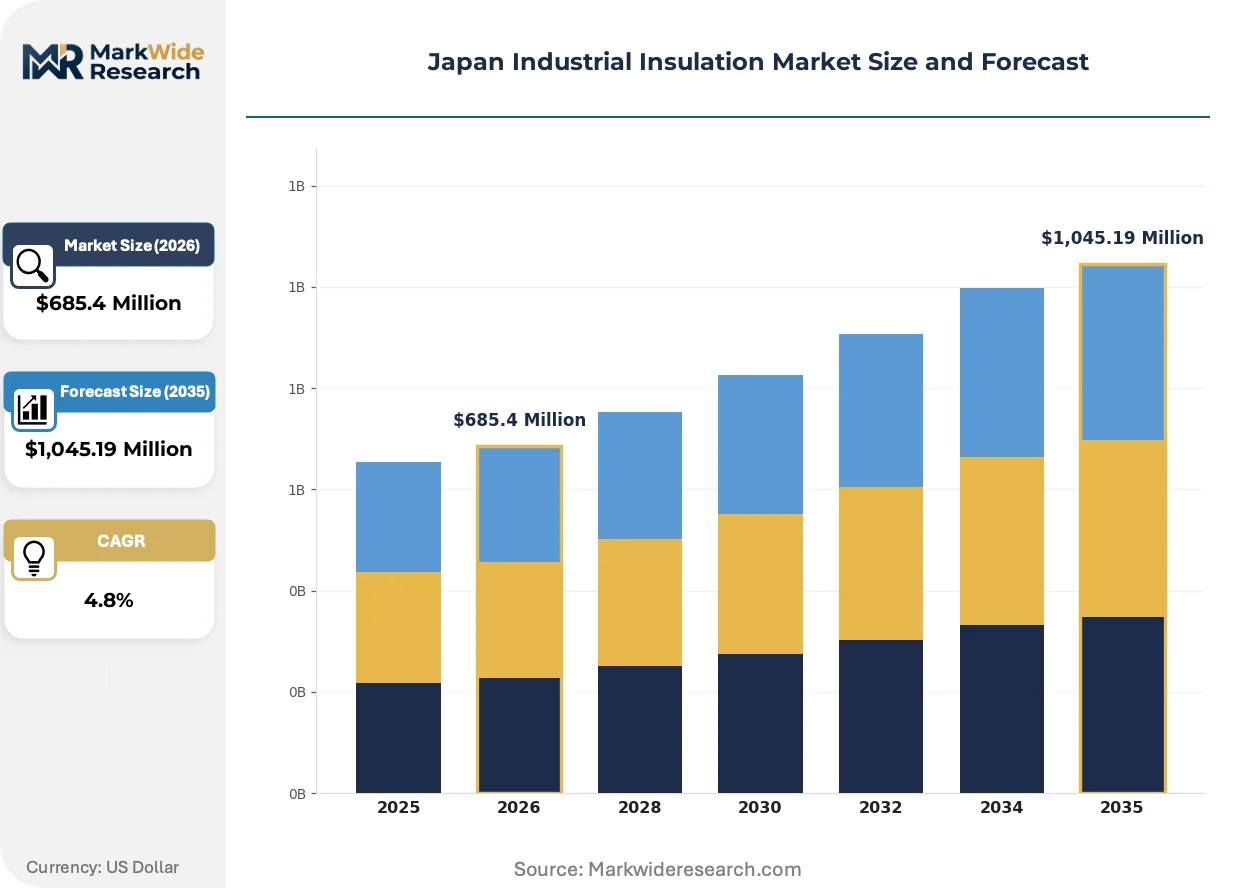
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,045.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiberglass, Mineral Wool, Foam, Cellular Glass End User: Manufacturing, Oil & Gas, Power Generation, Chemical Processing Application: Thermal Insulation, Acoustic Insulation, Fire Protection, Pipe Insulation Installation Type: New Construction, Retrofit, Maintenance, Industrial Upgrades |
| Companies Covered | 日本ケイカル株式会社, 株式会社フセアス, NICHIAS Corporation, 熊澤産業株式会社, SHINTO Industrial Co., Ltd., IBIDEN Co., Ltd., A&A Material Corporation, Yoshikawa Industry Co., Ltd., Isolite Insulating Products Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Industrial Insulation Market Trends and Innovations
Aerogel composite formulations and digitized thermal monitoring systems are redefining performance benchmarks, while procurement patterns shift toward lifecycle contracting models.
Aerogel-enhanced blanket insulation is collapsing the thickness-performance tradeoff that historically favored mineral wool in space-constrained petrochemical units. Refinery operators in the Keihin corridor are specifying silica aerogel composites for high-temperature piping where envelope dimensions are fixed. The technology is collapsing installed volume requirements and reducing structural load on existing support steel.
METI's 2023 amendments to the Energy Conservation Act mandate granular energy consumption reporting for designated factories above threshold energy use. Facility managers must now document thermal efficiency improvements in periodic audits, embedding insulation performance into compliance workflows. Chemical processors in Kanagawa Prefecture are responding by pre-emptively upgrading pipe insulation ahead of inspection cycles.
Lifecycle service contracts are displacing transactional material procurement in large-scale power generation accounts. Tokyo Electric and regional utilities now bundle insulation installation with multi-year thermal performance guarantees and predictive maintenance monitoring. This model concentrates purchasing authority with engineering-procurement-construction firms, compressing direct supplier relationships with end users.
Japan Industrial Insulation Market Segmentation
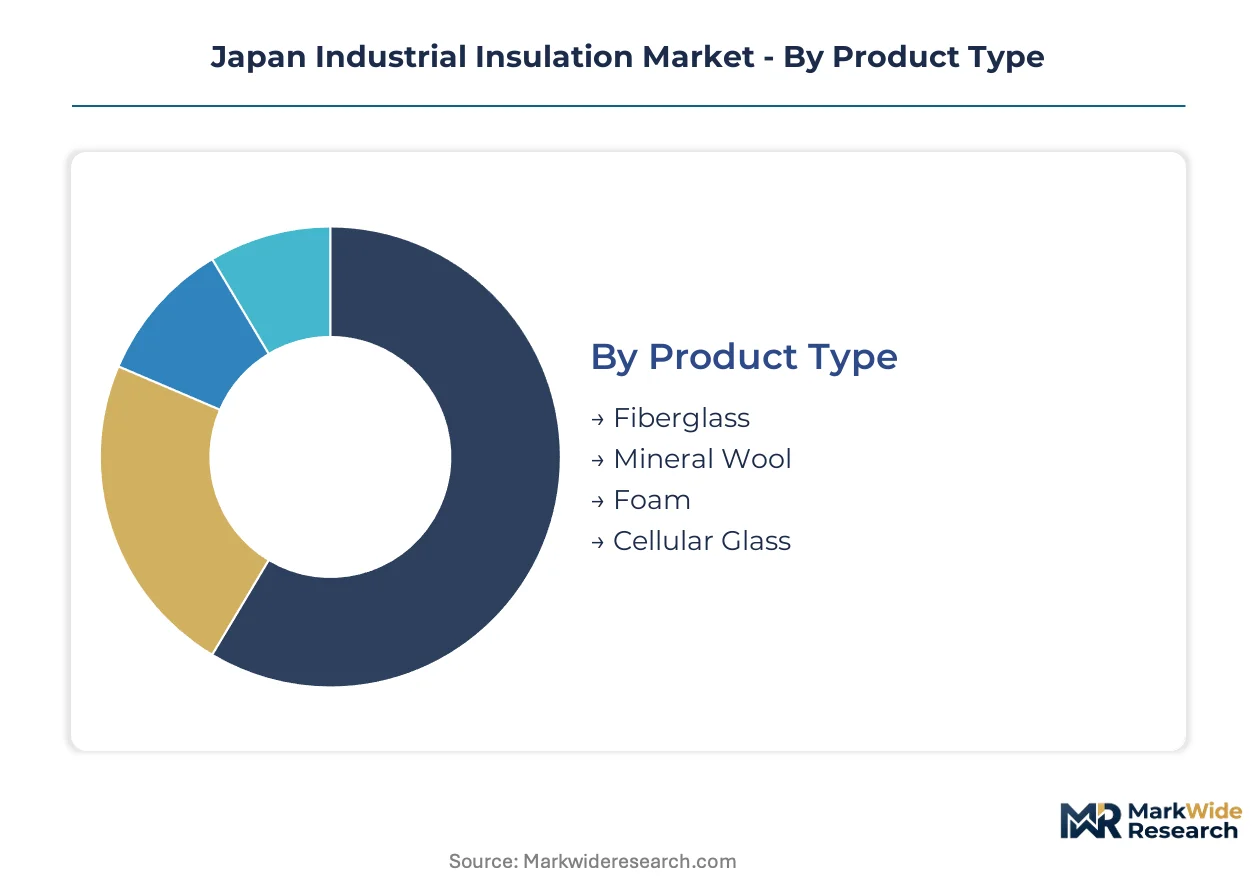
Segmentation in Japan's industrial insulation market reveals divergent replacement rhythms. Product types cycle at different speeds based on temperature exposure and mechanical degradation, while end-user verticals show stark contrasts between continuous-process industries and batch manufacturing.
Product Type:
Fiberglass and mineral wool turn over fastest due to thermal cycling fatigue in high-temperature environments, while cellular glass installations persist decades in cryogenic service. Foam systems occupy a middle ground with chemical degradation driving mid-cycle refresh.
- Fiberglass:Composed of fine glass fibers bound with thermosetting resins, delivering thermal resistance up to 540°C with moderate compressive strength. Demand concentrates in Keihin corridor power plants where METI audit cycles force systematic replacement of degraded pipe wrapping.
- Mineral Wool:Manufactured from molten rock or slag spun into fibrous mats, tolerating continuous exposure to 750°C with superior fire resistance. Petrochemical complexes in Kanagawa Prefecture specify rock wool for furnace linings under amended Energy Conservation Act compliance deadlines.
- Foam:Rigid polyisocyanurate and phenolic formulations providing high thermal resistance per inch with closed-cell moisture barriers. Cold storage and LNG receiving terminals in Osaka Bay specify foam for sub-ambient process lines.
- Cellular Glass:Foamed glass blocks with zero water absorption and dimensional stability across cryogenic to elevated temperatures. Hydrogen liquefaction pilot projects in Kyushu anchor emerging demand for sub-zero pipeline insulation.
Fiberglass anchors the volume base while cellular glass gains share at the steepest rate.
End User:
Cost tiers separate continuous-process industries with capitalized maintenance budgets from discrete manufacturing with project-based procurement. Oil & gas and chemical processing outspend manufacturing on a per-facility basis by an order of magnitude.
- Manufacturing:Discrete production facilities including automotive stamping and electronics assembly with intermittent thermal loads. Toyota and Nissan assembly plants in Aichi Prefecture specify lightweight fiberglass for paint booth temperature control.
- Oil & Gas:Refineries and LNG terminals with continuous high-temperature process streams requiring engineered insulation systems. JXTG Nippon Oil & Energy refineries in Yokkaichi deploy multi-layer mineral wool with stainless steel cladding.
- Power Generation:Thermal and nuclear plants with steam circuits operating above 500°C and strict heat rate efficiency targets. TEPCO and Chubu Electric retrofits concentrate demand in turbine building pipe galleries.
- Chemical Processing:Ethylene crackers and specialty chemical reactors with aggressive corrosion environments and frequent turnaround schedules. Mitsui Chemicals Osaka works specify acid-resistant cellular glass for sulfuric acid lines.
Power generation anchors the volume base while chemical processing climbs the fastest amid regulatory retrofit obligations.
Application:
Application types map to distinct specification hierarchies. Thermal performance dominates capital project engineering, while acoustic and fire protection respond to ordinance-driven retrofit triggers with compressed procurement timelines.
- Thermal Insulation:Systems designed to minimize heat transfer across process equipment, piping, and ductwork operating above ambient temperatures. Refinery crude units in Keihin corridor represent the largest specification volume for high-temperature pipe insulation.
- Acoustic Insulation:Sound-attenuation materials reducing machinery noise propagation to comply with occupational exposure limits and community ordinances. Osaka Bay manufacturing clusters face strict noise limits driving specification of mineral wool lagging with mass-loaded barriers.
- Fire Protection:Passive fireproofing systems maintaining structural steel integrity during hydrocarbon pool fires and jet fires. LNG terminals in Chiba Prefecture mandate cellular glass fireproofing for cryogenic spill protection.
- Pipe Insulation:Pre-formed sections and flexible wraps engineered for cylindrical surfaces with vapor barrier integration. District heating networks in Sapporo and Sendai deploy rigid foam with factory-applied aluminum jacketing.
Thermal insulation anchors the volume base while acoustic insulation expands most quickly around noise-sensitive urban manufacturing zones.
Installation Type:
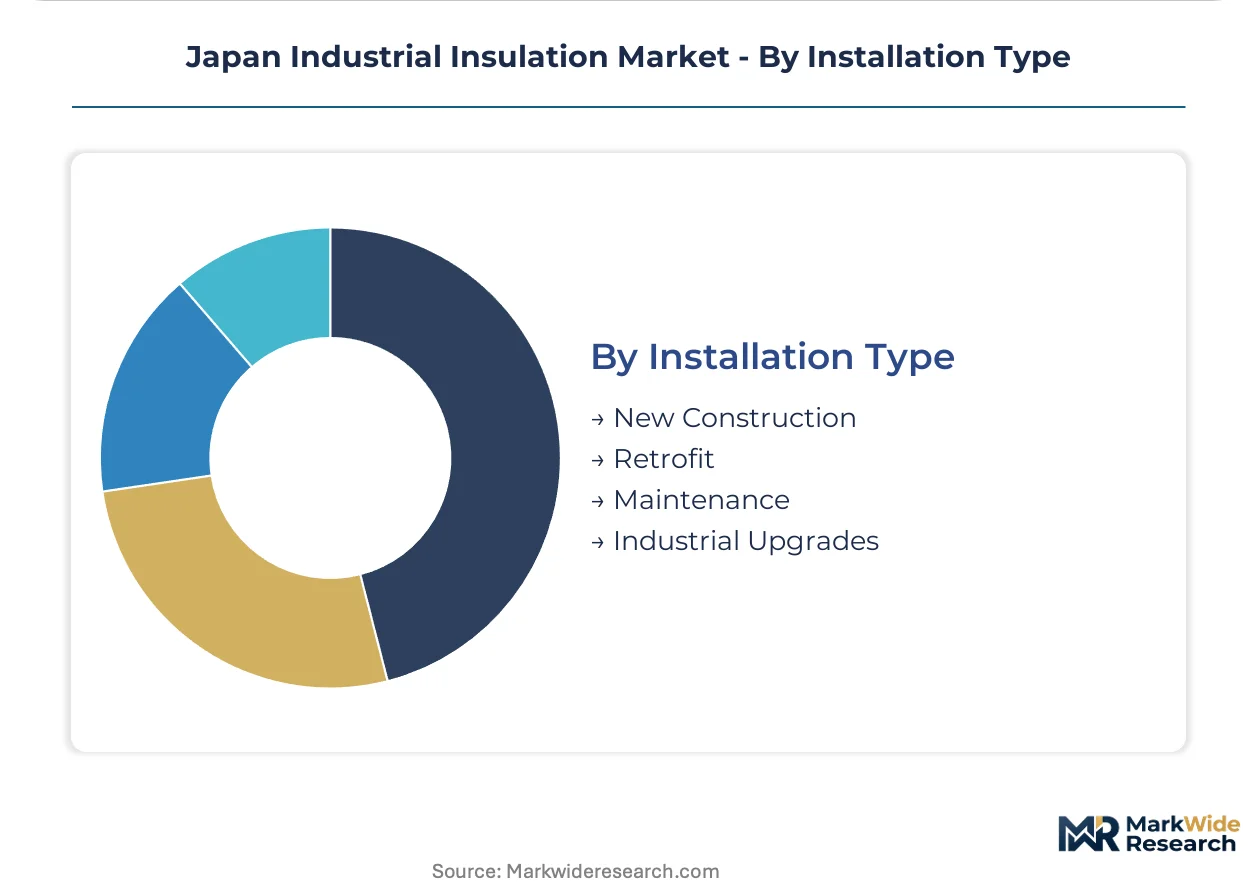
Customer type segmentation separates owner-operated maintenance teams from third-party engineering contractors. New construction flows through EPC firms with bundled procurement, while retrofit and maintenance fragment across specialist applicators.
- New Construction:Greenfield facility builds with integrated insulation specification during front-end engineering design. Semiconductor fabs under construction in Kumamoto and Hokkaido specify cleanroom-compatible fiberglass systems from commissioning.
- Retrofit:Energy-efficiency upgrades and capacity expansions requiring insulation removal and replacement in operating facilities. Designated factories under METI Energy Conservation Act face mandatory retrofit audits driving systematic pipe insulation replacement.
- Maintenance:Scheduled turnaround repair and localized damage replacement preserving existing insulation system integrity. Refinery maintenance turnarounds in Yokkaichi and Kashima concentrate demand for emergency mineral wool blanket supply.
- Industrial Upgrades:Process technology replacements with insulation system redesign for modified operating conditions. Hydrogen-ready refinery conversions in Kawasaki require cryogenic-compatible cellular glass for new hydrogen distribution headers.
Maintenance anchors the volume base while industrial upgrades accelerate on decarbonization-driven process reconfiguration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI's amended Energy Conservation Act and Top Runner standards are compressing replacement cycles for thermal insulation systems across Japan's industrial prefectures. Regional demand concentrates in legacy manufacturing belts and emerging semiconductor clusters.
Kanto/Tokyo
The Keihin industrial corridor spanning Tokyo and Kanagawa Prefecture generates sustained demand for high-temperature pipe insulation in petrochemical complexes and power plants. METI audit obligations force systematic replacement of degraded mineral wool systems in designated factories. JXTG Nippon Oil & Energy refineries in Yokkaichi deploy multi-layer insulation with stainless steel cladding under compliance deadlines.
Kansai/Osaka
Osaka Bay manufacturing clusters face stricter municipal noise ordinances driving specification of acoustic insulation packages. Chemical processors in Kanagawa Prefecture pre-emptively upgrade pipe insulation ahead of inspection cycles. Mitsui Chemicals Osaka works specify acid-resistant cellular glass for sulfuric acid lines in aggressive corrosion environments.
Chubu/Nagoya
Automotive stamping plants and electronics assembly facilities in Aichi Prefecture specify lightweight fiberglass for paint booth temperature control. Toyota and Nissan assembly operations generate intermittent thermal load demand distinct from continuous-process industries. Regional suppliers concentrate on maintenance contracts rather than greenfield project integration.
Kyushu
Advanced semiconductor manufacturing clusters and hydrogen liquefaction pilot projects anchor emerging demand for specialty glass wool and cryogenic cellular glass systems. Captive power plants serving fabs require high-purity insulation materials with cleanroom compatibility. Hydrogen economy infrastructure development positions the region for sub-zero pipeline insulation growth.
Hokkaido
District heating networks in Sapporo deploy rigid foam insulation with factory-applied aluminum jacketing for sub-ambient distribution lines. Cold climate operations extend cellular glass applications beyond cryogenic industrial use into municipal infrastructure. Regional project finance for energy-efficiency retrofits fragments procurement across mid-scale contractors.
Japan Industrial Insulation Market Competitive Landscape
On the supply side, the industry is consolidating around integrated material producers with established JIS certification relationships and captive supply capabilities. Domestic ceramic fiber specialists and glass wool fabricators dominate high-temperature applications, while regional contractors fragment retrofit and maintenance procurement. Three archetypes define competitive positioning: integrated engineering-procurement-construction firms bundling lifecycle contracts, mid-scale contractors capturing fragmented retrofit finance, and specialty material producers with deep technical service relationships. Competitive moves concentrate on backward integration into alumina-silica feedstock control and strategic partnerships for aerogel composite distribution.
Among domestic specialists, NICHIAS Corporation and IBIDEN Co., Ltd. exemplify the integrated material producer archetype with established positions in high-temperature and semiconductor-facing applications. A&A Material Corporation occupies a position within the technical service-intensive tier serving regional chemical processors. These three Japanese limited companies represent distinct strategic postures: ceramic fiber expertise for petrochemical environments, captive supply integration for power and semiconductor fabs, and deep regional relationship networks respectively.
| Leading Market Players |
|---|
| 日本ケイカル株式会社 |
| 株式会社フセアス |
| NICHIAS Corporation |
| 熊澤産業株式会社 |
| SHINTO Industrial Co., Ltd. |
| IBIDEN Co., Ltd. |
| A&A Material Corporation |
| Yoshikawa Industry Co., Ltd. |
| Isolite Insulating Products Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Alumina-silica raw material volatility compresses pricing tier spreads between JIS-certified domestic producers and uncertified imports while simultaneously forcing supply chain consolidation around captive feedstock control. Buyers face stark trade-offs between premium ceramic fiber pricing with supply security versus lower-cost mineral wool with import exposure.
Pricing Analysis
JIS certification grade creates the primary spread between premium domestic ceramic fiber and economy-tier uncertified imports. Project-based long-term contracting dominates, with pricing differentiation driven by thermal performance tier and after-sales service bundling. Cost compression in mid-temperature mineral wool intensifies because rigid foam substitutes erode volume leverage. Discrete manufacturing buyers exhibit highest price sensitivity, while power generation utilities prioritize thermal guarantees over unit economics.
Supply Chain Analysis
Tariff exposure between China and Japan dominates supply chain risk for refined alumina and silica feedstock imports. Domestic production concentrates in Kanagawa and Osaka Prefectures, with secondary sourcing from South Korea and Taiwan for specialty glass wool precursors. The chain rests on energy-intensive refractory mineral processing and petrochemical-derived binder chemistries. Single-source vulnerability runs through Keihin corridor ceramic fiber kilns. Distribution runs through engineering-procurement-construction firms bundling material with installation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Project finance fragmentation for METI-mandated energy retrofits creates niches for specialized contractors previously excluded from integrated procurement. This demand-side shift rewards agile mid-scale players over legacy volume suppliers.
For Market Incumbents: Entrench JIS certification relationships by backward integration into alumina-silica feedstock and exclusive aerogel composite distribution partnerships. Rigid foam substitution threatens mineral wool margins in sub-400°C applications. Prioritize captive supply of specialty glass wool to semiconductor fabs in Kyushu and Tohoku as a defensive moat. For New Entrants and Emerging Players: Build out certified installer networks targeting Osaka Bay acoustic retrofit clusters where noise ordinance deadlines compress procurement timelines. Hydrogen liquefaction pilot projects in Kyushu offer the most penetrable white-space for cryogenic cellular glass. Lead with lifecycle performance guarantees rather than material-only supply to bypass established EPC relationships. For Investors and Strategic Acquirers: The market sits at a regulatory enforcement phase that favors technical service-intensive specialists over commodity volume producers. Five-to-ten year viability hinges on carbon border adjustment readiness and verified lifecycle emissions data. Target acquisition archetypes include regional contractors with METI audit relationships and cleanroom-compatible material capabilities. Watch hydrogen economy infrastructure commitments as the inflection signal for cryogenic insulation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina-Silica Feedstock | Captive mineral supply secures margins against import volatility and JIS certification continuity. |
| Aerogel Composite Distribution Partnership | Silica aerogel access collapses thickness-performance tradeoffs for space-constrained Keihin refineries. |
| Certified Installer Network Expansion | Skilled technician scarcity in JIS-compliant application protocols creates bottleneck control. |
| Hydrogen-Ready Cellular Glass Capacity | Liquid hydrogen transport infrastructure in Kyushu anchors emerging cryogenic demand. |
| Lifecycle Service Contract Bundling | Tokyo Electric and regional utilities now demand multi-year thermal performance guarantees. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant engineers, procurement leads at petrochemical complexes, EPC contractors, and METI compliance officers; and secondary validation through customs trade data, JIS certification registries, METI energy audit disclosures, and SEC filings of listed material producers. Bottom-up segment sizing triangulated against top-down industry association estimates.
Forecast inputs considered product type replacement rhythms, end-user capital expenditure cycles, and regional regulatory enforcement intensity across the projection horizon. Segmentation dimensions modeled include temperature exposure tier, end-use vertical, application type, and installation mode. CAGRs derived from fitted growth curves applied to segment-level baseline values, with cross-checks against METI-mandated retrofit obligation schedules and semiconductor fab construction pipelines.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by ceramic fiber specialists or sudden JIS standard revisions would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
High-Performance Insulation Materials Market
Insulation Materials
Thermal Insulation Material Market
Insulation Materials
Insulation Boards Market
Insulation Materials
Carbon Foam Market
Insulation Materials
Microporous Insulation Material Market
Insulation Materials
North America Flexible Foam Market
Insulation Materials
Global Molded Foams Market
Insulation Materials
Global Fire Protection Materials Market
Insulation Materials
Industrial Pipe Insulation Market
Insulation Materials
Refrigeration Insulation Materials Market
Insulation Materials
Fireproofing Materials Market
Insulation Materials
Reflective Thermal Insulation Coatings Market
Insulation Materials
Fire Stopping Materials Market
Insulation Materials
North America Industrial Insulation Market
Insulation Materials
Global Extruded Polypropylene Foam Market
Insulation Materials
US Industrial Insulation Market