
 Micronized PTFE Market | 2026-2036
Micronized PTFE Market Size, Share, and Industry Trends Forecast 2026-2036
Micronized PTFE Market Intelligence
Revenue from specialty grade and modified PTFE formulations is reconfiguring the margin landscape previously dominated by standard grade sales. The Chemours Company specializes in high-performance fluoropolymer production, maintaining a strong market position. Daikin Industries Ltd. leverages its extensive background in fluorochemicals to compete on a global scale. In parallel, BYK Chemie GmbH differentiates through its focus on additives for coatings and plastics applications.
Micronized PTFE consists of finely powdered Polytetrafluoroethylene, typically with particle sizes in the micron range, produced through irradiation or thermal degradation. Its primary industrial purpose is as an additive to enhance properties like lubricity, wear resistance, and non-stick characteristics in host materials. Standard grade products command the largest volume, but modified and specialty grades are where margin concentration is highest. The coatings and lubricants applications represent the most significant end-use segments, driven by industrial machinery and automotive component manufacturing.
The market operates under increasing scrutiny from environmental regulators, including the EPA in the United States and frameworks like REACH in Europe, which are tightening controls on PFAS chemicals. In China, the MEE's evolving standards on industrial pollutants also influence production and use. Navigating this complex and divergent regulatory environment while developing non-restricted, high-performance alternatives is the central strategic challenge for producers.
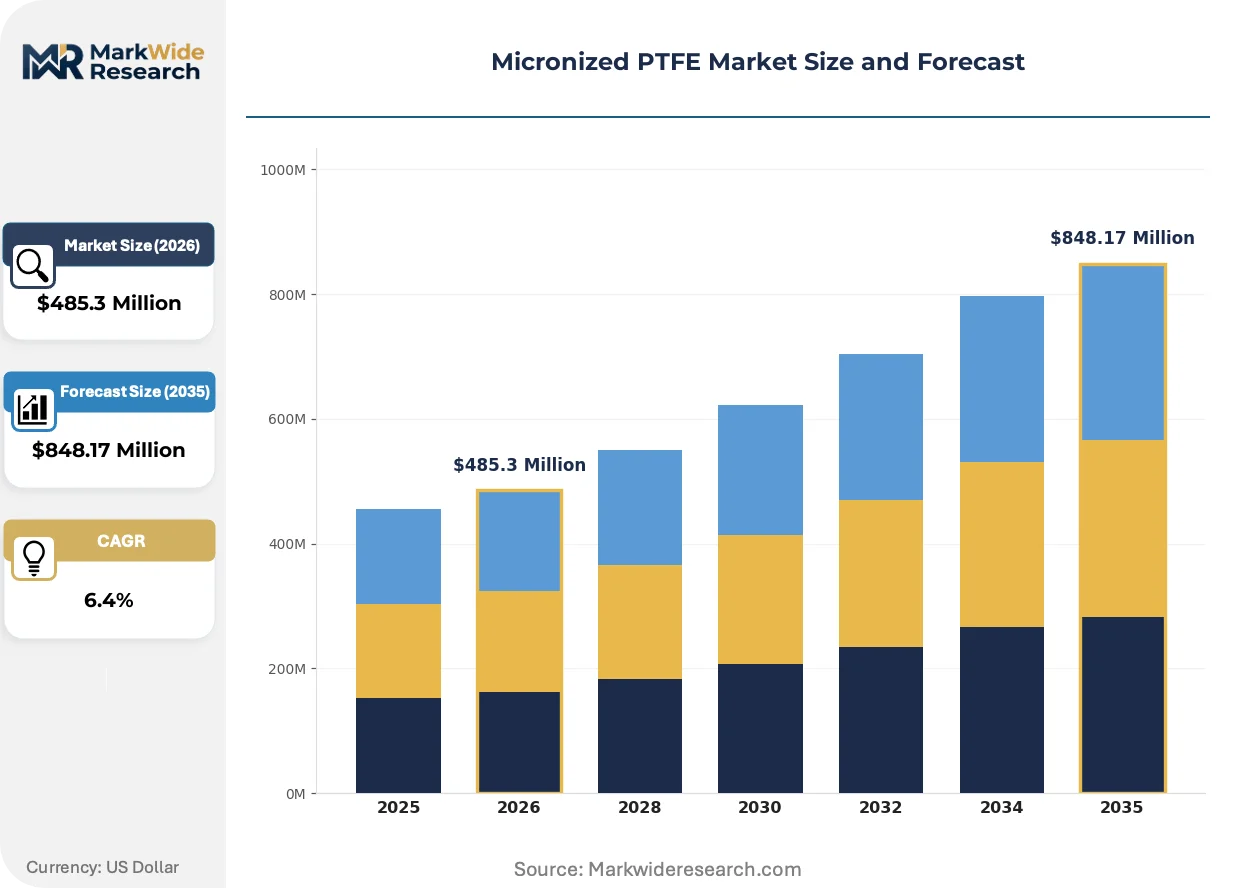
Market Dynamics
The central dynamic is the escalating regulatory pressure on PFAS chemicals, led by frameworks like the EU's REACH and actions from the EPA. This scrutiny is forcing a fundamental re-evaluation of material chemistry and product lifecycle management across the value chain.
Growth Catalysts
- Specialty Coatings:Demand from the electronics industry for high-performance coatings on components like printed circuit boards provides a significant pull for micronized PTFE.
- China's Industrial Base:China's extensive industrial manufacturing and chemical processing sectors represent a concentrated source of volume demand, particularly for standard grade products.
- Modified Grade Development:The creation of modified and specialty PTFE grades enables penetration into high-margin applications, improving overall profitability for producers.
Market Restraints
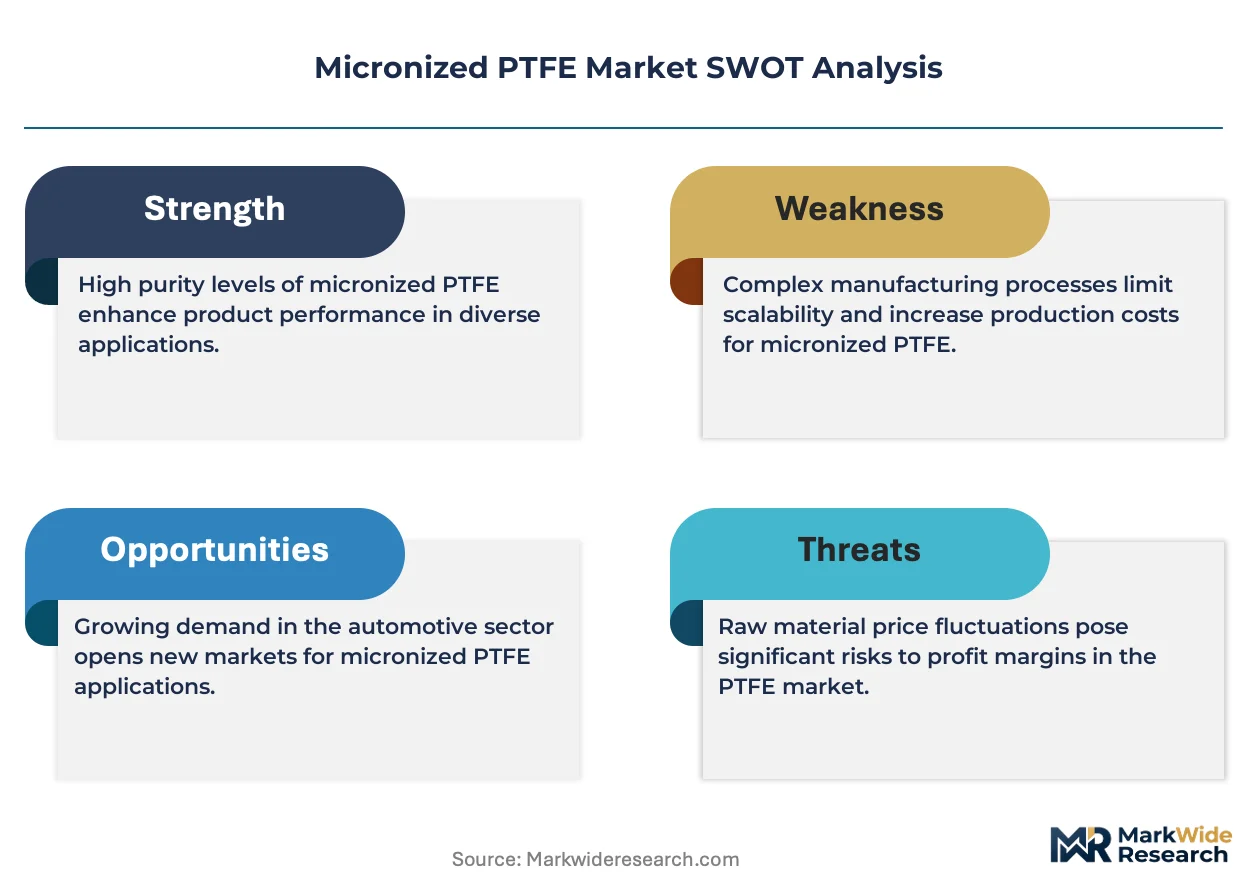
- Regulatory Scrutiny:Intensifying global regulations on PFAS chemicals, including the EU's REACH framework, create significant compliance costs and market uncertainty for producers.
- Substitution Risk:The development of non-fluorinated alternatives like ultra-high-molecular-weight polyethylene (UHMWPE) poses a substitution threat in certain wear-resistance applications.
- Raw Material Control:Dependence on a concentrated global supply of key fluorochemical precursors exposes manufacturers to potential price volatility and supply disruptions.
Strategic Opportunities
- PFAS-Free Alternatives:Developing and marketing high-performance, non-restricted alternatives to regulated fluoropolymers creates an opportunity to capture share from less agile competitors.
- Renewable Energy Sector:The renewable energy industry presents new applications for specialty coatings on components like wind turbine blades to enhance durability and efficiency.
- Geographic Diversification:Expanding into emerging industrial hubs in Southeast Asia, such as Vietnam and Indonesia, offers new growth vectors for industrial coatings and lubricants.
Industry Challenges
- Divergent Regulations:Navigating different regulatory timelines and requirements between Europe's REACH and the EPA in the United States complicates global product launches and supply chain management.
- Energy-Intensive Production:The irradiation and thermal degradation methods for producing micronized powders are highly energy-intensive, linking production costs directly to volatile energy markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micronized PTFE Market |
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $848.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Grade, High Purity, Specialty Grade, Conductive Grade, Modified PTFE Application: Coatings, Lubricants, Seals, Gaskets, Electrical Insulation, Mold Release End User Industry: Electronics, Chemical Processing, Food Manufacturing, Textile Production, Packaging Packaging Type: Bulk Bags, Drums, Plastic Containers, Fiber Drums |
| Companies Covered | Daikin Industries Ltd., Shamrock Technologies Inc., 3M Co., BYK Chemie GmbH, DEUREX AG, Solvay SA, Clariant International Ltd., AGC Chemicals, The Chemours Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micronized PTFE Market Strategic Shifts & Innovations
Innovation in the micronized PTFE market is defined by the tension between stringent environmental regulations and the unyielding demand for higher material performance. This dynamic compels producers to advance material science while re-engineering their compliance and production strategies.
Advanced simulation software allows for the digital design and performance prediction of new polymer formulations. R&D labs in the coatings sector are adopting this technology to shorten development timelines. This software-driven approach is virtualizing key stages of the material qualification process, compressing the path to commercialization for novel grades.
Europe's REACH regulation continues to tighten restrictions on specific fluorinated compounds, impacting the entire supply chain. This mandate forces product reformulation and extensive documentation for market access into the European Union. The coatings and plastics additives segments are most affected, accelerating the search for compliant, high-performance alternatives.
A clear shift towards lifecycle-based material selection is evident among OEMs in the industrial machinery sector. This evaluation method prioritizes long-term durability and wear resistance over initial purchase price, disrupting traditional procurement models. This behavior is most prominent within Germany’s advanced manufacturing ecosystem and for automotive components in Japan.
Micronized PTFE Market Segmentation
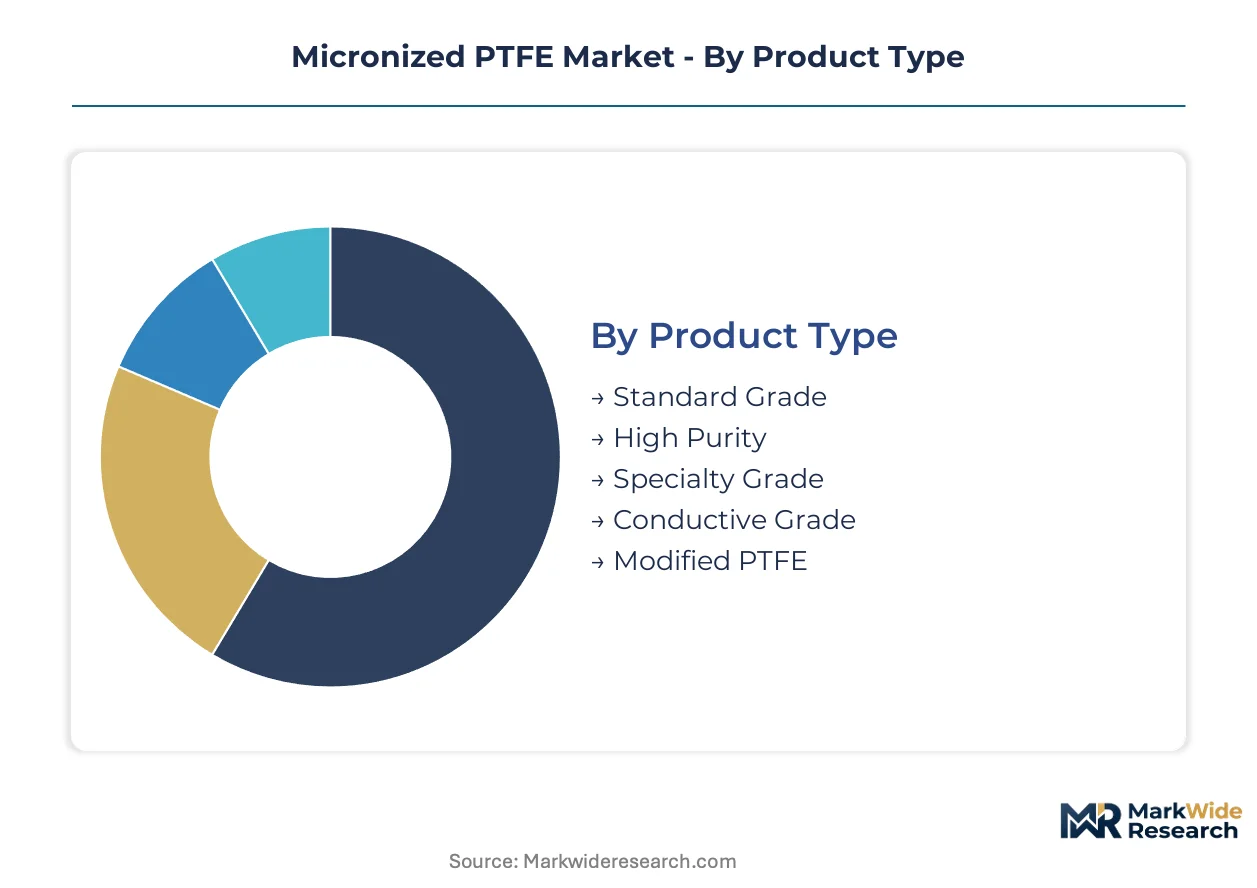
Micronized PTFE market segmentation provides a granular view of product variations and their specific applications, allowing producers to align R&D with distinct industrial requirements. This analysis dissects demand patterns across diverse end-use sectors, highlighting where material properties are most valued. Understanding these segments is critical for strategic product development and market penetration.
Product Type:
The product type segmentation highlights the diverse functional requirements micronized PTFE fulfills across various industrial use-cases.
- Standard Grade:This product type consists of finely powdered PTFE with broad applicability, offering enhanced lubricity and wear resistance in general industrial formulations. Demand for Standard Grade products is concentrated in China's extensive manufacturing base for high-volume applications.
- Specialty Grade:Specialty Grade micronized PTFE is engineered for specific performance attributes, such as enhanced thermal stability or improved dispersion in complex matrices. The electronics industry drives demand for these grades in high-performance coatings for printed circuit boards, where precision is paramount.
- High Purity:High Purity grades contain minimal contaminants, essential for sensitive applications in medical devices or advanced electronics.
- Conductive Grade:Conductive Grade PTFE incorporates conductive fillers, providing electrostatic discharge protection in specialized coatings and plastics.
- Modified PTFE:Modified PTFE incorporates co-monomers or surface treatments to improve adhesion or reduce permeability for demanding applications.
Established volume favors Standard Grade; emerging adoption favors Modified PTFE.
Application:
The application categories define where micronized PTFE delivers specific performance enhancements, influencing overall material value and margin potential.
- Coatings:Micronized PTFE serves as a crucial additive in coatings, imparting non-stick properties, improved scratch resistance, and enhanced durability for industrial surfaces. The automotive sector utilizes these coatings extensively for engine components and interior surfaces, requiring robust performance.
- Lubricants:In lubricants, micronized PTFE reduces friction and wear, extending the lifespan of mechanical components and improving energy efficiency. Industrial machinery manufacturing in Germany and Japan relies on PTFE-enhanced lubricants for critical moving parts.
- Seals:Micronized PTFE enhances the performance of seals by providing low friction and chemical inertness, crucial for fluid handling systems.
- Gaskets:Gaskets benefit from PTFE additives through improved compressibility and resistance to aggressive chemicals in chemical processing plants.
- Electrical Insulation:The material's excellent dielectric properties make it valuable in electrical insulation, particularly for high-frequency components in telecommunications.
- Mold Release:Micronized PTFE acts as an effective mold release agent, preventing adhesion and ensuring clean demolding in polymer and rubber processing.
Coatings and Lubricants represent the largest volume segments, while Electrical Insulation and Mold Release applications offer specialized demand.
End User Industry:
Understanding end-user industries reveals the specific demand drivers and performance expectations from industrial customers consuming micronized PTFE.
- Electronics:The electronics industry utilizes micronized PTFE for specialized coatings on circuit boards and components, requiring high-performance dielectric and non-stick properties. Demand from this sector is particularly strong in South Korea and Taiwan for advanced device manufacturing.
- Chemical Processing:In chemical processing, micronized PTFE enhances wear resistance and chemical inertness in pumps, valves, and liners, crucial for handling corrosive substances. Facilities in the United States and Europe prioritize these properties for operational safety and longevity.
- Food Manufacturing:Food manufacturing employs PTFE-enhanced materials for non-stick surfaces and hygienic seals in processing equipment.
- Textile Production:Textile production uses micronized PTFE in specific finishes to impart water repellency and stain resistance to fabrics.
- Packaging:The packaging industry integrates PTFE for low-friction surfaces in machinery and specialized release coatings for certain materials.
The Electronics sector drives innovation for specialty grades, while Chemical Processing maintains consistent demand for robust material properties.
Packaging Type:
Packaging type reflects the logistical requirements and scale of distribution for micronized PTFE products across the supply chain.
- Bulk Bags:Bulk bags are used for large-volume shipments of micronized PTFE, catering to industrial customers with high consumption rates and efficient material handling capabilities. This packaging method is prevalent for standard grade products supplied to major manufacturing hubs.
- Drums:Drums offer a versatile packaging solution for medium to large quantities, providing protection and ease of transport for various industrial applications. Many chemical distributors in Europe and North America receive and ship micronized PTFE in drums.
- Plastic Containers:Plastic containers are typically used for smaller, specialized orders or high-purity grades requiring precise handling.
- Fiber Drums:Fiber drums offer a lightweight and cost-effective alternative for certain micronized PTFE grades, particularly for domestic distribution.
Bulk Bags facilitate large-scale industrial use, whereas Drums provide a versatile solution for varied customer needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Micronized PTFE consumption patterns vary significantly across global regions, with distinct demand for standard versus specialty grades. China's extensive manufacturing base drives high-volume standard grade demand, contrasting with Europe and North America's focus on high-performance specialty applications. Producers tailor product offerings to align with these diverse regional requirements.
China
China's industrial manufacturing and chemical processing sectors generate substantial demand for standard grade micronized PTFE. The MEE's evolving standards on industrial pollutants influence production and use within the country. Extensive manufacturing hubs in the Yangtze River Delta and Pearl River Delta utilize PTFE for high-volume industrial applications.
United States
Demand for micronized PTFE in the United States stems from advanced electronics and chemical processing industries. The EPA's tightening controls on PFAS chemicals are forcing product reformulation and alternative development. Manufacturing clusters in Texas and California prioritize high-performance grades for specialized coatings and lubricants.
Germany
Germany's advanced manufacturing ecosystem, particularly industrial machinery and automotive components, drives demand for high-performance micronized PTFE. The EU's REACH regulation significantly impacts material selection and product development for market access. Production facilities in North Rhine-Westphalia and Bavaria focus on specialty additives for coatings and plastics.
Japan
Automotive component manufacturing and precision industrial machinery in Japan require micronized PTFE for enhanced durability and wear resistance. METI initiatives encourage sustainable material development, influencing fluoropolymer innovation. Major industrial centers in the Kanto region and Chubu region integrate PTFE into critical mechanical parts.
South Korea
South Korea's robust electronics industry creates strong demand for specialty grade micronized PTFE in high-performance coatings for printed circuit boards. The country's environmental regulations align with global efforts to manage fluorinated compounds. Advanced device manufacturing in the Seoul Capital Area and Gyeonggi Province utilizes PTFE for dielectric and non-stick properties.
Micronized PTFE Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another within the micronized PTFE market. The industry exhibits a tiered structure, with a few large multinational chemical companies dominating the premium and specialty segments. Smaller, regional players often compete on price in the standard grade market. Strategic archetypes include integrated fluoropolymer producers, specialized additive manufacturers, and regional distributors. Dominant competitive moves involve portfolio diversification into non-fluorinated alternatives and strategic partnerships for raw material security.
Integrated fluoropolymer producers like The Chemours Company exemplify a strong market position through their extensive high-performance fluoropolymer production capabilities. Daikin Industries Ltd. occupies a similar global position, leveraging its deep background in fluorochemicals to serve diverse industrial applications. BYK Chemie GmbH differentiates itself through a focused strategy on additives for coatings and plastics applications, representing a specialized additive manufacturer archetype. These companies anchor innovation in modified and specialty PTFE formulations, driving value creation in high-margin segments. Their strategic focus often involves developing advanced materials that meet stringent performance criteria in demanding end-use sectors.
| Leading Market Players |
|---|
| Daikin Industries Ltd. |
| Shamrock Technologies Inc. |
| 3M Co. |
| BYK Chemie GmbH |
| DEUREX AG |
| Solvay SA |
| Clariant International Ltd. |
| AGC Chemicals |
| The Chemours Company |
| Others |
Cost & Logistics Intelligence
China's Yangtze River Delta manufacturing capacity directly influences global pricing for standard grade micronized PTFE. This regional production scale dictates cost structures across downstream industries.
Pricing Analysis
Long-term offtake agreements characterize pricing for specialty grade micronized PTFE, while standard grades often trade on commodity spot markets. Price differentiation stems from quality grade, such as high purity requirements, and the specific geographic delivery costs. Pricing softness currently reflects escalating regulatory scrutiny on PFAS chemicals and the threat of non-fluorinated alternatives. Buyers in China's high-volume manufacturing base exhibit high price sensitivity for standard products, unlike the electronics sector for specialized formulations.
Supply Chain Analysis
Export control regimes, particularly those impacting fluorochemical precursors, influence the global micronized PTFE supply chain. Supply concentration centers on China, the United States, and Germany for production. Manufacturers depend on a concentrated global supply of key fluorochemical precursors and specialized irradiation equipment. Regulatory restrictions, such as the EU's REACH framework, pose a significant structural risk. Distribution runs through regional chemical distributors and direct sales channels to major OEM customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The micronized PTFE market requires a strong substitution defense, as incumbents must navigate the increasing threat from non-fluorinated alternatives like ultra-high-molecular-weight polyethylene (UHMWPE). This dynamic compels strategic re-evaluation across the value chain.
For Market Incumbents: Pre-empt further regulatory restrictions by aggressively diversifying into high-performance, PFAS-free alternatives. Form strategic partnerships to secure raw material supply chains, mitigating price volatility and single-source vulnerability. Invest heavily in R&D for non-fluorinated polymer development to counter substitution risks from materials like UHMWPE. This proactive stance defends against market uncertainty stemming from evolving EPA and REACH regulations.
For New Entrants and Emerging Players: Pursue niche opportunities in the renewable energy sector, targeting specialty coatings for components like wind turbine blades. Focus on emerging industrial hubs in Southeast Asia, such as Vietnam and Indonesia, for industrial coatings and lubricants. The most penetrable segment lies in high-performance, non-restricted alternatives for specialized applications. Market entry should emphasize value-based selling, highlighting enhanced durability and efficiency for OEMs.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized additive manufacturers with robust intellectual property in compliant alternatives. Long-term viability depends on continuous material science innovation to meet evolving performance and regulatory demands. Acquisition targets should possess strong R&D capabilities in non-fluorinated polymers or advanced modification techniques for existing PTFE. The signal to watch is the successful commercialization of high-performance, non-restricted alternatives gaining market traction in demanding applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Portfolio Diversification | Mitigates regulatory risk by offering compliant alternatives to PFAS. |
| R&D Investment in Non-Fluorinated Polymers | Develops next-generation materials for high-performance applications. |
| Strategic Partnerships for Raw Material Access | Ensures supply stability amid concentrated fluorochemical precursor markets. |
| Geographic Market Expansion in Southeast Asia | Captures new demand from developing industrial manufacturing bases. |
| Advanced Simulation Software Adoption | Accelerates new product development and material qualification timelines. |
Research Approach
A spread of perspectives from technical R&D directors, OEM procurement leads, chemical distributors, and environmental regulators converged on the working assumptions for this study. This involved extensive primary interviews validated against secondary data from industry association reports, customs data, and scientific literature. Our approach combined bottom-up market sizing with top-down validation, ensuring comprehensive coverage.
Demand-supply balance projections formed the core of our analytical framework across the analysis window. We modeled market segmentation by product type, application, end-user industry, packaging type, and regional regulatory cluster. Compound annual growth rates were derived from historical trends and projected market shifts. Key forecast inputs included anticipated regulatory changes and potential raw material price volatility.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated fluoropolymer producers or specialized additive manufacturers would shift outcomes. Unforeseen technological breakthroughs or sudden regulatory bans represent key risk factors. Material shifts in environmental policy would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Squalene Market
Specialty Chemicals
Plastic Stabilizer Market
Specialty Chemicals
Global Sodium Hyaluronate-Based Products Market
Specialty Chemicals
Ubiquinone Market
Specialty Chemicals
Sugarcane Wax Market
Specialty Chemicals
Rosin Press Market
Specialty Chemicals
Cubeb Oil Market
Specialty Chemicals
Immunochemistry Products Market
Specialty Chemicals
Europe Optical Brighteners Market
Specialty Chemicals
Bismaleimide Market
Specialty Chemicals
Eitelite Market
Specialty Chemicals
Coconut Derived Emollients Market
Specialty Chemicals
Organo-Modified Bentonite Market
Specialty Chemicals
Antioxidant 412S Market
Specialty Chemicals
Fatty Acid Methyl Ester Market
Specialty Chemicals
Global Baking Soda Substitute Market