
 Fatty Acid Methyl Ester Market | 2026-2036
Fatty Acid Methyl Ester Market Size, Share, and Industry Trends Forecast 2026-2036
Fatty Acid Methyl Ester Market Analysis
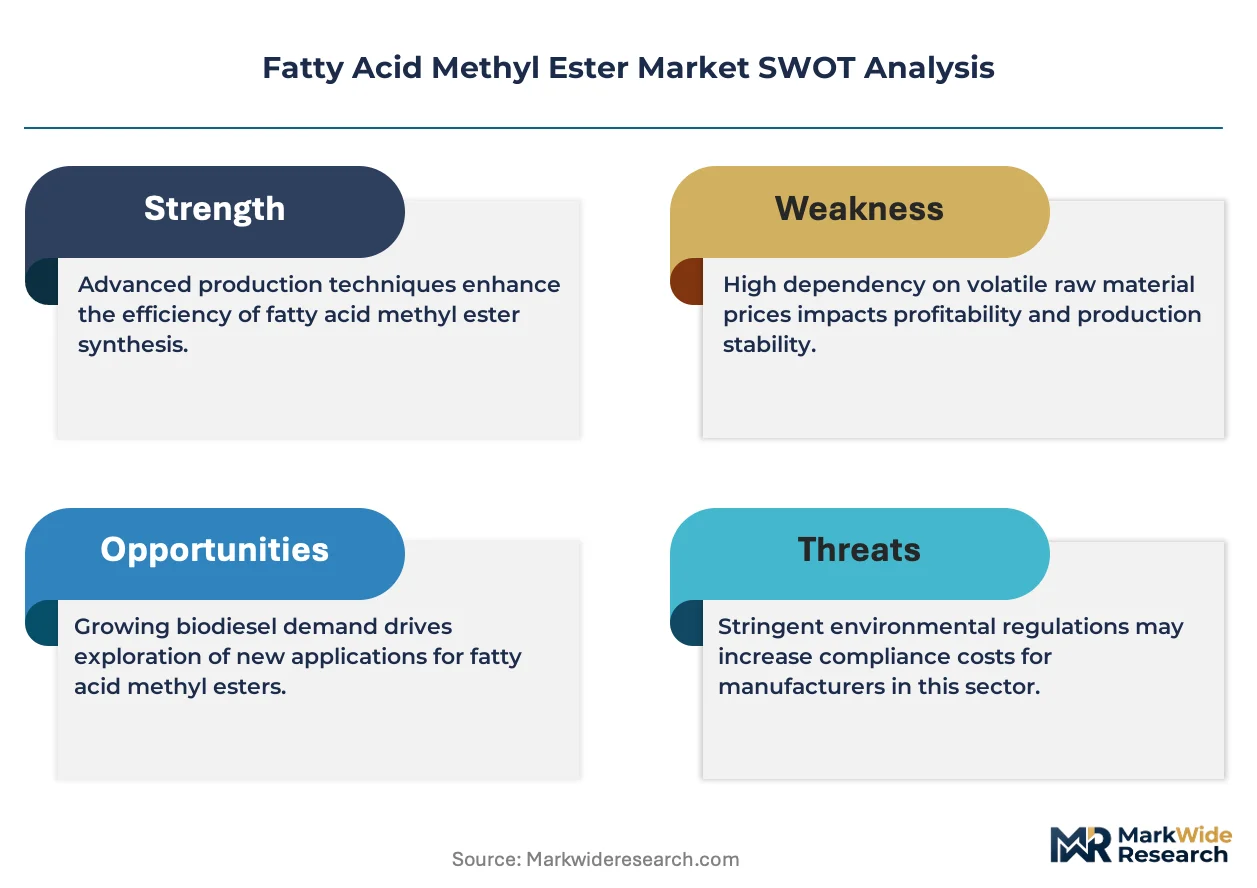
Marine fuel buyers is unwinding legacy bunker contracts in favor of FAME-blended distillates as IMO sulfur caps harden enforcement. KLK Oleo leverages integrated oleochemical complexes across Southeast Asia to secure feedstock cost advantages. Cargill Incorporated anchors its position through backward integration into oilseed crushing and downstream esterification. Emery Oleochemicals differentiates via specialized lubricant-grade esters for metalworking fluids.
Fatty acid methyl esters are alkyl esters derived from transesterification of triglycerides with methanol, typically yielding C12-C22 chain lengths with cloud points ranging from -5°C to 15°C depending on feedstock saturation; these compounds serve primarily as drop-in replacements for petroleum-derived intermediates in fuels, surfactants, and lubricant base stocks. Biodiesel commands the largest product volume pool though margin compression persists from feedstock volatility, while surfactant-grade esters capture expanding share in personal care as formulators phase out ethoxylated alternatives. The lubricants segment leads value creation through high-performance hydraulic and metalworking applications where biodegradability specifications command price premiums.
The EPA's Renewable Fuel Standard and the EU's Renewable Energy Directive II mandate minimum biofuel blending thresholds that institutionalize FAME offtake across transportation fuels. REACH registration requirements and ECHA substance evaluations constrain import access for non-compliant Asian producers. California's Low Carbon Fuel Standard and Indonesia's B35 biodiesel mandate illustrate how sub-national and national frameworks collectively shape trade flows. Stakeholders must monitor feedstock sustainability certification schemes as these evolve into de facto market access conditions.
Market Dynamics
Feedstock cost volatility and renewable fuel mandate enforcement are compressing margins while redirecting capital toward integrated production assets. The EU Green Deal's tightening carbon intensity thresholds are forcing biodiesel blenders to source certified sustainable feedstocks or face exclusion from compliance credit markets.
Growth Catalysts
- EU Renewable Energy Directive II:Binding biofuel blending thresholds institutionalize FAME offtake across transportation fuels, creating mandated demand floors that insulate producers from crude oil price swings.
- Metalworking fluid formulators:Biodegradable lubricant specifications in precision manufacturing are displacing petroleum-derived base stocks with ester alternatives that command price premiums for technical performance.
- Indonesia B35 mandate:Palm oil-based methyl ester requirements accelerate domestic crushing capacity expansion and redirect Southeast Asian export flows toward domestic energy security priorities.
Market Restraints
- Palm and soy oil price volatility:Agricultural commodity futures swings transmit directly to ester production economics, eroding forward margin visibility and discouraging long-term supply contracts.
- REACH registration concentration:ECHA compliance costs and data requirements create asymmetric barriers favoring incumbent European producers over import-dependent distributors.
- Hydrotreated vegetable oil competition:HVO's superior cold-flow properties and drop-in compatibility threaten FAME market share in premium diesel blending applications.
Strategic Opportunities
- Marine distillate blending:IMO sulfur cap enforcement at ports in Rotterdam, Singapore, and Los Angeles creates first-mover advantage for FAME-bunker fuel suppliers with ISO 8217 certification.
- Surfactant-grade ester substitution:Personal care formulators phasing out ethoxylated alcohols present volume expansion paths for C12-C14 methyl esters in sulfate-free cleansing applications.
- California LCFS credit stacking:Low Carbon Fuel Standard implementation rewards feedstock traceability investments with tradable credit premiums that improve project returns.
Industry Challenges
- ISCC certification timeline:Sustainability scheme audit backlogs and documentation requirements delay market access for new entrant producers seeking EU biodiesel qualification.
- Transesterification catalyst recovery:Homogeneous alkaline catalyst separation and wastewater treatment add capital intensity to continuous-process plant designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fatty Acid Methyl Ester Market |
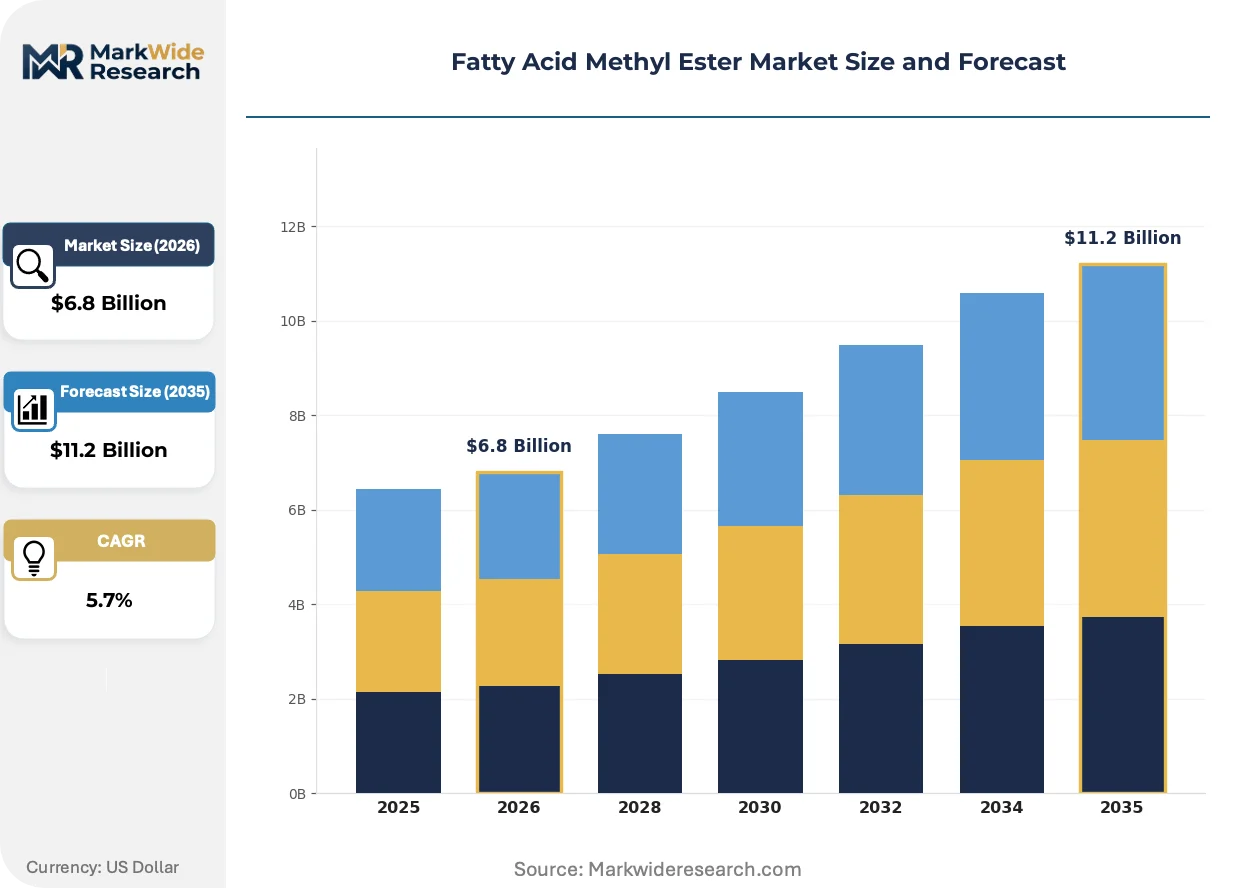
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biodiesel, Surfactants, Lubricants, Chemicals Application: Fuel Additive, Industrial Solvent, Personal Care, Detergents End Use: Transportation, Agriculture, Manufacturing, Household Distribution Channel: Direct Sales, Distributors, Retail, Online |
| Companies Covered | KLK Oleo, Bunge Limited, Wilmar International Limited, P&G Chemicals, IOI Group, Cargill Incorporated, Emery Oleochemicals, BASF SE, Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fatty Acid Methyl Ester Market Emerging Trajectories
Process intensification and digital traceability systems are reshaping how FAME producers defend margin position and access premium market segments. Technical differentiation now hinges on carbon intensity scoring rather than commodity parity.
Enzymatic transesterification using immobilized lipase biocatalysts is bifurcating the technology landscape between high-efficiency continuous systems and conventional alkaline batch processing. Specialty chemical producers in Germany and the Netherlands are adopting enzymatic routes for pharmaceutical-grade ester output where residual methanol specifications are stringent. This technology compression is enabling smaller-scale distributed production near feedstock origins while marginalizing centralized commodity refineries dependent on economies of scale.
The EU F-Gas Regulation's phase-down schedules for fluorinated greenhouse gases are redirecting industrial refrigeration and heat pump manufacturers toward bio-based ester working fluids. ECHA substance evaluations under REACH are simultaneously constraining import access for non-compliant Asian methyl ester producers. Metalworking fluid compounders in the Ruhr industrial cluster are responding by qualifying regionally sourced ester base stocks with documented renewable carbon content.
Blenders and distributors are consolidating procurement relationships around suppliers with integrated sustainability certification and captive logistics infrastructure. Long-term offtake agreements with fixed carbon intensity pricing are displacing spot-market purchasing in European biodiesel supply chains. This contractual evolution is most visible in Germany, where automotive OEM compliance departments now mandate supply chain transparency down to oilseed cultivation geography.
Fatty Acid Methyl Ester Market Segmentation
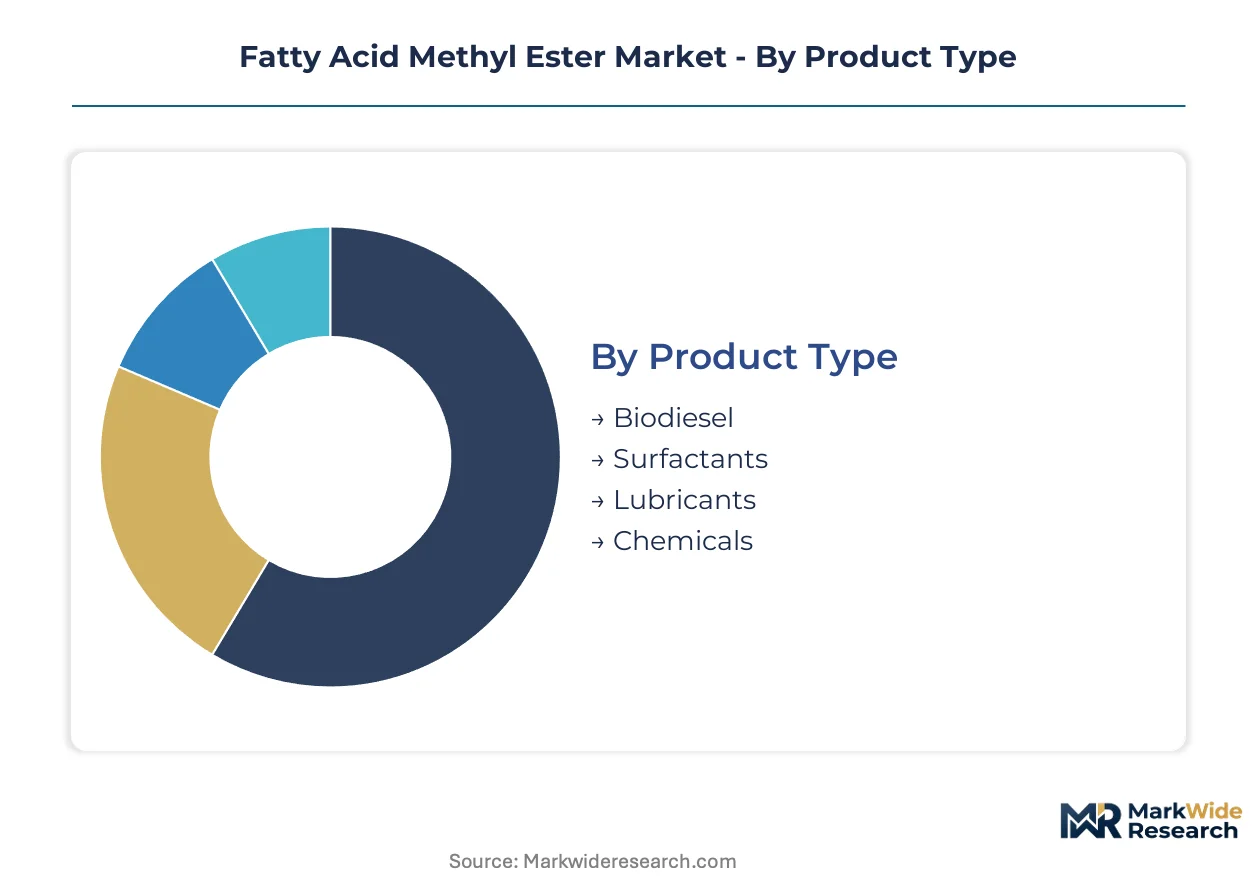
Channel economics and margin capture vary sharply across FAME segments. Biodiesel flows through commodity terminals while lubricant-grade esters command direct technical sales relationships with compounders.
Product Type:
Channel-mix dynamics split between bulk commodity terminals for fuel applications and specialized chemical distribution for performance grades.
- Biodiesel:C12-C22 alkyl esters from transesterified vegetable oils and animal fats, standardized to EN 14214 or ASTM D6751 specifications. Demand concentrates at blending terminals in Rotterdam and Singapore where IMO marine sulfur regulations enforce FAME-bunker integration.
- Surfactants:C12-C14 methyl esters serving as sulfate-free cleansing intermediates. Personal care formulators in Germany and the Netherlands are displacing ethoxylated alcohols with these bio-based alternatives.
- Lubricants:Ester base stocks for hydraulic and metalworking fluids where biodegradability specifications apply.
- Chemicals:Intermediate feedstocks for oleochemical derivatives and plasticizers.
Biodiesel dominates installed base. Surfactants is where expansion concentrates.
Application:
Cost-tier stratification separates commodity fuel blending from premium formulated products with technical service requirements.
- Fuel Additive:Cetane improvers and cold-flow enhancers for diesel blending. Transportation fleets in Indonesia and Germany absorb volume under B35 and RED II mandates.
- Industrial Solvent:Precision cleaning applications in electronics and metal finishing where volatility and residue specifications matter.
- Personal Care:Emollient esters and conditioning agents. Formulators phase out silicones and petrochemicals for bio-based alternatives with renewable carbon certification.
- Detergents:Surfactant intermediates for household and institutional cleaning products.
Fuel additive commands volume scale. Personal care delivers margin expansion.
End Use:
Customer-type fragmentation splits between mandated offtake in regulated transport and discretionary purchasing in consumer goods.
- Transportation:Marine, road, and rail diesel blending under renewable fuel mandates. EU Green Deal carbon intensity thresholds redirect procurement toward ISCC-certified supply chains.
- Agriculture:Tractor and equipment lubricants plus biodiesel for farm machinery. Brazilian and Indonesian producers serve domestic crushing byproduct utilization.
- Manufacturing:Metalworking fluids, hydraulic oils, and process solvents. German automotive OEMs mandate supply chain transparency to cultivation geography.
- Household:Consumer detergents and personal care products.
Transportation dominates installed base. Manufacturing is climbing the fastest.
Distribution Channel:
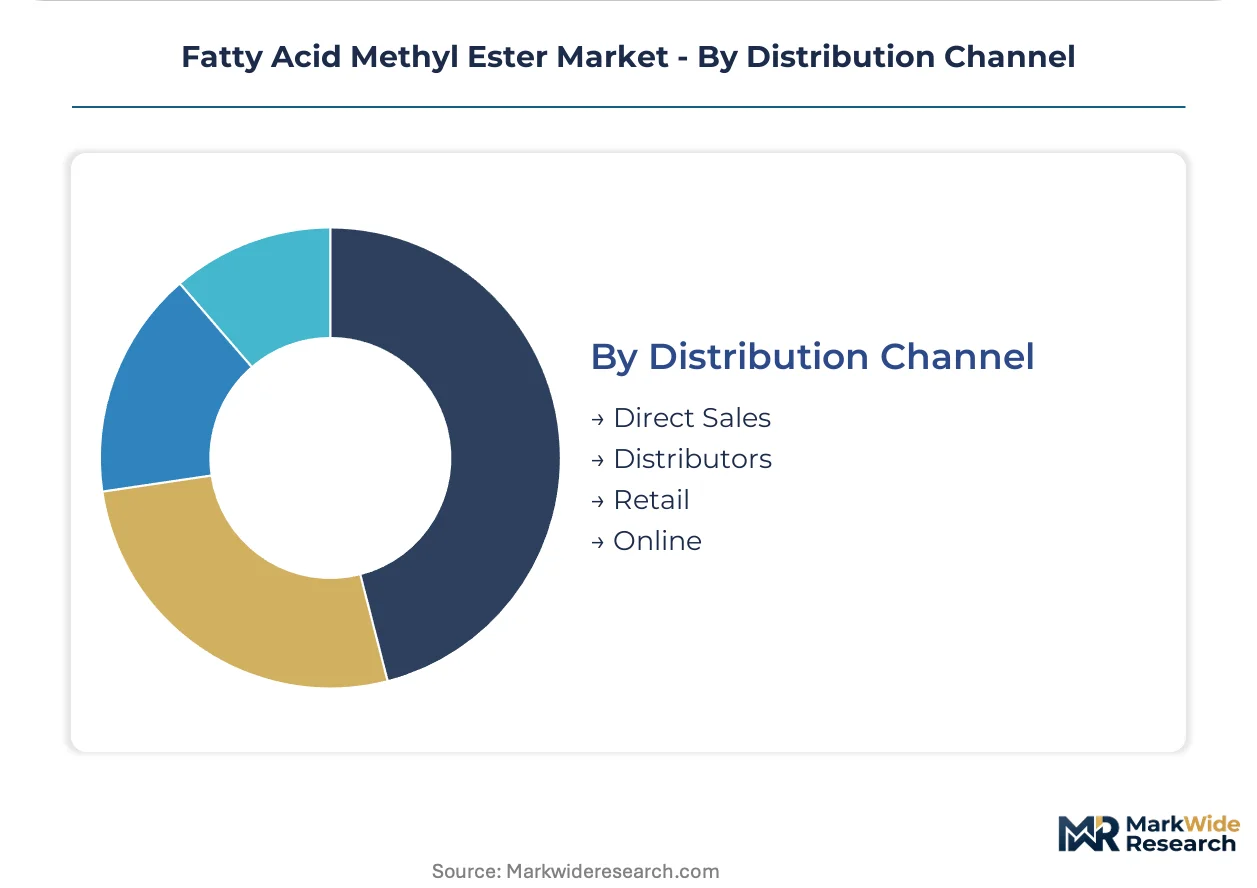
Supply concentration shapes channel power, with integrated producers bypassing intermediaries in biodiesel while specialty esters rely on technical distributors.
- Direct Sales:Long-term offtake agreements with fixed carbon intensity pricing. Cargill and KLK Oleo deploy captive logistics to European biodiesel blenders.
- Distributors:Technical chemical distributors with formulation support capabilities. Surfactant-grade esters reach personal care compounders through specialized intermediaries.
- Retail:Packaged lubricants and consumer products at automotive and home care outlets.
- Online:Emerging channel for small-volume specialty esters and technical documentation access.
Direct sales dominates installed base. Distributors is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesian methyl ester producers redirect palm oil-based output toward domestic B35 compliance, compressing traditional export volumes to European biodiesel blenders. Rotterdam and Hamburg terminals now source alternative feedstock origins to fill supply gaps.
Indonesia
Palm oil crushing capacity expansion accelerates across Sumatra and Kalimantan as the B35 mandate absorbs domestic methyl ester production. The Ministry of Energy and Mineral Resources enforces blending thresholds that prioritize national energy security over export commitments. Surabaya industrial clusters witness biodiesel infrastructure buildout to serve Java-based transportation fleets.
Germany
Automotive OEM compliance departments mandate supply chain transparency down to oilseed cultivation geography for lubricant-grade ester procurement. The EU Green Deal's carbon intensity thresholds redirect biodiesel blending toward ISCC-certified supply chains. Ruhr industrial clusters anchor metalworking fluid compounder demand for biodegradable ester base stocks.
United States
California LCFS credit stacking rewards feedstock traceability investments with tradable premiums that improve project economics for domestic producers. The EPA's Renewable Fuel Standard institutionalizes FAME offtake across transportation fuels with binding biofuel blending thresholds. Gulf Coast petrochemical corridors integrate renewable diesel capacity alongside legacy FAME production assets.
Netherlands
Rotterdam blending terminals enforce IMO sulfur cap compliance through FAME-bunker fuel integration for marine distillate markets. REACH registration requirements and ECHA substance evaluations constrain import access for non-compliant Asian producers. Amsterdam chemical distribution hubs concentrate surfactant-grade ester flows toward German and French personal care formulators.
China
Dual carbon goals under the national climate commitment framework redirect oleochemical investment toward bio-based ester intermediates for domestic lubricant and surfactant applications. The Ministry of Ecology and Environment tightens emissions standards for transesterification facilities in coastal provinces. Yangtze River Delta chemical clusters expand methyl ester capacity to serve regional manufacturing demand.
Fatty Acid Methyl Ester Market Vendor Landscape
Player mix skews toward integrated agribusiness conglomerates with captive oilseed crushing and downstream esterification assets. Structure concentrates around three strategic archetypes: plantation-backed Asian producers controlling feedstock origination, North American grain traders with backward integration into oilseed processing, and European specialty chemical houses focusing on performance-grade esters for technical applications. Dominant competitive moves include sustainability certification investments securing EU market access and long-term offtake agreements with fixed carbon intensity pricing displacing spot-market purchasing.
Among plantation-integrated producers, KLK Oleo and Wilmar International exemplify the feedstock-control archetype through Southeast Asian oleochemical complex networks. Cargill Incorporated anchors the grain-trader segment with North American oilseed processing integration. European positioning concentrates with BASF SE and Emery Oleochemicals representing specialty chemical differentiation toward lubricant and surfactant-grade specifications.
| Leading Market Players |
|---|
| KLK Oleo |
| Bunge Limited |
| Wilmar International Limited |
| P&G Chemicals |
| IOI Group |
| Cargill Incorporated |
| Emery Oleochemicals |
| BASF SE |
| Archer Daniels Midland Company |
| Others |
Supply Flow & Price Mechanics
ISCC certification timelines gate both European market access and carbon intensity premium capture for biodiesel blenders, compressing margin windows for non-compliant producers while rewarding integrated players with documented feedstock traceability. This dual qualification-pricing mechanism concentrates purchasing power among Rotterdam and Hamburg terminal operators with captive sustainability documentation systems.
Pricing Analysis
Alkaline batch processing commands commodity parity pricing against enzymatic continuous systems that extract 15-20% premiums for pharmaceutical-grade residual specifications. Pricing stratifies across ISCC-certified, REACH-registered, and uncertified tiers with carbon intensity scoring as the primary differentiation driver. Cost compression in the uncertified tier intensifies because Indonesian B35 mandate absorption redirects palm oil-based supply toward domestic markets. Road transportation fleets under EU Renewable Energy Directive II mandates show lowest price sensitivity, while spot-market biodiesel blenders exposed to agricultural futures volatility exhibit highest sensitivity.
Supply Chain Analysis
Strait of Malacca transit underwrites Southeast Asian palm oil export economics, with KLK Oleo and Wilmar International complexes in Malaysia and Indonesia anchoring upstream methyl ester supply. Feedstock origination draws from Malaysian and Indonesian palm oil plantations, Argentine soybean crushing, and European rapeseed cooperatives. Single-source vulnerability concentrates in Indonesian government-mandated domestic absorption policies that redirect export volumes without notice. Distribution runs through Rotterdam and Singapore commodity terminals for fuel grades, while lubricant-grade esters reach German metalworking compounders via specialized chemical distributors with technical service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fatty acid methyl ester procurement is evolving toward service-attach contracts where sustainability certification management and carbon intensity auditing expand faster than commodity ester production itself. Recurring revenue from compliance documentation and supply chain traceability services now exceeds hardware margins for integrated producers.
For Market Incumbents: Shield margin position by deepening backward integration into oilseed crushing and accelerating ISCC-EU certification coverage across Southeast Asian assets before ECHA substance evaluation deadlines tighten. Hydrotreated vegetable oil substitution in premium diesel blending represents the most acute technology threat requiring differentiated cold-flow performance positioning or strategic HVO co-location investments. For New Entrants and Emerging Players: ISCC-EU certification fast-track through Dutch and German accreditation bodies unlocks Rotterdam terminal access ahead of backlog-clearing timelines that currently delay Asian competitors. Marine distillate blending at Los Angeles and Singapore ports presents the most penetrable white-space segment given IMO sulfur cap enforcement intensity and limited certified supplier pools. Go-to-market execution should anchor on ISO 8217 bunker fuel qualification with integrated sustainability documentation bundles. For Investors and Strategic Acquirers: Carve-out targets emerge from agribusiness conglomerates divesting non-core oleochemical divisions to refocus on upstream plantation assets. Long-term viability centers on producers with demonstrated carbon intensity scoring capabilities and locked offtake agreements with fixed pricing mechanisms. The signal to watch is California LCFS credit market liquidity as an inflection indicator for traceability-premium sustainability across North American biodiesel supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Crushing | Cargill Incorporated leverages North American grain origination to secure captive feedstock supply for downstream esterification assets. |
| ISCC-EU Certification Program | Emery Oleochemicals differentiates lubricant-grade output through documented renewable carbon content qualifying for EU Green Deal compliance. |
| Enzymatic Transesterification Scale-Up | BASF SE deploys immobilized lipase biocatalysts for pharmaceutical-grade methyl esters with stringent residual methanol specifications. |
| Long-term Supply Agreement | KLK Oleo locks Rotterdam terminal offtake with fixed carbon intensity pricing displacing spot-market volatility exposure. |
| Joint Venture | Indonesian producers partner with domestic energy distributors to serve B35 mandate infrastructure buildout across Java-based transportation corridors. |
Methodological Framework
Cross-validation between trade flow databases and regulatory filing records anchors the qualitative findings across the fatty acid methyl ester value chain. Primary interviews with biodiesel blending terminal managers, lubricant compounder procurement leads, oleochemical plant operations directors, and sustainability certification auditors combined with secondary validation from customs/trade data, ECHA substance evaluation registers, EPA Renewable Fuel Standard compliance reports, and SEC 10-K filings. Bottom-up capacity installation tracking and top-down mandate-driven demand modeling triangulate volume estimates.
Sensitivity analysis around feedstock price volatility bands and mandate enforcement intensity scenarios shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product grade tier, end-use industry application, distribution channel structure, and regional regulatory cluster. CAGRs derive from installed base erosion rates and replacement demand curves indexed to carbon intensity threshold tightening schedules. Industry-specific forecast inputs incorporate palm oil futures curve movements and EU RED II blending threshold revision probabilities.
Decision-makers should treat outputs as directional under sustained renewable fuel mandate enforcement and current ISCC certification backlog timelines; material deviation would warrant model refresh. Forecasts reflect these base assumptions alongside implicit agricultural commodity price stability. Practitioners should keep alternative scenarios live as Indonesian domestic absorption policy and California LCFS credit market liquidity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Optical Whitening Agents Market
Specialty Chemicals
Squalene Market
Specialty Chemicals
Specialty Methacrylate Market
Specialty Chemicals
Photo Emulsion Market
Specialty Chemicals
Mexoryl SX (Ecamsule) Market
Specialty Chemicals
Petroleum Jelly Market
Specialty Chemicals
Chromium Polynicotinate Market
Specialty Chemicals
Precast Gels Market
Specialty Chemicals
Nucleotides Market
Specialty Chemicals
High-K and CVD ALD Metal Precursors Market
Specialty Chemicals
South Korea Cleanroom Disposable Gloves Market
Specialty Chemicals
Fe EDDHA Market
Specialty Chemicals
Fabric Antibacterial Spray Market
Specialty Chemicals
Sphingolipids Market
Specialty Chemicals
Global Spray Polyurethanes Foam Market
Specialty Chemicals
Ferrous Gluconate Market