
 Synthetic Ester Lubricants Market | 2026-2036
Synthetic Ester Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Synthetic Ester Lubricants Market Intelligence
The SAE AS5780 qualification for turbine engine oils is redrawing the competitive landscape for high-performance esters. ExxonMobil leverages its extensive R&D in polyol esters to meet these stringent specifications. Shell sustains its market position through a global distribution network for its aerospace lubricant portfolio. LANXESS specializes in specific ester chemistries, offering base stocks to other formulators.
Synthetic ester lubricants are high-performance oils synthesized through the esterification of an acid and an alcohol. They are characterized by their superior thermal stability, low-temperature fluidity, and inherent biodegradability compared to mineral oils. Within the base stock segment, polyol esters command a premium due to their use in demanding aerospace and refrigeration compressor oil applications. While the automotive application segment is large, industrial machinery applications for gear and chain oils represent the fastest-growing area.
The European Union's REACH regulation and its Ecolabel criteria directly influence the formulation and marketing of biodegradable lubricants. In the United States, the EPA's Vessel General Permit mandates the use of environmentally acceptable lubricants in marine applications, creating a dedicated market for synthetic esters. Formulators' strategic decisions will hinge on balancing the cost of advanced base stocks like complex esters against performance gains demanded by new equipment designs.
Market Dynamics
The market's central dynamic is the tension between extreme performance demands from sectors like aerospace and the stringent requirements of environmental regulations. This conflict compels formulators to develop advanced biodegradable base stocks that do not compromise thermal stability or oxidative resistance for next-generation machinery.
Growth Catalysts
- Environmental Regulations:The European Union's REACH framework and Ecolabel criteria are accelerating the shift towards biodegradable esters, particularly for industrial and marine applications where environmental release is a concern.
- Aerospace Sector Demand:The need for lubricants with exceptional high-temperature stability for jet turbine engines sustains a premium market for advanced polyol esters capable of meeting rigorous performance specifications.
- Industrialization in Asia:Rapid expansion within China's industrial machinery hubs creates consistent volume demand for high-performance synthetic gear, chain, and compressor oils to ensure equipment longevity and efficiency.
Market Restraints
- Cost Disparity:The high synthesis cost of complex and polyol esters relative to conventional mineral oils and even other synthetics like PAOs limits their use in price-sensitive, high-volume automotive and industrial segments.
- Feedstock Volatility:The supply chains for critical precursors, such as specialized fatty acids and neo-polyols, are concentrated, exposing formulators to significant price volatility and potential sourcing disruptions.
- Hydrolytic Stability:Certain ester chemistries are susceptible to hydrolysis upon contact with water, which can degrade the lubricant and form corrosive acids, requiring careful formulation and limiting use in some applications.
Strategic Opportunities
- New Refrigerant Fluids:The phase-out of high-GWP refrigerants creates an opportunity for specialized polyol esters (POEs) formulated for compatibility and miscibility with new, environmentally friendlier alternatives in refrigeration and AC systems.
- Marine Lubricant Mandates:The U.S. EPA's Vessel General Permit (VGP) mandate for Environmentally Acceptable Lubricants in marine vessels creates a durable, regulation-driven market for synthetic esters in applications with an oil-to-sea interface.
- Bio-based Feedstocks:Developing esters from renewable, non-food-competing bio-based raw materials provides a pathway to enhance sustainability profiles, meet corporate ESG targets, and appeal to environmentally conscious end users.
Industry Challenges
- Qualification Timelines:The extensive and costly testing required to achieve certifications, such as the SAE AS5780 standard for turbine engine oils, creates high barriers to entry and significantly lengthens the development-to-market cycle for new products.
- Formulation Expertise Scarcity:Balancing performance characteristics like thermal stability, lubricity, seal compatibility, and biodegradability requires a deep and scarce pool of formulation talent, posing a challenge for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synthetic Ester Lubricants Market |
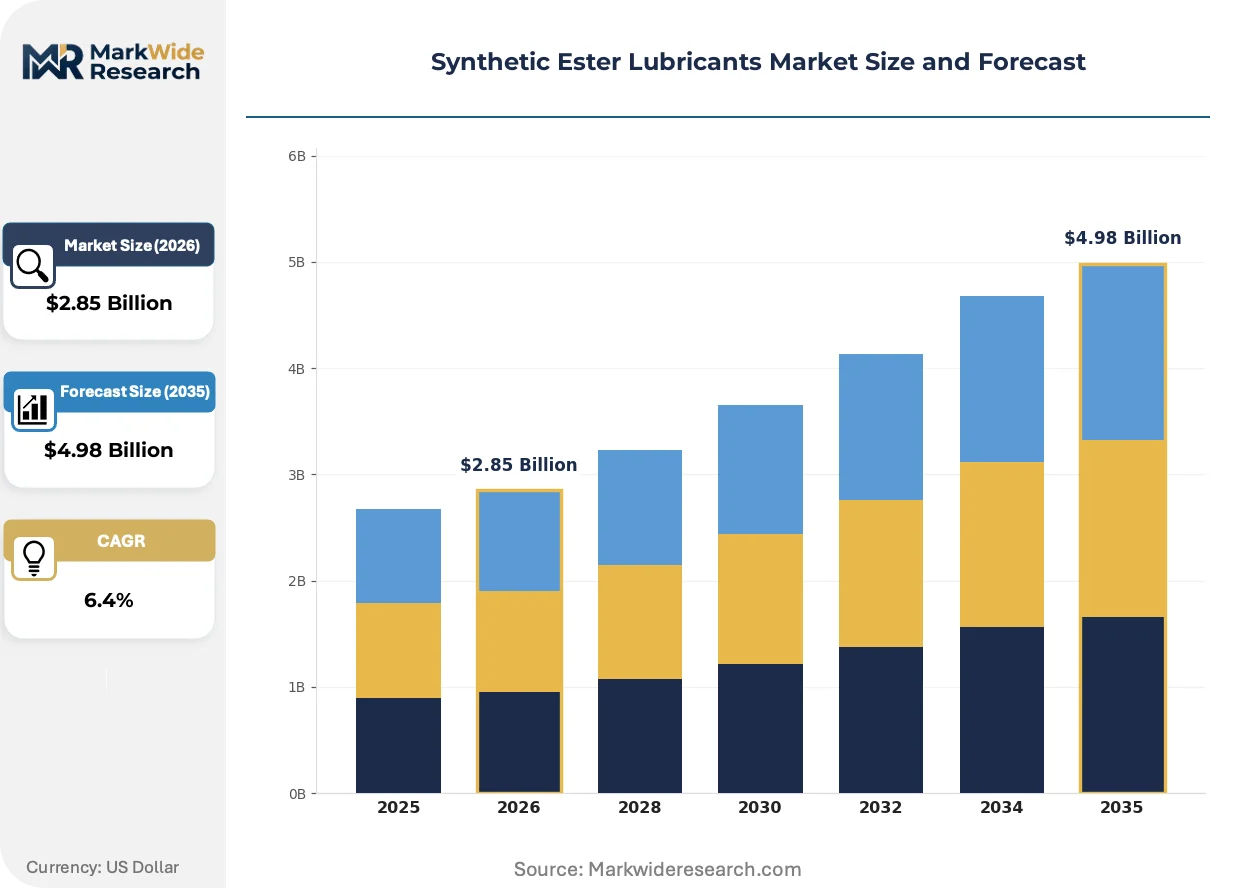
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $4.98 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Fluids, Compressor Oils, Gear Oils, Chain Oils Application: Aerospace, Marine, Automotive, Industrial Machinery Base Stock: Polyol Esters, Diester, Complex Esters, Monoester Performance Level: High-Performance, Standard, Extreme Pressure, Biodegradable |
| Companies Covered | ExxonMobil, Shell, BP, TotalEnergies, FUCHS, Chevron, Valvoline, AMSOIL, LANXESS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synthetic Ester Lubricants Market Strategic Shifts & Innovations
The evolution of lubricant formulation is shifting from general-purpose oils to highly specialized fluids engineered for specific applications and regulatory environments. This trend prioritizes performance precision over interchangeability, driven by advancements in equipment design and a stricter compliance landscape.
Polyol esters are high-performance synthetic base stocks that provide superior thermal and oxidative stability. The automotive sector, particularly for electric vehicle fluids, and the aerospace industry are adopting these advanced esters. This adoption is miniaturizing the performance gap that once allowed for wider use of conventional lubricants, making esters essential for next-generation compact, high-output engines and drivelines.
China's GB standards for industrial lubricants and its national 'dual carbon' goals are influencing domestic formulation requirements. The industrial consequence is a government-backed preference for energy-efficient and longer-lasting lubricants to reduce factory energy consumption and waste oil volumes. The industrial machinery segment is most affected, with local formulators prioritizing ester-based gear and compressor oils that offer demonstrable efficiency gains.
A significant shift in buyer behavior is the increasing reliance on original equipment manufacturer (OEM) approvals and third-party certifications over brand loyalty alone. This disrupts traditional sales models, empowering specialized distributors who can provide technical documentation and proof of performance for specific equipment. This trend is most visible in Germany's advanced manufacturing sector, where procurement decisions for hydraulic and gear oils are tied directly to equipment warranty requirements.
Synthetic Ester Lubricants Market Segmentation
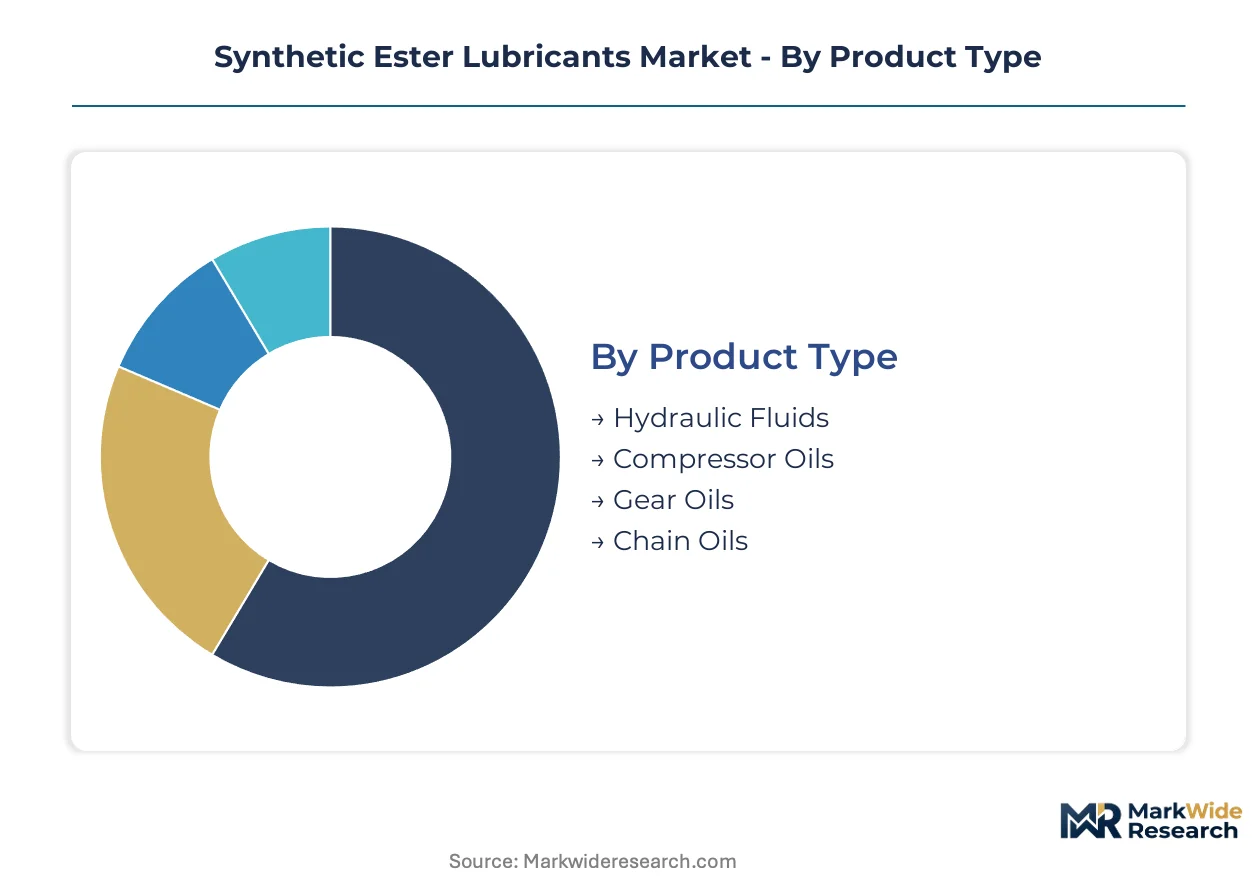
Synthetic ester lubricants serve diverse industrial and mobile applications, each with unique performance and regulatory demands. Understanding market segmentation reveals where specialized formulations deliver critical value and where cost pressures influence material selection. This granular view highlights areas of innovation and competitive intensity across the value chain.
Product Type:
The product type segmentation highlights areas where synthetic esters face significant substitution pressure from mineral oils due to cost, yet offer superior performance where equipment demands are high.
- Compressor Oils:These synthetic fluids maintain viscosity stability and prevent carbon deposits under extreme operating temperatures and pressures. Demand for these esters concentrates in industrial machinery hubs, particularly in China, where energy efficiency targets drive adoption.
- Gear Oils:Formulated to reduce friction and wear in heavy-duty enclosed gear systems, these lubricants extend equipment lifespan and enhance operational efficiency. Industrial machinery applications, especially in Germany's advanced manufacturing sector, prioritize these high-performance ester-based oils.
- Hydraulic Fluids:These esters provide excellent lubricity and thermal stability for power transmission in demanding hydraulic systems.
- Chain Oils:Designed for high-temperature and heavy-load applications, these lubricants minimize wear and reduce residue formation on industrial chains.
Hydraulic Fluids anchor the volume base while Compressor Oils gain share at the steepest rate.
Application:
Performance demands vary significantly across application segments, dictating the required base stock complexity and formulation cost for synthetic ester lubricants.
- Aerospace:This segment demands lubricants with exceptional thermal stability and low-temperature fluidity for jet turbine engines and hydraulic systems. Rigorous SAE AS5780 qualifications drive innovation in polyol ester formulations for this critical sector.
- Industrial Machinery:Covering gear, compressor, and hydraulic systems, this segment requires lubricants that enhance efficiency and extend equipment life in manufacturing and processing plants. China's industrial expansion drives substantial volume demand for high-performance ester-based solutions.
- Marine:Environmentally acceptable lubricants are mandated for marine vessels, particularly in the US, driving demand for biodegradable ester solutions.
- Automotive:While a large volume market, this segment primarily uses esters in specific high-performance or electric vehicle fluid applications due to cost considerations.
The Automotive segment represents a substantial volume opportunity, yet Aerospace applications command premium pricing due to stringent performance requirements.
Base Stock:
The base stock category reflects varying levels of supply chain concentration, influencing raw material availability and pricing for formulators.
- Polyol Esters:Synthesized from polyols and fatty acids, these base stocks offer superior thermal and oxidative stability for demanding applications. Aerospace and refrigeration compressor oils heavily utilize polyol esters due to their high performance attributes.
- Complex Esters:These multi-functional esters combine properties from different ester types, providing enhanced lubricity and seal compatibility for specialized industrial fluids. Formulators balance the cost of these advanced base stocks against specific performance gains in new equipment designs.
- Diester:Formed from dicarboxylic acids and alcohols, diesters provide good thermal stability and solvency, often blended with other base stocks.
- Monoester:Simple esters derived from monocarboxylic acids and alcohols, offering basic lubricity and often used as plasticizers or solvency enhancers.
Polyol Esters continue to drive innovation in high-performance formulations, while Monoester solutions offer cost-effective entry points for basic lubrication needs.
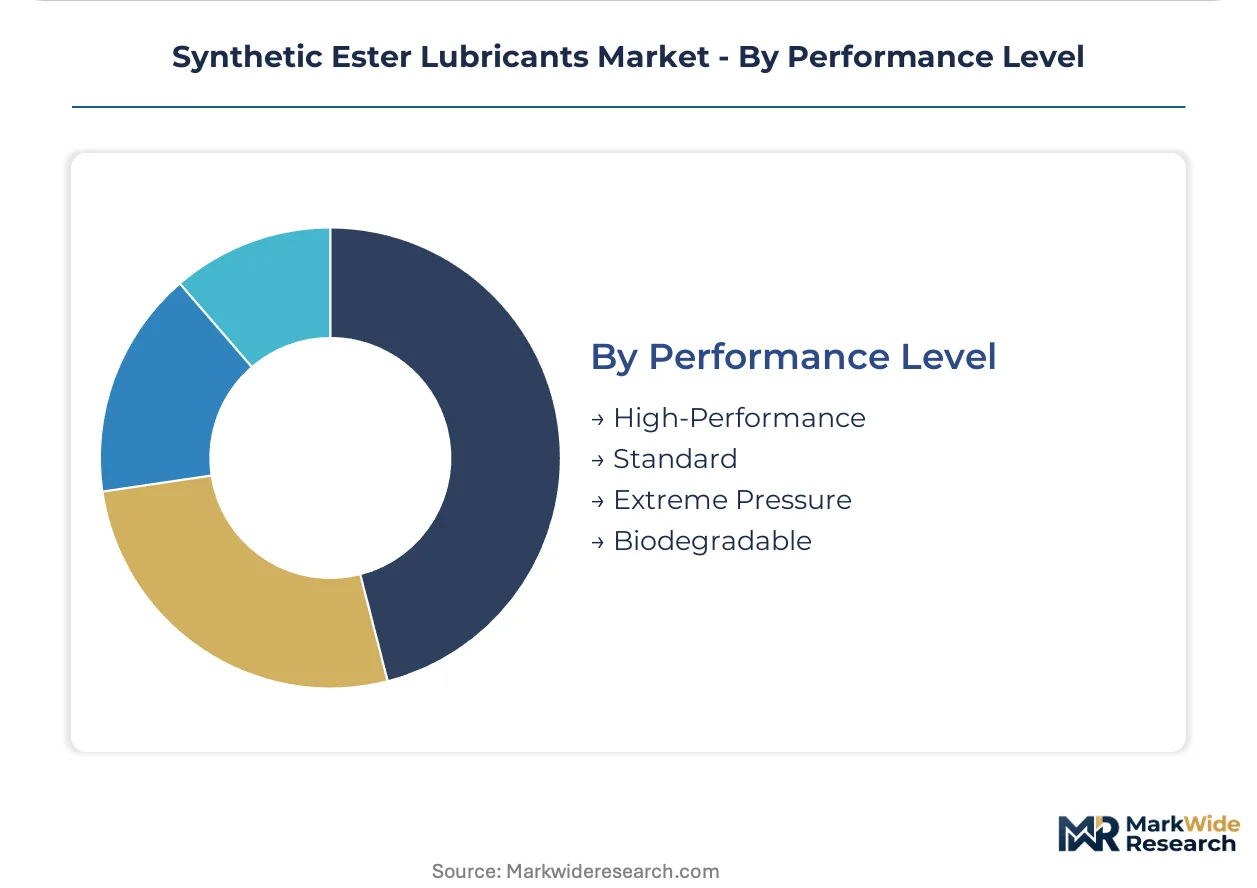
Performance Level:
Regulatory frameworks significantly influence the formulation and adoption of synthetic esters within specific performance level segments, particularly for environmental compliance.
- Biodegradable:These esters meet environmental standards like the EU Ecolabel and US EPA's Vessel General Permit, reducing ecological impact in sensitive applications. Marine and certain industrial uses prioritize these formulations to mitigate environmental release risks.
- High-Performance:Characterized by exceptional thermal stability, oxidative resistance, and low-temperature fluidity, these lubricants are critical for advanced machinery. Aerospace turbine engines and high-efficiency industrial compressors rely heavily on these specialized ester types.
- Standard:These esters offer balanced performance for general industrial and automotive applications where extreme conditions are not prevalent.
- Extreme Pressure:Formulations incorporating specific additives provide enhanced film strength and wear protection under high load and shock conditions.
Differentiation across performance levels enables tailored solutions for diverse equipment needs, from basic lubrication to highly specialized critical operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Environmental policy drivers influence the regional distribution of synthetic ester lubricant demand, especially in areas with stringent regulations. Specific government mandates and industrial efficiency targets shape market adoption across diverse geographies. This regulatory push encourages formulators to prioritize advanced ester chemistries for specialized applications.
China
China's industrial machinery hubs create substantial volume demand for high-performance synthetic gear and compressor oils. The country's GB standards for industrial lubricants and national 'dual carbon' goals influence domestic formulation requirements. Industrial clusters in the Yangtze River Delta and Pearl River Delta prioritize ester-based lubricants for energy efficiency and extended equipment life.
Germany
Germany's advanced manufacturing sector drives demand for high-performance ester lubricants, particularly for hydraulic and gear oils. The EU's REACH framework and Ecolabel criteria compel shifts towards biodegradable esters in sensitive applications. Procurement decisions in regions like Bavaria and North Rhine-Westphalia are increasingly tied to OEM approvals and equipment warranty requirements.
United States
The United States aerospace sector demands lubricants with exceptional thermal stability for jet turbine engines, sustaining a premium market for advanced polyol esters. The EPA's Vessel General Permit mandates environmentally acceptable lubricants in marine applications, creating a dedicated market for synthetic esters. Major aerospace and marine industry centers, such as those in the Pacific Northwest and the Gulf Coast, drive this specialized demand.
France
France's robust aerospace and defense industries require high-performance synthetic esters for critical engine and hydraulic systems. European Union environmental regulations, including REACH, influence the formulation of lubricants for industrial applications within the country. Key manufacturing regions like Auvergne-Rhône-Alpes and Île-de-France focus on advanced ester solutions for precision engineering.
India
India's ongoing industrialization and infrastructure development generate consistent demand for high-performance lubricants in machinery and manufacturing. Government initiatives promoting energy efficiency and equipment longevity encourage the adoption of advanced synthetic oils. Industrial corridors in Maharashtra and Gujarat are seeing a rise in ester-based lubricant use for demanding applications.
Synthetic Ester Lubricants Market Key Industry Players
Listed leaders compete with private specialists across the synthetic ester lubricants market, driving innovation in base stock chemistry and application-specific formulations. The market structure features a mix of integrated chemical producers and specialized lubricant blenders. Strategic archetypes include large-scale diversified chemical companies, performance-focused niche players, and regional formulators. Dominant competitive moves involve strategic partnerships for raw material sourcing and continuous R&D investment in advanced ester technologies.
Large, integrated energy and chemical companies, such as ExxonMobil, Shell, and TotalEnergies, leverage their extensive R&D capabilities and global distribution networks. These entities anchor the high-performance segment, particularly for aerospace and demanding industrial applications. LANXESS AG, a Germany-based specialty chemical company, exemplifies a focused base stock supplier, specializing in specific ester chemistries to serve other formulators globally.
| Leading Market Players |
|---|
| ExxonMobil |
| Shell |
| BP |
| TotalEnergies |
| FUCHS |
| Chevron |
| Valvoline |
| AMSOIL |
| LANXESS |
| Others |
Cost & Logistics Intelligence
SAE AS5780 qualification for turbine engine oils gates both product supply qualification and price differentiation for high-performance synthetic esters. This stringent standard ensures only specialized formulations can access premium aerospace applications.
Pricing Analysis
Certification level, such as SAE AS5780 for aerospace or EU Ecolabel for biodegradability, creates the primary spread in synthetic ester lubricant pricing. The market largely employs a three-tier pricing structure across premium, standard, and economy levels, reflecting varying performance needs and base stock costs. Price differentiation also stems from specific performance attributes like thermal stability and low-temperature fluidity. Pricing pressure stems from the high synthesis cost of polyol esters in price-sensitive segments like automotive. The aerospace sector exhibits the lowest price sensitivity, while the automotive segment remains highly cost-conscious.
Supply Chain Analysis
Germany, home to specialized chemical producers like LANXESS, concentrates the supply of specific ester base stocks for formulators. The synthetic ester lubricants supply chain draws from critical precursors such as specialized fatty acids and neo-polyols. Feedstock volatility for these concentrated raw materials presents a significant structural risk for formulators. Downstream, distribution runs through a mix of global networks by integrated energy companies and specialized distributors for niche applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
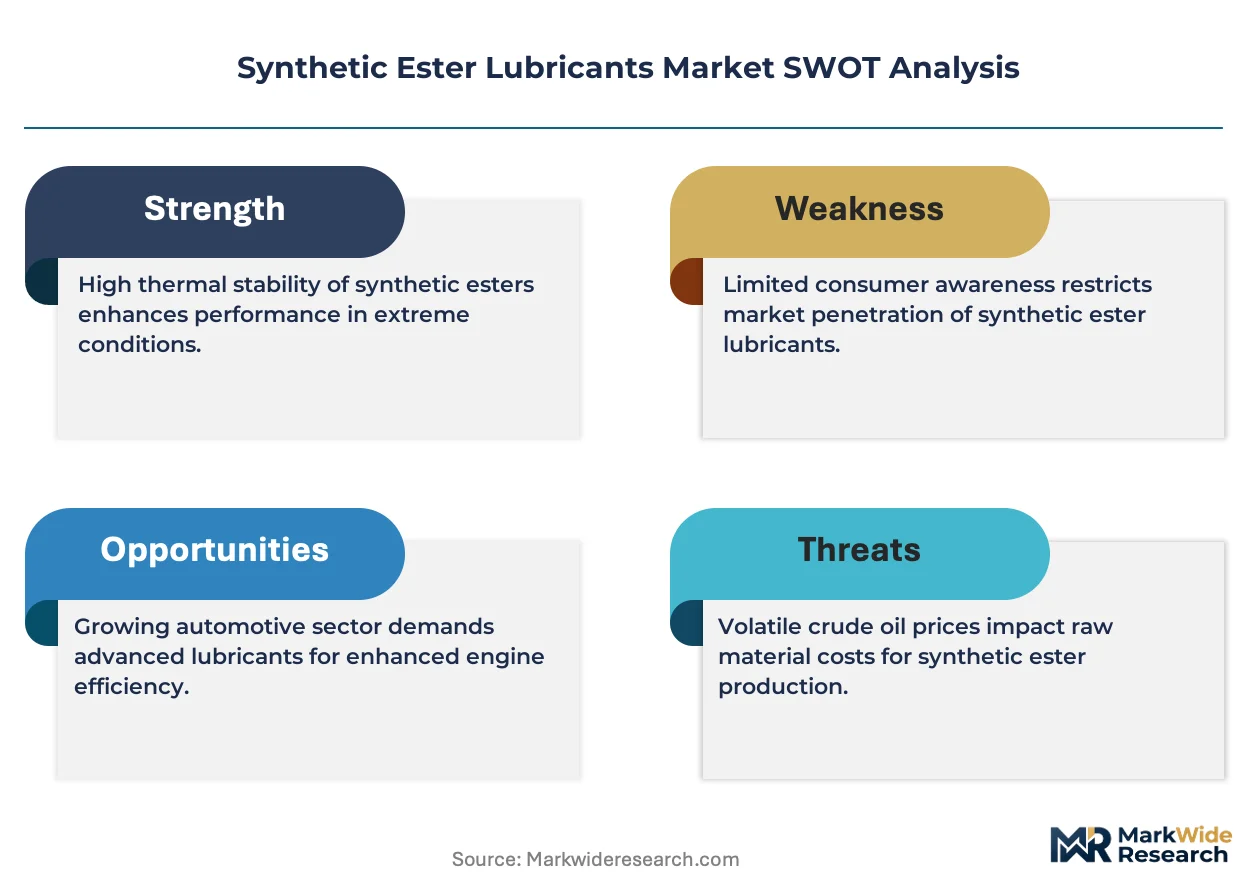
The synthetic ester lubricants market is defined by a deep scarcity of formulation expertise, particularly in balancing extreme performance demands with stringent environmental compliance. This specialized knowledge acts as a critical bottleneck for innovation and market entry.
For Market Incumbents: Consolidate market position through sustained R&D investment in advanced ester technologies, focusing on next-generation polyol esters for aerospace and EV fluids. Establish strategic partnerships for securing specialized fatty acids and neo-polyol precursors to mitigate feedstock volatility. Counter the threat of extended qualification timelines by streamlining internal testing processes and collaborating with key OEMs for early product validation.
For New Entrants and Emerging Players: Lead with specialized bio-based ester solutions that meet evolving environmental mandates like the EPA's VGP for marine applications. Target the growing demand for specialized polyol esters compatible with new refrigerant fluids in AC systems. A go-to-market angle emphasizing technical documentation and demonstrable performance proof for specific equipment will resonate with procurement decisions in advanced manufacturing sectors.
For Investors and Strategic Acquirers: The EU's REACH framework and global 'dual carbon' goals reshape the acquisition landscape, favoring companies with proven biodegradable ester portfolios. Long-term viability hinges on investments in firms possessing deep formulation expertise and robust intellectual property in high-performance, environmentally compliant base stocks. A key signal to watch is the expansion of environmental regulations into new industrial applications, indicating broader market adoption for advanced esters.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Bio-based Feedstock R&D | Reduces reliance on petrochemicals and enhances sustainability profiles for end-users. |
| Secure Long-term Neo-polyol Supply Agreements | Mitigates price volatility and ensures consistent production for high-performance esters. |
| Pursue SAE AS5780 Qualification for New Formulations | Unlocks access to the premium aerospace lubricant market and validates thermal stability. |
| Expand Global Distribution for Aerospace Portfolio | Leverages existing networks to capture demand in critical high-performance sectors. |
| Develop Specialized POEs for New Refrigerant Compatibility | Addresses emerging market needs driven by the phase-out of high-GWP refrigerant fluids. |
Research Approach
Initial hypotheses were tested against primary input from R&D directors, OEM procurement leads, product managers, and environmental compliance officers, and refined through iterative analysis. This involved extensive interviews with industry stakeholders across the value chain, validated by secondary research from chemical industry association reports, regulatory body publications from EPA and ECHA, patent databases, and company annual reports. Both bottom-up and top-down triangulation methods were applied to ensure data accuracy and consistency.
Variance decomposition informed the quantitative analytical framework, modeling market dynamics across the analysis window. Segmentation dimensions including product type, application, base stock, performance level, and regional regulatory landscape were meticulously modeled. Compound Annual Growth Rates (CAGRs) were derived by projecting demand drivers such as equipment design cycles and feedstock price trends, ensuring robust market trajectory estimates.
The analysis sits within stated boundaries; outcomes outside significant geopolitical events impacting feedstock supply or unforeseen technological breakthroughs would require recalibration. Forecasts reflect documented assumptions regarding regulatory stability and market adoption rates for advanced lubricants. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
China Commercial Vehicles Lubricants Market
Lubricants
China Lubricants Market
Lubricants
Angola Lubricants Market
Lubricants
Russia Lubricants Market
Lubricants
Asia-Pacific Automotive Lubricants Market
Lubricants
Europe Metalworking Fluids Market
Lubricants
Global Lubrication Systems Market
Lubricants
Spain Commercial Vehicles Lubricants Market
Lubricants
Spain Lubricants Market
Lubricants
Lubricants for Cement Industry Market
Lubricants
Philippines Lubricants Market
Lubricants
Lubricated Tracks Market
Lubricants
Friction Reducers Market
Lubricants
Hydraulic Oil Additives Market
Lubricants
Brazil Commercial Vehicles Lubricants Market
Lubricants
Germany Automotive Engine Oils Market