
 Polytetrafluoroethylene (PTFE) Market | 2026-2036
Polytetrafluoroethylene (PTFE) Market Size, Share, and Industry Trends Forecast 2026-2036
Polytetrafluoroethylene (PTFE) Market Intelligence
Expertise in sustainable fluoropolymer chemistry and PFAS-free alternatives is unwinding the market's traditional production dependencies. The Chemours Company leverages its scale in fluorochemicals to serve high-volume industrial applications. Daikin Industries, Ltd. specializes in advanced materials for electronics and semiconductors. Solvay positions itself with a portfolio of specialty polymers for demanding aerospace and automotive sectors.
Polytetrafluoroethylene (PTFE) is a high-performance fluoropolymer characterized by its exceptional chemical inertness and a very low coefficient of friction. Its molecular structure provides high thermal stability, making it suitable for applications requiring non-reactivity and heat resistance. Powder and granular forms are fundamental for processing, while finished forms like rods and sheets serve fabrication needs. Sealing solutions and electrical insulation remain the largest application segments, while demand for expanded PTFE in medical devices represents a high-margin growth area.
The regulatory environment is defined by increasing scrutiny over per- and poly-fluoroalkyl substances (PFAS). The US Environmental Protection Agency (EPA) and the European Chemicals Agency (ECHA) under REACH are implementing stricter controls on production and use. In parallel, China's Ministry of Ecology and Environment (MEE) is addressing fluorochemical pollution. Navigating these evolving regulations while investing in non-PFAS alternatives is the central strategic challenge for all market participants.
Market Dynamics
The central dynamic in the polytetrafluoroethylene market is the immense regulatory pressure on PFAS compounds. Actions by the US EPA and Europe's ECHA are forcing a systemic shift away from legacy chemistries toward sustainable fluoropolymers and non-PFAS alternatives.
Growth Catalysts
- Medical Grade Demand:The medical device sector's need for high-purity, biocompatible ePTFE is a significant catalyst, particularly for cardiovascular implants, surgical meshes, and advanced catheter systems that require inert materials.
- Advanced Electronics in China:China's strategic focus on its semiconductor and telecommunications industries drives demand for PTFE in high-frequency circuit boards, cable insulation, and corrosion-resistant manufacturing equipment.
- 5G Infrastructure:The global build-out of 5G networks requires low-loss PTFE dielectrics for high-frequency coaxial cables, connectors, and antennas to maintain signal integrity and minimize energy loss at millimeter-wave frequencies.
Market Restraints
- Regulatory Scrutiny:The US EPA's stringent regulations and health advisories on specific PFAS compounds create significant compliance costs, limit processing aid options, and introduce market uncertainty for producers.
- Material Substitution:High-performance thermoplastics such as PEEK and FEP present a substitution threat in certain automotive and industrial applications where their specific mechanical or processing advantages outweigh PTFE's benefits.
- Raw Material Volatility:Fluctuations in the price and availability of fluorspar, a key precursor material, present a major restraint as supply is concentrated and subject to geopolitical and trade policy shifts.
Strategic Opportunities
- Green Hydrogen Economy:The emerging green hydrogen sector offers a new frontier for PTFE microporous membranes used in electrolyzers and fuel cells as gas diffusion layers and separators, requiring chemical and thermal stability.
- PFAS-Free Formulations:Europe's REACH framework, while restrictive, creates a clear market opportunity for developing and commercializing certified PFAS-free alternatives and next-generation fluoropolymers that meet new compliance standards.
- Industrialization in India:India's expanding manufacturing base, particularly in chemical processing, pharmaceuticals, and automotive components, represents an underpenetrated market for PTFE applications in gaskets, seals, and linings.
Industry Challenges
- Capital-Intensive Compliance:Retrofitting or constructing new production facilities to meet evolving environmental standards from bodies like China's MEE for fluorochemical manufacturing requires substantial capital investment and long lead times.
- End-of-Life Recycling:Developing scalable and economically viable recycling processes for post-consumer PTFE remains a significant technical challenge due to the material's extreme inertness and high thermal stability.
- Aerospace Certification Delays:The rigorous and lengthy qualification and certification timelines for new PTFE materials in the aerospace sector can slow the adoption of innovative formulations and delay market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polytetrafluoroethylene (PTFE) Market |
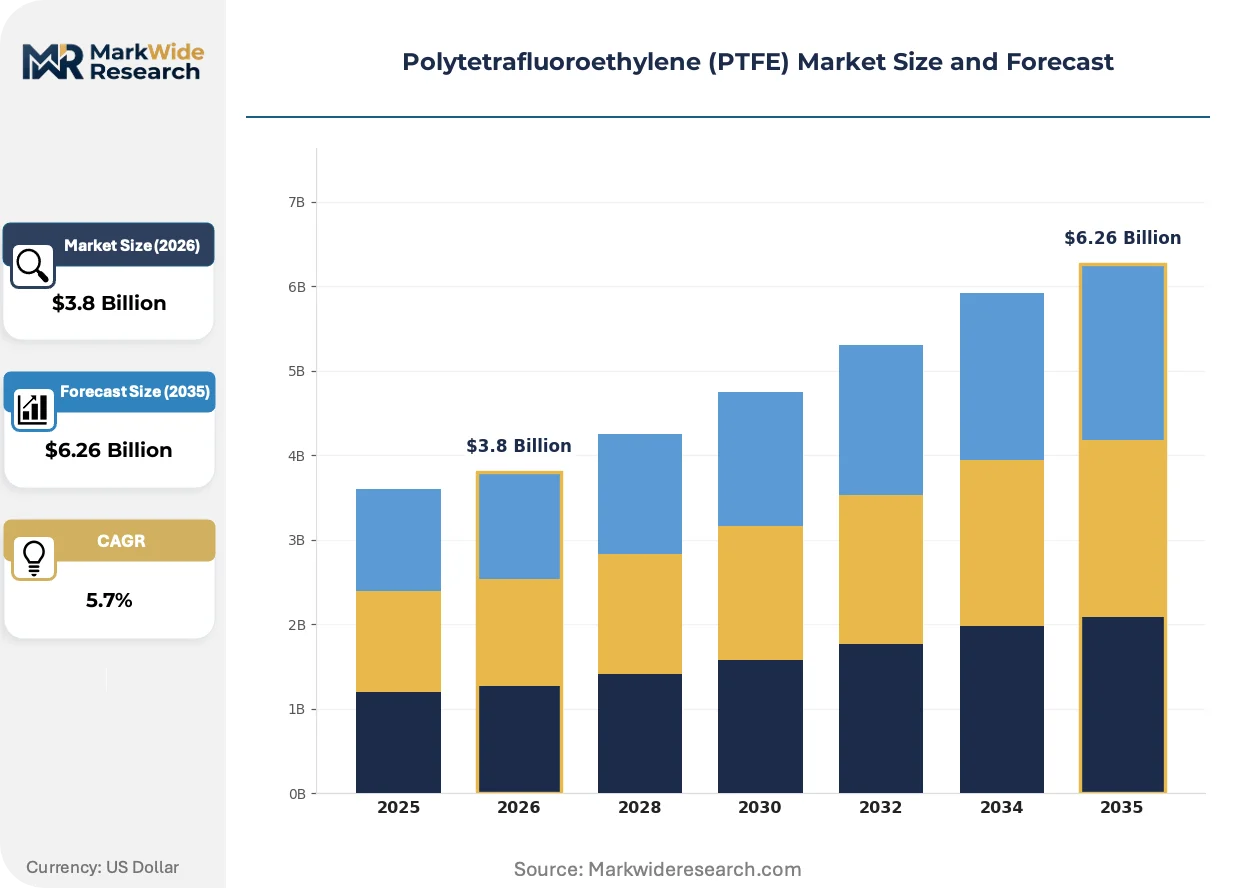
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Virgin PTFE, Filled PTFE, Expanded PTFE, Modified PTFE Form: Powder, Rod, Tube, Sheet, Film Application: Sealing Solutions, Electrical Insulation, Lubricants, Chemical Processing, Medical Devices End User Industry: Chemical Processing Plants, Electronics Manufacturers, Automotive Suppliers, Medical Equipment Producers, Aerospace Firms |
| Companies Covered | Gujarat Fluorochemicals Limited, 3M, AGC Inc., Halopolymer, Solvay, Daikin Industries, Ltd., Dongyue Group, Shanghai Huayi 3F New Materials Co. Ltd., The Chemours Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polytetrafluoroethylene (PTFE) Market Strategic Shifts & Innovations
Intensifying environmental oversight and technological advancements are forcing a re-evaluation of the entire PTFE lifecycle. This pressure is driving innovation in production chemistry, material properties, and end-use applications, moving the industry toward more specialized and sustainable solutions.
Modified PTFE, enhanced with comonomers or fillers, offers improved properties like reduced cold flow and superior weldability. Automotive and industrial sealing sectors are adopting these materials to meet higher performance and longevity standards for critical components. This advancement is bifurcating the market between standard commodity grades and high-value, specialized formulations for demanding applications.
The European Chemicals Agency's (ECHA) proposal under REACH to restrict a broad class of PFAS compounds is a defining regulatory action. This forces a fundamental reassessment of fluoropolymer supply chains and product portfolios across the continent. Industries such as medical devices and aerospace, which depend on PTFE for critical performance, are actively validating alternative materials to ensure future compliance.
Original equipment manufacturers are increasingly specifying PTFE components that are certified as being produced without PFOA or other specific PFAS of concern. This preference bypasses simple cost-based sourcing, favoring suppliers who can provide transparent supply chain documentation and material traceability. This trend is most prominent in consumer electronics and food contact applications across North America and Europe.
Polytetrafluoroethylene (PTFE) Market Segmentation
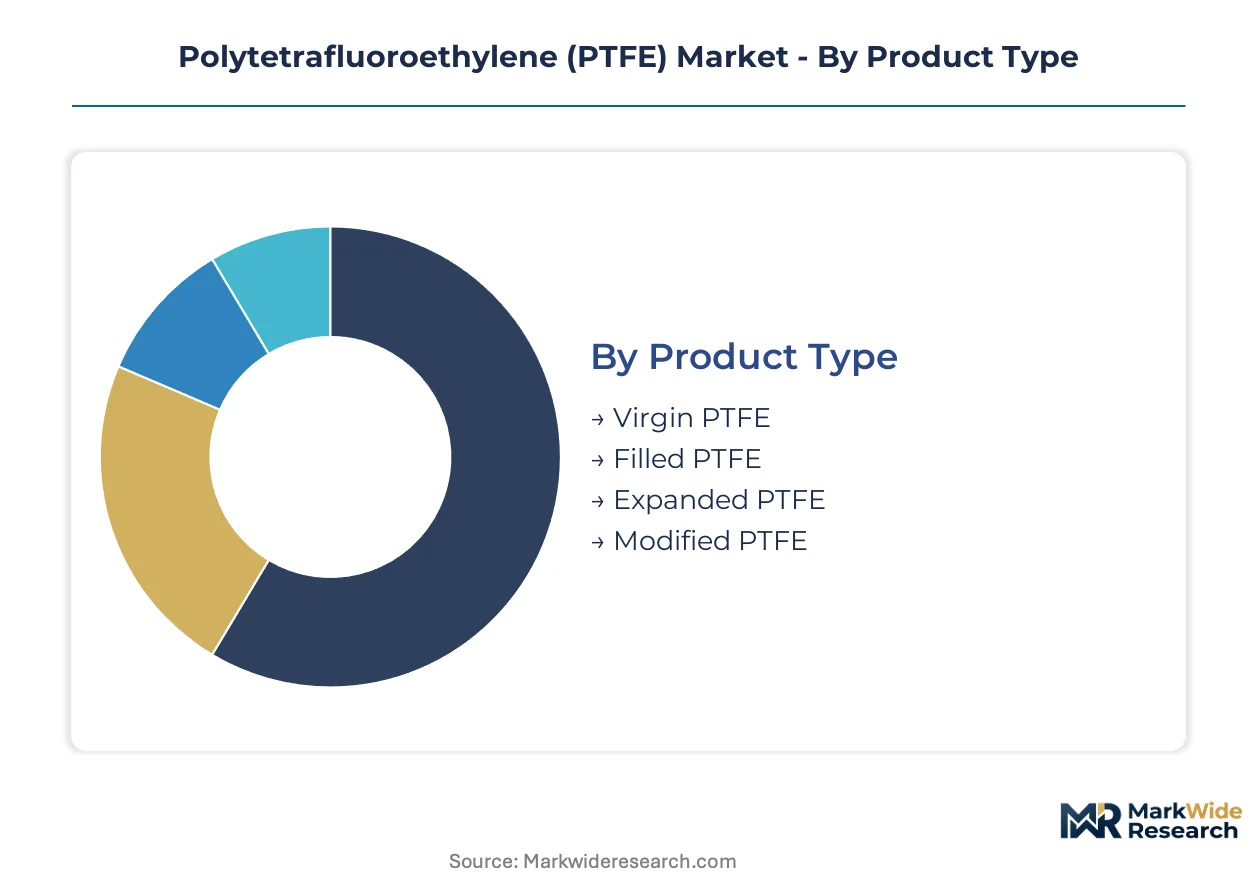
The polytetrafluoroethylene market segments reflect varying material properties, processing requirements, and end-use performance demands. Understanding these distinctions is critical for manufacturers navigating evolving regulatory pressures and identifying high-growth application niches. Each segment addresses specific functional needs across diverse industrial landscapes.
Product Type:
The product type segmentation highlights where material substitution pressures are most acute, particularly as regulatory bodies like the US EPA and ECHA scrutinize traditional PFAS compounds.
- Expanded PTFE:This high-purity, biocompatible, and porous form of PTFE is critical for advanced medical applications. Demand is concentrating in the medical devices sector for cardiovascular implants and advanced catheter systems, driven by requirements for inert, high-performance materials.
- Modified PTFE:Enhanced with comonomers or fillers, this variant offers improved properties such as reduced cold flow, superior weldability, and better creep resistance. Automotive and industrial sealing sectors are adopting these materials to meet higher performance and longevity standards for critical components.
- Virgin PTFE:This unmodified, pure PTFE resin is used for its inherent chemical inertness and low friction in general industrial applications.
- Filled PTFE:This type incorporates additives like glass fiber or carbon to enhance mechanical strength, wear resistance, or electrical conductivity for specific engineering requirements.
Virgin PTFE retains volume leadership; Expanded PTFE holds the steepest expansion curve.
Form:
The various forms of PTFE dictate their primary processing methods and suitability for specific applications, ranging from bulk manufacturing to precision component fabrication.
- Powder:Fine particles are used for molding, extrusion, and dispersion, serving as a fundamental raw material for various PTFE products. Demand is concentrated in the chemical processing industry for liners and coatings, where its inertness is crucial for corrosive environments.
- Sheet:Flat, solid forms produced by compression molding or skiving, suitable for gaskets, seals, and slide bearings. Fabrication needs in the general manufacturing and construction sectors drive demand for its non-stick and low-friction properties.
- Rod:Solid cylindrical shapes are used for machining into custom components like bushings, seals, and insulators in industrial machinery.
- Tube:Hollow cylindrical forms, often extruded, are utilized for fluid handling, electrical sleeving, and heat exchangers due to chemical resistance.
- Film:Thin, flexible sheets, often skived or cast, are employed in electrical insulation, non-stick surfaces, and sensitive medical packaging.
Powder forms are fundamental for primary processing, while finished forms like film are gaining traction in specialized electronics applications.
Application:
Application segments highlight where PTFE's unique properties deliver the most value, driving substantial volume and revenue across diverse industries.
- Sealing Solutions:This application leverages PTFE's chemical inertness, high temperature resistance, and low friction for gaskets, O-rings, and valve seats. The chemical processing and oil & gas industries drive demand, requiring reliable seals in aggressive environments.
- Medical Devices:This sector requires high-purity, biocompatible PTFE, particularly ePTFE, for cardiovascular implants, surgical meshes, and advanced catheter systems. Stringent regulatory approvals from bodies like the US FDA and Europe's EMA ensure material safety and performance.
- Electrical Insulation:This application utilizes PTFE's excellent dielectric strength and thermal stability for wire and cable insulation, connectors, and high-frequency circuit boards.
- Chemical Processing:This sector employs PTFE for linings, coatings, and components in pumps and valves due to its extreme resistance to corrosive chemicals.
- Lubricants:PTFE powder is incorporated into greases and oils to reduce friction and wear in industrial machinery and automotive components.
Sealing solutions maintain their position as a foundational application, with medical devices expanding rapidly due to specialized material requirements.
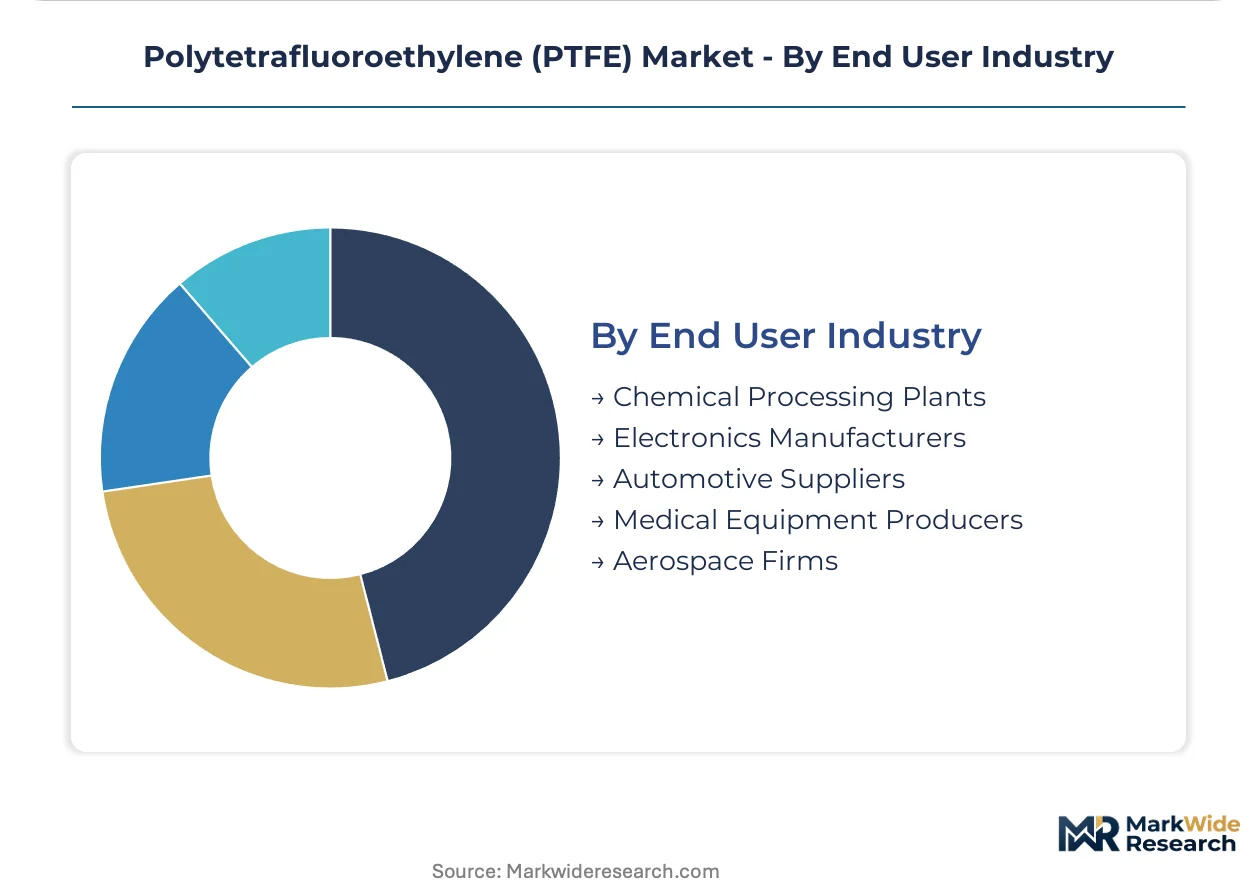
End User Industry:
End-user industries categorize the primary customer types benefiting from PTFE's performance characteristics, from heavy industrial operations to precision manufacturing.
- Medical Equipment Producers:This industry demands high-purity, biocompatible PTFE for implantable devices, surgical instruments, and diagnostic equipment. Regulatory compliance with bodies such as the US FDA and Europe's MDR is a paramount concern for material selection.
- Electronics Manufacturers:This industry utilizes PTFE for high-frequency circuit boards, cable insulation, and semiconductor manufacturing components due to its excellent dielectric properties and thermal stability. China's strategic investment in advanced electronics heavily influences this demand.
- Chemical Processing Plants:This sector relies on PTFE for corrosion-resistant linings, seals, and components in pumps and valves handling aggressive chemicals.
- Automotive Suppliers:This industry integrates PTFE into seals, bearings, and fuel system components for enhanced durability and reduced friction in vehicles.
- Aerospace Firms:This sector specifies PTFE for lightweight wiring, hydraulic seals, and structural components requiring extreme temperature and chemical resistance.
Medical equipment producers and electronics manufacturers are driving innovation due to their stringent performance and purity requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing-power asymmetry exists between established producers in Western economies and emerging manufacturing hubs in Asia. Regulatory shifts in Europe and the United States are driving innovation in sustainable alternatives, while China's industrial expansion fuels demand for traditional PTFE.
China
China's advanced manufacturing and electronics industries are driving substantial demand for PTFE in high-frequency circuit boards and cable insulation. The Ministry of Ecology and Environment (MEE) is implementing stricter controls on fluorochemical pollution, influencing local production practices. Concentrated in industrial clusters like the Yangtze River Delta, semiconductor and telecommunications firms require high-performance PTFE materials.
United States
Demand for high-purity expanded PTFE in medical devices, particularly for cardiovascular implants and catheter systems, propels the US market. The US Environmental Protection Agency (EPA) imposes stringent regulations on PFAS compounds, increasing compliance costs for manufacturers. Major medical device manufacturing hubs in states like Massachusetts and California are validating alternative materials to ensure future compliance.
Germany
Germany's automotive and aerospace sectors require specialized PTFE for seals, bearings, and lightweight components, prioritizing durability and performance. Europe's REACH framework, particularly the ECHA's PFAS restriction proposal, significantly impacts supply chains and material development in the country. The chemical industry in regions like North Rhine-Westphalia is investing in next-generation fluoropolymers to meet evolving standards.
India
India's expanding manufacturing base, especially in chemical processing, pharmaceuticals, and automotive components, represents a significant underpenetrated market for PTFE applications. The Bureau of Indian Standards (BIS) sets quality benchmarks for industrial materials, supporting local production. Industrial corridors like Gujarat and Maharashtra are seeing increased adoption of PTFE for gaskets, seals, and linings.
Japan
Japan's electronics and automotive industries demand high-performance PTFE for advanced applications, including precision components and electrical insulation. The Ministry of Economy, Trade and Industry (METI) supports research into sustainable materials and advanced polymer development. Companies in the Kanto region, particularly around Tokyo, are focusing on specialized PTFE formulations for high-tech exports.
Polytetrafluoroethylene (PTFE) Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the polytetrafluoroethylene market. The market structure is moderately consolidated at the top tier, with a broader base of specialized fabricators and compounders. Strategic archetypes include large-scale integrated fluoropolymer producers, specialized material developers, and regional convertors. Portfolio diversification into non-PTFE fluoropolymers and strategic partnerships for advanced material development are dominant competitive moves.
Among global fluoropolymer specialists, The Chemours Company exemplifies a large-scale integrated producer, leveraging its broad fluorochemical expertise for high-volume industrial applications. Daikin Industries, Ltd. represents an archetype focused on advanced materials, particularly for electronics and semiconductors, emphasizing high-purity and performance. Solvay occupies a position among specialty polymer providers, catering to demanding sectors like aerospace and automotive with tailored solutions.
| Leading Market Players |
|---|
| Gujarat Fluorochemicals Limited |
| 3M |
| AGC Inc. |
| Halopolymer |
| Solvay |
| Daikin Industries, Ltd. |
| Dongyue Group |
| Shanghai Huayi 3F New Materials Co. Ltd. |
| The Chemours Company |
| Others |
Cost & Logistics Intelligence
Days-of-inventory for high-purity ePTFE are tightening, reflecting specialized production requirements and concentrated supply chains that ultimately influence pricing power for advanced materials.
Pricing Analysis
Configured-to-order pricing for specialized PTFE grades commands a premium over standard commodity offerings. The dominant pricing model is contract-based long-term offtake, often hybridizing with spot market rates for virgin PTFE. Price differentiation stems from quality grade, certification levels (e.g., US FDA approval for medical devices), and customization complexity. Pricing pressure stems from regulatory scrutiny on legacy PFAS chemistries, impacting standard grades. Medical equipment producers and aerospace firms demonstrate low price sensitivity for critical components, while general industrial applications remain more price-sensitive.
Supply Chain Analysis
Fluorspar mining concentration in regions like China underpins the global PTFE supply chain, creating potential vulnerability. Key precursor material dependencies include hydrofluoric acid and chloroform. A structural supply chain risk is geopolitical and trade policy shifts affecting fluorspar availability and pricing. Distribution runs through a blend of direct sales to large original equipment manufacturers and specialized distributors catering to smaller fabricators. China, the United States, and Germany are significant production hubs, balancing local demand with export capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polytetrafluoroethylene market presents a service-attach opportunity, with specialized certification and compliance support expanding faster than the core material volumes.
For Market Incumbents:
Fortify research and development into PFAS-free alternatives to mitigate risks from intensifying regulatory scrutiny on legacy compounds. Expand production capacity for high-purity expanded PTFE to meet the growing demand from the medical device sector. Invest in advanced certification processes for new materials, leveraging existing channel control. This proactive approach helps insulate against material substitution threats from high-performance thermoplastics.
For New Entrants and Emerging Players:
Differentiate on sustainability credentials by developing and commercializing certified PFAS-free formulations. Target underpenetrated markets like India's expanding industrial base, focusing on applications in chemical processing and automotive components. A go-to-market strategy should emphasize transparent supply chain documentation and adherence to evolving environmental standards. Niche applications in green hydrogen economies, such as microporous membranes, represent a viable entry point.
For Investors and Strategic Acquirers:
Carve-out targets emerge from large chemical conglomerates seeking to divest non-core fluoropolymer assets facing significant regulatory headwinds. The long-term viability of high-performance PTFE remains strong, particularly for specialized, high-purity grades. Acquisition targets should include specialized material developers with robust intellectual property in non-PFAS alternatives or ePTFE manufacturing capabilities. The signal to watch is the final scope and implementation timeline of Europe's ECHA PFAS restriction proposal.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Reducing environmental footprint enhances brand reputation and ensures compliance with evolving regulations. |
| R&D in PFAS-free Alternatives | Developing new materials addresses regulatory pressures and opens new high-value application segments. |
| Capacity Expansion for ePTFE | Meeting the increasing demand from medical device and advanced electronics sectors secures market share. |
| Strategic Partnerships with Medical OEMs | Collaborations ensure materials meet stringent biocompatibility and performance requirements for critical devices. |
| Certification Investment for Aerospace Grades | Achieving rigorous aerospace qualifications unlocks access to high-margin, long-lifecycle applications. |
Research Approach
Initial hypotheses were tested against primary input from PTFE manufacturers, medical device engineers, electronics R&D specialists, and regulatory compliance officers, then refined. This involved combining insights from direct interviews with secondary validation through industry association reports, company 10-K filings, and trade statistics. A bottom-up approach to market sizing was triangulated with top-down validation from macro-economic indicators.
Variance decomposition informed the analytical framework, modeling market dynamics across the analysis window. Segmentation dimensions included product type, form, application, end-user industry, and regional regulatory impact. Compound annual growth rates were derived through a combination of historical trend analysis and projected shifts in market share. Key industry-specific forecast inputs included fluorspar price volatility and evolving PFAS regulatory timelines.
Material uncertainties — unforeseen regulatory bans or rapid material substitution breakthroughs — sit outside the modeled envelope, reflecting the inherent unpredictability of the market. Forecasts reflect assumptions regarding technological development and geopolitical stability. Practitioners should keep alternative scenarios live as global trade policies and environmental regulations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Calendering Resins Market
Polymers & Resins
Global Polyolefin Powders Market
Polymers & Resins
Bio-Based PU Market
Polymers & Resins
Low Density Polyethylene Market
Polymers & Resins
Polymer Modifiers Market
Polymers & Resins
Global Hydroxypropyl Cellulose Market
Polymers & Resins
Global Polyethylene Market
Polymers & Resins
Global Synthetic Polymers Market
Polymers & Resins
North America Super Absorbent Polymers (SAP) Market
Polymers & Resins
Ethylene Vinyl Acetate (EVA) Market
Polymers & Resins
Biopolymer Tubes Market
Polymers & Resins
Water Dispersible Polymers Market
Polymers & Resins
North America Fluoropolymer Market
Polymers & Resins
Silicon Anode Binder Polymers for Lithium-Ion Batteries Market
Polymers & Resins
Bio-Based Emulsion Polymers Market
Polymers & Resins
Sustainable Polymers Market