
 Bismaleimide Market | 2026-2036
Bismaleimide Market Size, Share, and Industry Trends Forecast 2026-2036
Bismaleimide Market Analytics
Aftermarket service revenue for composite repair and resin re-certification is reshaping margin distribution across the value chain. Evonik Industries leverages its backward integration into methylene dianiline feedstocks to sustain pricing power in specialty resin grades. Hexcel Corporation anchors North American aerospace demand through long-term supply agreements with tier-one laminators. Huntsman International competes on formulation breadth, offering customized bismaleimide blends for electronics and defense applications.
Bismaleimide denotes a class of thermosetting polyimides synthesized from maleic anhydride and aromatic diamines, typically curing at 180–250°C to yield glass transition temperatures exceeding 250°C and service temperatures up to 230°C in continuous operation. These properties make the material indispensable for structural composites, high-density printed circuit boards, and adhesive joints where thermal stability and dimensional integrity under load are non-negotiable. Prepreg formulations dominate value capture in aerospace programs, while liquid resins represent the fastest-growing format as automotive under-the-hood applications multiply. Composite forms command premium pricing relative to coatings and sealants due to qualification timelines and certification stickiness with OEMs.
REACH registration requirements in Europe and EPA TSCA Section 5 premanufacture notifications in the United States impose rigorous substance identity and hazard communication obligations on bismaleimide importers and formulators. China's GB standards for hazardous chemicals and SAMR product quality supervision add compliance layers for market access. The convergence of aviation emissions targets and electronics miniaturization trends will intensify scrutiny of cure chemistry efficiency and volatile organic compound profiles. Stakeholders must weigh qualification-investment horizons against the accelerating substitution threat from benzoxazine and cyanate ester chemistries in select temperature regimes.
Market Dynamics
Aerospace OEMs are consolidating resin specifications around high-temperature thermosets as next-generation airframe programs demand longer service intervals and lighter structural weight, compressing qualification timelines for alternative chemistries.
Growth Catalysts
- Aviation decarbonization mandates:FAA and EASA emissions targets are accelerating composite adoption in engine nacelles and thrust reversers, driving specification lock-in for BMI systems qualified above 200°C.
- Wind blade scale-up:Chinese manufacturers are building captive prepreg capacity for 120-meter-plus rotor designs that require thermoset stability under centrifugal load.
- 5G infrastructure buildout:High-frequency printed circuit board laminators specify low-dielectric-loss BMI formulations for base station antenna substrates.
Market Restraints
- Aromatic diamine feedstock volatility:Methylene dianiline pricing swings constrain margin predictability for specialty resin grades.
- East Asian supply concentration:China and Japan control 70% of refined maleic anhydride capacity, creating geographic vulnerability for European and North American formulators.
- Cure temperature floor:Minimum 180°C processing requirements exclude BMI from automotive exterior panels where paint-line compatibility demands sub-150°C cycles.
Strategic Opportunities
- Indian defense aerospace:Hindustan Aeronautics Limited's indigenous fighter programs lack qualified domestic BMI sources, opening import substitution potential.
- Out-of-autoclave processing:Oven-curable BMI prepregs eliminate autoclave bottlenecks at tier-two laminators serving satellite and drone manufacturers.
- EU Green Deal chemistry incentives:ECHA fast-track registration for reduced-VOC cure systems rewards reformulation investment with accelerated market access.
Industry Challenges
- Composite repair technician scarcity:OEM-approved re-certification protocols require specialized training that outpaces vocational pipeline output.
- Dual-qualified inventory management:Suppliers must maintain parallel AS9100 and ISO 9001 traceability systems for aerospace and industrial customers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bismaleimide Market |
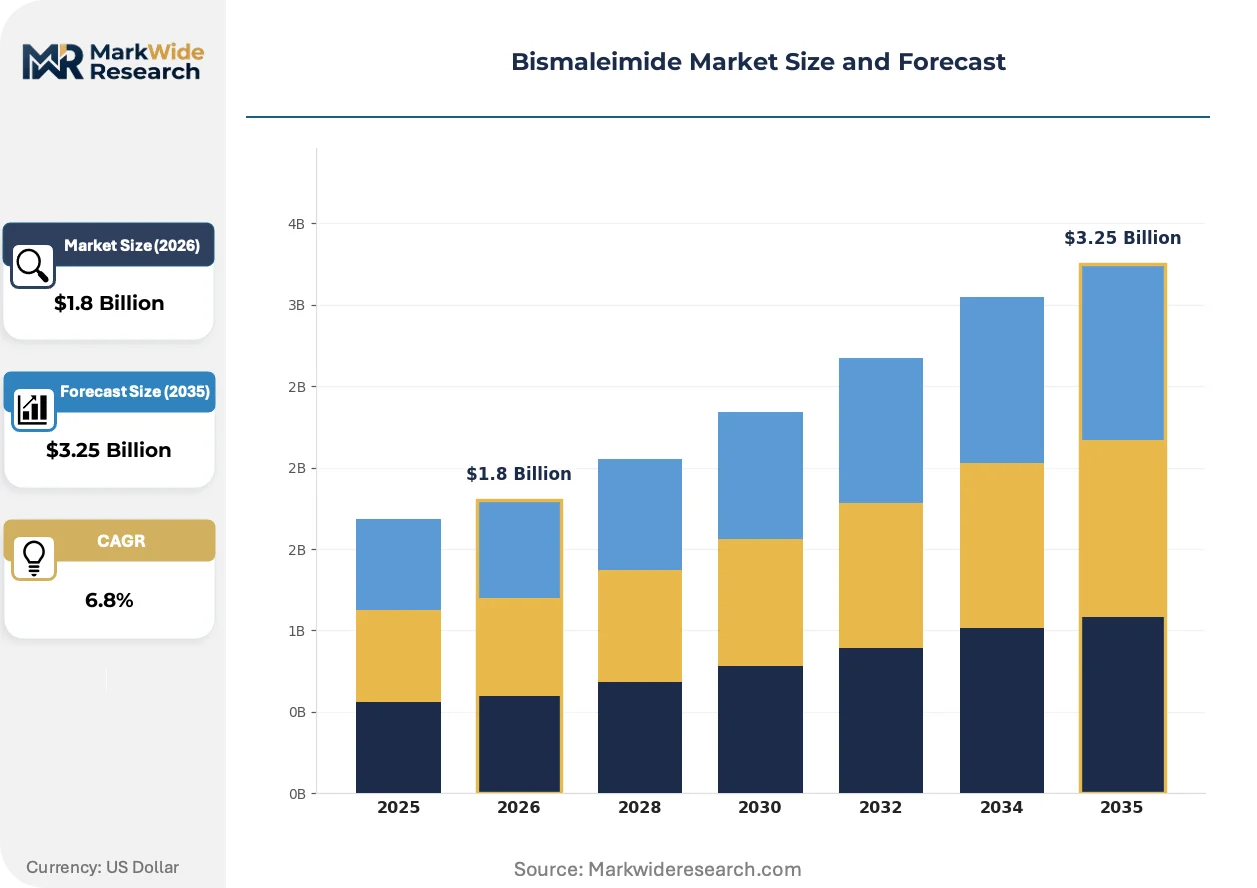
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid, Liquid, Prepreg, Resins End Use Industry: Aerospace, Electronics, Automotive, Telecommunications Form: Composite, Coating, Adhesive, Sealant Distribution Channel: Online, Direct Sales, Distributors, Retail |
| Companies Covered | Evonik Industries, Hexcel Corporation, Huntsman International, Solvay, Toray Industries, Mitsubishi Chemical Group, HOS-Technik, Renegade Materials Corporation, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bismaleimide Market Evolving Landscape
Thermoset chemistry is converging with out-of-autoclave processing methods and digital manufacturing controls, collapsing traditional barriers between aerospace qualification rigor and industrial scale economics.
Toughened BMI formulations is migrating from legacy autoclave-cured prepregs toward vacuum-bag-only processing protocols. Tier-two satellite structure manufacturers in Germany and California are adopting these systems to bypass autoclave capacity constraints. The shift is compressing capital requirements for new composite entrants and redistributing value capture from equipment suppliers toward resin formulators with process-control IP.
REACH authorization requirements for methylene dianiline are tightening substance volume thresholds and hazard communication obligations. European formulators face mandatory downstream user notification for aerospace adhesive applications. The regulation is forcing reformulation investment toward alternative aromatic diamines, with specialty resin producers in Switzerland and the Netherlands accelerating substitution R&D.
Buyers are unbundling resin supply from composite fabrication services, establishing direct procurement relationships with BMI formulators previously accessed through laminator intermediaries. Wind blade manufacturers in China and printed circuit board laminators in Taiwan are leading this disintermediation. The pattern concentrates price negotiation leverage with volume buyers and erodes traditional distributor margins in East Asian supply chains.
Bismaleimide Market Segmentation
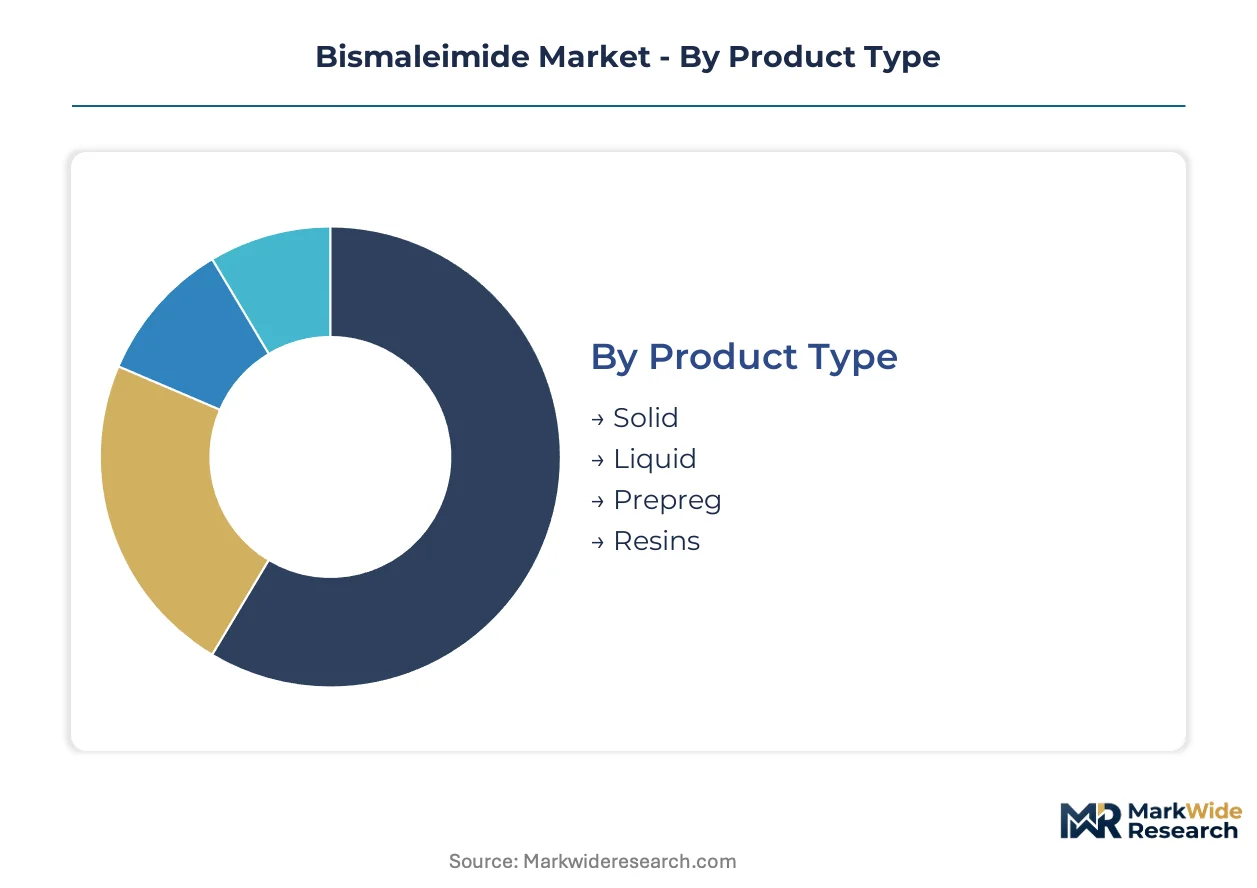
Bismaleimide procurement cycles vary dramatically across product formats, with aerospace prepregs demanding multi-year qualification timelines while liquid resins for automotive prototyping turn over in quarters. Understanding these velocity differentials helps suppliers align inventory strategies with cash flow requirements and customer lock-in durations.
Product Type:
Prepreg formulations command the longest production cycles due to freezer storage logistics and autoclave scheduling, whereas liquid resins move through formulation-to-delivery in weeks.
- Prepreg:Reinforced fiber sheets pre-impregnated with catalyzed BMI resin require continuous cold-chain logistics and frozen inventory management. Aerospace tier-one laminators in Germany and California maintain 18-24 month qualification buffers, creating sticky demand relationships that resist price erosion.
- Liquid:Uncatalyzed resin systems ship at ambient temperature and enable just-in-time procurement for electronics potting and automotive under-hood prototyping. Taiwanese printed circuit board manufacturers are expanding direct procurement relationships with formulators, bypassing traditional distributor markups.
- Solid:Powder and pellet formats serve compression molding operations for high-temperature insulators and specialty aerospace brackets.
- Resins:Base polymer intermediates supply captive compounding operations at wind blade manufacturers building in-house prepreg capacity.
Prepreg anchors the volume base while liquid resins gain share at the steepest rate.
End Use Industry:
Margin structures diverge sharply across customer verticals, with aerospace programs absorbing premium pricing for certified grades while automotive buyers drive commoditization pressures.
- Aerospace:Structural airframe and engine nacelle applications demand AS9100-traceable supply chains with batch-level resin re-certification protocols. FAA and EASA emissions mandates are accelerating composite adoption in thrust reversers, locking in BMI specifications above 200°C service thresholds.
- Electronics:High-frequency printed circuit board laminators specify low-dielectric-loss formulations for 5G base station antenna substrates. The segment rewards rapid formulation iteration over long-term qualification investment.
- Automotive:Under-hood applications in electric vehicle inverters and battery enclosures face paint-line compatibility constraints that exclude standard BMI cure cycles.
- Telecommunications:Fiber optic cable strength members and connector housings require moisture-resistant grades with simplified processing windows.
Aerospace commands the highest absolute margins while electronics delivers the most rapid volume expansion trajectory.
Form:
Composite forms concentrate value capture through qualification stickiness, whereas coatings and sealants compete on formulation flexibility and delivery speed.
- Composite:Fiber-reinforced structural laminates for satellite bus structures and fighter airframes carry 3-5 year OEM approval timelines that insulate incumbent suppliers from substitution threats. Out-of-autoclave processing variants are redistributing value from equipment suppliers toward resin formulators with process-control intellectual property.
- Adhesive:Film and paste formats for metal-to-composite bonding in engine assemblies face REACH authorization pressure on methylene dianiline content, forcing European formulators toward alternative aromatic diamine R&D.
- Coating:Powder and liquid protective layers for industrial tooling prioritize VOC compliance and rapid cure over thermal ceiling performance.
- Sealant:Gap-filling compounds for electronics enclosures and aerospace fuel tanks compete on thixotropic control and dispensing automation compatibility.
Composite forms dominate revenue concentration while adhesive applications face the most intense regulatory reformulation pressure.
Distribution Channel:
Channel selection reflects buyer scale and technical sophistication, with volume consumers disintermediating traditional supply chains while smaller accounts rely on technical service bundling.
- Direct Sales:Large aerospace OEMs and Chinese wind blade manufacturers negotiate multi-year supply agreements with formulators, capturing price transparency and technical collaboration that distributor relationships cannot match. Hindustan Aeronautics Limited's indigenous fighter programs exemplify import-substitution opportunities accessible only through direct technical engagement.
- Distributors:Regional chemical distributors serve mid-tier electronics laminators and automotive tier-two suppliers with formulation blending and just-in-time delivery services.
- Online:E-procurement platforms capture spot demand for R&D quantities and maintenance-repair-operations volumes in industrial segments with lower certification requirements.
- Retail:Limited to specialty adhesives and small-format resins for academic and prototype applications.
Direct sales channels capture the highest absolute volumes while online platforms expand most quickly in R&D and spot-buying segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes bismaleimide primarily for wind blade and circuit board manufacturing, while the United States and Germany concentrate demand in aerospace qualification programs with multi-year certification horizons.
China
Domestic wind blade manufacturers are building captive prepreg capacity for 120-meter-plus rotor designs requiring thermoset stability under centrifugal load. GB standards for hazardous chemicals and SAMR product quality supervision add compliance layers for market access. Yangtze River Delta clusters around Shanghai host the fastest-growing circuit board laminator base specifying low-dielectric-loss BMI formulations.
United States
FAA emissions mandates accelerate composite adoption in engine nacelles and thrust reversers, locking in BMI specifications above 200°C service thresholds. EPA TSCA Section 5 premanufacture notifications impose rigorous substance identity obligations on importers and formulators. California satellite structure manufacturers adopt out-of-autoclave processing variants to bypass equipment bottlenecks.
Germany
REACH authorization requirements for methylene dianiline tighten substance volume thresholds and hazard communication obligations on aerospace adhesive applications. ECHA fast-track registration for reduced-VOC cure systems rewards reformulation investment with accelerated market access. Bavarian tier-two satellite manufacturers lead European adoption of vacuum-bag-only BMI processing protocols.
India
Hindustan Aeronautics Limited's indigenous fighter programs lack qualified domestic BMI sources, opening import substitution potential for direct technical engagement. BIS certification requirements and DGFT import regulations shape procurement pathways for defense aerospace materials. Karnataka and Maharashtra defense manufacturing corridors represent concentrated demand nodes for high-temperature thermoset qualification.
Japan
METI industrial policy supports advanced materials R&D for next-generation airframe programs demanding longer service intervals and lighter structural weight. JIS standards govern quality benchmarks for electronics and aerospace resin applications. Nagoya aerospace manufacturing clusters maintain stringent supplier qualification protocols that compress substitution timelines for alternative chemistries.
Bismaleimide Market Competitive Landscape
Capability concentration sits with specialty resin formulators possessing process-control intellectual property; scale advantage sits with diversified chemical conglomerates commanding backward integration into aromatic diamine feedstocks. The vendor base stratifies across three tiers: integrated petrochemical majors with captive raw material access, mid-cap formulation specialists with aerospace qualification track records, and regional distributors serving spot-demand electronics laminators. Dominant competitive moves include capacity expansion in East Asian prepreg operations and technology licensing agreements for out-of-autoclave cure systems.
Within the specialty formulation tier, Evonik Industries and Hexcel Corporation exemplify divergent strategic positioning. Evonik leverages its German chemical heritage and feedstock integration to sustain pricing power in certification-intensive aerospace grades. Hexcel anchors North American demand through long-term supply relationships with tier-one laminators in California and Germany. Huntsman International occupies a position bridging formulation breadth and geographic diversification, with its US-incorporated structure supporting customized blend capabilities for defense and electronics verticals.
| Leading Market Players |
|---|
| Evonik Industries |
| Hexcel Corporation |
| Huntsman International |
| Solvay |
| Toray Industries |
| Mitsubishi Chemical Group |
| HOS-Technik |
| Renegade Materials Corporation |
| 3M |
| Others |
Value Network & Pricing Analysis
Yangtze River Delta port congestion amplifies freight cost volatility for bismaleimide resin shipments moving between Chinese maleic anhydride refiners and European formulators. This logistics corridor's cost dynamics concentrate pricing power with backward-integrated suppliers commanding captive aromatic diamine feedstocks, while downstream buyers face tiered cost absorption across aerospace certification grades versus industrial commodity tiers.
Pricing Analysis
Long-term offtake contracts dominate aerospace procurement, locking in volume commitments across 18-24 month qualification buffers that insulate premium grades from spot-market volatility. Price differentiation separates AS9100-traceable aerospace prepregs from industrial liquid resins, with certification stickiness and freezer-chain logistics commanding substantial premia. Cost compression in electronics-grade liquid resins intensifies as Taiwanese printed circuit board manufacturers consolidate direct procurement relationships. Wind blade manufacturers in China exhibit the highest price sensitivity, while German tier-one satellite laminators absorb premium pricing for out-of-autoclave qualification status.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk assessment for North American formulators dependent on East Asian maleic anhydride feedstocks. Manufacturing gravity centers on China, Japan, and Germany, with the former pair controlling refined maleic anhydride capacity and the latter anchoring European formulation expertise. Raw material dependencies rest on methylene dianiline, maleic anhydride, and specialized toughening agents. Single-source vulnerability concentrates in aromatic diamine supply for REACH-compliant European adhesive grades. Distribution runs through direct sales channels for volume aerospace OEMs and wind blade manufacturers, with regional chemical distributors serving mid-tier electronics and automotive accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified resin formulators possessing process-control intellectual property for out-of-autoclave cure systems represent the scarcest capability layer in this market. The gap between aerospace qualification rigor and industrial scale economics creates strategic leverage for specialists bridging both domains.
For Market Incumbents: Entrench certification lock-in by extending long-term supply agreements with tier-one laminators in California and Bavaria, compressing substitution windows for benzoxazine and cyanate ester alternatives. Prioritize backward integration into methylene dianiline feedstocks to defend margin position against aromatic diamine price volatility. Accelerate reformulation R&D toward alternative aromatic diamines ahead of REACH authorization tightening.
For New Entrants and Emerging Players: Build out out-of-autoclave processing capabilities targeting tier-two satellite and drone manufacturers in Germany and California, bypassing autoclave capacity constraints that bottleneck incumbent suppliers. Indian defense aerospace presents the most penetrable geography, with Hindustan Aeronautics Limited's indigenous fighter programs lacking qualified domestic BMI sources. Establish direct technical engagement teams capable of navigating BIS certification and DGFT import regulations.
For Investors and Strategic Acquirers: Mid-cap formulation specialists with aerospace qualification track records and captive prepreg capacity represent the highest-conviction acquisition archetype. Long-term viability hinges on differentiation durability against thermoset substitution threats across the next decade. Monitor benzoxazine qualification momentum in 180-200°C service temperature regimes as the critical inflection signal for BMI demand erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aromatic Diamines | Evonik Industries leverages captive methylene dianiline supply to sustain pricing power in specialty grades. |
| Out-of-Autoclave Process Development | Tier-two satellite manufacturers in Bavaria adopt vacuum-bag-only protocols to bypass equipment bottlenecks. |
| Long-term Supply Agreement Expansion | Hexcel Corporation anchors North American aerospace demand through multi-year contracts with California laminators. |
| Alternative Diamine Reformulation R&D | Swiss and Dutch specialty resin producers accelerate substitution research ahead of REACH authorization thresholds. |
| Direct Procurement Relationship Building | Taiwanese printed circuit board manufacturers bypass distributor markups through formulator-direct engagement. |
Research Methodology
A standing panel of resin formulators, aerospace tier-one laminators, electronics procurement leads, and wind blade manufacturing engineers provided ongoing calibration across the research cycle. Primary interviews with plant managers at Chinese prepreg operations, technical R&D directors at European specialty chemical firms, and distribution channel partners in East Asian supply chains combined with secondary validation from customs and trade data, ACC and Cefic industry reports, and SEC 10-K filings from publicly traded composite material suppliers. Bottom-up volume estimates triangulated against top-down market sizing from identified end-use applications.
Scenario bracketing anchored the analytical framework across the projection horizon, with demand trajectories modeled by product format, end-use industry vertical, geographic production hub, and certification tier. Segmentation dimensions included prepreg versus liquid versus solid resin formats, aerospace versus electronics versus automotive versus telecommunications end-uses, and composite versus adhesive versus coating versus sealant forms. CAGRs derived from fitted growth curves applied to baseline volume estimates, with inputs from aviation emissions mandate implementation timelines and 5G infrastructure deployment schedules.
Sensitivities concentrate around benzoxazine substitution velocity, REACH authorization enforcement intensity for methylene dianiline, and Chinese wind blade manufacturer captive capacity buildout rates. Forecasts reflect documented assumptions regarding qualification timeline compression and regulatory reformulation investment cycles. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Sugarcane Wax Market
Specialty Chemicals
Marine Hyaluronic Acid Market
Specialty Chemicals
Alkylene Carbonates Market
Specialty Chemicals
CMIT/MIT Market
Specialty Chemicals
Fe EDDHA Market
Specialty Chemicals
2-(2,2,2-Trifluoroethoxy)-1,3,2-Dioxaphospholane-2-Oxide Market
Specialty Chemicals
Niacin and Niacinamide Market
Specialty Chemicals
Spiroglycol Market
Specialty Chemicals
Ursolic Acid Market
Specialty Chemicals
Acesulfame K Market
Specialty Chemicals
Natural Ingredient Insect Repellent Market
Specialty Chemicals
Solanesol Market
Specialty Chemicals
Barium Sulfate Market
Specialty Chemicals
Phenoxycycloposphazene Market
Specialty Chemicals
Bio-Based Phenol Market
Specialty Chemicals
Natural Insect Repellent Market