
 Global Vapor Permeability Films Market | 2026-2036
Global Vapor Permeability Films Market Size, Share, and Industry Trends Forecast 2026-2036
Global Vapor Permeability Films Market Foresight
Medical packaging distribution is rewriting procurement relationships across the vapor permeability films sector. Mitsui Chemicals leverages its polymer science depth to anchor Asian supply chains for sterile medical barriers. Toray Industries sustains technology leadership through microporous membrane specialization. RKW competes on manufacturing scale across European hygiene and healthcare film segments.
Global vapor permeability films are engineered polymeric barriers with controlled moisture transmission rates, typically measured in grams per square meter per day, designed to prevent liquid water ingress while permitting gas exchange. Microporous polyethylene films dominate food packaging applications where breathability extends produce shelf life, while monolithic ethylene vinyl alcohol structures command premium positioning in pharmaceutical blister packs due to their precise barrier tunability. Construction membrane applications represent the fastest-growing technology segment as building codes tighten energy efficiency requirements across temperate climates.
FDA medical device regulations and EPA chemical safety frameworks in the United States, alongside REACH substance restrictions in Europe, collectively elevate compliance costs while screening out lower-grade film suppliers. ISO 11607 sterilization validation standards further constrain market access for non-certified manufacturers. Stakeholders must monitor evolving ECHA substance evaluations and anticipate how emerging state-level building efficiency codes in California and New York will reshape specification requirements for construction membrane grades.
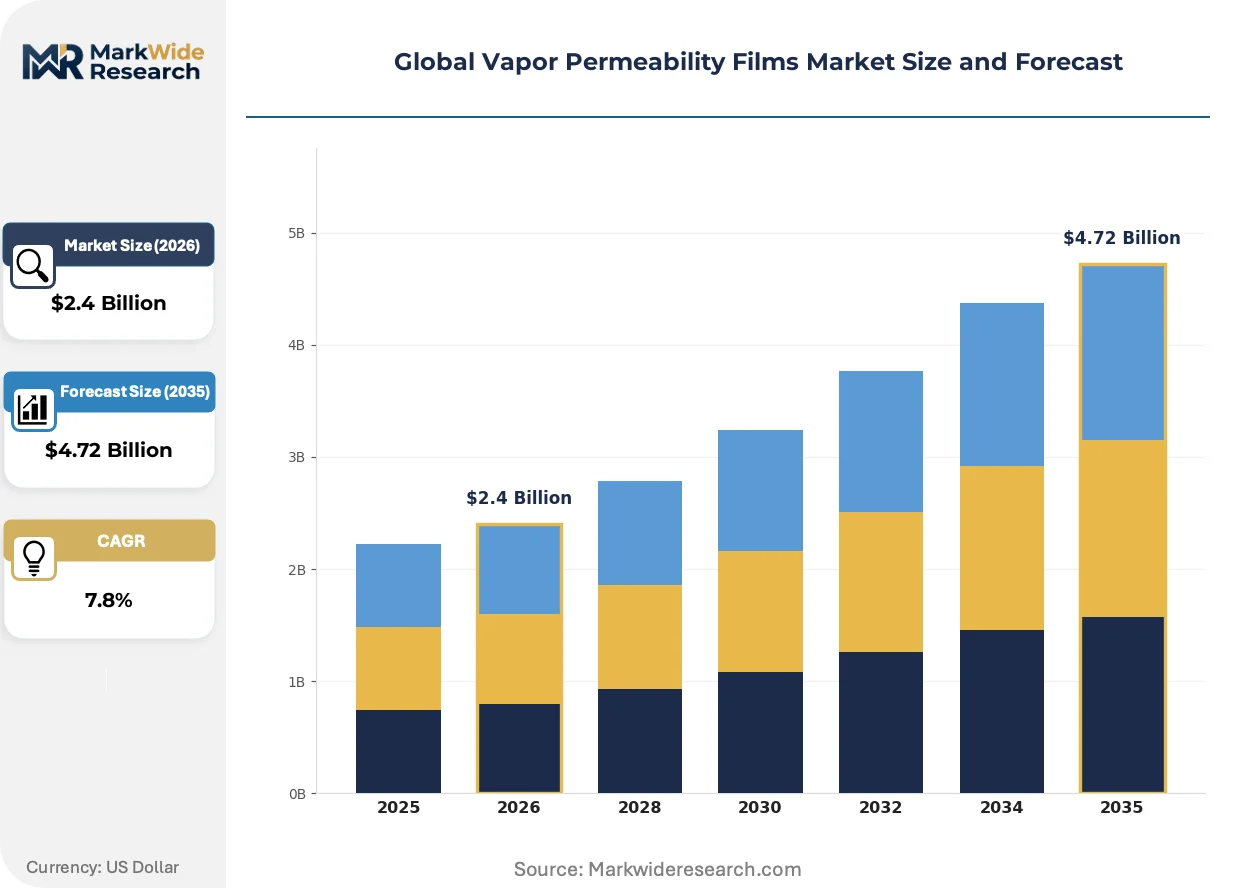
Market Dynamics
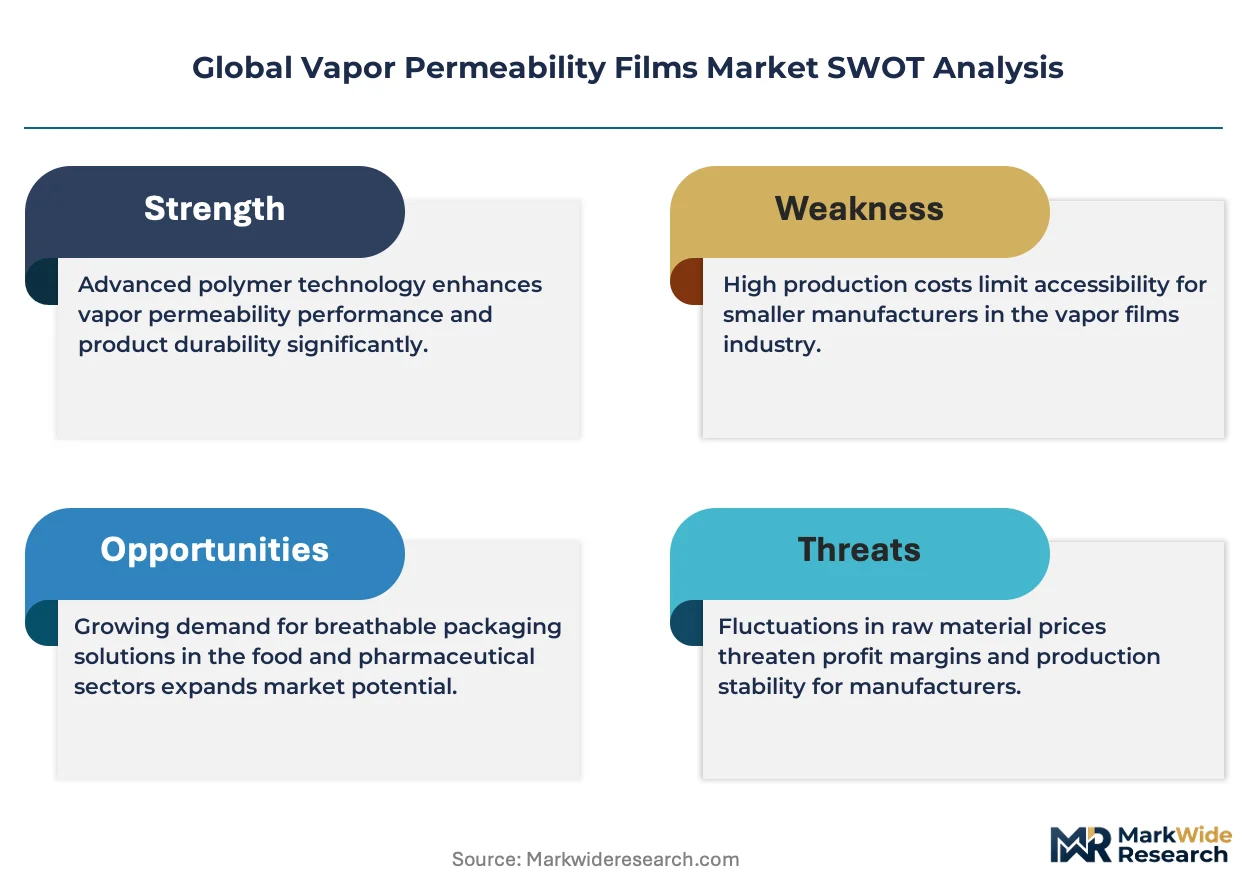
REACH substance evaluations and evolving EPA chemical safety frameworks are compressing supplier margins while simultaneously filtering out uncertified competitors, concentrating procurement relationships among ISO 11607-validated manufacturers.
Growth Catalysts
- Medical packaging sterilization mandates:ISO 11607 validation requirements for sterile barrier systems are accelerating specification upgrades across pharmaceutical blister pack applications.
- California Title 24 building codes:Tightened energy efficiency standards for envelope assemblies are mandating breathable membrane specifications in residential construction.
- Microporous polyethylene breathability:Extended produce shelf-life requirements in fresh food logistics are pulling film adoption through controlled atmosphere packaging.
Market Restraints
- Ethylene vinyl alcohol feedstock volatility:Petrochemical input cost swings compress margin predictability for monolithic barrier film grades.
- German manufacturing cluster concentration:Continental European supply hinges on Rhineland-Palatinate and Bavaria production nodes, amplifying geographic risk exposure.
- Fluorinated polymer substitution pressure:Per- and polyfluoroalkyl substance restrictions under REACH Annex XVII are forcing material transitions with performance trade-offs.
Strategic Opportunities
- India pharmaceutical packaging underpenetration:CDSCO regulatory alignment with international standards is opening sterile barrier specification upgrades for domestic generic drug exporters.
- Construction membrane retrofit demand:Building efficiency renovation mandates across New York State are creating specification windows for vapor-open exterior insulation systems.
- Bio-based polymer convergence:Polylactic acid and polyhydroxyalkanoate process integration is hybridizing with conventional extrusion lines for compostable breathable film grades.
Industry Challenges
- Multilayer coextrusion technician scarcity:Specialized die design and rheology expertise gaps constrain capacity expansion timelines for precision barrier film lines.
- ISO 11607 validation timeline compression:Sterilization qualification protocols for new film constructions extend product development cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Vapor Permeability Films Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.72 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Nylon, Polyester, Polyvinylidene Chloride, Ethylene Vinyl Alcohol Technology: Microporous, Monolithic, Porous Composite, Nanoporous, Extrusion Coating, Lamination Application: Food Packaging, Electronics Encapsulation, Medical Packaging, Construction Membranes, Protective Apparel, Agriculture Films End User Industry: Consumer Goods Manufacturers, Electronics Manufacturers, Pharmaceutical Companies, Building Material Suppliers, Agricultural Enterprises, Textile Producers |
| Companies Covered | Clopay Plastic Products, Mitsui Chemicals, RKW, Toray Industries, American Polyfilm, Arkema, Celanese, Covestro, Fatra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Vapor Permeability Films Market Shifts & Advancements
Material science convergence with regulatory chemistry is rewriting performance specifications across breathable barrier applications, compressing traditional polymer categories into multifunctional film architectures.
Monolithic ethylene vinyl alcohol copolymers with nanoscale dispersion layers are achieving oxygen transmission rates below 0.1 cc/m²/day while maintaining moisture vapor transmission above 500 g/m²/day. Pharmaceutical cold chain packaging engineers at temperature-sensitive biologics distributors are specifying these grades for 2-8°C stability windows. The technology is hybridizing gas barrier and breathability functions previously served by separate film laminations, collapsing bill-of-material complexity for sterile barrier designers.
REACH Annex XVII per- and polyfluoroalkyl substance restrictions are eliminating long-chain fluorinated polymer options from European medical and food contact applications by 2026. Film compounders are reformulating with short-chain fluorinated alternatives and silicone-based surface treatments, though moisture resistance coefficients degrade by 15-30 percent. German hygiene product manufacturers are absorbing reformulation costs while pushing specification changes downstream to private-label distributors.
Hospital procurement consortiums are consolidating sterile barrier film specifications into framework agreements with validated manufacturers, displacing spot-market purchasing for surgical kit components. Group purchasing organizations in the United States are mandating ISO 11607 third-party certification as a baseline qualification, compressing vendor pools to single-digit approved suppliers per category. This concentration is most visible in cardiovascular device packaging, where original equipment manufacturers now require direct mill relationships rather than distributor intermediation.
Global Vapor Permeability Films Market Segmentation
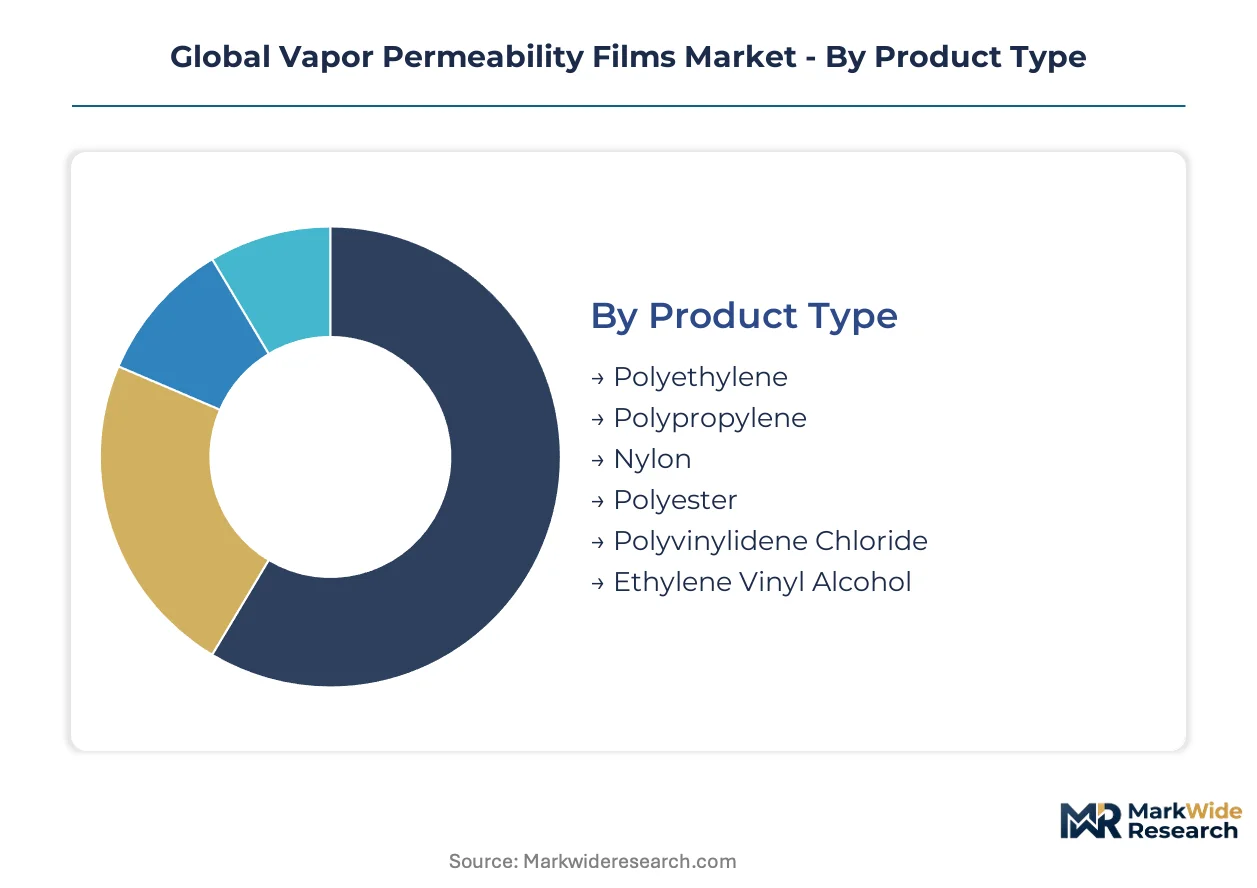
Vapor permeability films exhibit divergent specification requirements across polymer chemistry, manufacturing process, and end-use performance thresholds. Segmentation reveals where material science investments concentrate versus where commoditization pressures dominate procurement relationships.
Product Type:
Cost tier stratification separates commodity polyolefins from engineered barrier polymers with tunable transmission properties.
- Polyethylene:Microporous structures dominate fresh produce packaging through controlled atmosphere breathability. German retail chains specify these grades for extended shelf-life logistics across continental European distribution networks.
- Ethylene Vinyl Alcohol:Oxygen barrier precision below 0.1 cc/m²/day commands pharmaceutical blister pack specifications. Cold chain biologics distributors in the United States mandate these copolymers for 2-8°C stability windows per FDA medical device regulations.
- Polypropylene:Oriented film structures serve hygiene product backsheet applications with moisture management balance.
- Nylon:High-temperature resistance suits industrial protective apparel lamination requirements.
- Polyester:Optical clarity and dimensional stability anchor electronics encapsulation films.
- Polyvinylidene Chloride:High-barrier performance persists in legacy food packaging despite substitution pressures from REACH-compliant alternatives.
Polyethylene commands the established base. The steepest expansion runs through Ethylene Vinyl Alcohol.
Technology:
Manufacturing process selection determines whether films achieve breathability through physical porosity or molecular structure engineering.
- Microporous:Stretched polyolefin matrices create tortuous paths for moisture vapor while blocking liquid water. California Title 24 building codes now mandate these specifications for residential envelope assemblies.
- Monolithic:Continuous polymer phases transmit vapor through molecular diffusion without discrete pores. Pharmaceutical packaging engineers specify these for sterile barrier integrity under ISO 11607 validation protocols.
- Porous Composite:Hybrid architectures combine substrate support with functional coating layers.
- Nanoporous:Sub-100nm pore structures enable selective gas separation in emerging electronics applications.
- Extrusion Coating:Inline deposition of breathable layers onto woven or nonwoven substrates.
- Lamination:Adhesive bonding of dissimilar films to engineer composite barrier properties.
Monolithic technology anchors pharmaceutical certification requirements. Microporous formats are climbing the fastest through construction membrane adoption.
Application:
End-use performance thresholds range from food safety compliance to sterile medical barrier validation to building envelope energy codes.
- Medical Packaging:Sterile barrier systems require ISO 11607 third-party certification as baseline qualification. United States hospital procurement consortiums now mandate direct mill relationships, compressing approved supplier pools to single-digit counts per category.
- Construction Membranes:Vapor-open exterior insulation specifications are expanding most quickly. New York State renovation mandates and California Title 24 codes collectively reshape specification requirements for breathable envelope assemblies.
- Food Packaging:Controlled atmosphere packaging extends produce shelf-life through tuned moisture transmission rates.
- Electronics Encapsulation:Moisture protection without thermal trapping suits portable device reliability requirements.
- Protective Apparel:Breathable barriers balance chemical resistance with wearer comfort in industrial settings.
- Agriculture Films:Greenhouse climate management through humidity regulation drives specification.
Food Packaging retains volume leadership. Construction Membranes show the steepest upward trajectory from regulatory mandate acceleration.
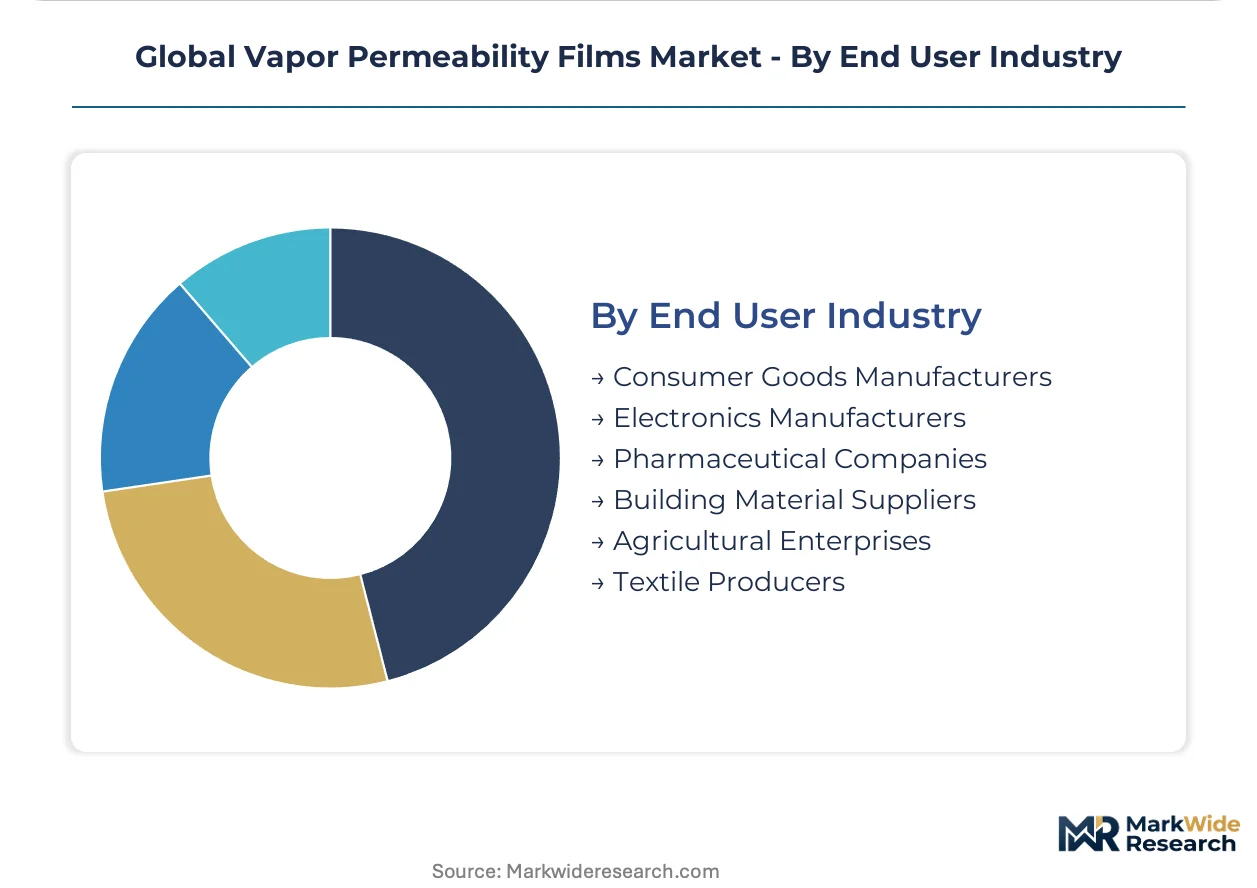
End User Industry:
Customer procurement sophistication ranges from framework agreement consolidation to spot-market commodity purchasing.
- Pharmaceutical Companies:Sterile barrier validation requirements elevate supplier qualification thresholds. CDSCO regulatory alignment in India is opening specification upgrades for domestic generic drug exporters targeting international markets.
- Building Material Suppliers:Code compliance documentation requirements differentiate specification sources. German manufacturing clusters serve continental European buyers with validated performance data for envelope assembly certifications.
- Consumer Goods Manufacturers:Private-label distributors absorb reformulation costs from REACH Annex XVII fluorinated polymer restrictions.
- Electronics Manufacturers:Miniaturization trends demand thinner films with maintained barrier performance.
- Agricultural Enterprises:Climate-controlled growing operations specify films for yield optimization.
- Textile Producers:Lamination partners for functional apparel applications.
Pharmaceutical Companies anchor premium pricing through certification barriers. Building Material Suppliers are gaining share fastest from efficiency code expansion across multiple jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's polymer logistics hub channels raw material flows to Rhineland-Palatinate film extrusion clusters, underwriting continental Europe's supply base for breathable barrier applications.
Germany
Medical packaging sterilization mandates from pharmaceutical exporters pull EVOH film specifications through Bavarian and Rhineland-Palatinate manufacturing nodes. REACH Annex XVII fluorinated polymer restrictions force compound reformulations with performance trade-offs. The Kaiserslautern industrial corridor concentrates microporous polyethylene capacity serving hygiene and healthcare segments.
United States
FDA medical device regulations and California Title 24 building codes simultaneously drive pharmaceutical blister pack upgrades and residential envelope membrane specifications. EPA chemical safety frameworks elevate compliance costs while filtering uncertified suppliers. The Gulf Coast petrochemical corridor feeds polymer inputs to Midwest extrusion operations.
China
Domestic pharmaceutical packaging expansion and construction membrane retrofit programs create dual demand vectors for breathable barrier films. NMPA regulatory alignment with ISO sterilization standards opens specification upgrades for export-oriented drug manufacturers. The Yangtze River Delta hosts integrated film-lamination complexes serving electronics encapsulation requirements.
India
CDSCO regulatory harmonization with international standards enables domestic generic drug exporters to qualify for sterile barrier specifications. Building efficiency code adoption in commercial construction creates emerging demand for vapor-open envelope systems. Maharashtra's chemical processing belt anchors multilayer coextrusion capacity expansion.
Japan
PMDA pharmaceutical packaging standards and METI building energy efficiency guidelines shape premium film specifications for domestic and export markets. Miniaturization trends in electronics packaging demand thinner films with maintained barrier performance. The Chubu region around Nagoya concentrates precision film manufacturing for automotive and electronics applications.
Global Vapor Permeability Films Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with polymer science depth and process-specific expertise. The supplier base concentrates among ISO 11607-validated manufacturers with direct mill relationships to hospital procurement consortiums. Three archetypes dominate: integrated chemical conglomerates with captive polymer feedstocks, specialized film extruders with validated sterile barrier lines, and regional hygiene product suppliers with private-label distribution networks. Competitive moves center on capacity expansion for multilayer coextrusion lines and strategic partnerships with pharmaceutical original equipment manufacturers.
Within the integrated chemical tier, Mitsui Chemicals and Toray Industries exemplify polymer science depth anchoring Asian supply chains for medical and industrial applications. RKW occupies a position among European-scale extruders serving hygiene and healthcare segments with validated manufacturing footprints. These three entities represent the concentration pattern where certification barriers and direct procurement relationships compress vendor pools to single-digit approved suppliers per category.
| Leading Market Players |
|---|
| Clopay Plastic Products |
| Mitsui Chemicals |
| RKW |
| Toray Industries |
| American Polyfilm |
| Arkema |
| Celanese |
| Covestro |
| Fatra |
| Others |
Supply & Pricing Matrix
Rhineland-Palatinate film extrusion clusters anchor continental European supply, concentrating capacity among ISO 11607-validated manufacturers who command premium positioning in pharmaceutical procurement channels. This geographic consolidation amplifies pricing leverage for sterile barrier grades while compressing margin buffers for non-certified competitors serving spot-market hygiene segments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ISO 11607-certified pharmaceutical grades from validated industrial films and commodity polyolefin backsheet materials. Certification tier and volume scale drive price differentiation, with hospital procurement consortiums extracting double-digit discounts through framework agreements. Pricing pressure stems from ethylene vinyl alcohol feedstock volatility and REACH-driven reformulation costs. Hygiene product distributors exhibit highest price sensitivity; cold chain biologics manufacturers prioritize barrier performance over unit economics.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from German manufacturing clusters support working capital for multilayer coextrusion capacity expansion. Germany, China, and the United States concentrate production of precision barrier films. Feedstock draws from Gulf Coast petrochemical corridors and Rotterdam polymer logistics hubs. Single-source vulnerability runs through Bavarian EVOH compounders serving pharmaceutical blister pack specifications. Distribution runs through direct mill relationships mandated by United States hospital group purchasing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through hospital procurement consortium consolidation, compressing approved supplier pools to single-digit counts per sterile barrier category and elevating qualification barriers for new market participants.
For Market Incumbents: Entrench certification advantages by accelerating ISO 11607 validation for next-generation monolithic EVOH constructions, countering fluorinated polymer substitution pressure under REACH Annex XVII. Deepen backward integration into polymer feedstock through Rhineland-Palatinate capacity expansion, defending margin position against ethylene vinyl alcohol cost volatility. Prioritize direct mill relationships with cardiovascular device original equipment manufacturers to lock out distributor intermediation. For New Entrants and Emerging Players: India's underpenetrated pharmaceutical packaging segment offers fertile ground for sterile barrier specification upgrades as CDSCO regulatory alignment accelerates. Target Maharashtra chemical processing belt for multilayer coextrusion capacity partnerships, leveraging domestic generic drug export growth. Enter through construction membrane retrofit demand in New York State and California, where building efficiency codes outpace established supplier response capacity. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-moat play because certification barriers and sterilization validation timelines protect incumbent returns while filtering speculative capital. Acquisition focus should center on mid-scale European extruders with validated sterile barrier lines and dormant multilayer capacity ripe for pharmaceutical qualification. Watch for ECHA substance evaluation announcements as inflection indicators for forced material transitions and consolidation catalysts.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Bavarian multilayer coextrusion lines address pharmaceutical backlog from ISO 11607 validation bottlenecks. |
| Backward Integration | Captive ethylene vinyl alcohol supply insulates margin compression from petrochemical input volatility. |
| Long-term Supply Agreement | Framework contracts with United States hospital procurement consortiums lock revenue visibility. |
| Joint Venture | Maharashtra partnerships accelerate India pharmaceutical packaging qualification for export markets. |
| Green Manufacturing Transition | Polylactic acid process integration captures compostable film premiums under evolving EPA guidelines. |
Research Methodology
Initial hypotheses were tested against primary input from sterile barrier engineers, pharmaceutical packaging procurement managers, multilayer coextrusion plant operators, and construction membrane specification consultants, then refined through secondary validation. Bottom-up demand modeling triangulated with top-down supply capacity assessments. Secondary sources included FDA medical device registration databases, ECHA substance evaluation dossiers, REACH Annex XVII restriction updates, ISO 11607 certification registries, and German chemical industry association trade flow data.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled by polymer chemistry, manufacturing technology, application performance tier, and end-user procurement sophistication. CAGRs derived from installed capacity expansion timelines, regulatory mandate acceleration curves, and substitution elasticity estimates for fluorinated polymer transitions. Forecast inputs incorporated California Title 24 code adoption rates and CDSCO regulatory harmonization progress.
The forecast holds incumbent behavior within observed patterns; aggressive certification investment by Asian chemical conglomerates or accelerated REACH restriction timelines would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Membrane Materials
Industrial Solvent Separation Membranes Market
Membrane Materials
Global Membrane Technology Market
Membrane Materials
Bitumen Membrane Sheets Market
Membrane Materials
Polymer Electrolyte Membrane Fuel Cells (Pemfcs) Market
Membrane Materials
Global Ceramic Membrane Market
Membrane Materials
Specialty Breathable Membranes Market
Membrane Materials
Inorganic Ion Exchange Materials Market
Membrane Materials
Geosynthetic Clay Liner Market
Membrane Materials
Global Geomembrane Market
Membrane Materials
Middle East and Africa Ceramic Membranes Market
Membrane Materials
Vapor Barrier Films Market
Membrane Materials
Global Chemical Separation Membranes Market
Membrane Materials
Membrane Polymers Market
Membrane Materials
Ultrafiltration Membrane Market
Membrane Materials
Self-Adhered Roofing Membranes Market
Membrane Materials
Membrane Touch Switch Material Market