
 Ubiquinone Market | 2026-2036
Ubiquinone Market Size, Share, and Industry Trends Forecast 2026-2036
Ubiquinone Market Analysis
Pharmaceutical wholesale channels is rewriting access dynamics for ubiquinone APIs across Asia-Pacific markets. Kaneka Corporation leverages its Japanese fermentation heritage to sustain premium positioning in coenzyme Q10 supply. Kyowa Hakko Bio anchors global pharmaceutical-grade output through integrated bioprocessing facilities. Xiamen Kingdomway competes aggressively on volume, dominating powder exports to European supplement manufacturers.
Ubiquinone denotes a lipid-soluble benzoquinone compound, specifically coenzyme Q10, functioning as an essential electron carrier in mitochondrial ATP synthesis with a molecular formula of C59H90O4 and a melting point near 48-52°C; industrial production relies primarily on yeast fermentation or chemical synthesis for pharmaceutical and nutraceutical applications. Coenzyme Q10 commands the largest revenue share among product types due to decades of clinical validation and established consumer recognition, while ubiquinol gains traction as the reduced antioxidant form in premium formulations. Softgel delivery systems capture disproportionate margin pools in dietary supplements, whereas powder forms dominate bulk pharmaceutical procurement.
Japan's Ministry of Health, Labour and Welfare classifies coenzyme Q10 as a food ingredient with specific purity thresholds, while China's National Medical Products Administration enforces GMP standards for pharmaceutical-grade ubiquinone exports. The US FDA oversees dietary supplement labeling under DSHEA, creating compliance divergence that shapes regional product portfolios. Stakeholders must monitor evolving fermentation patent landscapes and bioidentical synthesis claims to protect positioning.
Market Dynamics
Fermentation-based bioprocessing innovations are compressing production costs while purity thresholds tighten across pharmaceutical-grade supply chains, forcing manufacturers to choose between volume scale and certification tier positioning.
Growth Catalysts
- Functional wellness spending:Dietary supplement manufacturers are expanding ubiquinone formulations as consumer expenditure on mitochondrial health and cardiovascular support products intensifies across North American and European retail channels.
- DSHEA labeling framework:The US FDA's dietary supplement regulations provide clearer market access pathways, reducing compliance friction for imported coenzyme Q10 raw materials entering US distribution networks.
- Yeast fermentation advances:Strain optimization and bioreactor automation are lifting yields while cutting solvent use, enabling producers to serve both nutraceutical and pharmaceutical purity grades from single facilities.
Market Restraints
- Raw material concentration:Isoprenoid precursor supply chains cluster with specific petrochemical and agricultural feedstock regions, exposing fermentation operations to input cost volatility and logistics bottlenecks.
- Pharmaceutical-grade certification barriers:GMP compliance timelines for active pharmaceutical ingredient status extend 18-36 months, freezing smaller fermentation facilities out of high-margin therapeutic applications.
- Chemical synthesis competition:Synthetic ubiquinone from solanesol and other terpenoid precursors maintains cost advantages at industrial scale, pressuring bioprocessing margins in commodity nutraceutical segments.
Strategic Opportunities
- Ubiquinol premium conversion:The reduced antioxidant form commands 40-60% price premiums over oxidized coenzyme Q10, creating margin expansion pathways for manufacturers with hydrogenation and stabilization capabilities.
- Softgel delivery innovation:Lipid-based encapsulation technologies are opening functional food and beverage applications previously inaccessible to crystalline powder formulations.
- China NMPA pharmaceutical registration:Domestic manufacturers leveraging fermentation scale can capture import substitution benefits as China's national medical products administration tightens oversight of dietary supplement and API quality.
Industry Challenges
- Fermentation scale-up expertise:Industrial microbiology talent capable of optimizing high-cell-density yeast cultures for ubiquinone yields remains concentrated with legacy Japanese and European producers, constraining new facility ramp rates.
- Patent landscape navigation:Strain engineering and downstream processing IP from the 1990s-2000s creates licensing complexity for manufacturers seeking freedom-to-operate in key export markets.
- Analytical method standardization:Divergent HPLC and spectrophotometric protocols across pharmacopeias force redundant quality testing, extending batch release timelines and working capital cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ubiquinone Market |
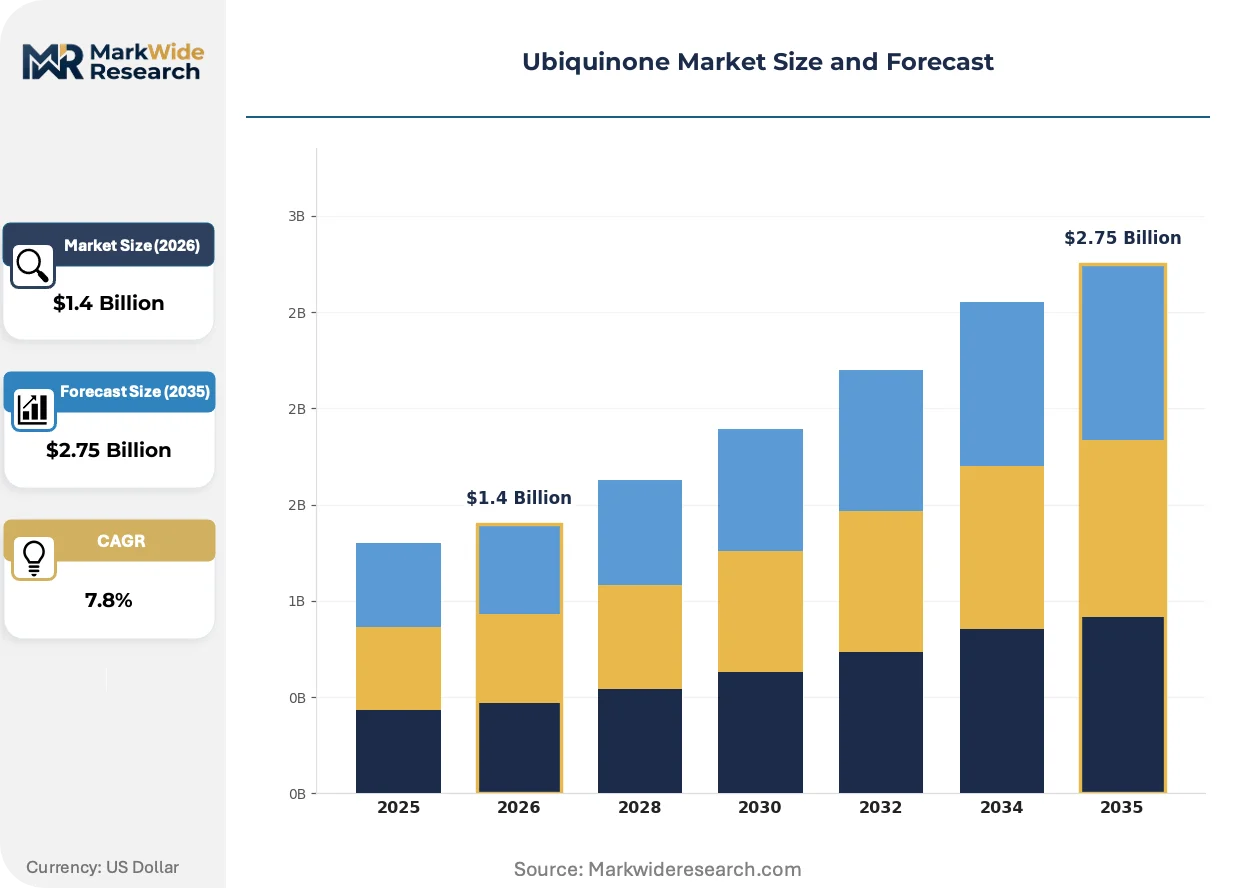
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.75 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coenzyme Q10, Ubiquinol, Ubiquinone Mitoquinone, Idebenone, Others Application: Dietary Supplements, Functional Foods, Pharmaceuticals, Cosmetics, Animal Nutrition Form: Powder, Capsules, Tablets, Softgels, Liquid Extracts End User: Supplement Manufacturers, Pharmaceutical Companies, Personal Care Brands, Veterinary Companies |
| Companies Covered | Kaneka Corporation, Kyowa Hakko Bio Co., Ltd., Oriental Yeast Co., Ltd., Xiamen Kingdomway Group Company, Shandong Octagon Chemicals Limited, Sinoway Industrial Co., Ltd., Spectrum Chemical Manufacturing Corp., Hangzhou Jinlan Pharmaceutical Technology Development Co., Ltd., Tokiwa Phytochemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ubiquinone Market Emerging Trajectories
Bioprocessing automation and analytical digitization are compressing batch-to-batch variability while regulatory divergence between food-grade and pharmaceutical-grade pathways forces parallel compliance investments.
Continuous fermentation monitoring via inline Raman spectroscopy and machine-learning feedback loops is digitizing quality control from offline laboratory testing to real-time parameter adjustment. Pharmaceutical-grade manufacturers in Japan and Switzerland are deploying these systems to reduce batch failure rates and accelerate certificate-of-analysis generation. The shift is digitizing documentation workflows and enabling predictive maintenance that cuts unplanned downtime in high-value production campaigns.
REACH registration requirements for imported coenzyme Q10 into European Union markets are tightening substance identity and impurity profiling obligations for non-EU fermentation facilities. The regulation forces Asian manufacturers to invest in European-qualified analytical laboratories and legal representation, raising fixed costs per export shipment. Dietary supplement distributors are responding by consolidating supplier relationships with REACH-registered entities, reducing qualified vendor pools by an estimated 30-40% in some procurement categories.
Direct-to-practitioner distribution models are displacing traditional wholesale channels for clinical-grade coenzyme Q10 in North American integrative medicine practices. Functional medicine clinics and naturopathic physician networks now source pharmaceutical-grade softgels through specialized compounding pharmacies and practitioner-exclusive brands, bypassing mass-market retail intermediaries. This channel fragmentation concentrates in California, New York, and Texas metropolitan corridors where licensed alternative medicine provider density supports dedicated distribution infrastructure.
Ubiquinone Market Segmentation
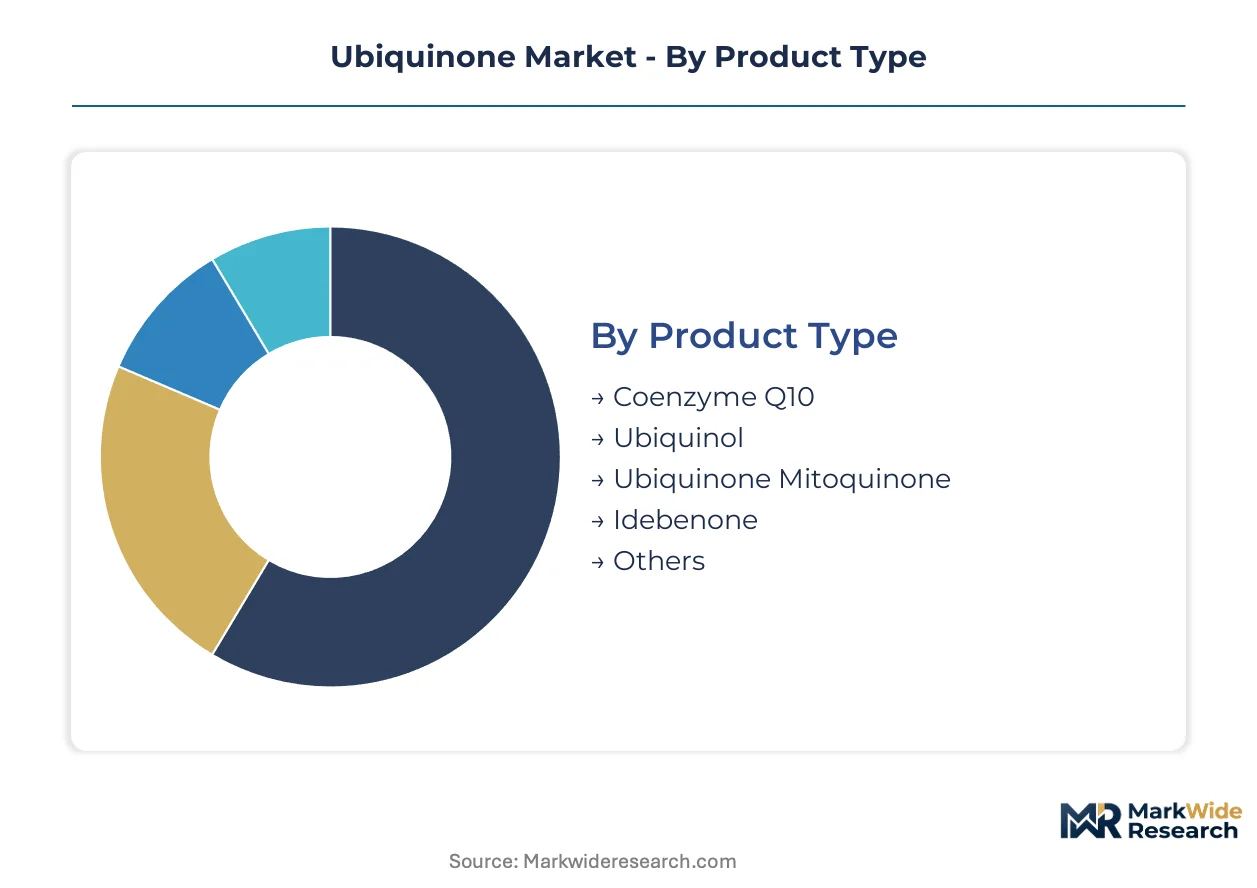
Ubiquinone market segmentation reflects divergent purity requirements and delivery system preferences across nutraceutical, pharmaceutical, and cosmetic value chains. Manufacturers configure production lines around specific form factors and certification tiers rather than serving interchangeable demand pools.
Product Type:
Mature clinical validation separates established coenzyme forms from emerging mitochondrial-targeted variants in commercial traction and pricing power.
- Coenzyme Q10:The oxidized ubiquinone form with established pharmacopeial monographs dominates bulk pharmaceutical procurement and mass-market supplement formulations. Demand concentrates in North American and European retail channels where decades of cardiovascular and energy metabolism research underpins consumer recognition.
- Ubiquinol:The reduced antioxidant form exhibits superior bioavailability in aging populations with declining endogenous conversion capacity. Japanese and Korean manufacturers lead hydrogenation and stabilization capabilities, capturing premium positioning in practitioner-distributed clinical nutrition products.
- Ubiquinone Mitoquinone:A mitochondria-targeted derivative with lipophilic cation modifications for enhanced cellular uptake.
- Idebenone:A synthetic short-chain benzoquinone analog developed for neurodegenerative therapeutic applications.
- Others:Emerging bioengineered variants and hybrid redox forms in pre-commercial development.
Coenzyme Q10 retains volume leadership; Ubiquinol holds the steepest expansion curve.
Application:
End-use concentration varies sharply by regulatory pathway, with pharmaceutical-grade certification filtering accessible market segments.
- Dietary Supplements:The largest consumption channel spanning cardiovascular support, fertility, and athletic recovery positioning. US FDA DSHEA compliance enables rapid formulation iteration, though NDI notifications constrain novel delivery claims.
- Pharmaceuticals:Prescription-grade ubiquinone for heart failure adjuvant therapy and statin-associated myopathy commands stringent GMP and API documentation. European EMA and Japanese PMDA approvals anchor therapeutic credibility, limiting supplier qualification to fermentation specialists with dedicated pharmaceutical facilities.
- Functional Foods:Fortified beverages and dairy alternatives incorporating lipid-soluble CoQ10 through microencapsulation.
- Cosmetics:Topical anti-aging serums leveraging mitochondrial energy claims in premium skincare.
- Animal Nutrition:Feed additives for breeding stock and high-performance equine applications.
Dietary Supplements anchor procurement scale; Pharmaceuticals concentrate margin extraction.
Form:
Delivery system selection determines bioaccessibility outcomes and manufacturing equipment requirements across customer segments.
- Softgels:Oil-based encapsulation in gelatin or plant-derived shells optimizes lipophilic nutrient absorption. Lipid-based delivery opens functional food and beverage applications previously inaccessible to crystalline formulations.
- Powder:Crystalline ubiquinone for bulk pharmaceutical procurement and in-house supplement manufacturing. Chinese fermentation facilities dominate powder exports to European contract manufacturers seeking REACH-registered raw materials.
- Capsules:Two-piece hard shells for powdered or granulated fill in vegetarian and conventional variants.
- Tablets:Compressed forms with binders and coatings for high-volume production economics.
- Liquid Extracts:Emulsified suspensions for pediatric and geriatric compliance applications.
Softgels command premium positioning; Powder dominates upstream trade flows.
End User:
Customer sophistication tiers separate specification-driven procurement from commodity spot purchasing.
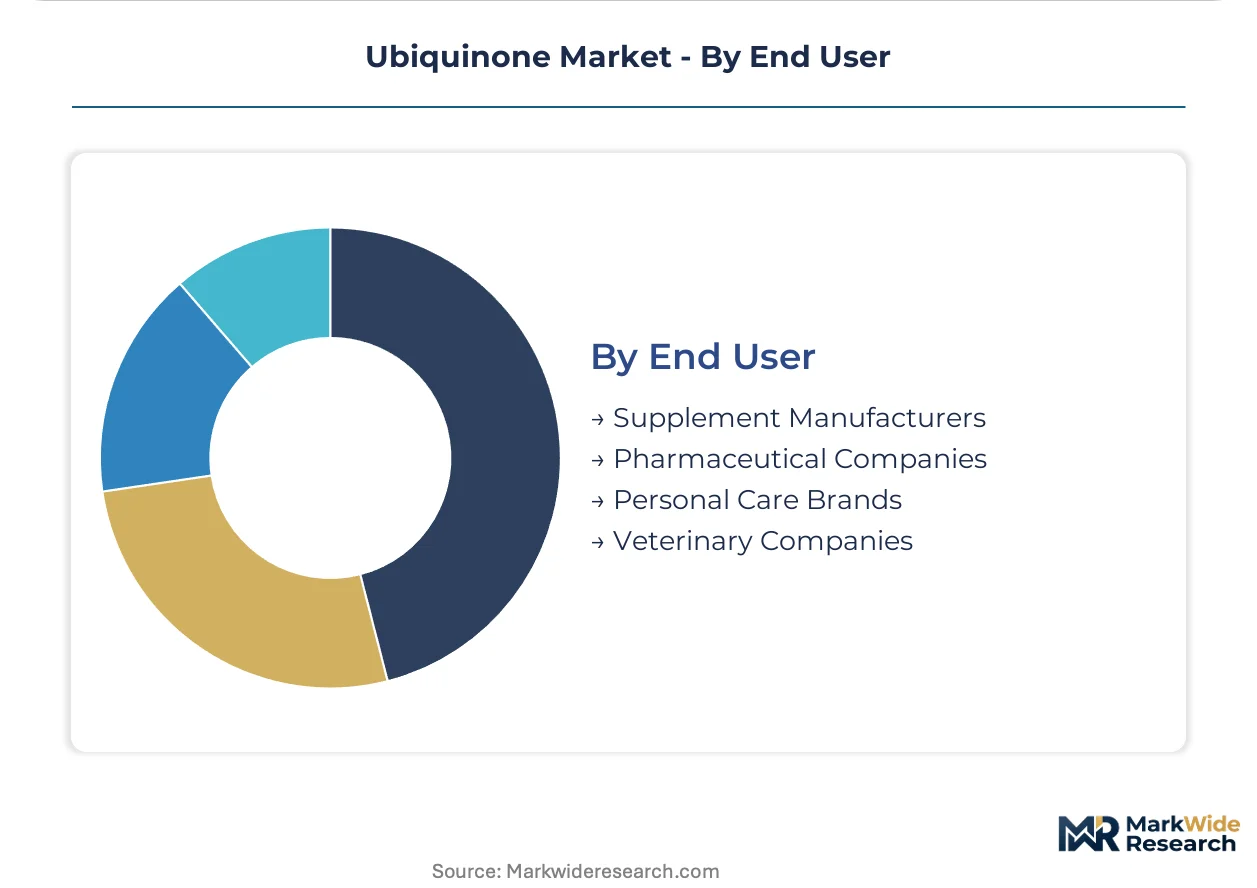
- Supplement Manufacturers:Brand owners and contract packagers sourcing raw materials for finished product assembly. Direct-to-practitioner distribution models in California and New York metropolitan corridors bypass traditional wholesale channels for clinical-grade softgels.
- Pharmaceutical Companies:API purchasers requiring certificate-of-analysis documentation and DMF filings. GMP compliance timelines extending 18-36 months freeze smaller fermentation facilities out of therapeutic applications.
- Personal Care Brands:Cosmetic formulators seeking stabilized ubiquinone for topical delivery systems.
- Veterinary Companies:Animal health specialists incorporating CoQ10 into companion animal and livestock nutrition.
Supplement Manufacturers drive procurement velocity; Pharmaceutical Companies enforce quality premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai's container throughput underwrites China's dominance in ubiquinone powder exports, while the Port of Rotterdam serves as the European entry point for REACH-registered fermentation products.
China
Domestic supplement consumption and pharmaceutical API exports drive demand concentration. NMPA's tightening GMP enforcement for dietary supplement quality creates compliance barriers for smaller fermentation facilities. Xiamen anchors substantial manufacturing capacity, with Kingdomway and Shandong Octagon operating integrated bioprocessing campuses serving European contract manufacturers.
Japan
Aging demographics and practitioner-distributed clinical nutrition sustain premium ubiquinol demand. PMDA's pharmaceutical-grade certification requirements limit API supplier qualification to dedicated fermentation specialists. Kaneka's Kagoshima fermentation heritage supports premium positioning in global coenzyme Q10 supply chains.
United States
Direct-to-practitioner distribution models in California and New York metropolitan corridors bypass traditional wholesale channels for clinical-grade softgels. FDA's DSHEA framework enables rapid formulation iteration, though NDI notifications constrain novel delivery claims. Functional medicine clinics concentrate procurement through compounding pharmacies and practitioner-exclusive brands.
Germany
REACH registration requirements for imported coenzyme Q10 tighten substance identity obligations for non-EU fermentation facilities. EMA's pharmaceutical-grade monographs anchor therapeutic credibility for prescription-grade ubiquinone. The Rhine-Ruhr industrial corridor hosts European-qualified analytical laboratories serving Asian manufacturers seeking export compliance.
Switzerland
Pharmaceutical-grade manufacturers deploy inline Raman spectroscopy and machine-learning feedback loops for real-time quality control. Swissmedic's certification standards support premium positioning in global API markets. Basel's bioprocessing automation cluster enables predictive maintenance that cuts unplanned downtime in high-value production campaigns.
Ubiquinone Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in fermentation strain optimization and downstream purification. The vendor base separates into three tiers: legacy Japanese producers with pharmaceutical-grade certification, Chinese volume specialists serving commodity nutraceutical segments, and European analytical service providers managing REACH compliance. Strategic moves concentrate on fermentation scale-up partnerships and analytical method standardization to reduce redundant quality testing across pharmacopeias.
Among Japanese fermentation heritage companies, Kaneka Corporation and Kyowa Hakko Bio Co., Ltd. exemplify the pharmaceutical-grade certification tier. Xiamen Kingdomway Group Company anchors the volume-specialist archetype. These three entities represent the structural segmentation between premium-positioned API suppliers and scale-driven powder exporters.
| Leading Market Players |
|---|
| Kaneka Corporation |
| Kyowa Hakko Bio Co., Ltd. |
| Oriental Yeast Co., Ltd. |
| Xiamen Kingdomway Group Company |
| Shandong Octagon Chemicals Limited |
| Sinoway Industrial Co., Ltd. |
| Spectrum Chemical Manufacturing Corp. |
| Hangzhou Jinlan Pharmaceutical Technology Development Co., Ltd. |
| Tokiwa Phytochemical Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
The Port of Shanghai's container throughput cost dynamics compress margins for Chinese powder exporters while amplifying price differentiation between pharmaceutical-grade and nutraceutical-grade tiers. Supply concentration in Xiamen and Shandong bioprocessing clusters concentrates volume-discount leverage with European contract manufacturers, forcing smaller facilities into spot-market commodity positioning.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Kaneka's pharmaceutical-grade API positioning from Kingdomway's bulk powder exports and spot-market chemical synthesis alternatives. Price differentiation hinges on GMP certification tier and fermentation purity grades, with hydrogenation capabilities for ubiquinol commanding substantial premiums. Cost compression in standard-grade powder runs through yeast feedstock volatility and REACH compliance overhead. Contract manufacturers exhibit highest price sensitivity; compounding pharmacies sourcing clinical-grade softgels show lowest elasticity.
Supply Chain Analysis
Isoprenoid precursor feedstock availability draws from petrochemical and agricultural terpenoid regions in China, Japan, and select European corridors. Raw material dependencies center on solanesol, yeast biomass, and specialized fermentation media formulations. Single-source vulnerability concentrates in strain engineering IP held by legacy Japanese producers. Distribution runs through pharmaceutical wholesale channels for API grades and direct-to-practitioner networks for clinical nutrition products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ubiquinone demand cycles track functional wellness expenditure patterns, with post-correction normalization in dietary supplement purchasing now restoring procurement velocity for fermentation capacity.
For Market Incumbents: Pre-empt synthetic ubiquinone price erosion by securing captive isoprenoid supply through backward integration into agricultural feedstock partnerships. Accelerate pharmaceutical-grade certification timelines before NMPA enforcement tightens further, freezing mid-tier competitors out of therapeutic applications. Deploy inline analytical systems to compress batch release cycles and working capital intensity. For New Entrants and Emerging Players: Pursue ubiquinol hydrogenation capability gaps in North American practitioner-distribution channels, where direct-to-clinic models bypass entrenched wholesale relationships. Functional medicine clinics in California and Texas corridors represent the most penetrable white-space. Lead with compounding pharmacy partnerships rather than retail shelf placement. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underutilized fermentation assets and dormant pharmaceutical-grade certifications. Long-term viability rests on bioprocessing automation differentiation and regulatory moat depth. Watch for inline Raman spectroscopy adoption rates as inflection signal for quality-control digitization maturity.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Scale-Up Partnership | Japanese strain engineering IP holders unlock capacity expansion for REACH-registered Chinese facilities. |
| Pharmaceutical-Grade Certification Investment | NMPA GMP compliance creates import substitution capture for domestic Chinese manufacturers. |
| Ubiquinol Hydrogenation Capacity Addition | Antioxidant form premiums justify capital deployment for aging-population clinical nutrition positioning. |
| Direct-to-Practitioner Channel Development | California and New York functional medicine networks bypass traditional wholesale margin extraction. |
| Analytical Method Standardization Consortium | Cross-pharmacopeia HPLC protocol alignment reduces redundant testing and batch release timelines. |
Methodological Framework
Desk research of customs trade databases, pharmacopeial monograph repositories, and fermentation patent filings preceded structured interviews with plant managers at bioprocessing facilities, procurement leads at European supplement contract manufacturers, regulatory affairs specialists navigating REACH and NMPA frameworks, and technical R&D directors optimizing yeast strain yields. Bottom-up capacity assessments triangulated against top-down demand modeling from functional wellness expenditure tracking and cardiovascular therapeutic adjuvant prescription patterns.
Assumptions held fixed include current regulatory divergence between food-grade and pharmaceutical-grade pathways, while strain optimization rates and practitioner-channel adoption trajectories were varied across sensitivity scenarios. Segmentation dimensions encompassed product type, application pathway, delivery form, end-user sophistication tier, and regional certification cluster. CAGRs derived from historical volume-price elasticity analysis and forward-looking fermentation yield improvement curves, with isoprenoid feedstock cost indices and DSHEA enforcement intensity as key forecast inputs across the analysis window.
Sensitivities concentrate around NMPA enforcement acceleration, REACH registration cost inflation for non-EU facilities, and synthetic ubiquinone cost parity achievement. Cross-checking against EMA prescription-grade ubiquinone volume trends and Japanese PMDA API import statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Global Vinyl Sulfone Market
Specialty Chemicals
Divinylbenzene (DVB) Market
Specialty Chemicals
Stable Isotopes Market
Specialty Chemicals
Global Vacuum Grease Market
Specialty Chemicals
PPG-20 Methyl Glucose Ether Market
Specialty Chemicals
Organic Sulfur Market
Specialty Chemicals
Global Water Based Acrylates Copolymer Rheology Modifiers Market
Specialty Chemicals
Octofluoropropane Market
Specialty Chemicals
Global Photoacid Generators Market
Specialty Chemicals
Nucleotides Market
Specialty Chemicals
Sandarac Market
Specialty Chemicals
North America Perms and Relaxants Market
Specialty Chemicals
Special Boiling Point Solvents Market
Specialty Chemicals
5-Hydroxymethylfurfural Market
Specialty Chemicals
Global Anti-Static Agents Market
Specialty Chemicals
Cholesteryl Isostearate Market