
 Organo-Modified Bentonite Market | 2026-2036
Organo-Modified Bentonite Market Size, Share, and Industry Trends Forecast 2026-2036
Organo-Modified Bentonite Market Analytics
REACH chemical authorization is repositioning the cost-of-entry calculus for European suppliers of organo-modified bentonite. Elementis PLC leverages its integrated clay sourcing and surface modification capabilities to sustain margin structures under tighter substance scrutiny. BYK Additives anchors its position through deep specialization in solvent-free coating rheology systems. Clariant AG competes across multiple industrial verticals with differentiated organophilic product lines.
Organo-modified bentonite consists of naturally occurring smectite clay rendered hydrophobic through quaternary ammonium cation exchange, typically achieving organic contents of 25–35% by weight and basal spacings exceeding 1.8 nanometers; this interlayer expansion enables gel formation and viscosity recovery in non-aqueous media. The material functions primarily as a thixotropic agent, suspending solids and preventing sag in paints, inks, greases, and oil-based drilling fluids. Coatings applications dominate current value capture given the segment's premium pricing for low-VOC compliant grades, while drilling fluids represent a mature volume pool with cyclical upstream capital spending. Organophilic bentonite exhibits the fastest structural expansion as formulators phase out conventional fumed silica and polyamide wax alternatives.
EPA oversight of volatile organic compound emissions in architectural coatings directly shapes product specification requirements for US market access, while ECHA REACH authorization processes govern substance registration and restriction timelines across European supply chains. China's GB standards for interior building materials, administered by SAMR, impose parallel testing protocols that influence export-oriented manufacturers. Stakeholders must monitor the divergence between regional hazard classification schemes and invest in multi-jurisdictional compliance infrastructure before product registration windows narrow.
Market Dynamics
REACH authorization timelines are compressing the window for European suppliers to reformulate legacy organophilic bentonite grades, forcing accelerated R&D cycles and supplier consolidation around integrated clay-to-modifier capabilities.
Growth Catalysts
- Low-VOC coating mandates:EPA architectural coating standards and ECHA REACH restrictions on solvent-based systems pull demand toward organophilic rheology modifiers that enable compliant high-solids formulations.
- Shale drilling resurgence:Cyclical upstream capital allocation to Permian and Bakken basins renews consumption of oil-based drilling fluid additives, with Wyoming bentonite feedstock securing preferential supply contracts.
- Quaternary ammonium chemistry advances:Dialkyl dimethyl ammonium chloride surface treatments achieve superior gel efficiency at lower loadings, reducing total additive cost-in-use for automotive OEM clearcoats.
Market Restraints
- Raw material concentration:Wyoming's Southern Bentonite District supplies over 70% of US smectite feedstock, creating geographic supply vulnerability to rail logistics disruptions and drought-driven mining constraints.
- Fumed silica substitution:Hydrophobic precipitated silica grades from Solvay and Evonik compete in premium automotive coatings, capturing share where optical clarity requirements exceed bentonite performance thresholds.
- ECHA authorization costs:REACH registration fees and substance evaluation timelines for new quaternary ammonium modifiers impose six-figure entry barriers for specialty chemical entrants lacking existing dossiers.
Strategic Opportunities
- Bio-based modifier platforms:Chitosan-quaternary ammonium hybrid intercalants derived from crustacean waste streams open positioning for marine-certified coatings serving Nordic offshore wind installations.
- India construction chemicals:BIS certification requirements for infrastructure-grade waterproofing membranes create localized demand for organophilic bentonite in tunneling and foundation applications.
- Waterborne system compatibility:Dual-function organo-modified grades that stabilize both solvent-borne and emerging water-reducible alkyd formulations capture formulators consolidating additive inventories.
Industry Challenges
- Intercalation chemistry talent scarcity:Formulation chemists with expertise in cation exchange capacity optimization and basal spacing control command premium compensation, constraining R&D throughput at mid-tier suppliers.
- Multi-jurisdictional dossier management:Divergent hazard classification between EPA TSCA, ECHA REACH, and China's MEE new chemical notification requirements force parallel testing expenditures for global product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organo-Modified Bentonite Market |
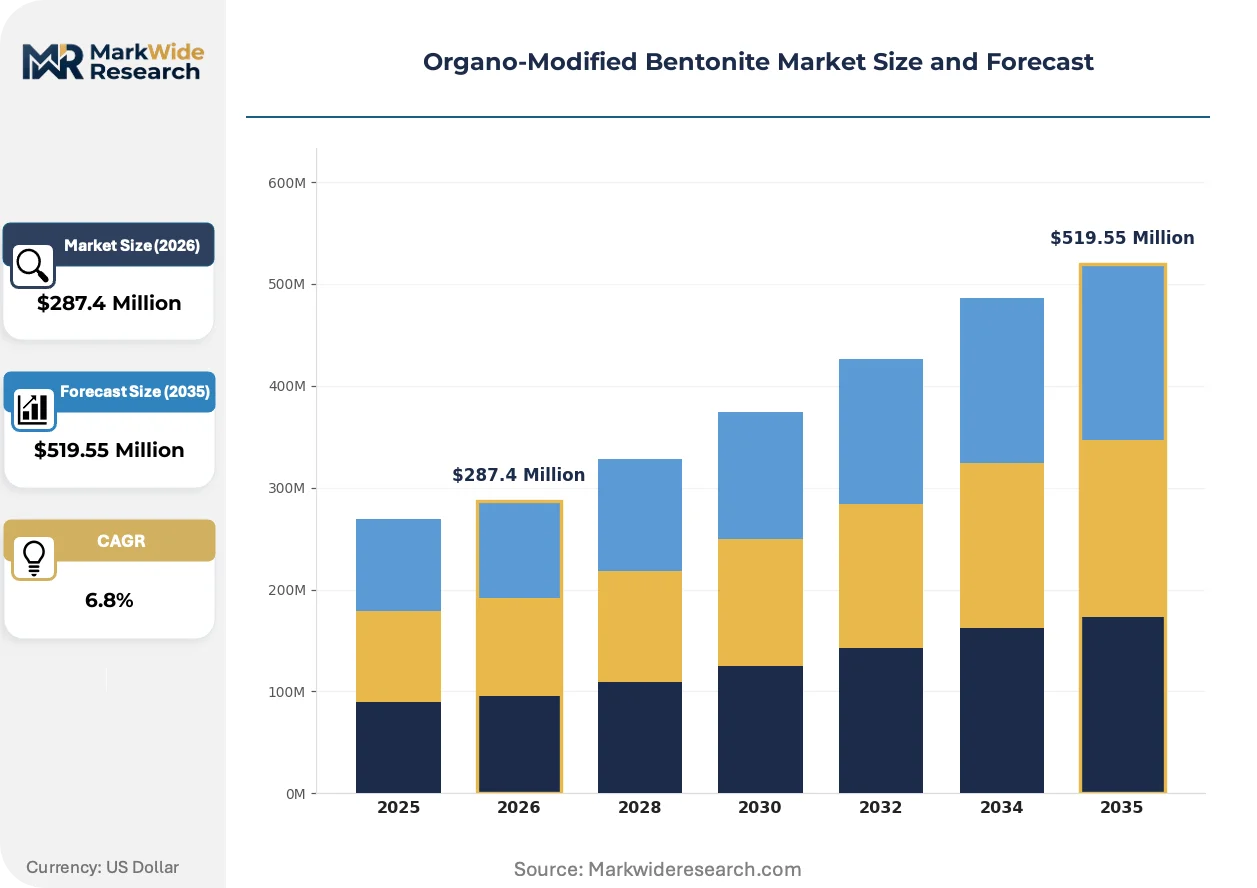
| Market Size in 2026 | $287.4 Million |
| Market Size in 2035 | $519.55 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Bentonite, Calcium Bentonite, Organophilic Bentonite, Multi-Functional Bentonite Application: Drilling Fluids, Foundry Sand Binders, Sealants, Coatings End User: Oil & Gas, Construction, Industrial, Personal Care Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | Zhejiang Huate Industry, Elementis PLC, BYK Additives, Tolsa Group, CETCO, Elementis Specialties, Laviosa Chimica Mineraria, Clariant AG, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organo-Modified Bentonite Market Evolving Landscape
Surface modification chemistry and regulatory chemistry are converging to redefine competitive advantage, with gel efficiency metrics now inseparable from substance authorization status in major industrial coatings markets.
Solvent-free activation processes using high-shear extrusion without aromatic diluents are overtaking conventional solvent-wet milling in European coating additive production. Automotive refinish shops in Germany and Italy now specify solvent-free organophilic grades exclusively. This shift is compressing demand for legacy toluene-dispersed products and rewarding suppliers with dry-process capabilities.
ECHA's restriction proposal for medium-chain chlorinated paraffins is accelerating reformulation timelines across metalworking fluid compounding. The proposed sunset date forces lubricant manufacturers to validate organoclay-based alternatives within compressed validation windows. Drilling fluid service companies in the North Sea basin are pre-qualifying replacement rheology packages ahead of anticipated enforcement.
Coatings formulators now unbundle rheology modifier specification from incumbent supplier relationships, conducting side-by-side sag resistance and leveling tests across three or more organophilic bentonite sources. Technical service teams from BYK and Elementis face direct comparison trials at AkzoNobel and BASF Coatings technical centers. This pattern is most pronounced in automotive OEM clearcoat procurement, where annual supplier performance scorecards now weight regulatory dossier completeness equally with technical performance metrics.
Organo-Modified Bentonite Market Segmentation
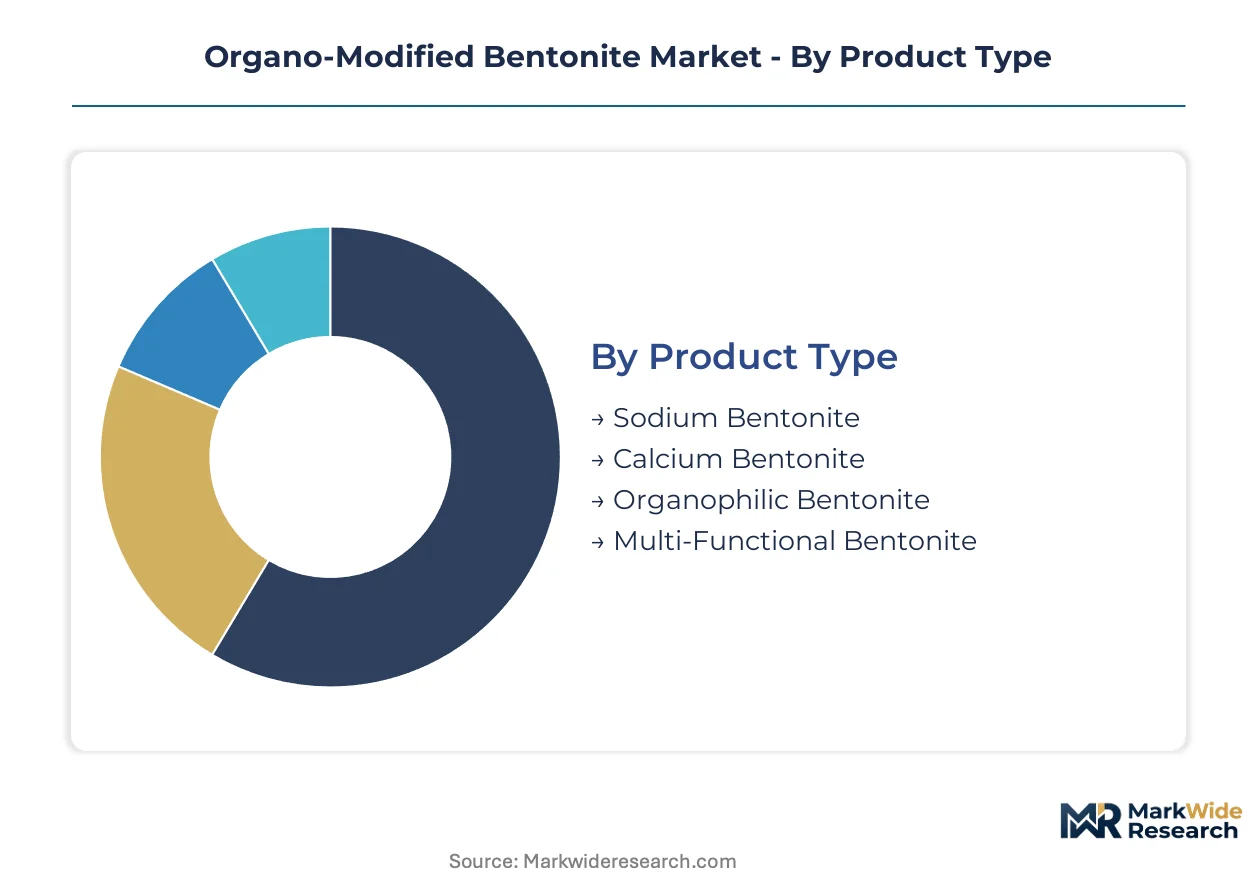
Segmentation in organo-modified bentonite reveals distinct value capture patterns across product chemistry, application performance tiers, and procurement relationships. Understanding these divisions exposes where formulation premiums concentrate and where supply contracts lock in recurring volume.
Product Type:
Surface chemistry sophistication determines whether grades function as standalone additives or require complementary modifiers in finished formulations.
- Organophilic Bentonite:Quaternary ammonium-treated smectite achieves organic carbon loads of 25-35% by weight, enabling thixotropic gel structures in hydrocarbon-based systems without polar activators. Coatings formulators in Germany and Italy now specify this grade exclusively for automotive refinish clearcoats as solvent-free activation processes displace legacy toluene-dispersed alternatives.
- Sodium Bentonite:Naturally hydrophilic montmorillonite with high cation exchange capacity serves as the unmodified feedstock for subsequent organophilic conversion, though limited direct use persists in water-based drilling fluid systems where Wyoming-sourced material commands supply premiums.
- Calcium Bentonite:Lower swelling capacity than sodium counterparts restricts application to foundry sand binders and specific sealant formulations where cost sensitivity outweighs performance requirements.
- Multi-Functional Bentonite:Dual-compatible grades engineered for both solvent-borne and emerging water-reducible alkyd systems allow formulators to consolidate additive inventories across reformulation cycles.
Volume placements concentrate in sodium bentonite as the conversion feedstock base; the faster expansion belongs to organophilic grades capturing low-VOC coating mandates.
Application:
Performance specifications diverge sharply between commodity fluid systems and premium surface treatment markets.
- Coatings:Rheology modifiers for high-solids architectural and automotive formulations command pricing premiums tied to REACH authorization status and EPA VOC compliance documentation. German coatings technical centers now conduct side-by-side sag resistance trials across multiple supplier sources.
- Drilling Fluids:Oil-based mud systems in Permian and Bakken basins consume cyclical volumes linked to upstream capital allocation, with Wyoming bentonite securing preferential supply contracts through integrated service company relationships.
- Sealants:Waterproofing membranes for tunneling and foundation work in India require BIS-certified grades, creating localized specification barriers for imported material.
- Foundry Sand Binders:Mature demand pool tied to metal casting output with limited pricing power and specification differentiation.
Revenue intensity peaks in coatings; drilling fluids deliver volume scale with cyclical volatility.
End User:
Procurement sophistication ranges from technical specification teams to commodity purchasing functions.
- Oil & Gas:Integrated drilling fluid service companies negotiate long-term offtake agreements with Wyoming mining operations, embedding volume commitments into upstream capital planning cycles.
- Construction:Infrastructure waterproofing specifications in India and Nordic offshore wind installations drive demand for marine-certified and BIS-validated grades.
- Industrial:Metalworking fluid compounders face compressed reformulation timelines as ECHA restrictions on medium-chain chlorinated paraffins accelerate organoclay alternative validation.
- Personal Care:Niche rheology applications in cosmetic formulations with stringent purity requirements and smaller batch sizes.
Contract duration extends longest in oil and gas; construction verticals show the steepest specification upgrade trajectory.
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and geographic proximity to formulation centers.
- Direct Sales:Large coatings manufacturers at AkzoNobel and BASF technical centers engage supplier technical teams for side-by-side performance trials and regulatory dossier review.
- Distributors:Regional chemical distributors stock solvent-free organophilic grades for mid-tier formulators lacking integrated supply chain teams.
- Wholesalers:Bulk material handlers serving foundry and construction segments with price-driven procurement and limited technical support.
- Online Retail:Small-volume specialty orders for personal care and research applications with minimal specification complexity.
Technical service intensity concentrates in direct sales; distributors capture share in fragmented regional markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in China's coastal provinces concentrate organo-modified bentonite processing capacity, attracting surface modification specialists with tax holidays and streamlined customs clearance for Wyoming-sourced feedstock.
United States
Upstream capital allocation to Permian and Bakken drilling operations sustains cyclical consumption of oil-based drilling fluid additives. EPA architectural coating standards tighten VOC thresholds annually, pulling formulators toward compliant organophilic rheology systems. Wyoming's Southern Bentonite District anchors domestic feedstock supply, with rail corridors linking mining operations to Gulf Coast coating formulation clusters.
Germany
Automotive OEM clearcoat procurement teams conduct side-by-side sag resistance trials across multiple supplier sources. ECHA REACH authorization timelines compress reformulation windows for legacy quaternary ammonium modifiers. The Rhine-Ruhr industrial corridor hosts technical centers where solvent-free activation processes displace toluene-dispersed alternatives in refinish specifications.
China
GB standards for interior building materials impose parallel testing protocols that influence export-oriented manufacturers. SAMR-administered certification requirements create specification barriers for imported material in infrastructure waterproofing. Yangtze River Delta formulation clusters drive demand for dual-compatible grades serving both solvent-borne and water-reducible alkyd systems.
India
BIS certification requirements for infrastructure-grade waterproofing membranes create localized demand in tunneling and foundation applications. Construction chemical procurement is shifting toward marine-certified grades for offshore wind installations. Gujarat and Maharashtra industrial corridors concentrate compounding capacity serving domestic waterproofing membrane producers.
Italy
Automotive refinish shops in Turin and Milan specify solvent-free organophilic grades exclusively. ECHA restrictions on medium-chain chlorinated paraffins accelerate metalworking fluid reformulation timelines. The Emilia-Romagna coatings cluster validates organoclay-based alternatives within compressed validation windows ahead of anticipated enforcement.
Organo-Modified Bentonite Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered supply positions. The vendor base concentrates around integrated clay-to-modifier capabilities and surface chemistry specialization. Three archetypes dominate: mining-integrated modifiers with captive Wyoming feedstock, formulation-technical specialists with deep rheology expertise, and diversified chemical conglomerates with multi-vertical organophilic portfolios. Competitive moves center on solvent-free process licensing and REACH dossier consolidation through strategic partnerships.
Among UK-registered integrated specialists, Elementis PLC occupies a position exemplifying mining-to-modifier vertical control. BYK Additives, a German GmbH, represents the formulation-technical archetype with concentrated expertise in coating rheology systems. Swiss-structured Clariant AG anchors the diversified chemical conglomerate tier, competing across multiple industrial verticals with differentiated product lines. These three entities collectively illustrate how geographic origin and corporate structure map to distinct competitive positioning in surface modification chemistry.
| Leading Market Players |
|---|
| Zhejiang Huate Industry |
| Elementis PLC |
| BYK Additives |
| Tolsa Group |
| CETCO |
| Elementis Specialties |
| Laviosa Chimica Mineraria |
| Clariant AG |
| BASF SE |
| Others |
Value Network & Pricing Analysis
Automotive OEM procurement teams in Germany and Italy concentrate purchasing power for REACH-authorized organophilic grades, forcing a contract-based long-term offtake model where solvent-free activation capabilities command substantial premiums over legacy toluene-dispersed alternatives.
Pricing Analysis
Short lead-time premiums separate solvent-free organophilic grades from spot-traded legacy inventories as ECHA authorization timelines compress. Three-tier pricing structure across REACH-authorized premium, standard industrial, and unmodified feedstock economy levels reflects certification investment recovery. Price differentiation centers on gel efficiency metrics and dual-compatibility for water-reducible systems. Cost compression in standard grades intensifies as fumed silica substitutes capture automotive clearcoat share; drilling fluid service companies show highest price sensitivity while coatings formulators prioritize regulatory dossier completeness.
Supply Chain Analysis
Rail freight costs from Wyoming's Southern Bentonite District to Gulf Coast and European formulation clusters represent a structural cost layer that Wyoming-mined, China-processed alternatives partially offset through Yangtze River Delta port access. Supply draws from the United States, China, and India as surface modification capacity concentrates in coastal special economic zones. Wyoming smectite feedstock, quaternary ammonium intercalants, and aromatic diluent alternatives constitute critical input dependencies. Single-source vulnerability to drought-driven mining constraints in the Southern Bentonite District threatens volume security. Distribution runs through integrated service company relationships in oil and gas, direct technical sales to coatings manufacturers, and regional chemical distributors serving fragmented formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The organo-modified bentonite market sits in a solvent-free activation transition, with high-shear extrusion processes displacing toluene-dispersed legacy systems across European automotive refinish specifications.
For Market Incumbents: Anchor solvent-free process capabilities through equipment licensing partnerships with German and Italian coating additive producers facing compressed REACH reformulation windows. Backward integration into Wyoming mining operations secures feedstock priority as drought risks intensify; simultaneous investment in dual-compatible grade R&D captures formulators consolidating additive inventories across water-reducible alkyd transitions.
For New Entrants and Emerging Players: Marine-certified coatings procurement teams at Nordic offshore wind developers represent an underserved buyer archetype with limited incumbent technical service presence. BIS-validated grades for Indian tunneling waterproofing membranes offer localized specification barriers that favor regional compounders; pursue joint development agreements with Gujarat construction chemical producers to bypass import certification delays.
For Investors and Strategic Acquirers: The window for entry favors integrated clay-to-modifier specialists with captive Wyoming feedstock and established REACH dossiers over pure-play surface chemistry firms lacking mining control. Long-term viability hinges on regulatory authorization asset durability rather than transient gel efficiency advantages. Watch ECHA substance evaluation timelines for new quaternary ammonium modifiers as the inflection signal for incumbent margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Solvent-Free Process Licensing | BYK and Elementis technical teams license high-shear extrusion capabilities to Italian refinish producers. |
| Backward Integration into Mining | Captive Wyoming smectite supply secures preferential offtake terms with Permian drilling fluid service companies. |
| Dual-Compatibility Grade Development | Clariant R&D targets water-reducible alkyd stabilization to capture inventory-consolidating formulators. |
| BIS Certification Partnership | Regional Indian compounders validate tunneling membrane grades ahead of infrastructure investment cycles. |
| Bio-Based Intercalant Platform | Chitosan-quaternary ammonium hybrids from crustacean waste target Nordic offshore wind marine certifications. |
Research Methodology
Document review covered SEC 10-K filings from listed chemical conglomerates, ECHA REACH registration databases, and USGS mineral commodity summaries, complemented by interviews with coatings formulators at AkzoNobel and BASF technical centers, Wyoming bentonite mining operations managers, and drilling fluid procurement leads at integrated service companies. Secondary validation drew from Cefic sector reports, customs trade data for Wyoming smectite exports, and automotive OEM clearcoat specification sheets. Bottom-up volume modeling triangulated against top-down market sizing from feedstock production estimates.
Historical shipment data cross-referenced against expert panel input from German automotive refinish compounders and Indian construction chemical distributors shaped the analytical framework. Segmentation dimensions included surface chemistry sophistication, application performance tier, and regional regulatory cluster. CAGRs derived from elasticity modeling of coating formulation demand against VOC mandate enforcement schedules and upstream capital allocation cycles to Permian and Bakken basins.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA authorization timeline delays, Wyoming drought severity, and fumed silica substitution rates in premium automotive applications. Forecasts reflect assumptions about REACH enforcement consistency and shale drilling capital commitment durability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
13X Molecular Sieve Activated Powder Market
Specialty Chemicals
LAMEA Metal Biocides Market
Specialty Chemicals
Rosin Market
Specialty Chemicals
Global 28-Homobrassinolide Market
Specialty Chemicals
Global Bio Based Esters Market
Specialty Chemicals
2-(2,2,2-Trifluoroethoxy)-1,3,2-Dioxaphospholane-2-Oxide Market
Specialty Chemicals
Barium Sulfate Market
Specialty Chemicals
Explosives and Pyrotechnics Market
Specialty Chemicals
Mexoryl SX (Ecamsule) Market
Specialty Chemicals
Global Hydroxy Ethyl Cellulose (HEC) Market
Specialty Chemicals
Europe Sugarcane Wax Market
Specialty Chemicals
Vulcanization Accelerators Market
Specialty Chemicals
North America Perms and Relaxants Market
Specialty Chemicals
Polyimide Varnish Market
Specialty Chemicals
Precast Gels Market
Specialty Chemicals
Dehazer Market